
 Global Lithium Mining Market | 2026-2036
Global Lithium Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lithium Mining Market Foresight
Downstream chemical processing margins is reshaping capital allocation across the lithium value chain. Albemarle Corporation leverages its Chilean brine assets and integrated conversion capacity to sustain cost leadership in battery-grade lithium hydroxide. Ganfeng Lithium anchors its position through captive offtake agreements with Australian spodumene producers and verticalized refining operations in China.
Lithium mining encompasses the extraction of lithium-bearing ores and brines, primarily spodumene pegmatites with grades of 1-2% Li2O and continental brines with lithium concentrations of 200-700 ppm, for conversion into chemicals that enable rechargeable battery cathodes. Hard-rock open pit operations dominate current supply volumes, yet brine extraction in South America's lithium triangle commands lower unit costs where evaporation rates and aquifer chemistry permit sustained pond-based concentration. Battery Manufacturing absorbs the majority of refined lithium output, while Lithium Hydroxide production lines are expanding fastest to serve high-nickel cathode chemistries.
Chile's environmental regulator enforces water-use quotas on Atacama brine operators, while Australia's EPA mandates progressive rehabilitation bonds for hard-rock mines. China's SAMR imposes GB standards on battery-grade lithium purity that constrain market access for unqualified refiners. Stakeholders must track how jurisdictional water scarcity rules and carbon border adjustments redirect investment toward DLE technologies and alternative feedstocks.
Market Dynamics
Direct lithium extraction technologies are disrupting century-old evaporation pond economics in Chile's Atacama and Argentina's salt flats, compressing project timelines from years to months while slashing water intensity.
Growth Catalysts
- EU Battery Regulation:Mandates recycled content quotas and carbon footprint declarations for lithium-ion cells, redirecting European OEM procurement toward certified low-carbon brine and DLE operations.
- High-nickel cathode chemistry migration:Battery manufacturers are converting lithium carbonate lines to hydroxide to serve NMC 811 and NCA formulations, pulling spodumene feedstock through integrated conversion assets.
- Chile's lithium nationalization framework:Codelco and SQM partnership structures are opening new state-backed concession blocks to private technology partners under revised royalty terms.
Market Restraints
- Atacama aquifer depletion limits:Chile's environmental regulator has imposed extraction ceilings on Salar de Atacama operators, capping sustainable brine withdrawal rates regardless of pond expansion.
- Spodumene concentrate freight volatility:Australian hard-rock producers face exposure to bulk shipping rate swings between Port Hedland and Chinese conversion facilities, eroding margin predictability.
- Geographic supply concentration:The lithium triangle and Western Australia account for over four-fifths of mined output, concentrating geopolitical and climate risk in two corridors.
Strategic Opportunities
- Argentina's Cauchari-Olaroz corridor:Greenfield brine projects in Jujuy Province offer untapped resource bases with favorable evaporation chemistry and provincial tax incentives for DLE deployment.
- Solid-state battery precursor demand:Next-generation cell architectures require ultra-high-purity lithium metal, creating premium pricing tiers for refiners with advanced electrolysis capabilities.
- US Inflation Reduction Act:Critical mineral domestic content thresholds for EV tax credits are incentivizing North American hard-rock development and midstream conversion investments.
Industry Challenges
- DLE process engineering talent scarcity:Commercial-scale selective adsorption and solvent extraction operations require specialized hydrometallurgists, with fewer than two dozen qualified engineering firms globally.
- Battery-grade certification timelines:China's SAMR GB/T 26008 purity standards and automotive OEM qualification protocols extend product approval cycles to 18-24 months for new refinery entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lithium Mining Market |
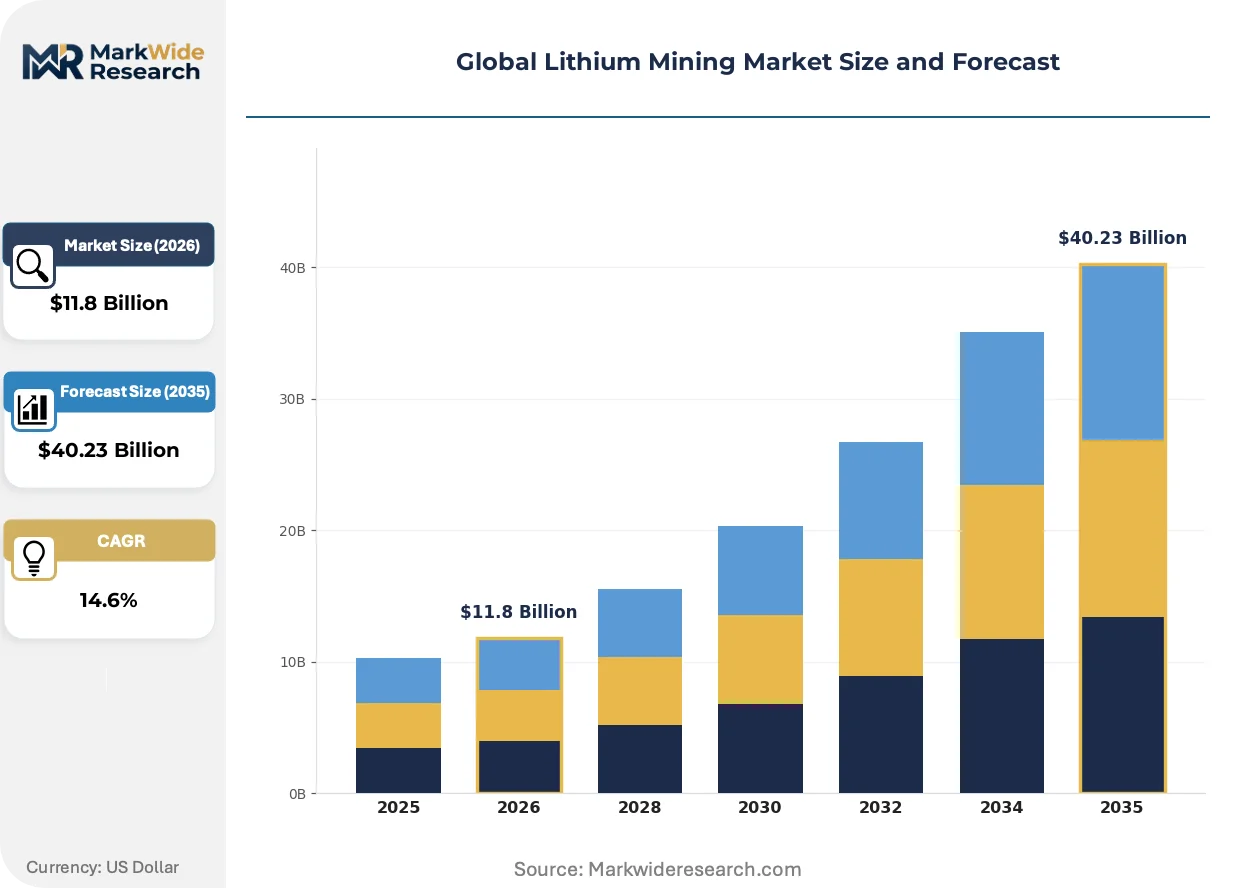
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Extraction Method: Open Pit, Underground, Brine Extraction, Clay Extraction Product Type: Spodumene, Lithium Carbonate, Lithium Hydroxide, Lithium Chloride End User Industry: Battery Manufacturing, Glass & Ceramics, Lubricants, Pharmaceuticals, Polymers Mining Equipment Type: Drilling Machines, Haul Trucks, Crushers, Conveyors |
| Companies Covered | Albemarle Corporation, Sociedad Química y Minera (SQM), Ganfeng Lithium, Tianqi Lithium, Rio Tinto, Pilbara Minerals, Livent Corporation, Lithium Americas, Mineral Resources Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lithium Mining Market Shifts & Advancements
Electrochemical processing advances and jurisdictional carbon accounting are rewiring investment flows across the lithium value chain, favoring modular extraction technologies and integrated refining colocation.
Direct lithium extraction using selective adsorbents and electrochemical cells is rendering obsolete traditional multi-stage evaporation ponds that have dominated South American brine operations since the 1990s. Battery-grade lithium hydroxide producers in China and South Korea are piloting DLE-fed feedstock to bypass carbonate intermediate steps. This compression of the process chain is collapsing the historical cost advantage of established pond operators.
China's SAMR has tightened GB standards on battery-grade lithium carbonate and hydroxide purity thresholds, disqualifying smaller refiners lacking ion-exchange polishing capacity. The regulation is accelerating consolidation in Jiangxi and Sichuan processing hubs as subscale operators face technical retrofit costs exceeding replacement value. Tier-1 cathode manufacturers are now requiring certificate-of-analysis documentation traceable to extraction source.
Automotive OEMs are consolidating lithium procurement through multi-year offtake agreements directly with miners and integrated converters, bypassing merchant traders and spot market exposure. This disintermediation is most visible among German and Korean battery producers securing ten-year supply commitments from Chilean and Australian assets. The shift is compressing price discovery transparency and locking in volume allocations before project commissioning.
Global Lithium Mining Market Segmentation
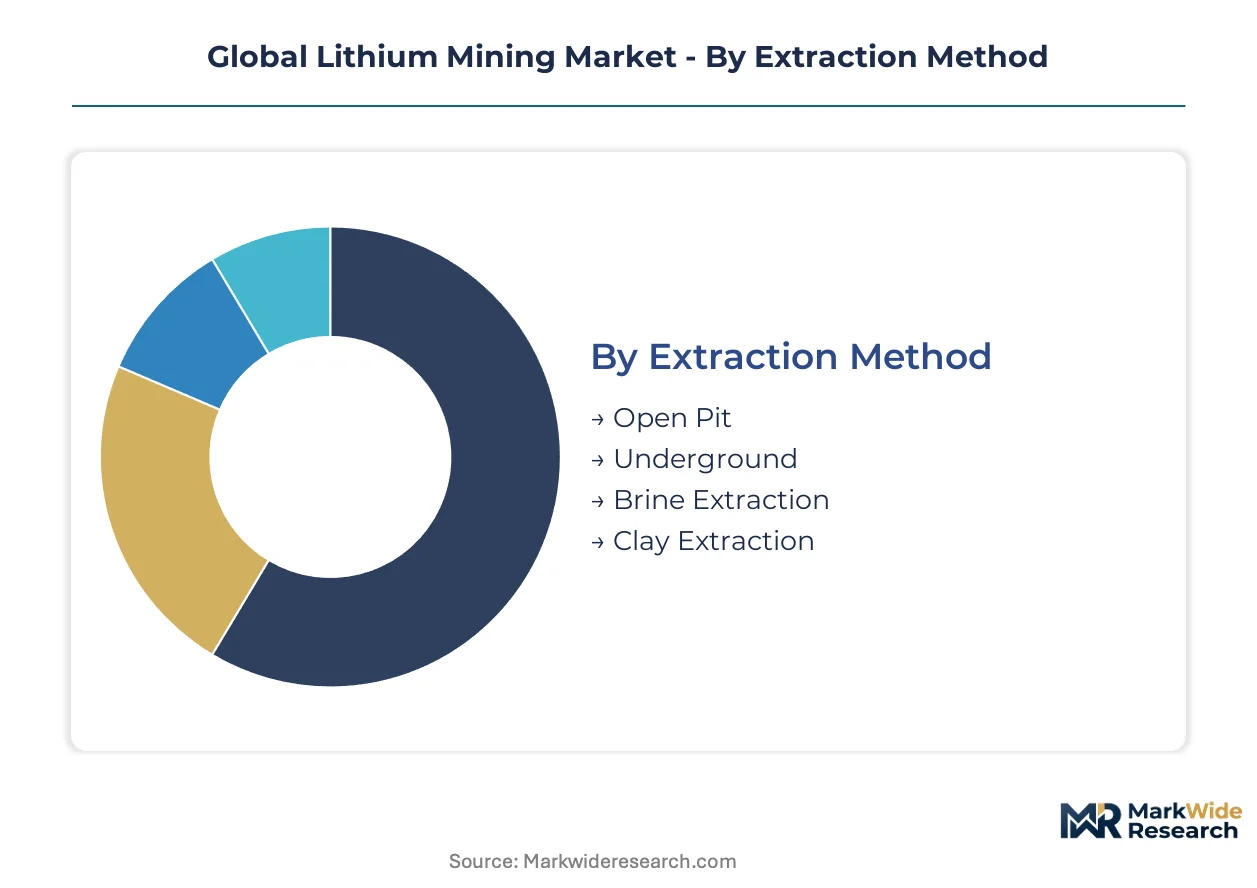
Lithium mining segmentation reveals how extraction physics, chemical conversion pathways, and end-use specifications create divergent margin profiles across the value chain. Understanding these segment boundaries enables capital allocation toward the highest-return nodes as battery chemistry requirements tighten.
Extraction Method:
Cycle times vary dramatically from months for brine pond concentration to years for hard-rock permitting, reshaping which methods attract development capital under different price environments.
- Open Pit:Surface excavation of spodumene pegmatites in Western Australia's Pilbara region yields 1-2% Li2O ore for crush-grind-float concentration. Australian EPA progressive rehabilitation bonds and diesel-powered fleet requirements are elevating all-in costs for new entrants.
- Brine Extraction:Continental salt flat pumping in Chile's Salar de Atacama and Argentina's Cauchari-Olaroz corridor exploits 200-700 ppm lithium concentrations through solar evaporation ponds or emerging DLE technologies. Chile's environmental regulator water-use quotas are capping sustainable withdrawal rates regardless of pond expansion.
- Underground:Decline development beneath weathered zones accesses higher-grade spodumene lenses with reduced surface disturbance footprints.
- Clay Extraction:Sedimentary-hosted lithium in Nevada's Clayton Valley and Sonora deposits requires acid leaching or thermal treatment, with sulfuric acid supply chains and tailings chemistry constraining project economics.
Open pit hard-rock anchors the volume base while brine extraction gains share at the steepest rate as DLE technologies compress production timelines.
Product Type:
Cost tiers separate commoditized intermediates from battery-grade specialties, with purification steps and certification overhead determining which products command sustainable premiums.
- Lithium Hydroxide:Monohydrate crystals meeting battery-grade specifications serve NMC 811 and NCA cathode chemistries requiring lower sodium and calcium tolerances than carbonate routes. Integrated converters in China and South Korea are expanding hydroxide lines fastest to capture high-nickel cathode migration.
- Spodumene:6% Li2O concentrate from Australian and African hard-rock mines feeds Chinese and European conversion facilities, with bulk shipping rate volatility between Port Hedland and Asian ports eroding margin predictability for merchant producers.
- Lithium Carbonate:Primary intermediate for LFP cathodes and industrial applications, with China's SAMR GB/T 26008 purity standards disqualifying smaller refiners lacking ion-exchange polishing capacity.
- Lithium Chloride:Feedstock for lithium metal production via molten salt electrolysis, with solid-state battery precursor demand creating premium tiers for ultra-high-purity output.
Spodumene concentrate underpins current supply volumes while lithium hydroxide is expanding most quickly to serve high-nickel cathode requirements.
End User Industry:
Application-specific purity thresholds and volume scale separate battery-grade contract markets from industrial spot purchasing, with qualification protocols creating divergent customer stickiness.
- Battery Manufacturing:Cathode active material producers and cell fabricators absorb the majority of refined lithium output, with automotive OEMs consolidating procurement through multi-year offtake agreements that bypass merchant traders.
- Glass & Ceramics:Feldspathic flux applications in container glass and ceramic glazes consume technical-grade lithium carbonate with lower purity requirements than battery specifications.
- Lubricants:Lithium soap greases for high-temperature bearing applications represent mature demand with limited growth elasticity.
- Pharmaceuticals:USP-grade lithium carbonate for mood disorder therapeutics requires dedicated production lines with FDA validation overhead.
- Polymers:Organolithium initiators for synthetic rubber and polymerization catalysts consume metal and butyllithium derivatives in smaller volume than battery applications.
Battery manufacturing dominates volume absorption while pharmaceutical applications retain the most stable pricing through regulatory moats.
Mining Equipment Type:
Customer type segmentation separates integrated majors with captive maintenance fleets from contract miners renting specialized units, with utilization rates driving ownership versus lease decisions.
- Haul Trucks:240-ton class rigid dumpers move waste and ore in Pilbara and Atacama operations, with electrification pilots targeting diesel cost and emissions reduction.
- Drilling Machines:Rotary blasthole rigs and diamond coring units define extraction advance rates in hard-rock and exploration programs.
- Crushers:Primary gyratory and secondary cone configurations reduce spodumene ore to flotation feed size, with energy intensity varying by ore competence.
- Conveyors:Overland and in-pit systems reduce truck fleet requirements where topography permits continuous material movement.
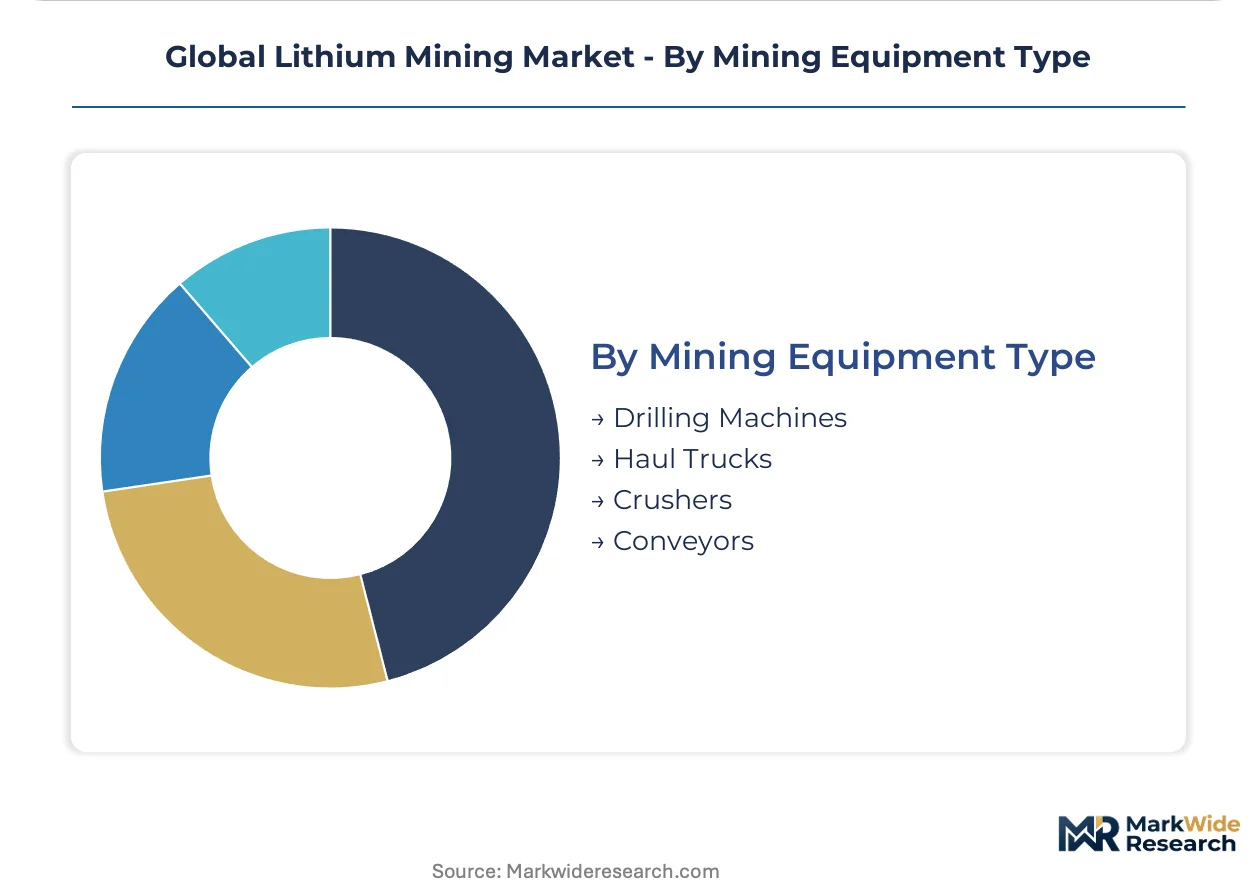
Haul trucks anchor fleet capital allocation while drilling machines command the highest day-rate premiums during exploration upswings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over four-fifths of mined lithium originates from just two corridors: South America's lithium triangle and Western Australia's Pilbara region. Chile's Atacama brine operations and Australia's hard-rock spodumene mines anchor current supply volumes, yet jurisdictional water scarcity and carbon border adjustments are redirecting investment toward Argentina's greenfields and North American development.
Chile
Chile's Salar de Atacama hosts the world's lowest-cost brine operations, where Codelco and SQM partnership structures now govern state-backed concession blocks. Chile's environmental regulator enforces strict water-use quotas on brine operators, capping sustainable aquifer withdrawal rates. Antofagasta and Calama anchor the extraction cluster, with DLE technology pilots compressing production timelines from years to months.
Australia
Western Australia's Pilbara region generates the majority of global spodumene concentrate through open-pit hard-rock operations feeding Chinese conversion facilities. Australia's EPA mandates progressive rehabilitation bonds for new mine approvals, elevating all-in costs for entrants. Port Hedland serves as the primary export gateway, with bulk shipping rate volatility eroding margin predictability for merchant producers.
Argentina
Argentina's Cauchari-Olaroz corridor in Jujuy Province offers untapped brine resources with favorable evaporation chemistry and provincial tax incentives. The national lithium nationalization framework permits private technology partners under revised royalty terms. Salta and Jujuy provinces anchor the greenfield expansion, with DLE deployment accelerating project commissioning timelines.
China
China's Jiangxi and Sichuan provinces concentrate midstream lithium refining capacity, where SAMR GB standards on battery-grade purity are accelerating consolidation. The country's dual carbon goals redirect capital toward lower-carbon processing routes. Ganzhou and Yibin anchor the chemical conversion cluster, with integrated hydroxide lines expanding fastest to serve high-nickel cathode demand.
United States
Nevada's Clayton Valley and Thacker Pass deposits represent North America's most advanced hard-rock and clay-hosted lithium development. The US Inflation Reduction Act's critical mineral domestic content thresholds incentivize North American mine-to-battery supply chains. Reno and Silver Peak anchor the emerging extraction cluster, with electrochemical processing advances rewiring investment flows toward modular technologies.
Global Lithium Mining Market Competitive Landscape
Integrated majors with captive conversion capacity and pure-play miners with merchant concentrate offtake split the market into divergent margin structures. Chilean brine operators leverage century-old pond infrastructure against Australian hard-rock producers optimizing spodumene flotation economics. Three archetypes dominate: state-affiliated Latin American brine operators, Australian scale-driven hard-rock miners, and Chinese vertically integrated refiners. Competitive dynamics center on DLE technology licensing races and multi-year automotive offtake negotiations that bypass spot market exposure.
Among Chilean state-partnered operators, Sociedad Química y Minera (SQM) and Albemarle Corporation occupy positions exemplifying the low-cost brine archetype, while Ganfeng Lithium represents the Chinese integrated refiner model with captive Australian spodumene supply. These three entities anchor distinct strategic postures: SQM and Albemarle leverage Atacama water rights and pond infrastructure, while Ganfeng exemplifies backward integration into upstream feedstock through offtake control.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Sociedad Química y Minera (SQM) |
| Ganfeng Lithium |
| Tianqi Lithium |
| Rio Tinto |
| Pilbara Minerals |
| Livent Corporation |
| Lithium Americas |
| Mineral Resources Limited |
| Others |
Supply & Pricing Matrix
Chilean Atacama brine concentration and Australian Pilbara spodumene output anchor upstream supply, concentrating margin capture downstream with Chinese hydroxide converters and Korean cathode producers. Battery-grade certification tiers separate qualified suppliers from merchant concentrate traders, with automotive OEM offtake agreements locking in volume allocations before project commissioning.
Pricing Analysis
China's SAMR GB/T 26008 purity standards dictate the pricing tier structure for battery-grade lithium chemicals, separating ion-exchange polished hydroxide from unqualified refinery output. Long-term offtake contracts between Chilean brine operators and Korean battery manufacturers trade at premiums to spot-indexed spodumene concentrate, reflecting certification overhead and volume security. Cost compression in Australian hard-rock supply chains is intensifying because diesel-powered fleet requirements and progressive rehabilitation bonds elevate all-in sustaining costs. Merchant spodumene producers exhibit the highest price sensitivity, while integrated majors with captive conversion capacity maintain pricing power through cathode chemistry qualification protocols.
Supply Chain Analysis
Extended payment terms from Chinese conversion facilities to Australian spodumene suppliers are compressing working capital cycles across the seaborne concentrate trade. Raw material flows draw from Chilean brine pumping, Australian hard-rock flotation, and emerging Argentine DLE operations, with sulfuric acid and reagent supply chains for clay-hosted projects in Nevada creating additional dependencies. Single-source vulnerability concentrates in the Port Hedland-to-China shipping corridor, where bulk freight rate volatility erodes margin predictability for merchant producers. Distribution runs through integrated converter networks in Jiangxi and Sichuan provinces, with automotive OEMs disintermediating merchant traders through direct miner partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium-ion battery chemistry advancement threatens incumbent lithium demand in stationary storage and entry-level electric vehicles, forcing established producers to defend chemistry-specific moats. Substitution defense requires locking in high-nickel cathode chemistry qualification and solid-state precursor positioning before alternative technologies achieve cost parity.
For Market Incumbents: Build process technology moats through DLE licensing control and captive hydroxide conversion capacity in Korean and Chinese chemical parks. Secure ten-year offtake agreements with German and Korean automotive OEMs before Argentine greenfield projects achieve commercial scale. Invest in ion-exchange polishing capacity to meet SAMR GB/T 26008 purity thresholds and disqualify subscale refinery competitors from battery-grade certification.
For New Entrants and Emerging Players: Build out modular DLE operations in Argentina's Cauchari-Olaroz corridor, where provincial tax incentives and favorable evaporation chemistry compress project timelines against established pond operators. Target the North American hard-rock development segment incentivized by US Inflation Reduction Act domestic content thresholds, with electrochemical processing advances enabling mine-to-battery supply chain integration. Establish direct cathode producer partnerships to bypass merchant trader networks and secure qualification protocols before commissioning.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated majors with captive conversion capacity and qualified automotive offtake coverage across the medium-term horizon. Acquisition targets should exhibit DLE technology licensing positions or control over Argentine brine concessions with permitted water rights. Watch for inflection signals in solid-state battery precursor demand, where ultra-high-purity lithium metal requirements create premium pricing tiers for advanced electrolysis capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| DLE Technology Licensing | Selective adsorption patents compress brine project timelines from years to months while slashing water intensity. |
| Long-term Supply Agreement | Automotive OEM offtake contracts bypass merchant traders and lock in volume allocations before commissioning. |
| Backward Integration | Captive spodumene offtake from Australian producers secures feedstock for Chinese hydroxide expansion. |
| Green Certification Program | EU Battery Regulation carbon footprint declarations redirect procurement toward certified low-carbon operations. |
| Joint Venture | Chilean state-backed concession partnerships open new blocks to private technology partners under revised royalty terms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with lithium extraction executives, cathode procurement leads at battery manufacturers, and hydrometallurgical engineering specialists; alongside secondary validation through SEC filings from integrated majors, Chilean environmental regulator water-use quota documentation, and Chinese SAMR GB standard publications. Bottom-up project-level capacity modeling triangulated against top-down demand forecasts from automotive OEM electrification roadmaps.
Forecast inputs span extraction method economics, cathode chemistry migration rates, and jurisdictional water scarcity rule evolution across the projection horizon. Segmentation dimensions include extraction physics, product purity tiers, end-use industry specifications, and regional regulatory clusters. CAGRs were derived from supply-demand balance modeling incorporating project commissioning timelines and qualification protocol durations. Industry-specific inputs capture DLE technology deployment rates and solid-state battery precursor demand curves.
Stress conditions across lithium carbonate-to-hydroxide price spreads, Atacama aquifer withdrawal enforcement, and Korean battery producer inventory cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on cathode chemistry adoption and regulatory implementation timelines. Macroeconomic recession, accelerated sodium-ion substitution, or breakthrough DLE process standardization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Automotive Cylindrical Lithium Batteries Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
21700 Lithium Battery Sales Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market