
 Lithium Silicon Battery Market | 2026-2036
Lithium Silicon Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Silicon Battery Market Analysis
US anode material producers is consolidating around pre-lithiation and nanostructured silicon architectures. Amprius Technologies Inc. leverages its silicon nanowire platform to dominate aviation and satellite power applications. Sila Nanotechnologies Inc. sustains a partnership model with automotive OEMs for Titan Silicon integration. Group14 Technologies Inc. anchors its position through a Washington-state manufacturing base serving battery cell customers across North America.
Lithium silicon batteries replace conventional graphite anodes with silicon composites that store up to ten times more lithium ions per unit mass, enabling energy densities above 400 Wh/kg in prototype cells. Pouch cells command premium positioning in electric vehicle platforms where volumetric efficiency determines pack architecture. Electric Vehicles as an end-user segment attracts the deepest capital commitments, while Solid-state technology lines attract parallel investment for post-2030 thermal stability requirements.
The US FAA certifies silicon-anode cells for unmanned aerial systems under evolving airworthiness directives, while the EU Battery Regulation mandates recycled content disclosures that reshape anode supply chain accountability. China's NMPA enforces GB standards on thermal runaway propagation that filter silicon-anode designs entering the domestic market. Stakeholders must monitor which anode architecture—porous silicon, silicon oxide, or silicon-carbon composites—secures dominant cell maker qualification first.
Market Dynamics
Silicon-anode qualification timelines at tier-one cell manufacturers are compressing pack integration cycles, forcing material suppliers to synchronize pilot-scale output with automotive platform launches eighteen months ahead of production ramps.
Growth Catalysts
- Aviation electrification mandates:The US FAA's evolving airworthiness directives for unmanned aerial systems create a certified pathway for silicon-anode cells in regional electric aircraft and satellite constellations.
- Pre-lithiation process maturation:Advances in stabilized lithium metal powders reduce first-cycle capacity loss in silicon composites, accelerating OEM qualification for premium electric vehicle platforms.
- South Korea's cathode cluster proximity:Concentrated anode-to-cell supply chains in Gyeonggi and Ulsan provinces minimize logistics friction for integrated battery producers.
Market Restraints
- Metallurgical-grade silicon price volatility:Solar panel manufacturers compete for polysilicon feedstock, creating input cost pressure for battery-grade silicon refinement.
- Single-source precursor dependence:High-purity silane gas production concentrates in Germany and the United States, exposing anode makers to geographic supply disruption.
- Solid-state electrolyte compatibility gaps:Silicon volume expansion during lithiation stresses ceramic and sulfide electrolyte interfaces, delaying dual-technology integration.
Strategic Opportunities
- India's PLI scheme for cell manufacturing:Production-linked incentives for advanced chemistry cells create localized demand for silicon-anode material imports during domestic precursor buildout.
- Maritime propulsion electrification:Ferry operators and short-sea shipping lines seek energy-dense pouch configurations for hybrid-electric vessel retrofits.
- EU Battery Regulation recycled content mandates:Anode material traceability requirements favor suppliers with closed-loop silicon recovery capabilities.
Industry Challenges
- Electrode coating technician scarcity:Thin-film nanowire deposition requires specialized cleanroom expertise that outpaces vocational training program output.
- Cell-to-pack thermal validation timelines:Silicon-anode thermal runaway propagation testing under China's GB standards extends certification cycles by four to six months.
- Legacy graphite anode equipment retrofit costs:Converting roll-to-roll coating lines for silicon slurry rheology demands capital outlays that strain mid-tier material producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Silicon Battery Market |
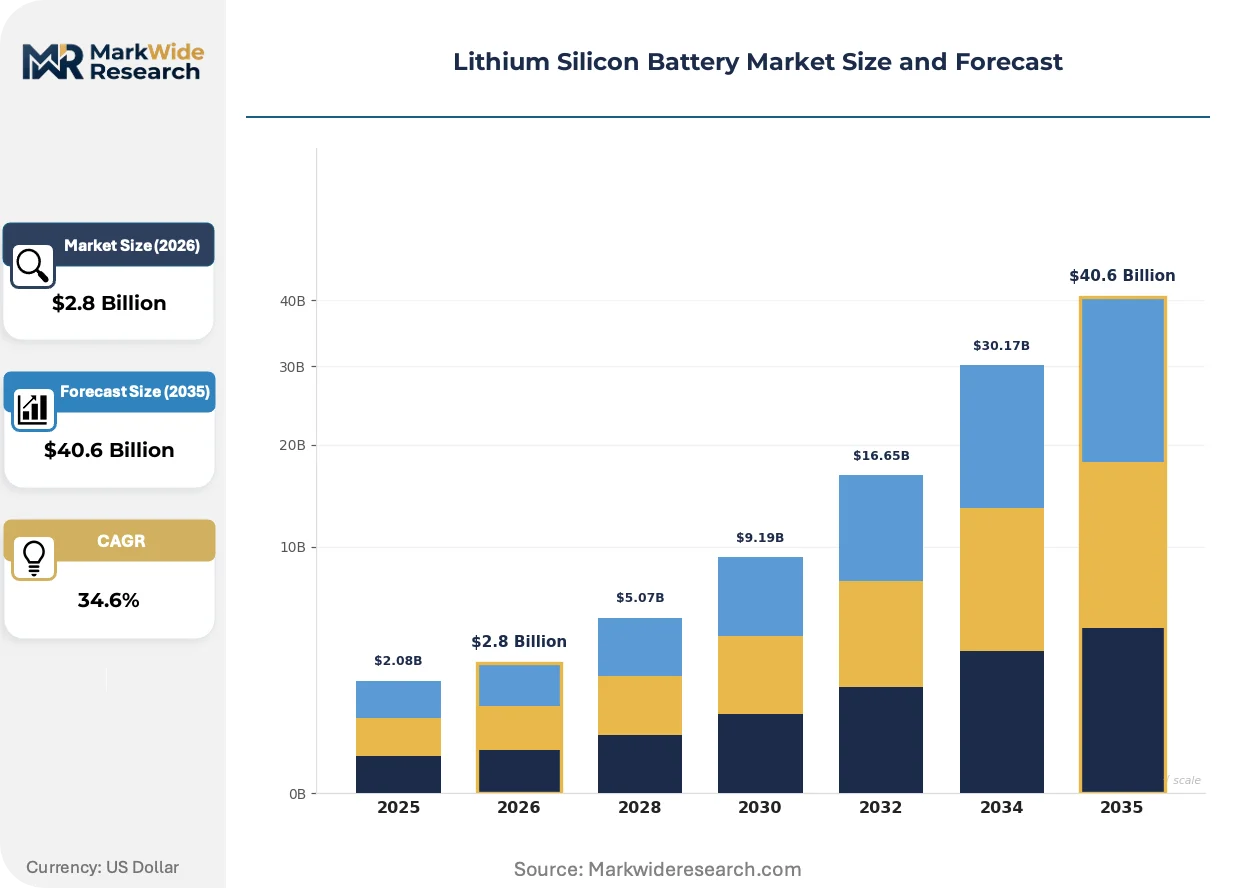
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $40.6 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical Cells, Prismatic Cells, Pouch Cells, Coin Cells End User: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Industrial Applications Technology: Lithium-ion, Solid-state, Thin-film, Hybrid Systems Application: Portable Devices, Electric Power Tools, Electric Bicycles, Aerospace |
| Companies Covered | Enevate Corp., Nexeon Ltd., Amprius Technologies Inc., LG Energy Solution, Contemporary Amperex Technology Co. Limited, Enovix Corp., Group14 Technologies Inc., Panasonic Holdings Corp., Sila Nanotechnologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Silicon Battery Market Emerging Trajectories
Silicon-anode architectures are diverging along performance-versus-cost tradeoffs, with aviation and satellite applications pulling toward nanowire platforms while automotive procurement favors silicon-carbon composite cost structures.
Pre-lithiated silicon oxide anodes are converging with dry electrode coating processes to eliminate solvent recovery infrastructure and compress manufacturing footprints. European cell producers pilot this combination for next-generation cylindrical formats. The pairing enables energy densities above 350 Wh/kg while reducing capex intensity for gigafactory expansions.
The EU Battery Regulation's recycled content disclosure mandates are forcing anode suppliers to document silicon provenance from mining through refining. Germany's KBA coordinates with ECHA to align vehicle-type approval with material passport requirements. Cell makers serving German automotive integration hubs now require batch-level traceability certifications from silicon precursor vendors.
Electric vehicle OEMs are consolidating cell procurement around long-term offtake agreements that specify anode chemistry roadmaps. Tier-one battery producers in South Korea negotiate five-year supply contracts that lock in silicon-carbon volume commitments. This contractual shift compresses spot market participation and favors anode material specialists with demonstrated scale-up credentials.
Lithium Silicon Battery Market Segmentation
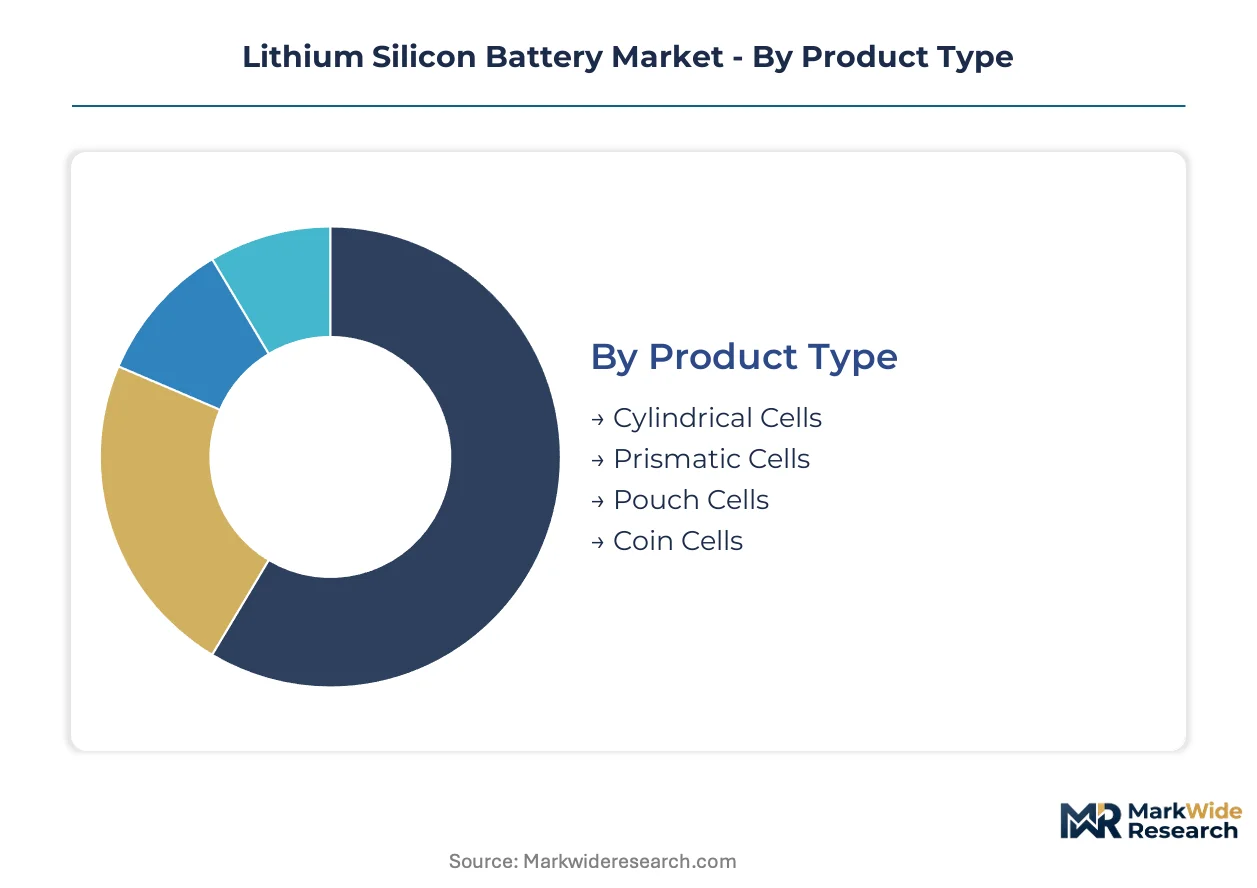
Silicon-anode battery architectures diverge sharply across form factors and thermal management requirements. Cell geometry determines pack integration complexity and manufacturing capex intensity for gigafactory operators.
Product Type:
Customization versus standardization tensions manifest most acutely in cell geometry, where aviation and automotive end-users demand opposite engineering tradeoffs.
- Pouch Cells:Laminated aluminum-polymer enclosures maximize volumetric energy density and enable non-standard dimensions for electric vehicle pack architectures. South Korean cell producers in Gyeonggi province concentrate pilot-line capacity here for premium automotive platforms.
- Cylindrical Cells:Rolled electrode jellyrolls in metal cans deliver superior thermal runaway containment and automated assembly economics. Tesla's Nevada gigafactory and Panasonic's Osaka lines anchor global cylindrical silicon-anode output for mass-market electric vehicle integration.
- Prismatic Cells:Hard-case rectangular formats optimize space utilization in Chinese electric bus and commercial vehicle battery packs.
- Coin Cells:Compact disc-shaped configurations serve laboratory qualification and small-format wearable electronics.
Most installed capacity flows through Cylindrical Cells. Expansion is steepest in Pouch Cells.
End User:
Volume concentration and margin capture split unevenly across customer categories, with automotive procurement dwarfing unit economics elsewhere.
- Electric Vehicles:Silicon-anode cells address range anxiety through 400+ Wh/kg prototypes. OEM qualification timelines at tier-one producers in South Korea and Germany compress material supplier ramp schedules to eighteen-month synchronization windows.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize cycle life over energy density, slowing silicon-anode penetration relative to automotive urgency.
- Energy Storage Systems:Grid-scale installations favor cost-per-kWh over gravimetric density, marginalizing silicon-anode value propositions.
- Industrial Applications:Forklifts and warehouse robotics demand high discharge rates that silicon-carbon composites increasingly satisfy.
Procurement volume clusters in Electric Vehicles. Margin expansion is sharpest in Industrial Applications.
Technology:
Maturity gradients separate near-term deployable platforms from architectures requiring electrolyte breakthroughs.
- Lithium-ion:Liquid electrolyte silicon-anode cells dominate commercial shipments, with pre-lithiation advances reducing first-cycle capacity loss below ten percent.
- Solid-state:Ceramic and sulfide electrolyte interfaces stress under silicon volume expansion, delaying dual-technology integration timelines.
- Thin-film:Vacuum-deposited silicon layers serve microelectronics and medical implant applications where energy density matters less than form factor flexibility.
- Hybrid Systems:Blended liquid-solid electrolyte architectures attempt to bridge manufacturing readiness with safety improvements.
Capital deployment concentrates in Lithium-ion. Patent filing velocity is highest in Solid-state.
Application:
Use-case specificity determines whether silicon-anode premiums justify performance gains over incumbent graphite systems.
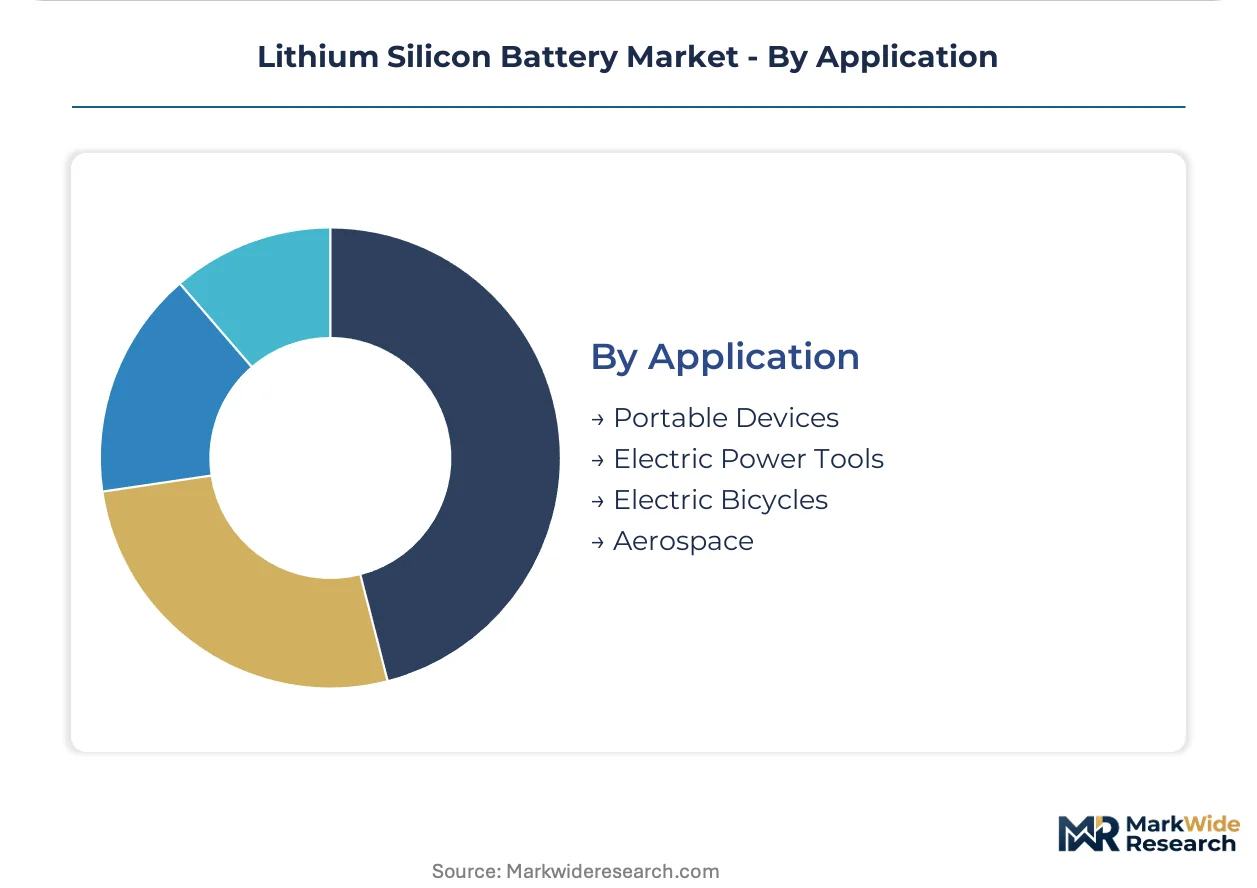
- Aerospace:FAA certification pathways for unmanned aerial systems and satellite constellations pull nanowire silicon platforms toward 500 Wh/kg targets. Amprius Technologies dominates this segment through aviation-specific cell designs.
- Electric Power Tools:High discharge rate requirements and compact handle geometries favor silicon-carbon composites in professional-grade equipment.
- Portable Devices:Smartphone manufacturers balance energy density against cycle life degradation, constraining silicon content to ten percent anode blends.
- Electric Bicycles:Price-sensitive Asian markets resist silicon-anode premiums despite range advantages.
Certification investment flows through Aerospace. Volume scaling is fastest in Electric Power Tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting silicon-anode production toward jurisdictions with streamlined certification pathways and concentrated precursor supply chains. Cost-of-compliance gaps between the EU Battery Regulation's traceability mandates and China's GB standard enforcement are accelerating facility siting decisions among material suppliers.
United States
Aviation electrification and defense satellite procurement pull nanowire silicon demand toward California and Washington state manufacturing clusters. The FAA's evolving airworthiness directives for unmanned aerial systems create certified market access that European competitors struggle to replicate. Amprius Technologies anchors aviation-specific cell production in the San Francisco Bay Area.
Germany
Automotive OEM qualification timelines compress material supplier ramp schedules to eighteen-month synchronization windows for premium electric vehicle platforms. The KBA coordinates with ECHA to align vehicle-type approval with EU Battery Regulation material passport requirements. Stuttgart and Munich integration hubs now require batch-level traceability certifications from silicon precursor vendors.
China
Domestic electric vehicle manufacturers accelerate silicon-anode procurement to extend driving range in premium battery electric vehicle platforms. The NMPA enforces GB standards on thermal runaway propagation that filter foreign silicon-anode designs entering the domestic market. Jiangsu and Fujian provinces concentrate cathode-to-anode integrated cell production for export and domestic absorption.
South Korea
Gyeonggi and Ulsan provinces minimize logistics friction between anode material suppliers and tier-one cell producers through concentrated cathode cluster proximity. The MFDS battery safety standards align with automotive OEM qualification timelines. Seoul Capital Area headquarters coordinate five-year offtake agreements that lock in silicon-carbon volume commitments from material specialists.
Japan
Consumer electronics manufacturers prioritize cycle life over energy density, slowing silicon-anode penetration relative to automotive urgency in other markets. METI industrial policy supports solid-state electrolyte research that stresses under silicon volume expansion. Osaka and Nagoya manufacturing corridors maintain cylindrical cell output for mass-market electric vehicle integration through Panasonic Holdings Corp. facilities.
Lithium Silicon Battery Market Vendor Landscape
US producers anchor the aviation and satellite power tier; South Korean and Japanese specialists hold automotive integration positions through tier-one cell partnerships. The vendor base concentrates around three strategic archetypes: nanowire platform specialists, silicon-carbon composite suppliers, and integrated cell manufacturers with captive anode development. Competitive moves cluster on long-term offtake agreements and pilot-scale capacity synchronization with automotive platform launches.
Within the nanowire platform tier, Amprius Technologies Inc. and Enovix Corp. occupy positions calibrated toward energy density maximization for weight-constrained applications. Among integrated cell manufacturers, LG Energy Solution and Panasonic Holdings Corp. exemplify backward integration into silicon-anode qualification. Sila Nanotechnologies Inc. sits within the partnership-model archetype, sustaining automotive OEM relationships for Titan Silicon integration without captive cell manufacturing.
| Leading Market Players |
|---|
| Enevate Corp. |
| Nexeon Ltd. |
| Amprius Technologies Inc. |
| LG Energy Solution |
| Contemporary Amperex Technology Co. Limited |
| Enovix Corp. |
| Group14 Technologies Inc. |
| Panasonic Holdings Corp. |
| Sila Nanotechnologies Inc. |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in South Korea and China anchor silicon-anode material supply, compressing procurement cycles for automotive OEMs while extracting volume-commitment pricing premiums from tier-one cell manufacturers.
Pricing Analysis
Distributor margins in the silicon-anode supply chain have compressed as direct-to-OEM offtake agreements displace spot-market intermediation. Long-term contract pricing stratifies across aviation-certified nanowire tiers, automotive-qualified silicon-carbon composites, and industrial-grade oxide blends. Cost compression in the automotive tier is intensifying because cathode material suppliers negotiate backward integration into anode precursor refining. Consumer electronics buyers exhibit the sharpest price sensitivity, while aviation procurement accepts premium positioning for FAA-certified cell designs.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs now mandate qualified silicon-anode supply from at least two of China, South Korea, and the United States. High-purity silane gas production concentrates in Germany and the United States, exposing anode makers to geographic supply disruption. Metallurgical-grade silicon feedstock draws from polysilicon refineries serving solar panel manufacturers, creating input competition. Distribution runs through cathode cluster hubs in Gyeonggi province and integrated cell manufacturing corridors in Jiangsu.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon-anode margins are expanding as pre-lithiation process maturation reduces first-cycle capacity loss below ten percent, enabling premium positioning in electric vehicle platforms.
For Market Incumbents: Anticipate solid-state electrolyte compatibility gaps as the primary substitute threat, compressing lithium-ion silicon-anode window advantage. Lock in five-year offtake agreements with South Korean cell producers before automotive platform launches synchronize. Invest in Washington-state or Gyeonggi-province capacity additions to defend proximity advantages. Pursue FAA certification investment for unmanned aerial system cell designs to capture aviation electrification premiums. For New Entrants and Emerging Players: India's PLI scheme for cell manufacturing opens a window for silicon-anode material import demand during domestic precursor buildout. Target maritime propulsion electrification as the most penetrable segment, where ferry operators seek energy-dense pouch configurations without automotive qualification timelines. Pursue EU Battery Regulation recycled content mandates as a go-to-market angle, positioning closed-loop silicon recovery capabilities for German automotive integration hubs. For Investors and Strategic Acquirers: Valuations sit cheapest among silicon-carbon composite specialists without captive cell manufacturing partnerships. Five-to-ten-year viability hinges on demonstrated scale-up credentials and tier-one cell maker qualification timelines. Target acquisition archetypes: pre-lithiation process technology holders with pilot-scale output. Watch FAA airworthiness directive expansion for unmanned aerial systems as the inflection signal for aviation-tier revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Lithiation Process Scale-Up | Reduces first-cycle capacity loss for silicon-anode qualification at LG Energy Solution and Panasonic. |
| FAA Airworthiness Certification | Creates certified market access for Amprius Technologies in unmanned aerial systems and satellite constellations. |
| Silicon-Carbon Composite Partnership | Locks in five-year offtake agreements with automotive OEMs through Sila Nanotechnologies' Titan Silicon integration model. |
| Closed-Loop Silicon Recovery | Aligns anode material suppliers with EU Battery Regulation recycled content mandates enforced by Germany's KBA. |
| Nanowire Platform Aviation Qualification | Captures premium positioning in regional electric aircraft through Amprius Technologies' silicon nanowire architecture. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cell manufacturer procurement directors, anode material R&D leads, aviation certification specialists, and automotive platform engineers with secondary validation against SEC filings from battery producers, FAA airworthiness directive databases, EU Battery Regulation implementation guidance, and China's NMPA GB standard enforcement records. Bottom-up cell shipment forecasts and top-down electric vehicle production projections were triangulated against cathode material demand models.
Segment-weighting approaches distributed value and volume across pouch, cylindrical, and prismatic form factors, with electric vehicle, consumer electronics, and aerospace applications receiving distinct elasticity assumptions. Technology splits between lithium-ion and solid-state architectures were modeled with parallel investment tracking. CAGRs were derived from production ramp schedules at tier-one cell manufacturers and automotive platform launch timelines. Pre-lithiation process maturation curves and silicon-anode qualification status at South Korean and German cell producers served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA thermal runaway propagation standard enforcement delays or solid-state electrolyte breakthrough timelines. Forecasts reflect assumptions regarding aviation electrification mandate acceleration and EU Battery Regulation traceability implementation. Deviation in metallurgical-grade silicon feedstock competition from solar panel manufacturers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Sodium Battery Electrolyte Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Bangladesh Lithium-Ion Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
18650 Lithium Battery for Electric Vehicle Market
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Silicon Anode Battery Market
Lithium-ion Battery
United Kingdom Electric Vehicle Battery Anode Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
EV All-Solid-State Battery Market