
 Li Air Battery Market | 2026-2036
Li Air Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Li Air Battery Market Outlook
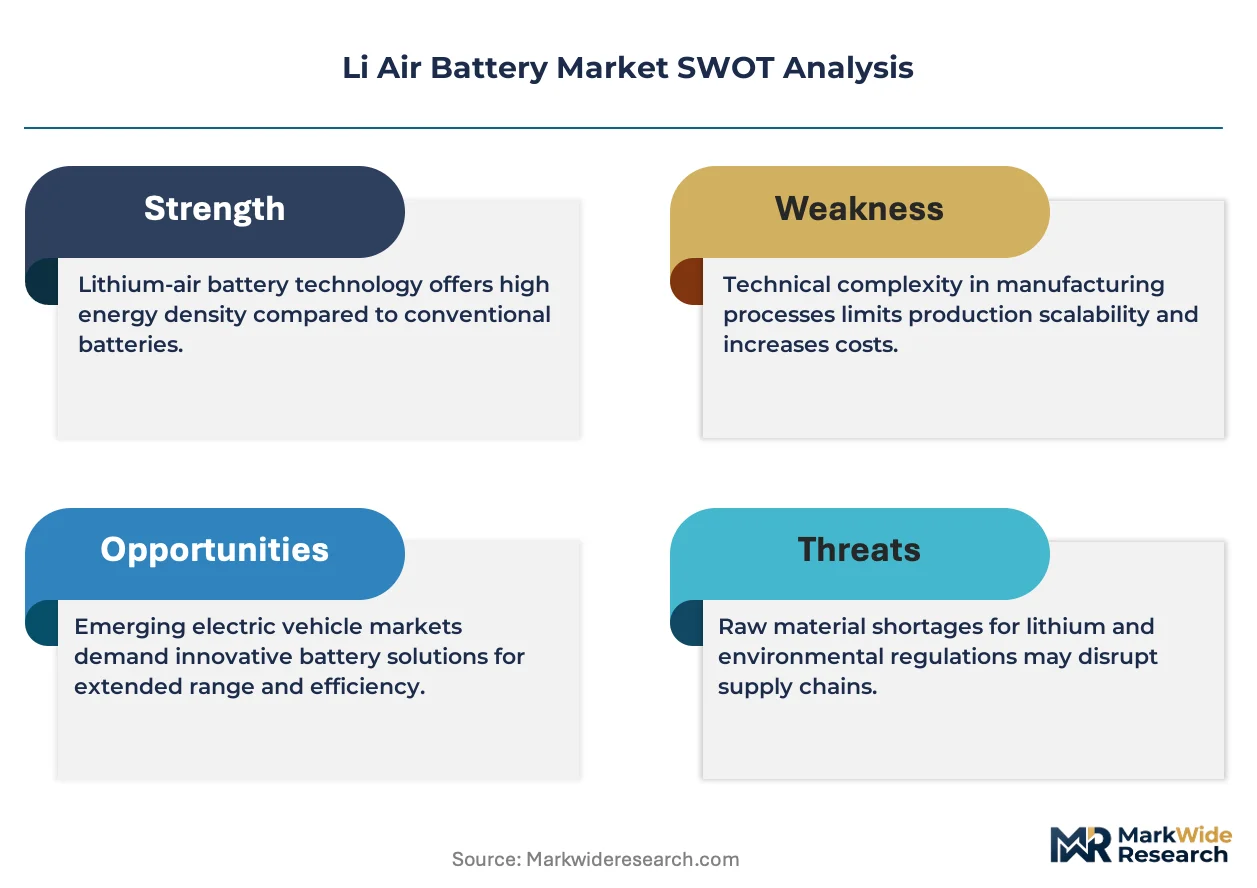
The EU Battery Regulation is restructuring the cost-of-entry calculus for Li air commercialization by mandating recycled content thresholds and carbon footprint declarations at the cell level. Toyota Motor Corporation leverages its solid-state electrolyte heritage to anchor prototype development in controlled-atmosphere fabrication. BMW AG differentiates through upstream control over lithium-sulfur precursor supply chains for hybrid cathode architectures.
A Li air battery electrochemically reduces oxygen at the cathode using metallic lithium at the anode, achieving theoretical energy densities exceeding 3,500 Wh/kg in non-aqueous configurations. The architecture stores energy through formation of lithium peroxide or lithium oxide discharge products, targeting range-critical applications where gravimetric performance dominates volumetric constraints. Cylindrical formats currently lead pilot manufacturing due to established winding equipment compatibility and pressure-sealing maturity. Solid-state technology represents the fastest-growing segment as polymer-ceramic composite electrolytes suppress dendrite penetration and extend cycle life beyond liquid analogues.
The EPA tailpipe emission standards and NHTSA CAFE requirements in the United States compress the commercialization window by penalizing fleet-average CO2 output. EMA and REACH compliance in Europe adds material qualification burdens for electrolyte solvents and binder chemistries. Stakeholders must monitor which regulatory jurisdiction first certifies a rechargeable Li air cell for automotive integration, as that determination will redirect capital flows and pilot production location decisions.
Market Dynamics
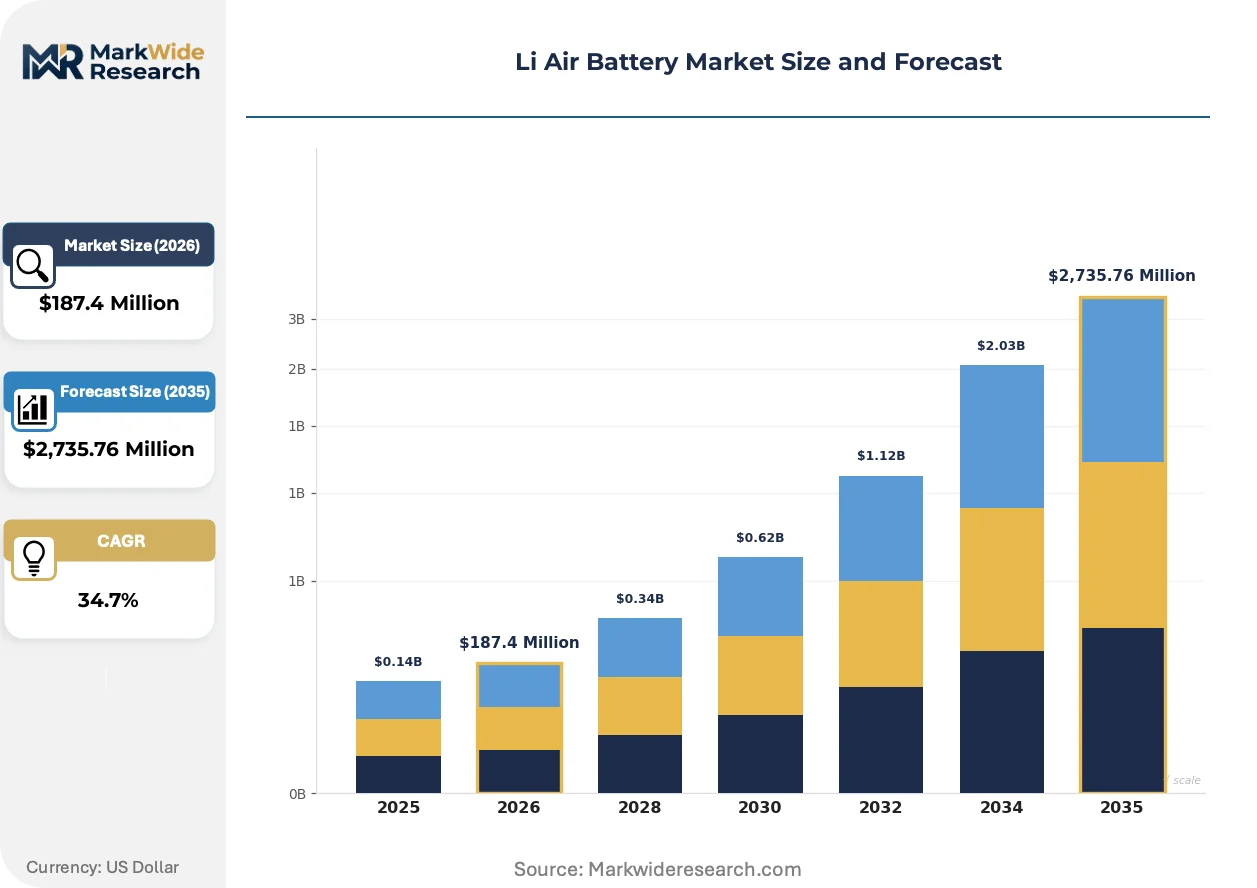
Solid-state electrolyte breakthroughs are compressing development timelines for commercial prototypes, while EU Battery Regulation mandates on recycled content and carbon footprint declarations restructure the cost-of-entry calculus for Li air commercialization.
Growth Catalysts
- REACH compliance frameworks:Material qualification requirements for electrolyte solvents and binder chemistries are accelerating standardization of safer, higher-performance chemistries across European manufacturing clusters.
- Electric vehicle range anxiety:Gravimetric energy density advantages exceeding 3,500 Wh/kg in non-aqueous configurations are pulling automotive OEMs toward pilot integration programs for next-generation powertrains.
- German applied research concentration:Stuttgart and Munich anchor dense networks of cathode architecture specialists, solid-state fabrication experts, and automotive testing facilities that shorten iteration cycles.
Market Restraints
- Lithium metal anode cost volatility:Purity requirements for dendrite-suppressing anode substrates expose developers to price swings in specialty lithium refining capacity concentrated in South American salar operations.
- Controlled-atmosphere fabrication infrastructure:Moisture-sensitive solid-state cell assembly requires dry room investments that concentrate pilot production among capital-rich tier-one suppliers.
- Cycle life technical ceiling:Lithium peroxide discharge product accumulation and electrolyte decomposition limit rechargeable cell longevity below automotive warranty thresholds.
Strategic Opportunities
- US IRA clean vehicle credits:Domestic content bonuses for battery cell manufacturing are redirecting pilot production location decisions toward North American assembly.
- Aerospace auxiliary power units:Gravimetric performance dominance opens range-critical applications in electric aviation where volumetric constraints are secondary.
- Polymer-ceramic composite convergence:Hybrid electrolyte architectures combining ionic conductivity with mechanical flexibility are unlocking cylindrical format scalability.
Industry Challenges
- Electrochemist talent scarcity:Specialized expertise in lithium-oxygen reaction mechanisms and solid-electrolyte interphase engineering concentrates among a narrow cohort of academic laboratories.
- Automotive certification timelines:UN ECE R100 and UL 2580 thermal propagation testing protocols for high-energy cells extend validation cycles beyond typical venture capital horizons.
- IP fragmentation across electrolyte patents:Dispersed ownership of ceramic-polymer interface technologies complicates freedom-to-operate assessments for integrated cell designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Li Air Battery Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,735.76 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Flexible, Pouch Technology: Hybrid, Solid-State, Liquid, Nano Application: Electric Vehicles, Energy Storage, Consumer Electronics, Aerospace End User: Manufacturers, Research Institutions, Retailers, Governments |
| Companies Covered | Mullen Technologies, Inc, Toyota Motor Corporation, Tesla, Inc, Poly Plus Battery Co, Lithium Air Industries, Inc, BMW AG, Ford Motor Company, IBM Corporation, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Li Air Battery Market Strategic Shifts
Electrolyte chemistry convergence and fabrication process maturation are actively reshaping competitive positioning in Li air development, with solid-state architectures overtaking liquid analogues in pilot manufacturing priority.
Solid-state polymer-ceramic composite electrolytes are overtaking conventional liquid organic electrolytes in prototype development pipelines. Electric vehicle manufacturers are adopting these architectures for pilot cylindrical cell production due to dendrite suppression and extended cycle life. The shift is compressing commercialization timelines for automotive-qualified cells by eliminating separator flammability risks.
EPA tailpipe emission standards and NHTSA CAFE requirements are tightening fleet-average CO2 penalties for US manufacturers. These regulations are forcing accelerated electrification roadmaps that pull forward demand for next-generation battery chemistries. Heavy-duty trucking and long-range passenger vehicle segments are responding with dedicated solid-state cell qualification programs.
Buyer procurement patterns are consolidating around vertically integrated cell suppliers capable of in-house solid electrolyte synthesis. Tier-one automotive suppliers are displacing modular component sourcing with captive cathode and electrolyte production to secure supply continuity. This concentration is most visible in Germany, where BMW and Bosch anchor applied research clusters demanding direct material control.
Li Air Battery Market Segmentation
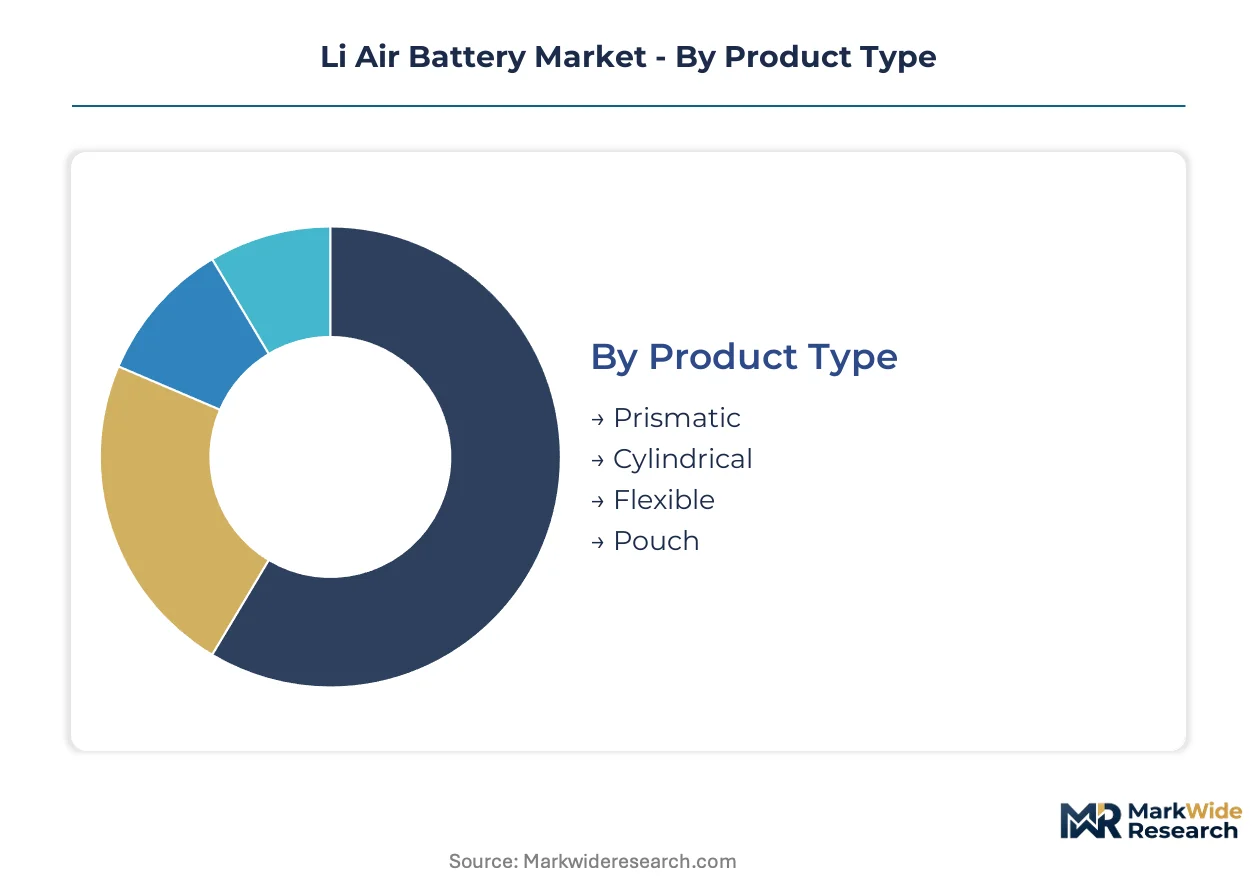
Li air battery segmentation reveals divergent capital requirements across cell architectures, with solid-state fabrication demanding dry-room infrastructure while liquid electrolyte formats leverage existing winding equipment. Understanding these investment profiles guides resource allocation for pilot production scale-up.
Product Type:
Cylindrical formats absorb the heaviest upfront tooling investment due to precision winding mandrels and pressure-sealing automation, whereas flexible architectures minimize capital barriers through roll-to-roll coating compatibility.
- Cylindrical:Established winding equipment from lithium-ion manufacturing adapts readily to Li air electrode stacks. Pilot production concentrates in Stuttgart and Munich where Bosch operates pressure-sealing lines for automotive qualification programs. The format dominates range-critical electric vehicle applications where gravimetric density outweighs packaging efficiency.
- Prismatic:Stacked electrode architecture accommodates thicker cathode layers for lithium-oxygen reaction zones. German OEMs favor this geometry for battery pack integration where volumetric efficiency competes with energy density priorities. Cell-to-pack assembly requires specialized laser welding stations that concentrate investment among tier-one suppliers.
- Pouch:Aluminum-laminate enclosures reduce mass overhead for aerospace auxiliary power units. Research institutions in Munich deploy pouch formats for rapid prototype iteration.
- Flexible:Polymer substrate compatibility enables conformal integration in wearable electronics. Thin-film deposition equipment carries lower capital thresholds than rigid formats.
Most installed capacity flows through Cylindrical. Expansion is steepest in Prismatic.
Technology:
Solid-state architectures command premium capital allocation for polymer-ceramic composite synthesis, while liquid electrolyte platforms sustain relevance through faster process qualification.
- Solid-State:Polymer-ceramic composite electrolytes suppress lithium dendrite penetration and extend cycle life. Toyota Motor Corporation anchors prototype development in controlled-atmosphere fabrication facilities. The technology pulls investment from electric vehicle manufacturers seeking automotive warranty compliance.
- Liquid:Organic carbonate solvents enable rapid ion transport but introduce flammability risks. Established supply chains for separator membranes reduce qualification timelines.
- Hybrid:Dual-phase electrolyte architectures combine ionic conductivity with mechanical flexibility. BMW AG explores hybrid cathode designs leveraging lithium-sulfur precursors.
- Nano:Structured cathode frameworks enhance lithium peroxide accommodation. Research institutions concentrate development near Stuttgart testing facilities.
Capital deployment concentrates in Solid-State. Process maturation advances most quickly in Hybrid.
Application:
Electric vehicle integration demands the steepest certification investment, while energy storage applications tolerate longer development cycles with lower regulatory burden.
- Electric Vehicles:Gravimetric energy density exceeding 3,500 Wh/kg addresses range anxiety in long-range passenger segments. EPA tailpipe standards and NHTSA CAFE requirements compress commercialization timelines. German OEMs anchor pilot programs near Munich automotive testing corridors.
- Aerospace:Auxiliary power units prioritize mass reduction over volumetric constraints. Electric aviation developers in Germany evaluate cylindrical formats for propulsion systems.
- Energy Storage:Grid-scale installations tolerate lower cycle life thresholds. Stationary applications bypass automotive thermal propagation testing.
- Consumer Electronics:Pouch and flexible formats dominate power density requirements. Retail procurement concentrates on established lithium-ion substitutes.
Validation spending concentrates in Electric Vehicles. Technical de-risking progresses fastest in Energy Storage.
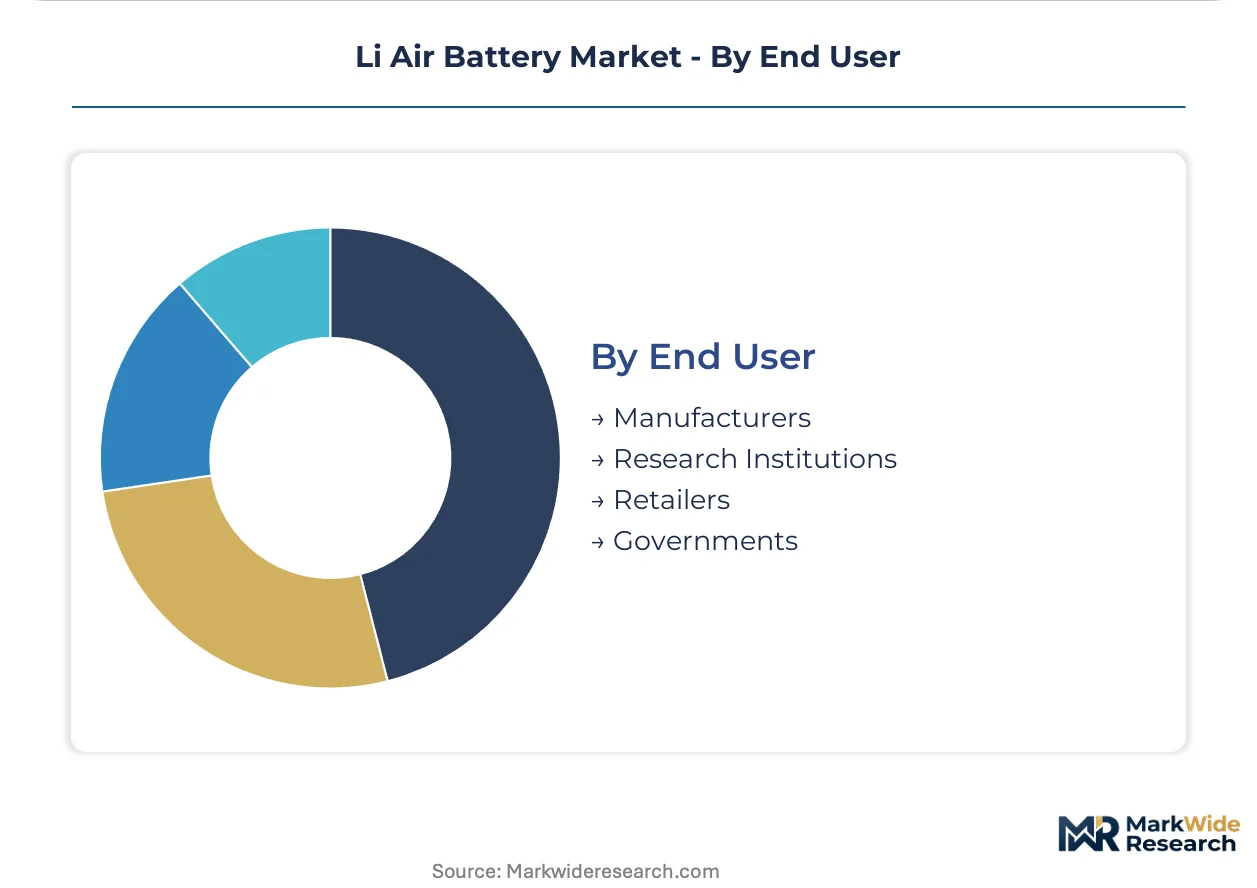
End User:
Manufacturers internalize the full capital stack from electrolyte synthesis to cell assembly, while research institutions access shared fabrication infrastructure through applied research clusters.
- Manufacturers:Vertical integration into cathode and electrolyte production secures supply continuity. BMW and Bosch in Germany demand direct material control for hybrid architectures. Tier-one suppliers concentrate pilot production near Stuttgart.
- Research Institutions:Shared dry-room facilities reduce individual capital burdens. Academic laboratories in Munich specialize in lithium-oxygen reaction mechanisms.
- Governments:Funding programs under EU Battery Regulation accelerate recycled content compliance. Public procurement favors domestic assembly qualification.
- Retailers:Distribution channels await automotive certification before inventory commitment. Consumer electronics retailers evaluate flexible format substitutes.
Capital absorption concentrates with Manufacturers. Funding velocity is highest through Governments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Li air battery development traces its applied research lineage to German automotive electrification programs, where BMW and Robert Bosch GmbH established controlled-atmosphere fabrication protocols that now anchor prototype qualification cycles across multiple jurisdictions.
Germany
Electric vehicle manufacturers anchor demand through Stuttgart and Munich research clusters. The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations at the cell level. Robert Bosch GmbH operates pressure-sealing lines for automotive qualification programs near Stuttgart, while BMW AG pursues upstream control over lithium-sulfur precursor supply chains.
United States
EPA tailpipe emission standards and NHTSA CAFE requirements compress commercialization timelines by penalizing fleet-average CO2 output. The IRA clean vehicle credits redirect pilot production location decisions through domestic content bonuses for battery cell manufacturing. Heavy-duty trucking developers in Michigan and California accelerate solid-state cell qualification programs.
Japan
Toyota Motor Corporation leverages solid-state electrolyte heritage to anchor prototype development in controlled-atmosphere fabrication facilities. METI funding programs support next-generation battery chemistry commercialization. Academic laboratories in Nagoya specialize in lithium-oxygen reaction mechanisms and solid-electrolyte interphase engineering.
China
MIIT dual carbon goals accelerate electrification roadmaps across heavy-duty trucking and long-range passenger vehicle segments. GB standards for high-energy cell safety create qualification pathways for automotive integration. Research institutions in Beijing and Shanghai evaluate cylindrical formats for electric aviation propulsion systems.
South Korea
MFDS material qualification frameworks for electrolyte solvents accelerate standardization of safer chemistries across manufacturing clusters. National funding programs under the K-battery strategy concentrate cathode architecture development in Seoul and Busan. Samsung SDI and LG Energy Solution anchor pilot production for hybrid electrolyte architectures.
Li Air Battery Market Competitive Environment
The competitive structure tilts toward automotive-incumbent archetypes with captive research infrastructure. Development concentrates among capital-rich tier-one suppliers capable of dry-room investments for moisture-sensitive solid-state cell assembly. Three archetypes dominate: vertically integrated OEMs with in-house electrolyte synthesis, tier-one automotive suppliers with pressure-sealing automation, and research institutions with shared fabrication facilities. Competitive moves center on strategic partnerships for cathode precursor supply and geographic expansion toward IRA-compliant North American assembly.
Among automotive-incumbent developers, Toyota Motor Corporation, BMW AG, and Robert Bosch GmbH occupy distinct positions within the competitive hierarchy. Toyota exemplifies the solid-state heritage archetype through controlled-atmosphere fabrication capabilities. BMW AG represents the upstream-control model through direct material sourcing for hybrid cathode architectures. Robert Bosch GmbH anchors the tier-one supplier archetype with pressure-sealing automation for cylindrical format qualification.
| Leading Market Players |
|---|
| Mullen Technologies, Inc |
| Toyota Motor Corporation |
| Tesla, Inc |
| Poly Plus Battery Co |
| Lithium Air Industries, Inc |
| BMW AG |
| Ford Motor Company |
| IBM Corporation |
| Robert Bosch GmbH |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed research consortia in Germany and Japan anchor upstream electrolyte precursor production, compressing margin capture for private developers while concentrating pricing power among capital-rich tier-one automotive suppliers capable of dry-room infrastructure deployment.
Pricing Analysis
Three-tier pricing structure across automotive-qualified, industrial-prototype, and research-grade cell levels dominates commercial transactions. Price differentiation separates UL 2580-certified automotive cells from unqualified laboratory batches, with volume scale and controlled-atmosphere fabrication yield as secondary tiering factors. Cost compression in research-grade tiers intensifies because shared dry-room facilities reduce individual capital barriers. Electric vehicle manufacturers exhibit lowest price sensitivity due to range-critical performance requirements, while energy storage developers demonstrate highest sensitivity as cycle life thresholds remain unproven.
Supply Chain Analysis
Specialized lithium metal freight from Chilean salar operations and ceramic-polymer composite electrolyte shipments from German fabrication clusters constitute the dominant logistics cost components. Raw material sourcing draws from South American lithium carbonate, Japanese ceramic powder specialists, and South Korean polymer substrate manufacturers. Single-source vulnerability concentrates in high-purity lithium metal refining capacity. Distribution runs through captive cathode synthesis facilities operated by BMW and Bosch near Stuttgart, with secondary channels feeding research institutions through Munich shared infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Li air battery market functions as a stable compounder anchored by automotive electrification mandates that pull forward demand regardless of near-term cycle life limitations.
For Market Incumbents: Acquire controlled-atmosphere fabrication assets in IRA-compliant North American jurisdictions to preempt domestic content bonus capture. BMW and Bosch should deepen backward integration into lithium-sulfur precursor supply chains before South Korean competitors consolidate cathode architecture patents. Solid-state electrolyte IP fragmentation presents acquisition targets among Nagoya academic laboratories. For New Entrants and Emerging Players: Solid-state polymer-ceramic interface engineering offers entry leverage against established liquid electrolyte incumbents. Aerospace auxiliary power units represent the most penetrable application segment where automotive certification burdens do not apply. Target research institution partnerships in Munich for rapid prototype iteration before scaling toward cylindrical format automotive qualification. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-one automotive suppliers with pressure-sealing automation but without captive electrolyte synthesis. Five-to-ten year viability hinges on which jurisdiction first certifies a rechargeable cell under UN ECE R100. Monitor EPA tailpipe standard stringency adjustments as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Fabrication Scale-Up | Dry-room investments by Bosch near Stuttgart compress automotive qualification timelines. |
| Polymer-Ceramic Composite Patent Acquisition | Freedom-to-operate consolidation unlocks cylindrical format commercialization for Toyota. |
| North American IRA-Compliant Assembly | Domestic content bonuses redirect pilot production location decisions toward Michigan corridors. |
| Lithium-Sulfur Precursor Supply Agreement | Upstream control by BMW secures hybrid cathode architecture differentiation against liquid electrolyte rivals. |
| Aerospace Auxiliary Power Unit Qualification | Gravimetric performance dominance opens electric aviation propulsion markets before automotive certification completion. |
Study Parameters
Multiple input streams — primary interviews with solid-state fabrication engineers, OEM platform electrification leads, and cathode precursor procurement officers; secondary validation through EPA regulatory filings, MIIT dual carbon policy documents, and EU Battery Regulation compliance databases; plus customs records for lithium metal trade flows — were reconciled through bottom-up cell cost modeling and top-down automotive demand projection triangulation.
Data-stream reconciliation across the analysis window applied segmentation dimensions spanning cell format geometry, electrolyte technology maturity, application certification tier, and end-user integration depth. CAGRs were derived from installed capacity build-out curves weighted against automotive OEM electrification roadmap commitments. Forecast inputs incorporated solid-state cycle life improvement trajectories and dry-room capital cost depreciation schedules.
The model holds under sustained EPA and EU tailpipe emission stringency; deviation in automotive warranty threshold relaxation or lithium metal supply disruption would shift commercialization timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium-Ion Battery Metal Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Salt Lake Battery Grade Lithium Carbonate Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market