
 Lithium Polymer Battery Market | 2026-2036
Lithium Polymer Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Polymer Battery Market Outlook
High energy density tiering is unwinding across the supply base as automotive OEMs demand cells above 300 Wh/kg. CATL leverages its vertical integration into cathode precursors to secure cost positions in premium pouch formats. LG Energy Solution anchors European gigafactory output with dedicated polymer lines for German EV platforms. BYD Company Limited differentiates through blade-cell architectures that bridge lithium iron phosphate and polymer chemistries.
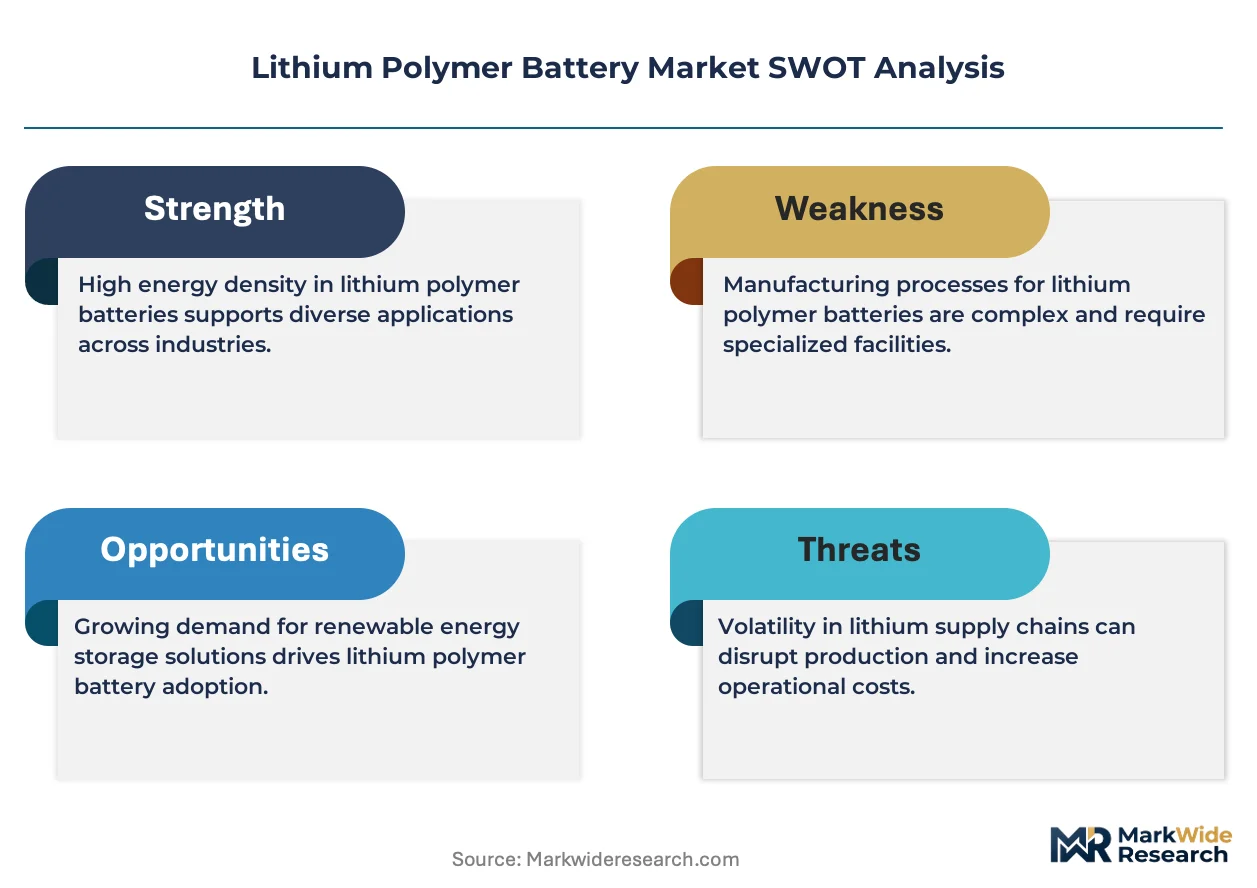
A lithium polymer battery uses a gel or solid polymer electrolyte rather than liquid electrolyte, typically packaged in flexible aluminum-laminated pouches with nominal voltages near 3.7V per cell and energy densities ranging from 150 to 300 Wh/kg depending on cathode chemistry. The technology serves applications requiring thin, lightweight, or conformal power sources where rigid cylindrical formats fail. Electric vehicles and consumer electronics represent the dominant product type segments, with EV-grade pouch cells capturing the deepest margin pools due to automotive qualification cycles and long-term supply agreements. Flexible batteries within the form factor dimension are gaining share in wearable technology applications where mechanical bending tolerance determines design viability, while hard-shell batteries retain volume in drone applications demanding structural rigidity under high-discharge loads.
China's NMPA enforces cell-level thermal runaway testing that extends certification timelines for imported polymer designs, while the EU Battery Regulation mandates recycled content disclosures and carbon footprint declarations at the module level. Japan's METI coordinates domestic solid-state polymer research with Korean suppliers through joint R&D frameworks. Stakeholders must track how solid-electrolyte interphase stability evolves against silicon-anode swelling, as this interface chemistry determines whether polymer formats retain cost advantages over prismatic alternatives in next-generation pack architectures.
Market Dynamics
Automotive OEM qualification cycles are compressing polymer cell development timelines, forcing suppliers to front-load thermal runaway validation before platform integration decisions lock in chemistry commitments for decade-long supply agreements.
Growth Catalysts
- Solid-state polymer electrolyte maturation:Korean-Japanese joint R&D frameworks under METI coordination are accelerating dry-electrode manufacturing readiness for next-generation pouch architectures.
- EU Battery Regulation recycled content mandates:Module-level carbon footprint declarations are creating certified supply chain premiums for polymer formats with documented precursor provenance.
- Drone sector energy density requirements:Hard-shell polymer derivatives are capturing high-discharge applications where cylindrical formats fail on mass-to-volume ratios.
Market Restraints
- Cathode precursor cost volatility:Nickel and cobalt price swings transmit directly to polymer cell bill-of-materials, eroding margin visibility for non-integrated manufacturers.
- China NMPA certification bottlenecks:Extended thermal runaway testing timelines for imported designs create six-to-nine month market access delays versus domestic competitors.
- Prismatic cell substitution threat:Blade-cell architectures bridging lithium iron phosphate and polymer chemistries are absorbing mid-range energy density applications.
Strategic Opportunities
- Wearable technology mechanical tolerance gaps:Flexible polymer formats with bending radii below 5mm are penetrating medical patch and fitness band designs where rigid alternatives fail.
- US IRA domestic content incentives:Critical mineral and battery component tax credits are reshoring polymer electrode manufacturing to North American assembly plants.
- Silicon-anode polymer compatibility:Solid-electrolyte interphase stabilization breakthroughs are opening 400 Wh/kg-class pouch designs for aviation propulsion applications.
Industry Challenges
- Electrolyte formulation talent scarcity:Polymer gel chemistry expertise concentrates in Korean and Japanese research institutes, constraining Western supplier R&D velocity.
- Gigafactory capex intensity:Dry-room infrastructure and coating line automation require capital commitments exceeding $500 million per terawatt-hour of annual capacity.
- Automotive platform qualification synchronization:OEM pack architecture freeze dates often precede polymer cell cycle life validation completion, forcing suppliers to assume performance risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Polymer Battery Market |
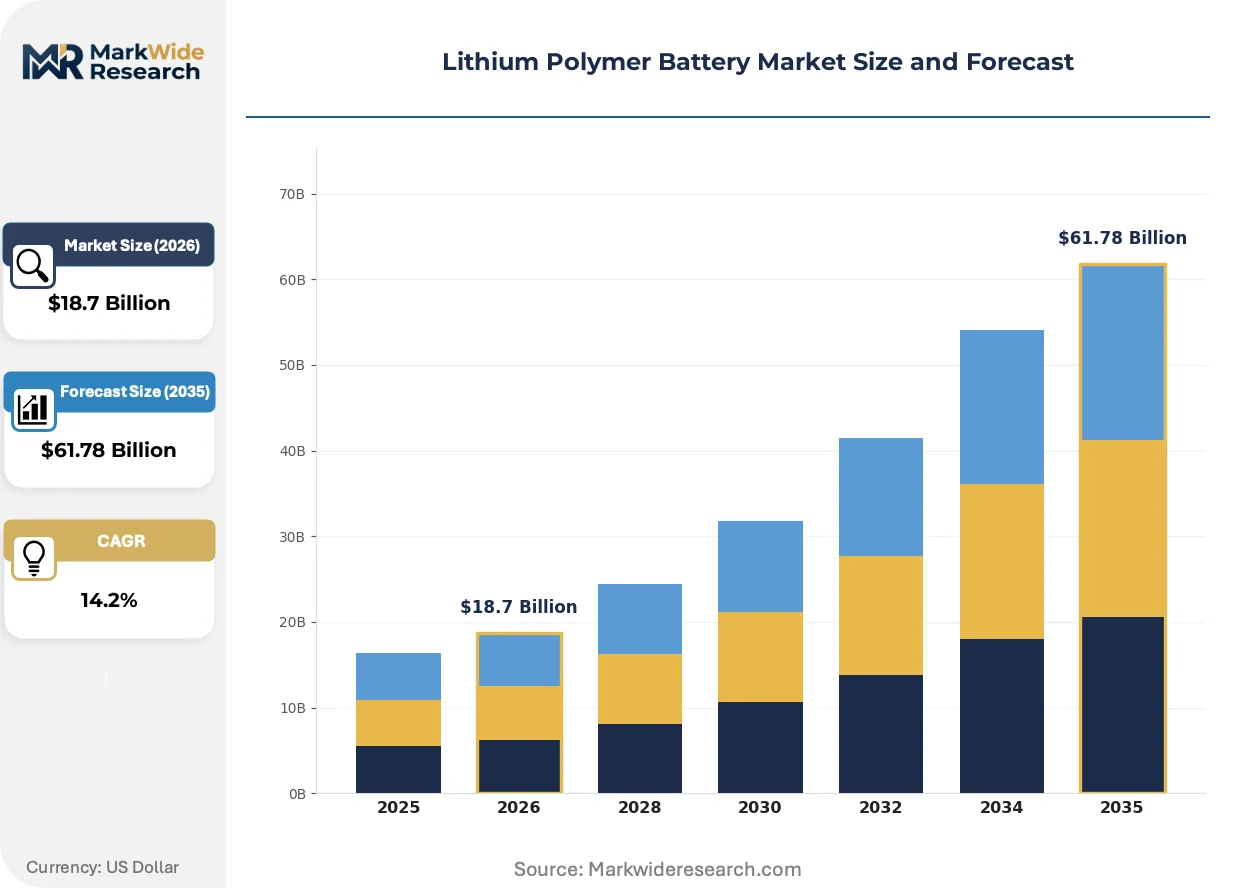
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Medical Devices End User: OEMs, Retail Consumers, Industrial Users, Government Agencies Application: Smartphones, Drones, Laptops, Wearable Technology Form Factor: Flexible Batteries, Hard-shell Batteries, Thin Film Batteries, Standard Batteries |
| Companies Covered | Contemporary Amperex Technology Co., Limited (CATL), BYD Company Limited, LG Energy Solution Ltd., Panasonic Holdings Corporation, Samsung Electronics Co., Ltd., Mitsubishi Electric Corporation, Wanxiang Group Corporation, Beijing Pride Power Battery Technology Co., Ltd., Tianneng Power International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Polymer Battery Market Strategic Shifts
Electrolyte chemistry and cell architecture are converging to redefine performance boundaries, with manufacturing process innovation outpacking traditional format distinctions and regulatory pressure accelerating disclosure standards across the value chain.
Solid-state polymer electrolytes with ceramic filler integration are supplanting conventional gel formulations in premium pouch designs. Automotive OEMs above 300 Wh/kg procurement thresholds are qualifying these architectures for 2027 platform entries. The shift is compressing liquid electrolyte market share in EV-grade segments where thermal stability margins determine pack insurance premiums.
China's NMPA cell-level thermal runaway testing protocols are extending certification timelines for imported polymer designs. Domestic manufacturers with pre-approved testing facilities are capturing six-month market access advantages. European suppliers are responding by establishing joint validation laboratories with Chinese partners to parallel-track homologation.
Long-term offtake agreements with cathode precursor suppliers are displacing spot-market procurement in polymer cell manufacturing. Tier-one automotive buyers are demanding five-year volume commitments with price collars to secure capacity allocation. Korean cathode material clusters are consolidating contract structures to favor vertically integrated cell producers with captive precursor supply.
Lithium Polymer Battery Market Segmentation
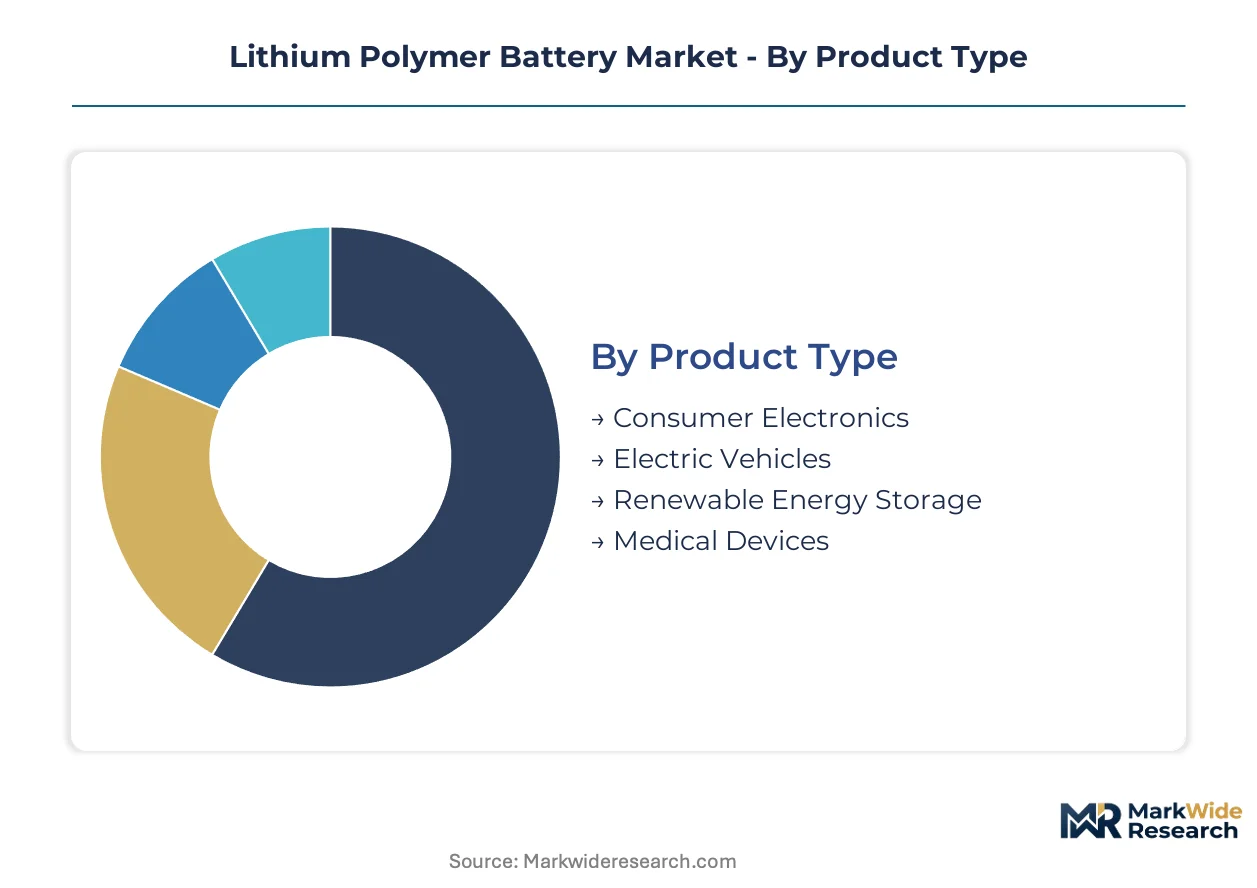
Lithium polymer battery segmentation reveals how format flexibility and energy density requirements fragment demand across incompatible use cases. Substitution threats from prismatic and cylindrical alternatives vary sharply by segment, reshaping supplier investment priorities.
Product Type:
Electric vehicle-grade cells face the most acute substitution pressure from blade-cell LFP architectures, while consumer electronics maintains polymer format lock-in due to thin-profile constraints.
- Consumer Electronics:Pouch cells dominate smartphones, tablets, and portable gaming devices where thickness below 4mm is non-negotiable. Demand concentrates in Shenzhen manufacturing corridors serving Apple and Samsung supply chains, with NMPA certification timelines creating six-month advantages for domestic suppliers.
- Electric Vehicles:Automotive OEMs specify polymer formats above 300 Wh/kg for premium platform entries, though LFP blade cells absorb mid-range energy density applications. German and Korean automakers anchor dedicated polymer lines through decade-long offtake agreements.
- Renewable Energy Storage:Grid-scale installations favor prismatic alternatives on cost-per-kWh metrics.
- Medical Devices:Implantable applications require biocompatible polymer electrolyte formulations with decade-long cycle life validation.
Consumer electronics retains volume leadership; electric vehicles holds the steepest expansion curve.
End User:
Procurement scale and qualification rigor create four distinct customer tiers with incompatible contracting structures and technical support expectations.
- OEMs:Automotive and electronics manufacturers demand five-year volume commitments with price collars and dedicated production lines. Korean cathode material clusters consolidate contract structures to favor vertically integrated cell producers with captive precursor supply.
- Industrial Users:Warehouse robotics and material handling equipment operators prioritize cycle life over energy density, accepting thicker pouch formats.
- Retail Consumers:Aftermarket replacement demand flows through e-commerce channels with minimal technical specification.
- Government Agencies:Defense and aerospace procurement mandates domestic content requirements under US IRA tax credit frameworks.
OEMs command the deepest margin pools; government agencies are expanding most quickly under reshoring incentives.
Application:
Mechanical stress tolerance and discharge rate requirements fragment the application landscape across incompatible cell architectures.
- Drones:Hard-shell polymer derivatives capture high-discharge applications where cylindrical formats fail on mass-to-volume ratios. Racing and cinematography segments in Shenzhen and Los Angeles drive 15C continuous discharge specifications.
- Wearable Technology:Flexible polymer formats with bending radii below 5mm penetrate medical patches and fitness bands where rigid alternatives fail. Japanese suppliers lead dry-electrode manufacturing readiness for conformal designs.
- Smartphones:Foldable device architectures demand polymer formats with 200,000-cycle bend tolerance.
- Laptops:Thinner profiles push toward 3mm maximum cell thickness with 60 Wh minimum capacity.
Smartphones retain volume leadership; wearable technology is gaining share fastest on medical device convergence.
Form Factor:
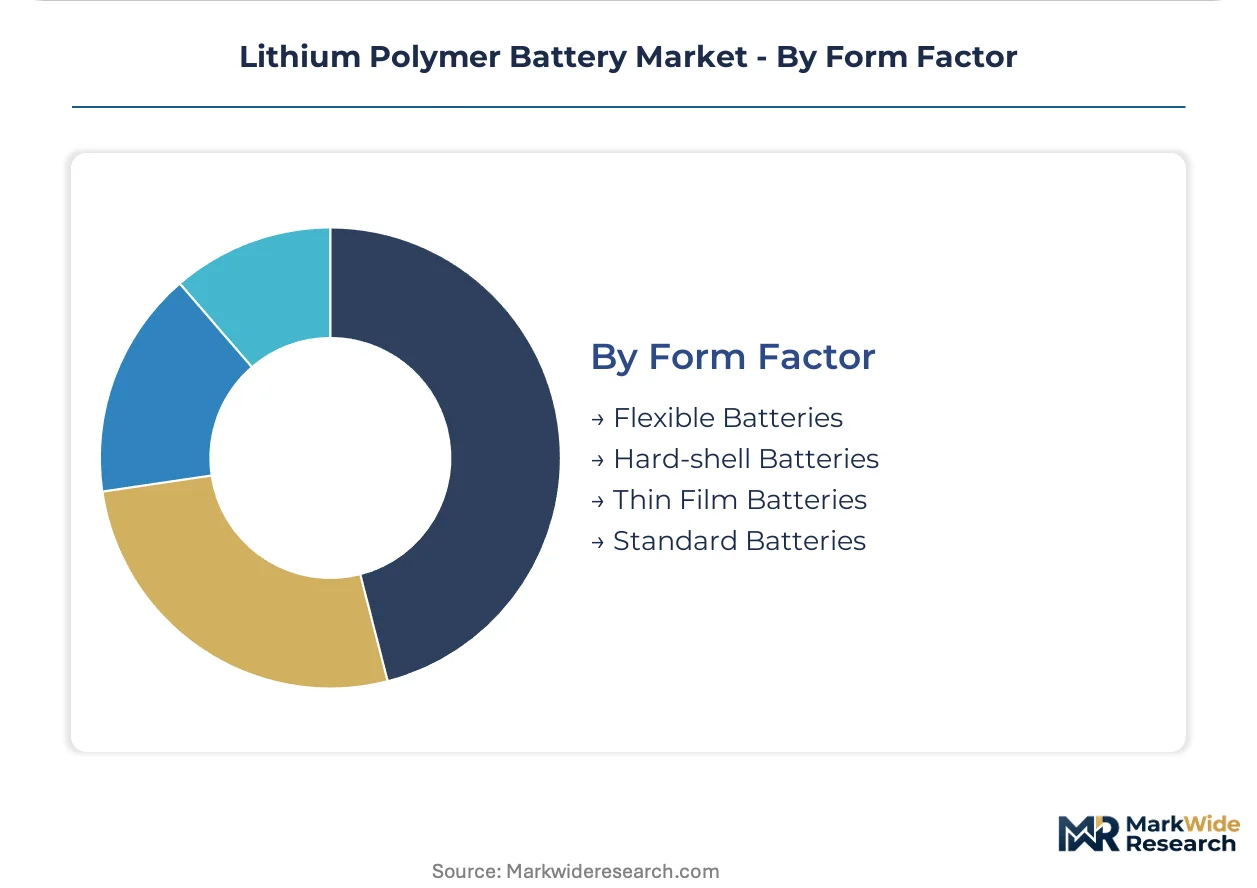
Manufacturing process maturity and automation compatibility stratify cost structures across format alternatives.
- Hard-shell Batteries:Aluminum-cased derivatives provide structural rigidity for high-discharge drone applications. Shenzhen suppliers dominate automated laser-welding production lines serving DJI and Autel Robotics.
- Flexible Batteries:Solid-state polymer electrolytes with ceramic filler integration are supplanting gel formulations in premium designs. Korean-Japanese joint R&D frameworks under METI coordination accelerate manufacturing readiness.
- Thin Film Batteries:Micro-scale polymer formats serve RFID and smart card applications with sub-1mm profiles.
- Standard Batteries:Conventional pouch formats retain cost advantages in consumer electronics with established coating line infrastructure.
Standard batteries retain volume leadership; flexible batteries hold the steepest expansion trajectory on solid-state maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping lithium polymer battery trade flows, with manufacturing capacity concentrating in East Asian production corridors while European and North American demand outpaces domestic supply. China's NMPA certification timelines create six-month access advantages for domestic producers over importers. German automakers and US defense contractors are accelerating reshoring timelines under regulatory pressure.
China
CATL and BYD absorb the majority of global automotive pouch cell demand through Shenzhen and Ningbo manufacturing corridors. NMPA thermal runaway testing protocols extend certification timelines for imported designs, privileging domestic suppliers with pre-approved facilities. The Yangtze River Delta cathode precursor clusters feed captive supply chains that compress cell-grade production costs below import parity.
South Korea
LG Energy Solution anchors European gigafactory output through dedicated polymer lines for German EV platforms. METI-coordinated joint R&D frameworks with Japanese partners accelerate solid-state electrolyte manufacturing readiness. The Gwangju cathode material clusters consolidate long-term offtake agreements that favor vertically integrated cell producers with backward integration into precursor supply.
Germany
BMW and Volkswagen procurement teams specify polymer formats above 300 Wh/kg for 2027 premium platform entries. EU Battery Regulation recycled content mandates and carbon footprint declarations at module level create certified supply chain premiums. The North Rhine-Westphalia industrial corridor hosts validation laboratories where European suppliers parallel-track NMPA homologation with Chinese partners.
United States
Defense and aerospace procurement mandates under IRA tax credit frameworks prioritize domestic content in polymer electrode manufacturing. FAA drone certification pathways favor hard-shell polymer derivatives for high-discharge cinematography applications in Los Angeles. The Pacific Northwest battery assembly plants leverage critical mineral tax credits to reshore electrode coating operations from Asian suppliers.
Japan
Panasonic and Mitsubishi Electric coordinate solid-state polymer research through METI-funded joint frameworks with Korean suppliers. PMDA biocompatibility requirements for implantable medical devices drive decade-long cycle life validation for conformal pouch formats. The Kanto region dry-electrode manufacturing readiness programs target 400 Wh/kg-class aviation propulsion applications with silicon-anode compatibility.
Lithium Polymer Battery Market Competitive Environment
Concentration sits with Asian conglomerates possessing captive cathode precursor supply and decade-long automotive qualification track records. The vendor base stratifies across three tiers: vertically integrated producers with in-house precursor control, cell specialists dependent on spot-market cathode procurement, and regional assemblers serving aftermarket replacement demand. Two dominant competitive moves are reshaping positioning: Korean-Japanese joint R&D frameworks accelerating solid-state electrolyte maturation, and European suppliers establishing Chinese validation laboratories to compress NMPA homologation timelines.
Among China-based producers, Contemporary Amperex Technology Co., Limited and BYD Company Limited occupy positions exemplifying the vertically integrated archetype with upstream control over cathode precursors. LG Energy Solution Ltd. represents the Korean specialist tier anchoring European automotive supply through dedicated gigafactory polymer lines. These three entities collectively illustrate how geographic concentration in East Asian production corridors combines with regulatory certification advantages to determine competitive access in premium EV-grade segments.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited (CATL) |
| BYD Company Limited |
| LG Energy Solution Ltd. |
| Panasonic Holdings Corporation |
| Samsung Electronics Co., Ltd. |
| Mitsubishi Electric Corporation |
| Wanxiang Group Corporation |
| Beijing Pride Power Battery Technology Co., Ltd. |
| Tianneng Power International Limited |
| Others |
Value Chain & Pricing Dynamics
Silicon-anode compatibility breakthroughs are displacing graphite-dependent polymer architectures, simultaneously shifting procurement gravity toward Korean-Japanese dry-electrode clusters and compressing margin structures for liquid-electrolyte legacy producers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with five-year volume commitments and price collars. Three-tier pricing structure across premium, standard, and economy levels separates automotive qualification-grade cells from consumer electronics and aftermarket replacement tiers. Cost compression in standard-tier pouch formats is intensifying because nickel and cobalt precursor volatility transmits directly to non-integrated manufacturers. Aftermarket retail consumers exhibit highest price sensitivity; automotive OEMs with captive precursor supply demonstrate lowest.
Supply Chain Analysis
Malacca Strait container throughput underwrites cathode precursor transit from Indonesian nickel processing to Chinese coating lines. Manufacturing concentrates in China, South Korea, and Japan with raw material dependencies on Australian lithium spodumene, Chilean carbonate, and DRC cobalt. Single-source vulnerability sits with Yangtze River Delta precursor clusters serving CATL and BYD captive supply. Distribution runs through Shenzhen electronics corridors and Korean automotive export channels to European gigafactory assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Application fragmentation across drones, wearables, and aviation propulsion creates specialty-format niches as foldable device architectures and medical patch designs outpace standard pouch commoditization.
For Market Incumbents: Fortify thermal runaway validation capabilities ahead of NMPA protocol expansions and anchor European carbon footprint certification premiums through module-level recycled content documentation. Blade-cell LFP substitution threatens mid-range energy density applications; backward integration into cathode precursors preserves margin visibility against spot-market volatility. For New Entrants and Emerging Players: Anchor in wearable technology mechanical tolerance gaps where bending radii below 5mm disqualify rigid alternatives, particularly medical patch and fitness band segments. Aviation propulsion silicon-anode compatibility offers penetrable white-space with 400 Wh/kg-class performance thresholds. Pursue Korean-Japanese joint R&D framework participation for dry-electrode manufacturing readiness. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrode coating specialists lacking captive precursor supply. Five-to-ten-year viability hinges on solid-state electrolyte maturation trajectories and automotive platform qualification track records. Monitor silicon-anode solid-electrolyte interphase stability breakthroughs as inflection signal for polymer format cost advantage retention against prismatic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Electrolyte Scale-Up | Dry-electrode manufacturing readiness under METI coordination accelerates premium pouch qualification for German OEM platforms. |
| Cathode Precursor Backward Integration | Captive nickel-cobalt supply chains insulate margin structures against London Metal Exchange volatility transmission. |
| NMPA Joint Validation Laboratory | European-Chinese parallel-track homologation compresses six-month certification delays for imported polymer designs. |
| Silicon-Anode Interface Stabilization | Solid-electrolyte interphase chemistry breakthroughs unlock aviation propulsion applications above 400 Wh/kg energy density. |
| EU Battery Regulation Compliance | Module-level carbon footprint declarations create certified supply chain premiums for documented precursor provenance. |
Study Parameters
A spread of perspectives from cell manufacturing executives, cathode precursor procurement leads, automotive platform engineers, and regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against NMPA filing databases, EU Battery Regulation implementation guidance, METI-funded R&D disclosure records, and customs trade flow data. Bottom-up cell production estimates triangulated against top-down automotive demand projections.
Product type, application, form factor, and end-user procurement tier segmentation anchored the analytical framework across the projection horizon. CAGRs derived from installed capacity buildout trajectories, platform entry timing, and substitution elasticity between polymer and prismatic formats. Silicon-anode cycle life validation curves and solid-state electrolyte manufacturing yield assumptions informed technology adoption curves.
Decision-makers should treat outputs as directional under continued NMPA certification timeline stability and precursor cost volatility within historical bands; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU recycled content mandates and US IRA domestic content incentives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Battery Metal Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market