
 North America Lithium-Ion Battery Separator Market | 2026-2036
North America Lithium-Ion Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lithium-Ion Battery Separator Market Outlook
Automotive OEM procurement is pivoting toward fewer, larger separator contracts as EV production scales. Celgard LLC leverages its North Carolina manufacturing base to supply domestic gigafactories. Asahi Kasei Corp. anchors the premium ceramic-coated segment through its wet-process technology leadership. Entek International LLC dominates the dry-process polyethylene niche for energy storage applications.
A lithium-ion battery separator is a microporous membrane, typically 10-30 micrometers thick, composed of polyethylene, polypropylene, or composite layers that electrically isolates anode and cathode while permitting ion transport. Wet-process separators achieve finer pore structures down to 0.03-0.1 micrometers through biaxial stretching of ultra-high molecular weight polyethylene, making them essential for high-energy-density automotive cells. The electric vehicle end user commands the largest volume share as OEMs specify thicker tri-layer composites for thermal shutdown protection. Coating technology represents the fastest-expanding segment because ceramic and PVDF layers command margin premiums over base membranes.
The Inflation Reduction Act, EPA automotive emissions standards, and NHTSA battery safety regulations collectively mandate domestic sourcing and stricter thermal runaway containment. These frameworks compel separator suppliers to certify North American production lines and validate abuse-test performance. Stakeholders must monitor how proposed FERC grid-storage interconnection rules reshape industrial equipment demand for separators.
Market Dynamics
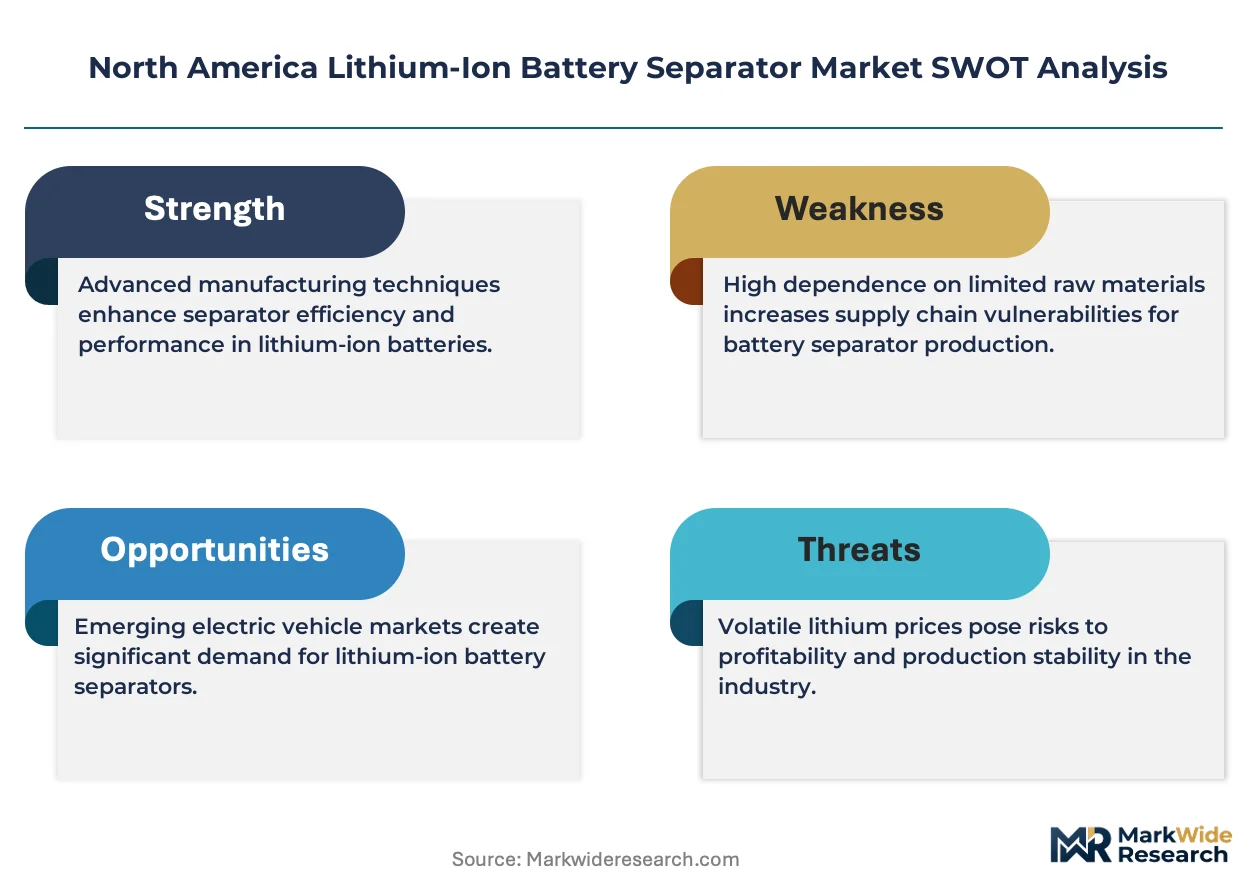
The Inflation Reduction Act's domestic content bonus credit is compressing separator supply chains into US-Mexico manufacturing corridors, forcing foreign suppliers to localize wet-process capacity or forfeit automotive OEM contracts.
Growth Catalysts
- IRA Production Tax Credits:The Inflation Reduction Act's $35 per kWh cell credit requires North American separator sourcing, compelling gigafactory builders to qualify domestic membrane suppliers.
- EPA Fleet Emissions Standards:The EPA's proposed light-duty vehicle rules through 2032 mandate steep CO2 reductions, locking OEMs into EV platforms that specify ceramic-coated separators for thermal stability.
- Texas-Mexico Battery Corridor:Concentrated cathode and cell investments across Austin, Monterrey, and Laredo create localized demand pull for regional separator logistics.
Market Restraints
- Ultra-High Molecular Weight Polyethylene Concentration:Base resin supply concentrates among three global chemical producers, exposing separator makers to feedstock allocation constraints.
- Wet-Process Capital Intensity:Stretching and extraction equipment for sub-0.1 micrometer pore structures requires $200M+ per line, freezing out mid-scale entrants.
- Polypropylene Substitution in Storage:Dry-process polypropylene membranes retain cost advantage in grid-scale lithium iron phosphate cells, capping polyethylene penetration in stationary applications.
Strategic Opportunities
- Quebec Hydropower Feedstock:Canadian UHMWPE production powered by low-carbon hydroelectricity qualifies for IRA clean manufacturing bonuses, attracting separator precursor investments.
- Solid-State Interface Layers:Next-generation sulfide electrolyte cells require modified ceramic-polymer composite separators, opening premium tier above conventional lithium-ion.
- Direct OEM Contracting:Bypassing cell makers to supply separators directly to automotive qualification labs shortens validation cycles and captures specification influence.
Industry Challenges
- Abuse Test Certification Timelines:NHTSA nail penetration and crush protocols demand 18-24 month validation cycles, delaying revenue recognition for new coating formulations.
- Process Engineer Scarcity:Biaxial stretching expertise for 10-30 micrometer membrane control resides with aging specialists in Japanese and Korean supplier bases.
- Legacy Equipment Retrofit Costs:Converting dry-process lines to hybrid ceramic coating capacity requires furnace and slurry system overhauls that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lithium-Ion Battery Separator Market |
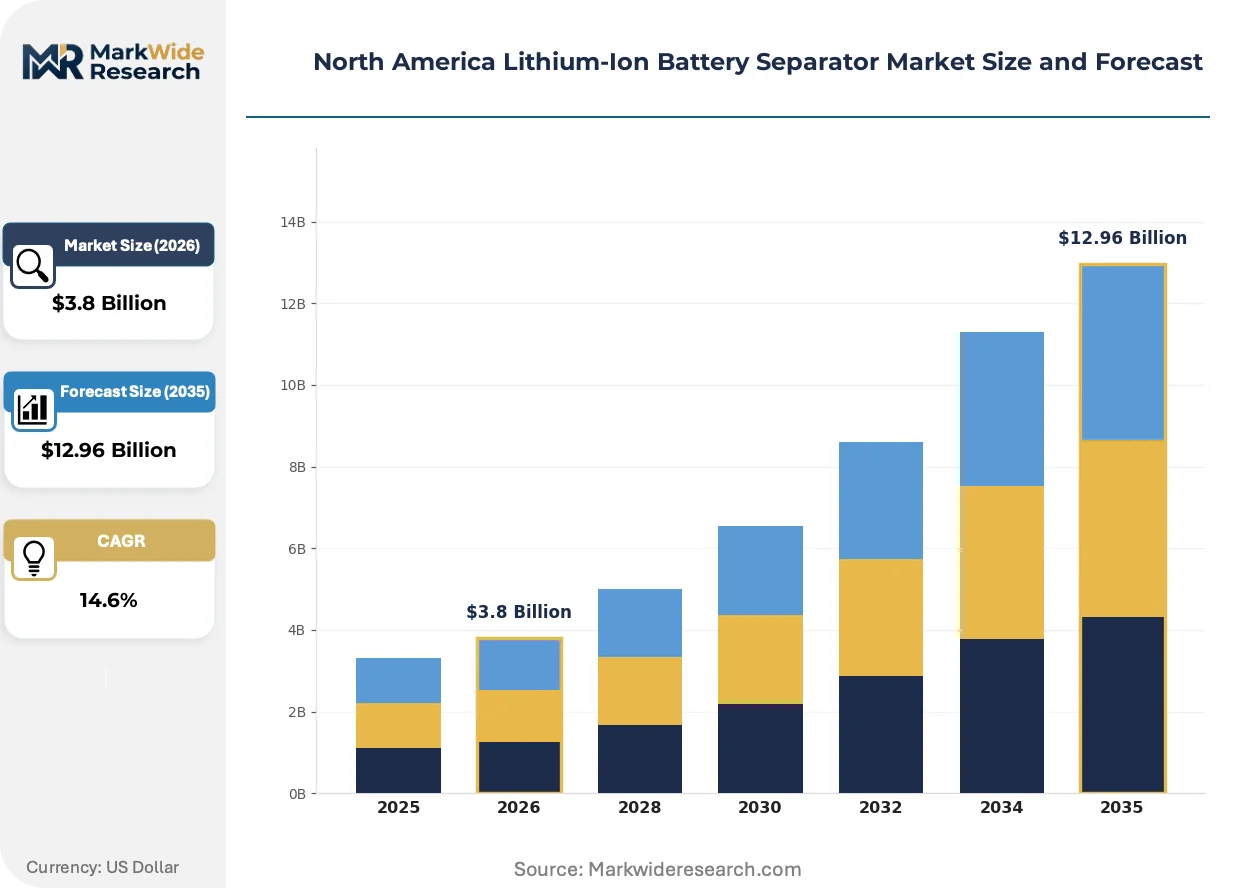
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Composite, Others End User: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Industrial Equipment Technology: Dry Process, Wet Process, Coating Technology, Others Capacity: Below 50 Ah, 50-100 Ah, 100-200 Ah, Above 200 Ah |
| Companies Covered | Entek International LLC, Celgard LLC, Asahi Kasei Corp., DuPont De Nemours Inc., BASF, Sumitomo Corporation, Coperion GmbH, W-Scope Corporation, SK Innovation Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lithium-Ion Battery Separator Market Strategic Shifts
Separator technology is bifurcating between commodity dry-process supply for energy storage and precision wet-process platforms for automotive energy density targets, with coating chemistry emerging as the primary differentiation lever.
Ceramic-alumina coating on polyethylene substrates is electrifying the high-nickhel cathode segment. Automotive OEMs specify 4-7 micrometer ceramic layers for cells exceeding 300 Wh/kg. The technology is electrifying margin structures, compressing uncoated membrane suppliers into price-competitive storage niches while coating specialists capture specification premiums.
The Inflation Reduction Act's domestic content rules are restructuring qualification protocols. Cell makers must document North American separator provenance to pass OEM audit trails. The regulation most affects Korean and Japanese suppliers, who are licensing wet-process technology to US joint ventures rather than exporting finished membrane.
Automotive OEM technical teams are embedding separator specification authority previously held by cell makers. Ford, GM, and Tesla now dictate coating thickness, pore size distribution, and shutdown temperature windows in direct supplier agreements. This shift concentrates procurement leverage in Detroit, Austin, and California engineering centers, displacing distributor-mediated purchasing.
North America Lithium-Ion Battery Separator Market Segmentation
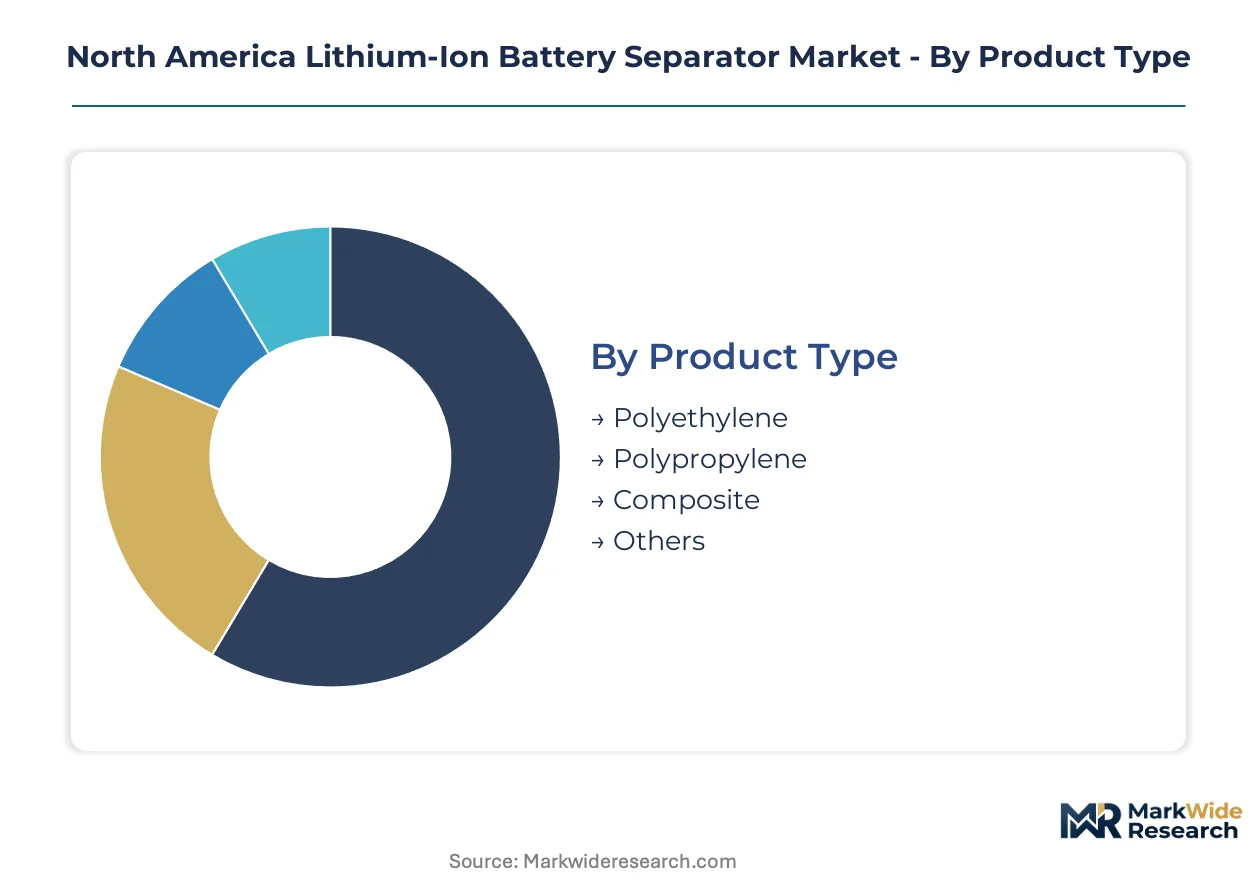
Separator procurement patterns diverge sharply across product chemistry and manufacturing process. OEM qualification protocols now segment suppliers by thermal performance thresholds rather than traditional material categories alone.
Product Type:
Polyethylene formulations demand the heaviest capital commitment, with biaxial stretching lines requiring nine-figure investments per production train.
- Polyethylene:Ultra-high molecular weight polyethylene membranes achieve sub-0.1 micrometer pore structures through solvent extraction and sequential stretching. Michigan and Tennessee gigafactories specify tri-layer polyethylene composites for NHTSA thermal runaway compliance.
- Composite:Ceramic-polymer hybrids stack alumina or boehmite layers atop polyethylene substrates, commanding specification premiums from automotive OEMs targeting 300+ Wh/kg cell energy density.
- Polypropylene:Dry-process homopolymer membranes dominate stationary lithium iron phosphate applications across Texas grid storage installations.
- Others:Aramid and cellulose-based alternatives serve niche defense and aerospace qualification pathways.
Most installed capacity flows through Polyethylene. Expansion is steepest in Composite.
End User:
Customer-type concentration determines margin structure, with direct OEM contracting displacing cell-maker intermediation.
- Electric Vehicles:Detroit Three and Tesla technical teams now specify separator coating thickness and shutdown temperature windows directly, bypassing cell maker procurement. The IRA domestic content bonus mandates North American membrane provenance for tax credit eligibility.
- Energy Storage Systems:FERC interconnection rulemakings are accelerating procurement of dry-process polypropylene separators for utility-scale lithium iron phosphate installations.
- Consumer Electronics:Thin single-layer polyethylene membranes serve smartphone and laptop cell requirements with minimal coating overhead.
- Industrial Equipment:Forklift and material handling applications specify mid-thickness polyethylene with basic ceramic treatment.
Volume concentrates in Electric Vehicles. Margin expansion is fastest in Energy Storage Systems.
Technology:
Process maturity separates incumbents from entrants, with wet-process expertise concentrated among Japanese and Korean licensing partners.
- Wet Process:Solvent-based extraction of ultra-high molecular weight polyethylene yields the finest pore structures, essential for high-nickel cathode cells. US joint ventures are localizing this capacity to satisfy IRA audit trails.
- Coating Technology:Ceramic and PVDF layer application represents the primary differentiation lever, with 4-7 micrometer alumina coatings specified for premium automotive tiers.
- Dry Process:Mechanical stretching of polypropylene avoids solvent recovery systems, lowering capital barriers for energy storage suppliers.
- Others:Electrospinning and phase inversion methods remain experimental for solid-state interface layers.
Revenue tilts toward Wet Process. Coating Technology is climbing the fastest.
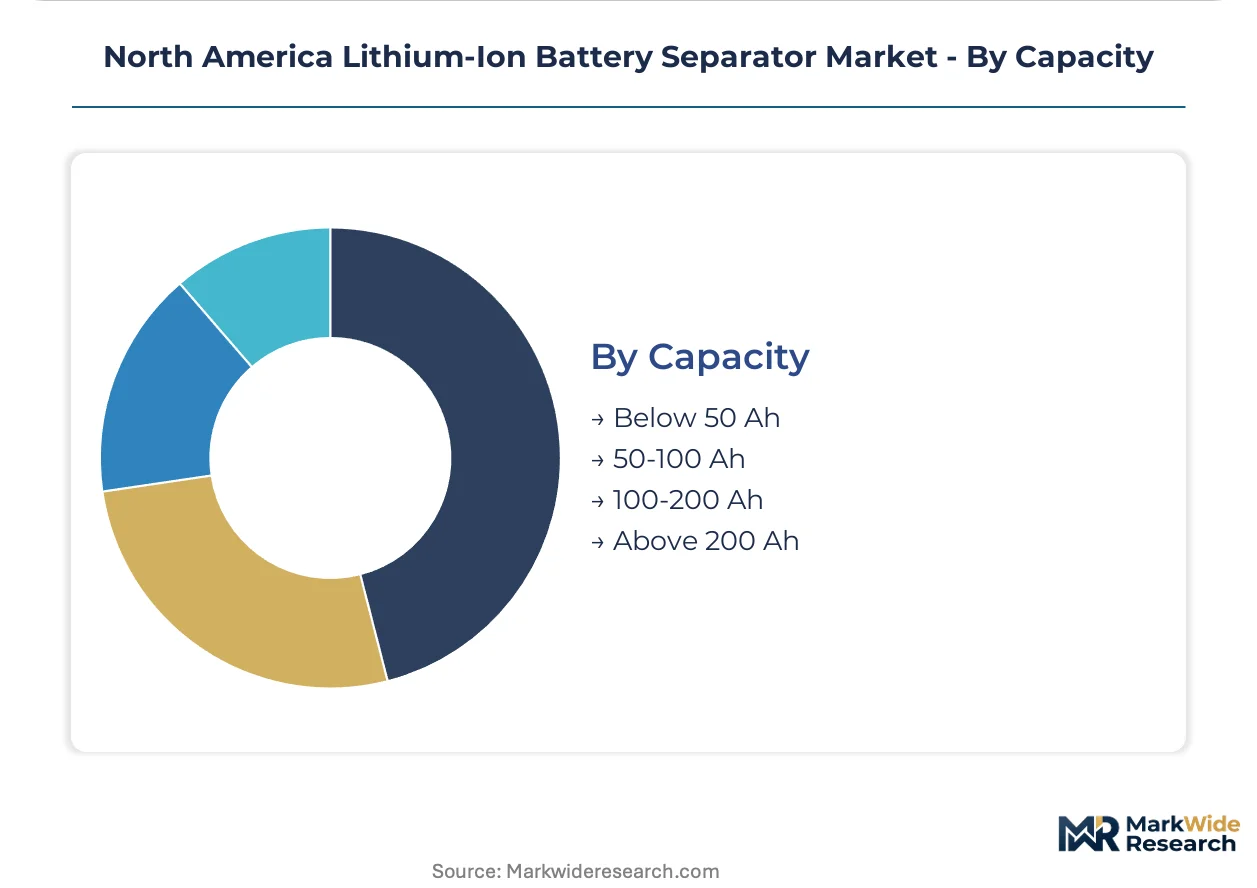
Capacity:
Cell format scale determines separator thickness and layer count, with pouch and prismatic designs driving multi-layer demand.
- Above 200 Ah:Automotive prismatic and large-format pouch cells require tri-layer polyethylene composites with ceramic coating on both faces, representing the most technically demanding specification tier.
- 100-200 Ah:Commercial vehicle and premium energy storage modules specify dual-layer polyethylene with single-side ceramic treatment.
- 50-100 Ah:Compact EV and industrial applications use standard wet-process polyethylene with minimal coating.
- Below 50 Ah:Consumer electronics and power tools rely on thin single-layer membranes with dry-process economics.
Specification authority concentrates in Above 200 Ah. Procurement volume is expanding most quickly in 100-200 Ah.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands separator demand through its gigafactory corridor, while Canada leverages hydropower-fed feedstock advantages to capture IRA clean manufacturing bonuses. Mexico anchors the southern logistics node through cathode and cell investments concentrated near the Texas border.
United States
Michigan and Tennessee host the densest concentration of cell manufacturing capacity, driving procurement of tri-layer polyethylene composites. The Inflation Reduction Act's domestic content bonus credit mandates North American membrane provenance for automotive qualification. Austin anchors the Texas battery corridor where cathode precursor investments create localized separator demand pull.
Canada
Quebec's ultra-high molecular weight polyethylene production benefits from low-carbon hydroelectricity, qualifying suppliers for IRA clean manufacturing incentives. The country's national energy regulator supports grid-scale storage deployment that specifies dry-process separators. Ontario's industrial corridor attracts separator precursor investments targeting US automotive supply chains.
Mexico
Monterrey and Laredo concentrate cathode active material investments that generate regional membrane demand. The country's proximity to Texas gigafactories shortens logistics cycles for just-in-time separator delivery. Nuevo León's manufacturing base hosts joint ventures localizing wet-process capacity to satisfy IRA audit requirements.
North America Lithium-Ion Battery Separator Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the separator value chain. The market exhibits tiered concentration with wet-process technology leaders commanding premium positioning while dry-process suppliers serve cost-sensitive storage applications. Strategic archetypes include Japanese-Korean technology licensors, US-based domestic qualification specialists, and European chemical conglomerates with backward resin integration. Capacity expansion and strategic licensing partnerships represent the dominant competitive moves as foreign suppliers localize production to capture IRA incentives.
Within the domestic qualification specialist tier, Celgard LLC and Entek International LLC exemplify US-based manufacturing archetypes. Asahi Kasei Corp. occupies a position representing premium ceramic-coated technology leadership through wet-process expertise. These three entities anchor the competitive structure across distinct process and coating specializations.
| Leading Market Players |
|---|
| Entek International LLC |
| Celgard LLC |
| Asahi Kasei Corp. |
| DuPont De Nemours Inc. |
| BASF |
| Sumitomo Corporation |
| Coperion GmbH |
| W-Scope Corporation |
| SK Innovation Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up domestic specialists anchor separator supply discipline, tightening working capital controls and enforcing contract-based offtake pricing that insulates wet-process capacity from spot resin volatility. Their consolidation of dry-process assets across the Texas-Mexico corridor feeds directly into procurement leverage against cell makers seeking IRA-compliant membrane sourcing.
Pricing Analysis
Capacity additions in Tennessee and Michigan are reshaping price floors for tri-layer polyethylene composites as domestic qualification lines absorb premium tier demand. Three-tier pricing structure across premium ceramic-coated, standard wet-process, and economy dry-process levels separates automotive OEM specifications from energy storage procurement. Cost compression in uncoated membrane tiers is intensifying because polypropylene substitution in lithium iron phosphate cells caps polyethylene penetration. Grid-scale storage buyers exhibit highest price sensitivity, while Detroit Three technical teams prioritize thermal runaway certification over unit cost.
Supply Chain Analysis
The Inflation Reduction Act's domestic content bonus is reshaping sourcing patterns toward US-Mexico manufacturing corridors and away from finished membrane imports. Feedstock supply draws from Saudi Arabia, South Korea, and Japan for ultra-high molecular weight polyethylene resin, with ceramic alumina precursors anchored in Chinese and German chemical processing. Single-source vulnerability concentrates in UHMWPE resin allocation among three global producers. Distribution runs through just-in-time logistics to gigafactory sites in Michigan, Tennessee, and Texas rather than distributor-mediated channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic coating premiums and captive resin integration are expanding margin capture for qualified suppliers, with IRA clean manufacturing bonuses accelerating cost-down trajectories for hydropower-fed Canadian feedstock operations.
For Market Incumbents: Hedge against wet-process technology licensing saturation by securing backward integration into Quebec hydropower-fed UHMWPE precursor supply. Accelerate ceramic coating furnace capacity in North Carolina and Tennessee to defend specification authority as Korean joint ventures localize production. Solid-state interface layer R&D represents the priority defensive patent position against next-generation sulfide electrolyte disruption. For New Entrants and Emerging Players: Energy storage system procurement teams at Texas utility-scale developers represent an underserved buyer archetype receptive to dry-process polypropylene alternatives with rapid qualification cycles. Bypass cell maker intermediation to contract directly with OEM technical teams in Austin and Detroit engineering centers. Target FERC interconnection-driven grid storage deployments with cost-optimized membrane specifications below automotive thermal performance thresholds. For Investors and Strategic Acquirers: Valuations sit cheapest among dry-process specialists with stranded capacity in industrial polyethylene segments lacking ceramic coating upgrade paths. Long-term viability centers on coating technology licensure and IRA clean manufacturing qualification rather than commodity membrane volume. Watch for NHTSA abuse test certification bottlenecks as the inflection signal separating qualified from speculative capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Capacity Expansion | Captures automotive OEM specification premiums for cells exceeding 300 Wh/kg energy density targets. |
| Quebec Hydropower Feedstock Integration | Qualifies suppliers for IRA clean manufacturing bonuses through low-carbon UHMWPE precursor production. |
| Wet-Process Technology Licensing | Enables Korean and Japanese suppliers to satisfy domestic content audit trails via US joint ventures. |
| Direct OEM Technical Contracting | Shortens validation cycles and displaces cell maker procurement leverage in Detroit and Austin. |
| Solid-State Interface Layer Development | Positions suppliers for premium tier above conventional lithium-ion through sulfide electrolyte compatibility. |
Study Parameters
Direct dialogue with separator plant managers, OEM platform engineers at Detroit Three and Tesla, cell maker procurement leads, and ceramic coating R&D directors grounded qualitative assessment in operational reality. Secondary validation drew from NHTSA safety filings, EPA automotive emissions documentation, FERC grid interconnection dockets, and SEC disclosures from listed chemical conglomerates. Bottom-up capacity modeling triangulated against top-down gigafactory demand projections across the analysis window.
Bottom-up segment modeling tracked polyethylene, composite, and polypropylene membrane volumes against automotive, energy storage, and consumer electronics demand tiers. Analytical frameworks incorporated process technology splits, coating penetration rates, and IRA qualification status as primary segmentation dimensions. CAGRs derived from installed capacity expansion schedules and OEM production ramp timelines. Forecast inputs included cathode chemistry shifts toward high-nickel formulations and FERC rulemaking acceleration for utility-scale storage interconnection.
Underlying measurement precision varies by segment; wet-process automotive qualification tiers carry tighter precision than experimental solid-state interface development pathways. Forecasts reflect assumptions regarding IRA domestic content rule permanence, UHMWPE resin allocation stability, and NHTSA thermal runaway test protocol evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
China Electric Vehicle Battery Manufacturing Market
Lithium-ion Battery
Liquid Lithium Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Materials Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Lithium-Ion Battery Wet-Process Separator Market
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
Consumer Lithium-Ion Battery Market
Lithium-ion Battery
Salt Lake Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market