
 South America Electric Vehicle Battery Materials Market | 2026-2036
South America Electric Vehicle Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electric Vehicle Battery Materials Market Insights
Specialized lithium extraction technicians is rotating toward Argentine salt flats and Chilean processing corridors, tightening regional labor pools just as cathode-active material plants multiply. BYD Co. Ltd leverages its integrated cell-to-pack architecture to secure offtake agreements with Brazilian bus electrification programs. Sigma Lithium anchors its position through hard-rock spodumene concentration in Minas Gerais, while CBMM dominates niobium-enhanced anode additive supply for fast-charging formulations.
South America electric vehicle battery materials encompass refined minerals and synthesized compounds—lithium carbonate or hydroxide, cobalt sulfate, nickel matte, and spheronized graphite—that meet purity thresholds above 99.5% for cathode and anode fabrication. These inputs enable electrochemical energy storage in lithium-ion cells where ion intercalation between electrodes drives reversible charge transfer. LFP cathode formulations lead volume shipments due to thermal stability and iron phosphate cost structures, yet NMC blends capture margin concentration as nickel content rises above 80% in premium automotive contracts. Graphite anode material sustains structural demand across both battery types, though silicon-doping research is redirecting some development expenditure.
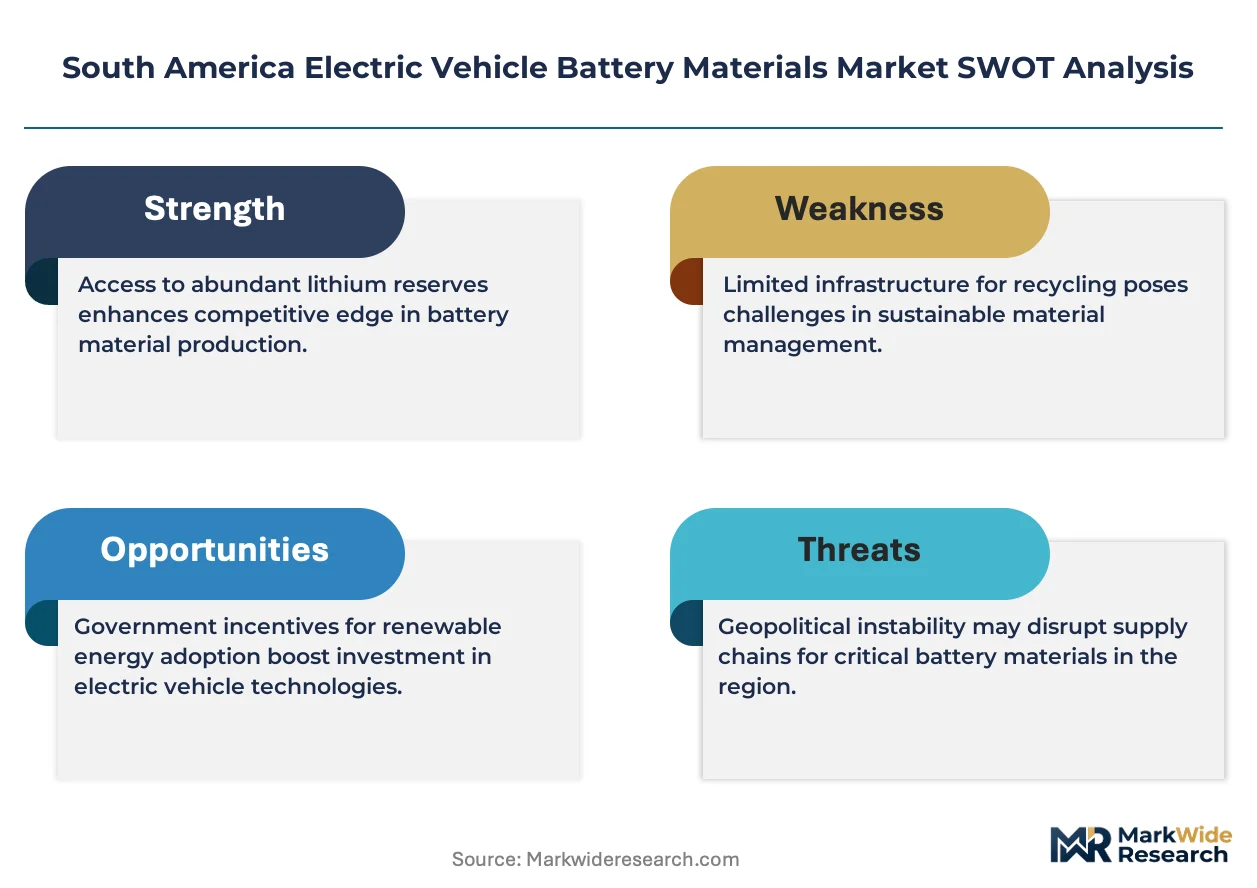
ANVISA oversees chemical substance registration for imported battery precursors, while Brazil's INMETRO certification mandates cell safety testing before domestic vehicle integration. Chile's environmental regulator imposes brine extraction quotas that cap lithium carbonate expansion rates regardless of price signals. Stakeholders must track how Argentine export duty restructuring and Brazilian local-content rules for the Rota 2030 automotive program jointly reshape procurement geography.
Market Dynamics
Argentina's lithium brine extraction quotas and Brazil's Rota 2030 local-content mandates are restructuring procurement geography, forcing battery material suppliers to relocate precursor production to capture automotive offtake contracts.
Growth Catalysts
- Chilean cobalt refining expansion:State-backed processing corridors in Antofagasta are attracting cathode-active material investment, reducing import dependence for Brazilian cell manufacturers.
- INMETRO cell safety certification:Mandatory pre-integration testing creates captive demand for domestically certified electrolyte and separator materials.
- Nickel-rich cathode migration:Automakers in São Paulo state are specifying NMC 811 formulations, pulling nickel matte imports through Santos port infrastructure.
Market Restraints
- Lithium carbonate input volatility:Argentine export duty restructuring creates price uncertainty for hydroxide conversion plants in Minas Gerais.
- Spodumene concentrate supply concentration:Hard-rock lithium processing clusters in southeastern Brazil face single-source dependency on Sigma Lithium's Greentech plant.
- Brine extraction quota caps:Chile's environmental regulator limits lithium carbonate expansion regardless of price signals from cathode manufacturers.
Strategic Opportunities
- Colombian grid storage deployment:Utility-scale battery procurement from Bogotá's grid operator creates demand for LFP cathode materials currently undersupplied regionally.
- Peruvian copper-nickel corridor development:Smelter investments in Arequipa could localize nickel matte supply currently imported from Indonesian laterite operations.
- Uruguayan renewable-battery pairing mandates:New auction rules require solar-wind developers to co-locate storage, opening electrolyte and anode material procurement channels.
Industry Challenges
- Lithium extraction technician scarcity:Specialized salt-flat operators are rotating toward Argentine and Chilean corridors, tightening labor availability for Brazilian hard-rock projects.
- ANVISA chemical registration timelines:Imported precursor substances face 18-24 month approval windows, delaying cathode plant commissioning.
- Cell-to-pack integration complexity:Bus electrification programs in São Paulo require module-level redesign to accommodate BYD's integrated architecture specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electric Vehicle Battery Materials Market |
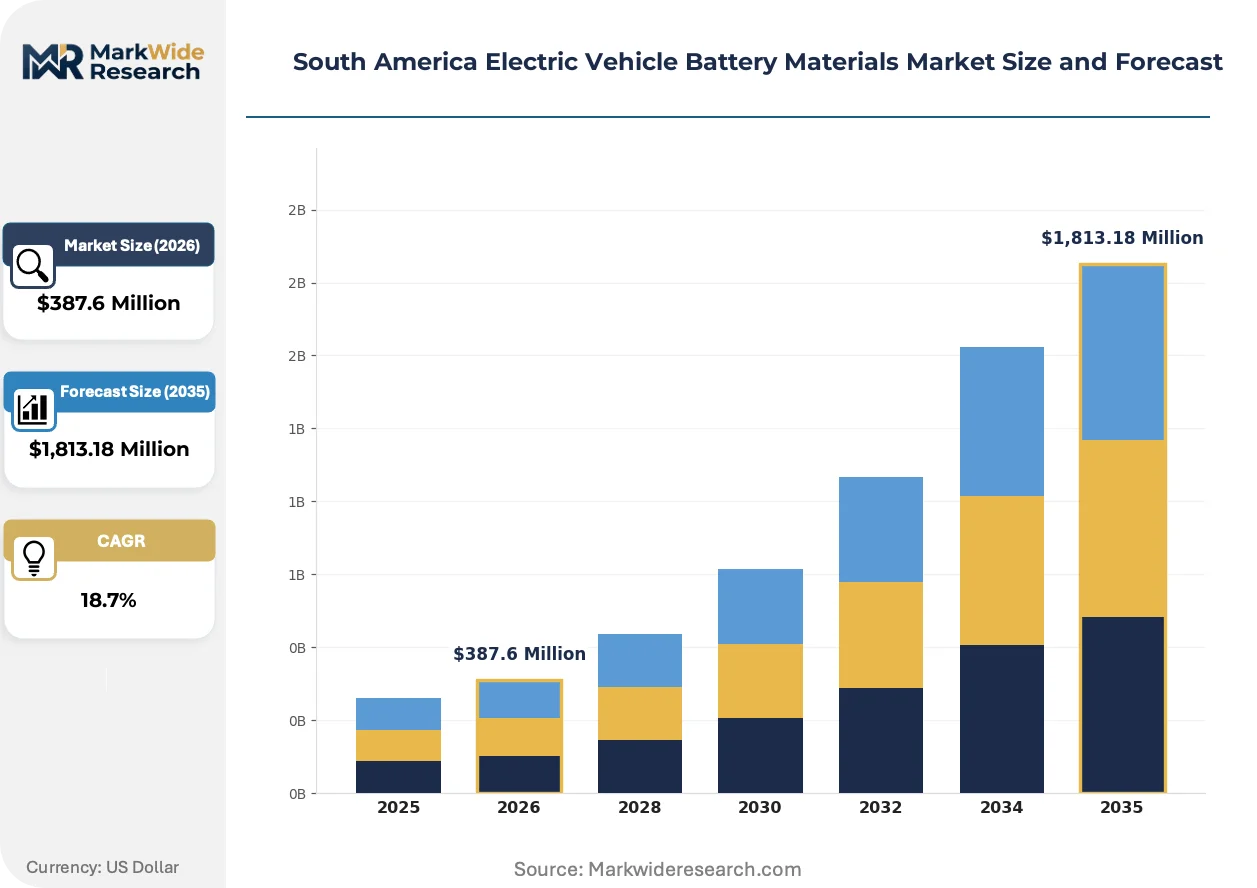
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,813.18 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium, Cobalt, Nickel, Graphite Battery Type: LFP, NMC, LCO, NCA End User: Automakers, Battery Manufacturers, Electronics, Energy Storage Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | BYD Co. Ltd, SK Innovation Co., Ltd., LG Chem Ltd, Panasonic Corporation, EnerSys, Exide Industries, Sigma Lithium, CBMM, Toshiba Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electric Vehicle Battery Materials Market Trends and Innovations
Electrochemical storage chemistry is pivoting toward nickel-dominant cathodes while anode formulations experiment with silicon doping, reshaping purity thresholds and processing equipment requirements across the supply chain.
Silicon-doped graphite anode material is fragmenting the traditional spheronized graphite market. Battery engineers in São Paulo are specifying 5-10% silicon loadings to boost energy density for premium automotive contracts. This formulation shift is fragmenting procurement patterns as anode suppliers retool milling and coating lines to handle silicon's volumetric expansion during cycling.
Chile's brine extraction quota system is capping lithium carbonate expansion rates regardless of cathode manufacturer demand signals. The policy compresses available feedstock for hydroxide conversion plants serving NMC 811 production lines. Brazilian cathode producers are responding by accelerating hard-rock spodumene offtake negotiations with Minas Gerais concentrate operations.
Fleet electrification procurement in São Paulo is consolidating around integrated cell-to-pack suppliers. Municipal bus operators are bypassing module-level vendors to contract directly with pack assemblers offering 15-year performance guarantees. This channel compression is most visible in Brazil's southeast corridor, where Rota 2030 local-content rules favor domestic pack integration over imported module assembly.
South America Electric Vehicle Battery Materials Market Segmentation
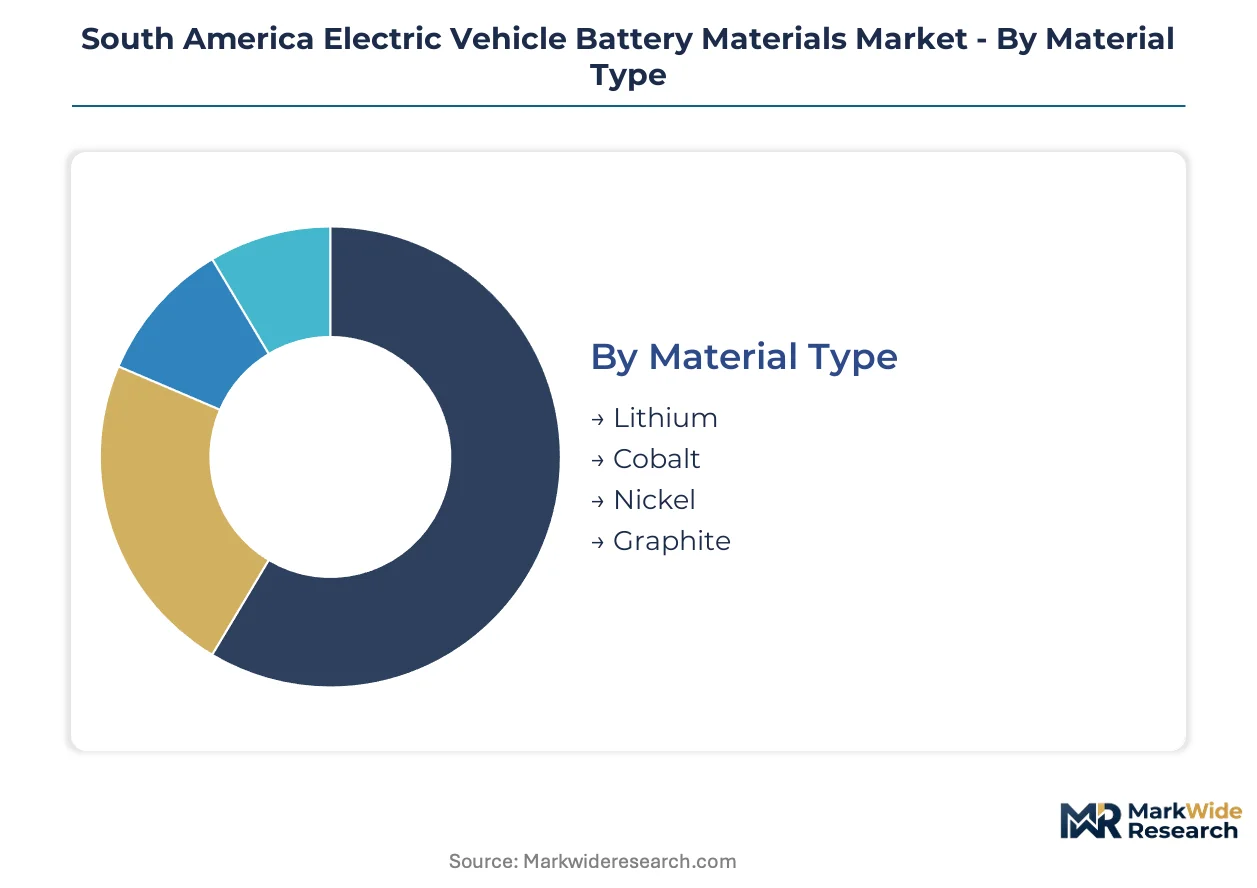
Battery material procurement in South America fragments across extraction geology, cell chemistry migration, and regulatory channel requirements. Each segmentation layer reveals distinct margin profiles and captive demand structures that reshape supplier positioning.
Material Type:
Substitution pressure intensifies around cathode-active minerals as nickel-rich formulations displace cobalt-dependent chemistries and synthetic graphite alternatives advance.
- Lithium:Extracted from Argentine salar brines and Minas Gerais hard-rock spodumene, this mineral feeds both carbonate and hydroxide conversion streams. Brazilian cathode plants in Minas Gerais are locking in spodumene offtake to bypass Chilean brine quota constraints.
- Nickel:Laterite-derived matte and refined sulfate enable NMC 811 cathode production for São Paulo automakers specifying premium energy density. Peruvian smelter investments in Arequipa could localize supply currently routed through Indonesian processing corridors.
- Cobalt:Chilean refining expansion in Antofagasta is reducing Brazilian import dependence for sulfate precursors.
- Graphite:Spheronized natural graphite sustains anode demand across LFP and NMC cell types, though silicon-doping research is redirecting some development expenditure.
Lithium anchors the volume base while nickel gains share at the steepest rate.
Battery Type:
Cost tier differentiation separates thermal-stable iron phosphate formulations from energy-dense nickel-cobalt blends commanding automotive premium contracts.
- LFP:Lithium iron phosphate cathodes dominate Brazilian bus electrification and Colombian grid storage procurement due to cycle life economics and thermal stability. BYD's cell-to-pack architecture favors this chemistry for São Paulo municipal fleet operators.
- NMC:Nickel-manganese-cobalt blends, particularly NMC 811 variants, capture margin concentration in premium passenger EV contracts from São Paulo automakers. Nickel content above 80% pulls matte imports through Santos port infrastructure.
- NCA:Nickel-cobalt-aluminum formulations serve high-performance automotive segments requiring maximum volumetric energy density.
- LCO:Lithium cobalt oxide retains niche demand in consumer electronics applications with limited South American cell production.
LFP captures the installed base while NMC expands most quickly in revenue terms.
End User:
Application concentration varies sharply between automotive qualification requirements and stationary storage procurement cycles.
- Automakers:Vehicle OEMs in São Paulo state specify cathode chemistry and purity thresholds through Rota 2030 local-content mandates, creating captive demand for domestically certified precursor materials.
- Battery Manufacturers:Cell producers in Minas Gerais and São Paulo corridors source active materials for both automotive and energy storage applications, with INMETRO certification requirements filtering supplier pools.
- Electronics:Consumer device demand pulls small-format LCO cells through import channels with limited regional material processing.
- Energy Storage:Colombian utility-scale procurement from Bogotá's grid operator and Uruguayan renewable-battery pairing mandates create demand for LFP materials currently undersupplied regionally.
Battery manufacturers intermediate the largest volume flows while energy storage is climbing the fastest as a demand segment.
Distribution Channel:
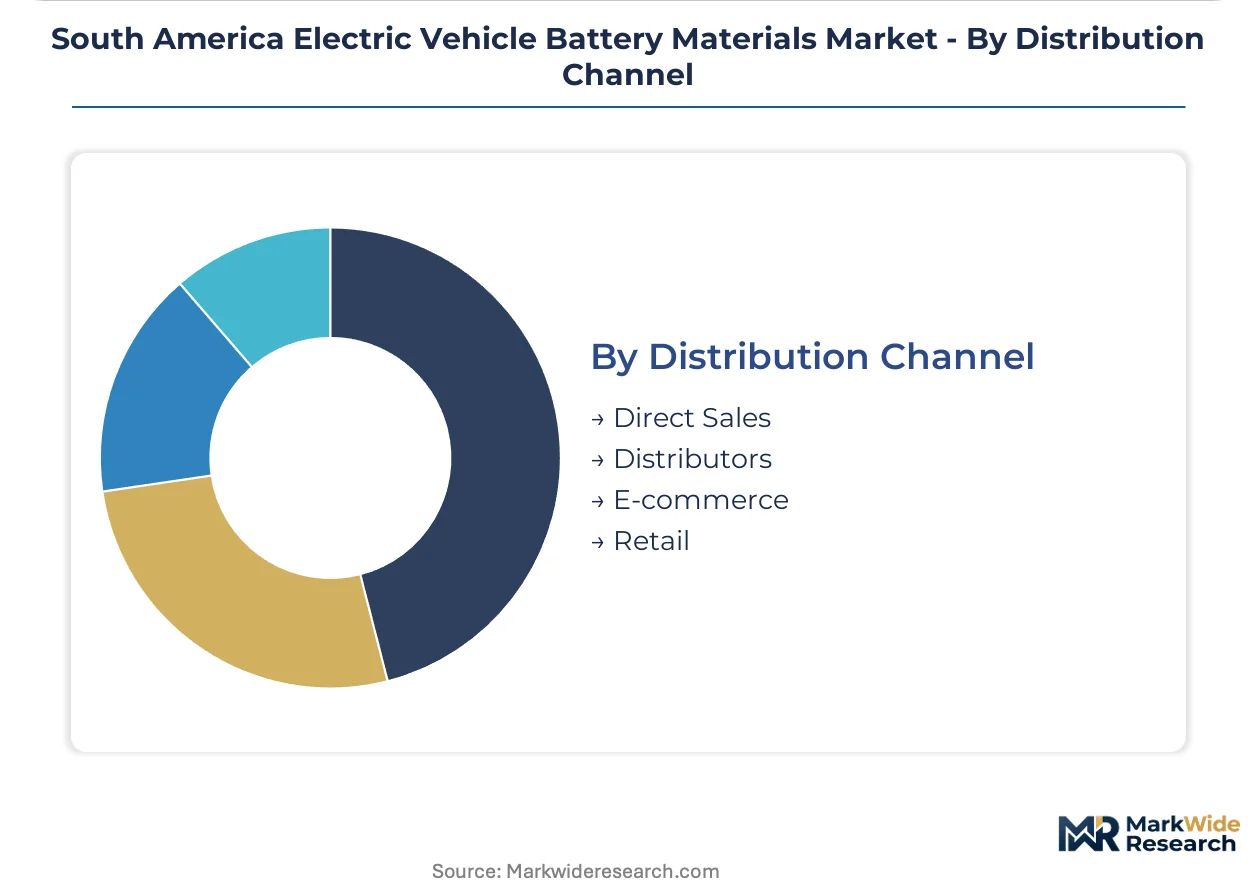
Customer type and contract scale determine whether procurement runs through integrated direct agreements or fragmented intermediary layers.
- Direct Sales:Long-term offtake agreements between Argentine brine operators and Brazilian hydroxide conversion plants lock in volume through Santos port logistics.
- Distributors:Chemical traders manage spot market liquidity for smaller cathode plants lacking integrated upstream supply.
- E-commerce:Digital procurement channels serve laboratory-scale and R&D material requirements with limited industrial relevance.
- Retail:Counter sales address maintenance and repair segments with negligible battery material volume.
Direct sales anchor the volume base while distributors gain relevance in spot market flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentine lithium brine producers command upstream pricing leverage over Brazilian cathode manufacturers, while Chilean refining corridors capture midstream margin concentration. This asymmetry is restructuring procurement geography across the continent.
Brazil
São Paulo automakers specify NMC 811 cathode formulations through Rota 2030 local-content mandates, pulling nickel matte imports through Santos port infrastructure. INMETRO certification creates captive demand for domestically certified electrolyte materials. Minas Gerais hosts hard-rock spodumene concentration operations supplying hydroxide conversion plants.
Argentina
Salta and Catamarca provinces host lithium brine extraction operations feeding carbonate and hydroxide conversion streams. Export duty restructuring creates price uncertainty for downstream Brazilian processors. Jujuy corridor development is attracting fresh capital commitments from battery supply chain investors seeking upstream integration.
Chile
Antofagasta refining corridors are expanding cobalt sulfate capacity to reduce Brazilian import dependence. Environmental regulator brine extraction quotas cap lithium carbonate expansion regardless of cathode manufacturer demand signals. Atacama salt flat operations remain the dominant regional feedstock source.
Colombia
Bogotá's grid operator is procuring utility-scale battery storage, creating demand for LFP cathode materials currently undersupplied regionally. National renewable integration targets are accelerating storage procurement timelines. Caribbean port infrastructure is being evaluated for material import logistics.
Uruguay
New auction rules require solar-wind developers to co-locate storage, opening electrolyte and anode material procurement channels. Montevideo is positioning as a regional distribution hub for Brazilian battery manufacturers. Renewable-battery pairing mandates are creating first-mover procurement advantages.
South America Electric Vehicle Battery Materials Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South America electric vehicle battery materials market. Integrated cell-to-pack suppliers capture premium automotive contracts through performance guarantees, while regional mineral processors compete on feedstock proximity and logistics efficiency. Three archetypes dominate: Asian integrated battery manufacturers with direct automotive relationships, South American lithium and specialty mineral extractors with upstream resource control, and regional chemical processors with INMETRO certification capabilities. Competitive moves center on long-term offtake agreements locking in volume and backward integration into precursor production.
Among Asian integrated manufacturers, BYD Co. Ltd and LG Chem Ltd exemplify the cell-to-pack architecture specialists securing municipal bus electrification contracts. Sigma Lithium and CBMM represent the regional upstream archetype, anchoring positions through hard-rock spodumene concentration and niobium-enhanced anode additive supply respectively. SK Innovation Co., Ltd. occupies a position bridging both technology integration and regional market development.
| Leading Market Players |
|---|
| BYD Co. Ltd |
| SK Innovation Co., Ltd. |
| LG Chem Ltd |
| Panasonic Corporation |
| EnerSys |
| Exide Industries |
| Sigma Lithium |
| CBMM |
| Toshiba Corporation |
| Others |
Pricing and Supply Chain Analysis
Hard-rock spodumene concentration economies in Minas Gerais are compressing conversion cost floors for Brazilian hydroxide plants, while Argentine brine quota constraints inflate carbonate feedstock premiums. This divergence between upstream extraction scale and midstream processing capacity is restructuring margin capture across the cathode-active material value chain.
Pricing Analysis
Configured-to-order cathode precursor pricing commands spreads above standard carbonate spot contracts, reflecting INMETRO certification premiums and Rota 2030 local-content compliance costs. Price differentiation separates automotive-grade NMC 811 formulations from bus fleet LFP standards, with nickel-rich blends absorbing matte import volatility through Santos port logistics. Pricing pressure stems from Chilean brine quota caps constraining carbonate availability for hydroxide conversion. Battery manufacturers in São Paulo state exhibit highest price sensitivity, while premium passenger EV automakers accept formulation premiums for energy density guarantees.
Supply Chain Analysis
Santos port throughput chokepoints govern nickel matte import velocity for São Paulo cathode plants, creating inventory vulnerability during peak automotive procurement cycles. Geographic supply concentration centers on Argentine salar brines, Chilean Atacama processing corridors, and Minas Gerais hard-rock spodumene operations. Raw material dependencies span lithium carbonate, nickel matte, and cobalt sulfate precursors. Single-source vulnerability concentrates around Sigma Lithium's Greentech plant for southeastern Brazilian concentrate supply. Distribution runs through long-term offtake agreements between Argentine brine operators and Brazilian conversion facilities, with spot market distributors serving smaller cathode producers lacking integrated upstream supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America electric vehicle battery materials market represents a high-growth disruption anchored by Rota 2030 local-content mandates and nickel-rich cathode chemistry migration. These twin inflections are rewiring procurement geography and supplier qualification requirements across the continent.
For Market Incumbents: Compound captive supply advantages by locking hard-rock spodumene offtake from Minas Gerais operations before Chilean brine quota constraints tighten further. Accelerate backward integration into precursor production to defend margin position against Asian integrated cell-to-pack suppliers entering Brazilian bus electrification procurement. Prioritize INMETRO certification investment as a channel control lever, creating technical barriers for unqualified importers facing ANVISA registration delays. For New Entrants and Emerging Players: Lead with Colombian grid storage deployment as the most penetrable white-space target, where Bogotá's utility-scale procurement faces regionally undersupplied LFP cathode availability. Target Uruguayan renewable-battery pairing mandates as a second entry vector, leveraging Montevideo's emerging distribution hub position for Brazilian battery manufacturer supply. Pursue electrolyte and separator material specialization as the go-to-market angle, capturing INMETRO-certified demand that incumbent mineral processors cannot easily replicate. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hard-rock spodumene concentrators with locked offtake agreements to Brazilian hydroxide conversion plants, offering volume visibility across the analysis window. Long-term viability favors acquisition targets with upstream resource control and midstream processing capabilities bridging Argentine brine or Brazilian hard-rock feedstock to cathode-active material output. The signal to watch is Argentine export duty restructuring, which would re-rate downstream processor margins and reposition geographic supply advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Hard-Rock Spodumene Concentration Expansion | Minas Gerais capacity additions bypass Chilean brine quota constraints for Brazilian cathode supply. |
| INMETRO Certification Investment | Pre-integration cell safety testing creates technical barriers for uncertified electrolyte importers. |
| Long-Term Offtake Agreement Structuring | Santos port logistics integration locks volume between Argentine brine operators and hydroxide converters. |
| Silicon-Doped Graphite Anode Development | São Paulo automotive specifications for 5-10% silicon loadings fragment traditional spheronized graphite procurement. |
| Peruvian Nickel Matte Smelter Investment | Arequipa corridor development could localize supply currently routed through Indonesian laterite operations. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with lithium extraction technicians, cathode plant procurement managers, and ANVISA regulatory affairs specialists; and secondary validation through Chilean environmental regulator quota filings, Brazilian INMETRO certification databases, and Argentine export duty restructuring documentation. Primary interviews spanned salt-flat operators in Catamarca, hydroxide conversion engineers in Minas Gerais, and fleet electrification procurement officers in São Paulo municipal transit authorities. Secondary sources included customs trade records for nickel matte imports through Santos port, SEC filings from integrated battery manufacturers with South American operations, and Rota 2030 local-content rule amendments. Bottom-up volume modeling from individual extraction and processing facilities was cross-checked against top-down demand estimates derived from automotive production forecasts and grid storage procurement announcements.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning material type, battery chemistry, end-user application, and distribution channel structure. CAGRs were derived from trajectory fitting across historical extraction capacity additions, announced conversion plant investments, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated brine extraction quota elasticity assumptions and Rota 2030 local-content phase-in schedules for domestic precursor certification requirements.
Forecasts assume regulatory continuity in Brazilian INMETRO certification regimes and Chilean environmental quota systems; material policy shifts would require re-modeling of cathode supply availability and pricing trajectories. Practitioners should keep alternative scenarios live as Argentine export duty restructuring and Peruvian smelter investment commitments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
Lithium Ion Battery Cathodes Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Battery for Passenger Car Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Lithium Cobalt Oxide Battery (LCO) Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market