
 Portable Lithium Battery Energy Storage Products Market | 2026-2036
Portable Lithium Battery Energy Storage Products Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Lithium Battery Energy Storage Products Market Insights
Aftermarket service revenue is rewriting margin capture across the portable lithium battery energy storage value chain. EcoFlow leverages its proprietary app ecosystem and firmware update infrastructure to sustain recurring engagement with installed-base owners. Bluetti Power anchors its competitive stance through backward integration into battery management system design and in-house production of LFP pack assemblies.
Portable lithium battery energy storage products are rechargeable electrochemical systems, typically employing lithium iron phosphate or nickel manganese cobalt oxide cathodes with energy densities between 150-300 Wh/kg, designed to deliver AC and DC output for off-grid, backup, and mobile power applications. Solar generators within the product type dimension command premium positioning due to integrated MPPT charge controllers and panel compatibility that expands use-case flexibility. The technology segment shows LFP chemistry leading volume shipments while NMC retains share in compact, weight-sensitive designs where higher energy density justifies cost premiums.
FCC certification requirements govern RF emissions for smart-connectivity features in the United States, while EU CE marking and RoHS substance restrictions shape product composition and market access across Europe. China's GB standards and SAMR quality supervision protocols enforce cell-grade consistency for domestic manufacturers exporting portable storage units. Stakeholders must track evolving UN 38.3 transport testing protocols and regional fire-safety codes as product capacities scale beyond 3000Wh thresholds.
Market Dynamics
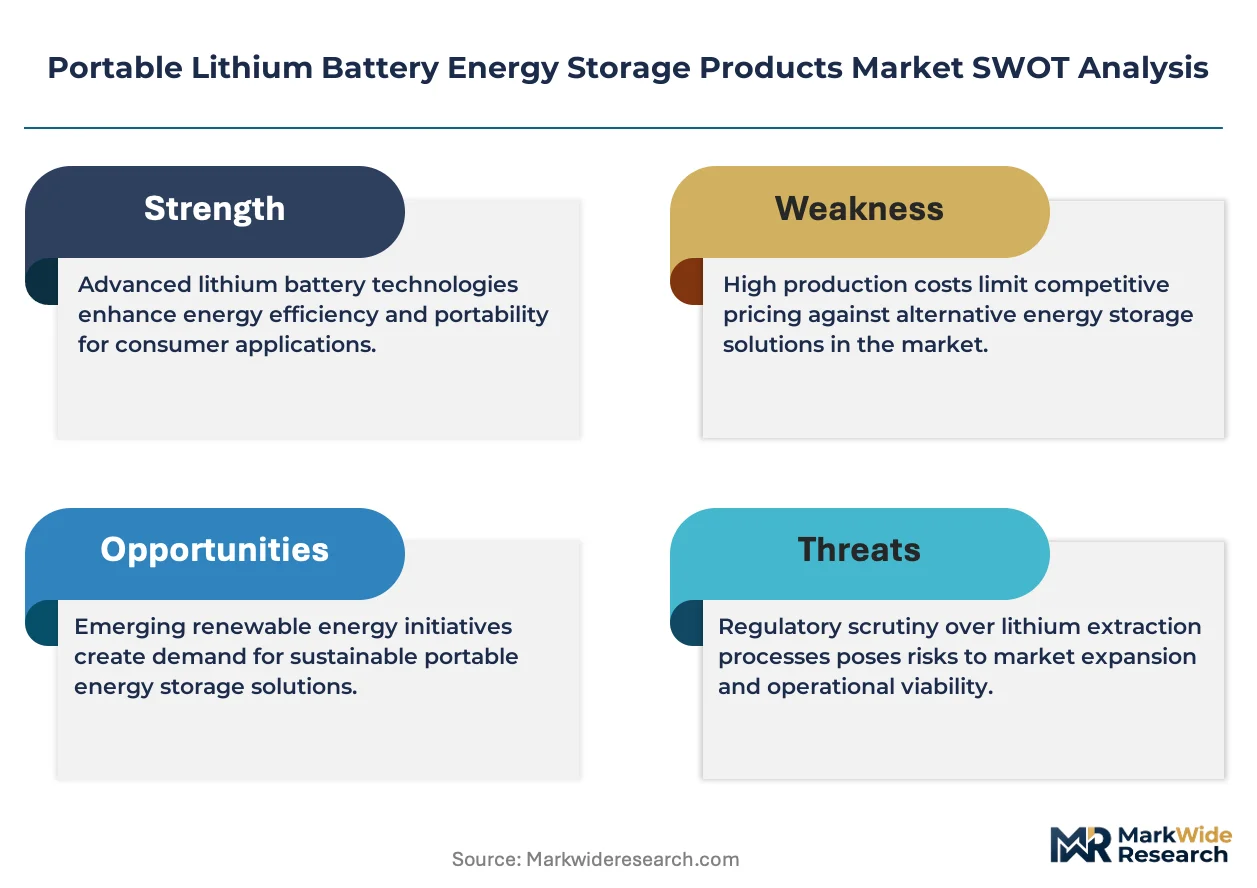
Cell-grade lithium iron phosphate chemistry is migrating from premium solar generator tiers toward mass-market power stations, compressing cost structures and displacing nickel manganese cobalt oxide across sub-3000Wh segments.
Growth Catalysts
- US Inflation Reduction Act domestic content incentives:Tax credits for battery assembly onshore are pulling manufacturing investment toward Arizona and Texas industrial corridors.
- Outdoor recreation infrastructure:National park electrification mandates and dispersed camping permit expansions are creating pull-through demand for solar-compatible portable units.
- LFP cathode material maturation:Chinese precursor supply scale and dry electrode coating advances are collapsing pack-level cost curves for 2000-5000Wh systems.
Market Restraints
- Graphite anode supply concentration:Synthetic and natural graphite processing clusters in Shandong and Heilongjiang provinces create single-source vulnerability for non-Chinese pack assemblers.
- UN 38.3 transport testing bottlenecks:Certified laboratory capacity constraints in North America and Europe are extending product launch timelines by 8-14 weeks for manufacturers seeking air freight approval.
- Lead-acid substitution inertia in emerging markets:Price-sensitive backup power buyers in Southeast Asia and Sub-Saharan Africa continue prioritizing flooded battery economics despite lithium lifecycle advantages.
Strategic Opportunities
- India off-grid electrification gap:Rural household solar-home-system retrofits present addressable demand for 500-1500Wh lithium replacements of lead-acid storage.
- V2H bidirectional charging convergence:Integration of portable power station protocols with electric vehicle onboard chargers is opening automotive aftermarket channel access.
- EU Green Deal repairability mandates:Upcoming battery passport and replaceable cell regulations will favor modular pack designs enabling aftermarket service revenue capture.
Industry Challenges
- BMS firmware talent scarcity:Embedded systems engineers with lithium-specific state-of-charge algorithm experience command 40-60% compensation premiums versus general battery electronics roles.
- Multi-certification timeline compression:Simultaneous FCC, CE, and GB standard compliance for global product launches requires parallel testing tracks that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Lithium Battery Energy Storage Products Market |
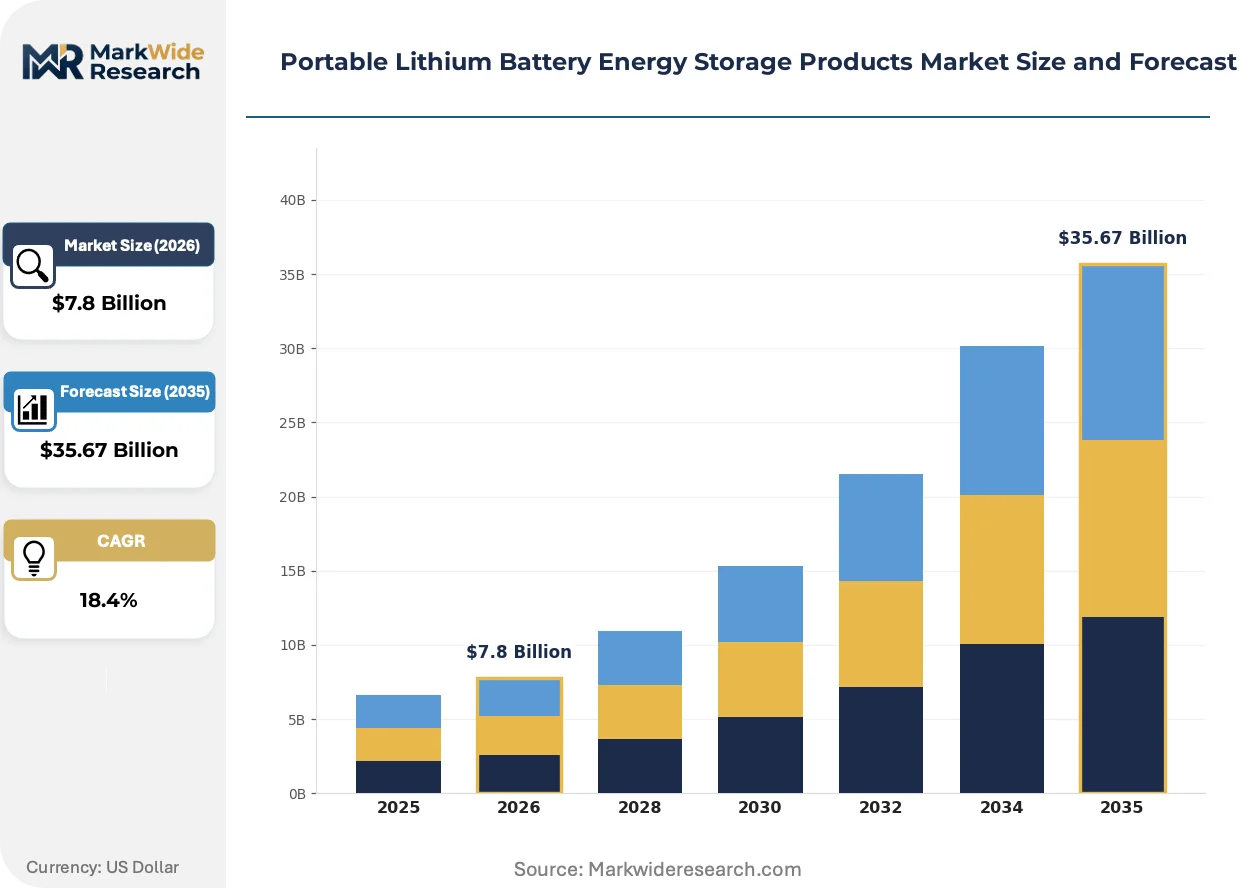
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $35.67 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Chargers, Power Banks, Solar Generators, UPS Systems End User: Households, Outdoor Enthusiasts, Emergency Services, RV Owners Technology: LFP, NMC, NCA, SLI Capacity: 1000Wh, 2000Wh, 3000Wh, 5000Wh |
| Companies Covered | Jackery Technology, EcoFlow, Bluetti Power, Goal Zero, Anker Innovations, Chint Global, AceOn Group, ATGepower, Jntech Renewable Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Lithium Battery Energy Storage Products Market Trends and Innovations
Active materials and system architectures are undergoing rapid recombination as manufacturers chase energy density gains without sacrificing cycle life or thermal stability margins.
Solid-state electrolyte development is migrating from laboratory demonstration to pilot production lines at Korean and Japanese cell manufacturers, with silicon-rich anode pairings promising 400+ Wh/kg system-level density. Outdoor expedition buyers and professional film production crews are absorbing 30-50% price premiums for early solid-state portable units despite limited cycle data. This chemistry transition is compressing the performance gap between stationary and mobile storage, enabling multi-day off-grid capacity in sub-25kg form factors previously unattainable with liquid electrolyte designs.
EU Battery Regulation 2023/1542 carbon footprint disclosure requirements are forcing supply chain documentation from mine to module, with due diligence obligations extending to cobalt, lithium, and natural graphite provenance. Pack assemblers serving European markets are responding by locking multi-year offtake agreements with Australian and Canadian hard-rock spodumene producers to secure Class 1 lithium hydroxide with auditable Scope 3 emissions. Solar generator product lines with embedded panel compatibility are experiencing accelerated certification complexity as integrated photovoltaic components trigger additional WEEE and ecodesign compliance layers.
Direct-to-consumer subscription financing is displacing traditional retail channel stocking for premium portable power stations, with manufacturers offering battery-as-a-service models that bundle hardware, warranty extension, and firmware feature unlocks. Specialty outdoor retailers and emergency preparedness distributors are seeing margin compression as brand-owned e-commerce captures attach-rate economics previously captured by intermediaries. This channel reconfiguration is most visible in German and US markets where credit-enabled purchasing and extended return windows reduce perceived adoption risk for first-time lithium storage buyers.
Portable Lithium Battery Energy Storage Products Market Segmentation
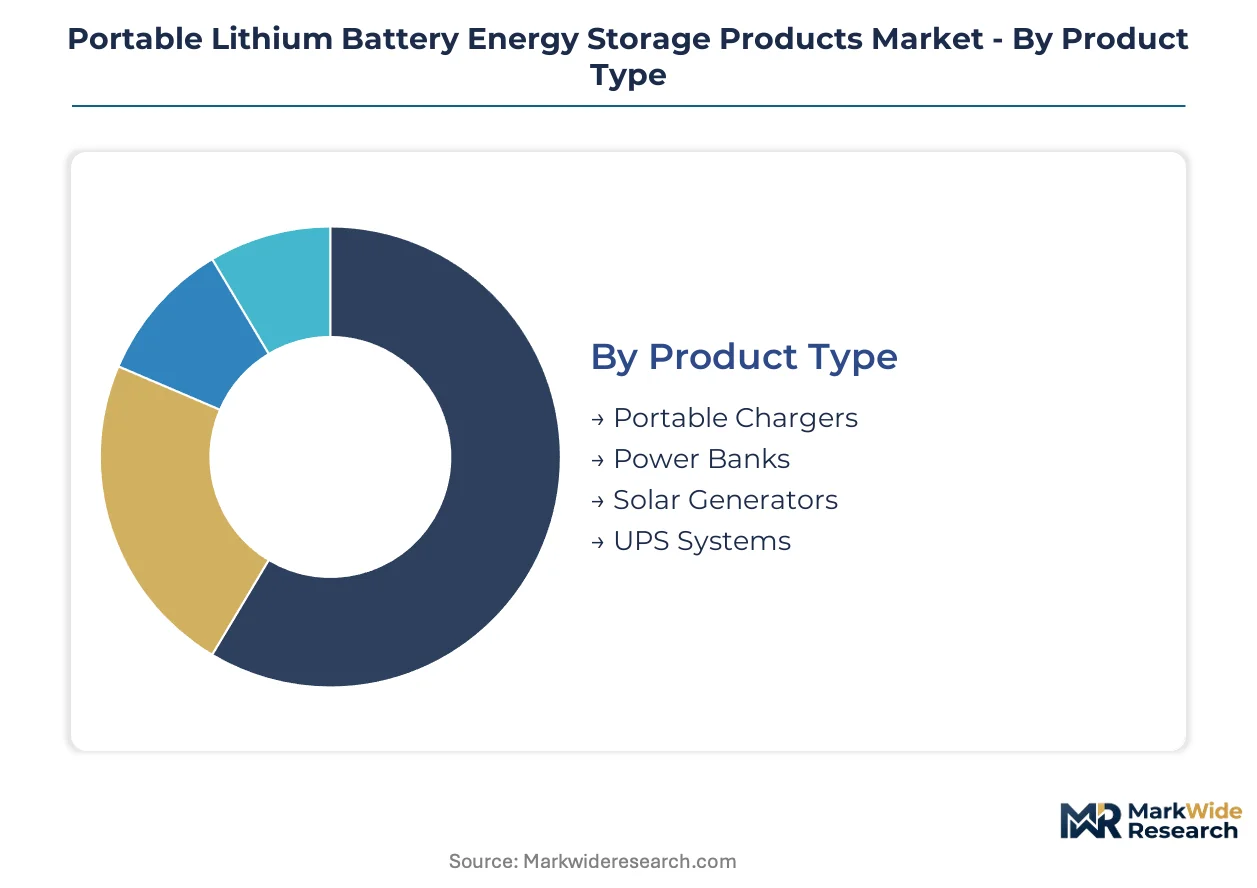
Segmentation in portable lithium battery energy storage reveals distinct performance requirements across use cases. Chemistry selection, capacity scaling, and integration features determine pricing architecture and channel strategy for manufacturers competing across residential backup, mobile recreation, and professional deployment scenarios.
Product Type:
Cost tier stratification separates entry-level charging accessories from integrated solar-ready systems commanding 5-10x price multiples.
- Solar Generators:Integrated MPPT charge controllers and panel compatibility enable off-grid deployment for film production crews and remote construction sites. Demand concentrates in Germany and the southwestern United States where dispersed camping permit expansions and national park electrification mandates create pull-through. LFP chemistry migration is compressing pack-level costs for 2000-5000Wh configurations.
- Power Banks:Compact lithium polymer or cylindrical cell assemblies deliver 20-100Wh pocket-scale capacity for smartphone and tablet charging. Urban commuters and business travelers in China and India drive volume procurement through e-commerce direct-to-consumer channels.
- Portable Chargers:AC outlet-equipped units in 100-500Wh range serve laptop power and small appliance backup during grid interruptions.
- UPS Systems:Pure sine wave output and millisecond switching capability protect sensitive electronics for home office and medical device applications.
Solar generators command the established base. The steepest expansion runs through power banks in emerging market urban corridors.
End User:
Application context determines durability specifications, warranty terms, and software feature requirements across buyer archetypes.
- Outdoor Enthusiasts:Weight-optimized designs with IP65 ingress protection and operating temperature ranges of -20°C to 60°C support backcountry expeditions and overlanding. Demand clusters in Colorado, Utah, and British Columbia where trail infrastructure investments and permit system digitization reduce access friction.
- RV Owners:3000Wh+ systems with 30A RV outlet compatibility and pass-through charging enable extended boondocking without generator noise. Retiree migration patterns toward Arizona and Florida sunbelt counties sustain replacement cycles.
- Emergency Services:MIL-STD-810G shock compliance and electromagnetic interference shielding support field medical equipment and communication relay operations.
- Households:Sub-2000Wh units with smartphone app monitoring and grid-tie capability address residential backup for refrigerator and medical device continuity.
Outdoor enthusiasts anchor current revenue concentration. The steepest expansion trajectory tracks emergency services procurement through federal and municipal preparedness grants.
Technology:
Chemistry selection trades energy density against cycle life, thermal stability, and supply chain concentration risk.
- LFP:Lithium iron phosphate cathodes deliver 3000-6000 cycle life with thermal runaway thresholds above 270°C, enabling indoor residential deployment without active cooling. Chinese precursor supply scale and dry electrode coating advances are collapsing cost curves across 2000-5000Wh mass-market power stations.
- NMC:Nickel manganese cobalt oxide retains 20-25% energy density advantage for weight-sensitive applications below 1000Wh where pack mass determines portability.
- NCA:Nickel cobalt aluminum formulations occupy premium compact segments where cylindrical cell manufacturing economies support limited production runs.
- SLI:Starting-lighting-ignition derivatives serve automotive jump-start accessories with high discharge rate tolerance.
LFP commands the established base. NMC retains share in compact form factors where energy density premiums justify cost differentials.
Capacity:
Volume scaling determines cell configuration complexity, thermal management requirements, and regulatory classification thresholds.
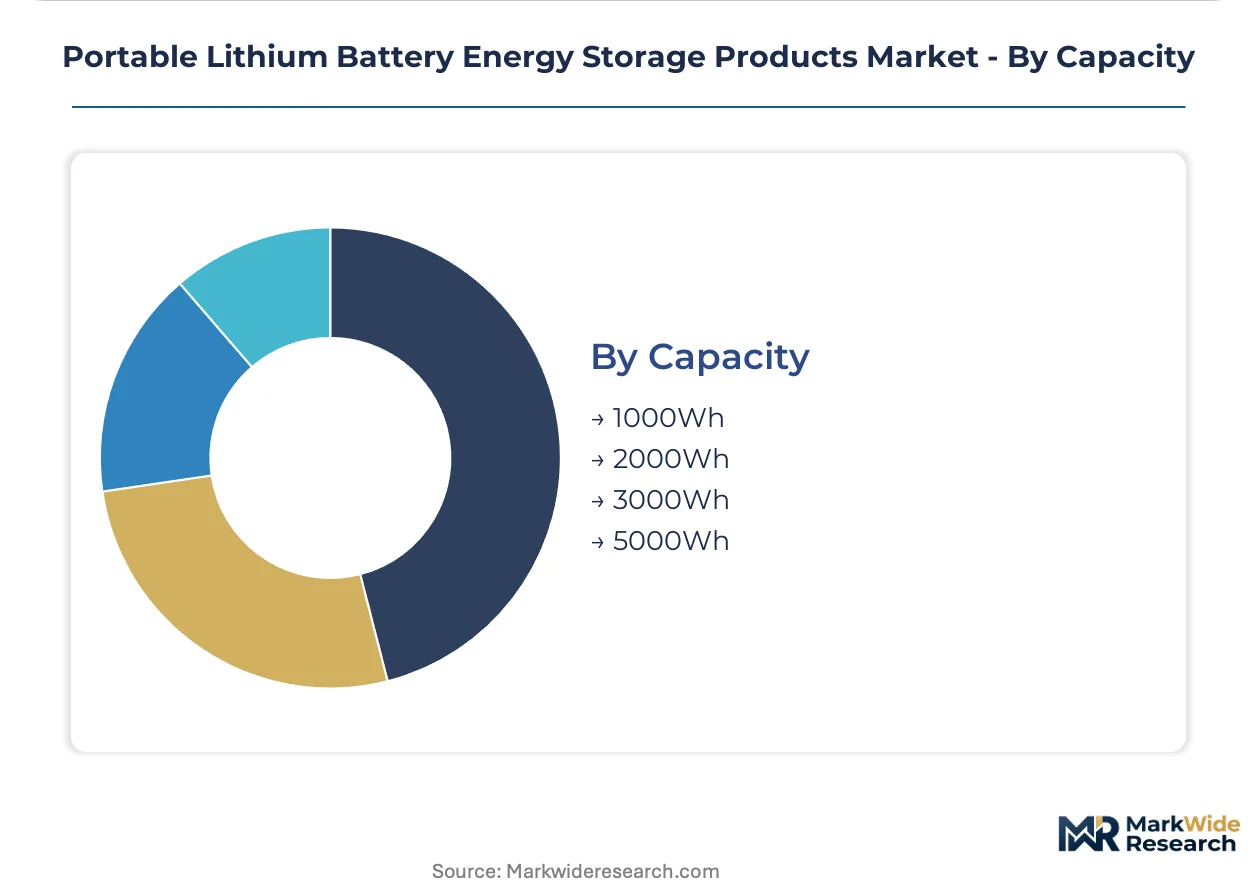
- 3000Wh:Three-kilowatt-hour systems represent the inflection point where UN 38.3 transport testing complexity escalates and residential appliance backup becomes comprehensive. German and US households with solar panel retrofits drive replacement of lead-acid storage in home energy management configurations.
- 5000Wh:Five-kilowatt-hour units enable multi-day off-grid operation for professional film production and construction site power where generator fuel logistics prove prohibitive.
- 1000Wh:Entry-level residential backup and weekend camping applications balance portability against refrigerator runtime.
- 2000Wh:Mid-tier configurations capture RV and vanlife conversions with microwave and small air conditioner compatibility.
3000Wh systems command the established base. 5000Wh configurations are gaining share fastest through commercial and professional deployment channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity in portable lithium battery energy storage diverges sharply across geographies. German buyers absorb 20-30% premiums for carbon-audited supply chains, while Southeast Asian procurement remains anchored to lead-acid substitution economics.
United States
IRA domestic content tax credits are pulling assembly operations toward Arizona and Texas industrial corridors. FCC certification governs RF emissions for smart-connectivity features in all portable units. The Mountain West region anchors outdoor recreation demand, with Colorado and Utah backcountry permit expansions driving solar generator procurement.
Germany
Dispersed camping permit digitization and national park electrification mandates create pull-through for MPPT-integrated solar generators. EU Battery Regulation 2023/1542 carbon footprint disclosure requirements enforce mine-to-module documentation. Bavaria's industrial corridor hosts pack assemblers locking multi-year offtake agreements with Australian spodumene producers.
China
GB standards and SAMR quality supervision protocols enforce cell-grade consistency for domestic manufacturers exporting portable storage units. Dry electrode coating advances in Jiangsu and Fujian provinces are collapsing LFP pack-level cost curves. The Yangtze River Delta concentration of precursor supply scale enables mass-market 2000-5000Wh system production.
India
Rural household solar-home-system retrofits present addressable demand for 500-1500Wh lithium replacements of lead-acid storage. BIS certification requirements and CEA grid-interconnection standards shape product composition for residential backup applications. Gujarat and Maharashtra industrial zones are emerging as assembly hubs for price-optimized power stations.
Australia
Hard-rock spodumene producers in Western Australia secure Class 1 lithium hydroxide with auditable Scope 3 emissions for European pack assemblers. TGA-equivalent electrical safety standards and state-level fire codes govern residential energy storage deployment. Queensland and New South Wales off-grid property markets sustain premium solar generator demand.
Portable Lithium Battery Energy Storage Products Market Competitive Landscape
Capability concentration sits with firmware and battery management system specialists; scale advantage sits with cell-grade manufacturers and channel-integrated brands. The vendor base stratifies across three tiers: premium solar generator specialists, mass-market power station assemblers, and private-label charging accessory suppliers. Dominant competitive moves include backward integration into LFP pack assembly and direct-to-consumer subscription financing that displaces traditional retail channel economics.
Within the integrated-app ecosystem tier, EcoFlow exemplifies recurring engagement models through proprietary firmware infrastructure. Jackery Technology and Bluetti Power anchor the premium solar generator segment, with the former representing direct-to-consumer channel mastery and the latter exemplifying in-house battery management system design. Goal Zero occupies a position bridging professional expedition deployment with consumer outdoor recreation markets.
| Leading Market Players |
|---|
| Jackery Technology |
| EcoFlow |
| Bluetti Power |
| Goal Zero |
| Anker Innovations |
| Chint Global |
| AceOn Group |
| ATGepower |
| Jntech Renewable Energy |
| Others |
Pricing and Supply Chain Analysis
Jiangsu and Fujian provinces anchor global LFP cathode precursor production, with dry electrode coating scale translating directly into pack-level pricing power for Chinese manufacturers exporting 2000-5000Wh systems. This upstream concentration compresses cost curves for mass-market power stations while forcing non-integrated assemblers to absorb margin pressure or surrender share.
Pricing Analysis
Long-term offtake contracts dominate lithium carbonate and Class 1 hydroxide procurement, though spot market exposure persists for graphite anodes and electrolyte salts. Price differentiation hinges on certification tier — UN 38.3 transport approval and UL 2743 safety listings command 15-25% premiums — and after-sales bundling through firmware-enabled service tiers. Cost compression in sub-3000Wh segments intensifies as Jiangsu-based LFP cell capacity floods export channels. Emergency preparedness buyers exhibit lowest price sensitivity, absorbing premiums for grid-tie compatibility and app-enabled monitoring, while Southeast Asian backup power purchasers remain anchored to lead-acid substitution economics.
Supply Chain Analysis
Upstream feedstock concentration centers on Australian hard-rock spodumene for Class 1 lithium hydroxide, Chinese synthetic graphite from Shandong processing clusters, and Korean/Japanese separator membrane production. Cell-grade LFP cathode active material draws from Yangtze River Delta precursor plants, while electrolyte formulations rest on fluorinated salt supply from domestic Chinese chemical majors. Single-source vulnerability concentrates in graphite anode processing, where Heilongjiang and Shandong facilities supply 70% of non-Chinese pack demand. Distribution runs through direct-to-consumer brand e-commerce, specialty outdoor retail, and emergency preparedness distributors, with subscription financing displacing traditional channel stocking in German and US markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable lithium battery energy storage is approaching a platform-economics inflection where firmware ecosystems and V2H protocol interoperability determine customer lifetime value capture. Manufacturers embedding bidirectional charging standards and app-enabled service layers are repositioning hardware margins into recurring revenue architectures.
For Market Incumbents: Entrench proprietary firmware infrastructure and BMS algorithm IP against modular open-standard challengers. Lock multi-year offtake agreements with Australian spodumene producers to secure carbon-audited lithium hydroxide before EU Battery Regulation due diligence obligations harden. Expand in-house LFP pack assembly capacity in Arizona and Texas industrial corridors to capture IRA domestic content tax credits and compress logistics costs for North American demand.
For New Entrants and Emerging Players: Pursue India rural electrification retrofits where 500-1500Wh lithium replacements of lead-acid storage face limited incumbent saturation. Target emergency services procurement channels fed by federal and municipal preparedness grants, where MIL-STD-810G certification requirements create defensible moats against consumer-grade competitors. Deploy direct-to-consumer subscription financing with extended return windows to reduce perceived adoption risk for first-time lithium storage buyers.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with captive battery management system firmware teams stranded outside core operations. Long-term viability favors assemblers with backward integration into LFP pack design and channel control through owned e-commerce rather than retail-dependent intermediaries. Watch V2H protocol standardization progress as the inflection signal — convergence with electric vehicle onboard charger architectures will determine which portable power station brands access automotive aftermarket channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LFP Pack Assembly | Captures IRA tax credits and collapses cell-to-system cost structures for 2000-5000Wh units. |
| Firmware Ecosystem Development | Converts transactional hardware sales into recurring service revenue through app-enabled feature unlocks. |
| Carbon-Audited Supply Chain Lock | Secures Australian spodumene offtake to satisfy EU Battery Regulation mine-to-module documentation mandates. |
| V2H Protocol Certification | Opens automotive aftermarket channel access through bidirectional charging integration with EV onboard systems. |
| Direct-to-Consumer Subscription Financing | Displaces retail margin compression by capturing attach-rate economics through brand-owned e-commerce. |
Research Methodology
A spread of perspectives from battery management system firmware engineers, pack assembly procurement leads, outdoor recreation retail buyers, and emergency preparedness distributors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through UN 38.3 testing laboratory filings, IRA domestic content guidance documents, and EU Battery Regulation implementation drafts. Bottom-up demand modeling triangulated against top-down cathode active material production capacity data from Jiangsu and Fujian province industrial bureaus.
Demand-supply balance dynamics across the analysis window anchored volume projections, with segmentation by chemistry type, capacity tier, and end-use archetype. The modeling framework incorporated product type splits across solar generators, power banks, and UPS systems; technology distinctions between LFP, NMC, and emerging solid-state formulations; and regional regulatory clusters reflecting FCC, CE marking, and GB standard compliance pathways. CAGRs derived from cell-grade cost curve trajectories and substitution elasticity estimates for lead-acid displacement in emerging markets.
Sensitivities concentrate around UN 38.3 certified laboratory capacity constraints, graphite anode supply disruption scenarios, and V2H protocol standardization timing. Forecasts reflect documented assumptions on LFP cathode cost compression rates and IRA domestic content interpretation stability. Cross-checking against IEA stationary storage deployment benchmarks and customs trade data for lithium-ion battery export flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
Automotive Cylindrical Lithium Batteries Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
Bangladesh Lithium-Ion Battery Market
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market