
 Vacuum Evaporators Market | 2026-2036
Vacuum Evaporators Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Evaporators Market Analysis
High-purity pharmaceutical-grade specifications is bifurcating the competitive landscape into premium engineering specialists and commodity equipment suppliers. Alfa Laval leverages its heat transfer technology portfolio to dominate falling film evaporator deliveries for European biopharma clients. GEA Group anchors its position through backward integration into stainless steel fabrication and in-house welding automation for ASME-coded vessels. Veolia Water Technologies differentiates via integrated service contracts that bundle evaporator hardware with remote monitoring and chemical optimization.
A vacuum evaporator is a thermal separation device that operates at sub-atmospheric pressure to lower the boiling point of process liquids, typically achieving temperatures between 40°C and 80°C to protect heat-sensitive compounds from degradation. The system relies on a vacuum pump, heat exchanger, and condenser to separate solvents or water from dissolved solids, salts, or concentrated products for industrial recovery and waste minimization. Falling film evaporators command the largest installed base in food processing due to gentle product handling and short residence times, though mechanical vapor recompression technology is capturing the fastest growth trajectory as energy costs reshape total cost of ownership calculations. Wastewater treatment applications concentrate margin pools in zero-liquid-discharge configurations where brine concentrators and crystallizers command premium pricing against conventional thermal evaporation.
The US EPA enforces effluent limitation guidelines that push chemical manufacturers toward closed-loop vacuum evaporation rather than discharge-intensive alternatives. EU REACH and the Industrial Emissions Directive compel solvent recovery rates above 95% in pharmaceutical and coatings operations, directly specifying thermal separation equipment performance. China's MEE implements stricter wastewater discharge standards for industrial parks that mandate evaporation-based concentration prior to deep well injection or crystallization. Stakeholders must monitor how carbon border adjustment mechanisms reshape the economics of energy-intensive thermal separation relative to membrane-based alternatives.
Market Dynamics
Mechanical vapor recompression technology is compressing energy intensity benchmarks across pharmaceutical and chemical processing clusters, forcing equipment upgrade cycles that favor integrated thermal separation systems over standalone evaporator units.
Growth Catalysts
- EU REACH solvent recovery mandates:Pharmaceutical manufacturers in Germany and the Netherlands must achieve recovery rates above 95%, compelling capital deployment into vacuum distillation trains with integrated evaporator-crystallizer sequences.
- China's MEE wastewater discharge standards:Industrial parks in Jiangsu and Shandong provinces face mandatory evaporation-based concentration prior to crystallization or deep well injection, driving retrofit demand across chemical and coatings facilities.
- Zero-liquid-discharge configurations:Brine concentrators paired with vacuum evaporators command premium positioning in semiconductor fabrication and battery material processing where wastewater volumes strain municipal treatment capacity.
Market Restraints
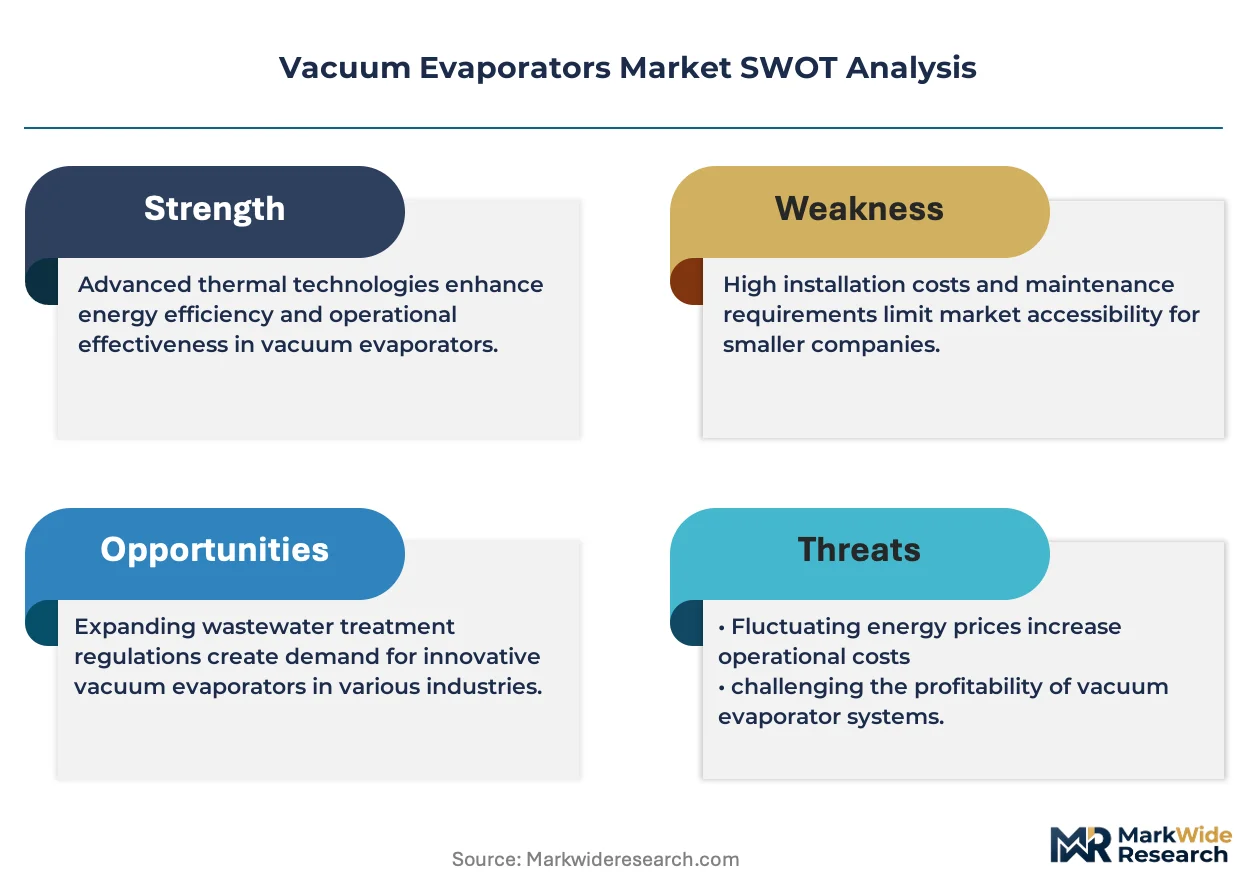
- Stainless steel price volatility:ASME-coded vessel fabrication depends on 316L and 904L alloy feedstock, with nickel content fluctuations compressing margin pools for mid-scale equipment fabricators.
- Specialized welding automation scarcity:Certified orbital welding capacity concentrates in German and Italian fabrication shops, creating bottlenecks for non-integrated suppliers lacking in-house vessel production.
- Membrane pre-concentration substitution:Reverse osmosis and nanofiltration systems capture dilute feed streams below 5% solids, shrinking the addressable volume for thermal evaporators in municipal and light industrial applications.
Strategic Opportunities
- India's pharmaceutical API clusters:Hyderabad and Ahmedabad manufacturing corridors lack solvent recovery infrastructure, creating first-mover positioning for evaporator-leasing models with chemical optimization bundled.
- Heat pump integration with MVR systems:Industrial heat pumps harvesting low-grade waste heat are converging with mechanical vapor recompression to slash steam demand in food and biochemical processing.
- Remote monitoring service contracts:Veolia and Suez have demonstrated bundled hardware-software offerings, opening white space for independent software vendors to unbundle predictive maintenance from captive equipment sales.
Industry Challenges
- ASME Section VIII certification timelines:Pressure vessel qualification for pharmaceutical-grade applications requires 12-18 month validation cycles, compressing product development cadence for new entrants.
- Legacy DCS integration complexity:Brownfield chemical plants operate proprietary distributed control systems from Honeywell or Yokogawa, forcing costly custom protocol bridges for evaporator automation retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Evaporators Market |
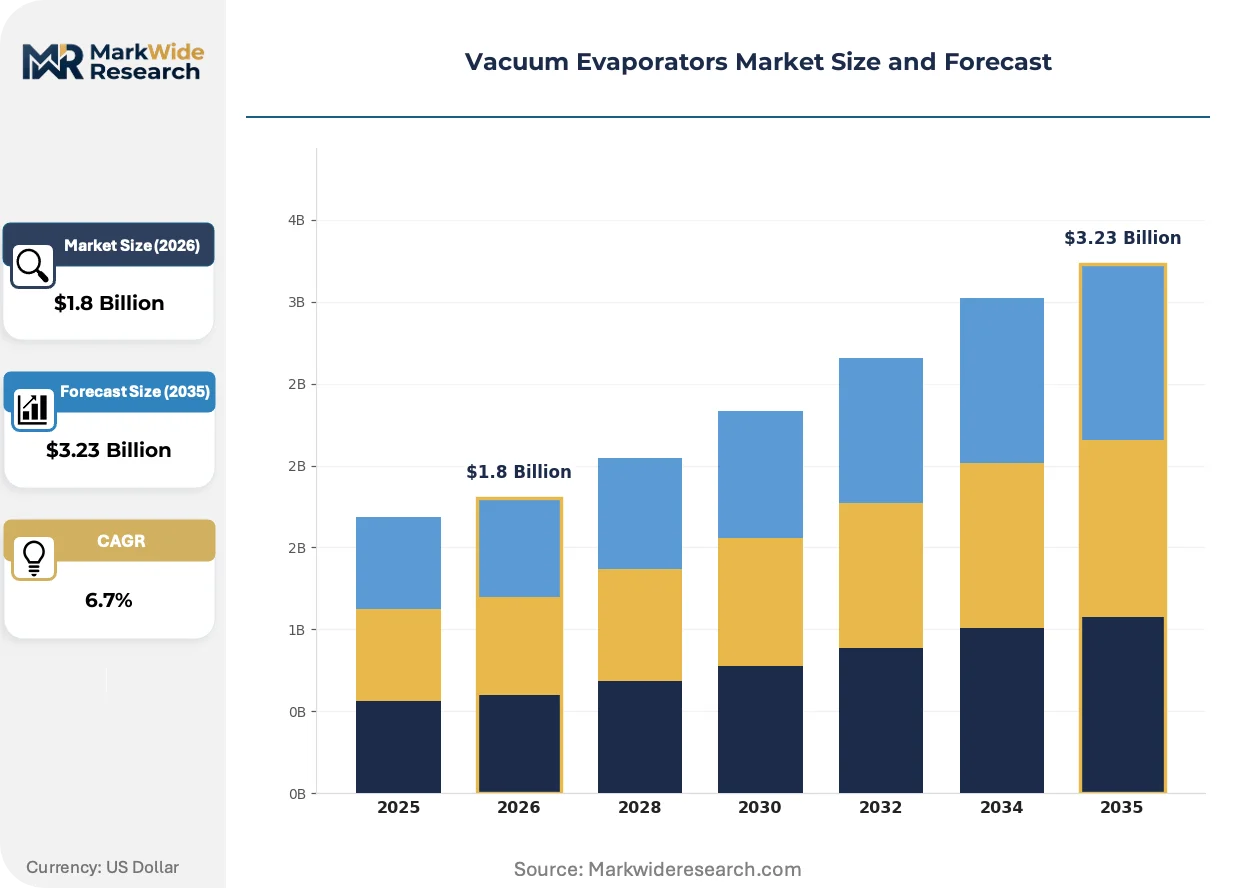
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brine Concentrators, Thin Film Evaporators, Falling Film Evaporators, Plate Evaporators End User: Food Processing, Pharmaceutical Industry, Chemical Manufacturing, Wastewater Treatment Technology: Mechanical Vapor Recompression, Multi-Effect Distillation, Reverse Osmosis, Thermal Evaporation Application: Concentration, Crystallization, Solvent Recovery, Desalination |
| Companies Covered | SPX Flow, De Dietrich Process Systems, Veolia Water Technologies, H2O GmbH, Saltworks Technologies, Alfa Laval, Condorchem Enviro Solutions, Suez Water Technologies & Solutions, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Evaporators Market Emerging Trajectories
Thermal separation hardware is converging with digital optimization layers and energy recovery subsystems, compressing the traditional boundaries between evaporator OEMs, process control vendors, and utility-scale engineering contractors.
Hybrid mechanical vapor recompression systems integrating industrial heat pumps are displacing conventional multi-effect evaporator trains in dairy and biochemical applications. European dairy cooperatives in Denmark and the Netherlands pilot these configurations to harvest waste heat from spray dryers, cutting steam consumption by half. The technology is compressing total cost of ownership calculations that previously favored membrane pre-treatment cascades.
China's MEE implements progressively stricter total dissolved solids limits for industrial park effluent, mandating evaporation-based concentration prior to zero-liquid-discharge crystallization. Chemical manufacturers in Shandong province retrofit solvent recovery infrastructure to comply with 2024 discharge amendments. Pharmaceutical clusters in Jiangsu accelerate thermal separation equipment procurement to avoid production suspension penalties.
Equipment-as-a-service contracting is displacing traditional capex purchasing in mid-scale chemical processing. Specialty chemical manufacturers in Germany and Switzerland lease falling film evaporators with guaranteed throughput and energy performance, transferring operational risk to OEM service arms. The model concentrates most visibly in pharmaceutical intermediates production where batch variability complicates internal capacity planning.
Vacuum Evaporators Market Segmentation
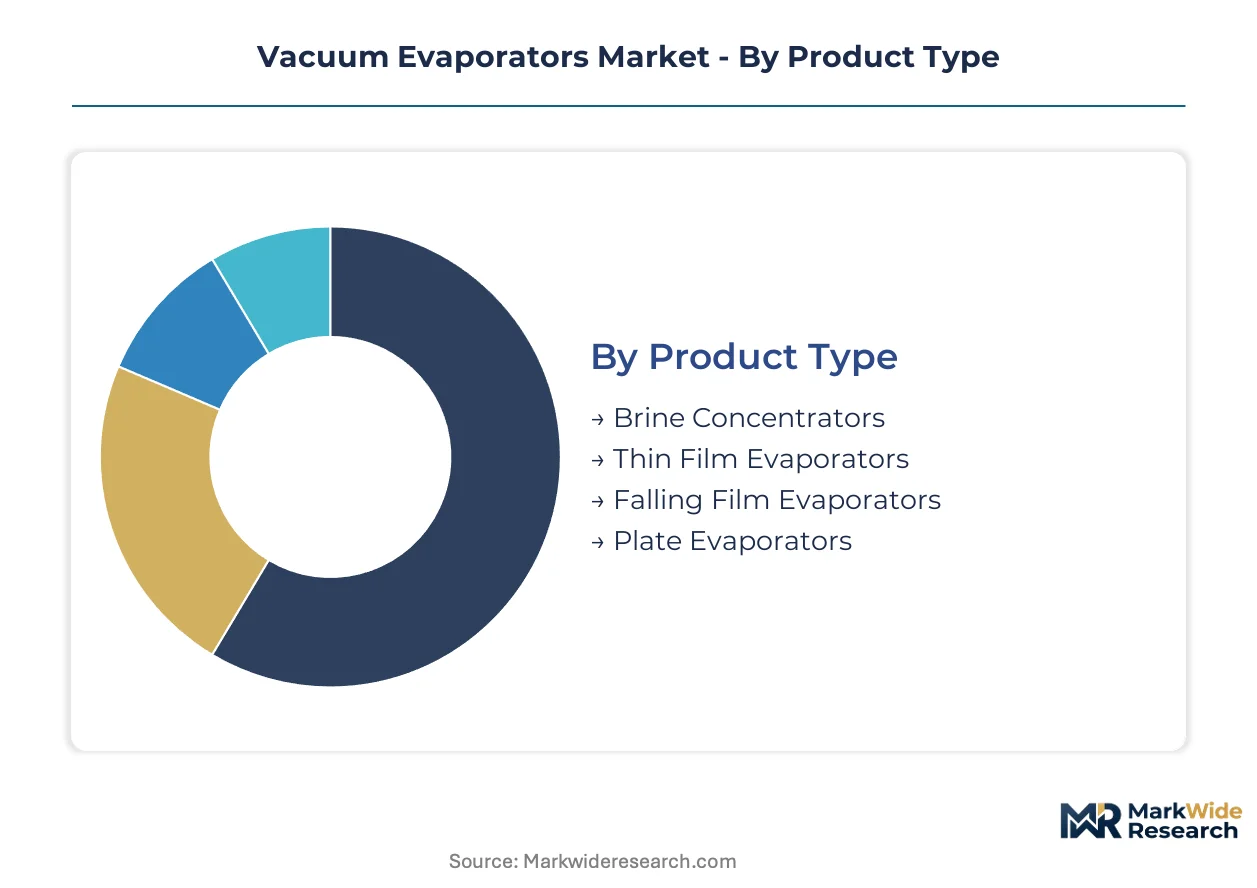
Technology substitution pressures and regulatory compliance costs fragment procurement patterns across vacuum evaporator categories. Buyers in pharmaceutical and chemical processing prioritize energy efficiency specifications over capital expenditure minimization, reshaping vendor prioritization across product configurations.
Product Type:
Membrane pre-concentration systems exert the strongest substitution pressure on thermal evaporator formats handling dilute feed streams below five percent solids.
- Falling Film Evaporators:These systems distribute process liquid as a thin film across heated vertical tubes, achieving residence times under thirty seconds to protect heat-sensitive compounds. Dairy cooperatives in Denmark and the Netherlands specify falling film configurations for milk powder concentration where protein denaturation risks disqualify longer-residence alternatives. EU energy efficiency directives accelerate replacement of aging calandria evaporators in these applications.
- Thin Film Evaporators:A rotating wiper blade maintains turbulent liquid films on heated cylindrical surfaces, enabling viscous or fouling-prone feed handling at temperatures down to forty degrees Celsius. Pharmaceutical API manufacturers in Hyderabad and Ahmedabad deploy thin film units for high-boiling-point solvent recovery where product degradation thresholds are narrow. India's CDSCO enforcement of solvent emission limits drives retrofit demand in these clusters.
- Brine Concentrators:Specialized forced-circulation crystallizers achieve total dissolved solids above twenty percent for zero-liquid-discharge compliance.
- Plate Evaporators:Compact gasketed or welded plate heat exchanger configurations serve smaller throughput requirements in food ingredient processing.
Falling film evaporators anchor the volume base while thin film evaporators gain share at the steepest rate.
End User:
Margin compression in commodity chemical processing forces equipment vendors toward service-contract differentiation, while premium pharmaceutical applications sustain standalone hardware pricing.
- Pharmaceutical Industry:Sterile-grade evaporator trains with ASME-BPE surface finish requirements command three-tier pricing stratification across premium certified, standard industrial, and economy non-validated equipment tiers. German and Swiss manufacturers deploy integrated evaporator-crystallizer sequences to meet EU REACH solvent recovery mandates above ninety-five percent. EMA inspection protocols for active pharmaceutical ingredient production enforce documentation standards that exclude non-specialist fabricators.
- Wastewater Treatment:Zero-liquid-discharge configurations pair brine concentrators with crystallizers for semiconductor fabrication and battery material processing facilities. China's MEE progressively tightens total dissolved solids discharge limits for industrial parks in Jiangsu and Shandong provinces, mandating evaporation-based concentration prior to deep well injection. Municipal treatment capacity constraints in these regions accelerate capital deployment.
- Chemical Manufacturing:Solvent recovery infrastructure retrofits dominate capital planning for coatings and specialty chemical producers.
- Food Processing:Dairy and ingredient concentration applications prioritize gentle thermal handling and short residence times.
Wastewater treatment anchors the volume base while pharmaceutical applications climb the fastest on regulatory compliance spending.
Technology:
Energy cost trajectories reshape total cost of ownership calculations, compressing payback period advantages that previously favored conventional thermal alternatives.
- Mechanical Vapor Recompression:Centrifugal or positive-displacement compressors recycle evaporated vapor as heating steam, cutting external energy demand by sixty to eighty percent versus single-effect evaporation. European dairy cooperatives pilot hybrid configurations integrating industrial heat pumps to harvest waste heat from spray dryers. These installations demonstrate steam consumption reductions exceeding fifty percent against multi-effect benchmark trains.
- Multi-Effect Distillation:Sequential pressure-staged evaporator bodies cascade vapor reuse across multiple temperature levels, balancing capital intensity against energy efficiency in large-scale desalination and chemical processing. Middle Eastern desalination contractors specify multi-effect thermal vapor compression for seawater applications where membrane fouling risks are prohibitive.
- Thermal Evaporation:Single-effect or steam-driven configurations persist in small-scale applications with simple feed chemistries.
- Reverse Osmosis:Membrane-based desalination and pre-concentration systems compete for dilute feed streams below five percent solids, shrinking thermal evaporator addressable volume in municipal and light industrial segments.
Multi-effect distillation anchors the volume base while mechanical vapor recompression expands most quickly on energy cost pressures.
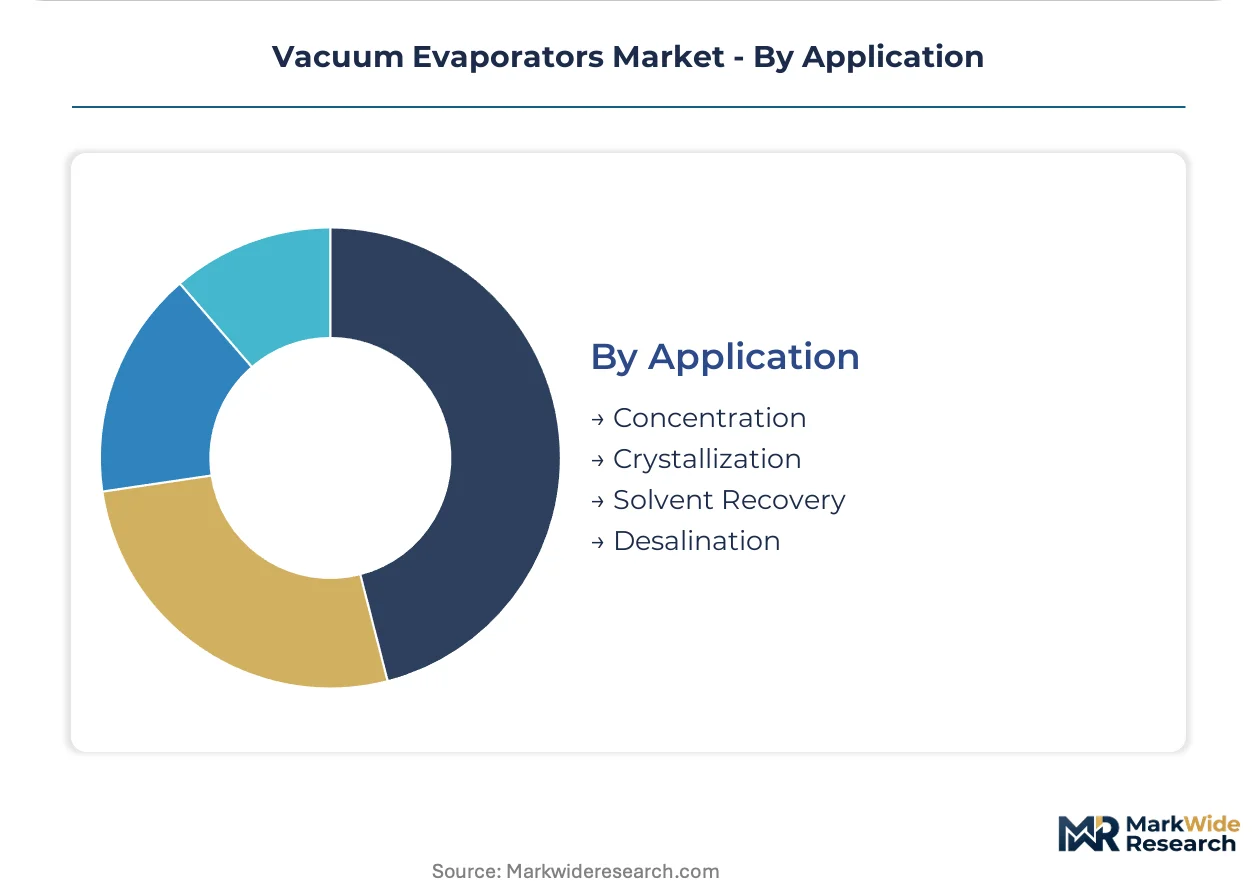
Application:
Crystallization and solvent recovery applications sustain premium pricing through integrated system complexity, while concentration functions face commoditization from membrane alternatives.
- Solvent Recovery:Integrated vacuum distillation trains with condenser and decanter subsystems achieve recovery rates above ninety-five percent for pharmaceutical and coatings operations. EU REACH framework enforcement compels German manufacturers to upgrade thermal separation equipment, directly specifying evaporator performance standards. Solvent recovery margins concentrate in turnkey engineering contracts bundling hardware with solvent-specific chemical optimization.
- Crystallization:Forced-circulation or draft-tube-baffle crystallizers downstream of brine concentrators produce solid salt products for zero-liquid-discharge compliance. Semiconductor fabrication facilities in Taiwan and South Korea deploy these configurations where wastewater volumes strain municipal treatment infrastructure.
- Concentration:Standard evaporator functions in food, chemical, and wastewater applications face displacement by reverse osmosis and nanofiltration pre-treatment.
- Desalination:Thermal desalination persists in regions with high-salinity feedwater or membrane-fouling risk profiles.
Concentration anchors the volume base while solvent recovery gains share fastest on regulatory compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment fabricators export vacuum evaporator systems to pharmaceutical clusters in India and China, while US-based engineering contractors supply zero-liquid-discharge configurations to semiconductor fabrication facilities across East Asia.
United States
Semiconductor fabrication facilities in Arizona and Texas deploy brine concentrator-crystallizer sequences for zero-liquid-discharge compliance. The US EPA enforces effluent limitation guidelines that push chemical manufacturers toward closed-loop vacuum evaporation. Battery material processing plants in the Midwest retrofit thermal separation infrastructure to manage rising wastewater volumes.
Germany
Pharmaceutical manufacturers in Baden-Württemberg and North Rhine-Westphalia achieve solvent recovery rates above ninety-five percent through integrated evaporator-crystallizer trains. EU REACH framework enforcement compels coatings and specialty chemical producers to upgrade thermal separation equipment. The country's national pharmaceutical regulator enforces documentation standards that exclude non-specialist fabricators from sterile-grade supply chains.
China
Chemical parks in Jiangsu and Shandong provinces retrofit solvent recovery infrastructure to comply with progressively stricter wastewater discharge standards. The Ministry of Ecology and Environment mandates evaporation-based concentration prior to deep well injection or crystallization. Pharmaceutical clusters in Jiangsu accelerate thermal separation equipment procurement to avoid production suspension penalties.
India
Active pharmaceutical ingredient manufacturers in Hyderabad and Ahmedabad lack solvent recovery infrastructure, creating deployment opportunities for evaporator-leasing models. The Central Drugs Standard Control Organization enforces solvent emission limits that drive retrofit demand in these manufacturing corridors. Gujarat's chemical processing belt concentrates procurement activity for falling film and thin film evaporator configurations.
Japan
Biochemical processing facilities in the Kansai region pilot hybrid mechanical vapor recompression systems integrating industrial heat pumps. The Ministry of Economy, Trade and Industry supports energy efficiency upgrades across dairy and food ingredient processing clusters. Osaka-based engineering contractors supply compact plate evaporator configurations to Southeast Asian food processing markets.
Vacuum Evaporators Market Vendor Landscape
Listed leaders compete with private specialists across engineering depth and service integration. The vendor base spans three tiers: diversified process equipment conglomerates with heat transfer portfolios, water technology specialists bundling hardware with chemical optimization, and regional fabrication shops serving commodity applications. Strategic archetypes include integrated thermal separation system providers, equipment-as-a-service operators, and ASME-certified vessel specialists. Competitive moves concentrate on backward integration into stainless steel fabrication and geographic expansion through local commissioning partnerships.
Among European-based diversified engineering groups, Alfa Laval AB, GEA Group AG, and Veolia Water Technologies occupy positions across the premium equipment and integrated services spectrum. Alfa Laval exemplifies the heat transfer technology archetype through its falling film evaporator positioning. GEA Group AG represents backward integration into stainless steel fabrication and in-house welding automation. Veolia Water Technologies anchors the bundled hardware-software service model with remote monitoring and chemical optimization contracts. SPX Flow, Inc. sits within the US-based process equipment tier serving food and industrial applications. De Dietrich Process Systems S.A.S. and Condorchem Enviro Solutions SL represent European specialists in corrosion-resistant and environmental configurations respectively.
| Leading Market Players |
|---|
| SPX Flow |
| De Dietrich Process Systems |
| Veolia Water Technologies |
| H2O GmbH |
| Saltworks Technologies |
| Alfa Laval |
| Condorchem Enviro Solutions |
| Suez Water Technologies & Solutions |
| GEA Group |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-month ASME Section VIII certification timelines compress inventory turnover for pharmaceutical-grade vessel fabricators, concentrating pricing power with German and Italian shops that command premium positioning against Asian competitors lacking orbital welding automation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers extract value through ASME-BPE surface finish certification and integrated service bundling, while commodity equipment faces downward pressure from membrane pre-concentration substitution in dilute feed applications. Pharmaceutical manufacturers show lowest price sensitivity due to regulatory compliance mandates, whereas municipal wastewater operators prioritize capital expenditure minimization.
Supply Chain Analysis
Germany and Italy anchor precision vessel fabrication through certified orbital welding capacity for ASME-coded equipment. Stainless steel feedstock draws from global nickel markets, with 316L and 904L alloy specifications tethered to commodity price volatility. Single-source vulnerability concentrates in specialized welding automation, while distribution runs through engineering-procurement-construction contractors serving zero-liquid-discharge project clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical vapor recompression technology is disrupting energy intensity benchmarks across pharmaceutical and chemical processing, creating a high-growth window as EU REACH and China's MEE tighten solvent recovery and wastewater discharge mandates.
For Market Incumbents: Consolidate backward integration into stainless steel fabrication to defend margin pools against nickel price volatility. Capture certified orbital welding capacity in German and Italian fabrication shops before bottlenecks harden. Expand equipment-as-a-service contracting to transfer operational risk from price-sensitive mid-scale chemical processors. For New Entrants and Emerging Players: Remote monitoring service gaps in incumbent hardware offerings create white-space positioning for independent software vendors. Target India's pharmaceutical API clusters in Hyderabad and Ahmedabad with evaporator-leasing models bundling chemical optimization. Deploy heat pump integration with MVR systems as a differentiated energy efficiency pitch to European dairy cooperatives. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because zero-liquid-discharge mandates are hardening across semiconductor fabrication and battery material processing. Acquisition targets should display ASME certification depth and service contract recurring revenue. Watch carbon border adjustment mechanism implementation as the signal for thermal-versus-membrane technology economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Captive supply of 316L and 904L alloys insulates margin pools from nickel price volatility. |
| Equipment-as-a-Service Contracting | Leasing models with guaranteed throughput transfer operational risk from pharmaceutical intermediate producers. |
| Heat Pump Integration with MVR Systems | Hybrid configurations harvesting spray dryer waste heat cut steam consumption for Danish dairy cooperatives. |
| Remote Monitoring Service Unbundling | Predictive maintenance software separates from captive equipment sales, opening white space for independent vendors. |
| ASME-BPE Certification Investment | Sterile-grade surface finish documentation excludes non-specialist fabricators from European biopharma supply chains. |
Methodological Framework
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary fieldwork combined with secondary validation from customs and trade data, SEC filings, and industry association reports covering ACC and Cefic chemical processing benchmarks. Bottom-up equipment shipment analysis triangulated against top-down wastewater infrastructure spending assessments.
Sensitivity analysis tested forecast outputs across technology substitution scenarios and regulatory implementation timelines. Segmentation dimensions modeled include evaporator technology type, end-use industry vertical, application function, and regional regulatory cluster. CAGRs derived from unit shipment trajectories and average selling price evolution, with energy cost projections and carbon pricing frameworks as key inputs.
Material uncertainties — stainless steel commodity volatility, ASME certification timeline extensions, membrane technology performance advances — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement intensity and industrial energy pricing. Recalibration cycles align with material shifts in EU carbon border adjustments and China's MEE discharge standard amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Underwater Lighting Market
Others
Europe Smart Homes Market
Others
Mainframe Market
Others
Wearable Brain Devices Market
Others
India 3D Printing Construction Market
Others
Live IP Broadcast Equipment Market
Others
Smart Home and Office Market
Others
Global Retail Media Networks Market
Others
Global Tobacco Market
Others
South Korea Smart Home Market
Others
Palatants Market
Others
Printing Machines Market
Others
Cat Food and Snacks Market
Others
North America Wiring Duct Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Latin America Smart Home Market