
 UK Cat Food Market | 2026-2036
UK Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
UK Cat Food Market Insights
The divide between premium and commodity cat food is hardening in concrete terms. Mars Petcare UK Ltd leverages its veterinary science heritage to command shelf space in specialist channels. Tesco Plc anchors the private-label economy tier through store-brand volume and distribution density. J Sainsbury Plc differentiates via tiered pricing across premium, standard, and economy levels.
Cat food comprises formulated nutritional products manufactured to FEDIAF and PFMA standards, typically containing protein meals, fats, vitamins, and moisture content calibrated to feline obligate carnivore physiology, with primary commercial purpose of delivering complete daily nutrition through retail and veterinary channels. Wet food leads value contribution due to higher unit pricing and palatability advantages, while raw diet occupies the fastest-growing niche as cold-chain logistics mature. Premium brand type captures the deepest margin pools, though private label competes aggressively on price.
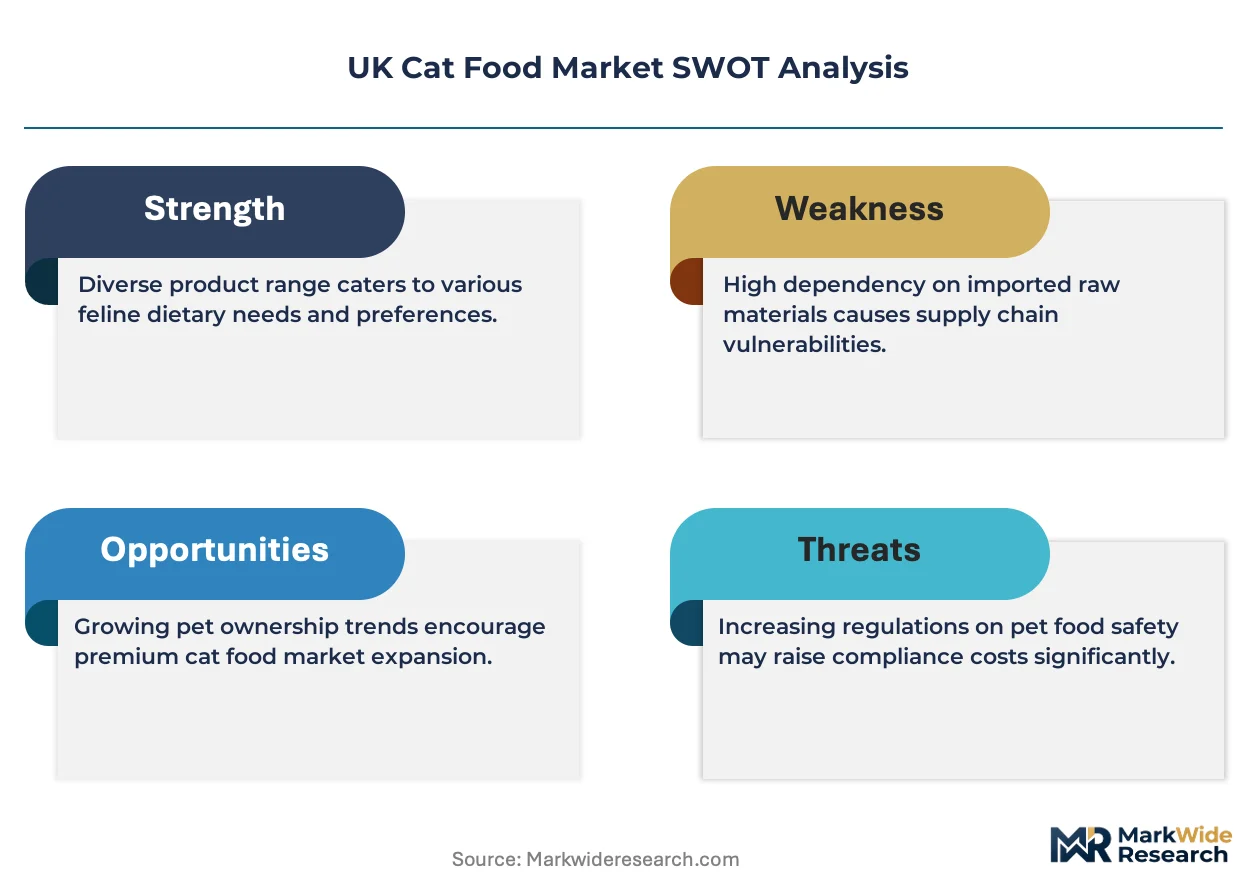
DEFRA enforces pet food hygiene and labeling rules under animal feed legislation, while FEDIAF sets nutritional adequacy protocols that manufacturers must meet for EU market access. The Food Standards Agency monitors contaminant thresholds, shaping reformulation priorities across suppliers. Stakeholders must monitor evolving PFMA sustainability commitments and potential packaging waste regulations that could reshape pouch and can supply chains.
Market Dynamics
Pet humanization among urban millennial households is compressing purchase cycles toward premium wet formats and subscription delivery, forcing manufacturers to reconfigure production lines for smaller batch sizes and higher moisture content formulations.
Growth Catalysts
- DEFRA Labeling Enforcement:Tightened ingredient disclosure rules under animal feed legislation are accelerating premium tier differentiation as brands compete on transparency credentials.
- Cold-Chain Logistics Maturation:Refrigerated last-mile networks in Greater London and the South East are enabling raw and fresh format penetration previously blocked by spoilage constraints.
- FEDIAF Nutritional Protocols:EU-wide adequacy standards are pulling UK manufacturers toward veterinary-channel certification, opening higher-margin prescription segments.
Market Restraints
- Animal Protein Input Volatility:Fish meal and poultry by-product prices fluctuate with agricultural commodity cycles, squeezing wet food margins disproportionately.
- Single-Source Packaging Concentration:Pouch and can supply chains cluster with limited UK-based converters, creating vulnerability to polymer feedstock disruptions.
- Raw Diet Safety Scrutiny:Food Standards Agency pathogen monitoring creates liability exposure that deters mainstream retail listing of unprocessed formats.
Strategic Opportunities
- Subscription Direct-to-Consumer Channels:Recurring delivery models bypass supermarket slotting fees and capture lifetime value data from millennial cat owners.
- PFMA Sustainability Commitments:Voluntary packaging reduction targets create first-mover advantage for recyclable mono-material pouch innovators ahead of potential mandates.
- Senior Cat Formulation Gap:Kidney-support and mobility-focused SKUs remain underdeveloped relative to aging UK feline demographics, presenting white space for condition-specific nutrition.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Formulation science expertise concentrates with legacy manufacturers, constraining new entrant R&D velocity.
- Legacy ERP Integration Friction:Batch-level traceability requirements for DEFRA compliance clash with decades-old production planning systems at mid-tier facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Cat Food Market |
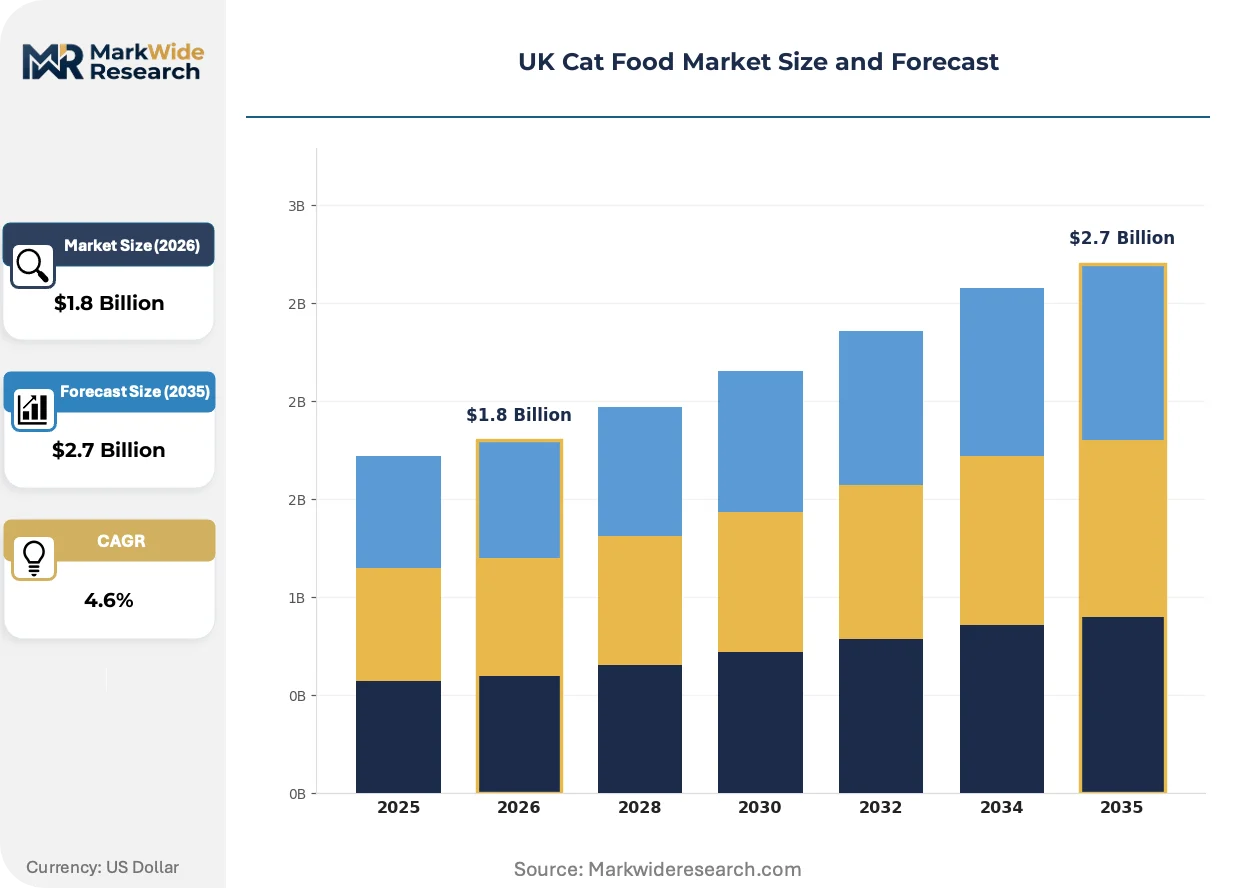
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Diet Ingredient Type: Meat, Fish, Grain-free, Vegetables Packaging Type: Bags, Cans, Pouches, Tubs Brand Type: Premium, Economy, Private Label, Organic |
| Companies Covered | J Sainsbury Plc, Tesco Plc, Asda Group Ltd, Pets Choice Ltd, Nestlé Purina Ltd, Mars Petcare UK Ltd, Hill's Pet Nutrition Ltd, Crown Pet Foods Ltd, MPM Products Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Cat Food Market Trends and Innovations
Reformulation priorities are pivoting toward moisture retention and palatability engineering as wet food claims value share from dry kibble, while regulatory pressure on packaging waste accelerates material science investment.
High-pressure processing for raw cat food is decentralizing production economics by eliminating the need for centralized retort facilities. Small-batch manufacturers in Bristol and Manchester are adopting HPP units to produce refrigerated raw meals locally. This technology is decentralizing supply chain geography and enabling regional brands to compete on freshness claims without national distribution infrastructure.
Extended Producer Responsibility packaging regulations are forcing UK manufacturers to redesign multi-layer pouches into recyclable mono-material structures. The industrial consequence is capital allocation toward polymer R&D partnerships rather than line expansion. Wet food brands targeting Tesco and Sainsbury shelves are most affected, responding with transparent sustainability roadmaps to secure retail listing renewals.
Millennial cat owners are consolidating purchases into subscription bundles combining food, litter, and veterinary supplements. Specialist online retailers are displacing supermarket periodic stocking for this demographic. Greater London exhibits the highest subscription penetration, where apartment-dwelling owners prioritize convenience delivery over bulk warehouse purchasing.
UK Cat Food Market Segmentation
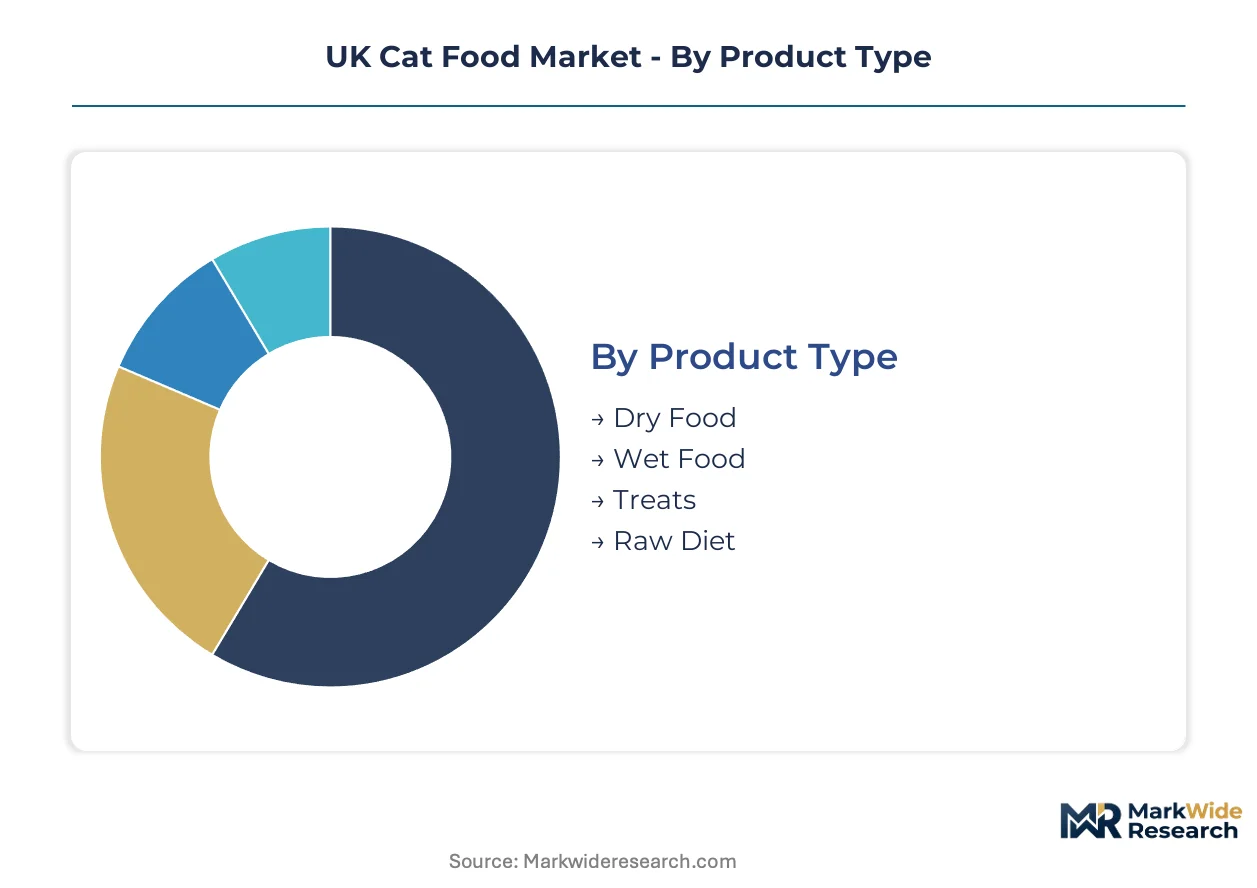
Cat food manufacturers configure production assets around format-specific moisture content, shelf-stability requirements, and retail channel slotting constraints. Segmentation discipline determines capital allocation between retort canning lines, extrusion dryers, and cold-chain refrigerated distribution networks.
Product Type:
Supply concentration clusters with wet food retort facilities in the Midlands and Greater London periphery, where pouch and can conversion capacity limits new entrant expansion.
- Wet Food:High-moisture formulations containing 75-85% water content, typically packaged in aluminum cans or multi-layer pouches. Demand concentrates in Greater London and the South East among urban millennial owners prioritizing palatability and hydration; DEFRA labeling enforcement is accelerating transparency claims on ingredient sourcing.
- Dry Food:Extruded kibble with 6-10% moisture content, offering extended shelf stability and lower per-calorie cost. Volume concentrates in supermarket economy tiers through Tesco and Sainsbury private-label programs; grain-free variants are displacing traditional cereal-based formulations in premium positioning.
- Treats:Supplementary caloric inputs including dental chews, freeze-dried protein pieces, and gravy-based toppers.
- Raw Diet:Unprocessed meat, bone, and organ blends requiring frozen or refrigerated distribution.
Wet food absorbs the bulk of installed capacity; raw diet is expanding most quickly.
Ingredient Type:
Cost tier stratification separates commodity poultry by-product formulations from single-source protein positioning in veterinary and specialist channels.
- Meat:Poultry, beef, and game-derived protein meals supplying essential taurine and amino acid profiles for obligate carnivore nutrition. Premium positioning concentrates on named single-source specifications; FEDIAF nutritional protocols are pulling manufacturers toward veterinary-channel certification for therapeutic formulations.
- Fish:Salmon, tuna, and whitefish meals delivering omega-3 fatty acid content. Whitefish variants from North Atlantic sourcing command shelf space in Sainsbury premium tiers; marine ingredient volatility is squeezing margin pools disproportionately against poultry-based alternatives.
- Grain-free:Potato, pea, and legume carbohydrate substitutes eliminating wheat and corn fillers.
- Vegetables:Supplementary fiber and micronutrient inputs including pumpkin, spinach, and carrot inclusions.
Meat-based formulations dominate volume throughput; grain-free is gaining share fastest.
Packaging Type:
Margin structure varies sharply by material conversion economics and Extended Producer Responsibility compliance exposure.
- Pouches:Flexible multi-layer or emerging mono-material structures enabling portion control and storage efficiency. Multi-layer supply chains cluster with limited UK-based converters, creating polymer feedstock vulnerability; PFMA sustainability commitments are forcing redesign toward recyclable mono-material alternatives ahead of potential mandates.
- Cans:Aluminum and steel cylindrical containers for wet food retort processing. Standard formats anchor economy-tier supermarket listings; cylindrical geometry limits shelf facings versus pouch flexibility in constrained retail environments.
- Bags:Multi-wall paper and plastic laminated structures for dry food bulk distribution.
- Tubs:Injection-molded polypropylene containers for fresh and refrigerated raw formats.
Pouches absorb the bulk of wet food capacity; mono-material recyclable alternatives are climbing the fastest.
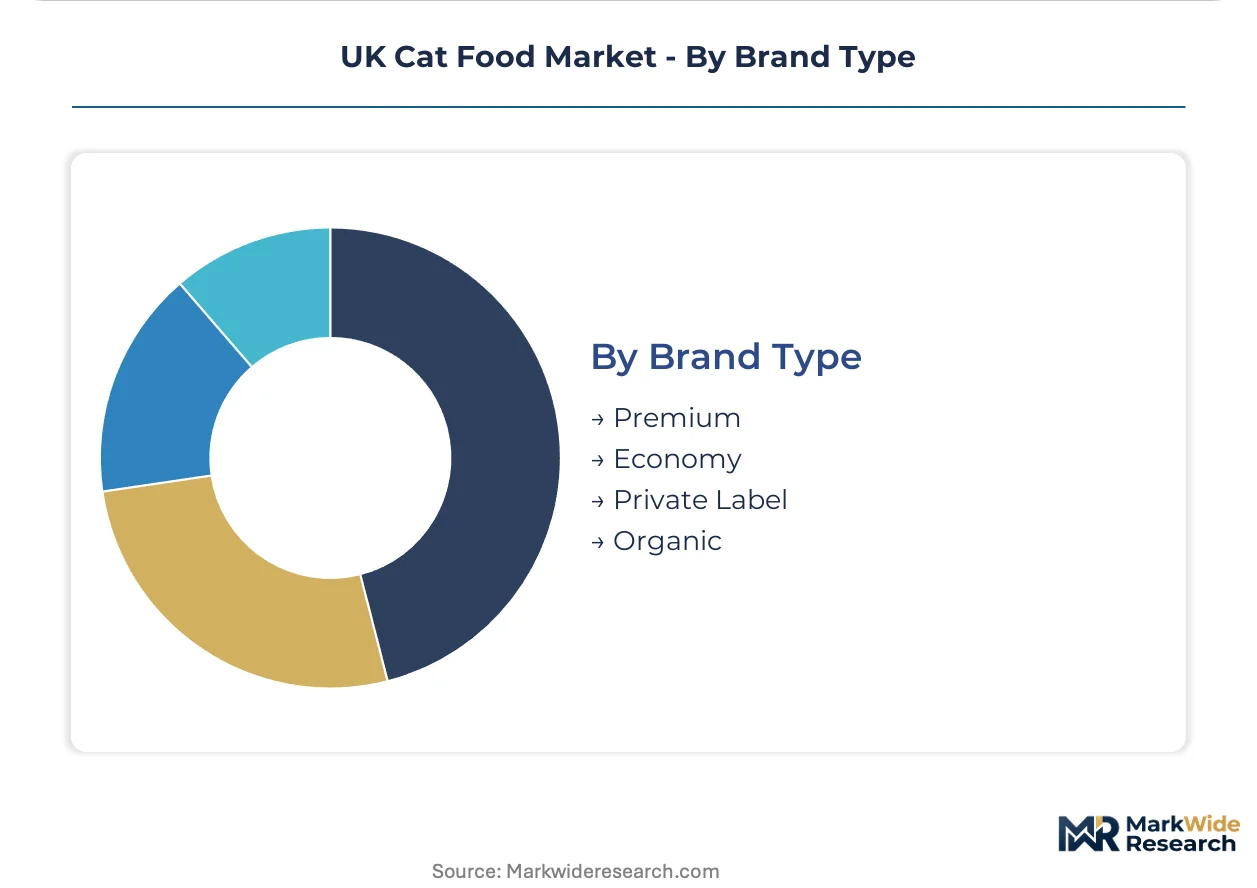
Brand Type:
Customer type segmentation separates subscription-direct millennial households from price-sensitive supermarket bulk purchasers.
- Premium:Veterinary science-backed formulations with named protein specifications and absence of artificial preservatives. Mars Petcare UK leverages heritage credentials to command specialist channel shelf space; kidney-support and mobility-focused SKUs remain underdeveloped relative to aging UK feline demographics.
- Private Label:Retailer-controlled brands manufactured through co-packing arrangements. Tesco anchors economy-tier volume through store-brand distribution density; tiered pricing structures across premium, standard, and economy levels enable Sainsbury differentiation.
- Economy:Commodity formulations prioritizing caloric density over ingredient specification transparency.
- Organic:Certified synthetic pesticide and antibiotic-free ingredient chains with audited supply traceability.
Premium positioning captures the deepest margin pools; private label competes aggressively on price.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London anchors UK cat food demand concentration, with millennial apartment-dwelling households driving premium wet format adoption through subscription delivery channels. Cold-chain logistics maturation in the South East is enabling raw diet penetration previously blocked by spoilage constraints.
London and the South East
Urban millennial pet humanization trends compress purchase cycles toward premium wet formats and subscription bundles. DEFRA labeling enforcement under animal feed legislation accelerates transparency claims on ingredient sourcing. Specialist online retailers in Greater London displace supermarket periodic stocking for this demographic.
Midlands
Wet food retort facilities cluster in the Midlands, where pouch and can conversion capacity limits new entrant expansion. FEDIAF nutritional protocols pull manufacturers toward veterinary-channel certification for therapeutic formulations. Birmingham and Leicester host co-packing operations serving private-label programs for major supermarket chains.
North England
Economy-tier dry food volume concentrates in Manchester and Leeds through supermarket distribution density. PFMA sustainability commitments force packaging redesign toward recyclable mono-material alternatives. Regional brands compete on price against national private-label offerings from Tesco and Sainsbury.
Scotland
Whitefish ingredient sourcing from North Atlantic fisheries supports premium positioning in Edinburgh and Glasgow. Food Standards Agency pathogen monitoring creates liability exposure that deters mainstream retail listing of unprocessed formats. Local cold-chain networks enable fresh format trials in affluent urban postcodes.
Wales
Agricultural by-product supply chains in rural Wales feed into poultry and fish meal processing for commodity formulations. Extended Producer Responsibility regulations pressure manufacturers to redesign multi-layer pouches. Cardiff and Newport serve as distribution nodes for South West England retail networks.
UK Cat Food Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the UK cat food market, with multinational manufacturers operating dedicated retort facilities while specialist brands outsource to co-packers. The structure tiers between veterinary science-backed premium players and retailer-controlled private-label volume. Three archetypes dominate: multinational heritage brands leveraging R&D scale, supermarket chains anchoring economy tiers through distribution density, and emerging specialists exploiting subscription direct-to-consumer channels. Competitive moves concentrate on M&A for formulation talent and capacity expansion in cold-chain refrigerated distribution.
Within the multinational heritage tier, Mars Petcare UK Ltd and Nestlé Purina Ltd exemplify veterinary science-backed positioning through specialist channel shelf space command. Among retailer-controlled fabricators, Tesco Plc and J Sainsbury Plc occupy positions as private-label volume anchors through store-brand distribution density and tiered pricing structures. These five entities represent the competitive core around which mid-tier specialists and emerging subscription brands maneuver for positioning.
| Leading Market Players |
|---|
| J Sainsbury Plc |
| Tesco Plc |
| Asda Group Ltd |
| Pets Choice Ltd |
| Nestlé Purina Ltd |
| Mars Petcare UK Ltd |
| Hill's Pet Nutrition Ltd |
| Crown Pet Foods Ltd |
| MPM Products Ltd |
| Others |
Pricing and Supply Chain Analysis
Premium wet food's hydration-value proposition against dry kibble's commodity positioning creates divergent margin structures across UK manufacturing footprints. DEFRA labeling enforcement and FEDIAF certification requirements feed directly into ingredient sourcing premiums and retort facility capital allocation decisions.
Pricing Analysis
Value-based pricing anchored on palatability outcomes and veterinary-channel certification separates Mars Petcare UK's specialist positioning from Tesco's private-label economy tier. Three-tier pricing structure across premium, standard, and economy levels enables Sainsbury differentiation through named protein specifications versus commodity poultry by-product formulations. Cost compression in wet food margins intensifies because fish meal and poultry by-product prices fluctuate with agricultural commodity cycles. Supermarket bulk purchasers exhibit highest price sensitivity; subscription-direct millennial households in Greater London show lowest sensitivity due to convenience bundling with litter and veterinary supplements.
Supply Chain Analysis
Formulation science expertise scarcity in the Midlands and Greater London periphery constrains new entrant R&D velocity and batch-level traceability compliance. Wet food retort facilities cluster in the Midlands, while cold-chain refrigerated networks concentrate in Greater London and the South East. Raw diet production draws from Bristol and Manchester HPP-equipped small-batch manufacturers. Single-source packaging concentration with limited UK-based pouch and can converters creates polymer feedstock vulnerability. Distribution runs through supermarket slotting fee structures for economy tiers and specialist online subscription platforms for premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK cat food market sits in a technology-transition phase as high-pressure processing displaces centralized retort infrastructure for raw and fresh formats. Cold-chain logistics maturation and mono-material packaging innovation are rewriting production economics and retail listing requirements.
For Market Incumbents: To counter subscription-direct specialists displacing supermarket periodic stocking, Mars Petcare UK and Nestlé Purina Ltd should deepen veterinary-channel certification investments under FEDIAF protocols to secure prescription segment margins. Backward integration into named single-source protein supply chains mitigates animal protein input volatility squeezing wet food margins. For New Entrants and Emerging Players: Begin with kidney-support and mobility-focused senior cat formulations where SKU development lags aging UK feline demographics. Raw diet penetration in Greater London and the South East offers the most penetrable geography given cold-chain logistics maturation. Specialist online subscription bundling with veterinary supplements provides the clearest go-to-market angle to bypass supermarket slotting fees. For Investors and Strategic Acquirers: Re-rating potential sits with HPP-equipped regional manufacturers given decentralization of production economics away from centralized retort facilities. Long-term viability favors asset-light designers with co-packer relationships over capital-heavy retort facility operators. Watch PFMA sustainability commitment enforcement as inflection indicator for mono-material packaging innovators ahead of potential Extended Producer Responsibility mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary-Channel Certification Investment | FEDIAF nutritional protocol compliance opens higher-margin prescription segments for therapeutic formulations. |
| Mono-Material Packaging Redesign | PFMA sustainability commitments ahead of Extended Producer Responsibility regulations secure Tesco and Sainsbury listing renewals. |
| Subscription Direct-to-Consumer Launch | Recurring delivery models capture lifetime value data from millennial cat owners in Greater London. |
| High-Pressure Processing Capacity Addition | HPP units in Bristol and Manchester enable regional brands to compete on freshness claims without national distribution infrastructure. |
| Senior Cat Formulation Development | Kidney-support and mobility-focused SKUs address white space relative to aging UK feline demographics. |
Research Methodology
Independent corroboration across DEFRA regulatory filings, FEDIAF nutritional adequacy protocols, and PFMA sustainability commitment disclosures underwrites the qualitative findings in this study. Primary interviews with pet food formulation scientists, veterinary nutritionists, supermarket category buyers, and cold-chain logistics operators combined with secondary validation from trade association reports and customs records. Bottom-up production capacity assessments and top-down retail audit data triangulate market sizing.
Comparable-period anchoring to historical retort facility utilization rates and cold-chain penetration metrics established the forecast window baseline. Segmentation modeling across product type, ingredient type, packaging type, and brand type dimensions structured volume and value projections over the projection horizon. CAGRs derived from trend extrapolation of millennial pet humanization rates, DEFRA enforcement trajectory, and polymer feedstock cost curves.
Animal protein price volatility, Extended Producer Responsibility implementation timing, and raw diet pathogen liability exposure are the dominant revision risks to forecast assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Machine Vision Systems Market
Others
Infant Positioning Aids Market
Others
Astrology Market
Others
Gym Wipes Market
Others
Internet Protocol Television (IPTV) Market
Others
Latin America Contract Packaging Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Paraffin Physical Therapy Market
Others
Rugged Tablet Market
Others
Nanomedicine for Drug Delivery Market
Others
Brazil Passenger Vehicles Lubricants Market
Others
Printing Machines Market
Others
Paper Shredder Market
Others
Brazil Lime Market
Others
Middle East Smart Home Market
Others
Industrial Computers Market