
 Italy Smart Home Market | 2026-2036
Italy Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Smart Home Market Insights
Italian electrical engineering talent is rotating toward IoT firmware and wireless protocol development, unlocking design capacity that domestic manufacturers previously imported. Legrand leverages its deep channel presence in continental Europe to sustain distribution advantages across Italian electrical wholesale networks. Samsung Electronics anchors consumer mindshare through appliance-integrated smart home ecosystems that compete with standalone device vendors. Bosch specializes in sensor-driven climate systems, differentiating on German engineering credibility within a market that prizes technical reliability.
Smart home technology encompasses residential and light commercial building systems that automate environmental control, security monitoring, energy management, and appliance coordination through interconnected sensors, actuators, and centralized or distributed control platforms operating across Wi-Fi, Zigbee, Z-Wave, or Bluetooth protocols with typical response latencies under 100 milliseconds for real-time automation triggers. Smart Security and Smart Thermostats command disproportionate margin pools due to Superbonus-linked renovation cycles and rising insurance premium incentives for monitored properties. Wi-Fi dominates connectivity shipments for DIY installations, yet Zigbee and Z-Wave gain ground in professional and integrated deployment channels where mesh reliability and lower interference prove decisive for builder specifications.
Italy's CEI (Comitato Elettrotecnico Italiano) publishes electrical installation standards that shape product certification requirements for connected devices, while the national transposition of EU Cybersecurity Act and GDPR frameworks governs data handling across cloud-enabled home systems. Builders and developers must navigate BSI (Bureau of Italian Standards) conformity assessments alongside ETSI harmonized standards for radio equipment to secure market access. Stakeholders should monitor whether pending EU Cyber Resilience Act implementation tightens firmware update obligations for installed base devices already serving Italian households.
Market Dynamics
Italy's Superbonus 110% fiscal incentive mechanism has restructured residential renovation economics, compressing payback periods for connected climate and security systems while redirecting contractor capacity toward retrofit channels over new-build deployments.
Growth Catalysts
- Superbonus 110% energy renovation framework:The Italian fiscal mechanism reimburses 110% of qualifying smart thermostat and building automation investments through tax credits, accelerating household upgrade cycles.
- Milan-Turin metropolitan corridor concentration:Northern Italy's dense residential construction pipeline integrates native smart infrastructure specifications that lock in long-term equipment demand.
- Zigbee and Z-Wave protocol maturation:Mesh networking reliability is supplanting Wi-Fi in professional installer specifications, expanding addressable market for integrated system vendors.
Market Restraints
- Semiconductor input cost volatility:RF module and sensor silicon pricing fluctuations compress margins for device manufacturers serving price-sensitive retrofit segments.
- GDPR and EU Cybersecurity Act compliance friction:Data localization and firmware certification requirements extend product launch timelines and elevate fixed compliance costs.
- Legacy electrical infrastructure incompatibility:Pre-1990s residential wiring standards in central and southern Italy regions limit seamless smart device deployment without costly electrical upgrades.
Strategic Opportunities
- Sicily and Calabria underpenetration:Southern Italy's lagging smart home adoption rates present first-mover expansion potential for regional distribution partnerships.
- Appliance-integrated ecosystem convergence:White goods manufacturers embedding control hubs within refrigerators and washing machines are creating new platform entry points beyond standalone devices.
- Insurance premium incentive expansion:Italian property insurers are piloting monitored security system discounts that could replicate Superbonus demand mechanics in the security segment.
Industry Challenges
- CEI certification timeline compression:Bureaucratic conformity assessment queues for radio equipment delay product launches by four to eight months versus comparable EU markets.
- IoT firmware engineering talent scarcity:Italian electrical engineering programs produce insufficient wireless protocol specialists, forcing manufacturers to recruit from German and Dutch labor pools.
- Multi-protocol integration complexity:Installer networks struggle to configure seamless interoperability across Wi-Fi, Zigbee, Z-Wave, and emerging Matter standards in heterogeneous retrofit environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Smart Home Market |
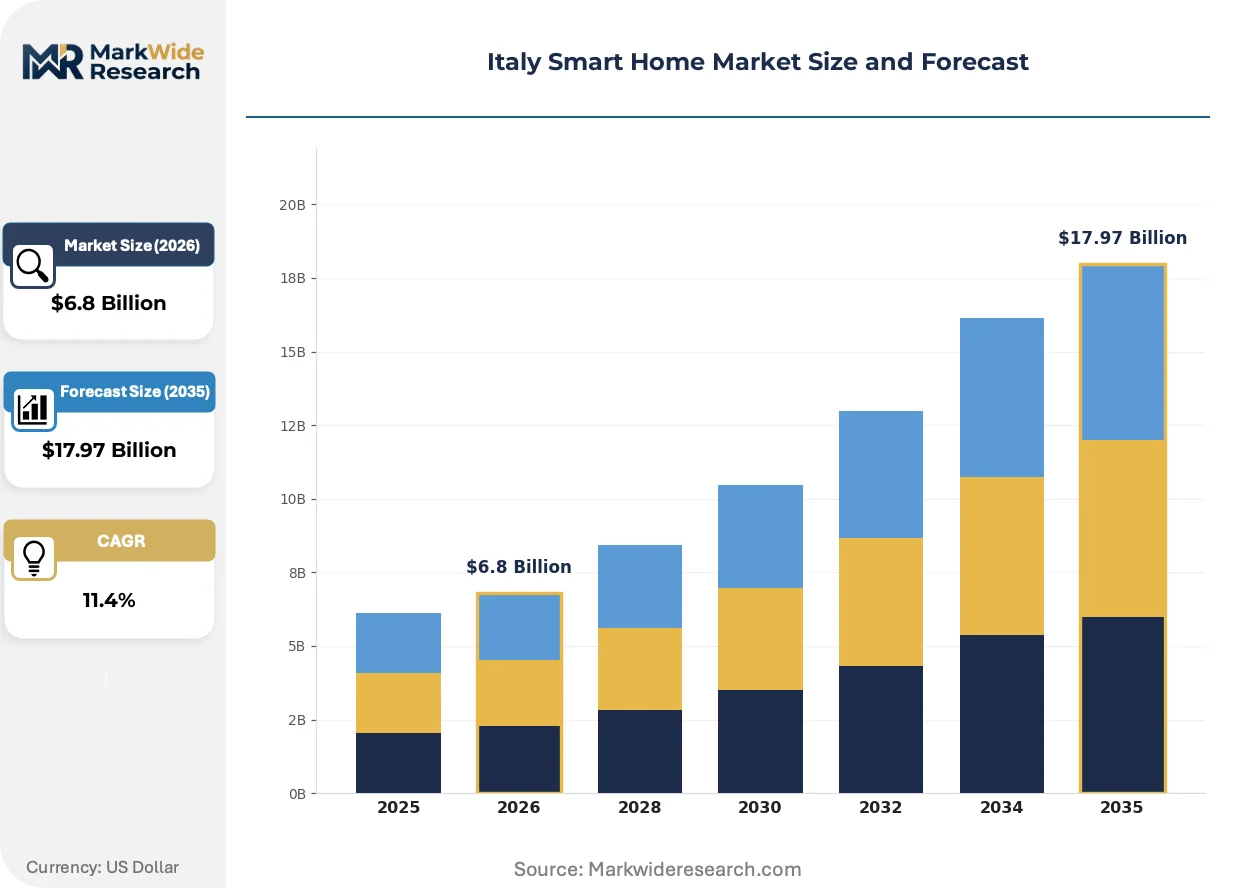
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Security, Smart Thermostats, Smart Appliances Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Installation: DIY, Professional, Hybrid, Integrated End User: Homeowners, Renters, Builders, Developers |
| Companies Covered | Legrand, ABB Ltd, Samsung Electronics, LG Electronics, Schneider Electric, Honeywell International, Amazon.com, Google, Bosch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Smart Home Market Trends and Innovations
Matter protocol standardization is consolidating previously fragmented device interoperability, while regulatory pressure on embodied carbon and operational energy efficiency is accelerating hardware refresh cycles across Italian residential stock.
Thread networking architecture is supplanting legacy hub-dependent topologies in new-build specifications across Lombardy and Veneto. Residential developers in Milan's Porta Nuova and CityLife districts specify Thread-native lighting and climate systems that eliminate single points of failure. This topology shift is compressing market share for bridge-dependent ecosystems while elevating demand for border router-integrated infrastructure.
Italy's transposition of the EU Cyber Resilience Act imposes mandatory firmware update obligations on connected device manufacturers serving Italian households. The national implementation requires documented security patch timelines spanning product lifecycles, elevating operational burdens for vendors without established software maintenance infrastructure. Smart security camera and door lock suppliers face the steepest compliance adjustments given extended installed base service expectations.
Builder-direct procurement channels are consolidating equipment specification authority away from traditional electrical wholesale networks. Lombardy-based residential developers now negotiate volume framework agreements directly with system integrators, compressing distributor margins and forcing electrical wholesalers to add technical configuration services. This channel shift is most pronounced in Turin's peripheral new-build zones where turnkey smart home packages have become standard amenity offerings.
Italy Smart Home Market Segmentation
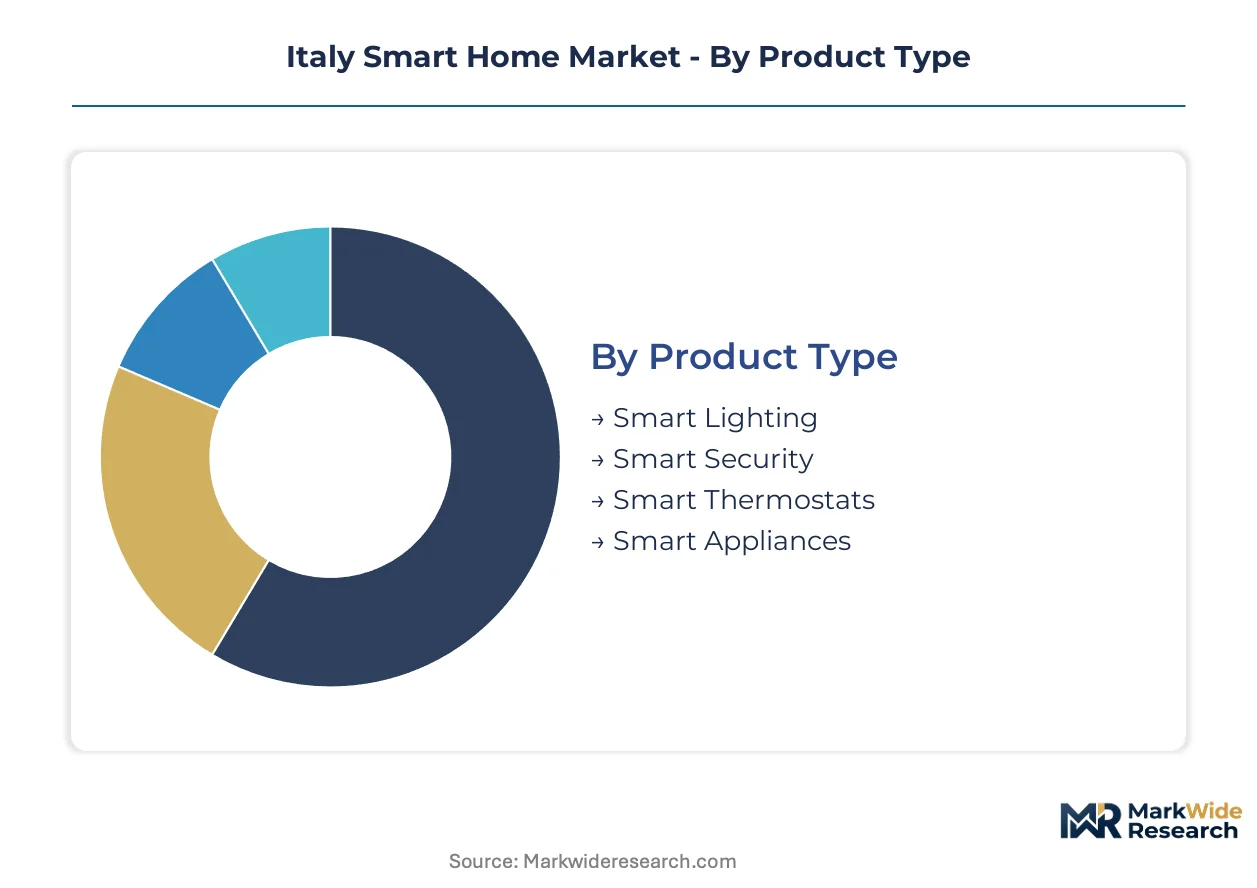
Smart home equipment flows through sharply divergent procurement channels in Italy, with tax-incentivized retrofits and new-build specifications creating distinct demand profiles that reshape how vendors configure product portfolios and pricing architectures.
Product Type:
Channel concentration varies dramatically across product categories, with Superbonus-eligible climate and security equipment flowing through contractor networks while lighting and appliance-integrated systems reach consumers through retail and builder-direct pathways.
- Smart Security:Monitored intrusion detection, video surveillance, and access control systems with cloud connectivity and mobile alerting. Demand clusters in Milan and Turin metropolitan zones where insurance premium discounts for monitored properties compound Superbonus 110% tax credits, compressing homeowner payback periods to under three years.
- Smart Thermostats:Programmable and learning-enabled climate controllers with occupancy sensing and weather-adaptive algorithms. Northern Italian renovation contractors specify these most aggressively, as CEI electrical certification requirements for heating system integration create installer loyalty to established brands with documented compliance histories.
- Smart Lighting:Connected fixtures and control systems enabling dimming, color temperature adjustment, and circadian scheduling.
- Smart Appliances:Refrigerators, washing machines, and cooking equipment with embedded connectivity hubs and energy monitoring.
Smart Security dominates installed base. Smart Thermostats is where expansion concentrates.
Technology:
Protocol selection dictates margin structure and customer lifetime value, with mesh-native technologies commanding premium pricing in professional channels while Wi-Fi sustains volume through mass-market retail.
- Wi-Fi:Ubiquitous IP-based connectivity leveraging existing residential infrastructure without dedicated hubs. DIY retail channels in Italy's big-box electrical stores move Wi-Fi-native devices fastest, though 2.4 GHz congestion in dense Milan apartment blocks drives return rates higher than mesh alternatives.
- Zigbee:Low-power mesh protocol with self-healing network topology and sub-100ms latency for real-time automation. Professional installers across Lombardy and Veneto specify Zigbee for whole-home integrations where reliability requirements exclude consumer-grade Wi-Fi, particularly in multi-unit residential developments.
- Z-Wave:Sub-GHz mesh protocol optimized for building penetration and minimal interference.
- Bluetooth:Point-to-point and mesh variants for proximity-based control and device commissioning.
Zigbee anchors professional specification authority. Wi-Fi captures retail volume leadership.
Installation:
Service intensity requirements separate margin pools, with integrated and hybrid deployments demanding technical configuration expertise that electrical wholesalers are racing to develop.
- Professional:Turnkey system design, installation, and commissioning by certified technicians. Turin and Milan developers now negotiate direct framework agreements with system integrators for new-build smart home packages, bypassing traditional electrical wholesale networks and compressing distributor margins.
- Integrated:Native smart infrastructure specified at construction phase with centralized control architecture. Lombardy residential builders in Porta Nuova and CityLife districts mandate Thread-native integrated specifications that eliminate bridge dependencies, locking in equipment choices before occupancy.
- DIY:Self-installed consumer devices with app-based configuration.
- Hybrid:Partial professional installation with consumer-managed expansion.
Professional installation commands margin premiums. Integrated specifications determine long-term equipment lock-in.
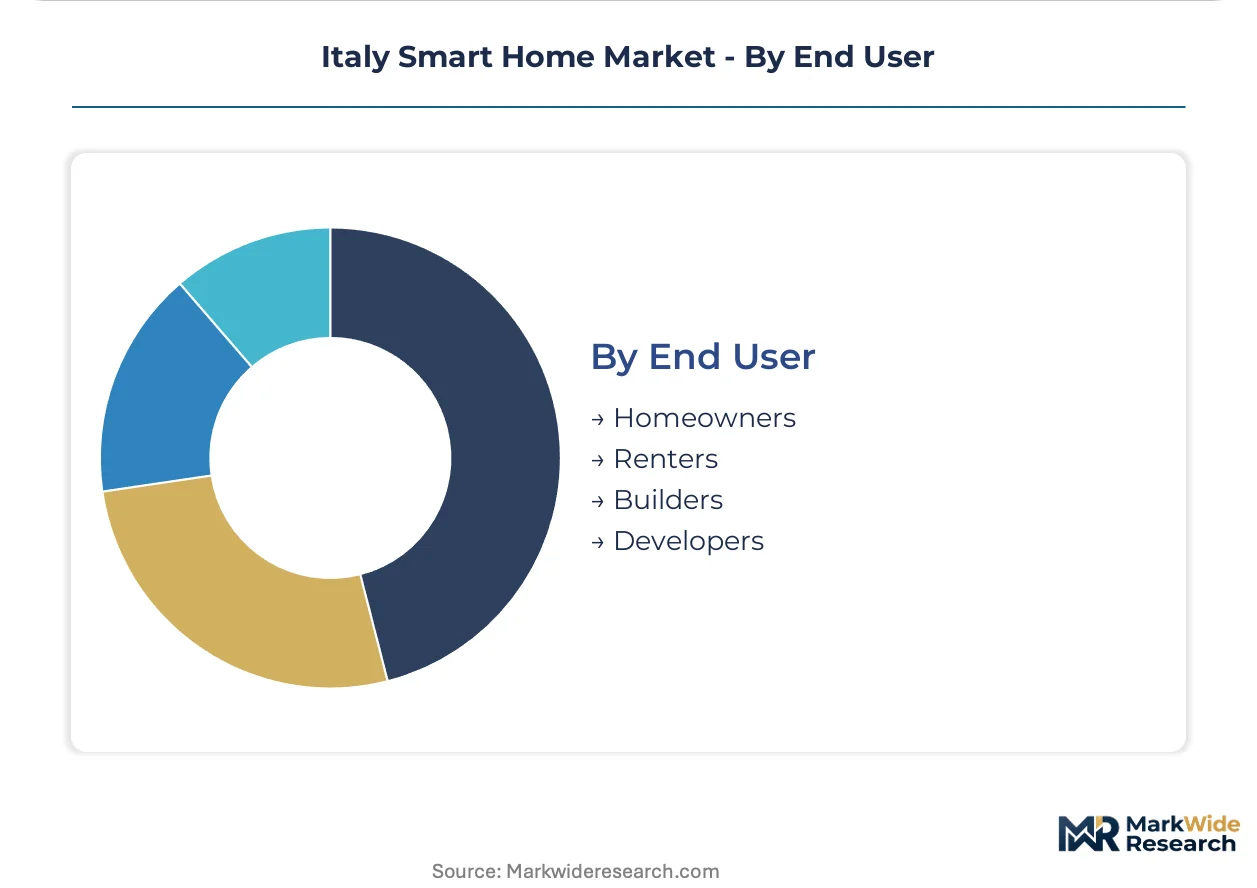
End User:
Purchasing authority is consolidating toward builder and developer entities in northern Italy's construction corridors, fragmenting traditional homeowner-driven demand patterns.
- Builders:Residential construction firms specifying smart infrastructure as standard amenity offerings. Veneto and Lombardy builders now embed native Thread and Zigbee systems in base specifications, treating connected infrastructure as comparable to HVAC or plumbing in project planning.
- Developers:Large-scale residential project sponsors negotiating volume procurement agreements. Milan's peripheral new-build zones see developers sourcing directly from system integrators rather than electrical wholesalers, reshaping channel economics across the Po Valley corridor.
- Homeowners:Individual property owners purchasing retrofit or upgrade equipment.
- Renters:Tenants seeking non-permanent smart home solutions with minimal installation requirements.
Builders control new-build specification authority. Developers are consolidating procurement scale fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEI (Comitato Elettrotecnico Italiano) anchors regulatory frameworks across the peninsula, with Superbonus 110% incentives concentrating demand in northern metropolitan corridors where new construction and renovation cycles overlap.
Lombardy
Milan's Porta Nuova and CityLife districts drive integrated smart infrastructure specifications, with Thread-native lighting and climate systems eliminating bridge dependencies. CEI electrical certification requirements shape product selection for heating system integrations. Residential developers negotiate direct framework agreements with system integrators, bypassing traditional electrical wholesale networks.
Piedmont
Turin's peripheral new-build zones standardize turnkey smart home packages as amenity offerings, compressing distributor margins and forcing electrical wholesalers toward technical configuration services. Superbonus-linked renovation cycles accelerate thermostat and security retrofits across the metropolitan zone. Builder-direct procurement channels consolidate equipment specification authority away from wholesale networks.
Veneto
Professional installers specify Zigbee mesh networks for whole-home integrations where reliability requirements exclude consumer-grade Wi-Fi, particularly in multi-unit residential developments. CEI publishes electrical installation standards that shape connected device certification requirements. Regional builders embed native smart infrastructure in base specifications comparable to HVAC or plumbing planning.
Emilia-Romagna
Appliance-integrated ecosystem convergence creates new platform entry points as white goods manufacturers embed control hubs within refrigerators and washing machines. The national transposition of EU Cybersecurity Act and GDPR frameworks governs data handling across cloud-enabled home systems. Bologna's industrial corridor hosts distribution partnerships targeting underpenetrated retrofit segments.
Lazio
Rome's pre-1990s residential wiring standards limit seamless smart device deployment without costly electrical upgrades, fragmenting adoption patterns versus northern regions. Pending EU Cyber Resilience Act implementation threatens to tighten firmware update obligations for installed base devices. Insurance premium incentives for monitored security systems pilot alternative demand mechanics to Superbonus structures.
Italy Smart Home Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Italian market. European electrical engineering conglomerates leverage deep channel presence in continental wholesale networks to sustain distribution advantages, while Asian consumer electronics groups anchor household mindshare through appliance-integrated ecosystems. The competitive terrain separates into three strategic archetypes: heritage electrical manufacturers with certification track records, platform-scale technology vendors with cloud infrastructure, and specialized sensor engineering firms with climate control expertise. Dominant competitive moves include direct framework agreements with residential developers and technical service layer expansion by electrical wholesalers facing margin compression.
Within the heritage electrical tier, Legrand and ABB Ltd exemplify established channel positions, while Samsung Electronics occupies a distinct position bridging consumer electronics and integrated home systems. Bosch represents engineering-credibility differentiation in sensor-driven climate applications. These three anchors illustrate how geographic origin and corporate structure map to competitive positioning: French and Swiss-Swedish electrical specialists, Korean diversified technology groups, and German industrial engineering firms each command distinct specification authority across professional installer networks, retail channels, and builder-direct procurement pathways.
| Leading Market Players |
|---|
| Legrand |
| ABB Ltd |
| Samsung Electronics |
| LG Electronics |
| Schneider Electric |
| Honeywell International |
| Amazon.com |
| Bosch |
| Others |
Pricing and Supply Chain Analysis
RF module scale economies in East Asian semiconductor fabrication anchor Italian smart home equipment pricing, concentrating component sourcing in Taiwan and South Korea while compressing margin floors for European device assemblers serving Superbonus-driven retrofit demand.
Pricing Analysis
Professional installer networks in Milan command 15-25% premiums over retail channels for identical Zigbee-native climate controllers, with price differentiation resting on CEI certification tier and post-installation technical support bundling. Cost compression in DIY Wi-Fi segments is intensifying as big-box electrical retailers consolidate procurement scale, while integrated Thread specifications in Lombardy new-builds sustain pricing power for vendors with documented builder-direct relationships. Homeowner retrofit buyers exhibit highest price sensitivity, whereas developer framework agreements prioritize reliability guarantees over unit cost.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for RF silicon and sensor modules originating from Taiwan, South Korea, and mainland China, compressing working capital cycles for Italian distributors. Component sourcing draws from Taiwanese foundries for wireless chipsets, German sensor engineering for climate applications, and Chinese PCB assembly for cost-optimized consumer tiers. Single-source vulnerability concentrates in Zigbee and Z-Wave protocol stacks licensed through US-based semiconductor houses. Distribution runs through electrical wholesale networks facing margin compression from builder-direct procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
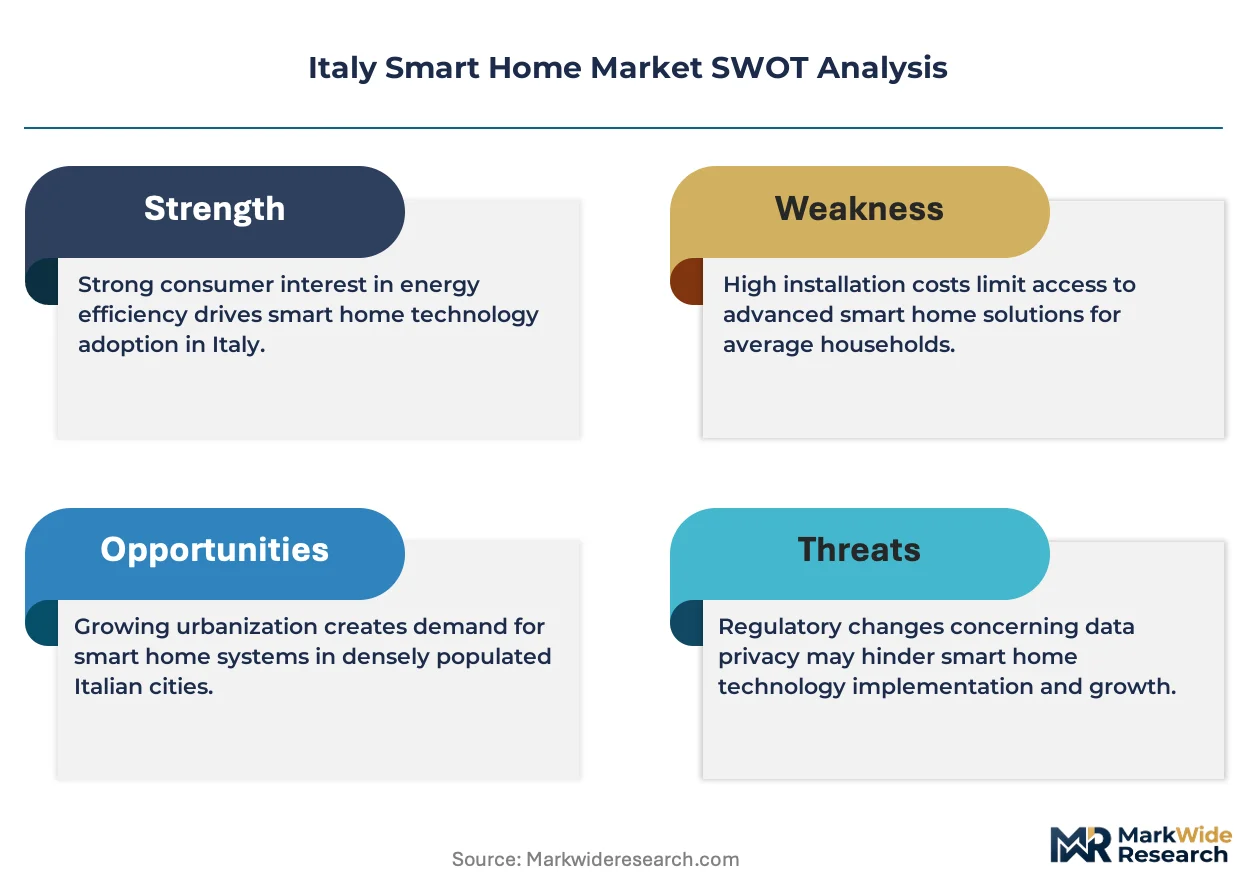
Italian smart home market fragmentation creates niche entry points as procurement authority fragments across developer-direct frameworks, professional installer networks, and retail channels, each demanding distinct product-service configurations.
For Market Incumbents: Compound specification authority in Thread-native integrated systems by securing framework agreements with Lombardy and Veneto developers before construction phase lock-in. Deepen technical service capabilities to defend against electrical wholesalers adding configuration expertise. Prioritize CEI certification maintenance as pending EU Cyber Resilience Act implementation threatens product launch timelines for non-compliant vendors.
For New Entrants and Emerging Players: Firmware update infrastructure as a service-layer gap presents white-space opportunity, as incumbent hardware vendors lack documented security patch timelines spanning product lifecycles. Sicily and Calabria underpenetration offers geographic expansion with lower competitive intensity than northern corridors. Appliance-integrated ecosystem partnerships with Emilia-Romagna white goods manufacturers provide platform entry points bypassing standalone device saturation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among monitored security system providers piloting insurance premium discount programs, creating subscription economics with lower customer acquisition costs than hardware-only vendors. Long-term viability favors acquisition targets with established software maintenance infrastructure capable of satisfying EU Cyber Resilience Act firmware obligations. Monitor Superbonus 110% extension negotiations as inflection indicator for retrofit segment demand durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Thread Protocol Native Certification | Eliminates bridge dependencies in Lombardy integrated specifications, locking developer framework preferences. |
| Firmware-as-a-Service Infrastructure Buildout | Satisfies EU Cyber Resilience Act patch timeline requirements for extended installed base obligations. |
| Southern Italy Distribution Partnership | Captures first-mover position in Sicily and Calabria underpenetrated retrofit segments before incumbent expansion. |
| Appliance-Integrated Hub Development | Leverages Emilia-Romagna white goods manufacturing corridor for platform convergence beyond standalone devices. |
| Insurance Premium Incentive Program Pilot | Replicates Superbonus demand mechanics in security segment through monitored system discount structures. |
Research Methodology
Initial hypotheses were tested against primary input from residential developers, professional system integrators, electrical wholesale procurement managers, and CEI certification specialists, then refined through secondary validation against EU Cyber Resilience Act implementation drafts, CEI electrical installation standards, Superbonus 110% fiscal mechanism documentation, and ETSI harmonized radio equipment specifications. Bottom-up equipment shipment estimates triangulated with top-down construction pipeline valuations across Lombardy, Piedmont, and Veneto regions.
Variance decomposition across product type, connectivity protocol, installation channel, and end-user archetype shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling calibrated to Superbonus incentive phase-out scenarios and new-build specification trend extrapolation. Forecast inputs incorporated semiconductor input cost volatility indices and builder-direct procurement channel migration rates.
Forecasts assume regulatory continuity in EU Cyber Resilience Act and GDPR frameworks; material policy shifts would require re-modeling compliance cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Electric Curtain Market
Others
Smart-Connected Power Plug Socket Market
Others
Military Wearable Market
Others
GCC Cigarette Market
Others
UK Cat Food Market
Others
Triathlon Clothing Market
Others
Global Military Wearable Sensors Market
Others
5G Devices Market
Others
Asia-Pacific Intercom Devices Market
Others
Rugged Tablet Market
Others
Computer on Module Market
Others
Global Platform Trolley Market
Others
Global Mobile Gambling Market
Others
Shear Testing Equipment Market
Others
Smartphone Gimbal Market
Others
Spain Automotive LED Lighting Market