
 Level Measuring Equipment Market | 2026-2036
Level Measuring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Level Measuring Equipment Market Analysis
Aftermarket service revenue is narrowing as manufacturers bundle predictive diagnostics with original equipment sales. Emerson Electric leverages its Plantweb digital ecosystem to lock in recurring software subscriptions alongside hardware deployments. KROHNE anchors its position through dedicated service hubs in major petrochemical clusters, sustaining long-term client relationships. Endress+Hauser differentiates by maintaining certified calibration laboratories that extend its influence beyond the initial sale.
Level measuring equipment encompasses instruments that detect, monitor, and transmit fluid or solid material heights within containment vessels, typically operating across pressure ratings from vacuum to 100 bar and temperature spans from cryogenic to 450°C. These devices serve critical process control, inventory management, and safety interlock functions in continuous manufacturing environments. Radar-based non-contact systems command premium positioning in aggressive media applications where ultrasonic sensors face signal attenuation challenges. Contact technologies retain cost advantages in benign water treatment and food processing installations where material compatibility requirements remain moderate. Float mechanisms persist in legacy tank gauging but face displacement by electronic alternatives in new capital projects.
The EPA enforces Clean Water Act provisions that mandate continuous level monitoring at wastewater treatment facilities, directly stimulating demand for redundant sensor architectures. IEC 61508 functional safety standards compel oil and gas operators to specify SIL-certified instruments for overfill prevention systems, raising certification barriers for unqualified suppliers. OSHA process safety management rules require documented proof testing intervals that favor equipment vendors offering automated verification capabilities. Stakeholders must weigh the capital cost of sensor migration against the operational risk of retaining obsolete measurement technologies that lack remote diagnostic connectivity.
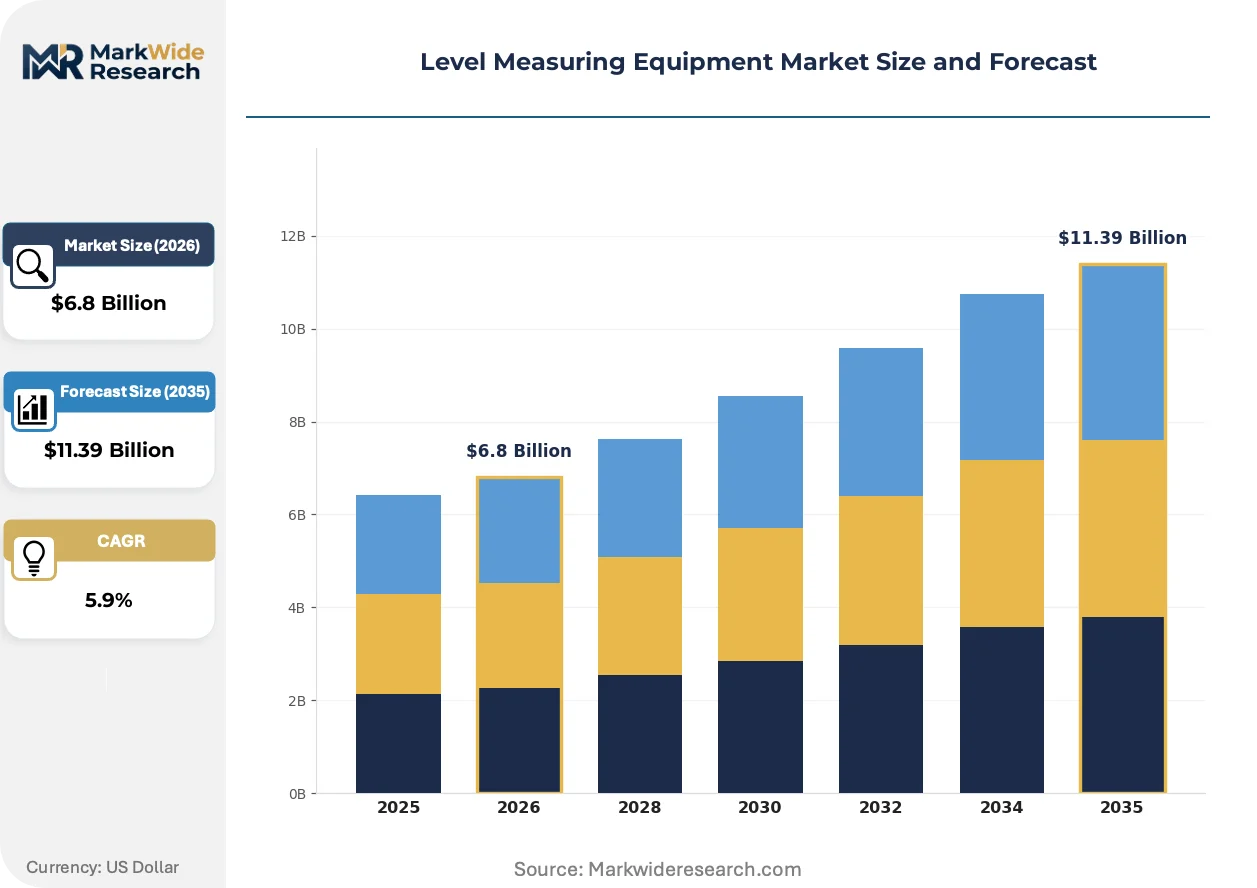
Market Dynamics
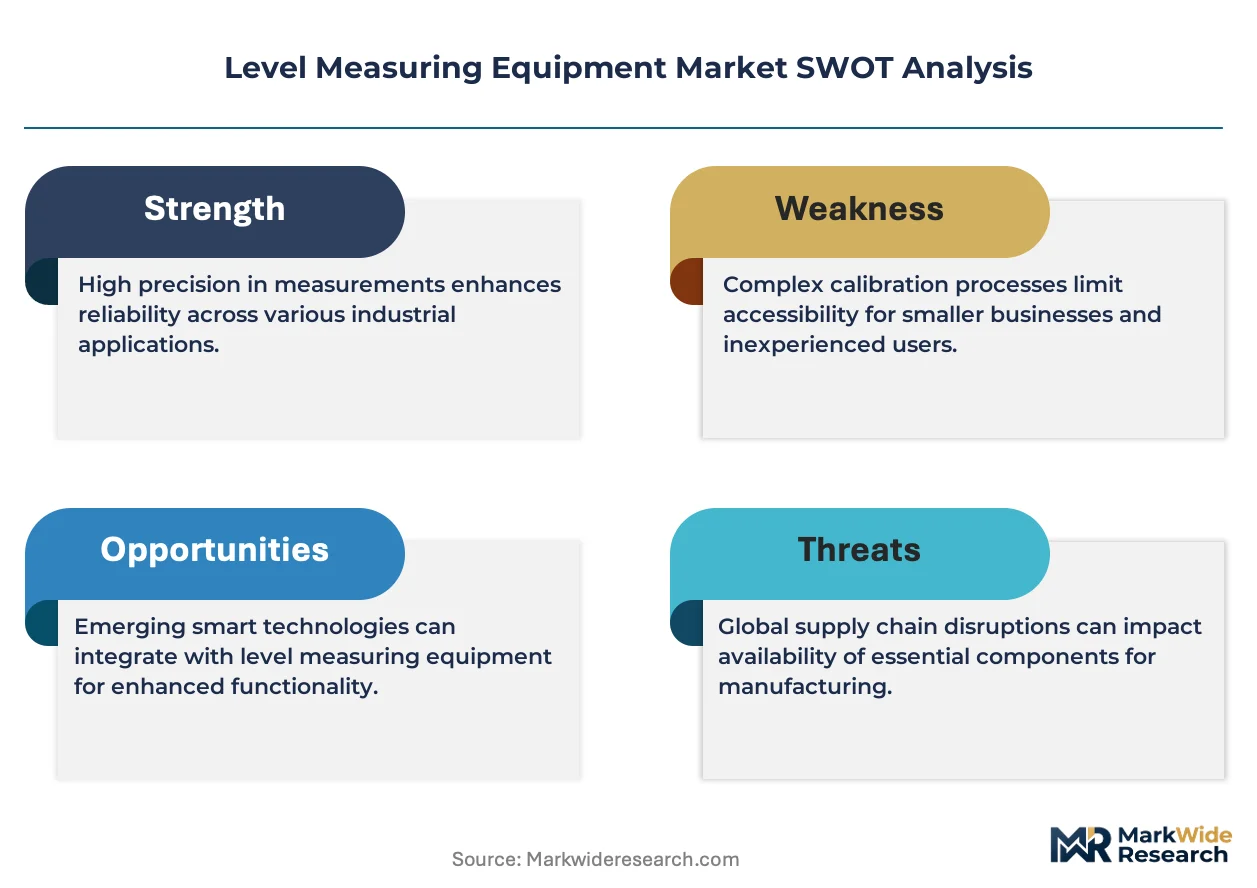
Sealed electronic level sensors are accelerating replacement of refrigerant-based systems across process industries, driven by the European Union's F-Gas Regulation and parallel environmental mandates in other jurisdictions. This technology transition is compressing replacement cycles while elevating certification requirements for suppliers.
Growth Catalysts
- Water Treatment Modernization:EPA Clean Water Act enforcement mandates continuous level monitoring at wastewater facilities. Municipal utilities are deploying redundant sensor architectures to meet stricter effluent standards.
- Functional Safety Mandates:IEC 61508 standards compel oil and gas operators to specify SIL-certified instruments for overfill prevention systems, raising barriers for uncertified competitors.
- Industrial Corridor Upgrades:Germany's chemical processors and automotive suppliers are modernizing tank farms, concentrating demand for precision measurement in the Rhine-Ruhr and Baden-Württemberg regions.
Market Restraints
- Semiconductor Supply Concentration:Sensor microcontroller and signal processing chip supply concentrates in East Asian foundries, exposing lead time volatility for European and North American manufacturers.
- Skilled Calibration Technician Shortage:Certified metrology expertise scarcity extends commissioning timelines and inflates service delivery costs for end-users.
- Legacy Float System Entrenchment:Existing mechanical tank gauging installations in bulk storage terminals resist displacement due to capital replacement thresholds and operational inertia.
Strategic Opportunities
- India Industrial Infrastructure:PLI scheme incentives for process manufacturing are stimulating greenfield chemical and pharmaceutical facilities requiring instrumented tank systems.
- Predictive Diagnostics Convergence:Integration of edge computing with vibration and level sensing enables condition-based maintenance models in continuous process plants.
- Hydrogen Economy Measurement:Cryogenic liquid hydrogen storage applications demand specialized radar and guided wave radar configurations for extreme temperature service.
Industry Challenges
- SIL Certification Timeline Compression:Third-party functional safety assessment backlogs delay product launches for manufacturers targeting oil and gas overfill protection applications.
- Legacy System Integration Complexity:Digital sensor deployment in brownfield facilities requires protocol gateway engineering to bridge HART, Foundation Fieldbus, and proprietary legacy control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Level Measuring Equipment Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Capacitive, Radar, Pressure Technology: Contact, Non-Contact, Laser, Float End User: Water Treatment, Oil & Gas, Chemical Processing, Food & Beverage Installation: Fixed, Portable, Remote, Integrated |
| Companies Covered | Honeywell, KROHNE, Emerson Electric, Magnetrol International, Endress+Hauser, ABB, VEGA, Leica Geosystems, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Level Measuring Equipment Market Emerging Trajectories
Sensor architecture is evolving from isolated measurement points to networked diagnostic nodes, embedding intelligence at the device edge. This transformation compresses maintenance intervals while generating operational data streams that reshape service delivery models.
80 GHz FMCW radar is digitizing level measurement in aggressive media applications where foam, vapor, and condensation previously attenuated ultrasonic signals. Chemical processors in the US Gulf Coast are adopting these systems for sulfuric acid and caustic storage. The technology is digitizing maintenance workflows by enabling remote echo curve analysis without vessel entry.
The EU F-Gas Regulation is accelerating phase-out of refrigerant-based mechanical level switches in cold storage and refrigeration applications. Food processing facilities across Denmark and the Netherlands face compliance deadlines requiring sealed electronic alternatives. Tank OEMs are responding by pre-qualifying radar and capacitive sensors for original equipment integration.
Aftermarket service unbundling is fragmenting traditional vendor-customer relationships in water treatment and municipal sectors. End-users in California and Texas are separating calibration contracts from hardware procurement, engaging third-party metrology laboratories. Equipment vendors are countering by embedding automated verification routines that reduce external dependency.
Level Measuring Equipment Market Segmentation
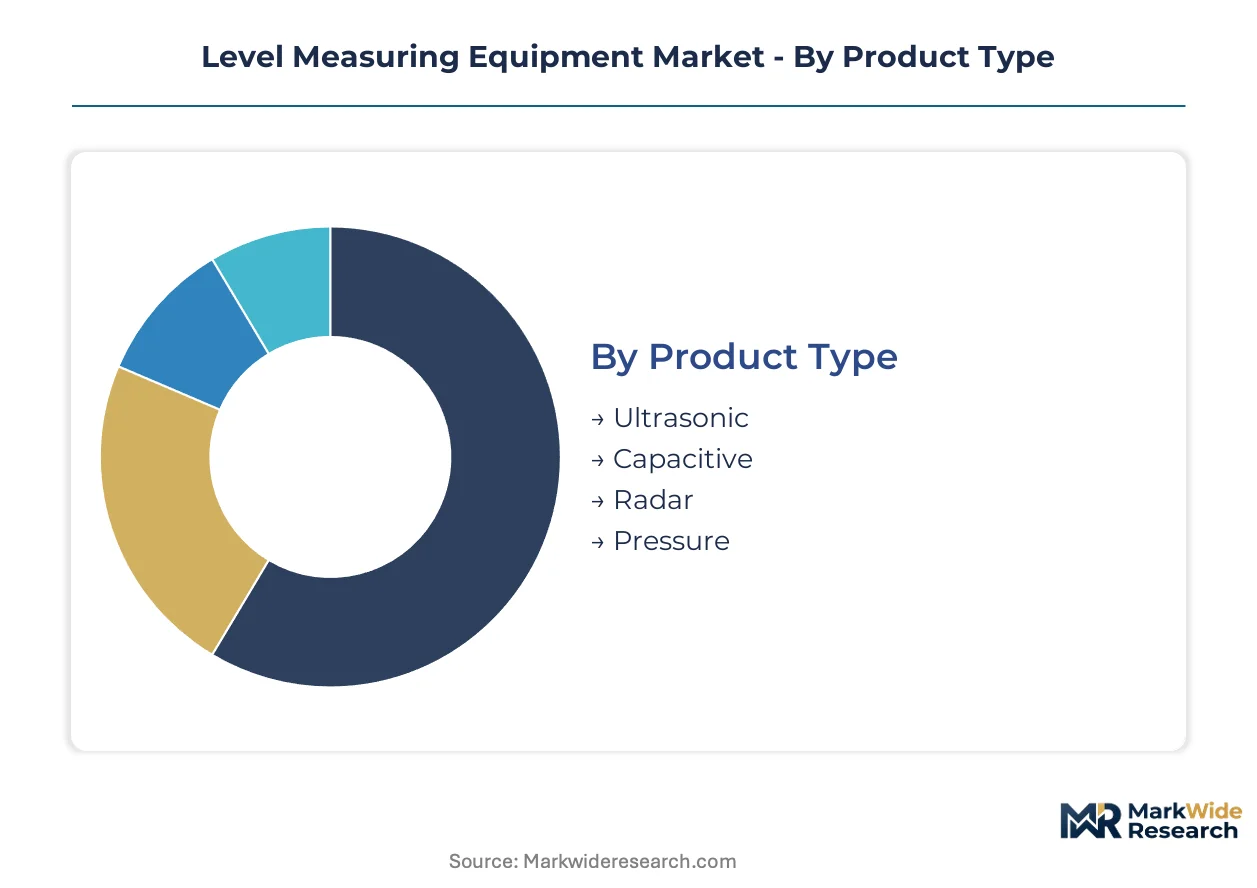
Level measuring equipment segmentation reflects divergent technical requirements across process environments. Radar systems command premium positioning in aggressive chemical service, while ultrasonic and float technologies retain cost-sensitive applications. Installation architecture choices determine maintenance accessibility and integration complexity in brownfield versus greenfield deployments.
Product Type:
Cost tier stratification separates premium sealed electronic systems from legacy mechanical alternatives, with replacement cycles compressing at the high end due to regulatory phase-outs.
- Radar:80 GHz FMCW systems transmit continuous wave signals that penetrate foam and vapor layers that attenuate competing technologies. Chemical processors on the US Gulf Coast deploy these for sulfuric acid and caustic storage where signal reliability is critical. Demand concentrates in Germany's industrial corridor where automotive suppliers modernize tank farms under stricter effluent mandates.
- Ultrasonic:Piezoelectric transducers emit high-frequency sound pulses for level detection in benign media applications. Water treatment utilities across California and Texas specify redundant ultrasonic architectures to meet EPA Clean Water Act continuous monitoring requirements. The technology faces displacement pressure in aggressive chemical service where signal attenuation degrades measurement accuracy.
- Capacitive:Dielectric measurement probes suit food processing and pharmaceutical tank applications with moderate material compatibility demands.
- Pressure:Hydrostatic transmitters convert liquid head to electrical signals for open vessel and sump level monitoring in municipal wastewater infrastructure.
Radar holds installed capacity in petrochemical clusters. Ultrasonic is rotating up the share rankings in municipal water treatment modernization programs.
Technology:
Application severity dictates contact versus non-contact selection, with measurement accuracy requirements and media aggressiveness driving the specification decision.
- Non-Contact:Electromagnetic and acoustic measurement eliminates sensor exposure to corrosive or abrasive process fluids. Oil and gas operators specify non-contact radar for overfill prevention systems requiring IEC 61508 SIL certification. The European Union's F-Gas Regulation accelerates replacement of refrigerant-based mechanical switches with sealed electronic alternatives in cold storage applications across Denmark and the Netherlands.
- Contact:Immersed probes and guided wave radar provide measurement in applications where mounting geometry restricts line-of-sight sensor placement. Bulk liquid storage terminals in legacy tank farms retain contact technologies due to capital replacement thresholds and operational inertia. Food processing installations specify contact capacitive probes where material compatibility requirements remain moderate.
- Laser:Time-of-flight optical measurement serves specialized applications with extreme temperature spans or explosive atmosphere requirements.
- Float:Mechanical buoyancy devices persist in legacy tank gauging but face displacement by electronic alternatives in new capital projects.
Non-contact systems are climbing the fastest in oil and gas safety instrumented systems. Float mechanisms retain entrenched positions in bulk storage terminals resisting capital replacement.
End User:
Customer type differentiation reflects divergent regulatory exposure and safety integrity requirements across process industries.
- Oil & Gas:Exploration, production, and refining operations demand SIL-certified instruments for overfill protection and inventory control. IEC 61508 functional safety standards compel operators to specify certified devices, raising qualification barriers for suppliers. Hydrogen economy infrastructure development creates demand for cryogenic liquid hydrogen storage measurement using specialized radar configurations.
- Chemical Processing:Aggressive media storage and reactor level control require corrosion-resistant sensor materials and redundant measurement architectures. Rhine-Ruhr and Baden-Württemberg regions concentrate modernization activity as German processors upgrade tank farms.
- Water Treatment:Municipal utilities deploy continuous level monitoring to meet EPA enforcement of Clean Water Act provisions at wastewater facilities.
- Food & Beverage:Hygienic design requirements and CIP/SIP compatibility constrain sensor selection in dairy, brewing, and processed food production.
Oil and Gas commands specification authority for safety-critical applications. Water Treatment is expanding most quickly in sensor deployment density for effluent compliance.
Installation:
Volume deployment patterns separate permanent infrastructure from mobile and distributed measurement architectures.
- Fixed:Permanent vessel-mounted sensors serve continuous manufacturing processes with hardwired integration to control systems. Germany's chemical processors specify fixed installations for tank farm modernization projects. The architecture dominates capital-intensive process plants where measurement reliability supports safety interlock functions.
- Remote:Wireless transmitters and satellite-connected devices enable level monitoring in distributed storage and mobile tanker applications. Edge computing integration supports condition-based maintenance models without physical site access.
- Portable:Battery-powered handheld units support calibration verification and temporary measurement needs in field service applications.
- Integrated:Pre-engineered sensor-control system packages reduce commissioning complexity for greenfield pharmaceutical and chemical facilities under India's PLI scheme incentives.
Fixed installations hold installed capacity across continuous process industries. Remote architectures are gaining share fastest in distributed storage and hydrogen logistics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's chemical corridor exhibit the lowest price elasticity, prioritizing SIL certification and predictive diagnostics over procurement savings. Municipal utilities in the United States show higher sensitivity, unbundling calibration contracts from hardware purchases to reduce lifecycle costs.
United States
Water treatment modernization drives sensor deployment across California and Texas municipal utilities. EPA Clean Water Act enforcement mandates continuous level monitoring at wastewater facilities, compelling redundant sensor architectures. The US Gulf Coast chemical processors adopt 80 GHz FMCW radar for sulfuric acid storage.
Germany
Automotive suppliers and chemical processors in the Rhine-Ruhr and Baden-Württemberg regions are modernizing tank farms under stricter effluent mandates. The EU F-Gas Regulation accelerates replacement of refrigerant-based mechanical switches with sealed electronic alternatives. Industrial clusters concentrate demand for precision measurement systems.
India
PLI scheme incentives stimulate greenfield chemical and pharmaceutical facilities requiring instrumented tank systems. The country's national industrial regulator supports process manufacturing expansion through production-linked incentives. Maharashtra and Gujarat host expanding pharmaceutical manufacturing corridors driving level sensor procurement.
China
Dual carbon goals and process safety mandates elevate demand for SIL-certified instruments in petrochemical and hydrogen storage applications. The national environmental ministry enforces stricter emissions monitoring at industrial facilities. Yangtze River Delta chemical processors upgrade tank gauging systems for compliance.
Netherlands
Food processing facilities across Denmark and the Netherlands face EU F-Gas Regulation compliance deadlines requiring sealed electronic level sensors. Cold storage and refrigeration applications drive replacement demand. The Randstad region concentrates food technology innovation and sensor qualification activity.
Level Measuring Equipment Market Vendor Landscape
Capability concentration sits with tier-one automation conglomerates; scale advantage sits with specialized measurement technology firms. The market structure divides between diversified industrial automation platforms and focused instrumentation specialists. Strategic archetypes include predictive diagnostics integrators, certified calibration service providers, and regional service hub operators. Dominant competitive moves encompass digital ecosystem bundling and automated verification capability deployment.
Within the diversified automation tier, Emerson Electric and Honeywell exemplify platform-scale positioning through integrated digital ecosystems. KROHNE anchors the specialized instrumentation segment with dedicated service infrastructure. Endress+Hauser occupies a position emphasizing metrology certification and calibration laboratory networks. Siemens AG represents European industrial automation breadth extending into process measurement applications.
| Leading Market Players |
|---|
| Honeywell |
| KROHNE |
| Emerson Electric |
| Magnetrol International |
| Endress+Hauser |
| ABB |
| VEGA |
| Leica Geosystems |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Overcapacity in East Asian semiconductor foundries compresses component lead times while elevating pricing leverage for European and North American sensor manufacturers who can guarantee delivery certainty. This utilization dynamic rewards suppliers with certified calibration infrastructure and punishes pure hardware vendors lacking service depth.
Pricing Analysis
Aftermarket service contracts drive lifetime value as manufacturers bundle predictive diagnostics with original equipment sales. Three-tier pricing structure across premium SIL-certified, standard industrial-grade, and economy non-certified levels segments buyers by safety integrity requirements. Cost compression in the economy tier intensifies because municipal utilities unbundle calibration from hardware procurement. Water treatment buyers in California and Texas exhibit highest price sensitivity, while German chemical processors prioritize certification over procurement savings.
Supply Chain Analysis
Extended payment terms from automotive OEMs and chemical processors strain working capital for sensor microcontroller suppliers. Component supply concentrates in Taiwan, South Korea, and China for signal processing chips and piezoelectric transducers. Manufacturing draws from specialty steel for corrosion-resistant housings, fluoropolymer seals, and sapphire optical windows. Single-source vulnerability in advanced radar module fabrication elevates risk for 80 GHz FMCW system availability. Distribution runs through authorized industrial automation distributors with regional calibration service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from sealed electronic sensors displacing refrigerant-based mechanical switches under environmental mandates. Defense requires pre-emptive certification investment and service infrastructure lock-in.
For Market Incumbents: Pre-empt displacement of legacy float systems by embedding automated verification routines that reduce third-party calibration dependency. Secure SIL certification for overfill prevention architectures before third-party assessment backlogs worsen. Vertical integration into edge computing modules strengthens predictive diagnostics bundling against unbundling pressures from municipal utilities.
For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical manufacturing corridors under PLI scheme incentives where greenfield facilities lack incumbent relationships. Target hydrogen economy cryogenic storage applications requiring specialized radar configurations that tier-one vendors have not yet optimized. Lead with integrated sensor-control system packages that reduce commissioning complexity versus brownfield retrofit specialists.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because service infrastructure and calibration laboratory networks create durable moats against hardware commoditization. Acquire specialists with certified metrology capabilities in petrochemical clusters. Watch third-party functional safety assessment backlogs as inflection indicator for certification-constrained supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Verification Capability Deployment | Reduces municipal utility dependency on external calibration laboratories in California and Texas. |
| Backward Integration into Edge Computing Modules | Enables condition-based maintenance models without physical site access for distributed storage. |
| SIL Certification Pre-Investment | Accelerates product launches before oil and gas overfill protection assessment backlogs worsen. |
| Service Hub Expansion in Petrochemical Clusters | Sustains long-term client relationships through dedicated infrastructure in Rhine-Ruhr region. |
| Hydrogen Storage Radar Configuration Development | Captures cryogenic liquid hydrogen measurement demand before incumbent optimization. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from automation conglomerates, and IEC certification registries. Interviews covered maintenance directors at chemical processors, OEM procurement teams, aftermarket service heads, and plant engineers across water treatment and oil and gas facilities. Bottom-up sensor shipment estimates triangulated against top-down process industry capital expenditure patterns.
Forecast inputs include technology substitution rates, regulatory compliance deadlines, and regional industrial modernization cycles. Segmentation dimensions span product type, contact versus non-contact architecture, end-user industry, and installation configuration across the projection horizon. CAGRs derived from historical replacement cycle compression and greenfield facility commissioning schedules. Hydrogen economy infrastructure development and F-Gas Regulation phase-out timelines inform scenario weightings.
Sensitivities concentrate around semiconductor supply volatility, third-party certification backlogs, and municipal budget cycles. Forecasts reflect assumptions on regulatory enforcement consistency and technology migration rates. Macroeconomic contraction, accelerated refrigerant phase-out schedules, or breakthrough sensor technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Global RFID Sensor Market
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Europe Sensors Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Piezoelectric Devices Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Smart Glove Market