
 Manometers Market | 2026-2036
Manometers Market Size, Share, and Industry Trends Forecast 2026-2036
Manometers Market Outlook
Industrial facility managers are reorganizing instrument procurement budgets toward HVAC and calibration applications, displacing traditional oil and gas buyers as the dominant demand archetype. WIKA leverages its German manufacturing base to dominate precision calibration manometer supply. Honeywell competes through integrated building automation channels that bundle pressure sensing with climate control systems. Dwyer Instruments specializes in cost-optimized analog units for North American mechanical contractors.
A manometer measures fluid pressure by balancing a liquid column against an unknown pressure, typically using mercury, water, or oil with resolutions spanning 0.1 mm to 100 mm of fluid column. The device serves critical functions in HVAC commissioning, medical gas line verification, and industrial process control where differential pressure accuracy prevents system failure. Digital manometers now capture the fastest expansion as electronic pressure transducers displace mechanical columns in field service applications. Analog manometers retain stubborn share in educational and backup metering roles where power independence matters. Differential manometers concentrate margin pools in pharmaceutical cleanroom and semiconductor fab applications requiring traceable calibration chains.
The US EPA enforces refrigerant leak detection protocols that mandate accurate pressure verification during HVAC maintenance, directly stimulating digital manometer demand. ISO 17025 accreditation requirements for calibration laboratories in Europe and North America raise barriers for uncertified suppliers while rewarding established metrology houses. China's GB standards for pressure instrumentation safety testing create separate compliance pathways for domestic and export-oriented manufacturers. Stakeholders must monitor how building electrification codes and refrigerant phase-down schedules redirect procurement volume across end-user segments.
Market Dynamics
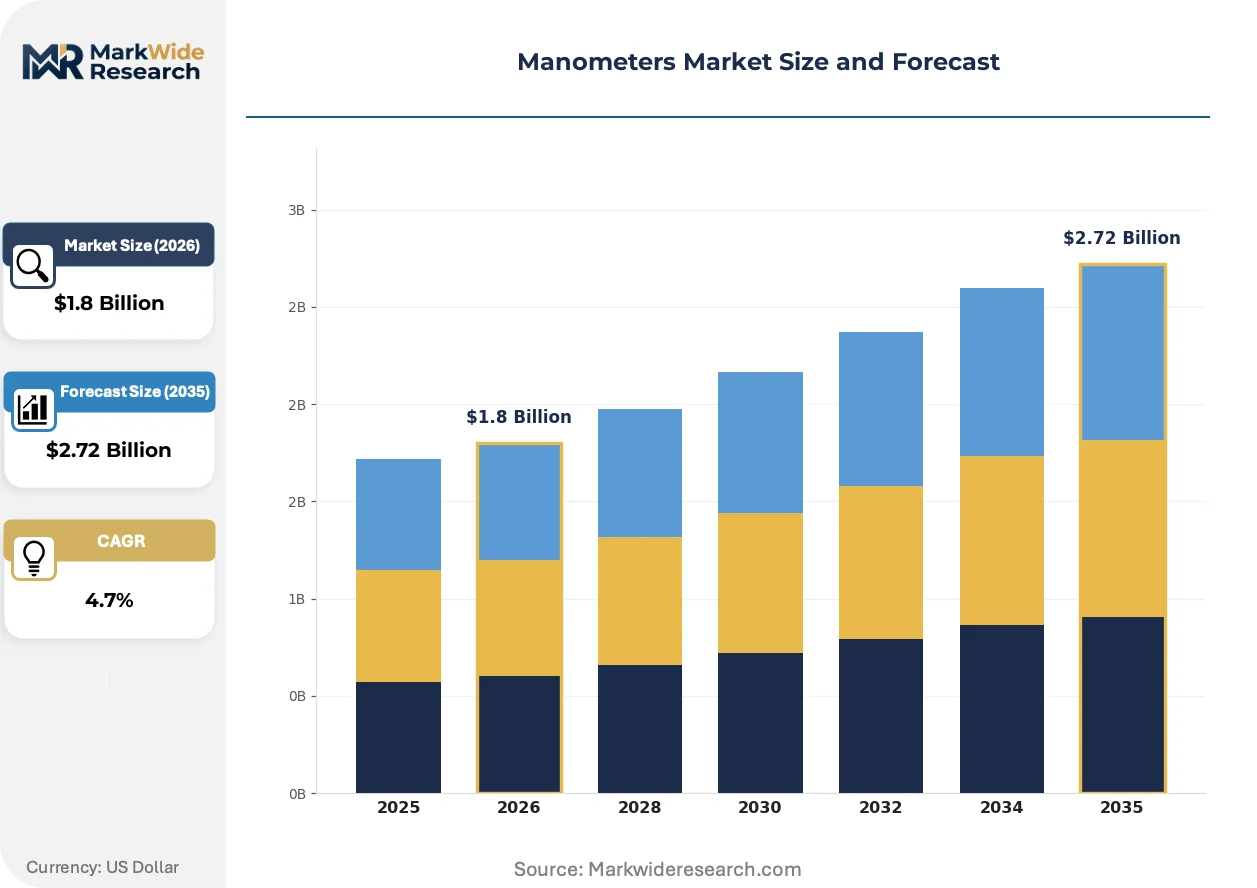
The manometers market is undergoing a fundamental demand reorientation as building electrification mandates and refrigerant phase-down schedules redirect procurement volume from oil and gas toward HVAC commissioning and calibration laboratories. This structural pivot favors digital pressure instrumentation with traceable accuracy chains over legacy mechanical columns.
Growth Catalysts
- EPA Refrigerant Management Rules:The US EPA's tightening leak detection protocols mandate precision pressure verification during HVAC maintenance, directly stimulating digital manometer procurement across commercial and industrial facilities.
- ISO 17025 Laboratory Accreditation:European and North American calibration laboratories face rising certification barriers that reward established metrology houses with accredited instrument portfolios.
- Semiconductor Fabrication Expansion:Cleanroom differential pressure monitoring requirements in pharmaceutical and chip manufacturing are concentrating margin pools in high-accuracy differential manometer segments.
Market Restraints
- Mercury Disposal Liabilities:Environmental handling costs for legacy mercury manometers create stranded asset risks for educational institutions and industrial backup systems.
- Sensor Supply Concentration:MEMS pressure transducer fabrication concentrates in East Asian foundries, exposing digital manometer assemblers to single-source vulnerabilities.
- Calibration Infrastructure Gaps:Developing economies lack sufficient accredited laboratories to support precision instrument deployment, capping addressable demand.
Strategic Opportunities
- India Building Code Modernization:The country's energy conservation building codes are mandating HVAC commissioning protocols that require portable pressure verification instruments.
- Wireless Sensor Convergence:Integration of Bluetooth-enabled manometers with building automation systems enables predictive maintenance contracts in commercial real estate portfolios.
- EU F-Gas Regulation Phase-Down:The regulation's refrigerant containment requirements are accelerating replacement cycles for mechanical service tools across the continent.
Industry Challenges
- Metrology Technician Shortage:Calibration laboratories struggle to recruit personnel with ISO 17025 audit competency and pressure standard traceability expertise.
- Legacy System Integration Friction:Digital manometer adoption in industrial process control requires protocol bridging with 4-20 mA analog infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manometers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Manometers, Analog Manometers, Differential Manometers, Vacuum Manometers End User: Manufacturing, Oil & Gas, Automotive, Healthcare Technology: Mechanical, Electronic, Fluidic, Optical Application: Pressure Testing, HVAC Systems, Research Labs, Calibration |
| Companies Covered | WIKA, Omega Engineering, Dwyer Instruments, Honeywell, Ashcroft, Setra Systems, Yokogawa Test & Measurement Corporation, Fieldpiece Instruments, Keller America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manometers Market Strategic Shifts
Electronic pressure transduction is fragmenting the traditional manometer landscape as solid-state sensors enable field-service portability that liquid-column instruments cannot match. Three concurrent developments are compressing product lifecycles and reshaping competitive positioning.
Silicon piezoresistive pressure sensing is fragmenting the portable instrument category by delivering millibar resolution in battery-powered handheld formats. HVAC service contractors are adopting these units for refrigerant charge verification, displacing mechanical gauges from truck-mounted tool inventories. The technology is fragmenting price-performance tiers that previously separated laboratory-grade from field-service instruments.
The EU F-Gas Regulation's refrigerant containment mandates are forcing facility managers to document pressure integrity during every maintenance cycle. Industrial consequence includes mandatory digital record-keeping that analog instruments cannot satisfy. Pharmaceutical cleanroom operators across Germany and France are responding by specifying manometers with integrated data-logging and calibration certificate storage.
Facility managers are consolidating instrument procurement through integrated building automation vendors rather than standalone pressure instrument distributors. Mechanical contractors in North American commercial construction are bundling manometer purchases with thermostat and actuator orders. This concentration is most visible in US federal building retrofits where GSA schedule purchasing favors single-source climate control suppliers.
Manometers Market Segmentation
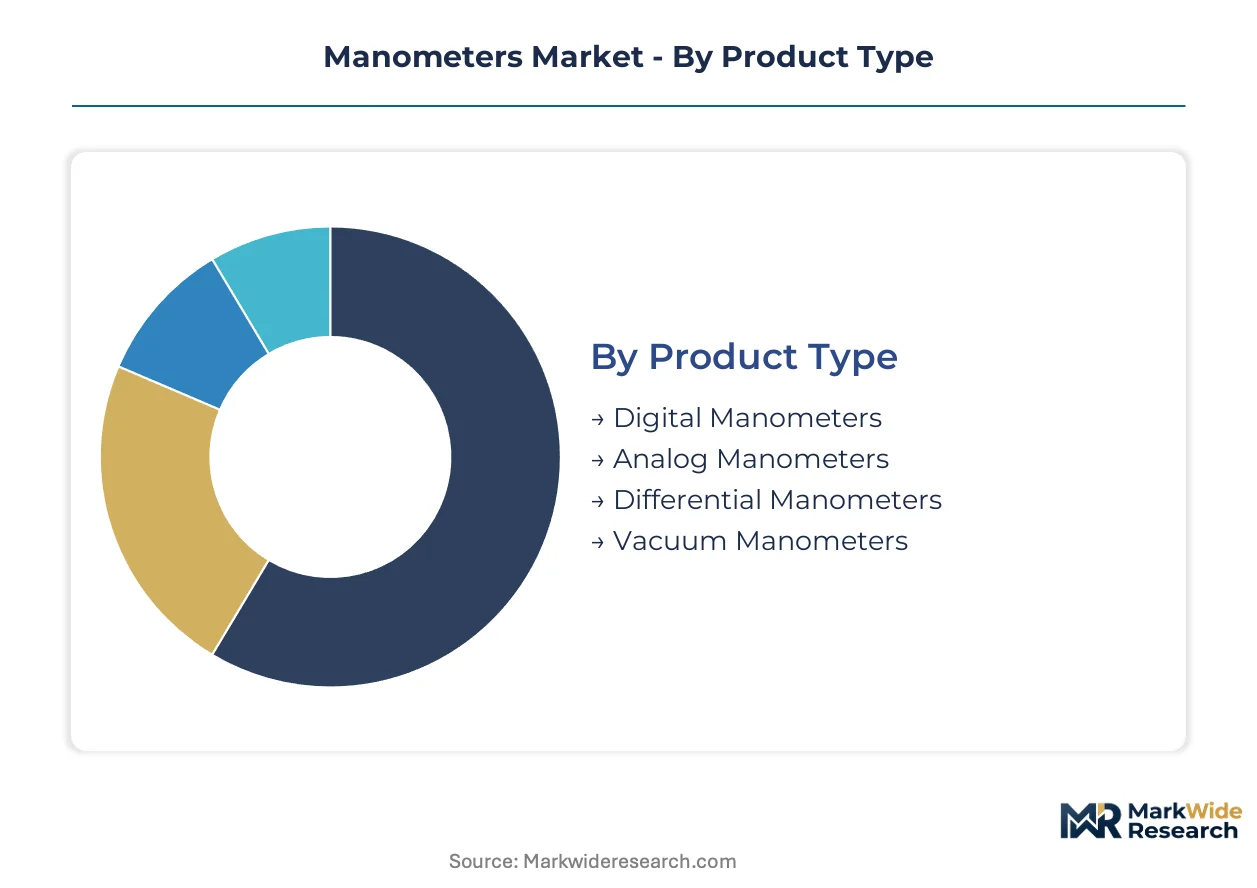
Pressure instrumentation procurement patterns diverge sharply across product architectures and end-use environments. Segment boundaries determine which suppliers capture margin pools versus volume turnover.
Product Type:
Electronic pressure sensing is displacing liquid-column instruments across field-service applications, forcing analog manufacturers into educational and backup-metering niches.
- Digital Manometers:Silicon piezoresistive transducers deliver millibar resolution in battery-powered handheld formats. HVAC contractors in Germany and the United States are standardizing these units for refrigerant charge verification, displacing mechanical gauges from service truck inventories.
- Analog Manometers:U-tube or inclined-tube liquid columns using mercury, water, or oil remain indispensable where power independence matters. Educational institutions across China retain these for laboratory instruction despite rising mercury disposal liabilities.
- Differential Manometers:Cleanroom pressure monitoring in pharmaceutical manufacturing concentrates margin pools in traceable-calibration units.
- Vacuum Manometers:Pirani and ionization gauges serve semiconductor fabrication and research applications requiring ultra-low pressure measurement.
Digital manometers anchor the volume base while differential manometers gain share at the steepest rate.
End User:
Procurement budgets are migrating from hydrocarbon extraction toward building systems and precision manufacturing.
- Manufacturing:Process control applications require 4-20 mA output compatibility and NIST-traceable calibration certificates. Automotive parts suppliers in Detroit and Stuttgart specify these for quality assurance protocols.
- Oil & Gas:Pipeline pressure monitoring and wellhead instrumentation once dominated procurement volume. Exploration budget compression has shifted this segment toward maintenance-only purchasing.
- Automotive:EV battery pack leak testing and thermal management system validation are creating new demand for high-precision differential units.
- Healthcare:Medical gas line verification and ventilator calibration require ISO 13485-certified instruments with documented accuracy chains.
Manufacturing commands the largest installed base while healthcare applications expand most quickly.
Technology:
Cost tiers separate laboratory-grade accuracy from field-service portability.
- Mechanical:Bourdon tubes and liquid columns deliver reference-grade stability without electrical power. Metrology laboratories in Paris and Beijing maintain these as primary standards.
- Electronic:MEMS-based transducers enable wireless data logging and Bluetooth integration with building automation systems. Facility managers in commercial real estate portfolios are specifying these for predictive maintenance contracts.
- Fluidic:Pneumatic pressure standards serve calibration laboratories requiring deadweight tester compatibility.
- Optical:Fiber-optic pressure sensors withstand electromagnetic interference in MRI suites and high-voltage environments.
Electronic technology dominates new installations while mechanical systems persist in calibration chains.
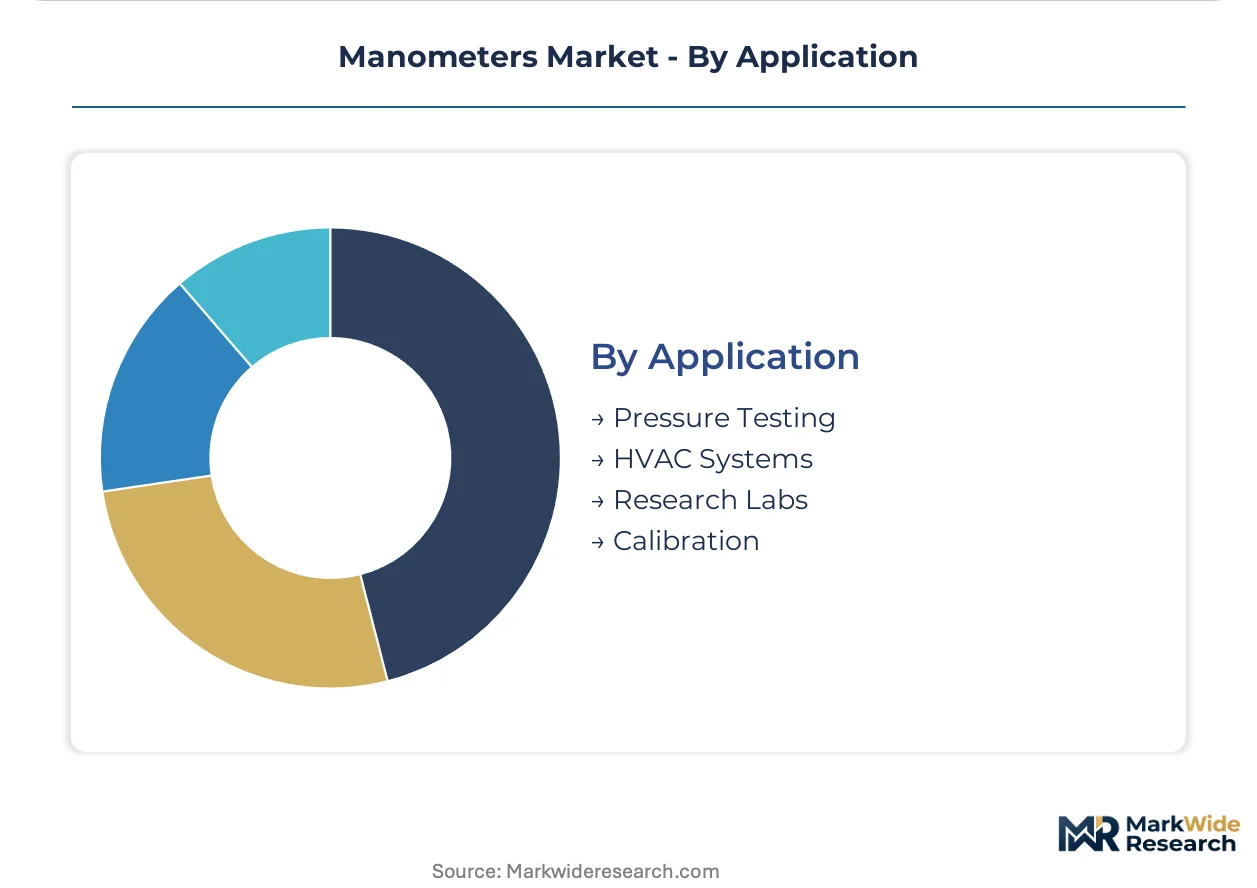
Application:
Regulatory compliance intensity varies dramatically across use cases.
- Pressure Testing:Pipeline integrity verification and vessel certification require documented accuracy traceable to national standards. Inspectors in Houston and Rotterdam mandate digital record-keeping that analog instruments cannot satisfy.
- HVAC Systems:EPA refrigerant management rules and EU F-Gas Regulation phase-down schedules mandate precision pressure verification during every maintenance cycle. Service contractors are upgrading truck-mounted inventories to comply.
- Research Labs:Academic and government laboratories balance budget constraints against ISO 17025 accreditation requirements.
- Calibration:Accredited metrology houses in Germany and the United States command premium pricing for certified reference instruments.
HVAC applications drive the highest shipment volumes while calibration commands the steepest price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision calibration manometers to North American HVAC contractors and Asian semiconductor fabs. This trade corridor shapes procurement patterns across three continents.
United States
Commercial building retrofits and federal GSA purchasing concentrate demand for integrated climate control systems. EPA refrigerant management rules mandate digital pressure verification during HVAC maintenance cycles. Detroit automotive suppliers specify NIST-traceable instruments for EV battery pack leak testing protocols.
Germany
Pharmaceutical cleanroom operators and calibration laboratories drive premium-tier procurement. EU F-Gas Regulation phase-down schedules accelerate replacement cycles for mechanical service tools. Stuttgart metrology houses command premium pricing for ISO 17025-accredited reference instruments.
China
Domestic HVAC installation and semiconductor fabrication expansion fuel volume demand. GB standards for pressure instrumentation safety testing create separate compliance pathways for local manufacturers. Yangtze River Delta fabrication clusters specify differential manometers for cleanroom pressure monitoring.
India
Energy conservation building codes mandate HVAC commissioning protocols requiring portable verification instruments. Bureau of Indian Safety certification requirements raise entry barriers for uncertified suppliers. Maharashtra industrial corridors are upgrading mechanical contractor tool inventories to digital formats.
Japan
Automotive thermal management validation and medical device manufacturing sustain precision instrument demand. METI industrial standards emphasize traceable calibration chains for export-oriented production. Nagoya automotive clusters specify high-accuracy differential units for quality assurance protocols.
Manometers Market Competitive Environment
Listed leaders compete with private specialists across certification-grade and field-service segments. The vendor base organizes into three tiers: precision calibration houses, integrated building automation suppliers, and cost-optimized mechanical contractors. German and Japanese entities anchor the premium tier through metrology heritage. Competitive moves concentrate on ISO 17025 accreditation expansion and Bluetooth-enabled sensor integration with building management systems.
Within the precision calibration tier, WIKA exemplifies manufacturing-base leverage for traceable instrument supply. Honeywell occupies a position among integrated automation vendors bundling pressure sensing with climate control systems. Dwyer Instruments represents cost-optimized analog fabrication for North American mechanical contracting channels.
| Leading Market Players |
|---|
| WIKA |
| Omega Engineering |
| Dwyer Instruments |
| Honeywell |
| Ashcroft |
| Setra Systems |
| Yokogawa Test & Measurement Corporation |
| Fieldpiece Instruments |
| Keller America |
| Others |
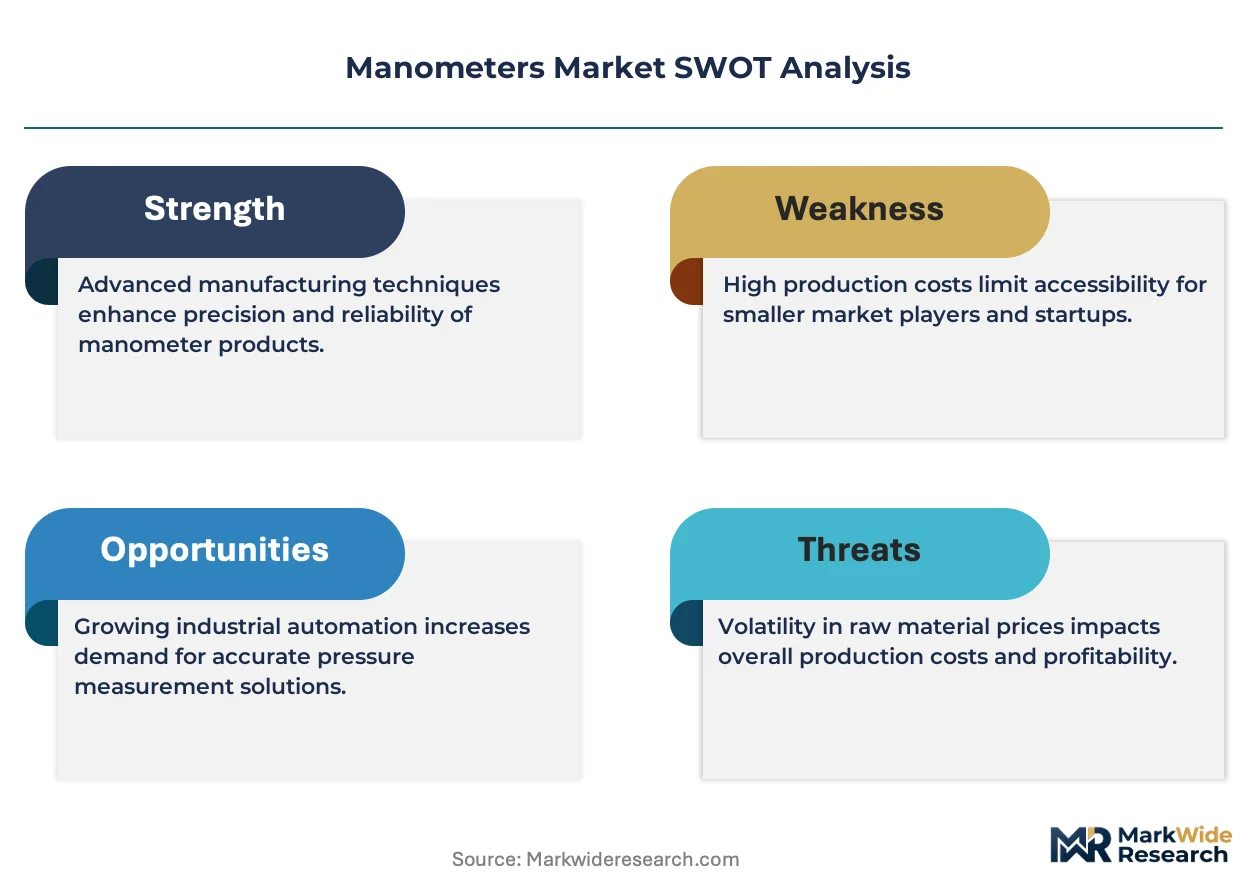
Value Chain & Pricing Dynamics
Silicon piezoresistive transducer substitution for mercury and mechanical columns simultaneously relocates manufacturing gravity toward East Asian MEMS foundries and collapses the historical price premium separating laboratory-grade from field-service instruments. This input transition rewards digital instrument assemblers with component cost curves that analog manufacturers cannot match.
Pricing Analysis
Current-generation digital handheld units, prior-generation mechanical columns, and next-generation Bluetooth-integrated sensors occupy distinct price-performance tiers. Three-tier pricing structure across premium calibration-grade, standard HVAC-service, and economy educational-backup levels stratifies the market. Price differentiation hinges on ISO 17025 accreditation status and NIST-traceable certification chains. Cost compression in standard-tier field instruments is intensifying because MEMS sensor commoditization erodes hardware margins. Mechanical contractors exhibit the highest price sensitivity, while pharmaceutical cleanroom operators accept substantial premiums for documented accuracy chains.
Supply Chain Analysis
Taiwan Strait semiconductor transit underwrites global MEMS pressure transducer availability for digital manometer assembly. Component sourcing draws from Taiwan, South Korea, and Japan for piezoresistive dies, while German and US metrology houses supply reference-grade calibration standards. Single-source vulnerability concentrates in East Asian foundry capacity for sensor fabrication. Distribution runs through integrated building automation vendors and specialized industrial instrument distributors serving HVAC contractors and calibration laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled manometer integration with building management platforms signals a platform-economics inflection, where instrument interoperability becomes the primary procurement filter rather than standalone accuracy specifications.
For Market Incumbents: Compound certification portfolio depth with backward integration into MEMS sensor sourcing to defend against modular disruptors. ISO 17025 accreditation expansion into emerging Asian markets provides channel control leverage. Incumbents must counter price erosion in standard-tier digital units by bundling predictive maintenance software subscriptions. For New Entrants and Emerging Players: Anchor in India's HVAC commissioning market, where Bureau of Indian Safety certification requirements create a 24-month window before established suppliers achieve full compliance. White-space targets include wireless sensor retrofit kits for legacy commercial building automation systems. A direct-to-mechanical-contractor digital sales channel bypasses incumbent distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision instrument portfolios in Germany and Japan that face succession planning pressures. Long-term viability favors targets with embedded software capabilities and recurring calibration service revenue. Watch for EPA refrigerant rule enforcement intensity as the inflection signal indicating HVAC service tool replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Expansion | Unlocks pharmaceutical cleanroom procurement in Germany and France where traceable calibration is mandatory. |
| Bluetooth Sensor Integration | Enables predictive maintenance contracts with US commercial real estate portfolios adopting building automation convergence. |
| MEMS Sensor Backward Integration | Reduces single-source exposure to Taiwan foundry concentration while capturing sensor margin pools. |
| India Distribution Partnership | Positions for energy conservation building code enforcement across Maharashtra industrial corridors. |
| Mercury Disposal Service Bundling | Captures stranded asset replacement demand from educational institutions facing environmental liability costs. |
Study Parameters
Cross-validation between regulatory filing analysis and distributor channel interviews anchors the qualitative findings in this study. Primary engagement with HVAC service contractors, calibration laboratory technicians, building automation procurement officers, and industrial facility maintenance directors combined with secondary validation through EPA enforcement records, EU F-Gas Regulation implementation reports, customs trade data, and ISO accreditation databases. Bottom-up shipment estimates and top-down instrumentation spending analysis provided triangulation across the modeling period.
Sensitivity analysis tested forecast robustness against refrigerant phase-down schedule acceleration and semiconductor fabrication investment delays. Segmentation dimensions include product architecture, end-use environment, technology generation, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and replacement cycle compression. Industry-specific inputs incorporated HVAC contractor truck inventory refresh patterns and calibration laboratory accreditation backlog data.
Material uncertainties — EPA rule enforcement intensity, MEMS foundry capacity allocation shifts, and mercury disposal liability litigation — sit outside the modeled envelope. Forecasts reflect documented assumptions about building electrification code adoption trajectories. Practitioners should keep alternative scenarios live as EU F-Gas Regulation phase-down schedules and China GB standard harmonization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Pregnancy Tracker Apps Market
Others
Digital Media Adaptor (DMA) Market
Others
Vegetable Carbon Market
Others
Reinforcement Geosynthetics Market
Others
Global Surface Analysis Market
Others
Coloring Apps Market
Others
Japan Coal Market
Others
Digital Tattoos Market
Others
Global Fertility Tracking Apps Market
Others
Global Virtual Keyboard Market
Others
Solar Lighting Tower Market
Others
Smart Home Gateways Market
Others
Smart Badge Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
Latin America Video Conferencing Hardware Market
Others
North America Halal Food and Beverage Market