
 Global Smartphone ODM Market | 2026-2036
Global Smartphone ODM Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smartphone ODM Market Outlook
Southeast Asian contract manufacturing capacity is pivoting toward higher-complexity 5G assemblies. Wingtech Technology leverages its Noida and Jakarta facilities to anchor large-volume programs for Indian and Indonesian carriers. BYD Electronics sustains captive component flows through in-house semiconductor packaging. Longcheer Holdings differentiates through AI-optimized camera module integration.
Original design manufacturing for smartphones encompasses the full-cycle engineering, industrial design, and assembly of mobile devices to client specifications, typically involving surface-mount technology lines, cleanroom environments, and RF calibration for cellular bands. The primary commercial purpose is enabling brand owners to launch devices without owning capital-intensive fabrication assets. Smartphone segments within the product type dimension dominate absolute volume, while wearables represent the fastest-expanding margin pool due to sensor miniaturization complexity. OEM customer types command the largest contract values, though telecom operators are consolidating purchasing power through multi-year framework agreements.
China's MIIT enforces GB standards for electromagnetic compatibility and network access licensing, while India's BIS mandates compulsory registration for lithium-ion cells and chargers. REACH compliance in the European Union restricts hazardous substances in solder and coatings, redirecting material sourcing toward certified Asian suppliers. Stakeholders must monitor how India's PLI scheme revisions and Vietnam's emerging electronics cluster policies reshape cost-competitive manufacturing geography.
Market Dynamics
China's MIIT 5G module integration mandates are compressing design cycles and forcing ODMs to absorb RF engineering complexity that brands previously handled in-house.
Growth Catalysts
- India PLI scheme revisions:The production-linked incentive program for electronics manufacturing is attracting ODMs to establish final assembly capacity in Noida and Chennai corridors.
- 5G mid-band deployment:Southeast Asian carriers require sub-6GHz optimized devices, creating volume contracts for regional ODM facilities.
- Sensor miniaturization:Wearable form factors demand advanced SiP packaging expertise that smartphone ODMs can repurpose from handset programs.
Market Restraints
- Concentrated APAC substrate supply:High-density interconnect PCB fabrication concentrates in Taiwan and South Korea, exposing ODMs to single-source disruption.
- EU REACH substance restrictions:The ECHA framework limits lead-free solder alternatives, forcing material requalification cycles.
- Legacy 4G inventory overhang:Carrier warehouse stockpiles of previous-generation devices delay 5G refresh procurement.
Strategic Opportunities
- Vietnam electronics cluster policies:Bac Ninh and Bac Giang provinces offer tax holidays for component localization that reduce landed cost for EU-bound shipments.
- AI inference at edge:NPU integration into camera pipelines creates premium tier differentiation for ODMs with ISP tuning capabilities.
- Direct-to-carrier distribution:Bypassing traditional brand licensing layers lets ODMs capture design fees previously allocated to brand markups.
Industry Challenges
- RF calibration talent scarcity:Millimeter-wave antenna tuning expertise resides with a narrow pool of engineers concentrated in Shenzhen and Hsinchu.
- Cleanroom capex intensity:ISO Class 7 assembly environments for camera module integration require facility investments that strain mid-tier ODM balance sheets.
- MIIT network access licensing timelines:GB standard compliance documentation delays commercial launch windows by weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smartphone ODM Market |
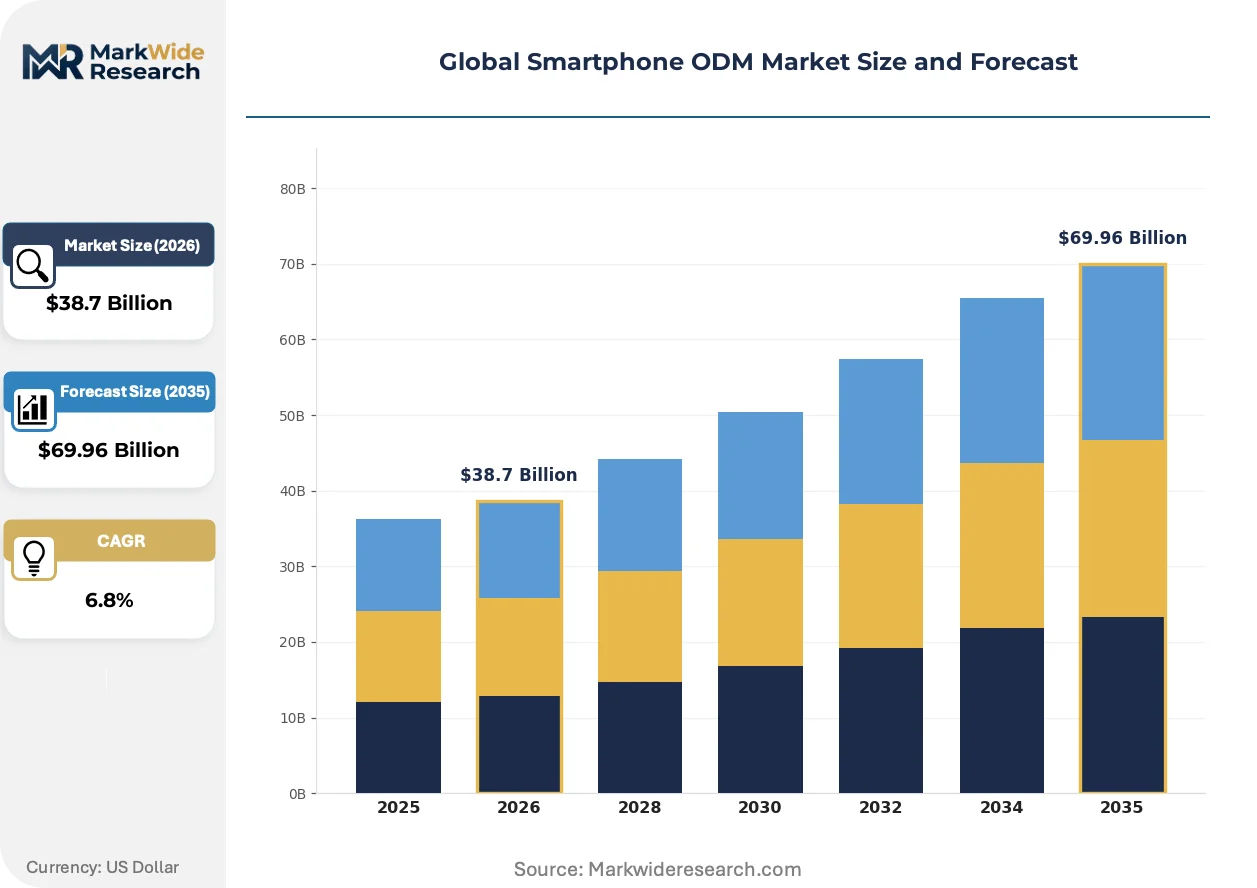
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Wearables, Accessories Customer Type: OEMs, Retailers, Telecom Operators, Distributors Technology: 5G, AI, IoT, Augmented Reality Sales Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Huizhou Desay Industrial, Shenzhen Xeltek, Wingtech Technology, Jabil, FIH Mobile, Huawei Device, Longcheer Holdings, Flex, BYD Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smartphone ODM Market Strategic Shifts
Modular RF subsystems and AI-driven thermal management are redrawing the engineering boundary between ODMs and their brand customers. Three developments dominate competitive positioning.
System-in-package architectures for 5G baseband and RF front-end are integrating discrete components into single modules that ODMs mount directly during SMT passes. Indian and Indonesian carriers specify these pre-certified subsystems to compress type-approval timelines. The technology is integrating formerly separate procurement streams for modem, PA, and filter components into single-source vendor relationships.
China's MIIT GB/T electromagnetic compatibility standards are tightening spurious emission limits for devices operating in n78 and n79 bands. ODMs must redesign shielding can geometries and ground plane routing, adding weeks to EVT phases. Vietnam-based facilities serving European markets face dual compliance tracks against both GB and CE marking requirements.
Telecom operator procurement teams are consolidating device sourcing through multi-year framework agreements that specify volume tiers and price bands upfront. The shift displaces spot-market purchasing and locks ODMs into capacity commitments. This pattern is most visible across Indonesian and Philippine carrier groups seeking supply security amid logistics volatility.
Global Smartphone ODM Market Segmentation
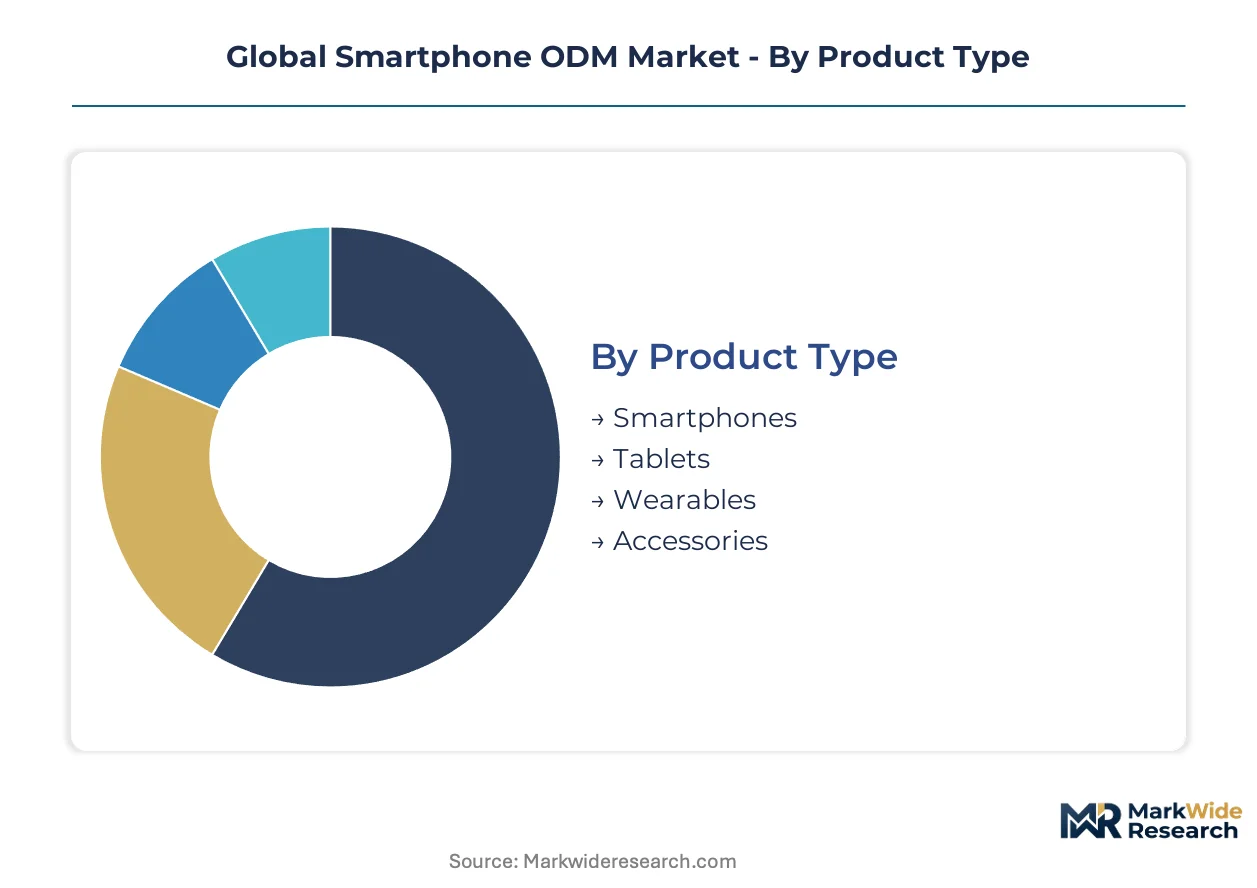
Segmentation in smartphone ODM contracting determines capital allocation priorities, with product type driving cleanroom investment scale and technology choice dictating RF engineering headcount requirements. Customer type shapes margin structure, while sales channel selection influences geographic facility placement decisions.
Product Type:
Smartphone assembly demands the heaviest upfront capital commitment, with ISO Class 7 cleanrooms and automated SMT lines representing fixed costs that wearables and accessories avoid.
- Smartphones:Full-cycle engineering encompassing industrial design, RF calibration for cellular bands, and surface-mount technology assembly in controlled environments. Volume concentrates with Indian and Indonesian carriers pursuing 5G mid-band deployment, though MIIT GB standard compliance documentation extends EVT phases. Smartphone segments absorb the bulk of installed capacity; wearables is expanding most quickly.
- Tablets:Larger form factor devices requiring modified thermal management solutions and expanded battery cell configurations. Demand clusters in education sector procurement across Southeast Asian markets, with BIS lithium-ion registration mandates affecting charger sourcing.
- Wearables:Sensor miniaturization complexity and system-in-package architectures for health monitoring modules. Vietnamese facilities leverage component localization tax incentives for EU-bound shipments.
- Accessories:Peripheral manufacturing including cases, chargers, and audio devices with lower barrier to entry and faster inventory turnover cycles.
Smartphone programs anchor facility utilization rates; wearables climb the fastest as health sensor integration deepens.
Customer Type:
Contract value concentration varies sharply by purchaser sophistication, with telecom operators consolidating procurement through multi-year frameworks that differ from spot-market OEM engagements.
- OEMs:Brand owners outsourcing full device engineering and assembly without owning fabrication assets. Programs span premium through economy tiers with design fee structures tied to volume commitments. OEMs command the largest absolute contract values; telecom operators are gaining procurement leverage fastest.
- Telecom Operators:Carrier-direct sourcing bypassing traditional brand licensing layers, prevalent across Indonesian and Philippine groups seeking supply security. Framework agreements specify volume tiers and price bands upfront, displacing spot-market purchasing.
- Retailers:Private-label device programs for electronics chains and e-commerce platforms, typically mid-tier specifications with compressed margin expectations.
- Distributors:Regional wholesalers aggregating demand from smaller brands, with logistics volatility driving consolidation toward fewer, larger fulfillment partners.
OEM relationships dominate engineering resource allocation; telecom operators are consolidating purchasing power most rapidly.
Technology:
Technology segmentation determines which ODMs capture premium design fees, with 5G RF complexity and AI integration creating capability moats that IoT and AR have yet to match.
- 5G:Sub-6GHz and millimeter-wave module integration with MIIT-mandated network access licensing and spurious emission compliance. Noida and Jakarta facilities optimize for Indian and Indonesian carrier specifications. 5G programs absorb the majority of RF engineering talent; AI integration is climbing the fastest.
- AI:Neural processing unit integration into camera pipelines and thermal management algorithms. Differentiation centers on ISP tuning capabilities for premium tier positioning.
- IoT:Low-power wide-area connectivity modules for industrial and consumer applications, with simpler certification tracks than cellular devices.
- Augmented Reality:Optical waveguide and depth sensor integration requiring specialized cleanroom protocols still emerging from prototype phases.
5G programs dominate current capacity allocation; AI inference at edge is gaining share fastest among new design wins.
Sales Channel:
Channel selection reshapes geographic manufacturing placement, with online-direct models favoring Vietnam's EU export logistics while retail distribution requires regional hub proximity.
- Online:E-commerce and brand-direct fulfillment with centralized warehousing and cross-border logistics optimization. Bac Ninh and Bac Giang provinces attract volume through tax holidays for component localization.
- Retail:Brick-and-mortar electronics chains requiring regional distribution centers and localized packaging compliance. Retail channels maintain the broadest geographic footprint; direct sales is expanding most quickly.
- Wholesale:Bulk transactions to regional distributors with price bands negotiated against volume commitments and payment term structures.
- Direct Sales:Carrier-direct and enterprise procurement bypassing intermediary layers, capturing design fees previously allocated to brand markups.
Retail distribution retains the widest facility network; direct sales channels are climbing the fastest as carriers consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polysilicon feedstock from Xinjiang and semiconductor-grade silicon from Hsinchu anchor manufacturing geography across the Global Smartphone ODM Market. Contract assembly capacity clusters where component ecosystems and carrier procurement intersect. Regulatory divergence between MIIT certification tracks and CE marking requirements shapes facility placement decisions.
China
Shenzhen and Dongguan corridor hosts the densest concentration of RF engineering talent and SMT line capacity. MIIT enforces GB/T electromagnetic compatibility standards for n78 and n79 5G bands, extending EVT phases by weeks. Dongguan facilities absorb the bulk of domestic carrier volume while serving as engineering hubs for Southeast Asian programs.
Vietnam
Bac Ninh and Bac Giang provinces attract EU-bound volume through component localization tax holidays. REACH compliance documentation for solder and coatings runs parallel to MIIT tracks for China-destined output. The emerging electronics cluster reduces landed cost for European retail channels.
India
Noida and Chennai corridors expand final assembly capacity under PLI scheme revisions for electronics manufacturing. BIS mandates compulsory registration for lithium-ion cells and chargers, affecting sourcing timelines. Domestic carriers consolidate procurement through multi-year framework agreements specifying volume tiers.
Indonesia
Jakarta-based facilities anchor large-volume programs for carrier-direct sourcing models. Sub-6GHz 5G mid-band deployment drives specification requirements from Telkomsel and XL Axiata. Local content regulations for network equipment create procurement complexity for imported modules.
South Korea
Seoul Capital Area concentrates high-density interconnect PCB fabrication, exposing ODMs to single-source substrate risk. MFDS alignment with international electromagnetic standards streamlines export certification. Busan-Ulsan corridor supplies advanced memory packaging for premium tier camera pipelines.
Global Smartphone ODM Market Competitive Environment
Global majors compete with regional champions across RF engineering capability and carrier relationship depth. The vendor base stratifies into three tiers: scale-driven integrators with captive component flows, mid-tier specialists with regional carrier lock-in, and emerging players competing on compressed design cycles. Strategic moves concentrate on cleanroom capacity expansion in Vietnam and India, plus AI inference IP acquisition for camera pipeline differentiation.
Among China-based fabricators, Wingtech Technology and BYD Electronics exemplify the scale-driven archetype with integrated supply chain positioning. Longcheer Holdings occupies a specialist tier distinguished by ISP tuning capabilities. Jabil and Flex represent the global contract manufacturing archetype with multi-region facility networks. The competitive frontier sits between carrier-direct framework agreements and traditional OEM design-fee structures.
| Leading Market Players |
|---|
| Huizhou Desay Industrial |
| Shenzhen Xeltek |
| Wingtech Technology |
| Jabil |
| FIH Mobile |
| Huawei Device |
| Longcheer Holdings |
| Flex |
| BYD Electronics |
| Others |
Value Chain & Pricing Dynamics
Telecom operator procurement consolidation through multi-year framework agreements anchors contract pricing across the Global Smartphone ODM Market, with volume-tier commitments compressing design fees while after-sales service bundles determine margin retention.
Pricing Analysis
Warranty and software update bundling separates premium-tier ODM contracts from economy engagements, with MIIT compliance documentation and extended EVT phases commanding surcharge structures. Three-tier pricing stratifies across flagship 5G assemblies, mid-band carrier specifications, and legacy 4G refreshes, with price differentiation hinging on RF engineering complexity and ISO Class 7 certification status. Pricing pressure intensifies from legacy 4G inventory overhang delaying carrier refresh cycles. Economy-tier programs exhibit highest price sensitivity; premium AI-integrated camera pipelines retain pricing power.
Supply Chain Analysis
Freight cost volatility from Red Sea routing disruptions amplifies landed cost differentials between Vietnam's Bac Ninh corridor and Dongguan hub facilities serving European markets. High-density interconnect PCB fabrication concentrates in Taiwan and South Korea, while semiconductor-grade silicon feeds from Hsinchu and advanced memory packaging centers on Busan-Ulsan. Single-source substrate vulnerability from concentrated APIC supply exposes ODMs to disruption. Distribution runs through carrier-direct frameworks and retail channel hubs with divergent logistics requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom capex intensity and RF calibration talent scarcity constrain capacity expansion, propping design fee structures for qualified ODMs across the analysis window.
For Market Incumbents: Anticipate margin compression from carrier framework agreements locking in volume-price bands by securing captive component flows through backward integration into semiconductor packaging and expanding ISO Class 7 capacity in Vietnam's tax-incentivized corridors. MIIT network access licensing timeline extensions threaten launch windows; defend through pre-certified RF subsystem partnerships. For New Entrants and Emerging Players: The mid-tier pricing gap between Wingtech-scale integrators and economy assemblers offers entry latitude for specialists with AI inference IP or regional carrier relationships. Target Indonesian and Philippine carrier-direct procurement consolidating through multi-year agreements, leveraging sub-6GHz specification expertise as the go-to-market anchor. For Investors and Strategic Acquirers: The window for entry favors ODMs with ISP tuning capabilities and cleanroom assets in India PLI corridors or Vietnam electronics clusters. Acquisition archetypes center on mid-tier specialists with regional carrier lock-in and AI camera pipeline differentiation. Watch for MIIT GB standard tightening on spurious emissions as inflection signal for RF engineering premium repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO Class 7 facilities in Bac Ninh and Noida capture carrier-direct volume tiers. |
| Backward Integration into SiP Packaging | In-house system-in-package modules reduce substrate dependency from Taiwan suppliers. |
| AI Inference IP Acquisition | Neural processing unit integration commands premium design fees from OEM camera programs. |
| Carrier Framework Agreement Lock-in | Multi-year Indonesian and Philippine contracts displace spot-market purchasing volatility. |
| Dual-Track Compliance Certification | Parallel MIIT GB and CE marking capability expands addressable EU-bound shipment share. |
Study Parameters
Document review covered SEC filings from contract manufacturers, MIIT network access licensing databases, and carrier procurement disclosures, complemented by interviews with ODM engineering directors, RF calibration specialists, telecom operator device sourcing managers, and semiconductor packaging executives. Secondary validation drew from customs trade records, BIS registration filings, and Vietnam electronics cluster policy documents. Bottom-up assembly cost modeling and top-down carrier spend analysis were triangulated.
Cross-referencing historical capacity utilization patterns against panel input from facility operators anchored volume projections across the modeling period. Segmentation dimensions spanned product type, customer archetype, technology tier, and sales channel with geographic facility placement as industry-specific overlay. CAGRs were derived from elasticity-adjusted carrier procurement forecasts and component cost trajectory assumptions, with 5G module integration complexity and AI camera pipeline attach rates as key forecast inputs.
Inputs from MIIT compliance documentation and carrier framework agreement disclosures were available through the study window; gaps in millimeter-wave antenna tuning talent pool data introduce uncertainty bands around premium-tier capacity expansion timelines. Forecasts reflect documented assumptions on PLI scheme continuity and REACH substance restriction enforcement; stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Cloud Advertising Market
Others
Global Hardware As a Service (Haas) Market
Others
Global Thermally Conductive Grease Market
Others
US Cat Food Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Enterprise Video Content Management Market
Others
Magnetic Stripe Readers Market
Others
Hip Tendinitis Market
Others
Cellular-Connected Laptops Market
Others
France 3D Printing Construction Market
Others
Digital Transformation of Maritime Freight Market
Others
US Tablet Market
Others
Embedded Computer Market
Others
Germany Smart Home Market
Others
Europe Medical Simulation Market
Others
China Automotive LED Lighting Market