
 Receiving Scales Market | 2026-2036
Receiving Scales Market Size, Share, and Industry Trends Forecast 2026-2036
Receiving Scales Market Outlook
Aftermarket calibration and certification revenue is reconfiguring profit pools away from hardware-only transactions across the receiving scales value chain. Mettler-Toledo leverages its global service infrastructure to capture recurring revenue from compliance-driven recalibration contracts. Rice Lake Weighing Systems anchors its competitive position through deep specialization in custom-capacity floor scales for food processing and agriculture terminals. Avery Weigh-Tronix differentiates via integrated software platforms that connect scale data directly to warehouse management systems.
Receiving scales are precision weighing instruments designed to measure inbound goods, materials, or freight at the point of delivery, typically employing load-cell technology with resolutions from 0.01 kg to over 10,000 kg and accuracy classes certified to OIML R76 or NIST Handbook 44 standards. These devices serve as critical control points in supply chains, verifying supplier quantities, triggering payment workflows, and flagging discrepancies before inventory enters storage or production. Digital scales now command the dominant share of value across product categories, while strain-gauge and electromechanical technologies compete for share in high-vibration industrial environments. The 100-500 kg capacity band captures the densest concentration of unit demand from logistics and retail distribution centers, though 1000+ kg floor-scale configurations generate superior margins in manufacturing and bulk-material handling.
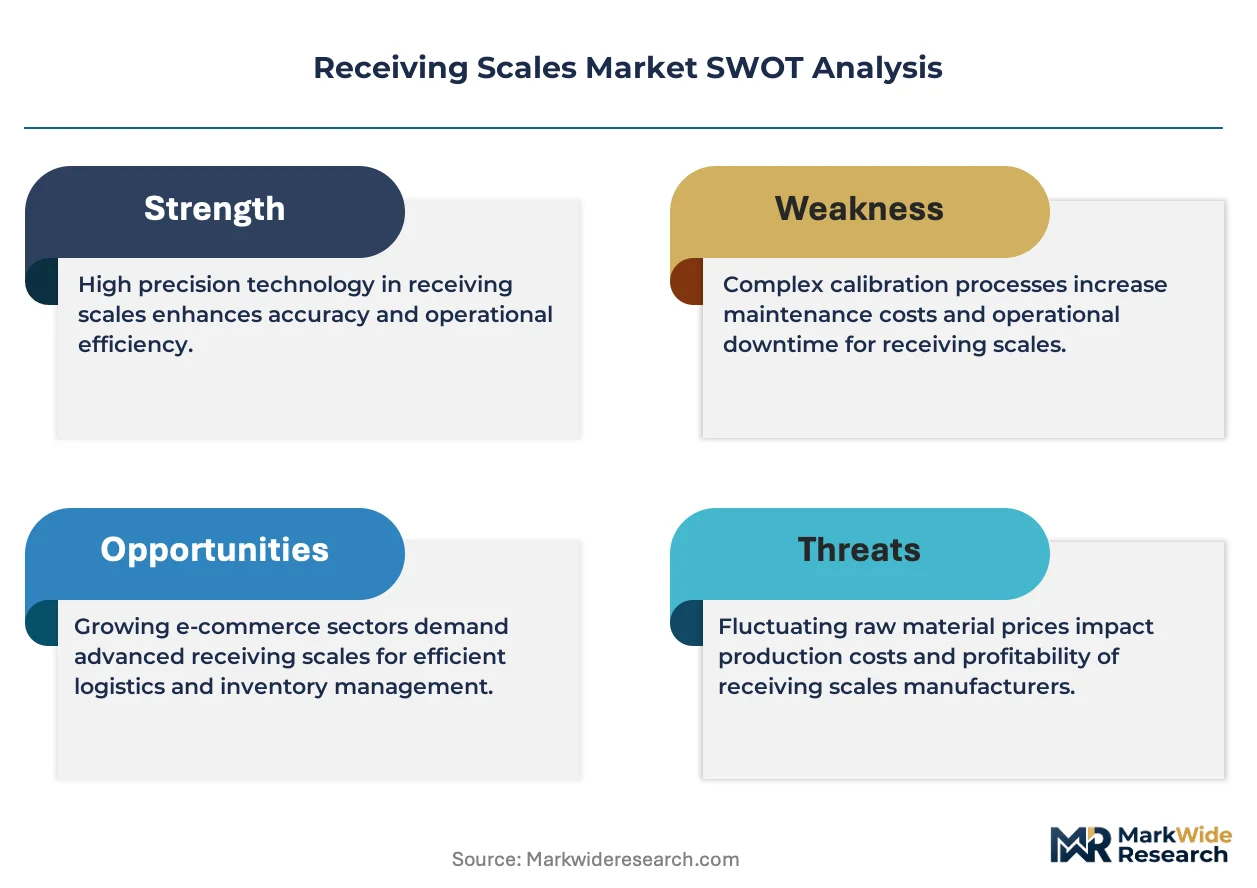
NIST in the United States, OIML across Europe, and METI in Japan enforce metrological compliance frameworks that mandate periodic verification, directly shaping replacement cycles and service-attach rates for receiving scale vendors. The EU's Measuring Instruments Directive and emerging CSRD reporting requirements are extending traceability obligations deeper into supplier networks, compelling buyers to prioritize certified, data-logging platforms. Stakeholders must weigh the pace of warehouse automation investment against regulatory harmonization risks as they allocate R&D budgets between connected-scale architectures and next-generation sensor technologies.
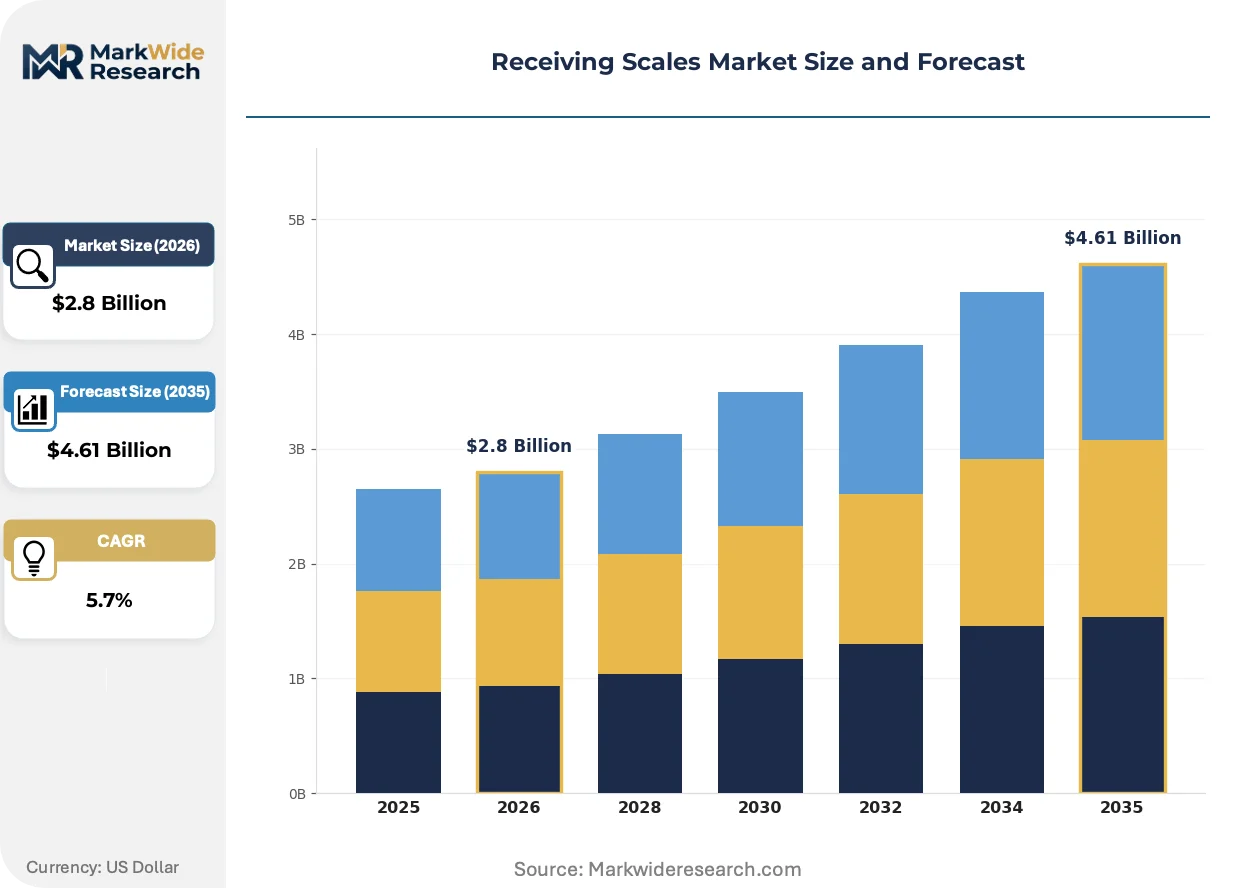
Market Dynamics
Warehouse automation investment and NIST Handbook 44 recalibration mandates are compressing replacement cycles while elevating service-attach rates as primary profit drivers across the receiving scales value chain.
Growth Catalysts
- Regulatory compliance cycles:NIST Handbook 44 mandates in the United States and OIML R76 requirements across Europe force periodic verification, generating recurring calibration revenue streams.
- Food processing automation:Agriculture terminals and protein processing facilities in Brazil deploy custom-capacity floor scales to automate inbound freight verification and supplier payment workflows.
- Digital load-cell platforms:Strain-gauge and electromechanical technologies face displacement as logistics operators prioritize connected platforms with direct warehouse management system integration.
Market Restraints
- Semiconductor input volatility:Load-cell signal processors and analog-to-digital converters face supply concentration risks from East Asian foundry capacity constraints.
- Calibration infrastructure scarcity:Certified metrology laboratories concentrate in Germany, Japan, and the United States, creating geographic service gaps in secondary markets.
- Legacy system interoperability:Electromechanical scales with analog outputs persist in high-vibration industrial environments, slowing full-platform replacement.
Strategic Opportunities
- EU CSRD traceability mandates:The Corporate Sustainability Reporting Directive extends measurement verification obligations into supplier networks, expanding certified platform demand.
- India warehouse modernization:PLI scheme incentives for logistics infrastructure accelerate automated receiving system deployment in Mumbai and Delhi distribution corridors.
- Edge-to-cloud convergence:Integration of Bluetooth Low Energy load-cell transmitters with SaaS inventory platforms creates new subscription revenue architectures.
Industry Challenges
- Metrology technician scarcity:Certified calibration specialists face supply constraints relative to fleet-scale deployment timelines, extending service wait periods.
- Multi-protocol integration complexity:Warehouse management system connectivity requires navigating proprietary data formats from SAP, Oracle, and regional logistics software vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Receiving Scales Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Scales, Mechanical Scales, Floor Scales, Bench Scales Technology: Load Cell, Strain Gauge, Electromechanical, Capacitive End User: Manufacturing, Logistics, Retail, Warehousing Capacity: 0-100 kg, 100-500 kg, 500-1000 kg, 1000+ kg |
| Companies Covered | Mettler-Toledo, Rice Lake Weighing Systems, Fairbanks Scales, Avery Weigh-Tronix, AandD Weighing, Doran Scales, Detecto Scale Company, Seca GmbH and Co.Kg, Health O Meter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Receiving Scales Market Strategic Shifts
Connected-scale architectures and regulatory traceability mandates are restructuring how receiving scales generate value, shifting revenue from hardware transactions toward data-enabled service ecosystems.
Bluetooth-enabled load-cell transmitters paired with cloud-native inventory platforms is digitizing how warehouses verify inbound freight weights. Third-party logistics operators in the United States and Germany deploy these systems to eliminate manual data entry and accelerate supplier payment cycles. The technology is digitizing traditional scale-to-ERP workflows, compressing implementation timelines from months to weeks.
Japan's METI enforcement of JIS B 7611 accuracy standards and periodic verification protocols tightens compliance windows for industrial weighing equipment. Manufacturers must now embed tamper-evident seals and automated calibration logging to satisfy inspection requirements. Food processing and pharmaceutical distribution centers face the steepest compliance burden, driving preference toward certified platforms with built-in audit trails.
Buyers now unbundle hardware acquisition from ongoing calibration service contracts, treating metrological compliance as a subscription rather than a capital expense. This procurement model shift pressures vendors to restructure pricing around per-weighing or per-verification metrics rather than upfront equipment sales. The pattern is most visible among United States-based logistics operators managing multi-site fleet deployments under centralized procurement functions.
Receiving Scales Market Segmentation
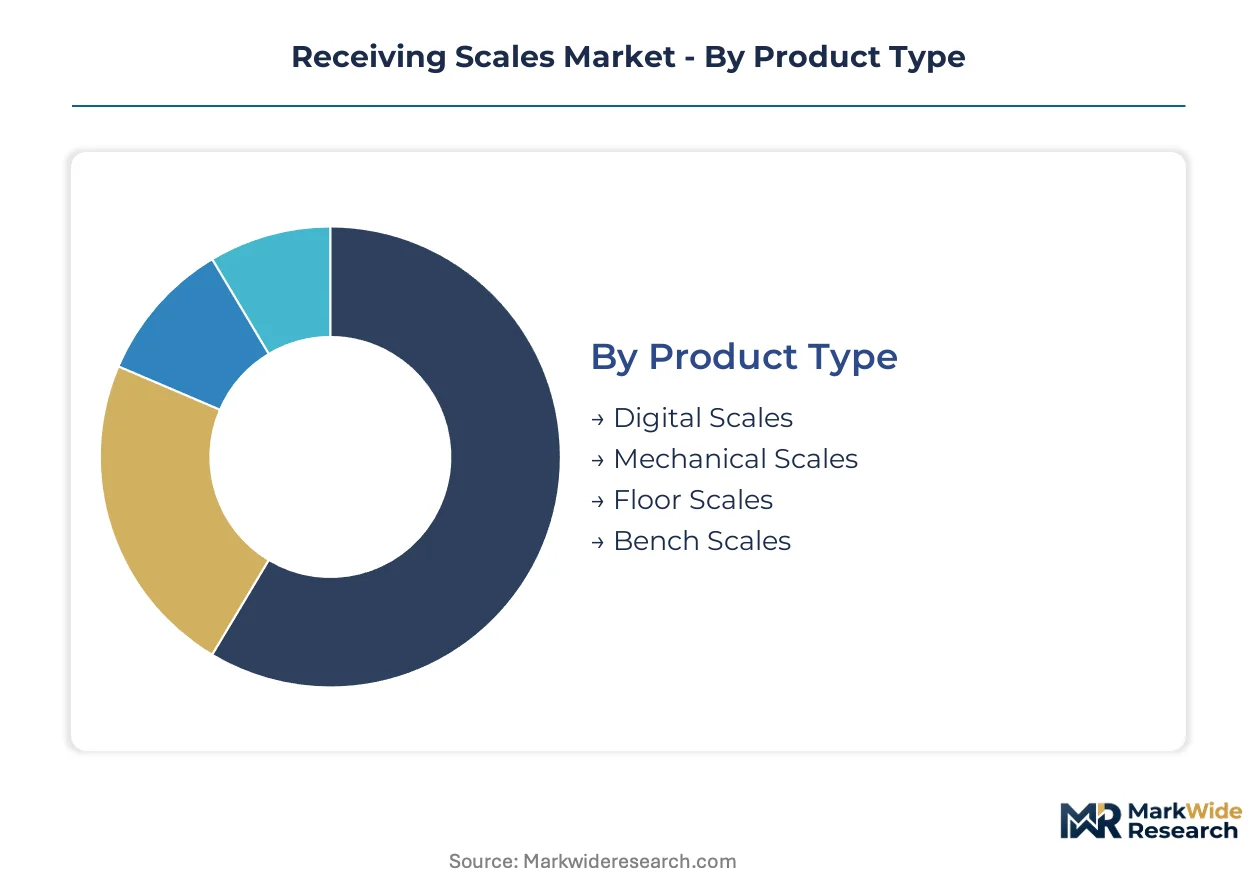
Receiving scales serve divergent operational requirements across weight classes, connectivity standards, and compliance regimes. Procurement patterns fragment sharply between facilities automating inbound verification and those maintaining legacy electromechanical infrastructure for cost containment.
Product Type:
Mature digital platforms dominate procurement budgets while mechanical alternatives retain defensive positions in cost-sensitive applications.
- Digital Scales:Load-cell platforms with analog-to-digital signal processing deliver 0.01 kg resolution and direct warehouse management system integration. Logistics operators in Germany and Japan prioritize these units to compress supplier payment cycles and eliminate manual data entry errors.
- Mechanical Scales:Spring and lever-based systems operate without electrical power, serving remote agriculture terminals and backup verification roles. Brazilian protein processors deploy these units where grid reliability fluctuates, accepting lower precision for operational continuity.
- Floor Scales:Low-profile platforms with 1000+ kg ratings handle palletized freight and bulk material verification.
- Bench Scales:Compact 0-100 kg units serve parcel sorting and small-parts counting in retail distribution.
Digital Scales retains volume leadership; Floor Scales holds the steepest expansion curve.
Technology:
Cost tiers separate precision instrumentation from commodity alternatives, with calibration infrastructure availability determining viable deployment geographies.
- Load Cell:Strain-gauge transducers bonded to aluminum or steel elements convert mechanical deformation to electrical signals with OIML R76-certified linearity. United States logistics fleets under NIST Handbook 44 mandates standardize on these platforms for compliance traceability.
- Strain Gauge:Thin-film resistive sensors measure substrate deformation in high-vibration industrial environments where electromagnetic interference disrupts capacitive alternatives.
- Electromechanical:Motor-driven force restoration balances deliver legal-for-trade precision in pharmaceutical and precious metals applications.
- Capacitive:Non-contact displacement sensing suits explosive atmosphere classifications and washdown-intensive food processing lines.
Load Cell commands procurement volume; Capacitive is expanding most quickly in hazardous environment certifications.
End User:
Application-specific accuracy requirements and integration complexity separate high-margin manufacturing deployments from standardized logistics configurations.
- Manufacturing:Incoming raw material verification with 0.1% tolerance requirements triggers production scheduling and supplier payment workflows. Japanese automotive component plants embed these scales directly into just-in-time receiving docks.
- Logistics:Third-party operators across United States distribution corridors deploy fleet-scale receiving scale networks to automate freight billing and dimensional weight compliance.
- Retail:High-volume parcel scales with Bluetooth connectivity accelerate cross-dock operations and returns processing.
- Warehousing:Bulk storage facilities verify inbound pallet weights against advance shipping notices before putaway authorization.
Logistics retains volume leadership; Manufacturing holds the steepest expansion curve.
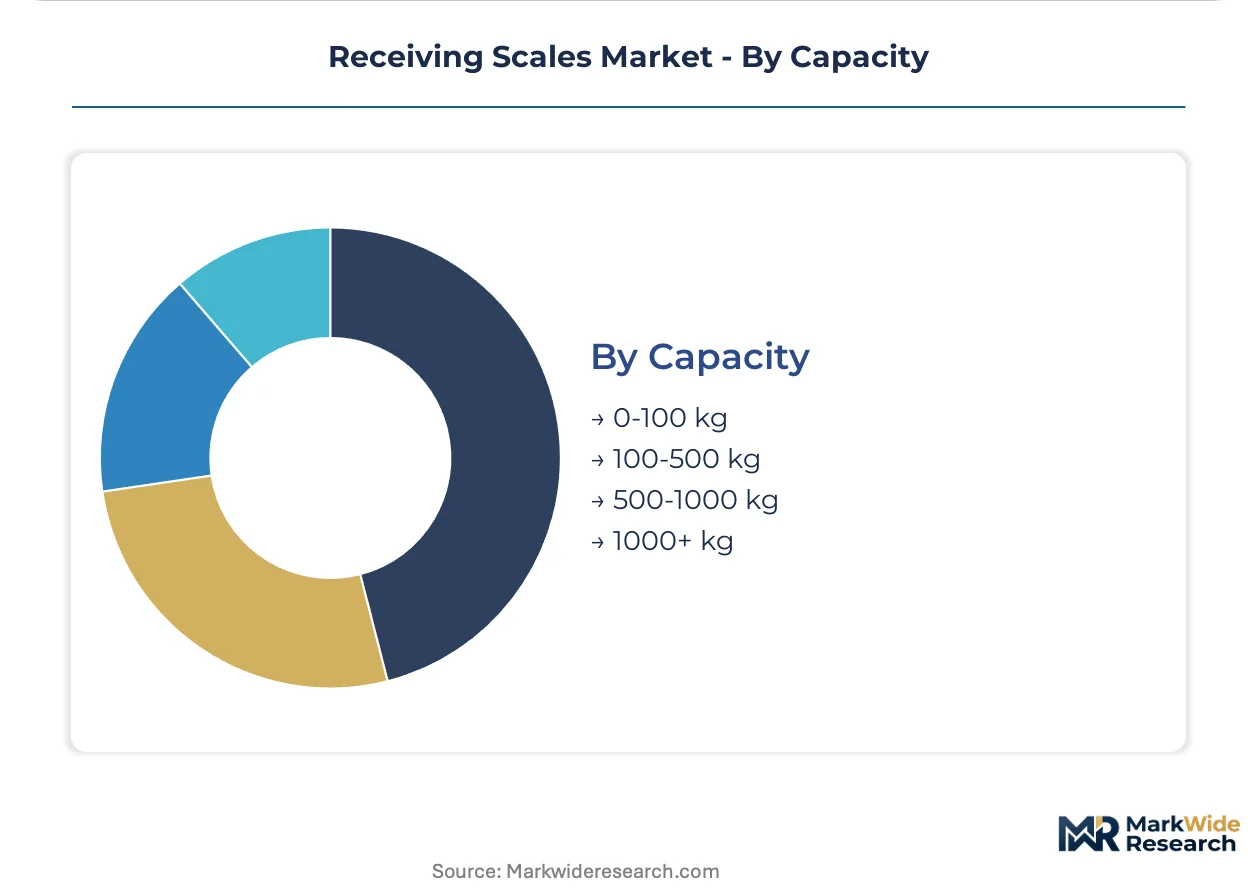
Capacity:
Customer type stratification concentrates unit demand in mid-range bands while premium configurations capture superior margins.
- 100-500 kg:The densest demand concentration serves palletized freight verification and mixed-SKU receiving in retail distribution centers. These platforms balance portability sufficient for dock mobility with precision adequate for supplier quantity disputes.
- 1000+ kg:Heavy-capacity floor scales with structural steel decks handle bulk material receiving and manufacturing raw material intake. Custom configurations for agriculture terminals in Brazil command pricing premiums through specialized deck coatings and corrosion-resistant load cells.
- 0-100 kg:Bench and portable units serve parcel post and small-parts counting applications.
- 500-1000 kg:Intermediate platforms bridge light industrial and heavy-capacity requirements with modular deck extensions.
100-500 kg retains volume leadership; 1000+ kg holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics operators in the United States deploy receiving scales primarily for freight billing automation, while Japanese manufacturers embed them directly into just-in-time production workflows, and Brazilian agriculture terminals prioritize ruggedized platforms for remote grid-unreliable environments.
United States
Third-party logistics operators across Chicago, Dallas-Fort Worth, and Los Angeles distribution corridors are expanding fleet-scale receiving scale deployments to comply with NIST Handbook 44 recalibration mandates. The Federal Trade Commission enforces accuracy standards for commercial weighing equipment through periodic verification protocols. Memphis and Louisville cargo hubs concentrate demand for 100-500 kg digital platforms integrated directly into warehouse management systems.
Germany
Automotive component plants in Baden-Württemberg and Bavaria embed receiving scales into incoming raw material verification workflows with 0.1% tolerance requirements. The EU Measuring Instruments Directive mandates OIML R76 certification for legal-for-trade applications, compressing replacement cycles. The Rhine-Ruhr logistics corridor drives procurement of connected load-cell platforms with direct ERP integration for supplier payment automation.
Japan
Pharmaceutical distribution centers in the Kanto region face steep compliance burdens under METI enforcement of JIS B 7611 accuracy standards and periodic verification protocols. The Osaka-Kobe manufacturing belt deploys electromechanical force restoration balances for precious metals and high-value component receiving. Automotive plants in Nagoya integrate tamper-evident sealed platforms with automated calibration logging to satisfy inspection requirements.
Brazil
Protein processing facilities and agriculture terminals in São Paulo and Minas Gerais deploy custom-capacity floor scales to automate inbound freight verification and supplier payment workflows. ANVISA enforces metrological traceability for food safety applications, driving preference for certified platforms. The Paraná grain corridor commands pricing premiums for specialized deck coatings and corrosion-resistant load cells in bulk material handling operations.
India
Distribution centers in Mumbai and Delhi-NCR corridors accelerate automated receiving system deployment under PLI scheme incentives for logistics infrastructure modernization. The Bureau of Indian Standards enforces certification requirements for commercial weighing equipment, elevating demand for traceable digital platforms. Gujarat pharmaceutical manufacturing clusters prioritize data-logging platforms to satisfy emerging export compliance obligations for EU and US markets.
Receiving Scales Market Competitive Environment
Capability concentration sits with specialized metrology houses; scale advantage sits with diversified instrumentation conglomerates. The vendor base organizes around three strategic archetypes: global service infrastructure operators capturing recurring calibration revenue, custom-capacity specialists anchoring position in food and agriculture terminals, and integrated software-platform vendors differentiating through warehouse management system connectivity. Dominant competitive moves include backward integration into load-cell manufacturing and geographic expansion through certified metrology laboratory networks.
Among diversified instrumentation conglomerates, Mettler-Toledo and Avery Weigh-Tronix exemplify the global service infrastructure archetype, leveraging international calibration networks to capture compliance-driven recurring revenue. Rice Lake Weighing Systems occupies a specialist position, representing the custom-capacity fabrication tier with deep concentration in agricultural and food processing applications. These three anchors illustrate how competitive positioning fragments between scale-driven platform breadth and specialized vertical expertise.
| Leading Market Players |
|---|
| Mettler-Toledo |
| Rice Lake Weighing Systems |
| Fairbanks Scales |
| Avery Weigh-Tronix |
| AandD Weighing |
| Doran Scales |
| Detecto Scale Company |
| Seca GmbH and Co.Kg |
| Health O Meter |
| Others |
Value Chain & Pricing Dynamics
Semiconductor input volatility from East Asian foundry concentration determines both pricing tier spreads and supply chain shape across receiving scales procurement. Load-cell signal processors and analog-to-digital converters face supply concentration risks that compress margins in economy-tier platforms while premium certified systems absorb cost through service-attach pricing.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement for fleet-scale logistics operators, while spot purchasing persists in small-scale agriculture terminals. Price differentiation hinges on NIST Handbook 44 certification grade and after-sales calibration bundling. Cost compression in economy-tier mechanical scales is intensifying because Brazilian protein processors prioritize operational continuity over precision. Third-party logistics operators in the United States exhibit lowest price sensitivity due to compliance-driven replacement mandates.
Supply Chain Analysis
Extended payment terms from German and Japanese metrology equipment vendors shape working capital requirements for distributors serving secondary markets. Load-cell manufacturing concentrates in Germany, Japan, and China, with strain-gauge transducers and aluminum alloy substrates drawing from precision metalworking clusters. Single-source vulnerability in analog-to-digital converter supply creates exposure to foundry capacity constraints. Distribution runs through authorized metrology service partners with certified calibration laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The receiving scales market functions as a defensive-moat story anchored in regulatory entrenchment. NIST Handbook 44, OIML R76, and METI JIS B 7611 mandates create switching costs that lock buyers into certified vendor relationships.
For Market Incumbents: Build switching-cost moats through embedded calibration service contracts that synchronize with regulatory verification cycles. Acquire certified metrology laboratories in India and Brazil to close geographic service gaps before regional competitors consolidate. Defend against low-cost digital platform entrants by deepening software integration with SAP and Oracle warehouse management systems. For New Entrants and Emerging Players: Mid-market warehousing operators in India represent the most penetrable entry point, as PLI scheme incentives accelerate infrastructure investment without entrenched vendor relationships. Target Bluetooth-enabled load-cell transmitter niches where cloud-native inventory platforms seek hardware-agnostic integration partners. Pursue white-label manufacturing partnerships with established load-cell fabricators to bypass capital-intensive certification timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors service infrastructure operators over hardware-only manufacturers. Long-term viability rests on recurring calibration revenue streams rather than transactional equipment sales. Monitor METI enforcement intensity in Japan and CSRD traceability mandate rollout in Europe as inflection indicators for certified platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Load-Cell Manufacturing | Captive supply of strain-gauge transducers insulates margin pressure from East Asian foundry volatility. |
| Certified Metrology Laboratory Expansion | Geographic coverage in India and Brazil closes service gaps that delay fleet-scale deployment timelines. |
| Warehouse Management System Platform Integration | Direct SAP and Oracle connectivity accelerates supplier payment cycles and locks in logistics operator accounts. |
| Calibration Service Subscription Repricing | Per-verification metrics transform compliance costs from capital expenditure to operational budget line items. |
| Bluetooth Low Energy Transmitter Development | Edge-to-cloud convergence creates SaaS inventory platform partnerships with compressed implementation timelines. |
Study Parameters
A spread of perspectives from logistics procurement directors, metrology laboratory technicians, warehouse automation engineers, and food processing plant managers converged on the working assumptions. Primary interviews combined with secondary validation from NIST Handbook 44 documentation, OIML R76 certification records, METI JIS B 7611 standards filings, and customs trade data for load-cell component imports. Bottom-up unit demand modeling triangulated against top-down market sizing across digital, mechanical, floor, and bench scale categories.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user industry, and capacity band alongside regional regulatory cluster intensity. CAGRs derived from replacement cycle analysis calibrated to NIST, OIML, and METI verification mandates. Forecast inputs incorporated warehouse automation investment trajectories and semiconductor foundry capacity utilization rates.
Macroeconomic conditions sit as an overlay; deviation in logistics capital expenditure cycles or East Asian trade policy would shift the trajectory. Forecasts reflect assumptions on regulatory harmonization pace and calibration technician supply elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Security Bottles Market
Others
GCC Cigarette Market
Others
Solar Animal Repellent Market
Others
Binoculars and Mounting Solutions Market
Others
Programmatic Display Market
Others
Quadrant Scale Market
Others
Mobile MRI Services Market
Others
Wind and Solar Hybrid Street Light Market
Others
Cryogenic Storage Tanks Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Global Surface Analysis Market
Others
Smart Badge Market
Others
Global Extruded Plastics Market
Others
Global Molded Plastics Market
Others
Insoluble Sulfur Market
Others
Social Media Engagement Applications Market