
 Finished Leather Market | 2026-2036
Finished Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Finished Leather Market Analysis
Leather Working Group (LWG) certification is reorganizing supplier hierarchies in the finished leather value chain, favoring tanneries with audited traceability and wastewater protocols. Hermès International sustains its position through captive tannery operations and strict vertical control over raw material grading. Stahl Holdings B.V. dominates water-based finishing chemistry, while LANXESS AG extends its portfolio into sustainable biocide-free preservation systems.
Finished leather denotes hides and skins that have completed the full tanning, retanning, dyeing, and surface finishing sequence, achieving specified thickness tolerances, tensile strength above 20 MPa, and controlled moisture content for end-use performance. Its primary commercial purpose is delivering dimensionally stable, abrasion-resistant material for goods requiring both aesthetic grading and functional durability. Full grain commands the premium grade tier due to intact fiber structure and natural pore character, while upholstery as an end-use channel captures expanding margin pools from hospitality and aviation refurbishment cycles. Corrected grain occupies the volume tier where uniform surface embossing supports cost-sensitive footwear programs.
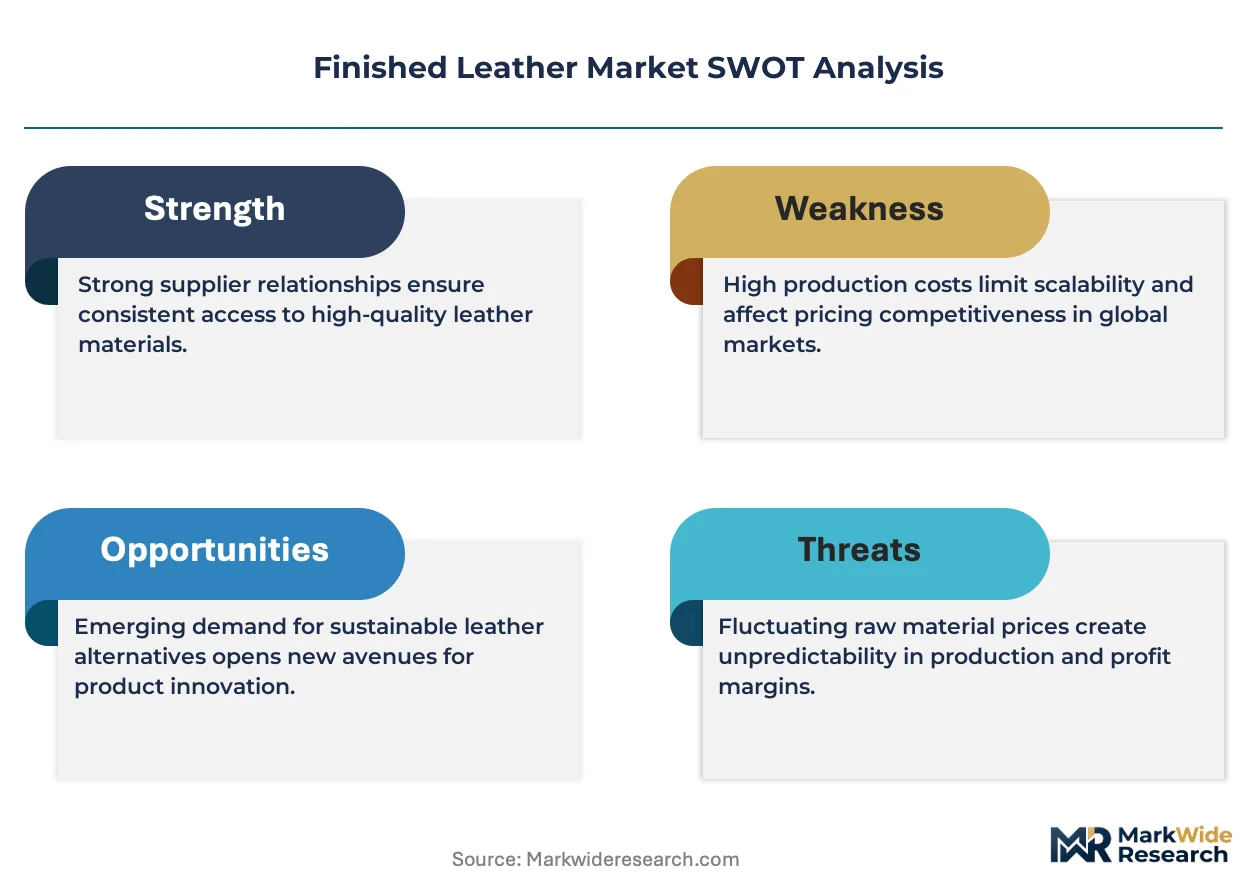
REACH in Europe, EPA effluent guidelines in the United States, and ZDHC Manufacturing Restricted Substances List together constrain permissible chemistries in tanning and finishing, redirecting R&D spend toward bio-based retanning agents and closed-loop water systems. India's Central Pollution Control Board mandates chrome recovery infrastructure for large tanneries, reshaping export eligibility for Kanpur and Kolkata clusters. Stakeholders must monitor how pending regulatory deadlines for perfluorinated compound phase-outs alter waterproof finishing specifications before committing to multi-year chemical supply agreements.
Market Dynamics
The finished leather market is restructuring around chemical compliance mandates, with EU REACH chromium VI restrictions and ZDHC Manufacturing Restricted Substances List requirements forcing tanneries to abandon legacy chemistries and rebuild finishing protocols from raw material intake through wastewater discharge.
Growth Catalysts
- REACH regulatory tightening:The European Chemicals Agency's progressive chromium VI limits are accelerating investment in chrome-free tanning systems across Italian and Spanish tanneries, creating certified supply premiums for compliant finishers.
- Aviation refurbishment cycles:Commercial airline cabin retrofits are expanding demand for fire-retardant upholstery grades that meet FAA burn-test standards, pulling specialized finishing capacity toward aerospace certification tiers.
- Water-based chemistry advances:Polyurethane dispersions with improved flex resistance are penetrating automotive seating programs, displacing solvent-borne systems in German and Japanese OEM supply chains.
Market Restraints
- Raw material cost volatility:Salt-cured hide prices fluctuate with livestock herd cycles and meatpacking plant throughput in Brazil and Argentina, compressing tannery margins during supply crunches.
- Supply concentration risk:Italy's Arzignano cluster controls a disproportionate share of premium finishing capacity for European luxury brands, creating geographic single-point vulnerability.
- Synthetic substitution pressure:Microfiber polyurethane alternatives from Korean and Taiwanese producers are capturing cost-sensitive footwear and furniture segments through improved hand-feel replication.
Strategic Opportunities
- Indian export compliance infrastructure:The Central Pollution Control Board's chrome recovery mandates are filtering out subscale Kanpur tanneries, opening certified supply positions for compliant exporters to EU and US buyers.
- Biocide-free preservation systems:LANXESS and specialty chemical suppliers are developing salt-free preservation for wet-blue intermediates, addressing ZDHC compliance gaps in cross-border hide trading.
- Hospitality direct sourcing:Hotel chains and restaurant groups are bypassing distributors to contract directly with LWG-certified tanneries for uniform upholstery programs with traceable origin documentation.
Industry Challenges
- Finishing technician scarcity:Master craftsmen capable of hand-rubbed aniline finishing and specialized pull-up effects are aging out of the workforce in Italy's Veneto region without sufficient apprenticeship pipelines.
- Multi-certification burden:Tanneries serving automotive, aviation, and luxury goods simultaneously must maintain parallel audit streams for IATF 16949, AS9100, and LWG protocols, diverting management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finished Leather Market |
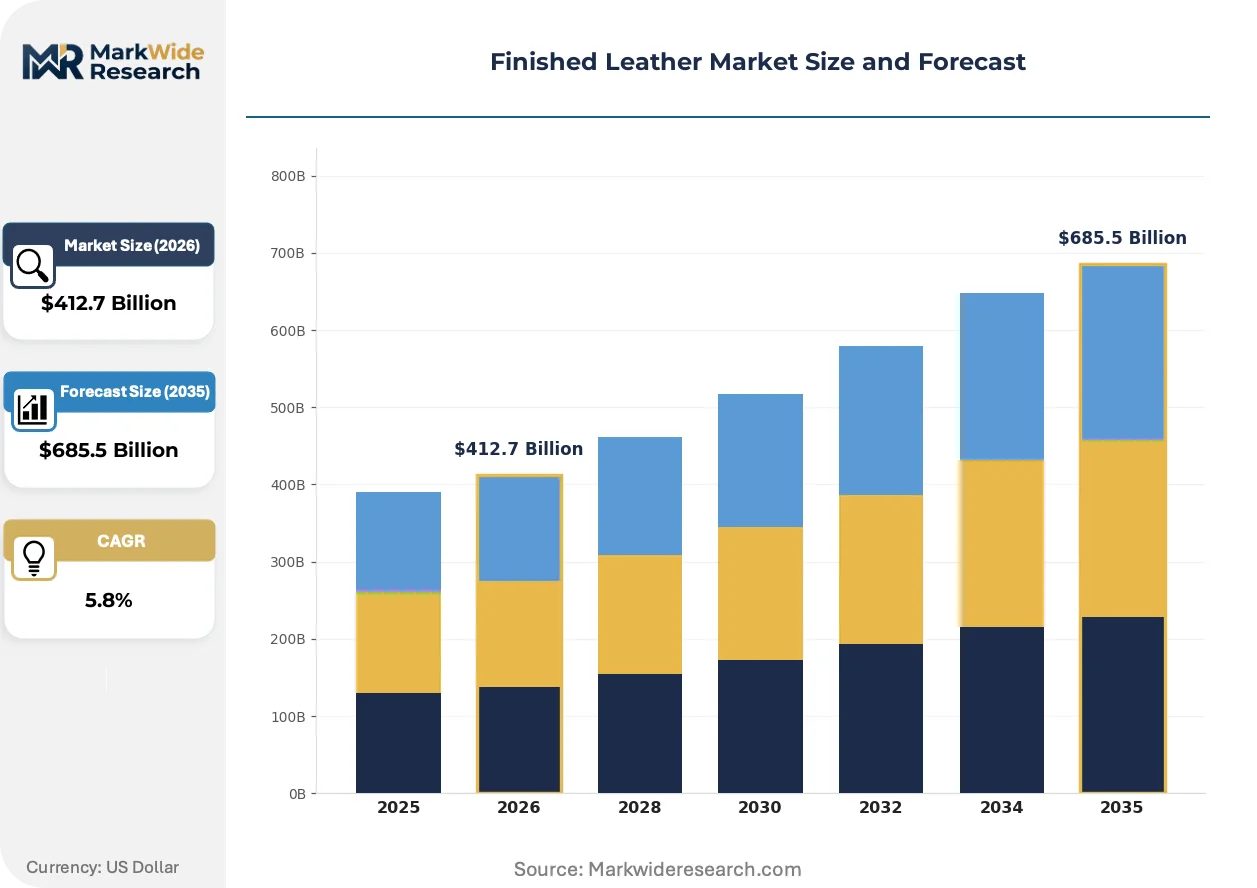
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $685.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Finished Splits, Full Grain, Top Grain, Corrected Grain End Use: Footwear, Apparel, Upholstery, Accessories Packaging Type: Rolls, Hides, Sheets, Drum Grade: Premium, Standard, Economy, Specialty |
| Companies Covered | Clariant AG, DuPont de Nemours Inc, BASF SE, Hermès International, Eastman Chemical Company, Stahl Holdings B.V., TFL Ledertechnik GmbH, LVMH, LANXESS AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finished Leather Market Emerging Trajectories
Digital traceability and bio-based chemistry are converging to redefine how finished leather is specified, audited, and valued across buyer segments, with transparency becoming a tradable attribute rather than a compliance checkbox.
Enzymatic degreasing and bio-retanning agents derived from olive leaf extract and chestnut tannins are decomposing the petroleum-dependency of conventional processing. Premium Italian automotive suppliers are piloting these systems for BMW and Mercedes-Benz contract renewals. The technology is decomposing the cost advantage of mineral-tanned commodity grades in high-specification applications.
EPA effluent guideline revisions under the Clean Water Act are tightening discharge limits for chromium and sulfide in US tanneries, particularly affecting Pennsylvania and Tennessee operations serving domestic footwear brands. Facilities are responding with membrane filtration and chrome recovery investments, though smaller processors face facility closure decisions.
Brand-led supply chain mapping is displacing traditional hide merchant intermediaries as Hermès, Kering, and LVMH deploy blockchain-tracked sourcing platforms. Luxury goods houses now require lot-level traceability from abattoir to finished article. This transformation is most advanced in French and Italian leather goods manufacturing, where captive tannery relationships provide audit control.
Finished Leather Market Segmentation
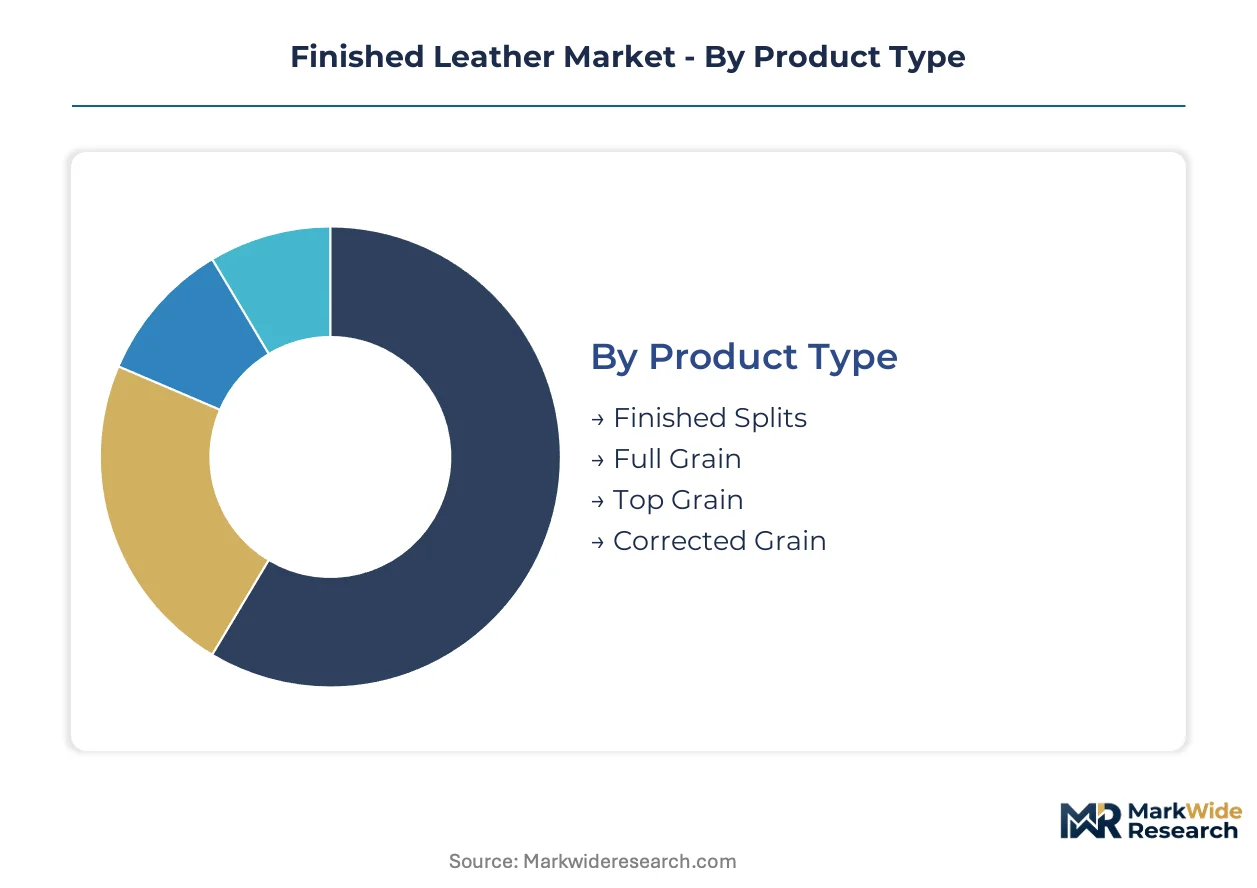
Finished leather segmentation reflects divergent compliance burdens and performance specifications across buyer tiers. Regulatory thresholds from ECHA REACH and ZDHC MRSL reshape which product grades and end-use channels absorb capital investment versus face substitution pressure.
Product Type:
REACH chromium VI limits and ZDHC MRSL substance restrictions fragment product type viability, with chrome-free tanning systems commanding certified supply premiums while conventional mineral-tanned grades face compliance-driven demand erosion.
- Full Grain:Intact fiber structure preserves natural pore character and tensile strength above 20 MPa. Italian tanneries in the Arzignano cluster supply BMW and Mercedes-Benz seating programs where LWG certification and REACH compliance justify material premiums.
- Corrected Grain:Uniform surface embossing through sanding and pigment coating enables cost-sensitive footwear production. Brazilian and Argentine tanneries serve volume footwear brands where synthetic microfiber alternatives from Korean producers erode market position.
- Top Grain:Slightly sanded surface retains fiber integrity with enhanced dye absorption for apparel applications.
- Finished Splits:Flesh layer processing with polymer coating achieves suede-like aesthetics at reduced raw material cost.
Established volume favors Corrected Grain; emerging adoption favors Full Grain.
End Use:
Application-specific certification tiers reshape procurement patterns, with aviation and automotive channels demanding parallel audit streams that filter supplier participation.
- Upholstery:Fire-retardant grades meeting FAA burn-test standards pull specialized finishing capacity toward aerospace retrofit cycles. Commercial airline cabin refurbishment programs in Germany and Japan concentrate demand for certified upholstery supply.
- Footwear:Corrected grain and finished splits dominate volume production where cost sensitivity accelerates synthetic substitution. Korean and Taiwanese microfiber producers capture margin compression through improved hand-feel replication.
- Apparel:Lightweight full grain and top grain specifications serve luxury garment manufacturers requiring traceable origin documentation.
- Accessories:Small leather goods demand premium grades with strict thickness tolerances for precision cutting and edge finishing.
Footwear retains volume concentration; upholstery climbs the fastest on certification-driven specification tightening.
Packaging Type:
Logistics configuration reflects hide preservation chemistry and customer processing infrastructure, with salt-free wet-blue intermediates demanding specialized drum packaging for biocide-free preservation systems.
- Hides:Whole hide preservation in salt or chrome-tanned wet-blue enables tannery-level splitting and grading flexibility. Indian Central Pollution Control Board chrome recovery mandates reshape export packaging standards for Kanpur and Kolkata clusters.
- Rolls:Finished leather in continuous rolls supports automated cutting systems in automotive and furniture manufacturing. German OEM seating plants specify roll format for just-in-sequence production.
- Sheets:Pre-cut dimensions serve small-batch apparel and accessory manufacturers with limited splitting equipment.
- Drum:Wet-blue and wet-white intermediates in drum packaging preserve moisture content for cross-border trading under ZDHC-compliant preservation protocols.
Hides dominate commodity flow; rolls gain share fastest on manufacturing automation penetration.
Grade:
Grade stratification aligns with certification tier and end-use performance requirements, with premium grades absorbing traceability technology costs and economy grades facing synthetic displacement.
- Premium:Full grain with intact natural surface, hand-rubbed aniline finishing, and blockchain-tracked origin documentation. Hermès and LVMH captive tannery relationships enforce lot-level traceability from abattoir to finished article.
- Specialty:Custom pull-up effects, waxed finishes, and specialized hand techniques requiring master craftsmen. Aging workforce in Italy's Veneto region constrains supply expansion without apprenticeship pipeline investment.
- Standard:Semi-aniline and pigmented finishes balancing durability with cost control for mid-tier automotive and furniture applications.
- Economy:Corrected grain with heavy pigment coating and embossed uniform surfaces for price-sensitive footwear and mass-market furniture.
Premium and Standard absorb compliance investment; Specialty faces capability scarcity constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's dominance in specialty tanning chemistry distribution, while the Suez Canal corridor channels raw hide flows between South American slaughterhouses and Asian processing centers.
Italy
Luxury automotive seating contracts from BMW and Mercedes-Benz sustain demand for full-grain upholstery grades. ECHA REACH chromium VI restrictions force Arzignano tanneries to rebuild finishing protocols around chrome-free systems. The Veneto tanning cluster concentrates premium finishing capacity where master craftsmen execute hand-rubbed aniline effects.
United States
Commercial airline cabin refurbishment programs drive fire-retardant upholstery specifications meeting FAA burn-test standards. EPA effluent guideline revisions under the Clean Water Act tighten chromium and sulfide discharge limits for Pennsylvania and Tennessee tanneries. Domestic footwear brands source from smaller processors facing facility closure decisions absent membrane filtration investments.
India
Export eligibility to EU and US buyers hinges on compliance infrastructure for chrome recovery and wastewater treatment. The Central Pollution Control Board mandates chrome recovery systems for large tanneries across Kanpur and Kolkata clusters. Compliant exporters capture certified supply positions as subscale competitors exit.
Brazil
Salt-cured hide exports fluctuate with livestock herd cycles and meatpacking plant throughput. ANVISA chemical registration requirements shape preservative chemistry selection for wet-blue intermediates. São Paulo state processors serve volume footwear brands where synthetic microfiber alternatives erode market position.
Germany
Automotive OEM seating plants specify roll-format finished leather for just-in-sequence production lines. KBA vehicle type approval standards intersect with REACH compliance for interior material emissions. Bavarian chemical suppliers develop water-based polyurethane dispersions displacing solvent-borne systems in German supply chains.
Finished Leather Market Vendor Landscape
Listed leaders compete with private specialists across chemical supply and captive tannery operations. The vendor base separates into three tiers: diversified chemical conglomerates supplying retanning agents and finishing polymers, luxury houses maintaining backward integration into raw material grading, and mid-scale finishers competing on LWG certification and REACH compliance. Strategic moves concentrate on M&A for chemical technology access and capacity expansion in certified finishing lines.
Within the specialty chemical tier, Stahl Holdings B.V. and LANXESS AG exemplify European suppliers pivoting toward water-based and biocide-free preservation systems. Hermès International occupies a distinct position through captive tannery relationships that enforce lot-level traceability from abattoir to finished article. These three entities anchor different competitive vectors: chemistry innovation, vertical supply control, and audit-intensive brand alignment.
| Leading Market Players |
|---|
| Clariant AG |
| DuPont de Nemours Inc |
| BASF SE |
| Hermès International |
| Eastman Chemical Company |
| Stahl Holdings B.V. |
| TFL Ledertechnik GmbH |
| LVMH |
| LANXESS AG |
| Others |
Supply Flow & Price Mechanics
Arzignano cluster capacity utilization above 85 percent anchors premium grade price floors while compressing margins on commodity grades. REACH compliance investments and chrome recovery infrastructure reshape supplier economics, concentrating pricing power among LWG-certified finishers serving BMW and Mercedes-Benz seating programs.
Pricing Analysis
Certification level creates the primary spread across finished leather tiers, with LWG Gold-rated tanneries commanding 15-25 percent premiums over unrated competitors in automotive and aviation channels. Pricing stratifies across premium full-grain, standard semi-aniline, and economy corrected-grain tiers based on traceability depth and hand-finishing labor intensity. Cost compression in corrected-grain footwear segments is intensifying because Korean microfiber producers replicate hand-feel at 40 percent lower unit economics. Mass-market footwear buyers exhibit highest price sensitivity, while Hermès and LVMH captive supply relationships demonstrate lowest elasticity due to origin-documentation requirements.
Supply Chain Analysis
Inventory lead times for salt-cured hides extend 45-60 days from Brazilian and Argentine slaughterhouses to Italian finishers, creating working capital intensity that filters subscale participants. Raw material flows draw from South American livestock herds, German polyurethane dispersion chemistry, and Indian wet-blue intermediates. Single-source vulnerability concentrates in Arzignano's master craftsman pool for hand-rubbed aniline effects. Distribution runs through Rotterdam chemical handling infrastructure for specialty retanning agents, with roll-format finished leather shipping direct to German OEM seating plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finished leather sits in early-cycle expansion as aviation refurbishment programs and chrome-free tanning system adoption create certified supply premiums. REACH regulatory tightening and ZDHC compliance gaps generate durable tailwinds for compliant finishers across European and North American buyer segments.
For Market Incumbents: Compound certification advantages by acquiring distressed Kanpur tanneries with Central Pollution Control Board-compliant chrome recovery infrastructure. Deepen backward integration into wet-blue preservation chemistry through LANXESS-style biocide-free system partnerships. Synthetic microfiber substitution in footwear and hospitality furniture represents the central threat requiring premium grade differentiation. For New Entrants and Emerging Players: Anchor in Indian export compliance infrastructure where CPCB mandates filter subscale competitors and create certified supply positions for EU and US buyers. Target fire-retardant upholstery grades for commercial aviation retrofit cycles in Germany and Japan. Lead with blockchain-tracked origin documentation as the go-to-market wedge against established hide merchant intermediaries. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors chemical suppliers with water-based polyurethane dispersion portfolios over commodity tannery operators. Five-to-ten year viability hinges on bio-retanning agent R&D pipelines and closed-loop water system deployment. Monitor perfluorinated compound phase-out deadlines as the critical inflection signal for waterproof finishing specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Chrome-Free Tanning Capacity Expansion | ECHA REACH compliance deadlines force Italian and Spanish tanneries into capital-intensive protocol rebuilds. |
| Blockchain Traceability Platform Deployment | Hermès and Kering lot-level sourcing requirements displace traditional hide merchant intermediaries. |
| Biocide-Free Preservation Chemistry Partnership | LANXESS salt-free wet-blue systems address ZDHC MRSL gaps in cross-border hide trading. |
| Aviation Certification Tier Investment | FAA burn-test standard compliance pulls specialized finishing capacity toward aerospace retrofit demand. |
| Apprenticeship Pipeline Development | Veneto region master craftsman aging threatens hand-rubbed aniline finishing supply expansion. |
Methodological Framework
Initial hypotheses were tested against primary input from tannery operations managers, automotive OEM procurement leads, chemical supplier technical directors, and luxury goods supply chain executives and refined through secondary validation. Customs records, LWG audit databases, ECHA regulatory filings, and EPA effluent discharge reports provided triangulation anchors. Bottom-up capacity modeling across Italian, Indian, and Brazilian production clusters converged with top-down demand segmentation by end-use channel.
Variance decomposition across product type, end-use application, grade tier, and regional production hub informed the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by certification penetration rates and chrome-free tanning system adoption curves. Hide price volatility indices and REACH compliance cost curves served as industry-specific forecast inputs.
Material uncertainties — livestock herd cycle fluctuations, perfluorinated compound regulatory phase-out timing, and synthetic microfiber hand-feel replication advances — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification adoption rates and automotive seating content per vehicle. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Thailand Commercial Vehicles Lubricants Market
Others
Roasted Wheat Market
Others
North America Smart Homes Market
Others
Content Experience Platforms Market
Others
China Packaging Primers Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Underwater Lighting Market
Others
Disposable Non Woven Sponge Market
Others
8K Technology Market
Others
Global Enterprise Mobility in Healthcare Market
Others
Enterprise Video Content Management Market
Others
Latin America Domestic CEP Market
Others
Global Fertility Tracking Apps Market
Others
Fluid Dispensing Systems Market
Others
Digital Transformation of Maritime Freight Market
Others
Global Tobacco Market