
 Coriolis Meters Market | 2026-2036
Coriolis Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Coriolis Meters Market Analysis
Titanium is repositioning stainless steel in Coriolis meter construction as producers chase corrosion resistance without density penalties. Emerson Electric leverages captive metallurgy partnerships to secure titanium supply chains. Endress+Hauser anchors its European manufacturing base with in-house tube fabrication. KROHNE Messtechnik competes through specialized hygienic designs for food-grade applications.
A Coriolis meter measures mass flow and fluid density by detecting phase shifts in vibrating flow tubes, typically operating at resonance frequencies between 80 Hz and 1.2 kHz depending on tube geometry and fluid properties. The device eliminates the need for separate temperature and density compensation, making it indispensable for precise custody transfer in hydrocarbon trading and batch dosing in pharmaceutical synthesis. Mass flow meters occupy the largest revenue pool given their universality across process industries, while multivariable meters represent the fastest-expanding category as plants consolidate instrumentation counts. Wireless-enabled units are gaining share in retrofit environments where cabling costs dominate project economics.
The US EPA mandates emission quantification protocols that favor direct mass measurement over inferred calculations, steering operators toward certified Coriolis installations. In Europe, the Measuring Instruments Directive and ATEX certification requirements shape product design for hazardous zone deployment. China's SAMR enforces metrological approval standards that foreign suppliers must navigate for market access. Stakeholders should monitor how digital twin integration and edge-computing analytics reshape the value proposition from hardware sales toward performance-guaranteed service contracts.
Market Dynamics
Coriolis meter demand is bifurcating between high-precision custody transfer installations and compact multivariable units for process optimization, as end-users consolidate instrumentation footprints while tightening measurement certainty requirements.
Growth Catalysts
- EPA greenhouse gas protocols:The US EPA mandates direct mass measurement for emission quantification, eliminating inferred calculations and certifying Coriolis installations for compliance reporting.
- Chemical processing clusters:Germany's industrial corridor concentrates demand for hygienic multivariable meters in batch synthesis and reactor feed control applications.
- Titanium metallurgy:Advanced tube fabrication techniques enable corrosion-resistant construction without density measurement penalties, expanding addressable applications in sour gas and acidic process streams.
Market Restraints
- Titanium supply concentration:Sponge and mill product availability concentrates with limited qualified suppliers, creating input cost volatility and extended lead times for high-specification meters.
- SAMR metrological barriers:China's State Administration for Market Regulation enforces approval standards that foreign suppliers navigate through extended certification timelines and local testing protocols.
- Ultrasonic substitution:Clamp-on ultrasonic meters advance in non-custody transfer applications where density measurement is secondary, compressing addressable volume in water and clean fluid segments.
Strategic Opportunities
- Wireless retrofit channels:Battery-powered transmitters with WirelessHART protocols penetrate brownfield installations where trenching and cable routing dominate project economics.
- Edge analytics convergence:Integration of vibration spectrum analysis with on-device computing enables predictive maintenance contracts that shift revenue from hardware sales to performance guarantees.
- India's PLI scheme:Production-linked incentives for process instrumentation manufacturing attract local assembly investments to serve petrochemical expansions on the western coast.
Industry Challenges
- Metrology technician scarcity:Qualified personnel for field verification and traceable calibration remain concentrated with original equipment manufacturers, constraining service network expansion.
- Legacy system integration:Foundation Fieldbus and proprietary bus architectures in installed bases complicate digital twin connectivity and data standardization initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coriolis Meters Market |
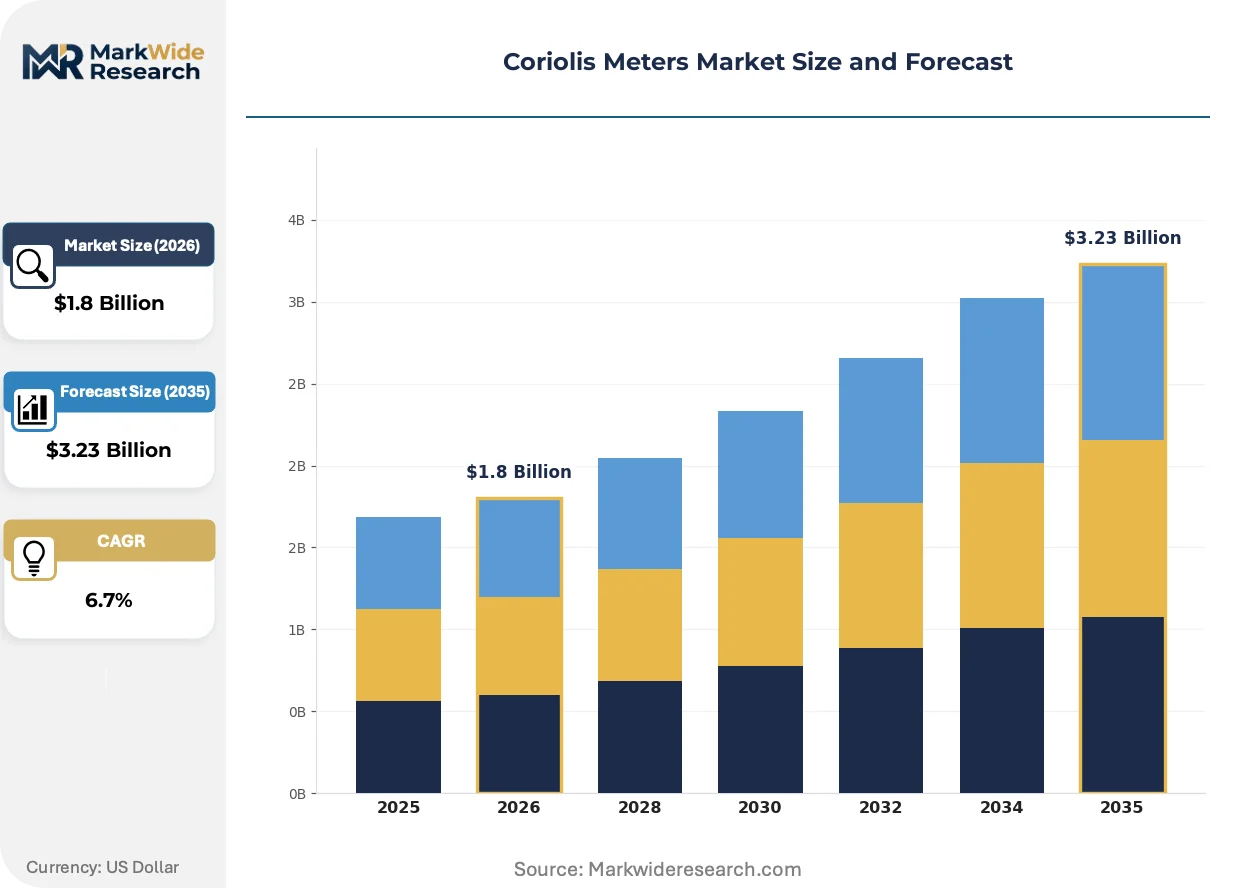
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mass Flow Meters, Density Meters, Multivariable Meters, Compact Meters End User: Oil & Gas, Chemical Processing, Food & Beverage, Water Treatment Technology: Digital, Analog, Wireless, Remote Monitoring Application: Bulk Measurement, Quality Control, Process Monitoring, Custody Transfer |
| Companies Covered | Emerson Electric, Endress+Hauser, KROHNE Messtechnik, Siemens, Yokogawa Electric, ABB, Baker Hughes, Bronkhorst High-Tech, Rheonik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coriolis Meters Market Emerging Trajectories
Digitalization is compressing the value chain from sensor hardware toward embedded diagnostics and remote verification capabilities, reshaping how operators procure and maintain flow measurement assets.
Dual-curved tube geometries are absorbing torsional stress more efficiently than traditional U-tube designs, enabling higher flow capacity in compact form factors. Offshore platform operators and FPSO contractors are specifying these configurations to reduce skid weight and footprint. The technology is absorbing market share in subsea and space-constrained installations where conventional meters face mechanical fatigue limits.
REACH substance restrictions and the EU F-Gas Regulation are phasing out certain sealing materials and heat transfer fluids used in transmitter housings. Meter manufacturers are reformulating elastomer specifications and migrating to alternative thermal management approaches. European chemical and pharmaceutical end-users are prioritizing suppliers with full material disclosure and substitution documentation to preempt compliance gaps.
Service unbundling is separating hardware procurement from calibration and verification contracts. Large refining and LNG operators are negotiating multi-site framework agreements with independent metrology service providers, bypassing traditional single-source OEM maintenance structures. This pattern is most pronounced in the US Gulf Coast and North Sea basins where operator consolidation has centralized procurement functions.
Coriolis Meters Market Segmentation
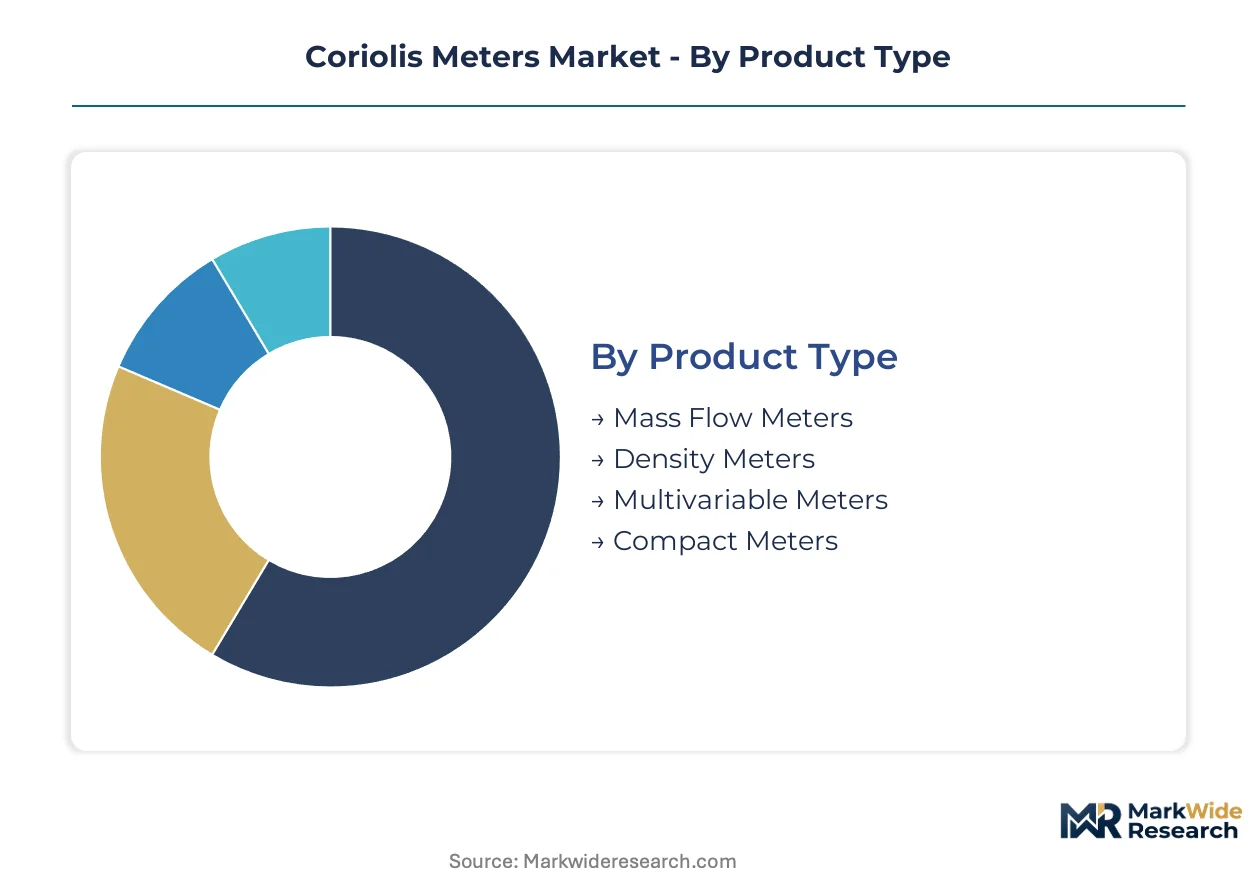
Coriolis meter segmentation reflects divergent procurement patterns between precision-critical custody transfer installations and cost-optimized process instrumentation. Buyers prioritize measurement certainty in hydrocarbon trading while seeking footprint consolidation in chemical synthesis and water treatment applications.
Product Type:
Standalone mass flow meters dominate high-value custody transfer installations, while embedded multivariable configurations penetrate process optimization networks where instrumentation consolidation drives purchasing decisions.
- Mass Flow Meters:These instruments measure mass flow rate directly through vibrating tube phase shift detection, eliminating temperature and density compensation requirements. Oil and gas custody transfer applications in the US Gulf Coast and North Sea basins concentrate demand as operators seek certified measurement certainty for hydrocarbon trading.
- Multivariable Meters:Devices integrating mass flow, density, temperature, and volumetric outputs within single transmitters reduce wiring and installation costs. German chemical processing clusters around Ludwigshafen and Leverkusen favor these configurations for reactor feed control and batch synthesis applications where panel space is constrained.
- Density Meters:Specialized units for concentration monitoring in beverage blending and pharmaceutical formulation.
- Compact Meters:Reduced-footprint designs for skid builders and OEM integration in mobile processing equipment.
Mass flow meters lead volumes today; multivariable meters are gaining share fastest.
End User:
Capital intensity and measurement risk exposure determine segment profitability, with hydrocarbon trading commanding premium pricing and water treatment operating at thinner margins.
- Oil & Gas:Exploration, production, pipeline, and LNG terminal operators require certified custody transfer accuracy for fiscal metering. EPA greenhouse gas reporting protocols mandate direct mass measurement, steering US operators toward Coriolis installations over inferred calculation methods.
- Chemical Processing:Batch reactor operations and continuous process plants demand hygienic designs with full material traceability. REACH substance restrictions and EU F-Gas Regulation compliance requirements shape supplier selection among European chemical manufacturers.
- Food & Beverage:Hygienic designs with 3A and EHEDG certifications for dairy, brewing, and ingredient dosing applications.
- Water Treatment:Municipal and industrial wastewater facilities deploying compact units for chemical feed control and sludge density monitoring.
Oil and gas commands the highest average selling prices; chemical processing shows the steepest expansion trajectory.
Technology:
Retrofit economics versus greenfield architecture preferences split procurement patterns across installation types.
- Digital:Microprocessor-based transmitters with digital signal processing enable advanced diagnostics and remote configuration. These units penetrate new installations across all end-use sectors as standard infrastructure.
- Wireless:Battery-powered WirelessHART transmitters eliminate trenching and cable routing costs in brownfield expansions. Offshore platform upgrades and remote pipeline metering stations favor these configurations where cabling dominates project economics.
- Analog:4-20 mA output devices persist in legacy system integrations and cost-sensitive applications.
- Remote Monitoring:Cloud-connected architectures enabling centralized asset management across distributed facilities.
Digital technology anchors current installed base; wireless configurations are climbing the fastest.
Application:
Regulatory enforcement intensity and commercial risk exposure create tiered demand patterns across use cases.
- Custody Transfer:Fiscal metering for hydrocarbon trading, LNG loading, and refined product pipeline handoffs demands certified accuracy classes and traceable calibration chains. SAMR metrological approval requirements in China create compliance barriers that filter supplier participation in this high-value segment.
- Process Monitoring:Real-time mass flow and density feedback for reactor control, blending optimization, and yield management. Chemical and pharmaceutical manufacturers deploy these installations for continuous process verification rather than batch record documentation.
- Bulk Measurement:Inventory management and loading rack applications where precision requirements are moderate.
- Quality Control:Laboratory and at-line testing for product release and specification verification.
Custody transfer generates the highest margins; process monitoring shows the strongest volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor around Ludwigshafen and Leverkusen concentrates multivariable meter demand from chemical processing clusters. The United States, China, India, and Saudi Arabia anchor regional expansion trajectories through divergent regulatory and investment cycles.
United States
Gulf Coast refineries and Permian Basin production operators drive custody transfer installations for hydrocarbon trading. EPA greenhouse gas reporting protocols mandate direct mass measurement, eliminating inferred calculation methods from compliance pathways. Houston anchors service unbundling trends as large operators negotiate multi-site framework agreements with independent metrology providers.
Germany
Chemical manufacturers around Ludwigshafen deploy hygienic multivariable meters for batch synthesis and reactor feed control. REACH substance restrictions and EU F-Gas Regulation compliance requirements shape supplier selection priorities. The industrial corridor concentrates demand for full material disclosure and substitution documentation to preempt regulatory gaps.
China
Petrochemical expansions along the western coast and Yangtze River Delta absorb compact meter volumes for process optimization. SAMR metrological approval standards create extended certification timelines that filter foreign supplier participation in custody transfer segments. State-owned refineries prioritize local testing protocols for fiscal metering installations.
India
Production-linked incentives for process instrumentation manufacturing attract local assembly investments to serve petrochemical capacity additions. Reliance Industries and Indian Oil Corporation drive demand for certified custody transfer accuracy in Gujarat and Maharashtra refining complexes. Western coast industrial zones concentrate brownfield retrofit opportunities where wireless configurations eliminate cabling costs.
Saudi Arabia
Aramco and SABIC expansion programs in the Eastern Province anchor high-precision meter procurement for LNG and chemical export facilities. Local content requirements under Vision 2030 steer joint venture structures for manufacturing localization. Jubail Industrial City concentrates demand for corrosion-resistant titanium constructions in sour gas processing applications.
Coriolis Meters Market Vendor Landscape
Strategic partnerships dominate the current landscape as producers secure captive titanium supply chains and in-house tube fabrication capabilities. The vendor base stratifies across three tiers: integrated multinationals with metallurgy partnerships, specialized hygienic design houses, and regional assembly operations serving price-sensitive process industries. Archetypes include full-stack solution providers, component specialists, and local certification navigators. M&A activity and capacity expansion in titanium tube fabrication represent the dominant competitive vectors.
Within the integrated multinational tier, Emerson Electric Co. and Endress+Hauser AG exemplify archetypes built on captive supply chain control and European manufacturing anchoring respectively. KROHNE Messtechnik GmbH occupies a position among specialized design houses targeting hygienic applications. These three entities represent distinct strategic postures: backward integration into metallurgy, in-house fabrication depth, and application-specific engineering focus.
| Leading Market Players |
|---|
| Emerson Electric |
| Endress+Hauser |
| KROHNE Messtechnik |
| Siemens |
| Yokogawa Electric |
| ABB |
| Baker Hughes |
| Bronkhorst High-Tech |
| Rheonik |
| Others |
Supply Flow & Price Mechanics
Titanium tube fabrication advances simultaneously compress production costs and concentrate supply leverage among qualified metallurgical partners, forcing meter producers to secure captive sourcing or absorb volatile sponge pricing. This metallurgical transition reshapes procurement economics as corrosion-resistant specifications displace stainless steel in sour gas and acidic process applications.
Pricing Analysis
Input-cost pass-through from titanium sponge and mill products dominates pricing dynamics, with three-tier pricing structure across premium, standard, and economy levels reflecting certification grade and volume scale differentiation. Price differentiation hinges on OIML R117 custody transfer certification and ATEX hazardous zone approval tiers. Pricing pressure stems from ultrasonic meter substitution in non-critical water applications. Water treatment operators exhibit highest price sensitivity; LNG terminal operators show lowest.
Supply Chain Analysis
Freight cost escalation from Asia-Pacific titanium sponge sources amplifies landed cost volatility for European and North American fabricators. Supply concentrates in China, Russia, and Japan for titanium sponge; Germany and Switzerland for precision tube forming. Raw material dependencies encompass titanium sponge, nickel alloys, and specialized elastomer seals. Single-source vulnerability pervades qualified mill product supply. Distribution runs through OEM direct sales for custody transfer segments and specialized instrumentation distributors for process applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EPA greenhouse gas protocols and EU F-Gas restrictions force end-users toward premium-certified instrumentation with full material traceability.
For Market Incumbents: To counter ultrasonic meter encroachment in water treatment, deepen titanium supply partnerships in Russia and Japan while expanding WirelessHART retrofit service capabilities. Prioritize SAMR certification navigation to defend custody transfer positioning in China. Anchor backward integration into tube fabrication to capture margin from metallurgical value-add. For New Entrants and Emerging Players: Begin with India's PLI-attracted assembly investments serving Reliance and Indian Oil western coast expansions, where wireless configurations address brownfield cabling constraints. Target chemical processing clusters around Ludwigshafen for multivariable meter white space. Pursue independent metrology service contracts to bypass entrenched OEM maintenance structures. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized hygienic design houses lacking titanium supply captivity but possessing EHEDG certification depth. Long-term viability favors producers with dual-curved tube geometry patents and edge analytics integration. Monitor EPA enforcement intensity on greenhouse gas reporting as inflection signal for custody transfer upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Titanium Supply Agreement | Secures sponge and mill product access against Russian supply disruption risks. |
| WirelessHART Retrofit Channel Expansion | Captures brownfield offshore platform and pipeline metering upgrade demand. |
| SAMR Certification Infrastructure Investment | Enables custody transfer participation in China state-owned refinery procurement. |
| Edge Analytics Platform Development | Shifts revenue model from hardware sales toward predictive maintenance contracts. |
| Dual-Curved Tube Geometry Patent Portfolio | Differentiates compact form factor offerings for FPSO and subsea applications. |
Methodological Framework
Direct dialogue with plant engineers at Gulf Coast refineries, metrology technicians at North Sea LNG terminals, procurement leads at German chemical manufacturers, and aftermarket service heads at instrumentation distributors grounded qualitative insights. Secondary validation drew from EPA enforcement databases, SAMR approval registries, EU F-Gas implementation reports, and customs trade data for titanium mill products. Bottom-up and top-down triangulation cross-checked segment-level demand against macro industrial production indices.
Bottom-up modeling aggregated individual facility procurement patterns across custody transfer, process monitoring, and quality control applications. Segmentation dimensions encompassed product type, end-use industry, technology configuration, and regional regulatory cluster. CAGRs derived from weighted average of historical replacement cycles and projected capacity additions. Industry-specific inputs incorporated EPA protocol enforcement timelines and REACH substance restriction phase-out schedules.
Several conditions sit outside the modeled scope, including abrupt titanium supply disruptions from geopolitical events, rapid ultrasonic meter accuracy breakthroughs, and unanticipated SAMR regulatory liberalization. Forecasts reflect assumptions about continued EPA greenhouse gas reporting stringency and sustained EU chemical sector investment levels. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Light Meter Market
Others
Grna Market
Others
Aircraft Exterior Lighting Market
Others
Balsa Wood Market
Others
North America 3D Printing Construction Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Cloud-Based Streaming Services Market
Others
Advertising Intelligence Solution Market
Others
Manometers Market
Others
Billet Market
Others
Bio-Imaging Technologies Market
Others
Global Sportswear Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
Asia-Pacific Camping and Caravanning Market
Others
China Smart Home Market
Others
Trusted Platform Module (TPM) Market