
 Delumper Market | 2026-2036
Delumper Market Size, Share, and Industry Trends Forecast 2026-2036
Delumper Market Outlook
The EPA National Emission Standards for Hazardous Air Pollutants is repositioning capital equipment priorities across bulk solids processing. Franklin Miller Inc. dominates the inline delumper category through captive supply of precision-cut rotors and screens. Stedman Machine Company anchors the heavy-duty segment with in-house production of abrasion-resistant alloy housings. Prater Industries specializes in sanitary designs that navigate FDA dairy and meat processing inspections.
A delumper is a size-reduction machine that employs closely spaced crushing rolls or rotors with intermeshing teeth to fracture agglomerated materials into uniform free-flowing particles, typically achieving outputs from 1/4 inch down to 20 mesh depending on screen configuration. Its primary industrial purpose centers on restoring flowability to caked or lumped bulk solids before they enter conveyors, mixers, or reactors. Inline delumper configurations lead the product type landscape because they integrate directly into pneumatic conveying lines without requiring separate feed hoppers or operator intervention. Batch delumpers occupy the premium tier in pharmaceuticals where isolated containment and validated cleanability command margin pools. Mechanical technology sustains the largest installed base, though electric drive systems are displacing pneumatic alternatives in food processing plants seeking energy recovery.
OSHA combustible dust standards and FDA Current Good Manufacturing Practice regulations jointly determine equipment specifications, material certifications, and documentation burdens for suppliers serving North American buyers. REACH chemical safety obligations in Europe restrict certain hardened steel alloys and surface coatings, pushing manufacturers toward certified alternative metallurgies. Stakeholders must monitor how evolving EPA per- and polyfluoroalkyl substances restrictions affect seal and gasket material choices across the installed base.
Market Dynamics
OSHA combustible dust enforcement and FDA food safety modernization are compressing equipment replacement cycles while forcing specification upgrades across chemical and food processing installations.
Growth Catalysts
- OSHA Process Safety Management:Chemical manufacturers face mandatory combustible dust hazard assessments that trigger delumper procurement for safe bulk solids handling.
- Energy recovery mandates:Food processors replace pneumatic drives with electric systems to capture regenerative braking energy and cut utility costs.
- Inline integration:Pneumatic conveying line retrofits favor delumpers that eliminate separate feed hoppers and manual operator intervention.
Market Restraints
- Abrasion-resistant alloy supply:REACH restrictions on certain hardened steel grades force costly metallurgy substitutions and extended qualification timelines.
- Precision rotor manufacturing concentration:Captive production of intermeshing tooth rotors limits supplier base and extends lead times for custom configurations.
- Batch containment cost structure:Pharmaceutical-grade isolated delumpers require validated cleanability features that price out mid-scale chemical processors.
Strategic Opportunities
- EPA PFAS transition:Seal and gasket material replacements across the installed base create aftermarket service and retrofit revenue streams.
- Modular sanitation architectures:Quick-disconnect components that satisfy USDA dairy inspections open meat and poultry processing segments.
- Remote condition monitoring:Vibration and temperature sensors bundled with predictive maintenance contracts displace traditional break-fix service models.
Industry Challenges
- Cross-functional qualification expertise:Engineers must simultaneously navigate FDA cGMP documentation, OSHA mechanical integrity standards, and EPA emission testing protocols.
- Legacy system integration:Retrofitting inline delumpers into existing pneumatic conveying networks requires custom transition pieces that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Delumper Market |
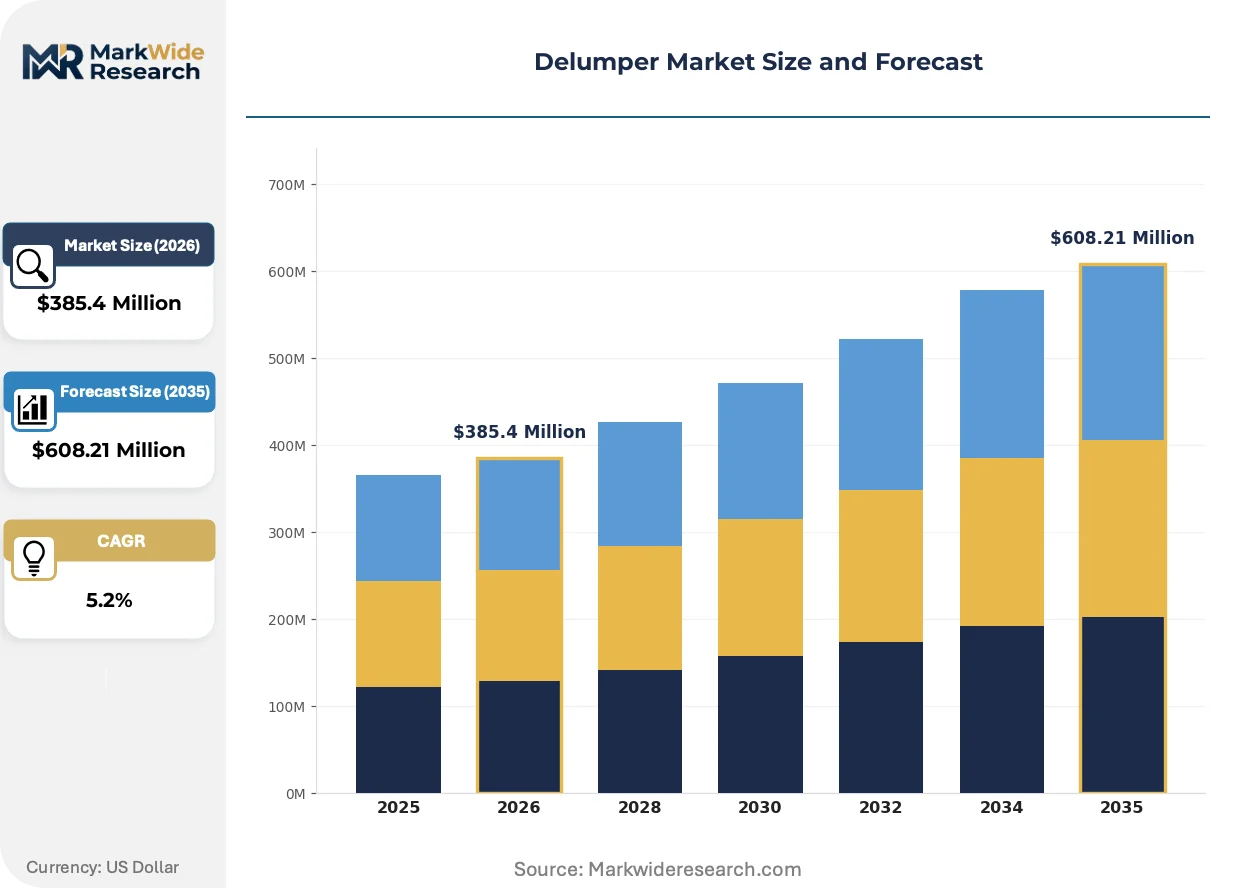
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Delumper, Batch Delumper, Pre-Breaker, Heavy-Duty Delumper Application: Food Processing, Chemical Manufacturing, Plastics Processing, Pharmaceuticals End User: Food & Beverage, Chemicals, Cosmetics, Healthcare Technology: Mechanical, Pneumatic, Hydraulic, Electric |
| Companies Covered | Stedman Machine Company, Schutte Hammermill, Franklin Miller Inc., Jersey Crusher, FLSmidth A/S, Prater Industries, Hosokawa Micron Corporation, Carrier Vibrating Equipment, Munson Machinery Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Delumper Market Strategic Shifts
Equipment architectures are fragmenting into configurable subsystems that let processors mix-and-match containment, drive, and discharge options without full custom engineering.
Sanitary delumper design is modularizing around tool-free disassembly protocols that cut cleaning validation time from hours to minutes. Dairy and meat processors in the Upper Midwest are specifying these configurations to pass USDA inspection cycles without production line shutdowns. The approach compresses supplier margins on standardized units while creating premium pools for validated documentation packages.
REACH chemical safety obligations are restricting certain surface coatings and hardened steel alloys across European installations. Manufacturers are shifting toward certified alternative metallurgies that satisfy ECHA substance restrictions without sacrificing abrasion resistance. This regulatory friction most impacts heavy-duty chemical processing applications where rotor longevity directly determines maintenance intervals.
Buyer preference is pivoting toward lifecycle cost contracts that bundle equipment, spare rotors, and predictive maintenance into fixed annual fees. Food processing cooperatives in California are leading this shift, displacing traditional capital purchase models with performance-guaranteed arrangements. Suppliers must restructure revenue recognition and inventory positioning to accommodate these extended obligation periods.
Delumper Market Segmentation
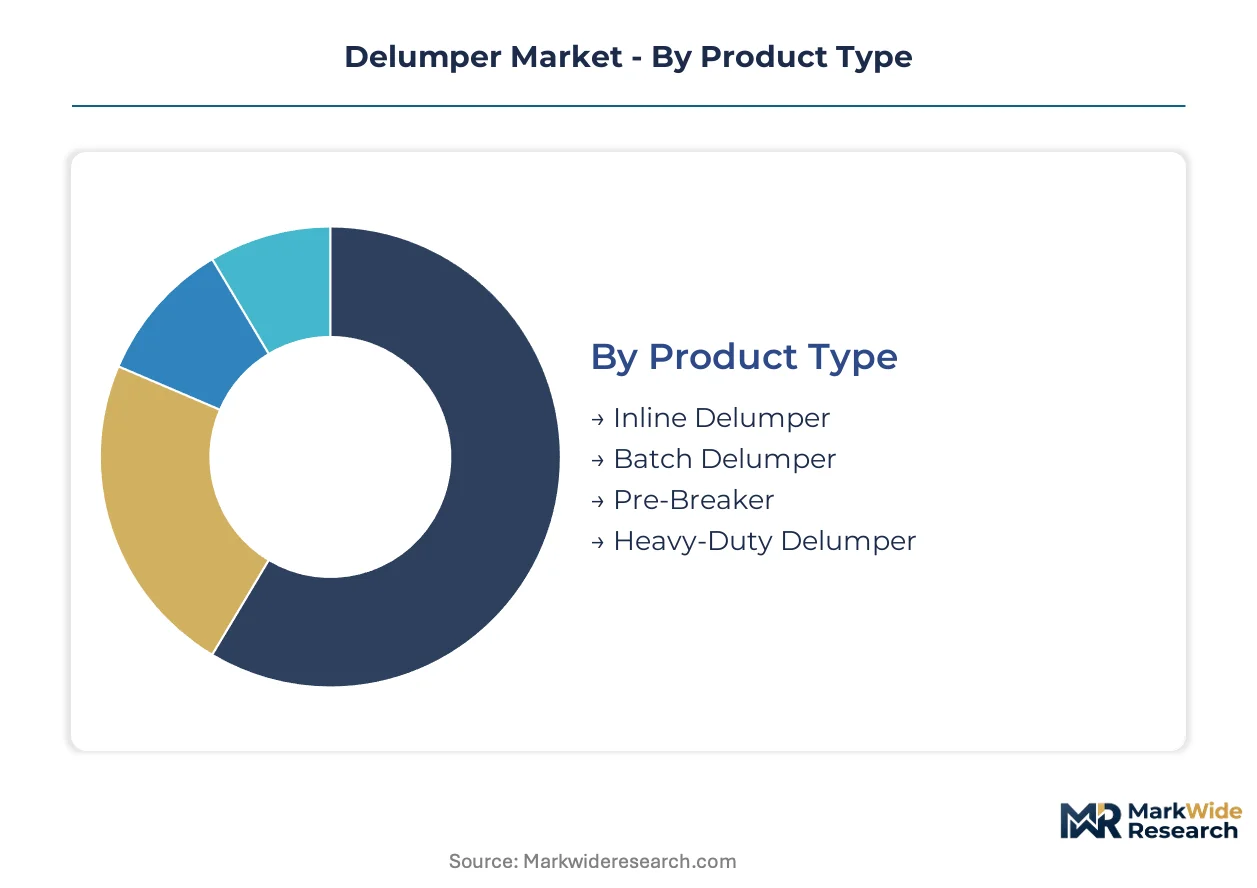
Delumper procurement decisions hinge on integration architecture, regulatory exposure, and energy infrastructure. Buyers segment equipment choices by how materials enter the process, what contaminants threaten compliance, and which power systems align with plant utility strategies.
Product Type:
Buyers differentiate by installation geometry and throughput continuity—inline systems favor uninterrupted pneumatic lines while batch units serve contained pharmaceutical suites.
- Inline Delumper:These units mount directly into pneumatic conveying circuits, eliminating feed hoppers and manual intervention. Demand concentrates among chemical manufacturers retrofitting bulk solids handling systems to meet OSHA combustible dust requirements in Texas and Louisiana Gulf Coast facilities.
- Batch Delumper:Isolated containment designs serve pharmaceutical manufacturers requiring validated cleanability between product changeovers. FDA Current Good Manufacturing Practice documentation burdens compress margins while creating premium pools for suppliers delivering complete validation packages.
- Pre-Breaker:Coarse initial size reduction handles severely agglomerated materials before secondary delumping.
- Heavy-Duty Delumper:Abrasion-resistant alloy housings process high-silica minerals and mining byproducts.
Volume sits with Inline Delumper configurations; growth tilts toward Batch Delumper as pharmaceutical containment requirements expand.
Application:
Regulatory intensity and material hazard profiles determine specification tiers across processing sectors.
- Food Processing:Sanitary designs with tool-free disassembly dominate dairy and meat operations facing USDA inspection cycles. Upper Midwest cooperatives specify modular architectures that compress cleaning validation from hours to minutes.
- Chemical Manufacturing:Combustible dust handling drives procurement as OSHA Process Safety Management mandates trigger hazard assessments. Facilities prioritize inline integration to minimize ignition sources in pneumatic transfer lines.
- Plastics Processing:Reclaim lines require consistent particle size to protect extruder feed screws.
- Pharmaceuticals:Isolated containment and documented cleanability command premium pricing for validated suites.
Food Processing carries the largest installed base; Chemical Manufacturing is climbing the fastest on regulatory enforcement.
End User:
Customer procurement sophistication ranges from cooperative purchasing consortia to centralized engineering standards at multinational chemical firms.
- Food & Beverage:California processing cooperatives pioneer lifecycle cost contracts bundling equipment, spare rotors, and predictive maintenance into fixed annual fees.
- Chemicals:Multinational firms enforce centralized mechanical integrity standards across North American sites.
- Cosmetics:Batch flexibility requirements favor quick-changeover sanitary designs.
- Healthcare:Pharmaceutical manufacturing subsidiaries impose documentation burdens matching parent-company FDA submission standards.
Food & Beverage generates the highest unit volumes; Chemicals delivers the steepest expansion trajectory on safety compliance investments.
Technology:
Energy recovery mandates and plant compressed-air capacity constrain drive system selection.
- Mechanical:Direct-coupled gearboxes and chain drives sustain the largest legacy installed base across chemical processing.
- Pneumatic:Explosion-proof operation suits combustible dust environments but faces displacement as energy costs rise.
- Hydraulic:High-torque applications in mining and minerals processing favor variable displacement pumps.
- Electric:Servo drives with regenerative braking capture recovered energy, displacing pneumatic alternatives in food plants seeking utility cost reductions.
Mechanical technology dominates current installations; Electric systems are gaining share fastest on sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the largest share of delumper capacity while Germany and Japan concentrate precision manufacturing. China and India represent emerging procurement centers as domestic chemical and food processing sectors expand.
United States
Chemical manufacturers along the Texas and Louisiana Gulf Coast are retrofitting bulk solids handling systems to satisfy OSHA Process Safety Management mandates for combustible dust containment. FDA food safety modernization rules compel dairy and meat processors in the Upper Midwest to specify sanitary delumper designs with tool-free disassembly. California food processing cooperatives are pioneering lifecycle cost contracts that bundle equipment, spare rotors, and predictive maintenance into fixed annual arrangements.
Germany
REACH chemical safety obligations enforced by ECHA are restricting certain hardened steel alloys and surface coatings across European chemical processing installations. Manufacturers are shifting toward certified alternative metallurgies that satisfy substance restrictions without sacrificing abrasion resistance. The Ruhr industrial corridor hosts heavy-duty equipment fabricators adapting rotor designs to comply with evolving material certification requirements.
Japan
Pharmaceutical manufacturers under PMDA oversight are driving demand for batch delumpers with validated cleanability documentation between product changeovers. METI energy efficiency guidelines are accelerating displacement of pneumatic drive systems with electric alternatives featuring regenerative braking. The Kansai region around Osaka contains specialized fabricators serving domestic pharmaceutical containment requirements.
China
Domestic chemical producers are expanding delumper procurement to meet GB standards for process safety and dust explosion prevention. MIIT industrial upgrading programs are encouraging adoption of electric drive systems over legacy pneumatic configurations. The Yangtze River Delta hosts bulk solids processing equipment manufacturers scaling production to serve both domestic and export markets.
India
FSSAI food safety regulations are tightening sanitary equipment requirements across dairy and spice processing operations. BIS certification mandates for industrial machinery are elevating specification standards for imported and domestically manufactured units. Gujarat and Maharashtra industrial corridors are attracting delumper suppliers establishing local assembly operations to serve South Asian chemical and food processing demand.
Delumper Market Competitive Environment
The competitive structure tilts toward specialized engineering fabricators with captive production of precision components. Equipment manufacturers cluster around three strategic archetypes: heavy-duty abrasion-resistant specialists serving mining and minerals, sanitary design experts navigating FDA and USDA compliance, and inline integration providers for pneumatic conveying retrofits. Dominant competitive moves include backward integration into precision rotor manufacturing and geographic expansion through regional assembly partnerships.
Among United States-based specialists, Franklin Miller Inc. exemplifies the inline integration archetype through captive supply of precision-cut rotors and screens. Stedman Machine Company anchors the heavy-duty segment with in-house production of abrasion-resistant alloy housings. Prater Industries occupies a position within the sanitary design tier, specializing in configurations that navigate FDA dairy and meat processing inspections.
| Leading Market Players |
|---|
| Stedman Machine Company |
| Schutte Hammermill |
| Franklin Miller Inc. |
| Jersey Crusher |
| FLSmidth A/S |
| Prater Industries |
| Hosokawa Micron Corporation |
| Carrier Vibrating Equipment |
| Munson Machinery Company |
| Others |
Value Chain & Pricing Dynamics
Precision rotor machinists in the Upper Midwest command wage premiums that compress margins on standard inline units while widening spreads between economy and certified pharmaceutical-grade systems. Labor-cost differentials between domestic fabrication and imported assemblies feed directly into three-tier pricing architectures across food processing and chemical applications.
Pricing Analysis
Margin tightening in economy-tier inline delumpers reflects REACH-driven metallurgy substitutions and extended alloy qualification timelines. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated batch containment from OSHA-compliant chemical handling from basic food-grade configurations. Pricing pressure stems from California cooperatives negotiating lifecycle cost contracts that bundle predictive maintenance. Chemical manufacturers show least price sensitivity due to mandatory combustible dust compliance investments.
Supply Chain Analysis
Single-source vulnerability sits with German specialty steel foundries supplying abrasion-resistant alloys for heavy-duty rotor housings. Precision-cut rotor manufacturing concentrates in the United States, Japan, and Germany. Raw material dependencies include nickel-hardened steel alloys, FDA-compliant elastomeric seals, and servo drive electronics. Supply chain risk centers on ECHA substance restrictions forcing metallurgy pivots. Distribution runs through OEM direct sales for large chemical processors and regional equipment distributors serving mid-scale food operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around fabricators with captive precision manufacturing capabilities as REACH compliance costs and documentation burdens force sub-scale suppliers toward exit.
For Market Incumbents: Cement rotor manufacturing dominance through backward integration into specialty alloy supply agreements with Ruhr corridor foundries. Expand validated documentation service offerings to capture pharmaceutical margin pools as FDA cGMP enforcement tightens. Defend against modular sanitation specialists by pre-empting quick-disconnect patent positions in dairy and meat processing segments. For New Entrants and Emerging Players: Begin with aftermarket seal and gasket retrofit services targeting EPA PFAS transition requirements across the installed base. Target India's Gujarat and Maharashtra corridors where BIS certification mandates elevate entry barriers for unqualified imports. Pursue joint venture assembly partnerships with domestic fabricators to bypass tariff exposure on precision components. For Investors and Strategic Acquirers: Re-rating potential sits with sanitary design specialists possessing validated FDA documentation packages given pharmaceutical containment requirement expansion. Five-to-ten year viability favors fabricators with electric drive integration capabilities serving energy recovery mandates. Watch California cooperative contract structures as the signal indicating mainstream adoption of performance-guaranteed procurement models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Captive metallurgy sourcing insulates against ECHA restriction volatility and secures rotor longevity guarantees. |
| Modular Sanitation Architecture Development | Tool-free disassembly protocols unlock USDA dairy inspection cycles without production line shutdowns. |
| Predictive Maintenance Service Bundling | Vibration sensor contracts displace break-fix models and lock in recurring revenue from California cooperatives. |
| Regional Assembly Partnership in India | Gujarat-based operations satisfy BIS certification requirements while serving South Asian chemical demand growth. |
| PFAS-Compliant Seal Material Transition | EPA-driven retrofit services capture aftermarket revenue from legacy installed base gasket replacements. |
Study Parameters
Document review covered SEC filings from disclosed equipment manufacturers, OSHA enforcement databases, FDA warning letter archives, and ECHA substance restriction registers, complemented by interviews with plant engineers at Gulf Coast chemical facilities, procurement leads at Upper Midwest dairy cooperatives, aftermarket service heads at regional distributors, and technical directors at precision fabrication shops. Secondary validation drew from customs trade data, ACC chemical industry reports, and USDA inspection cycle documentation. Bottom-up unit demand estimates triangulated against top-down capital expenditure projections across processing sectors.
Installed base and revenue outputs were generated through segmented modeling across product type, application, technology, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from regression analysis against historical compliance-driven replacement cycles and projected enforcement intensity. Industry-specific inputs included OSHA combustible dust inspection frequency trends and FDA dairy facility modernization grant allocations.
Underlying measurement precision varies by segment; inline chemical processing configurations carry tighter precision than emerging pharmaceutical containment categories due to established procurement reporting. Forecasts reflect documented assumptions about regulatory enforcement continuity and alloy substitution timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Postal Services Market
Others
Cloud Broadcasting Solutions Market
Others
Fiberglass Storage Tanks Market
Others
China Cloud Gaming Technology Market
Others
Global Hardware As a Service (Haas) Market
Others
Vegetable Carbon Market
Others
Workbench Tanks Market
Others
Enterprise Video Market
Others
Linseed Oil Market
Others
Europe Electric Forklift Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Video Encoder Market
Others
Advanced Fiber-Based Gasket Market
Others
India Home Automation Market
Others
Bitcoin Mining Hardware Market
Others
Wearable AI Market