
 LED Work Light Market | 2026-2036
LED Work Light Market Size, Share, and Industry Trends Forecast 2026-2036
LED Work Light Market Outlook
OSHA workplace illumination standards is realigning the cost-of-entry calculus for manufacturers serving North American industrial buyers. Eaton Corporation leverages its electrical infrastructure heritage to anchor premium hardwired installations across commercial facilities. Milwaukee Tool dominates the cordless segment with battery ecosystem lock-in that sustains replacement part revenue. Larson Electronics LLC specializes in hazardous-location certifications that differentiate its floodlight portfolio from general-purpose competitors.
An LED work light is a solid-state lighting fixture employing semiconductor diodes to produce directional illumination typically ranging from 500 to 10,000 lumens, engineered with aluminum heat sinks and polycarbonate lenses to withstand impact, moisture, and temperature cycling in demanding work environments. Its primary purpose is to deliver reliable, energy-efficient task lighting where permanent fixtures are impractical or where supplemental illumination reduces occupational hazards. Portable units lead the product type mix due to contractor mobility requirements, while solar-powered technology represents the fastest-growing segment as off-grid construction and emergency response budgets expand. The application landscape shows construction absorbing the dominant volume share, though emergency response commands margin premiums driven by NFPA certification requirements and rapid-deployment specifications.
The US Department of Energy enforces minimum efficacy thresholds through its Commercial and Industrial Lighting Equipment program, while the EU Ecodesign Directive and CE marking framework restrict market access for products failing electromagnetic compatibility and material safety tests. OSHA, EPA, and state-level building codes collectively shape product specifications by mandating color rendering indices and glare control in commercial environments. Buyers and suppliers must monitor battery chemistry regulations and right-to-repair legislation as these frameworks increasingly determine cordless product design cycles and aftermarket service obligations.
Market Dynamics
OSHA's workplace illumination standards are compressing replacement cycles as facility managers pre-emptively upgrade lighting fleets to avoid citation exposure. Semiconductor supply constraints for driver ICs and aluminum heat sinks are simultaneously forcing manufacturers to reconfigure sourcing strategies and redesign thermal management architectures.
Growth Catalysts
- Efficacy mandates:The US Department of Energy's Commercial and Industrial Lighting Equipment program mandates higher lumen-per-watt thresholds, compelling retrofit demand across aging commercial installations.
- Construction mobility:Contractor fleet expansion for portable illumination responds to stricter site safety enforcement and 24-hour shift scheduling in infrastructure projects.
- Emergency response budgets:NFPA-certified rapid-deployment specifications drive premium procurement for fire departments and disaster relief agencies.
Market Restraints
- Aluminum price volatility:Heat sink raw material costs fluctuate with energy-intensive smelting operations concentrated in China and Gulf states.
- Driver IC supply concentration:Taiwan and South Korea foundries control critical semiconductor capacity for LED power electronics.
- Right-to-repair friction:EU and US state-level legislation threatens sealed-unit designs that protect proprietary battery ecosystems.
Strategic Opportunities
- Off-grid construction:Solar-integrated work lights penetrate remote infrastructure sites lacking grid connectivity in Australia and Canada.
- Industrial IoT convergence:Embedded occupancy sensors and mesh networking create connected lighting nodes for smart facility management.
- Hazardous location certification:ATEX and IECEx compliance opens petrochemical, mining, and grain handling applications with severe service requirements.
Industry Challenges
- Optical engineering talent scarcity:Thermal simulation and photometric design expertise concentrates among senior specialists approaching retirement.
- Multi-certification timelines:Simultaneous UL, CE, and country-specific testing extends product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Work Light Market |
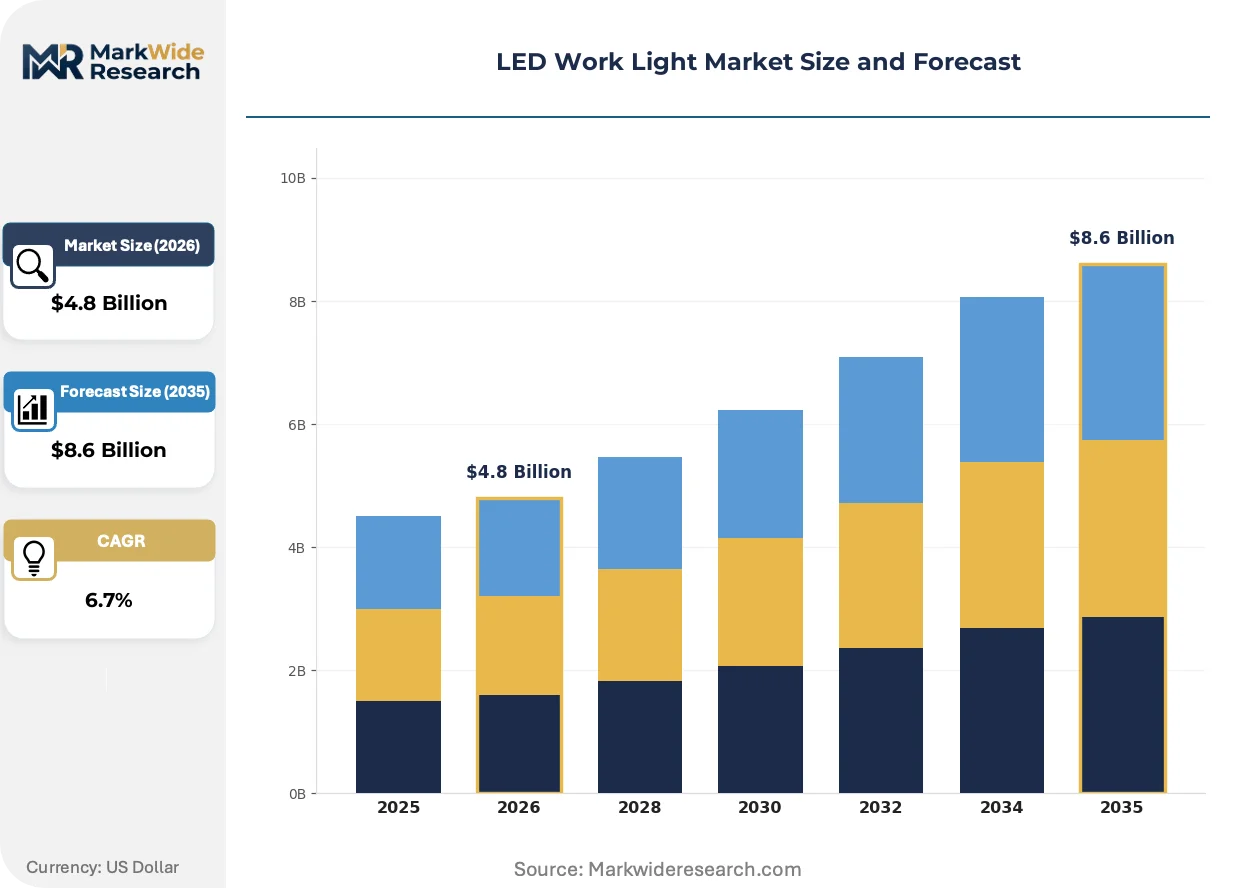
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Floodlight, Lantern, Magnetic Application: Construction, Emergency Response, Automotive Repair, Home Improvement Technology: Cordless, Solar-Powered, Rechargeable, Hardwired End User: Contractors, DIY Enthusiasts, Industrial Workers, Electricians |
| Companies Covered | Bayco Products Inc., Eaton Corporation, Streamlight Inc., Larson Electronics LLC, Ericson Manufacturing Company, Stanley Black and Decker Inc., Acuity Brands Lighting Inc., Hella GmbH & Co. KGaA, Milwaukee Tool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Work Light Market Strategic Shifts
Photovoltaic integration and solid-state battery chemistry are collapsing the boundary between portable lighting and autonomous power systems. These converging technologies enable deployment scenarios previously requiring generator support or grid tethering.
GaN (gallium nitride) power semiconductors are decentralizing driver electronics by enabling higher switching frequencies in smaller form factors. Industrial maintenance teams are adopting GaN-based floodlights for confined-space entry where thermal footprint constraints previously limited LED output. The technology is decentralizing the trade-off between lumen density and fixture size that has governed portable lighting design for two decades.
The EU Ecodesign Directive's 2023 amendments impose standby power limits and material disclosure requirements on commercial lighting equipment. Manufacturers serving European industrial buyers must now document rare earth content and circularity pathways. German automotive suppliers and Dutch logistics operators are accelerating compliance timelines to secure preferred vendor status with ESG-screening procurement departments.
Rental and subscription models are displacing capital purchase for contractor lighting fleets. Equipment rental chains in the US and Australia now stock connected work light inventories with usage-based billing. Construction superintendents prefer this arrangement for project-specific illumination without carrying residual asset risk between contracts.
LED Work Light Market Segmentation
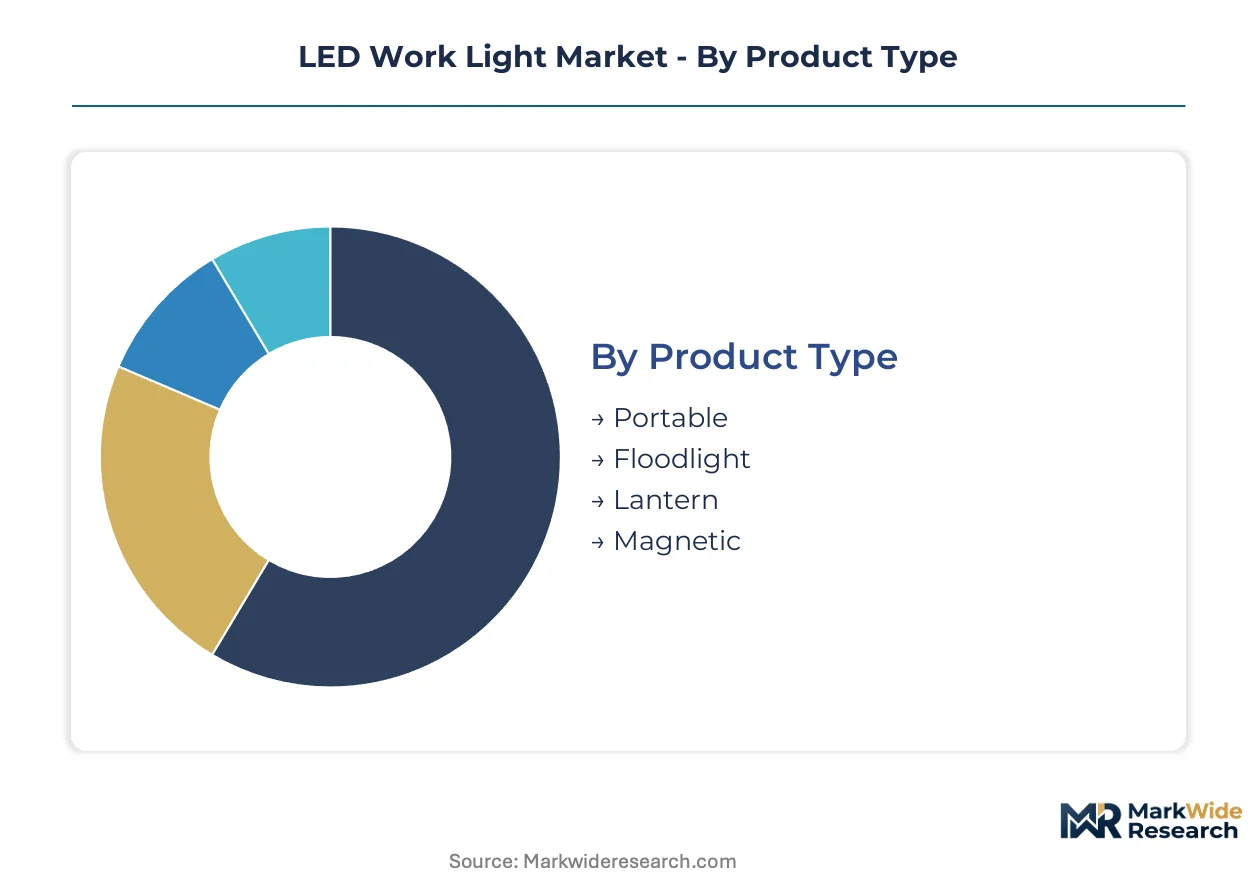
LED work light procurement decisions fragment across four distinct dimensions, each imposing unique certification burdens and supply chain requirements. Product type determines thermal management architecture and impact resistance specifications. Application context governs NFPA, OSHA, and ATEX compliance thresholds that filter vendor eligibility.
Product Type:
Certification intensity varies sharply across form factors, with hazardous-location ratings concentrating in fixed installations while portable units navigate battery transportation regulations.
- Portable:Battery-integrated units with aluminum heat sinks and polycarbonate housings dominate contractor fleet procurement. Construction superintendents in Germany and the United States are expanding portable inventories to meet stricter site illumination mandates and 24-hour shift scheduling.
- Floodlight:High-lumen stationary fixtures engineered for perimeter illumination and large-area coverage require UL or CE certification for commercial installation. Industrial facilities in Canada and Australia specify floodlights for mining and petrochemical applications where hazardous-location ratings command premium positioning.
- Lantern:Omnidirectional units with carrying handles and collapsible designs serve camping and emergency backup use cases. Consumer demand clusters in North American and European retail channels with seasonal purchasing patterns.
- Magnetic:Base-mounted units with rare-earth attachment systems target automotive repair and metal fabrication environments. Magnetic mounting eliminates tripod setup time in confined spaces.
Portable sits at the top of the volume ranking, with Solar-Powered climbing the fastest across all product categories.
Application:
End-use context determines margin structure, with emergency response and hazardous industrial environments supporting three-tier pricing stratification absent in consumer segments.
- Construction:Infrastructure contractors deploy portable and floodlight units across commercial building, roadwork, and utility projects. German industrial safety regulations enforcing minimum lux levels are accelerating replacement cycles for aging halogen fleets.
- Emergency Response:NFPA-certified rapid-deployment specifications for fire departments and disaster relief agencies drive premium procurement with specialized battery chemistry and ingress protection requirements. Margin premiums reflect certification timelines and liability exposure.
- Automotive Repair:Service bay illumination demands color rendering indices above 80 for paint matching and diagnostic accuracy. Magnetic-base portability supports under-vehicle task lighting.
- Home Improvement:DIY enthusiasts purchase through retail and e-commerce channels with price sensitivity shaping feature trade-offs between lumen output and battery runtime.
Construction absorbs the dominant volume share, though Emergency Response commands the steepest expansion trajectory in value terms.
Technology:
Power architecture determines supply chain exposure, with cordless designs dependent on semiconductor foundry capacity and solar-integrated units vulnerable to photovoltaic cell pricing.
- Cordless:Lithium-ion battery ecosystems with proprietary form factors create vendor lock-in and sustained aftermarket revenue. Milwaukee Tool and similar manufacturers leverage battery compatibility to defend replacement part margins.
- Solar-Powered:Photovoltaic-integrated units with solid-state battery storage collapse the boundary between lighting and autonomous power systems. Off-grid construction sites in remote regions of Australia and Canada are adopting solar work lights to eliminate generator fuel logistics.
- Rechargeable:AC-powered charging with cordless operation bridges grid-tethered and fully portable use cases. Facilities maintenance teams favor rechargeable units for predictable duty cycles.
- Hardwired:Permanent electrical installation with integrated drivers and thermal management anchors commercial facility retrofits. Eaton Corporation leverages electrical infrastructure heritage to capture premium hardwired specifications.
Cordless leads installed base volume, while Solar-Powered is gaining share fastest in remote infrastructure applications.
End User:
Professional versus amateur usage splits procurement channels, with trade contractors purchasing through industrial distributors and DIY segments flowing through retail.
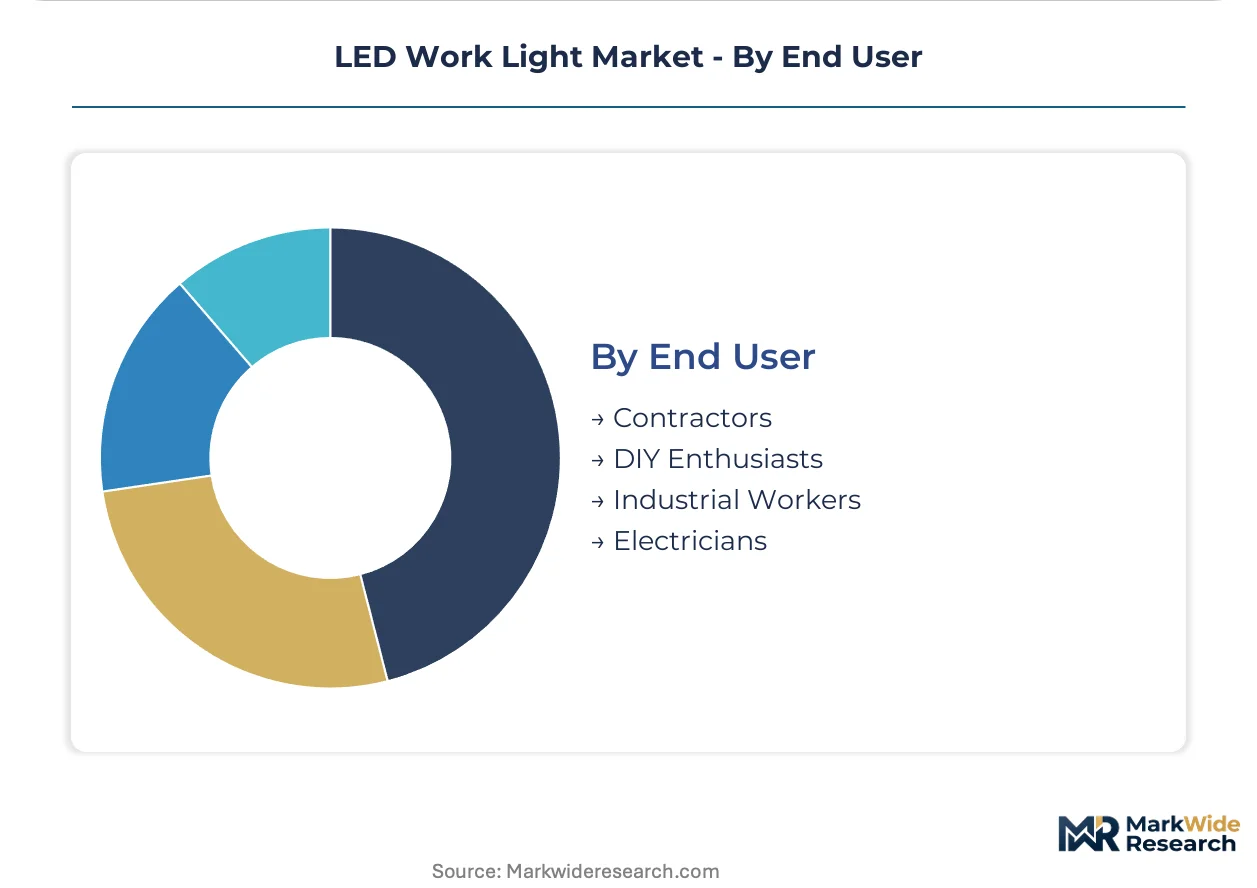
- Contractors:General and specialty construction firms operating under OSHA workplace illumination standards pre-emptively upgrade lighting fleets to avoid citation exposure. Rental models are displacing capital purchase for project-specific illumination.
- DIY Enthusiasts:Home improvement consumers prioritize portability and price accessibility over certification depth. E-commerce penetration concentrates this segment in North American and European markets.
- Industrial Workers:Manufacturing and logistics facility managers specify work lights for maintenance tasks and emergency backup. EU Ecodesign Directive standby power limits are reshaping procurement criteria.
- Electricians:Licensed electrical contractors require insulated housings and voltage-rated designs for energized circuit work. Professional-grade specifications filter vendor eligibility.
Contractors represent the largest addressable base, with Industrial Workers expanding most quickly as smart facility management converges with connected lighting nodes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
LED work light manufacturing originated in post-war German industrial zones before scaling through North American construction booms and Asia-Pacific electronics corridors. Distribution patterns now reflect these historical foundations while responding to localized safety mandates and energy transition policies.
United States
Infrastructure contractors are modernizing portable lighting fleets to satisfy OSHA workplace illumination standards and avoid citation exposure. The Department of Energy's Commercial and Industrial Lighting Equipment program mandates higher efficacy thresholds that accelerate commercial retrofit demand. Texas and Florida construction corridors drive volume procurement for 24-hour shift scheduling on energy and transportation projects.
Germany
Industrial safety regulations enforcing minimum lux levels across manufacturing floors compress replacement cycles for aging halogen systems. The EU Ecodesign Directive's standby power limits and material disclosure requirements reshape procurement criteria for automotive suppliers. Bavarian automotive clusters and North Rhine-Westphalia logistics hubs accelerate compliance timelines to secure ESG-screening preferred vendor status.
China
Domestic construction activity and export manufacturing capacity expansion sustain demand for aluminum heat sink components and driver IC assemblies. The country's national quality regulator enforces electromagnetic compatibility testing for commercial lighting equipment under GB standards. Yangtze River Delta electronics manufacturing clusters concentrate semiconductor packaging capacity for LED power electronics.
Canada
Remote infrastructure development and mining operations in Alberta and British Columbia drive adoption of solar-integrated work lights to eliminate generator fuel logistics. Health Canada regulates battery transportation and disposal for cordless equipment deployed in federal project zones. Prairie Provinces energy corridor contractors specify hazardous-location certifications for petrochemical site illumination.
Australia
Off-grid construction sites in Western Australia and Queensland adopt photovoltaic-integrated units where grid connectivity remains impractical. The national electrical safety regulator mandates compliance with AS/NZS standards for commercial lighting equipment. Mining operations in the Pilbara region command premium positioning for ATEX-certified floodlight installations.
LED Work Light Market Competitive Environment
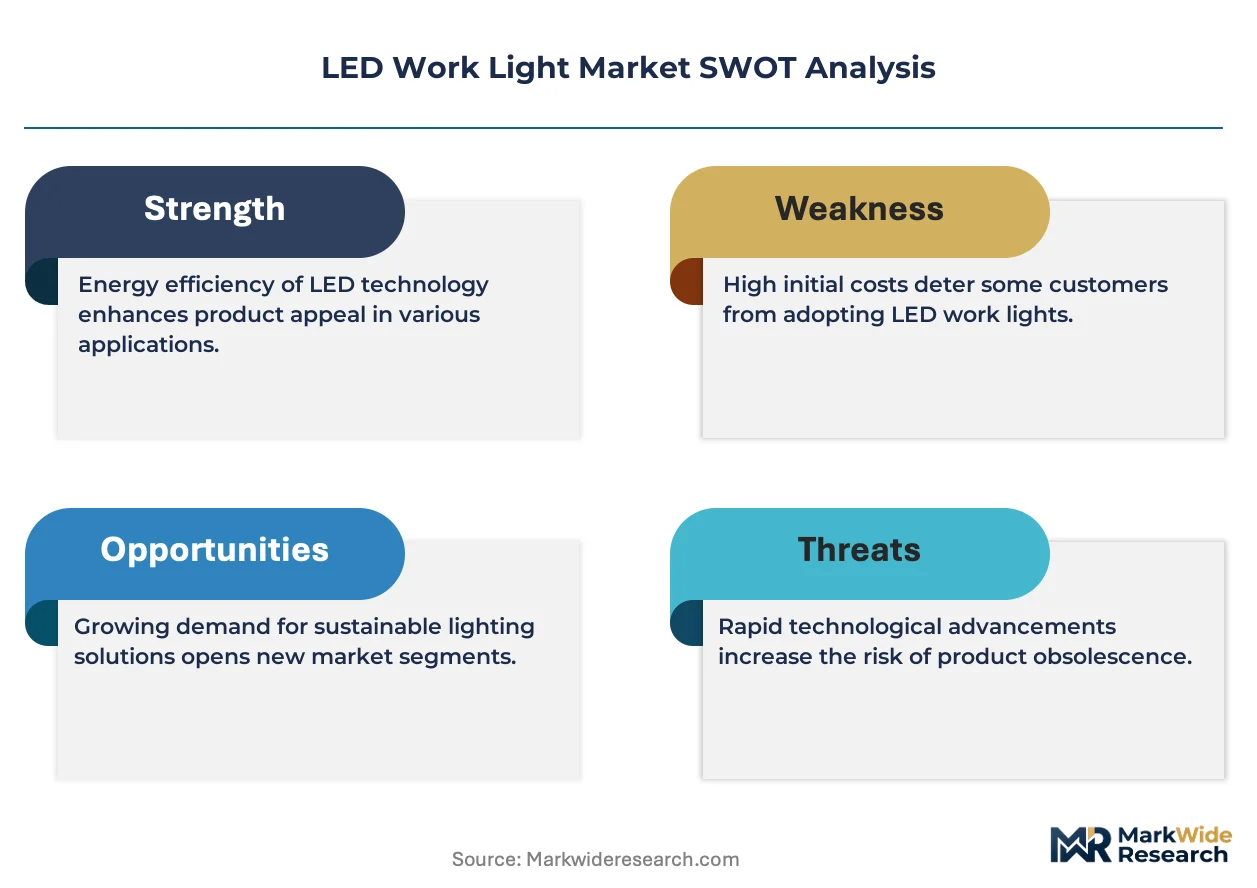
The competitive structure tilts toward diversified electrical equipment conglomerates with infrastructure heritage. Consolidation pressure concentrates among mid-scale specialists seeking thermal engineering and photometric design capabilities. Three archetypes dominate: battery ecosystem builders leveraging proprietary form factors, hazardous-location certification specialists capturing petrochemical premiums, and electrical infrastructure incumbents anchoring hardwired commercial retrofits. Geographic expansion and portfolio diversification represent the dominant competitive moves as manufacturers respond to multi-certification timelines extending launch windows.
Within the battery ecosystem tier, Milwaukee Tool exemplifies vendor lock-in strategies that sustain replacement part revenue through proprietary lithium-ion compatibility. Eaton Corporation occupies a position among electrical infrastructure conglomerates leveraging hardwired installation heritage for commercial facility specifications. Larson Electronics LLC represents the hazardous-location certification specialist archetype, with its portfolio differentiated by ATEX and IECEx compliance for severe service environments. These three anchors illustrate how competitive positioning fragments across cordless mobility, permanent installation, and explosion-proof specialization vectors.
| Leading Market Players |
|---|
| Bayco Products Inc. |
| Eaton Corporation |
| Streamlight Inc. |
| Larson Electronics LLC |
| Ericson Manufacturing Company |
| Stanley Black and Decker Inc. |
| Acuity Brands Lighting Inc. |
| Hella GmbH & Co. KGaA |
| Milwaukee Tool |
| Others |
Value Chain & Pricing Dynamics
GaN power semiconductor adoption is collapsing thermal management costs while simultaneously redistributing manufacturing leverage toward foundries with compound semiconductor expertise. This technology shift compresses bill-of-materials for high-lumen portable units and intensifies supplier concentration in Taiwan and South Korea driver IC corridors.
Pricing Analysis
Bundled battery ecosystem sales versus unbundled bare-tool procurement splits pricing architecture across contractor segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and after-sales service bundling. Price differentiation rests on OSHA compliance tier and proprietary battery compatibility. Cost compression in economy cordless tiers is intensifying because aluminum heat sink spot markets remain volatile. DIY enthusiasts exhibit highest price sensitivity, while emergency response agencies accept premium positioning for NFPA-certified rapid-deployment specifications.
Supply Chain Analysis
Certification timelines for UL, CE, and ATEX compliance gate supplier eligibility and extend product launch windows by 8-14 months. Manufacturing concentrates in China for aluminum heat sink fabrication, Taiwan for driver IC foundry capacity, and Germany for precision optical component finishing. Raw material dependencies span aluminum smelter output, lithium-ion cell chemistry, and rare-earth magnetic materials. Single-source vulnerability in Taiwan semiconductor packaging creates chokepoint exposure. Distribution runs through industrial equipment rental chains and electrical distributor networks serving contractor procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Demand is concentrating toward premium specifications as German automotive suppliers and Dutch logistics operators accelerate EU Ecodesign Directive compliance timelines.
For Market Incumbents: Hedge aluminum price exposure through long-term smelter offtake agreements or backward integration into heat sink extrusion capacity. Defend cordless market position by deepening proprietary battery ecosystem lock-in before right-to-repair legislation fragments aftermarket revenue. Certification investment in ATEX and IECEx hazardous-location ratings protects margin structure against commodity cordless competitors.
For New Entrants and Emerging Players: Solar-integrated work lights for off-grid construction in Western Australia and Alberta represent an underserved buyer archetype with weak incumbent presence. Penetrate remote mining and infrastructure corridors where generator fuel logistics burden creates willingness-to-pay for autonomous power systems. Pursue direct rental fleet partnerships rather than retail channel builds to bypass Milwaukee Tool and Stanley Black and Decker battery ecosystem dominance.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale hazardous-location specialists with ATEX certification depth but limited geographic footprint. Long-term viability favors manufacturers with compound semiconductor partnerships and thermal engineering talent pipelines. Watch for inflection when EU Ecodesign Directive material disclosure requirements trigger consolidation among non-compliant component suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Integration | Photovoltaic-integrated units with solid-state storage collapse generator dependency for remote Australian and Canadian construction sites. |
| Hazardous Location Certification | ATEX and IECEx compliance opens petrochemical, mining, and grain handling applications with severe service margin premiums. |
| Industrial IoT Convergence | Embedded occupancy sensors and mesh networking create connected lighting nodes for smart facility management in German automotive plants. |
| Rental Model Expansion | Usage-based billing through equipment rental chains displaces capital purchase for US and Australian contractor lighting fleets. |
| GaN Power Semiconductor Adoption | Higher switching frequencies in smaller form factors enable confined-space floodlights previously limited by thermal footprint constraints. |
Study Parameters
Multiple input streams — primary interviews, trade data reconciliation, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Conversations with maintenance directors at German automotive suppliers, plant engineers in Alberta mining operations, electrical distributor procurement heads, and aftermarket service managers informed operational assumptions. Secondary validation drew from OSHA enforcement databases, EU Ecodesign Directive amendment texts, US Department of Energy efficacy threshold documentation, and customs records for aluminum heat sink trade flows. Bottom-up product-type demand modeling and top-down construction spending allocation were cross-checked for consistency.
Historical shipment patterns were cross-referenced against panel input from component suppliers and rental fleet operators to anchor growth trajectory assumptions. The analytical framework models demand across product type, application context, power architecture, and end-user professionalization level throughout the forecast period. CAGRs were derived from segment-level unit economics and replacement cycle compression factors. Forecast inputs include semiconductor foundry capacity expansion timelines, aluminum smelter energy cost trajectories, and regulatory compliance deadline clustering.
Inputs from OSHA enforcement records and EU regulatory filings were available through the study window; gaps in real-time contractor fleet inventory data introduce uncertainty bands around portable segment estimates. Forecasts reflect documented assumptions regarding efficacy mandate implementation pacing and battery chemistry substitution elasticities. A model refresh is warranted upon material change in Taiwan foundry capacity allocation or aluminum price volatility regime.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Light Bar Market
LED
North America Indoor LED Lighting Market
LED
Asia Pacific LED Lighting Market
LED
LED Encapsulation Market
LED
East Africa LED Lighting Market
LED
UK Indoor LED Lighting Market
LED
India LED Lighting Market
LED
China LED Market
LED
North America Outdoor LED Lighting Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
North America Micro-LED Display Market
LED
Gan Micro LED Market
LED
GCC LED Lighting Market
LED
LED Light Market
LED
Egypt LED Lighting Market
LED
LED Modules and Light Engines Market