
 North America Indoor LED Lighting Market | 2026-2036
North America Indoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Indoor LED Lighting Market Insights
Human-centric lighting with circadian-tunable spectra is tilting the technology stack away from static white-only systems toward dynamic, sensor-integrated platforms. Acuity Brands, Inc. leverages its Atrius IoT architecture to anchor intelligent building ecosystems across commercial portfolios. Signify Holding competes through Interact software layers that extend beyond illumination into space analytics and energy optimization. Current Lighting Solutions, LLC. specializes in horticultural and industrial LED subsystems, occupying niche verticals where spectral precision commands premium positioning.
North America Indoor LED Lighting encompasses solid-state luminaires employing gallium nitride emitters, phosphor-converted white architectures, and secondary optics engineered for luminous efficacy exceeding 130 lumens per watt in commercial-grade products; these systems replace legacy fluorescent and HID sources across enclosed environments where color rendering, flicker metrics, and controllability determine specification outcomes. Downlights and troffers dominate retrofit volumes in aging commercial stock, while smart lighting with embedded occupancy sensing captures margin pools through recurring software and service attach rates. Panel lights lead specification in healthcare and educational verticals where uniform glare-free illumination aligns with WELL Building standards, and tunable white technology is accelerating fastest in hospitality and corporate wellness projects seeking circadian programmability.
The U.S. Department of Energy maintains federal test procedures and conservation standards under 10 CFR Part 430, while California's Title 24 and the Canadian Standards Association C22.2 No. 250.0 shape product certification barriers and efficacy floors that filter non-compliant imports from market participation. The U.S. Environmental Protection Agency ENERGY STAR program and DesignLights Consortium Qualified Products List further segment demand by creating preferred procurement channels for verified high-performance luminaires. Stakeholders must monitor divergence between federal efficiency rollbacks and state-level acceleration, as this regulatory fragmentation will determine which product portfolios retain access across the largest state markets.
Market Dynamics
The convergence of Title 24 efficacy mandates and circadian-tunable LED platforms is compressing specification cycles across commercial real estate portfolios. Facility managers now face simultaneous pressure to cut energy spend and meet WELL Building illumination standards.
Growth Catalysts
- California Title 24 Building Code:Tightened luminaire efficacy requirements in 2025 are forcing wholesale retrofit decisions in the state's aging office stock.
- Human-centric lighting:Circadian-tunable spectra are displacing static white systems in healthcare and corporate wellness projects.
- U.S. Northeast corridor:State-level energy mandates coincide with aging commercial building stock, concentrating demand velocity.
Market Restraints
- Gallium nitride substrate costs:Wafer price volatility constrains margin expansion for high-efficacy emitter manufacturers.
- Supply concentration in East Asia:Phosphor and driver component sourcing remains concentrated outside the region.
- Fluorescent asset stranding:Existing ballast infrastructure delays full LED conversion in budget-constrained municipal buildings.
Strategic Opportunities
- Canadian commercial retrofits:Ontario and Quebec lag U.S. penetration rates, offering whitespace for specification-grade products.
- Sensor-integrated platforms:Convergence of occupancy sensing with daylight harvesting opens recurring software revenue streams.
- Inflation Reduction Act incentives:Tax credits for energy-efficient building upgrades accelerate payback calculations for multi-site rollouts.
Industry Challenges
- Controls integration complexity:BACnet and DALI protocol fragmentation forces custom commissioning on every major project.
- DLC Premium certification timelines:Third-party verification delays are compressing construction schedules and penalty clauses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Indoor LED Lighting Market |
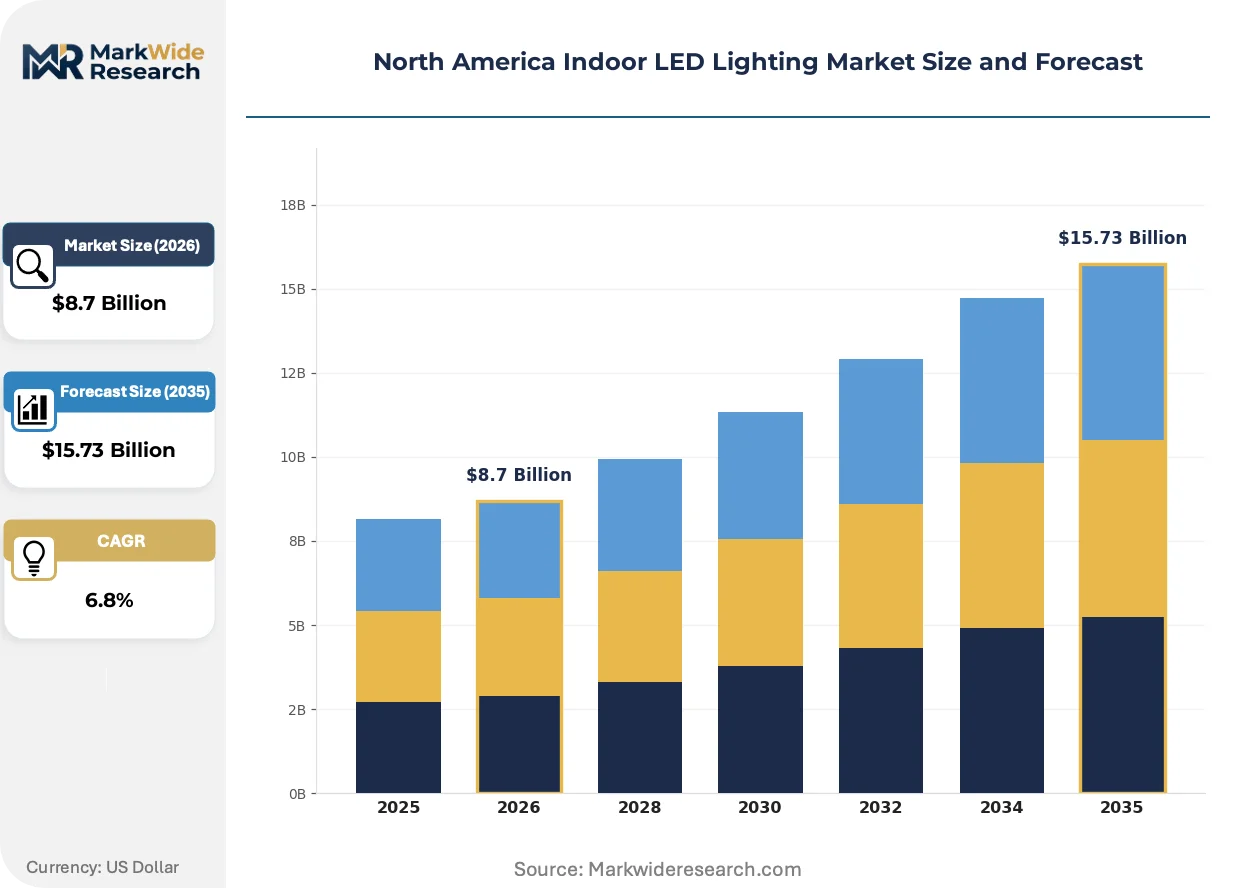
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Downlights, Troffers, Panel Lights, High-Bay Lights Technology: Smart Lighting, Dimming, RGB, Tunable White Application: Residential, Commercial, Hospitality, Educational End User: Homeowners, Facility Managers, Contractors, Architects |
| Companies Covered | Acuity Brands, Inc., Current Lighting Solutions, LLC., Signify Holding, Cree Lighting USA, LLC., Hubbell, LEDVANCE GmbH, Panasonic Holdings Corporation, Dialight, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Indoor LED Lighting Market Trends and Innovations
Specification logic is pivoting from lumen-per-watt metrics toward integrated building system outcomes. Buyers now evaluate luminaires as data infrastructure nodes rather than standalone commodities.
Power-over-Ethernet (PoE) lighting architecture is digitizing fixture-level energy monitoring and granular zone control. Corporate real estate teams in Class A office towers are adopting PoE at accelerated pace. The technology is digitizing how landlords bill tenants for lighting energy and enabling real-time space utilization analytics.
The U.S. Department of Energy's 10 CFR Part 430 conservation standards are tightening test procedure stringency for commercial luminaires. Manufacturers face expanded scope of covered products and shortened compliance windows. Downlight and troffer categories are absorbing the greatest certification burden as efficacy floors ratchet upward.
Performance contracting is displacing capital purchase models in municipal and university verticals. Energy Service Companies now specify and install LED systems, recovering costs through guaranteed savings shares. This shift is most visible in California and New York state facilities where budget constraints block upfront capital deployment.
North America Indoor LED Lighting Market Segmentation
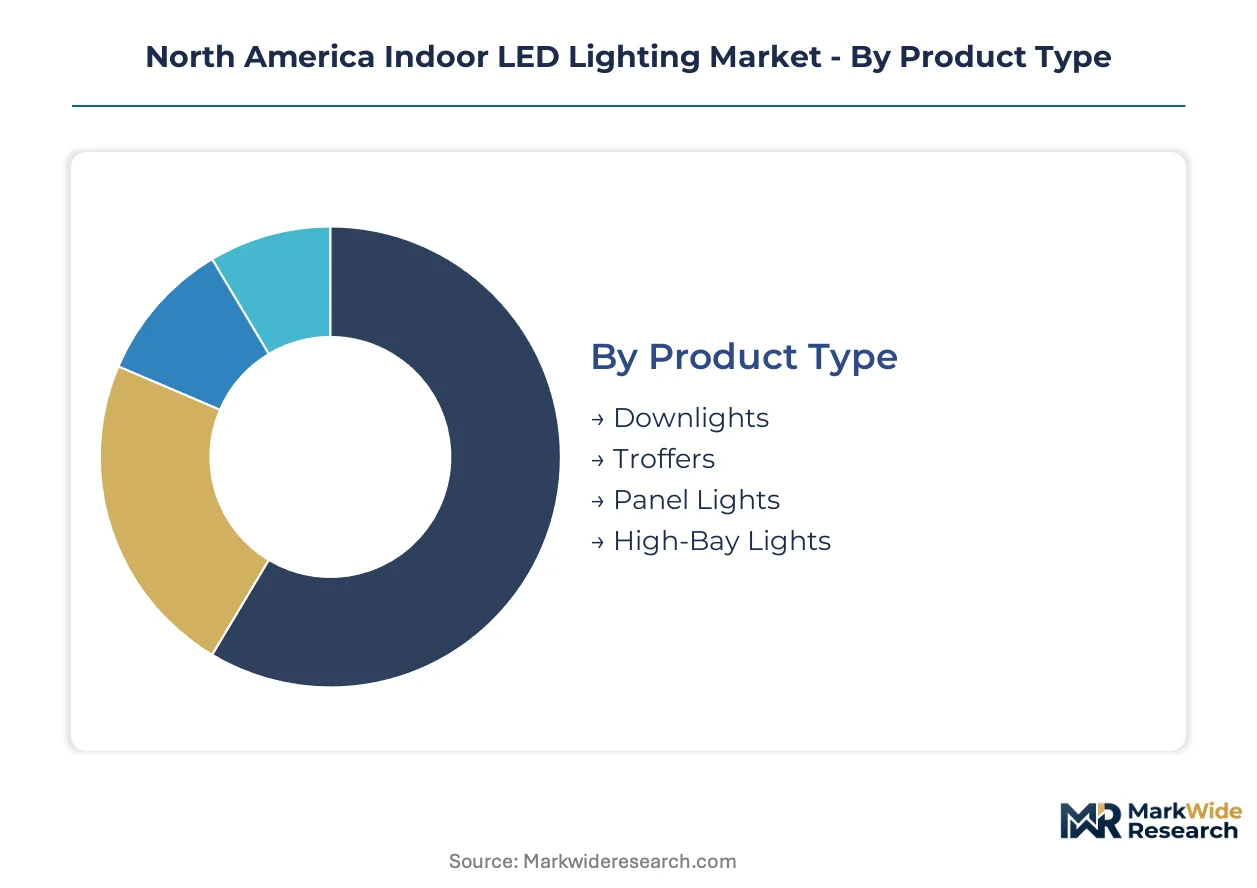
Segmentation in North America Indoor LED Lighting reveals how specification logic fragments across building codes, procurement channels, and performance tiers. Buyers prioritize different attributes depending on whether they answer to energy mandates, wellness standards, or first-cost constraints.
Product Type:
Mature retrofit hardware dominates volume, while emerging form factors capture specification premiums in new construction.
- Downlights:Recessed ceiling luminaires with integrated heat sinks and beam-angle optics. Facility managers in California office retrofits specify these under Title 24 efficacy mandates that disqualify older fluorescent can conversions.
- Troffers:Lay-in ceiling fixtures engineered for T-bar grid systems with 2x2 and 2x4 footprints. The U.S. Northeast corridor concentrates demand as aging commercial stock requires wholesale fluorescent replacement without structural modification.
- Panel Lights:Edge-lit or direct-lit flat panels delivering uniform surface brightness. Healthcare and education verticals specify these for WELL Building compliance.
- High-Bay Lights:Industrial-grade fixtures with high lumen packages for ceiling heights exceeding 20 feet. Warehouses and distribution centers in Ontario and Quebec drive specification.
Troffers handle the majority of throughput; Panel Lights are the fastest mover on share.
Technology:
Cost tier stratification separates commodity controls from integrated platforms commanding software attach rates.
- Smart Lighting:Networked luminaires with embedded sensors and API-accessible management layers. Corporate real estate teams in Class A towers adopt these for space utilization analytics and tenant billing granularity.
- Dimming:Phase-cut or 0-10V analog control for illuminance adjustment. Budget-constrained municipal buildings specify these as minimum viable upgrades.
- RGB:Multi-channel emitters enabling saturated color output. Hospitality venues in Las Vegas and Miami deploy these for ambient programming.
- Tunable White:Correlated color temperature adjustment across 2700K to 6500K ranges. Corporate wellness projects specify these for circadian programmability.
Dimming handles the majority of throughput; Tunable White is expanding most quickly.
Application:
Customer type determines whether procurement flows through capital budgets, operating leases, or performance contracts.
- Commercial:Office, retail, and institutional environments with professional facility management. Energy Service Companies target this vertical with guaranteed savings agreements.
- Residential:Single-family and multi-family dwelling units with homeowner or landlord procurement. Big-box retail channels dominate distribution.
- Hospitality:Hotels, restaurants, and entertainment venues prioritizing ambiance and brand expression. Design-build firms specify aesthetic-forward luminaires.
- Educational:K-12 and university facilities with deferred maintenance backlogs. State-level energy grants accelerate LED conversion in public districts.
Commercial handles the majority of throughput; Hospitality is gaining share fastest.
End User:
Volume concentration sits with repeat buyers, while specification influence concentrates with design professionals.
- Facility Managers:Corporate and institutional operators managing multi-site portfolios. These buyers standardize on DLC Premium products to secure utility rebate eligibility.
- Contractors:Electrical and general construction firms executing bid work. Procurement runs through distributor stocking programs with volume pricing tiers.
- Homeowners:Individual consumers purchasing through retail or e-commerce. Replacement cycles follow fixture failure rather than efficiency optimization.
- Architects:Design professionals specifying luminaires during schematic design. These stakeholders prioritize photometric performance and aesthetic integration.
Contractors handle the majority of throughput; Facility Managers are climbing the fastest on specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility managers across the United States and Canada dominate procurement volumes, with specification influence concentrating in the U.S. Northeast corridor and California where energy mandates intersect with aging building stock.
United States
California Title 24 building codes and federal IRA tax credits accelerate commercial retrofit decisions. The U.S. Department of Energy's 10 CFR Part 430 conservation standards tighten efficacy floors for downlights and troffers. The Northeast corridor from Boston to Washington D.C. concentrates specification-grade demand as state-level mandates outpace federal requirements.
Canada
Ontario and Quebec lag U.S. LED penetration rates, creating whitespace for specification-grade products in industrial and commercial verticals. The Canadian Standards Association C22.2 No. 250.0 shapes product certification barriers that filter non-compliant imports. Toronto and Montreal anchor demand concentration as facility managers pursue energy cost reductions in aging office stock.
Mexico
Nuevo León and the Bajío Region drive industrial LED demand from automotive and electronics manufacturing facilities. Mexico's national energy efficiency standards create compliance obligations for multinational facility operators. Monterrey concentrates specification activity as industrial parks modernize lighting infrastructure to meet corporate sustainability targets.
North America Indoor LED Lighting Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven manufacturers face pressure from niche specialists. The vendor base organizes around three strategic archetypes: diversified electrical conglomerates with broad distribution reach, pure-play lighting specialists with deep specification relationships, and component-integrated platforms with captive LED emitter supply. Dominant competitive moves include portfolio diversification into sensor-integrated smart systems and strategic partnerships with energy service companies to capture performance contracting flows.
Within the diversified conglomerate tier, Acuity Brands, Inc. and Eaton exemplify channel-controlling players with specification influence across commercial portfolios. Signify Holding occupies a position as a technology-integrated specialist with software-layer differentiation. Current Lighting Solutions, LLC. represents the niche vertical specialist archetype, focusing on industrial and horticultural subsystems where spectral precision commands premium positioning.
| Leading Market Players |
|---|
| Acuity Brands, Inc. |
| Current Lighting Solutions, LLC. |
| Signify Holding |
| Cree Lighting USA, LLC. |
| Hubbell |
| LEDVANCE GmbH |
| Panasonic Holdings Corporation |
| Dialight |
| Eaton |
| Others |
Pricing and Supply Chain Analysis
Dongguan's LED packaging cluster dictates downstream pricing power through gallium nitride wafer allocation and phosphor-converted white emitter availability. U.S. and Canadian luminaire manufacturers face margin compression when substrate costs spike, while buyers in the Northeast corridor absorb premium pricing for DLC Premium-certified products.
Pricing Analysis
Cost-plus contracts with gallium nitride wafer indexation dominate procurement between emitter suppliers and luminaire OEMs. Three-tier pricing structure across premium, standard, and economy levels separates DLC Premium-certified fixtures from Title 24 baseline products and import alternatives. Pricing pressure stems from Title 24 efficacy mandates forcing R&D pass-through. Municipal buyers exhibit highest price sensitivity; corporate real estate teams in Class A towers show lowest.
Supply Chain Analysis
Supplier-financing facilities extending 90-120 day payment terms anchor working capital structures for Taiwanese and Chinese substrate vendors. GaN-on-silicon and sapphire substrates draw from Taiwan, China, and South Korea. Phosphor materials, LED drivers, and thermal management components rest on East Asian sourcing. Single-source vulnerability concentrates in advanced MOCVD reactor capacity. Distribution runs through electrical distributor stocking programs with volume pricing tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Indoor LED Lighting Market sits in early-cycle expansion as human-centric lighting penetration in healthcare and corporate wellness projects accelerates specification upgrades beyond basic retrofit economics.
For Market Incumbents: Build switching-cost moats through Atrius-style IoT platform entrenchment across multi-site commercial portfolios. Deepen captive supply of gallium nitride emitters to buffer wafer price volatility. Expand DLC Premium certification pipelines to secure utility rebate channel control against emerging sensor-integrated competitors. For New Entrants and Emerging Players: Pursue Canadian commercial whitespace in Ontario and Quebec where LED penetration lags U.S. benchmarks. Target industrial high-bay segments in Monterrey's automotive manufacturing corridor. Lead with PoE-enabled space analytics to differentiate from legacy dimming-only competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-integrated platform providers with software attach rates. Long-term viability favors vendors controlling both emitter supply and controls integration capability. Watch for Title 24 efficacy mandate acceleration as inflection signal for specification-grade demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Platform Development | Acuity's Atrius and Signify's Interact demonstrate software-layer monetization beyond hardware. |
| DLC Premium Certification Investment | Qualification unlocks utility rebate channels across California and Northeast corridor markets. |
| GaN Substrate Backward Integration | Captive wafer supply insulates margins from East Asian price volatility in MOCVD capacity. |
| Energy Service Company Partnership | Performance contracting flows in municipal and university verticals bypass capital budget constraints. |
| PoE Architecture Deployment | Corporate real estate teams adopt fixture-level monitoring for tenant billing and space analytics. |
Research Methodology
Desk research of DOE appliance efficiency standards, DLC Qualified Products List databases, and California Energy Commission Title 24 documentation preceded structured interviews with commercial facility managers, electrical contractor procurement leads, and lighting designer specification professionals. Primary fieldwork across the U.S. Northeast corridor and California markets validated secondary trade flow and regulatory trajectory assumptions. Bottom-up luminaire shipment analysis triangulated against top-down energy efficiency mandate compliance modeling.
Assumptions held fixed include Title 24 efficacy floor trajectories and IRA tax credit continuity, while variables tested included gallium nitride wafer price scenarios and circadian-tunable adoption curves across healthcare and hospitality verticals. Segmentation modeling spanned product type, technology tier, application vertical, and end-user procurement channel. CAGRs derived from installed base turnover rates and new construction specification mix shifts. Forecast inputs incorporated WELL Building Standard penetration assumptions and PoE infrastructure deployment timelines.
Sensitivities concentrate around federal efficiency standard rollbacks, gallium nitride substrate supply disruptions, and DLC certification timeline extensions. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Superluminescent Diodes Market
LED
Global Outdoor LED Lighting Market
LED
Small Pitch LED Display Market
LED
Japan LED Market
LED
North America Commercial LED Lighting Market
LED
Asia Pacific LED Lighting Market
LED
Asia Pacific Indoor LED Lighting Market
LED
Saudi Arabia LED Lights Market
LED
LED Services Market
LED
Europe Outdoor LED Lighting Market
LED
Smart LED Indoor Signage Market
LED
France LED Lighting Market
LED
LED Lighting Controllers Market
LED
UV LED Market
LED
Philippines LED Market
LED
East Africa LED Lighting Market