
 Germany Rechargeable Battery Market | 2026-2036
Germany Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Rechargeable Battery Market Insights
Electrochemical engineering talent is bifurcating between legacy automotive hubs and emerging gigafactory corridors across eastern Germany. CATL leverages its Erfurt plant to anchor cathode-active-material supply for European OEM programs. Samsung SDI competes through solid-state R&D partnerships with German premium automakers. Volkswagen Group dominates vertical integration by controlling cell design, module assembly, and vehicle-platform deployment from its Salzgitter complex.
Germany rechargeable batteries are electrochemical storage devices designed for repeated charge-discharge cycling, typically employing lithium-ion chemistries with nickel-manganese-cobalt or lithium-iron-phosphate cathodes, graphite or silicon-blend anodes, and organic electrolyte formulations to deliver energy densities exceeding 250 Wh/kg for traction and stationary applications. Lithium-ion systems lead product type demand due to their superior specific energy and declining cost curve, while nickel-metal hydride retains niche presence in hybrid-electric vehicle buffering where thermal stability outweighs energy density requirements. High-capacity and ultra-high-capacity segments attract the fastest investment as German automakers specify battery packs exceeding 100 kWh for premium electric SUV and sedan platforms.
The EU Battery Regulation and CE marking framework mandate supply-chain due diligence, carbon footprint labeling, and minimum recycled lithium content thresholds that reshape product design and sourcing obligations for all suppliers operating in Germany. Germany's Federal Motor Transport Authority enforces type-approval standards for traction batteries that interface with UNECE safety protocols, creating compliance barriers for non-certified imports. Stakeholders must monitor how delegated acts under the EU Battery Regulation define performance and sustainability benchmarks before committing to long-term cathode chemistry and recycling infrastructure bets.
Market Dynamics
The EU Battery Regulation's carbon footprint declaration mandate is forcing German cell producers to reconfigure cathode supply chains and localize precursor chemical production ahead of phased compliance deadlines.
Growth Catalysts
- Automotive platform electrification:German OEMs are specifying 100+ kWh packs for premium SUV and sedan architectures, pulling demand for high-nickel cathode chemistries through dedicated offtake agreements.
- CE marking and type-approval harmonization:KBA enforcement of UNECE safety protocols for traction batteries creates predictable certification pathways that accelerate homologation timelines for qualified suppliers.
- Eastern Germany gigafactory corridor formation:Thuringia and Saxony-Anhalt are attracting cathode-active-material and cell manufacturing investments through streamlined permitting and grid infrastructure commitments.
Market Restraints
- Lithium hydroxide price volatility:Battery-grade lithium compound costs fluctuate with South American and Australian spodumene concentrate availability, compressing cell producer margins during supply tightness.
- Cathode precursor import dependency:German manufacturers rely on East Asian refined nickel and cobalt sulfate, exposing production schedules to maritime logistics bottlenecks and geopolitical trade friction.
- Solid-state electrolyte manufacturing scale-up:Sulfide-based ceramic electrolyte production requires dry-room environments below -40°C dew point, limiting viable production sites and extending qualification timelines.
Strategic Opportunities
- Second-life stationary storage:Retired automotive packs from Baden-Württemberg and Bavaria vehicle fleets are being repurposed for grid-buffering applications, creating circular revenue streams before recycling obligations activate.
- Recycled content mandate preparation:The EU Battery Regulation's minimum recycled lithium thresholds by 2031 incentivize investment in hydrometallurgical refining capacity within Germany's existing chemical industry clusters.
- Silicon-anode integration:Silicon-blend anodes are penetrating high-end German EV platforms, offering 20-40% energy density improvement over graphite-only architectures for premium segment differentiation.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and manufacturing process engineering expertise concentrates among legacy automotive suppliers and startup spinouts, lengthening recruitment cycles for new production facilities.
- UNECE R100 certification complexity:Thermal propagation testing and abuse-tolerance validation for novel cell formats require 18-24 month approval timelines, delaying platform launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Rechargeable Battery Market |
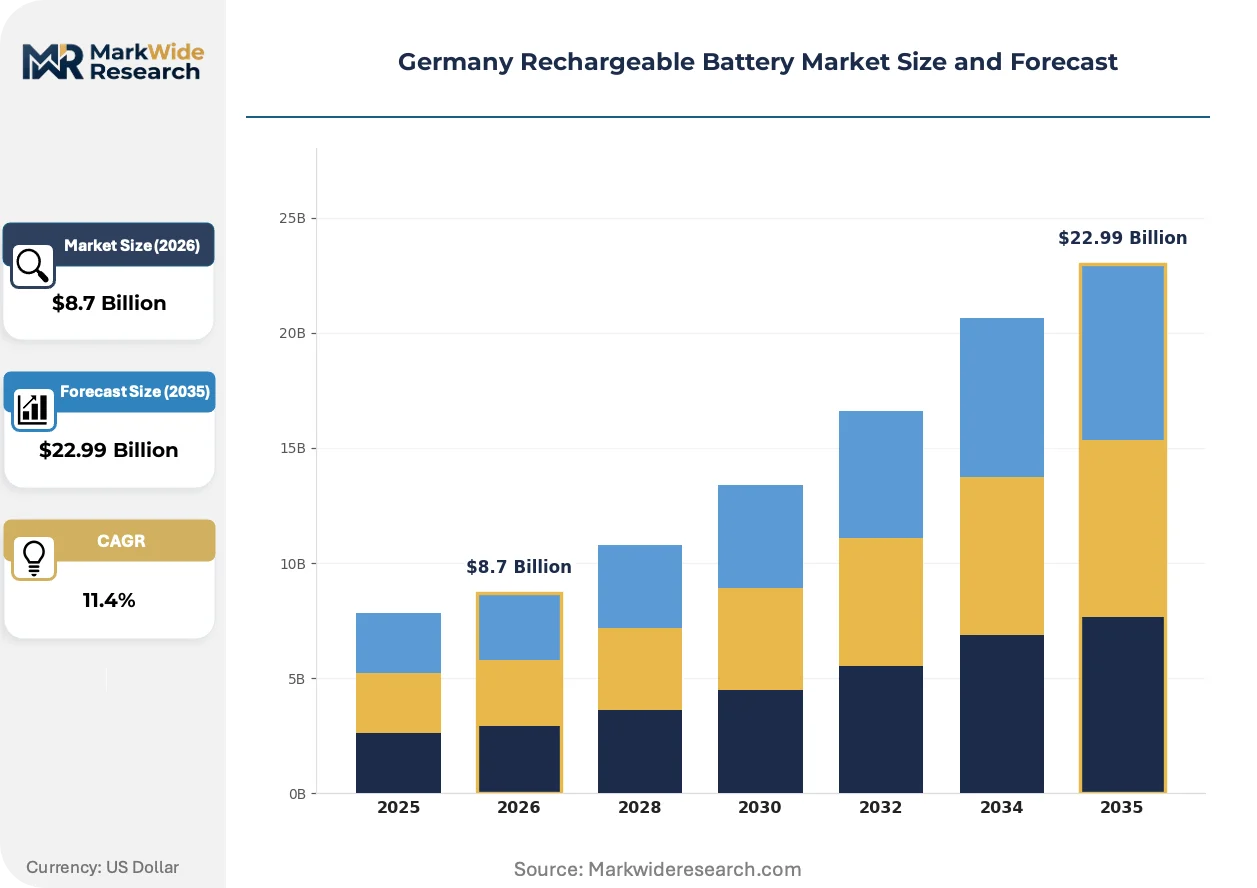
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Sodium-Sulfur End User: Automotive, Consumer Electronics, Industrial, Renewable Energy Installation: Stationary, Portable, Modular, Integrated Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | LG Energy Solution, CATL, Panasonic Holdings Corp., Samsung SDI, BYD, SK Innovation, GS Yuasa Corp., Volkswagen Group, Manz AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Rechargeable Battery Market Trends and Innovations
Solid-state cell architectures and silicon-dominant anodes are converging with regulatory pressure on supply-chain transparency, compressing development cycles and reshaping how German producers qualify new chemistries for automotive programs.
Silicon-blend anodes with pre-lithiation treatments are supplanting graphite-only architectures in German premium EV platforms. BMW and Volkswagen Group cell engineering teams have accelerated silicon incorporation roadmaps from 2030 to 2026-2027 model years. This chemistry shift is compressing anode supplier qualification timelines and forcing electrode coating equipment retrofits across Salzgitter and Erfurt production lines.
Delegated acts under the EU Battery Regulation are mandating granular supply-chain due diligence for cobalt, lithium, and natural graphite. Cell producers must deploy blockchain-traceability systems and third-party audited mass-balance accounting by 2027. German cathode material suppliers in North Rhine-Westphalia are responding by integrating direct-of-mine partnerships with Canadian and Australian hard-rock mining operations.
Fleet operators and energy utilities are consolidating procurement through long-term service contracts that bundle cell supply with state-of-health monitoring and residual value guarantees. This unbundles the traditional vehicle-OEM-as-intermediary model. The shift is most visible in Bavaria, where municipal transit authorities are negotiating directly with cell producers for 12-year total-cost-of-ownership agreements on electric bus platforms.
Germany Rechargeable Battery Market Segmentation
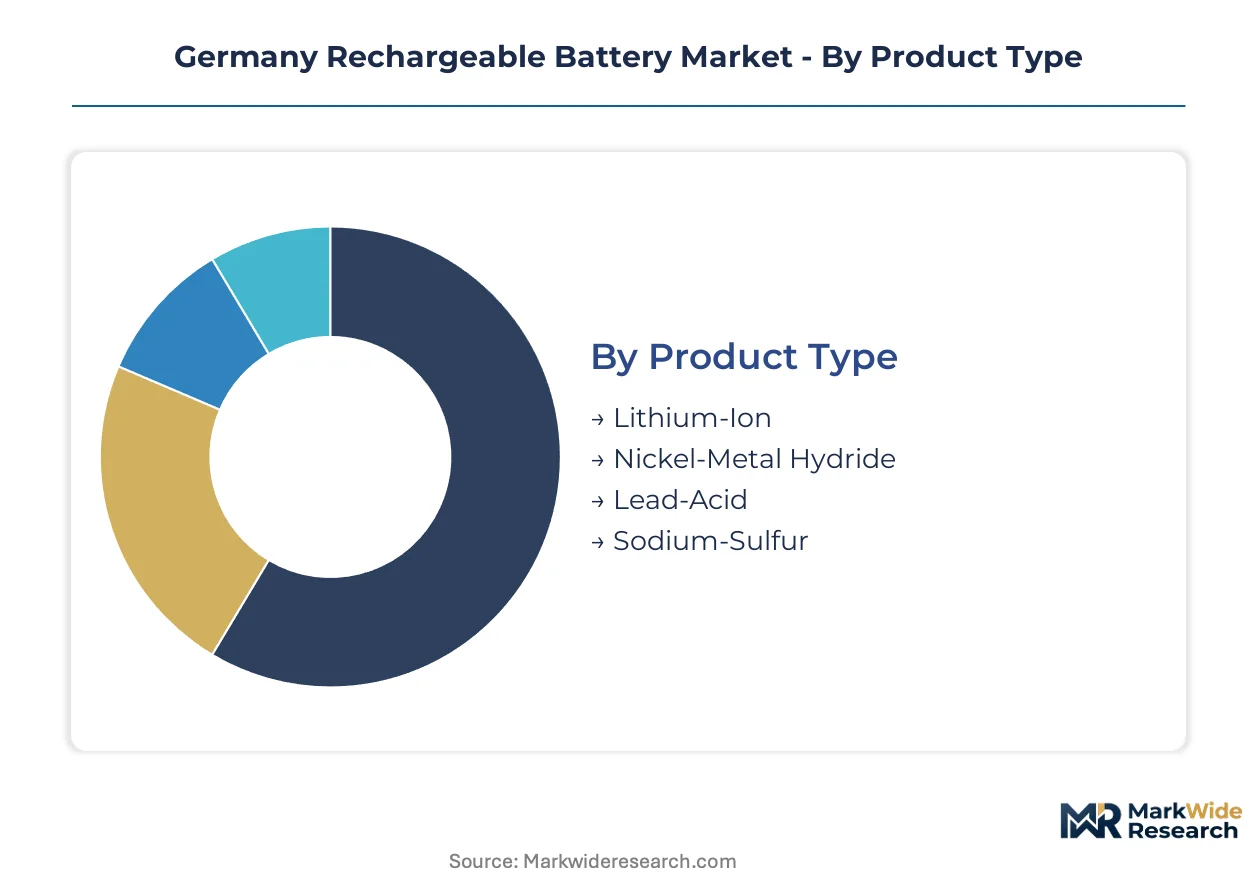
Segmentation in the German rechargeable battery market reveals how distinct electrochemical architectures and deployment modes align with specific procurement channels. Each dimension carries implications for compliance pathways under the EU Battery Regulation and KBA type-approval requirements.
Product Type:
Channel mix varies sharply by chemistry: lithium-ion flows predominantly through automotive OEM direct procurement, while lead-acid and nickel-metal hydride distribute through aftermarket distributors and industrial integrators.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate cathode variants dominate automotive traction applications, delivering energy densities above 250 Wh/kg. Demand concentrates in Baden-Württemberg and Bavaria, where Volkswagen Group and BMW specify high-nickel packs for premium EV platforms. The EU Battery Regulation's carbon footprint declarations are forcing cathode supply chain reconfiguration ahead of compliance deadlines.
- Nickel-Metal Hydride:Metal hydride anode paired with nickel oxyhydroxide cathode delivers thermal stability for hybrid-electric vehicle buffering. Procurement runs through Toyota and Honda European operations for mild-hybrid architectures where energy density requirements are secondary to abuse tolerance. KBA type-approval protocols treat these as distinct safety classes from lithium-ion systems.
- Lead-Acid:Mature flooded and valve-regulated designs persist in stationary backup and industrial motive power through distributor networks. Automotive starter battery replacement demand flows through aftermarket channels in North Rhine-Westphalia's dense logistics corridor.
- Sodium-Sulfur:High-temperature ceramic electrolyte systems serve grid-scale storage pilots for municipal utilities in eastern Germany's renewable energy zones. Procurement concentrates through E.ON and EnBW direct contracting for multi-megawatt hour installations.
By volume, lithium-ion leads. By growth pace, sodium-sulfur is gaining share fastest in utility-scale deployments.
End User:
Cost tier stratification separates automotive premium packs from industrial economy-grade systems, with consumer electronics occupying a mid-tier efficiency-optimized band.
- Automotive:Traction batteries for battery-electric and plug-in hybrid vehicles represent the highest value-per-kWh segment, with OEMs specifying 100+ kWh architectures for SUV and sedan platforms. Volkswagen Group's Salzgitter complex and BMW's pilot lines in Bavaria anchor demand concentration. CE marking and UNECE R100 certification create compliance barriers for non-qualified suppliers.
- Consumer Electronics:Cylindrical and prismatic cells for smartphones, laptops, and power tools flow through electronics manufacturing services in Saxony's semiconductor corridor. Energy density requirements above 700 Wh/L drive silicon-anode adoption in premium device tiers.
- Industrial:Forklift motive power and uninterruptible power systems prioritize cycle life over specific energy, with lead-acid and emerging lithium-iron-phosphate chemistries competing on total cost of ownership. Procurement runs through MHI and Jungheinrich service networks.
- Renewable Energy:Grid-buffering and residential solar-plus-storage applications in Thuringia and Brandenburg favor modular lithium-iron-phosphate architectures with 6000+ cycle warranties. Direct utility procurement is displacing traditional distributor channels.
Automotive commands the highest revenue per unit. Renewable Energy is expanding most quickly as EEG reform accelerates storage deployment.
Installation:
Application context dictates physical form factor, with stationary systems requiring seismic anchoring and thermal management infrastructure absent in portable designs.
- Stationary:Rack-mounted containerized systems for grid and commercial storage require active cooling and fire suppression integration. Erfurt and Magdeburg production corridors are specializing in megawatt-scale system integration for German TSO contracts.
- Portable:Cylindrical and pouch formats for consumer and light industrial tools distribute through retail and B2B channels with minimal installation overhead. Energy density optimization drives silicon-anode penetration in premium power tool segments.
- Modular:Hot-swappable rack architectures allow capacity scaling without system shutdown, preferred by data center operators in Frankfurt's cloud computing cluster. Procurement emphasizes 15-year service life guarantees with cell-level monitoring.
- Integrated:Pack-to-chassis designs for automotive platforms eliminate module housings, with BMW and Volkswagen Group engineering teams specifying structural battery enclosures. KBA structural integrity requirements add qualification complexity.
Stationary installations lead by megawatt-hour deployment. Integrated formats are climbing the fastest as automotive platform electrification accelerates.
Capacity:
Margin structure inverts across the capacity spectrum, with ultra-high-capacity packs commanding premium pricing for automotive applications while low-capacity cells compete on manufacturing scale.
- High Capacity:50-100 kWh automotive packs for mid-size EV platforms represent the volume anchor for Erfurt and Salzgitter production lines. Nickel-manganese-cobalt cathodes with graphite-silicon blend anodes balance energy density with manufacturing yield.
- Ultra High Capacity:Exceeding 100 kWh, these architectures enable 600+ kilometer range ratings for premium SUV and sedan segments. BMW and Mercedes-Benz Group specify cell-to-pack designs with structural integration. Solid-state R&D partnerships aim to push these boundaries further.
- Medium Capacity:10-50 kWh systems serve plug-in hybrid and light commercial vehicle applications, with lithium-iron-phosphate gaining share for thermal stability in commercial duty cycles.
- Low Capacity:Sub-10 kWh formats for consumer electronics, power tools, and residential backup systems compete on cell manufacturing scale and automated assembly efficiency.
High Capacity leads by unit volume across German production facilities. Ultra High Capacity shows the steepest expansion trajectory as OEMs extend range benchmarks for premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg and Bavaria concentrate automotive-grade cell demand through integrated OEM assembly, while eastern federal states attract precursor chemical and gigafactory investments under streamlined permitting regimes.
Baden-Württemberg
BMW operates pilot cell production lines in Munich and Dingolfing for premium EV platforms, specifying high-nickel cathode architectures. KBA enforces UNECE R100 type-approval protocols for traction battery safety certification. Stuttgart anchors supplier engineering offices for electrode coating equipment and cell testing systems.
Bavaria
Volkswagen Group's Salzgitter complex sources cathode-active-material from Erfurt corridor suppliers for 100+ kWh pack integration. The EU Battery Regulation mandates carbon footprint declarations that reconfigure procurement geography. Munich hosts solid-state R&D partnerships between Samsung SDI and German premium automakers.
North Rhine-Westphalia
Industrial motive power and stationary backup applications sustain lead-acid and emerging lithium-iron-phosphate demand through distributor networks. REACH compliance obligations govern chemical handling in electrode manufacturing. Cologne-Düsseldorf logistics corridors channel aftermarket battery replacement volume for commercial vehicle fleets.
Thuringia
CATL's Erfurt plant anchors cathode-active-material supply for European OEM programs, leveraging eastern Germany's grid infrastructure commitments. Delegated acts under the EU Battery Regulation define recycled content thresholds that reshape local sourcing obligations. Jena and Gera clusters specialize in dry-room construction and precision coating equipment for cell production.
Lower Saxony
Volkswagen Group's Salzgitter complex controls cell design, module assembly, and vehicle-platform deployment through backward integration into upstream materials. Federal grid expansion programs prioritize renewable energy zones for stationary storage deployment. Braunschweig technical universities supply electrochemical engineering talent for manufacturing scale-up.
Germany Rechargeable Battery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with automotive OEM captive operations and independent cell producers occupying distinct competitive bands. The structure bifurcates between volume-scale gigafactory operators and technology-differentiated solid-state developers. Two archetypes dominate: Asian-headquartered scale producers with European manufacturing footprints, and German automotive groups pursuing in-house cell production. Competitive moves center on cathode supply chain localization and silicon-anode qualification acceleration.
Within the Asian scale-producer tier, LG Energy Solution and CATL exemplify manufacturing footprint expansion through dedicated European plants. Samsung SDI occupies a position bridging volume production and next-generation solid-state development through German R&D partnerships. These three anchors represent the competitive tension between cost-driven scale and technology-led differentiation that defines procurement negotiations with German OEMs.
| Leading Market Players |
|---|
| LG Energy Solution |
| CATL |
| Panasonic Holdings Corp. |
| Samsung SDI |
| BYD |
| SK Innovation |
| GS Yuasa Corp. |
| Volkswagen Group |
| Manz AG |
| Others |
Pricing and Supply Chain Analysis
Gigafactory scale economies in Thuringia and Lower Saxony concentrate cathode-active-material procurement power among three producers, compressing price floors for mid-tier cell suppliers while elevating premium-tier pricing power for solid-state-qualified architectures.
Pricing Analysis
Long-term offtake agreements dominate procurement between German OEMs and cell producers, with spot-market lithium hydroxide purchases serving only marginal volume adjustments. Three-tier pricing structure across premium, standard, and economy levels separates structural battery packs with KBA certification from industrial-grade systems and aftermarket replacement cells. Cost compression in standard-tier automotive packs is intensifying because nickel sulfate import dependency exposes margins to maritime logistics volatility. Fleet operators exhibit highest price sensitivity through total-cost-of-ownership negotiations, while premium SUV platforms show least sensitivity due to range-performance bundling.
Supply Chain Analysis
Maritime container availability on Asia-Europe trade lanes dictates inbound precursor chemical scheduling, with Rotterdam and Hamburg port congestion extending cathode material lead times. German cell production draws from Chinese refined nickel, South Korean cobalt sulfate, and Australian spodumene concentrate, creating multi-continental dependency chains. Single-source vulnerability concentrates in East Asian cathode precursor refining, where geopolitical trade friction threatens production continuity. Distribution runs through automotive OEM direct procurement for traction batteries, while industrial and stationary segments channel through MHI and Jungheinrich service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German rechargeable battery demand is recovering from lithium price cyclicality troughs, with automotive platform electrification schedules providing visible volume commitments across the analysis window.
For Market Incumbents: Compound backward integration into Salzgitter and Erfurt corridor cathode precursor facilities to defend against Korean and Chinese scale-producer margin pressure. Secure UNECE R100 certification ahead of delegated EU Battery Regulation acts to lock in premium-tier pricing power before compliance barriers harden.
For New Entrants and Emerging Players: Anchor in second-life stationary storage refurbishment, where retired Baden-Württemberg automotive packs feed Thuringia grid-buffering installations with minimal cell engineering qualification. Target municipal transit authorities in Bavaria with direct 12-year service contracts that bypass traditional OEM intermediary structures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors silicon-anode electrode coating equipment specialists with dry-room construction capabilities in Jena and Gera clusters. Five-to-ten year viability hinges on EU Battery Regulation recycled content mandate execution; monitor hydrometallurgical refining capacity announcements in North Rhine-Westphalia chemical corridors as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Localization | Reduces maritime logistics exposure for Erfurt and Salzgitter production lines under EU Battery Regulation carbon footprint rules. |
| Solid-State R&D Partnership | Samsung SDI collaboration with BMW accelerates sulfide electrolyte qualification timelines for premium EV platforms. |
| Second-Life Storage Integration | Retired automotive packs from Bavaria fleets create circular revenue streams before recycling obligations activate. |
| Silicon-Anode Equipment Retrofit | Electrode coating line upgrades across Salzgitter enable 20-40% energy density improvement for 2026-2027 model years. |
| Hydrometallurgical Refining Investment | North Rhine-Westphalia chemical clusters prepare for EU Battery Regulation minimum recycled lithium thresholds. |
Research Methodology
Cross-validation between KBA type-approval databases and EU Battery Regulation delegated acts anchors the qualitative findings on compliance pathway evolution. Primary interviews with OEM platform engineers, cathode material procurement leads, dry-room construction specialists, and recycling facility operators combined with secondary validation from UNECE safety protocol filings, Bundesnetzagentur grid expansion records, and chemical industry cluster investment disclosures. Bottom-up cell production capacity modeling triangulates against top-down automotive electrification penetration assumptions.
Sensitivity analysis around lithium hydroxide price scenarios and solid-state manufacturing yield rates shapes the analytical framework across the projection horizon. Segmentation dimensions span cathode chemistry tier, end-use application, installation format, and capacity class, with regional production cluster adoption patterns providing additional stratification. CAGRs derive from production capacity buildout schedules cross-referenced with OEM platform launch timelines and stationary storage procurement auctions.
Decision-makers should treat outputs as directional under base assumptions of sustained automotive electrification commitment and EU Battery Regulation enforcement continuity; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Modular Uninterrupted Power Supplies (UPS) Market
Power Systems
EV Power Module Market
Power Systems
Central Battery Systems Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Asia-Pacific Uninterruptible Power Supply (UPS) Market
Power Systems
Battery Equalizer Market
Power Systems
Embedded Power Generation Market
Power Systems
Pulse Generator Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Thermoelectric Coolers Market
Power Systems
USB Power Adapters Market
Power Systems
Electric Vehicle Inverter Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
Silicon Carbide Power Devices Market
Power Systems
Shunt Reactor Market
Power Systems
Global Uninterruptible Power Supply (UPS) Market