
 High-Brightness Light-Emitting Diodes (LED) Headlamps Market | 2026-2036
High-Brightness Light-Emitting Diodes (LED) Headlamps Market Size, Share, and Industry Trends Forecast 2026-2036
High-Brightness Light-Emitting Diodes (LED) Headlamps Market Foresight
Aftermarket service revenue is fragmenting as vehicle electrification shifts warranty and replacement cycles toward integrated LED modules rather than standalone bulb swaps. Osram Opto Semiconductors leverages its vertical control over epitaxial wafer production to sustain margin capture in OEM channels. HELLA GmbH & Co. KGaA competes through specialized adaptive-beam software that differentiates its module offerings from commodity suppliers.
High-brightness light-emitting diodes (LED) headlamps are semiconductor-based solid-state lighting devices that emit luminous intensities exceeding 100 lumens per watt through gallium nitride chip architectures, primarily engineered to replace halogen and xenon arc lamps in forward vehicle illumination. The automotive lighting application segment leads value generation as OEMs mandate full-LED signatures across premium and mid-range platforms, while the COB LED technology segment captures the fastest growth trajectory due to its superior thermal management and compact form factor enabling slim headlamp housings. The rechargeable product type occupies niche positioning in emergency services and outdoor equipment channels where portable high-output sources remain essential.
NHTSA in the United States and ECE R48/R112 standards in Europe shape beam-pattern compliance and glare-limitation requirements that dictate LED array geometry and driver circuit design. China's SAMR enforces GB standards for automotive lighting that restrict market access to certified module suppliers. Stakeholders must monitor how adaptive driving beam regulations evolve across these jurisdictions to anticipate module complexity and pricing thresholds.
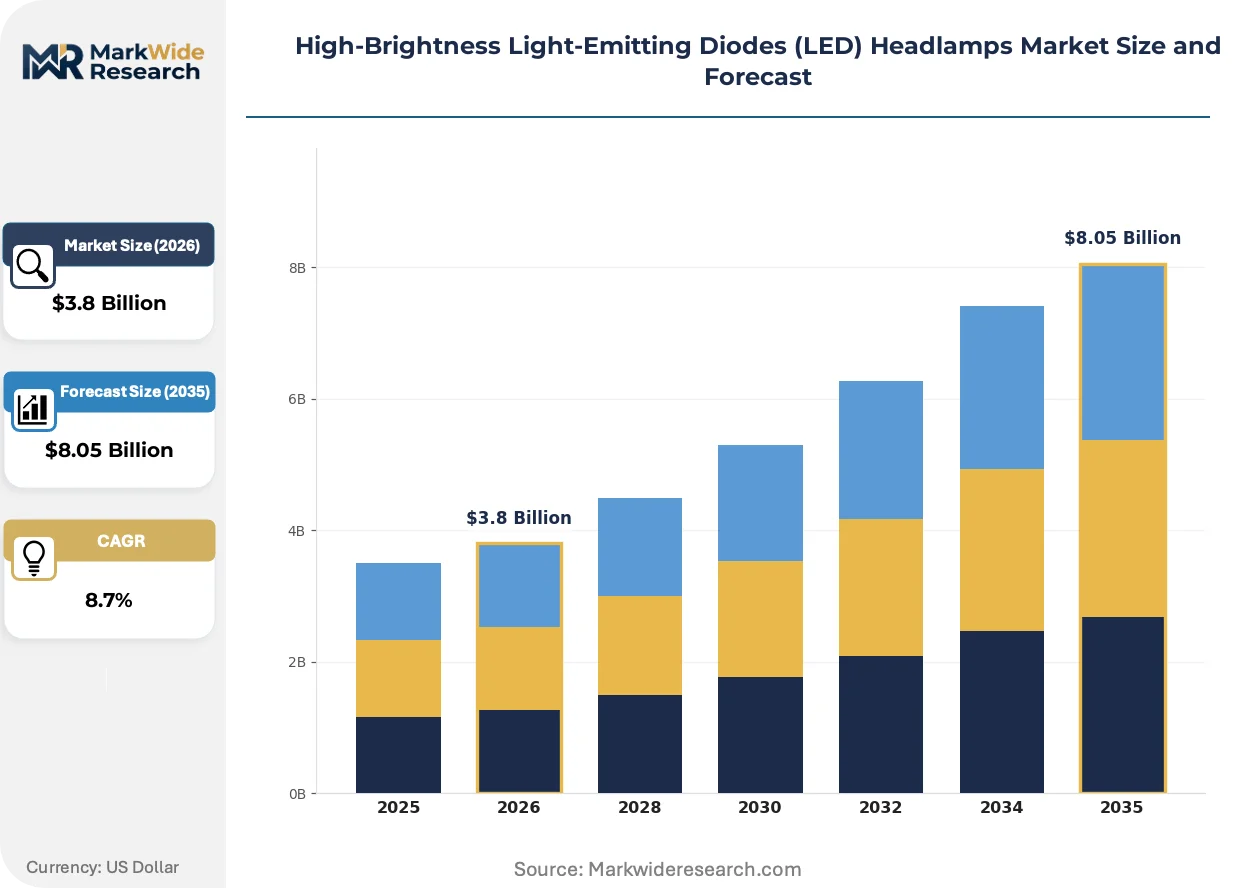
Market Dynamics
Automotive OEM procurement is pivoting toward full-LED signatures as NHTSA and ECE R112 tighten beam-pattern compliance thresholds, forcing module suppliers to redesign thermal management and driver electronics for slimmer headlamp housings.
Growth Catalysts
- ECE R48/R112 glare-limitation mandates:European regulators now require adaptive driving beam functionality in premium vehicle categories, compelling LED array redesigns that lift module complexity and pricing.
- Chip-on-board thermal architectures:COB LED technology enables compact form factors that satisfy styling demands for narrow headlamp apertures on electric vehicle platforms.
- China's GB standard enforcement:SAMR certification requirements restrict market access to qualified suppliers, consolidating procurement toward certified module manufacturers.
Market Restraints
- Gallium nitride wafer supply concentration:Epitaxial substrate production clusters in East Asian foundries, exposing OEMs to single-source risk for high-brightness chip architectures.
- Adaptive beam software integration costs:Module suppliers must absorb escalating R&D expenditure for pixel-level control algorithms without guaranteed platform volume.
- Xenon arc lamp residual installed base:Mid-range vehicle fleets retain HID systems with sufficient lumen output, delaying replacement cycles in cost-sensitive segments.
Strategic Opportunities
- India's automotive safety mandate expansion:Central Motor Vehicle Rules revisions position the market for LED headlamp penetration as domestic assembly scales.
- Rechargeable emergency services channel:Portable high-output LED modules address unmet demand in fire, rescue, and outdoor equipment applications outside automotive OEM supply.
- Vehicle-to-everything lighting integration:Convergence of LED arrays with sensor housing and communication modules creates new value pools in autonomous platform development.
Industry Challenges
- Optical design talent scarcity:Specialized expertise in free-form lens simulation and ray-tracing software remains concentrated among tier-one lighting suppliers.
- Multi-jurisdiction certification timelines:Simultaneous NHTSA, ECE, and GB homologation processes extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Brightness Light-Emitting Diodes (LED) Headlamps Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable, Solar-Powered, Battery-Operated, Hybrid Application: Outdoor Activities, Industrial Use, Automotive Lighting, Emergency Situations Technology: Cob LED, SMD LED, Halogen, Xenon End User: Manufacturers, Retail Consumers, Construction Workers, Emergency Services |
| Companies Covered | Philips Lumileds, Osram Opto Semiconductors, Cree, Samsung Electronics, Seoul Semiconductor, Nichia Corporation, HELLA GmbH & Co. KGaA, Koito Manufacturing, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Brightness Light-Emitting Diodes (LED) Headlamps Market Shifts & Advancements
Module miniaturization and software-defined beam control are compressing hardware differentiation while elevating adaptive functionality as the primary competitive battleground.
Matrix LED technology is collapsing the distinction between high and low beam hardware by using individually addressable pixels to mask oncoming traffic without mechanical shutters. Premium German OEMs now specify 84-pixel and 1024-pixel arrays as standard equipment. This compression eliminates separate projector modules and reduces housing depth by 40 millimeters.
Europe's F-Gas Regulation is phasing out sulfur hexafluoride in automotive manufacturing processes, compelling LED module suppliers to transition thermal interface materials toward graphene-based alternatives. Assembly lines in Germany and the Czech Republic are retrofitting dispensing equipment to handle new die-attach compounds. The shift elevates material costs but insulates suppliers from future compliance penalties.
Fleet operators are consolidating lighting procurement through direct module sourcing rather than tiered supplier hierarchies, disintermediating traditional bulb distributors. North American commercial vehicle lessors now specify LED headlamp lifecycles in total cost of ownership models. This behavioral shift compresses aftermarket service revenue and redirects margin capture toward OEM-authorized module channels.
High-Brightness Light-Emitting Diodes (LED) Headlamps Market Segmentation
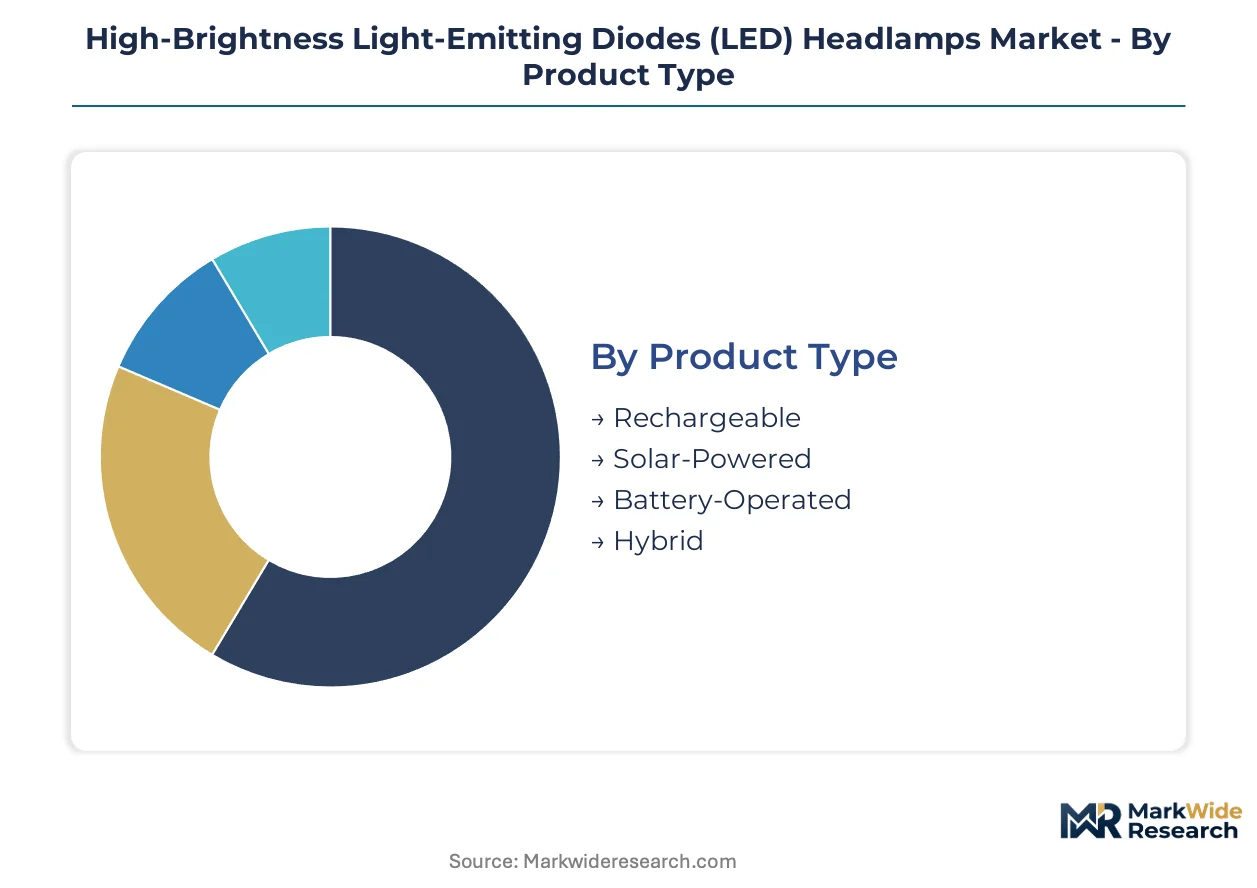
LED headlamp segmentation reveals divergent technology maturity and application economics. Product architecture choices directly determine thermal management requirements, regulatory compliance pathways, and channel margin structures across automotive OEM and aftermarket supply chains.
Product Type:
Mature battery-operated designs dominate volume, while rechargeable architectures represent the emerging frontier in professional and emergency deployment.
- Battery-Operated:Disposable alkaline or lithium primary cell configurations deliver lowest upfront cost for consumer retail channels. Demand concentrates in North American big-box retail and European DIY segments where purchase convenience outweighs lifetime cost considerations.
- Rechargeable:Lithium-ion cell integration with USB-C or proprietary dock systems enables 500+ cycle lifespans. Fire departments and search-and-rescue units in Germany and the United States specify these for operational cost control and reduced field failure rates.
- Solar-Powered:Photovoltaic panel integration with supercapacitor buffering addresses off-grid emergency preparedness demand.
- Hybrid:Dual-source architectures combining rechargeable cells with solar trickle charging serve military and expeditionary applications requiring operational redundancy.
Battery-operated retains volume leadership; rechargeable holds the steepest expansion curve.
Application:
Cost tier stratification separates regulated automotive specifications from discretionary consumer purchases.
- Automotive Lighting:OEM-grade LED modules must satisfy NHTSA FMVSS 108 and ECE R112 beam-pattern standards with thermal cycling validation. Assembly lines in Germany, China, and the United States mandate full-LED signatures across premium and mid-range vehicle platforms, concentrating procurement toward certified module suppliers.
- Emergency Situations:First responder specifications require IP67 ingress protection, strobe functionality, and helmet mounting compatibility. Fire services in the United States and industrial safety teams in Germany drive specification tightening for runtime reliability under thermal stress.
- Outdoor Activities:Camping and hiking demand prioritizes weight reduction and lumen-to-watt efficiency over durability metrics.
- Industrial Use:Mining and construction specifications emphasize explosion-proof housing and intrinsic safety certifications.
Automotive lighting commands pricing premiums; emergency situations are expanding most quickly as procurement professionalizes.
Technology:
Supply concentration in epitaxial wafer production shapes competitive access to high-brightness architectures.
- Cob LED:Chip-on-board packaging eliminates individual LED packages by mounting bare die directly on ceramic or metal substrates. Electric vehicle platforms in China and Germany specify COB modules for headlamp housings under 60 millimeters depth, where thermal density and form factor constraints exclude conventional packaged LEDs.
- SMD LED:Surface-mount device packaging with discrete 2835 or 5050 footprints dominates aftermarket retrofit applications. Cost-sensitive segments in India and Brazil retain SMD architectures where lumen-per-dollar optimization outweighs thermal performance.
- Halogen:Tungsten-halogen incandescent technology persists in legacy fleet maintenance and developing market entry vehicles.
- Xenon:High-intensity discharge arc lamps retain installed base in mid-range European vehicle fleets with sufficient lumen output to delay LED conversion cycles.
COB LED captures technology leadership; SMD LED maintains broadest geographic penetration.
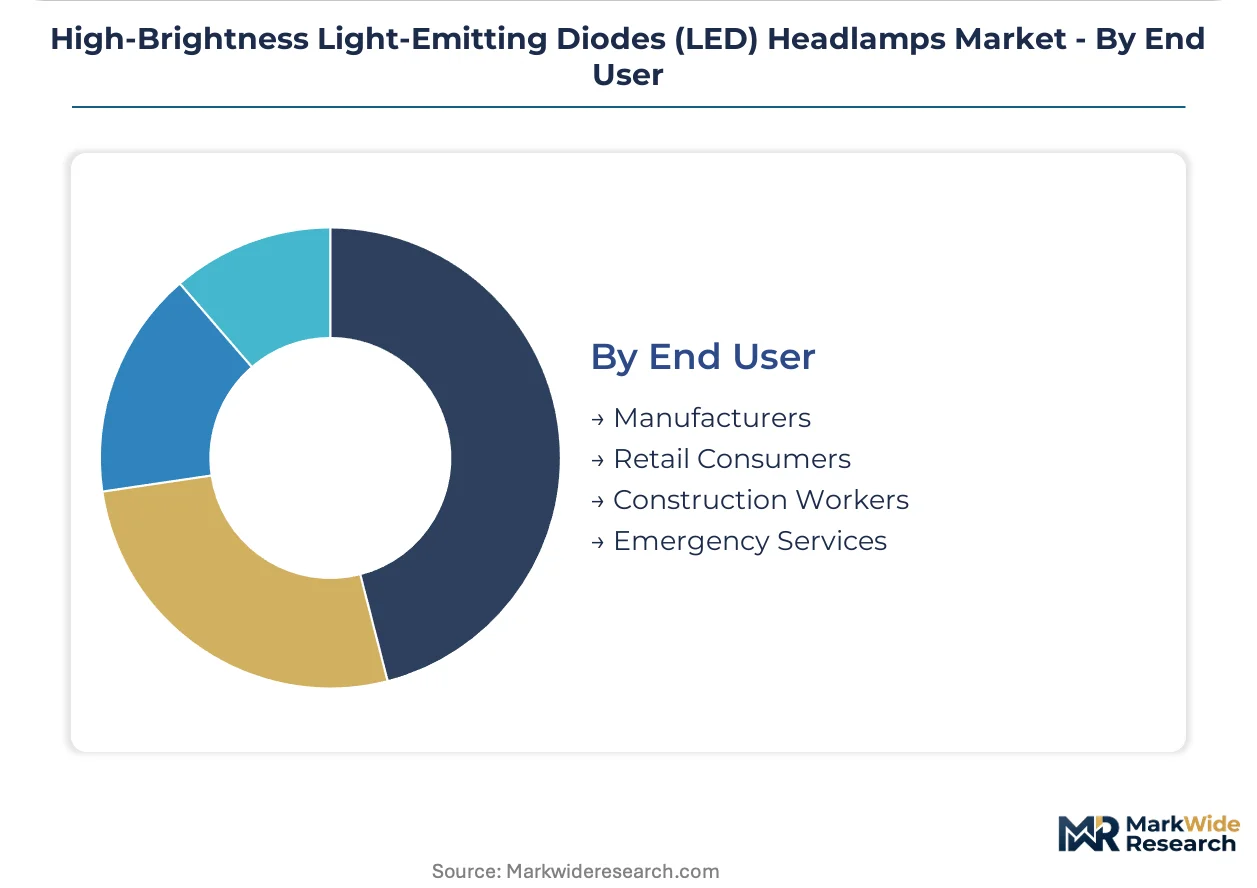
End User:
Customer type determines procurement channel structure and specification authority.
- Manufacturers:Tier-one automotive lighting suppliers and OEM module integrators specify LED die and driver electronics at the component level. Procurement concentrates through direct supplier agreements with epitaxial wafer foundries in East Asia, bypassing distribution markup.
- Emergency Services:Municipal fire departments and federal search-and-rescue agencies issue centralized procurement contracts with runtime and warranty requirements. German and United States federal specifications increasingly mandate rechargeable architectures with standardized battery interfaces.
- Construction Workers:Employer-provided personal protective equipment programs drive mid-tier specification with cost amortization across crew sizes.
- Retail Consumers:E-commerce and big-box channels dominate with brand recognition and lumen claims as primary purchase determinants.
Manufacturers retain supply concentration; emergency services are gaining share fastest as public safety budgets professionalize equipment standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German and United States buyers absorb premium module costs for adaptive beam functionality, while Indian and Brazilian fleet operators prioritize lumen-per-dollar metrics that delay full-LED conversions.
United States
NHTSA FMVSS 108 compliance deadlines accelerate OEM procurement of matrix LED arrays. The Infrastructure Investment and Jobs Act channels federal vehicle procurement toward domestic assembly platforms. Detroit-Windsor corridor suppliers retool for slimmer headlamp housings on electric truck platforms.
Germany
ECE R112 adaptive driving beam mandates now apply to premium vehicle categories. The F-Gas Regulation phases sulfur hexafluoride from thermal interface manufacturing. Ingolstadt and Stuttgart assembly lines specify 1024-pixel LED arrays as standard equipment.
China
SAMR GB standard enforcement restricts market access to certified module suppliers. Dual carbon goals pressure domestic OEMs toward energy-efficient LED signatures. Yangtze River Delta foundries dominate gallium nitride epitaxial wafer supply for high-brightness chip architectures.
India
Central Motor Vehicle Rules revisions mandate improved forward illumination for new vehicle registrations. PLI scheme incentives attract module assembly investment. Tamil Nadu and Gujarat automotive clusters scale domestic LED sourcing for mid-range platforms.
Japan
METI automotive safety guidelines encourage adaptive beam technology diffusion. JIS standard harmonization with ECE regulations simplifies export certification. Kansai region lighting suppliers specialize in compact COB modules for kei car platforms.
High-Brightness Light-Emitting Diodes (LED) Headlamps Market Competitive Landscape
Capability concentration sits with epitaxial wafer specialists; scale advantage sits with diversified electronics conglomerates. The market structures around three tiers: captive semiconductor divisions of automotive tier-ones, independent LED die specialists with upstream wafer control, and module integrators competing on optical design software. Consolidation pressure favors M&A between module integrators and thermal management specialists, while geographic expansion targets Indian and Southeast Asian assembly markets.
Within the semiconductor die tier, Osram Opto Semiconductors and Seoul Semiconductor exemplify upstream integration strategies. Among module integrators, HELLA GmbH & Co. KGaA occupies a position defined by adaptive-beam software differentiation. Samsung Electronics represents the diversified conglomerate archetype leveraging captive semiconductor capacity across multiple lighting applications.
| Leading Market Players |
|---|
| Philips Lumileds |
| Osram Opto Semiconductors |
| Cree |
| Samsung Electronics |
| Seoul Semiconductor |
| Nichia Corporation |
| HELLA GmbH & Co. KGaA |
| Koito Manufacturing |
| Valeo |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor channels gallium nitride wafer shipments from Yangtze River Delta foundries to European module assembly plants, with freight cost volatility amplifying margin compression for uncertified suppliers while reinforcing pricing power among SAMR-certified incumbents serving premium automotive OEMs.
Pricing Analysis
Aftermarket service revenue from replacement modules and extended warranty contracts now drives lifetime value capture, with three-tier pricing structure across premium, standard, and economy levels separating adaptive-beam arrays from basic LED retrofits. Pricing stratifies across premium, standard, and economy tiers based on pixel density certification and thermal management grade, with German and United States OEMs absorbing premium costs for matrix functionality while Indian fleet operators prioritize lumen-per-dollar metrics. Margins are tightening due to gallium nitride substrate cost pass-through from East Asian foundries. Price-sensitive buyers concentrate in mid-range vehicle retrofit channels; least sensitive buyers occupy emergency services procurement with runtime reliability specifications.
Supply Chain Analysis
Export-control restrictions on advanced epitaxial deposition equipment limit wafer production expansion outside established East Asian foundries, concentrating high-brightness chip supply in China, South Korea, and Taiwan. Module assembly draws from gallium nitride substrates, ceramic thermal interface materials, and precision driver ICs. Single-source vulnerability persists for MOCVD reactor components and qualified die-attach compounds. Distribution runs through tier-one automotive lighting suppliers with direct OEM platform integration contracts, bypassing traditional aftermarket distributors for new vehicle content.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LED headlamp module demand sits in early-cycle expansion as ECE R112 and NHTSA beam-pattern mandates accelerate OEM procurement of adaptive driving beam architectures across premium and mid-range vehicle platforms.
For Market Incumbents: Harden thermal management IP through captive ceramic substrate production or exclusive supply agreements with Yangtze River Delta foundries, defending against margin erosion from commodity COB suppliers. Deepen software-defined beam control capabilities to differentiate from hardware-focused competitors as matrix LED pixel counts standardize at 84 and 1024 configurations.
For New Entrants and Emerging Players: Build out rechargeable emergency services channel presence with IP67-rated, strobe-capable modules for German and United States federal procurement contracts, the most penetrable segment outside automotive OEM supply. Pursue direct sourcing relationships with municipal fire departments and industrial safety teams bypassing traditional distributor hierarchies.
For Investors and Strategic Acquirers: Optical design software specialists with free-form lens simulation capabilities represent the most attractive acquisition archetype as hardware differentiation compresses and adaptive functionality becomes the primary competitive battleground. Monitor ECE regulatory expansion into mid-range vehicle categories as the inflection signal for module complexity and pricing threshold expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Epitaxial Wafer Backward Integration | Captive gallium nitride substrate production insulates margin capture from East Asian foundry pricing power. |
| Adaptive Beam Software Acquisition | Pixel-level control algorithm ownership differentiates module offerings as hardware standardizes. |
| Emergency Services Channel Direct Entry | Municipal procurement contracts in Germany and the United States bypass tiered automotive supplier hierarchies. |
| SAMR Certification Investment | GB standard compliance unlocks access to Yangtze River Delta OEM assembly platforms. |
| Graphene Thermal Interface Transition | F-Gas Regulation compliance eliminates sulfur hexafluoride exposure penalties in European manufacturing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across tier-one automotive lighting procurement teams, OEM platform engineering directors, aftermarket distributor category managers, and emergency services equipment specification officers. Secondary validation incorporated NHTSA FMVSS 108 compliance filings, ECE R112 homologation records, SAMR GB certification databases, and vehicle production registration data from Germany, China, and the United States. Bottom-up module shipment estimates triangulated against top-down automotive lighting market value assessments.
Calibration against historical adoption curves for xenon-to-LED transition cycles informed growth rate derivation across the analysis window. Segmentation dimensions modeled include product architecture, application tier, technology platform, and end-user procurement authority, with vehicle class and regional regulatory cluster as automotive-specific overlays. Driver circuit complexity indices and thermal management material cost trajectories served as industry-specific forecast inputs alongside OEM platform launch timelines.
Practitioners should monitor adaptive driving beam regulatory expansion timelines and gallium nitride wafer capacity announcements for early signals of supply-demand imbalance. Forecasts reflect documented assumptions regarding ECE R112 enforcement scope and SAMR certification pathway duration. Material shifts in export-control regime stringency or multi-jurisdiction homologation timeline convergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Brazil LED Market
LED
UV-C LED Market
LED
China LED Lighting Market
LED
LED Digital Scoreboard Market
LED
Led Video Walls Market
LED
Japan Outdoor LED Lighting Market
LED
LED Mask Market
LED
US Outdoor LED Lighting Market
LED
LED Lighting Solution Market
LED
Global Industrial and Commercial LED Lighting Market
LED
UV LED Market
LED
Germany Outdoor LED Lighting Market
LED
France Indoor LED Lighting Market
LED
LED Light Market
LED
Asia Pacific Indoor LED Lighting Market
LED
North America Micro-LED Display Market