
 Microled Market | 2026-2036
Microled Market Size, Share, and Industry Trends Forecast 2026-2036
Microled Market Outlook
The capital-intensity divergence between foundry-dependent and vertically integrated players is bifurcating competitive trajectories in MicroLED manufacturing. Samsung Electronics leverages in-house semiconductor fabrication to sustain wafer-level processing cost advantages. PlayNitride anchors its position through dedicated nitride epitaxy capacity, while Aledia competes via silicon-nanowire architecture that reduces transfer-step complexity.
MicroLED denotes an emissive display technology comprising self-illuminating inorganic LEDs with individual chip dimensions below 50 micrometers, fabricated through gallium-nitride epitaxy on sapphire or silicon substrates followed by mass transfer onto backplanes. Displays command the dominant revenue pool as television and smartwatch brands prioritize luminance efficiency and burn-in immunity over incumbent OLED panels. Automotive end-user applications represent the fastest-expanding segment, driven by HUD and transparent dashboard requirements where Modules and Tiles integrate into curved cabin surfaces. Digital Signage applications sustain premium pricing through fine-pitch outdoor durability demands.
FCC equipment authorization rules in the United States constrain transmitter-integrated MicroLED timelines, while REACH substance restrictions in Europe shape RoHS-compliant phosphor and solder material selections. China's GB standards for display energy efficiency, enforced by SAMR, create market-access thresholds for imported panels. Stakeholders must monitor which regulatory jurisdiction first mandates MicroLED-specific recycling protocols, as this will force premature design-cycle investments across the supply base.
Market Dynamics
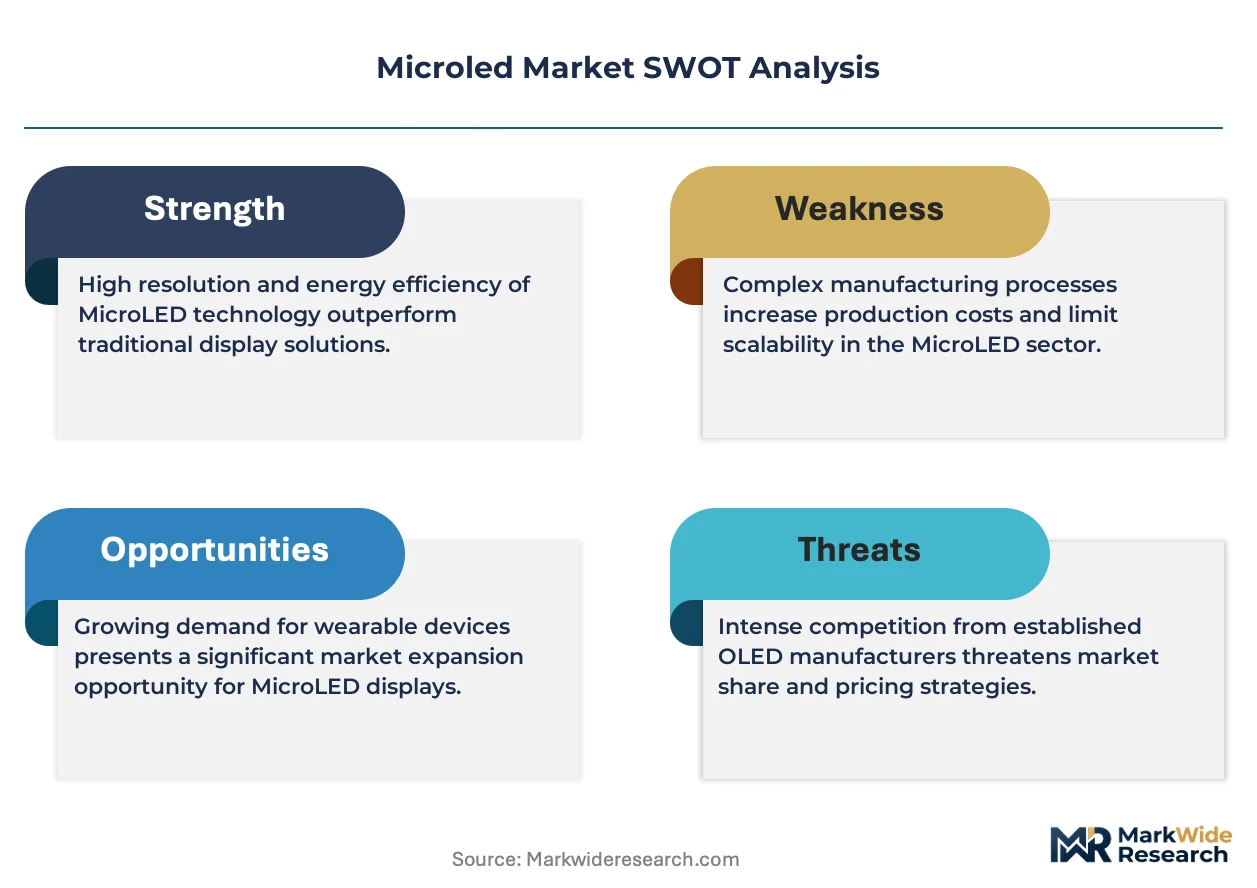
Mass transfer yield limitations and epitaxy wafer supply concentration in Taiwan are forcing display manufacturers to reconfigure equipment procurement timelines and foundry partnerships.
Growth Catalysts
- Automotive HUD Mandates:NHTSA visibility standards in the United States and METI regulations in Japan are compelling OEMs to source MicroLED panels for transparent dashboard integration.
- Energy Efficiency Frameworks:China's GB standards enforced by SAMR establish efficiency thresholds that privilege MicroLED luminance performance over competing display technologies in public procurement.
- Gallium-Nitride Epitaxy Maturation:Dedicated nitride capacity expansion at Hsinchu Science Park is compressing wafer lead times for display backplane integration.
Market Restraints
- Sapphire Substrate Cost Volatility:Raw material pricing fluctuations for single-crystal aluminum oxide wafers compress foundry margins during capacity ramp phases.
- FCC Equipment Authorization Friction:Transmitter-integrated MicroLED timelines face extended certification cycles under United States wireless device rules.
- OLED Substitution Threat:Mature organic LED supply chains in South Korea retain cost advantages in sub-65-inch consumer television segments.
Strategic Opportunities
- Underpenetrated Medical Imaging:Surgical display applications in Germany and Japan present white space where MicroLED color accuracy specifications exceed incumbent LCD performance.
- Silicon-Nanowire Convergence:Integration of nanowire architectures with CMOS backplanes eliminates pick-and-place transfer steps, reducing capital intensity for mid-scale panel production.
- RoHS-Compliant Phosphor Innovation:REACH substance restrictions in Europe are creating first-mover advantages for suppliers with compliant rare-earth dopant formulations.
Industry Challenges
- Chiplet Bonding Expertise Scarcity:The specialized technician pool for sub-50-micrometer die placement remains concentrated among legacy LED and semiconductor equipment operators.
- Dual Certification Complexity:Simultaneous compliance with automotive AEC-Q100 and display IEC 62341 standards extends product qualification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microled Market |
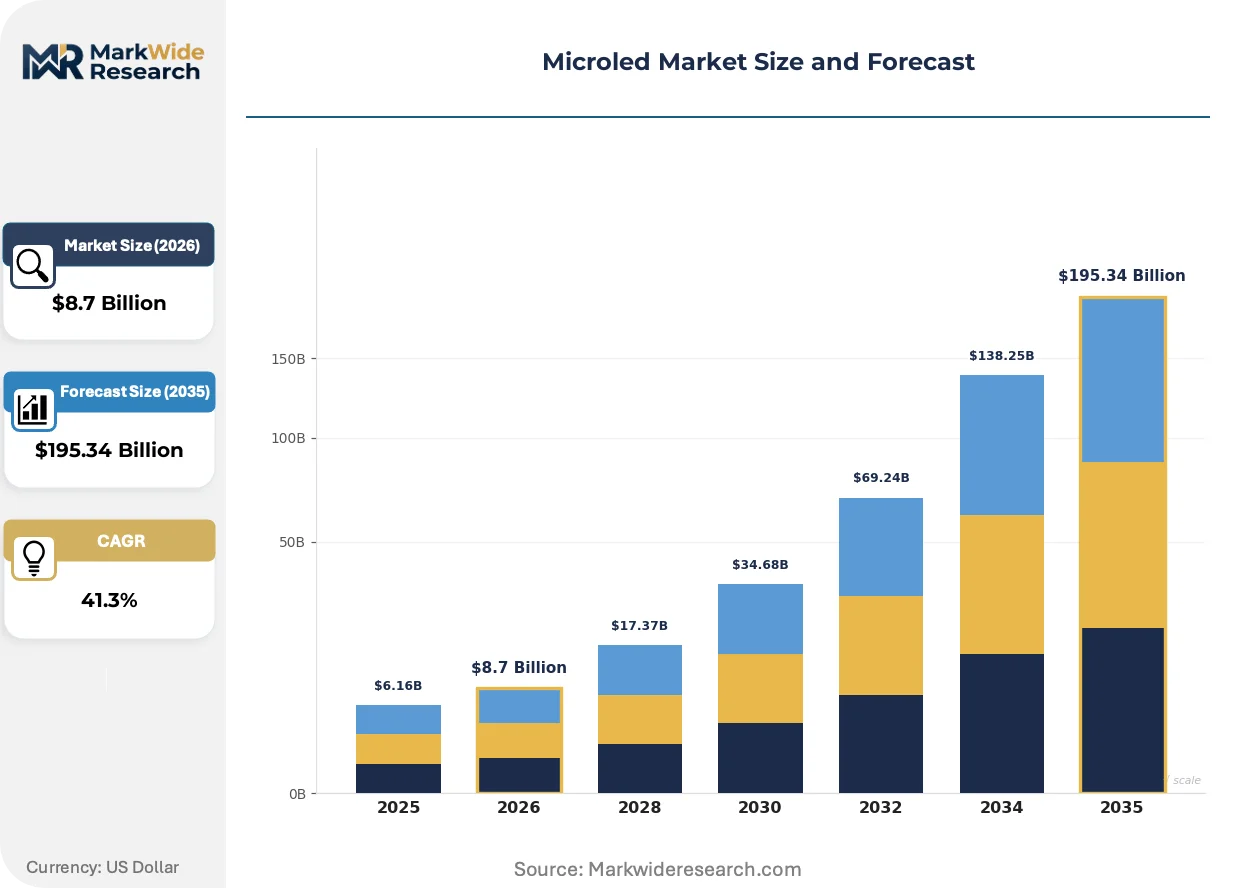
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $195.34 Billion |
| CAGR (2026 – 2036) | 41.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Displays, Modules, Tiles, ICs End User: Retail, Residential, Commercial, Automotive Installation Type: On-Wall, Free-Standing, Ceiling-Mounted, Embedded Application: Advertising, Entertainment, Sports, Digital Signage |
| Companies Covered | Samsung Electronics Co., Ltd, Sony Corporation, Apple Inc., LG Display Co., Ltd, BOE Technology Group Co., Ltd, AU Optronics Corp., PlayNitride, Aledia, X-Celeprint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microled Market Strategic Shifts
Active matrix driving architectures and laser-based mass transfer methods are compressing the cost gap between MicroLED pilot production and commercial-scale OLED economics.
Laser-induced forward transfer (LIFT) is displacing mechanical pick-and-place as the dominant mass transfer modality for chips below 20 micrometers. Automotive cockpit integrators in Germany and Japan are adopting LIFT-enabled curved panel designs at pilot scale. This displacement is compressing capital equipment payback periods for tier-one display foundries.
REACH substance restrictions enforced by ECHA are reshaping phosphor and solder material selections across European-bound display shipments. Manufacturers must reformulate indium-gallium-zinc oxide backplanes and lead-free interconnects to maintain market access. Television and digital signage categories face the steepest compliance cost adjustments.
Automotive OEM technical specifications now mandate 10-year operational lifespans for cockpit displays, a threshold that OLED burn-in characteristics struggle to satisfy. Tier-1 suppliers in Japan and Germany are rewriting RFQ templates to prioritize inorganic LED architectures. This specification shift is most visible in premium electric vehicle platforms targeting 2027-2028 production windows.
Microled Market Segmentation
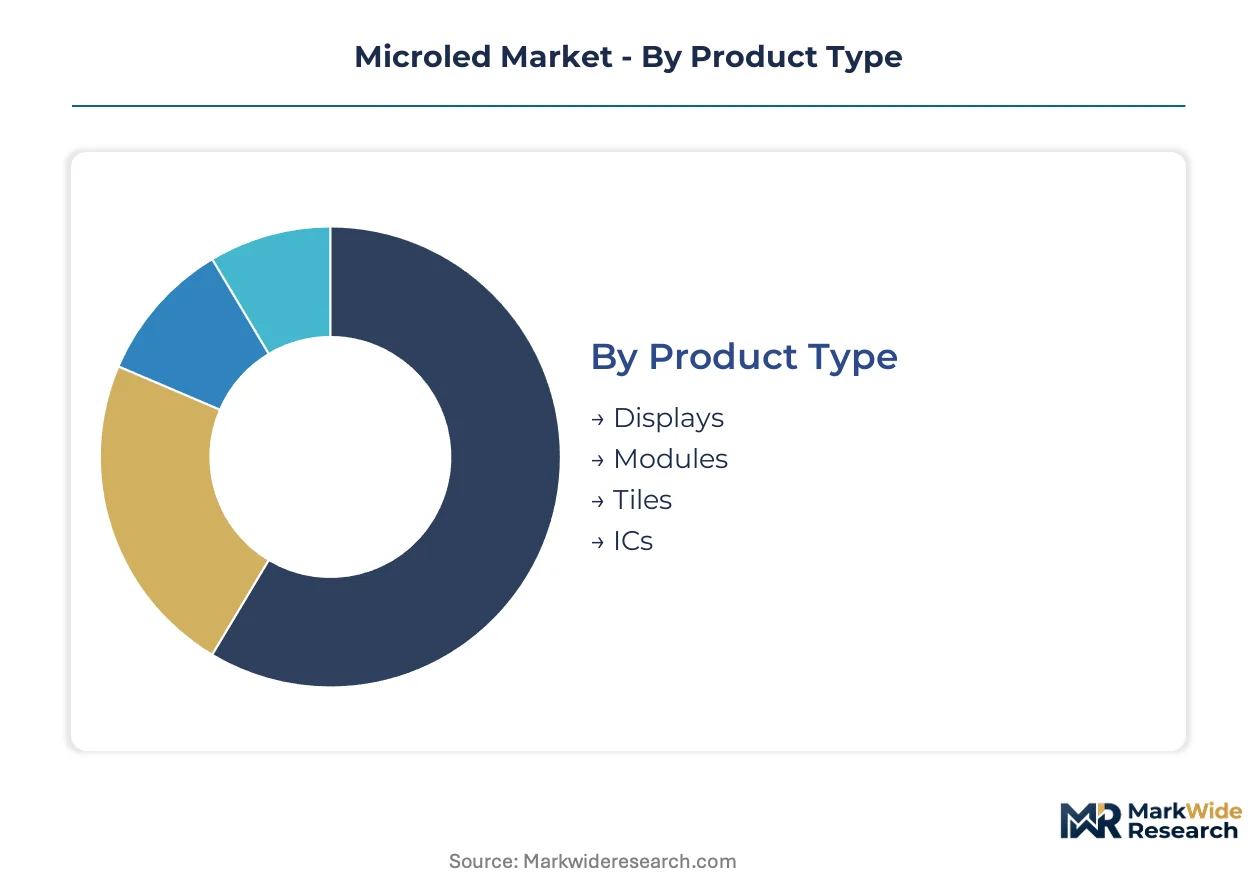
MicroLED market segmentation reveals how technical specifications and deployment contexts reshape procurement priorities across display categories. Each dimension carries distinct regulatory, installation, and performance requirements that determine supplier qualification pathways.
Product Type:
REACH substance restrictions enforced by ECHA and China's GB standards enforced by SAMR create divergent compliance burdens across finished goods versus component categories.
- Displays:Finished panels integrating gallium-nitride epitaxy layers with active matrix backplanes for direct consumer and commercial deployment. Television manufacturers in Germany and Japan prioritize these units for burn-in immunity in premium product lines, while NHTSA visibility standards in the United States accelerate automotive cockpit procurement.
- Modules:Sub-assembly units combining MicroLED chips with driver electronics for integration into larger systems. Automotive OEMs in Japan source METI-compliant modules for transparent dashboard configurations, compressing qualification timelines for tier-1 cockpit integrators.
- Tiles:Modular panel segments designed for seamless large-format assembly in digital signage and architectural applications.
- ICs:Integrated circuits governing pixel driving and power management for MicroLED backplane control.
Displays handles the majority of throughput; Modules is the fastest mover on share.
End User:
Customer procurement scale ranges from single-unit residential installations to fleet-scale automotive contracts with decade-long service specifications.
- Automotive:OEM and tier-1 suppliers integrating transparent dashboard and HUD configurations where 10-year operational lifespans exceed OLED burn-in thresholds. Germany's KBA and Japan's METI regulations mandate visibility standards that privilege inorganic LED architectures in premium electric vehicle platforms.
- Commercial:Corporate, hospitality, and institutional buyers deploying fine-pitch indoor and outdoor signage where luminance efficiency determines total cost of ownership.
- Retail:Brand environments and point-of-sale installations requiring high ambient-light visibility and continuous operation durability.
- Residential:Consumer television and home theater applications competing directly with mature OLED supply chains from South Korea.
Commercial absorbs the largest volume commitment; Automotive is climbing the fastest on contract value.
Installation Type:
Physical mounting constraints determine thermal management requirements and service accessibility, with embedded configurations demanding the most stringent pre-qualification testing.
- Embedded:Integration within architectural surfaces, automotive cabin structures, or equipment housings where replacement access is severely limited. Germany's automotive OEMs specify these installations for curved cockpit surfaces, triggering AEC-Q100 and IEC 62341 dual certification requirements that extend qualification timelines.
- On-Wall:Direct surface mounting for commercial and residential displays with standard VESA or proprietary bracket systems.
- Free-Standing:Kiosk, totem, and mobile display configurations for retail and event deployments.
- Ceiling-Mounted:Suspended installations for digital signage and architectural lighting in commercial environments.
On-Wall dominates shipment volume; Embedded is gaining share fastest on per-unit margin.
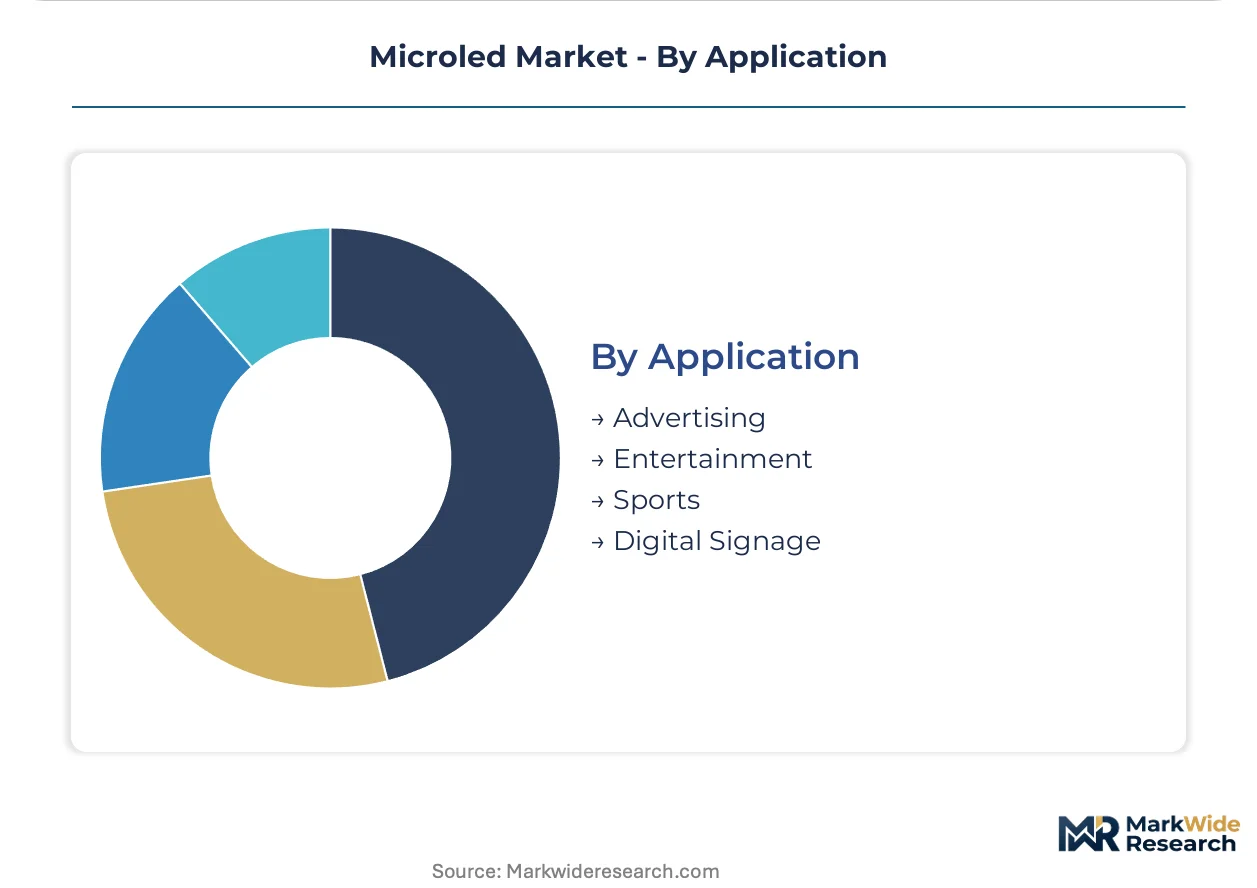
Application:
Content refresh rates and ambient exposure conditions vary dramatically across use cases, with outdoor durability commanding premium pricing tiers.
- Digital Signage:Permanent commercial installations requiring fine-pitch resolution, weather resistance, and continuous operation reliability. China's SAMR-enforced GB energy efficiency standards privilege MicroLED luminance performance in public procurement tenders, creating market-access advantages over competing technologies.
- Advertising:High-visibility commercial displays in transit hubs, retail environments, and outdoor billboards.
- Entertainment:Cinema, broadcast, and live event applications where color accuracy and high dynamic range specifications exceed incumbent LCD performance.
- Sports:Stadium and arena installations requiring extreme brightness for daylight visibility and impact resistance.
Digital Signage commands the revenue concentration; Automotive cockpit integration (captured within broader procurement) is expanding most quickly as a specification category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Taiwanese foundry clusters while German automotive OEMs absorb premium markups for cockpit-qualified panels. This asymmetry reshapes procurement geography across the value chain.
United States
NHTSA visibility standards for driver information systems compel Detroit and Silicon Valley automakers to source MicroLED HUD modules. FCC equipment authorization rules extend certification cycles for transmitter-integrated displays. Austin and Phoenix host pilot production facilities where tier-1 suppliers qualify curved panel architectures.
Germany
KBA mandates for transparent dashboard visibility privilege inorganic LED architectures in premium electric vehicle platforms. REACH substance restrictions enforced by ECHA reshape phosphor and solder material selections for European-bound shipments. Stuttgart and Munich anchor cockpit integration engineering where AEC-Q100 and IEC 62341 dual certification extends qualification timelines.
Japan
METI regulations for automotive display visibility accelerate OEM procurement of transparent dashboard configurations. JIS standards govern industrial display deployments in factory automation and medical imaging applications. Nagoya and Osaka host tier-1 cockpit integrators rewriting RFQ templates to prioritize 10-year operational lifespans.
Taiwan
Hsinchu Science Park concentrates gallium-nitride epitaxy wafer supply where dedicated nitride capacity expansion compresses lead times for display backplane integration. Foundry-dependent manufacturers face capital-intensity divergence from vertically integrated competitors. Taichung and Tainan host mass transfer equipment pilots where laser-induced forward transfer methods displace mechanical pick-and-place.
China
GB energy efficiency standards enforced by SAMR establish thresholds that privilege MicroLED luminance performance in public procurement tenders. Dual carbon goals accelerate display technology transitions in state-backed infrastructure projects. Beijing and Shenzhen host panel assembly operations where domestic backplane IC design reduces import dependency.
Microled Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the MicroLED value chain. Vertically integrated electronics conglomerates leverage in-house semiconductor fabrication for wafer-level processing advantages, while dedicated epitaxy specialists anchor supply security through captive nitride capacity. The competitive terrain separates into three strategic archetypes: conglomerate integrators, pure-play epitaxy houses, and architecture innovators. Dominant competitive moves include backward integration into gallium-nitride materials and strategic partnerships for mass transfer yield improvement.
Within the conglomerate integrator tier, Samsung Electronics Co., Ltd and Sony Corporation occupy positions that exemplify scale-driven ecosystem control. PlayNitride represents the pure-play epitaxy archetype with dedicated nitride capacity concentration. Aledia anchors the architecture innovation vector through silicon-nanowire approaches that reduce transfer-step complexity. These three players collectively illustrate how competitive positioning fragments across technology, cost, and supply security dimensions.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd |
| Sony Corporation |
| Apple Inc. |
| LG Display Co., Ltd |
| BOE Technology Group Co., Ltd |
| AU Optronics Corp. |
| PlayNitride |
| Aledia |
| X-Celeprint |
| Others |
Value Chain & Pricing Dynamics
Wafer lead times extending beyond 16 weeks for gallium-nitride epitaxy layers compress foundry margins and amplify pricing power for Taiwan-based suppliers serving automotive cockpit integrators in Germany and Japan.
Pricing Analysis
Configured-to-order cockpit displays for premium electric vehicle platforms command spreads exceeding standard digital signage panels by multiples reflecting AEC-Q100 certification costs and 10-year operational lifespan guarantees. Project-based contracting dominates automotive procurement while transactional spot purchasing governs commercial signage volumes. Price differentiation hinges on dual certification status and volume scale, with METI-compliant modules from Japan's tier-1 integrators capturing premiums over uncertified alternatives. Cost compression in standard-resolution tiles intensifies as Chinese panel assemblers expand domestic backplane IC capacity. Residential television buyers exhibit highest price sensitivity, deferring to mature OLED alternatives where MicroLED premiums exceed perceptible quality deltas.
Supply Chain Analysis
Sapphire substrate supply from Russia and synthetic crystal growth facilities in the United States constitutes a chokepoint where raw material pricing volatility propagates through gallium-nitride epitaxy operations. Manufacturing concentrates in Taiwan, South Korea, and China, with Hsinchu Science Park anchoring nitride wafer output. The supply chain draws from indium-gallium-zinc oxide sputtering targets, rare-earth phosphor dopants, and CMOS backplane wafers. Single-source vulnerability around laser-induced forward transfer equipment from German and Japanese vendors threatens capacity expansion timelines. Distribution runs through tier-1 automotive cockpit integrators and display foundry direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technician pools for sub-50-micrometer die placement remain thinner than equipment installation schedules require, creating persistent bottlenecks for mass transfer yield improvement and chiplet bonding qualification.
For Market Incumbents: Compound captive nitride capacity advantages at Hsinchu Science Park with backward integration into sapphire substrate supply to defend against price volatility in raw material markets. Prioritize AEC-Q100 pre-certification investments before IEC 62341 dual qualification timelines extend competitive windows for emerging entrants. Lock long-term offtake agreements with automotive OEMs in Germany and Japan before RFQ templates solidify around 10-year lifespan specifications. For New Entrants and Emerging Players: Post-warranty service networks for embedded automotive installations represent a service-layer gap where incumbents under-serve, creating white-space for independent technical service organizations. Target medical imaging applications in Germany and Japan where color accuracy specifications exceed incumbent LCD performance and procurement committees lack established MicroLED vendor relationships. Pursue silicon-nanowire architecture licensing to bypass capital-intensive pick-and-place transfer steps and compress qualification timelines for mid-scale panel production. For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because gallium-nitride epitaxy expertise and mass transfer yield improvement capabilities concentrate in undervalued pure-play specialists outside conglomerate structures. Acquisition target archetypes include dedicated nitride foundries with automotive qualification pipelines and laser transfer equipment developers with pilot-scale validation data. Monitor NHTSA rulemaking timelines for HUD visibility standards as the signal indicating accelerated procurement velocity from Detroit automakers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sapphire Substrate Supply | Captive raw material sourcing insulates margins from aluminum oxide wafer price volatility affecting foundry economics. |
| Laser-Induced Forward Transfer Equipment Scale-Up | Displacement of mechanical pick-and-place compresses capital payback periods for tier-one display manufacturers. |
| Dual Certification Pre-Investment | Early AEC-Q100 and IEC 62341 qualification locks supplier status before automotive RFQ templates finalize. |
| Silicon-Nanowire Architecture Licensing | Elimination of transfer steps reduces capital intensity for entrants targeting mid-scale medical and signage applications. |
| Post-Warranty Service Network Buildout | Embedded automotive installations with 10-year lifespans create recurring revenue streams from technical support contracts. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with epitaxy process engineers, automotive tier-1 procurement directors, display foundry operations managers, and regulatory compliance specialists; and secondary validation through SAMR GB standard filings, NHTSA rulemaking dockets, ECHA REACH substance registrations, and SEC disclosures from vertically integrated electronics conglomerates. Bottom-up capacity modeling across Hsinchu Science Park foundries triangulated against top-down automotive procurement forecasts.
Across the analysis window, projections integrated product type segmentation by certification burden, end-user segmentation by procurement scale, and installation type segmentation by thermal management complexity. CAGRs derived from wafer throughput expansion curves, mass transfer yield improvement trajectories, and automotive platform adoption timelines. Forecast inputs included gallium-nitride epitaxy capacity buildout schedules and laser transfer equipment installation pipelines.
Forecasts assume regulatory continuity in NHTSA visibility standards, METI automotive display rules, and ECHA REACH substance restrictions; material policy shifts would require re-modeling procurement velocity assumptions. Practitioners should keep alternative scenarios live as OLED burn-in improvement claims and quantum dot enhancement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Middle East LED Lighting Market
LED
UK Outdoor LED Lighting Market
LED
UK Indoor LED Lighting Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Surface Mount PLCC Leds Market
LED
China Outdoor LED Lighting Market
LED
China Indoor LED Lighting Market
LED
LED Display Market
LED
LED Panel Light Drivers Market
LED
LED Light Market
LED
LED Services Market
LED
Asia Pacific Indoor LED Lighting Market
LED
Japan LED Lighting Market
LED
Arrow LED Displays Market
LED
LED Display Control Card Market
LED
LED Modules and Light Engines Market