
 Organic Light Emitting Diode (OLED) Market | 2026-2036
Organic Light Emitting Diode (OLED) Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Light Emitting Diode (OLED) Market Analysis
The EU Green Deal is pivoting commercial lighting procurement toward energy-efficient display technologies across member states. Samsung Display leverages vertical integration to sustain manufacturing scale in South Korea. LG Display anchors premium television panel supply through differentiated white OLED architectures.
Organic Light Emitting Diode refers to a self-emissive display technology employing organic compounds that emit light when electric current passes through emissive and conductive layers deposited between electrodes, with active matrix configurations using thin-film transistors for pixel control. The technology eliminates backlight requirements, enabling sub-millimeter form factors and superior contrast ratios for visual applications. Flexible OLEDs command expanding share in smartphone and wearable segments where mechanical bend tolerance determines design freedom. Transparent OLEDs occupy nascent but growing positions in commercial signage and automotive head-up displays where see-through functionality creates novel interface possibilities. Phosphorescent OLEDs lead efficiency metrics through triplet harvesting, though fluorescent variants persist in cost-sensitive applications.
REACH compliance in Europe and EPA energy efficiency guidelines in the United States constrain hazardous substance use and set minimum performance thresholds for display products entering respective markets. China's GB standards and NMPA certification requirements govern domestic panel quality and electromagnetic compatibility for consumer electronics deployment. Stakeholders must monitor evolving material substitution timelines as phosphorescent emitter complexes face supply concentration and intellectual property licensing constraints.
Market Dynamics
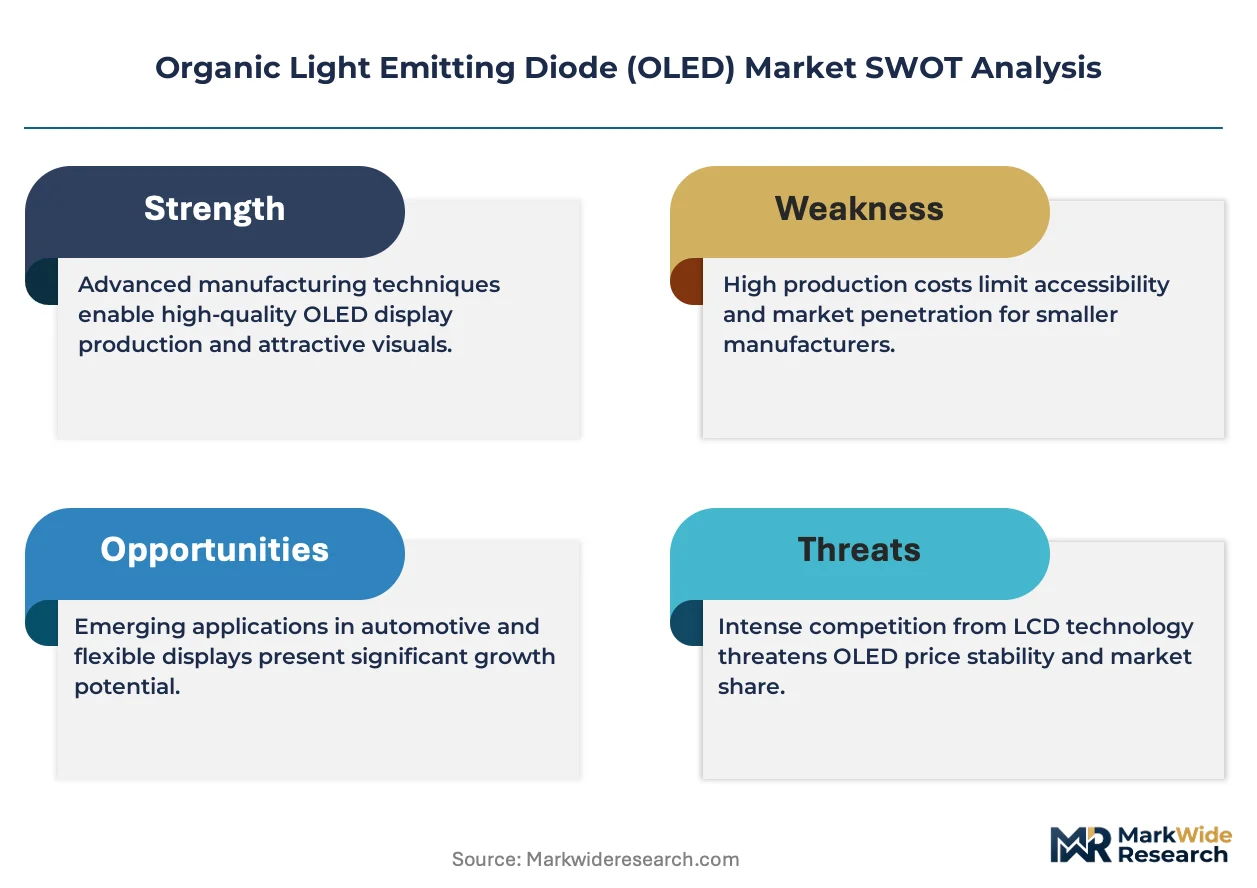
Automotive electrification and the EU Green Deal's phased lighting restrictions are forcing rapid substitution toward self-emissive display technologies across transportation and commercial building sectors. Supply concentration in East Asian panel fabrication is reshaping procurement geography for European and North American integrators.
Growth Catalysts
- EU Green Deal phased restrictions:Mandatory efficiency thresholds under the F-Gas Regulation and building energy codes are accelerating replacement of conventional lighting in commercial real estate across Germany, France, and Italy.
- Automotive interior display expansion:Electric vehicle platforms are integrating curved and flexible panels for instrument clusters and center consoles, with tier-one suppliers scaling dedicated OLED production lines.
- Phosphorescent emitter efficiency gains:Triplet harvesting architectures are extending operational lifetime in high-brightness applications, reducing thermal management requirements for signage and architectural lighting.
Market Restraints
- Input cost volatility:Iridium and platinum group metal prices in phosphorescent emitter complexes create margin pressure for premium panel tiers.
- Supply concentration risk:Vacuum thermal evaporation equipment and fine metal mask production are concentrated among Japanese and South Korean capital equipment suppliers.
- Technical limitation:Blue emitter degradation rates remain 3-4x higher than red and green, constraining full-color display lifetime in commercial signage applications.
Strategic Opportunities
- Transparent display white space:Head-up display integration in automotive windshields and retail storefront applications in South Korea and Japan represent underpenetrated volume.
- Microdisplay convergence:Silicon backplane integration with OLED emitters is enabling augmented reality headset form factors previously unattainable with liquid crystal on silicon.
- India PLI scheme incentives:Domestic panel assembly and component sourcing mandates are creating localized supply chain entry points for display module integrators.
Industry Challenges
- Skill scarcity in vapor deposition:Thin-film encapsulation and organic layer stack engineering require specialized cleanroom technicians with 5-7 year training horizons.
- Certification timeline compression:REACH substance authorization and EPA energy star qualification cycles are extending product launch windows for new emitter material formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Light Emitting Diode (OLED) Market |
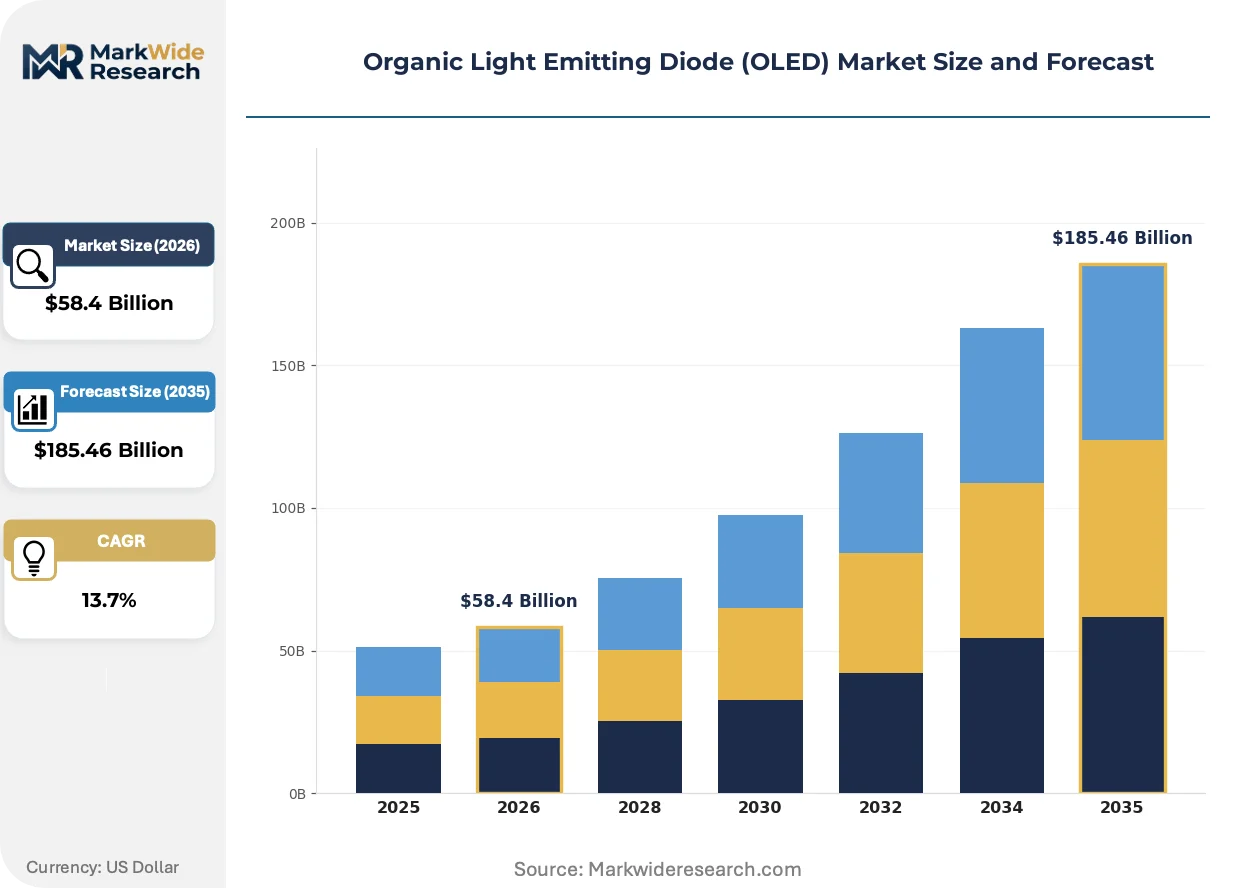
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $185.46 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid OLEDs, Flexible OLEDs, Transparent OLEDs, RGB OLEDs Application: Televisions, Smartphones, Monitors, Lighting Technology: Phosphorescent OLEDs, Fluorescent OLEDs, White OLEDs, Dual-Emissive OLEDs End User: Residential, Commercial, Industrial, Automotive |
| Companies Covered | Samsung Display, LG Display, BOE Technology, AU Optronics, Universal Display Corporation, Sony Corporation, Tianma Microelectronics, Visionox, Osram, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Light Emitting Diode (OLED) Market Emerging Trajectories
Quantum dot enhancement layers and tandem stack architectures are compressing performance gaps between OLED and emerging microLED technologies. Material science advances in delayed fluorescence emitters are rewriting efficiency assumptions without iridium dependency.
Tandem stack architectures with dual emissive layers are rewriting luminance efficiency benchmarks for premium television and professional monitor segments. Samsung Display and LG Display are commercializing these structures for 2024-2025 product cycles, compressing the power consumption gap with miniLED backlit liquid crystal alternatives.
REACH authorization requirements for new organometallic compounds are extending material qualification timelines for European market entry. The European Chemicals Agency's evolving substance restriction lists are forcing reformulation of hole transport layers, with display manufacturers accelerating halogen-free alternative development for 2026 compliance deadlines.
Automotive OEMs are consolidating display procurement under single-source agreements with tier-one integrators, displacing the historical multi-vendor panel sourcing model. This concentration is visible in German premium vehicle programs where Continental and Bosch are capturing full cockpit display contracts, compressing direct panel supplier relationships and shifting specification authority upstream.
Organic Light Emitting Diode (OLED) Market Segmentation
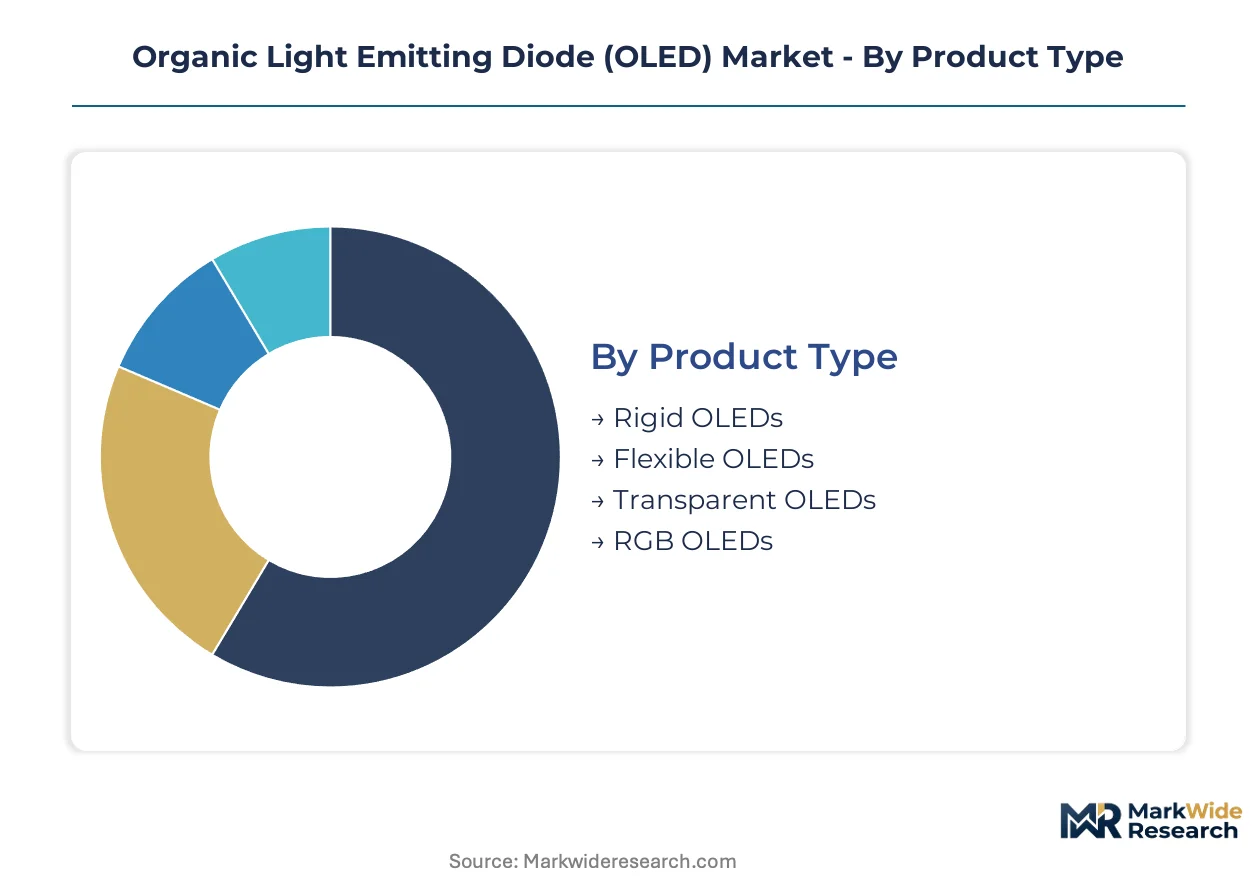
Technology architecture and form factor specifications determine manufacturing investment intensity and end-use viability across OLED deployment. Segment boundaries reflect divergent material requirements, encapsulation complexity, and thermal management protocols that shape procurement economics.
Product Type:
Mechanical flexibility and substrate composition define the core specification axis for panel differentiation.
- Flexible OLEDs:Polyimide substrate architectures enable dynamic bend radii below 5mm for foldable smartphones and curved automotive clusters. South Korean manufacturers dominate capacity expansion for this segment as Chinese fabs in Chengdu and Hefei ramp polymer deposition lines.
- Rigid OLEDs:Glass substrate construction maintains structural stability for television panels and professional monitors where flat-plane precision outweighs mechanical adaptability. LG Display anchors supply for premium television tiers through differentiated white OLED architectures on rigid backplanes.
- Transparent OLEDs:Partially transmissive anode/cathode stacks enable see-through display functionality for retail signage and automotive head-up applications.
- RGB OLEDs:Discrete red-green-blue subpixel patterning delivers color purity for broadcast reference monitors and medical imaging displays.
Mature deployment sits with rigid OLEDs. Newer deployment is concentrated in flexible OLEDs.
Application:
Display size and brightness specification requirements segment procurement patterns across consumer and professional use cases.
- Smartphones:High pixel density requirements above 500 ppi drive fine metal mask precision and vapor deposition control for sub-6-inch panels. Samsung Display leverages in-house production of driver integrated circuits to sustain manufacturing scale for flagship device programs.
- Televisions:Large-area deposition uniformity challenges and thermal dissipation requirements distinguish premium panel tiers from commercial-grade alternatives. Tandem stack architectures with dual emissive layers are compressing power consumption gaps with miniLED backlit liquid crystal alternatives.
- Monitors:Color accuracy specifications for creative professional workflows demand factory calibration protocols and extended gamut coverage.
- Lighting:Luminous efficacy targets and operational lifetime metrics differentiate architectural illumination panels from display applications.
Volume concentration favors smartphones. Margin expansion is steepest in televisions.
Technology:
Emitter excitation mechanism and layer stack architecture determine efficiency benchmarks and material cost structures.
- Phosphorescent OLEDs:Triplet harvesting enables internal quantum efficiency approaching unity through iridium-based emitter complexes. Supply concentration in phosphorescent emitter complexes faces intellectual property licensing constraints and platinum group metal price volatility.
- Dual-Emissive OLEDs:Tandem configurations with stacked emissive layers multiply luminance output per watt for premium television and professional monitor segments. Samsung Display and LG Display are commercializing these structures for upcoming product cycles.
- Fluorescent OLEDs:Singlet emission pathways persist in cost-sensitive applications where material substitution outweighs efficiency optimization.
- White OLEDs:Single-color emission with color filter arrays simplifies manufacturing for large-area television panels.
Phosphorescent architectures anchor premium tiers. Dual-emissive configurations are gaining share fastest in professional segments.
End User:
Procurement authority and specification authority diverge sharply between direct consumer markets and industrial integration channels.
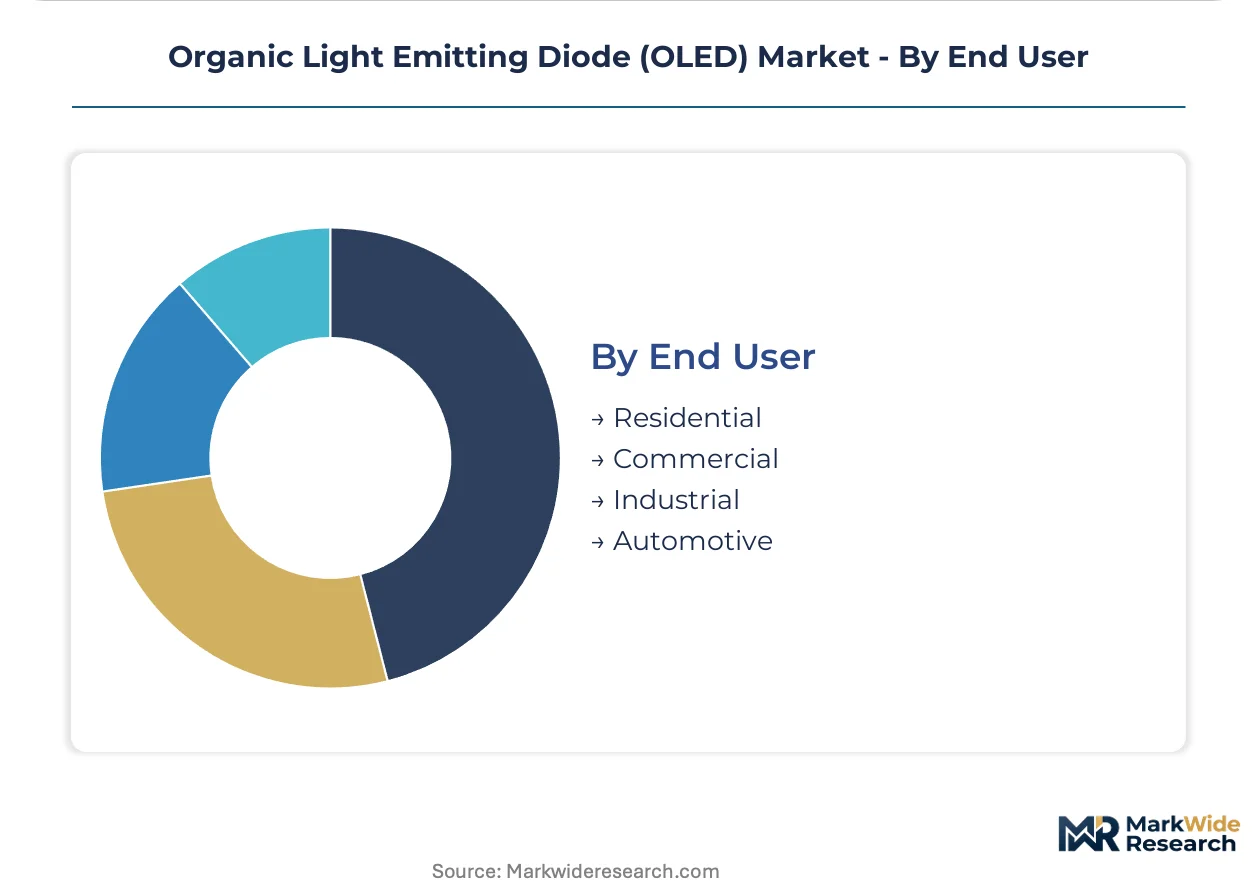
- Automotive:Electric vehicle platforms are integrating curved and flexible panels for instrument clusters and center consoles, with tier-one suppliers scaling dedicated production lines. German premium vehicle programs are consolidating display procurement under single-source agreements with Continental and Bosch.
- Commercial:Retail signage and corporate display networks prioritize operational longevity and remote fleet management capabilities.
- Residential:Consumer television and lighting procurement responds to energy efficiency labeling and price-positioning relative to liquid crystal alternatives.
- Industrial:Harsh environment specifications and continuous operation requirements drive encapsulation robustness for factory automation interfaces.
Specification authority is fragmenting across automotive. Direct procurement dominates residential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Panel fabrication concentrates in East Asia while consumption spreads across North America and Europe. Manufacturing scale advantages in South Korea and China create supply dependencies for downstream integrators in Germany and the United States. Regulatory pressure in the European Union accelerates substitution timelines for energy-inefficient display technologies.
South Korea
Domestic display fabs supply premium smartphone panels and television screens to global electronics brands. The Ministry of Trade, Industry and Energy (METI) channels R&D subsidies into next-generation emitter materials and tandem stack architectures. Samsung Display operates manufacturing complexes in Asan and Tangjeong, scaling production of flexible substrates for foldable device programs.
China
Domestic panel demand from smartphone OEMs and emerging automotive display programs absorbs expanding local capacity. GB standards and NMPA certification govern electromagnetic compatibility and quality thresholds for consumer electronics deployment. BOE Technology and Visionox are enlarging fabrication bases in Chengdu and Hefei, targeting flexible OLED output for both domestic consumption and export markets.
Japan
Precision equipment and materials suppliers anchor the upstream value chain for vacuum thermal evaporation systems and fine metal masks. METI coordinates industry consortia addressing phosphorescent emitter efficiency and operational lifetime extension. Manufacturing clusters in Chubu and Kansai regions concentrate capital equipment production for export to Korean and Chinese panel fabs.
Germany
Automotive OEM procurement for curved instrument clusters and center console displays drives specialized panel demand from tier-one integrators. The EU Green Deal and F-Gas Regulation impose mandatory efficiency thresholds accelerating LED and OLED substitution in commercial lighting. Continental and Bosch in Baden-Württemberg and Bavaria are consolidating cockpit display contracts under single-source agreements, compressing direct supplier relationships.
United States
Consumer electronics procurement and professional monitor demand sustain import volumes despite minimal domestic panel fabrication. EPA energy efficiency guidelines and FCC electromagnetic compatibility rules constrain product entry and set minimum performance thresholds. Technology development clusters in California and Texas focus on microdisplay architectures for augmented reality applications, leveraging silicon backplane integration with OLED emitters.
Organic Light Emitting Diode (OLED) Market Vendor Landscape
The competitive structure tilts toward vertically integrated display specialists with captive materials development and in-house driver IC production. Korean and Chinese manufacturers command fabrication scale, while Japanese suppliers concentrate precision equipment and emitter materials. Two archetypes dominate: integrated panel makers controlling full stack production, and materials specialists licensing phosphorescent emitter complexes. Capacity expansion and strategic technology licensing constitute the primary competitive vectors.
Among Korean integrated manufacturers, Samsung Display and LG Display exemplify the scale-driven archetype with end-to-end control over substrate processing, organic layer deposition, and module assembly. BOE Technology represents the Chinese challenger model, expanding through state-supported capacity buildouts in multiple provincial hubs. Universal Display Corporation occupies the materials-specialist position, anchoring intellectual property licensing for phosphorescent emitter technologies without direct panel manufacturing exposure.
| Leading Market Players |
|---|
| Samsung Display |
| LG Display |
| BOE Technology |
| AU Optronics |
| Universal Display Corporation |
| Sony Corporation |
| Tianma Microelectronics |
| Visionox |
| Osram |
| Others |
Supply Flow & Price Mechanics
Tandem stack commercialization in premium television panels is compressing power consumption benchmarks while concentrating production investment among Korean and Chinese fabs with captive emitter development. This dual-layer architecture simultaneously raises manufacturing complexity and locks in pricing power for vertically integrated producers able to source phosphorescent complexes internally.
Pricing Analysis
Margin tightening in premium television tiers reflects iridium price volatility in phosphorescent emitter complexes and the capital intensity of vacuum thermal evaporation equipment. Three-tier pricing structure across premium, standard, and economy levels separates tandem-stack panels with dual emissive layers from single-stack alternatives and fluorescent-based economy grades. Pricing pressure intensifies in smartphone flexible substrates as Chinese fabs in Chengdu and Hefei add polymer deposition capacity. Automotive integrators exhibit lowest price sensitivity due to specification authority consolidation under Continental and Bosch single-source agreements.
Supply Chain Analysis
Refurbishment flows for decommissioned deposition equipment and recovered iridium from spent emitter complexes are creating secondary supply channels for emerging fabs in India under PLI scheme incentives. Manufacturing concentration rests on South Korea, China, and Japan for panel fabrication, precision equipment, and fine metal mask production respectively. Raw material dependencies draw from iridium and platinum group metals for phosphorescent complexes, polyimide substrates for flexible architectures, and photoresists for patterning. Single-source vulnerability in vacuum thermal evaporation equipment from Japanese suppliers creates chokepoint exposure. Distribution runs through tier-one automotive integrators and direct procurement contracts with consumer electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around fabrication scale and captive materials development as phosphorescent emitter IP licensing constraints and capital equipment scarcity force sub-scale players toward exit.
For Market Incumbents: Extend tandem stack production capacity in Asan and Tangjeong to widen the efficiency gap with single-layer alternatives. Secure long-term offtake agreements for iridium complexes through backward integration into emitter material production or exclusive supplier partnerships. Defend against Chinese challenger expansion by accelerating halogen-free hole transport layer qualification ahead of REACH substance authorization deadlines. For New Entrants and Emerging Players: Capture transparent display white space in automotive head-up display programs where see-through functionality creates specification differentiation. Target India PLI scheme incentives for domestic panel assembly and component sourcing mandates as the most penetrable geography with localized procurement requirements. Pursue silicon backplane microdisplay convergence for augmented reality headset applications as the go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by Korean or Chinese integrated manufacturers seeking phosphorescent emitter IP portfolios and specialized cleanroom engineering teams. Long-term viability favors materials specialists with iridium-complex licensing revenue streams over capital-intensive panel fabs facing margin compression. Watch for delayed fluorescence emitter commercialization as the inflection signal that could rewrite efficiency assumptions without platinum group metal dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Tandem Stack Capacity Expansion | Dual emissive layer deployment compresses power consumption gaps with miniLED alternatives in premium television tiers. |
| Phosphorescent Emitter Backward Integration | In-house iridium complex production reduces supply concentration risk and margin exposure to platinum group metal volatility. |
| Halogen-Free Transport Layer Development | REACH substance authorization compliance for 2026 deadlines secures European market entry for new material formulations. |
| India PLI Scheme Manufacturing Localization | Domestic panel assembly and component sourcing mandates create supply chain entry points for display module integrators. |
| Silicon Backplane Microdisplay Partnership | OLED emitter integration with CMOS substrates enables augmented reality headset form factors for professional and consumer segments. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with display panel procurement managers, vacuum equipment engineers, phosphorescent materials R&D directors, and automotive tier-one supplier program managers were cross-validated against ECHA substance authorization databases, EPA energy efficiency guidelines, and NMPA certification records. Bottom-up capacity buildout tracking across Chengdu, Hefei, Asan, and Tangjeong complexes was reconciled with top-down consumption modeling for smartphone, television, and automotive applications.
Data-stream reconciliation between production volume disclosures and end-use shipment records shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology architecture, form factor flexibility, emitter excitation mechanism, and end-use application intensity. CAGRs were derived from installed capacity trajectories, substitution elasticity estimates for EU Green Deal compliance timelines, and price elasticity assumptions for premium versus commercial grade tiers. Forecast inputs incorporated phosphorescent emitter lifetime extension curves and fine metal mask precision yield rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to iridium supply concentration, delayed fluorescence emitter commercialization timelines, and REACH substance restriction evolution. Forecasts reflect documented assumptions on technology substitution rates and regulatory enforcement intensity. Practitioners should monitor ECHA substance authorization decisions, India PLI scheme disbursement patterns, and automotive single-source procurement consolidation for early signals of structural shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Driver Market
LED
Middle East LED Lighting Market
LED
North America LED Lighting Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
Global Chip Scale Package (CSP) LED Market
LED
LED Light Bar Market
LED
Architectural LED Products Market
LED
LED Flip Chip Market
LED
France LED Lighting Market
LED
UK Outdoor LED Lighting Market
LED
LED Light Market
LED
Xenon Market
LED
US LED Downlight Market
LED
France Outdoor LED Lighting Market
LED
Japan Outdoor LED Lighting Market
LED
Microled Market