
 Saudi Arabia LED Lights Market | 2026-2036
Saudi Arabia LED Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia LED Lights Market Intelligence
Gallium nitride substrates displacing conventional silicon carbide bases is recalibrating lumen-per-watt economics across mid-power packages. Philips Lighting Saudi Arabia Company Limited leverages captive semiconductor sourcing to sustain margin structure in premium commercial projects. Osram Middle East FZE anchors its position through specialized horticultural and architectural wavelength portfolios. Samsung Electronics Saudi Arabia Limited competes on vertically integrated chip-to-fixture control across smart home ecosystems.
LED lights are solid-state semiconductor devices that emit visible light when electrical current passes through a gallium-based p-n junction, typically operating at efficacy thresholds exceeding 100 lumens per watt in qualified products. Their primary commercial purpose is to replace legacy incandescent and fluorescent sources with directional, instant-on illumination that reduces thermal load and maintenance cycles in conditioned and unconditioned spaces. Panel formats dominate volume in commercial fit-outs where recessed modular grids prevail, while smart technology layers command expanding margin pools through connected commissioning and energy management protocols. Downlight and tube categories occupy mature replacement cycles in existing building stock across the Kingdom's major metropolitan zones.
SASO 2870 minimum energy performance standards and the Saudi Energy Efficiency Center's product registration requirements shape demand by filtering non-compliant imports from distribution channels. The Saudi Building Code and municipal green building guidelines in Riyadh and Jeddah embed LED specifications into new construction permitting, reinforcing specification lock-in for contractors and developers. Stakeholders must monitor enforcement granularity at port-of-entry inspection points and evolving efficacy tier thresholds that could strand inventory held in bonded warehousing near Dammam and Jeddah.
Market Dynamics
Gallium nitride substrates are compressing lumen-per-watt economics across mid-power LED packages, forcing fixture manufacturers to recalibrate procurement strategies around semiconductor sourcing rather than legacy luminaire assembly.
Growth Catalysts
- SASO 2870 enforcement:The Saudi Energy Efficiency Center's product registration requirements filter non-compliant imports from distribution channels, compressing demand toward certified luminaires and accelerating replacement cycles in commercial stock.
- Municipal street lighting programs:Riyadh and Jeddah are accelerating fixture replacement cycles, creating concentrated demand spikes for high-bay and roadway-optimized packages.
- Panel format dominance:Recessed modular grids in hospitality and healthcare construction across the Eastern Province and Mecca Region disproportionately specify flat-panel luminaires over legacy troffers.
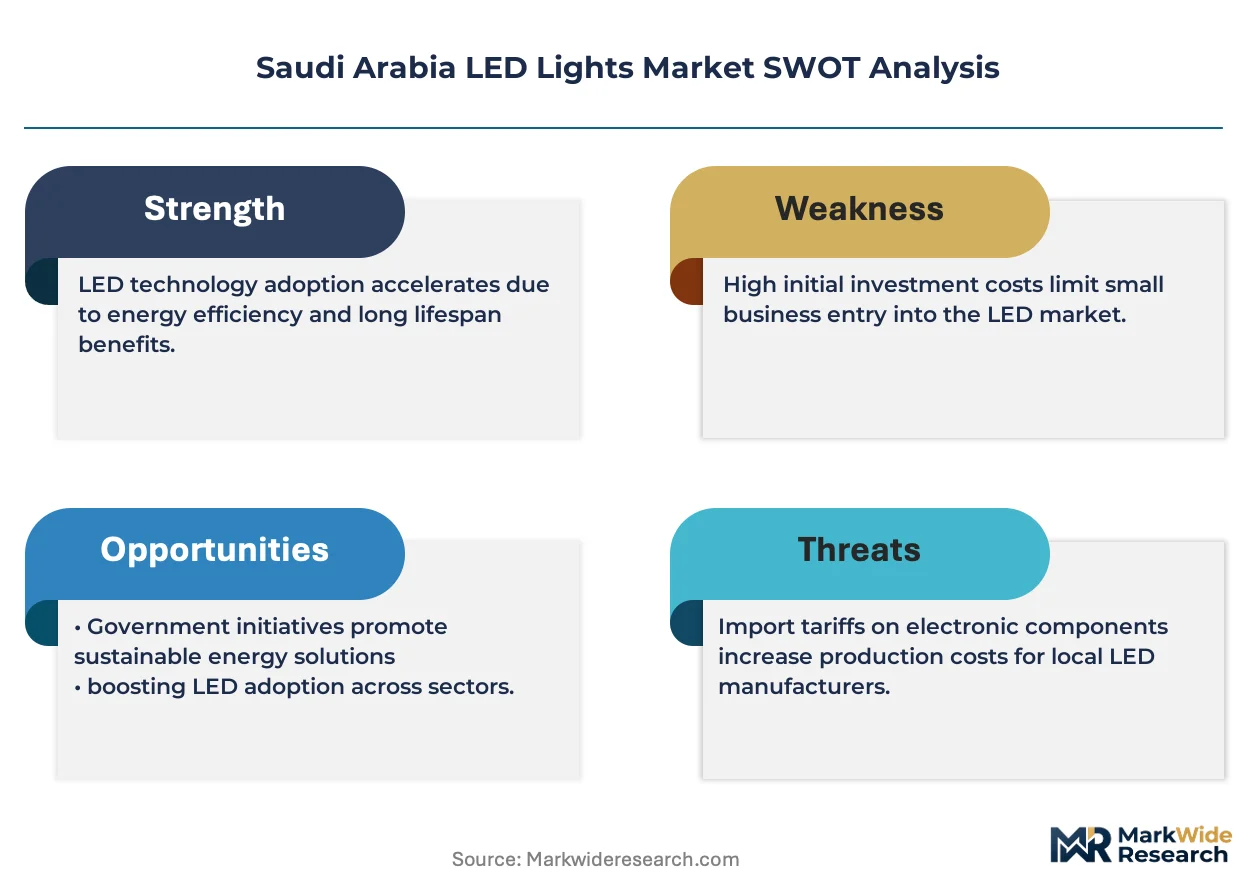
Market Restraints
- Semiconductor supply concentration:Gallium nitride substrate production concentrates among a limited supplier base, exposing fixture assemblers to input volatility and allocation constraints.
- Technical efficacy ceilings:Mid-power packages face thermal dissipation limits that constrain lumen density in high-ambient applications like Dammam industrial zones.
- Regulatory friction at port-of-entry:SASO 2870 inspection granularity at Jeddah and Dammam bonded warehousing creates inventory stranding risk for non-conforming shipments.
Strategic Opportunities
- Smart technology convergence:Connected commissioning and energy management protocols are commanding expanding margin pools through integration with building automation systems in Riyadh commercial towers.
- Horticultural wavelength specialization:Controlled-environment agriculture in the Qassim Region creates demand for tunable-spectrum fixtures optimized for photosynthetic photon flux density.
- Downlight replacement acceleration:Mature building stock across Jeddah's central business district presents concentrated retrofit opportunity as fluorescent tube cycles expire.
Industry Challenges
- Certification timeline compression:SASO 2870 efficacy tier evolution requires continuous product re-qualification, straining R&D bandwidth for smaller fixture manufacturers.
- Integration complexity with legacy controls:Smart fixture deployment in existing Saudi building stock faces interoperability friction with incumbent 0-10V and DALI infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia LED Lights Market |
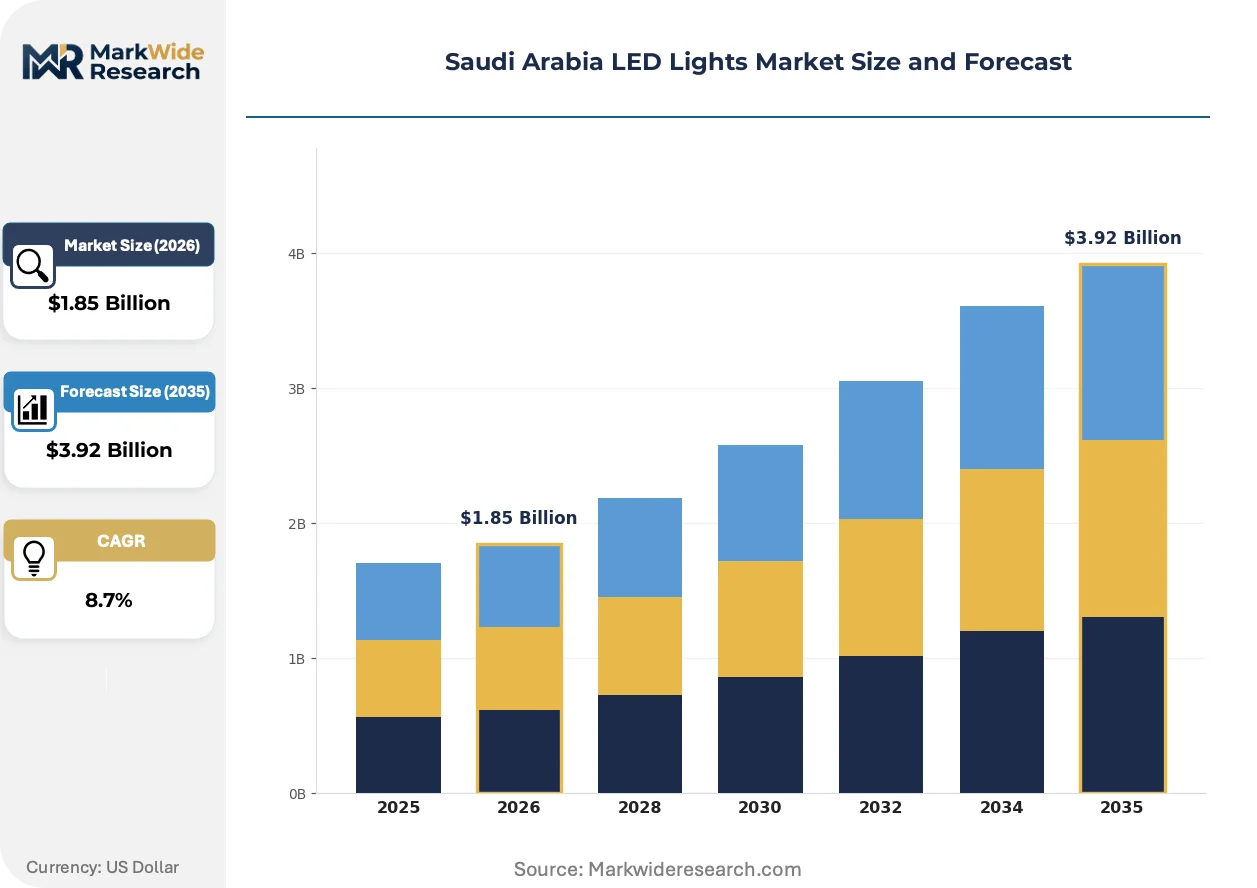
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Tubes, Panels, Downlights Technology: Smart, Dimmable, RGB, Standard Application: Residential, Commercial, Industrial, Outdoor End User: Homeowners, Businesses, Contractors, Government |
| Companies Covered | General Electric Saudi Arabia, Zumtobel Group Middle East FZE, Philips Lighting Saudi Arabia Company Limited, Dialight Saudi Arabia Limited, Samsung Electronics Saudi Arabia Limited, Osram Middle East FZE, Hubbell Incorporated – Saudi Arabia, Panasonic Lighting Saudi Arabia Co. Ltd., Acuity Brands Lighting Saudi Arabia LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia LED Lights Market Strategic Shifts & Innovations
Semiconductor substrate evolution and enforcement tightening are rewriting competitive positioning across the Saudi fixture value chain, compressing margins for assemblers while expanding capture for chip-scale specialists.
Gallium nitride substrates are rewriting lumen-per-watt economics in mid-power LED packages by enabling higher current density with reduced thermal resistance. Hospitality and healthcare contractors in the Eastern Province are specifying GaN-based fixtures for recessed modular grids at accelerating pace. This substrate shift is compressing demand toward vertically integrated suppliers capable of captive semiconductor sourcing.
SASO 2870 minimum energy performance standards are filtering non-compliant imports from Saudi distribution channels and embedding LED specifications into new construction permitting. The Saudi Building Code and municipal green building guidelines in Riyadh and Jeddah reinforce specification lock-in for contractors and developers. Panel and downlight categories face the most acute compliance pressure as efficacy thresholds ratchet upward.
Connected commissioning protocols are displacing traditional fixture-only procurement in premium commercial verticals across the Kingdom. Building automation integrators in Riyadh and Jeddah are bundling smart lighting with energy management dashboards, unbundling after-sales service from hardware margins. This behavioral shift is most visible in hospitality and healthcare construction where operational technology budgets now eclipse standalone lighting allocations.
Saudi Arabia LED Lights Market Segmentation
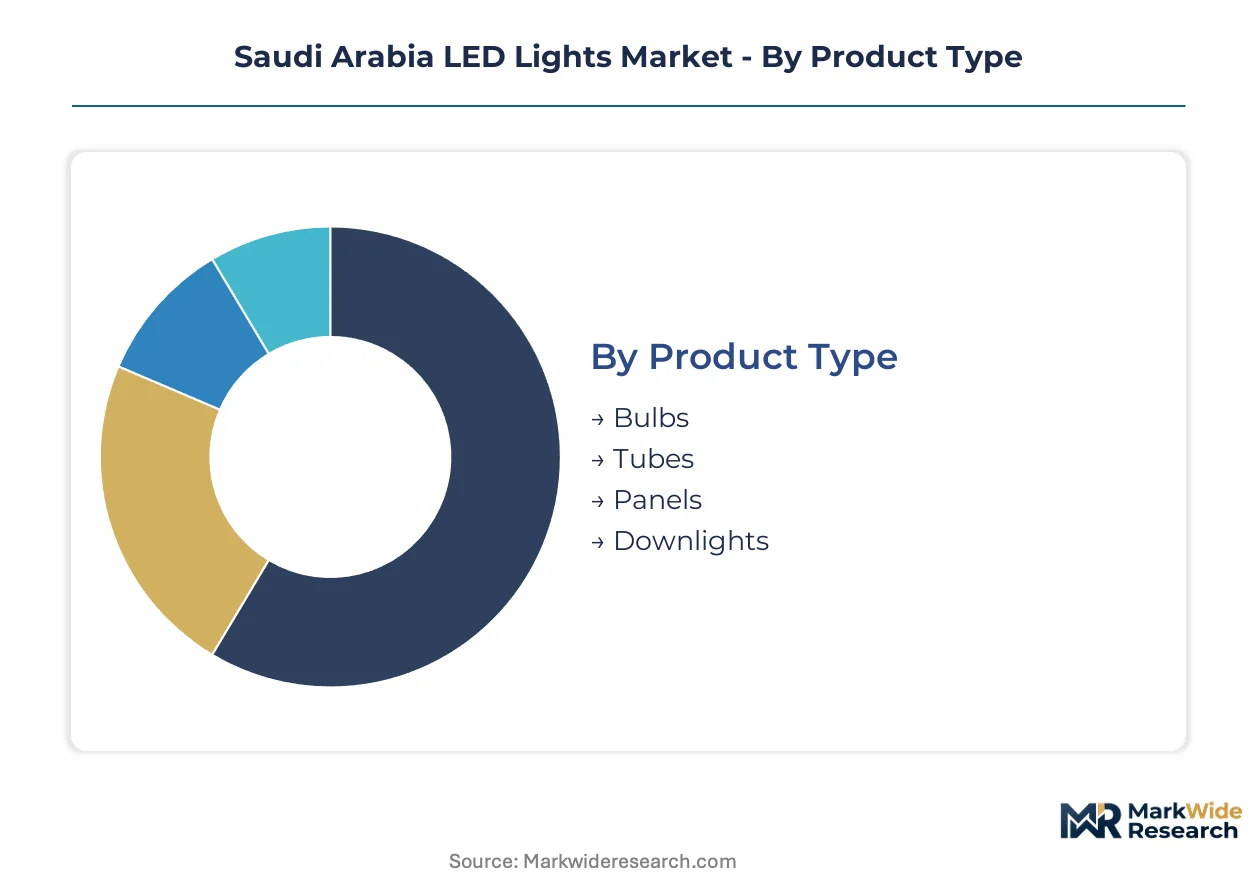
Semiconductor substrate evolution and SASO 2870 enforcement are fragmenting procurement patterns across the Saudi fixture value chain. Specification power now concentrates with contractors and government procurers who control certification compliance and connected commissioning budgets.
Product Type:
Supply concentration among gallium nitride substrate producers is forcing fixture assemblers to specialize around form factors that optimize lumen density and thermal management.
- Panels:Recessed modular grids in Eastern Province hospitality and Mecca Region healthcare construction specify flat-panel luminaires for uniform illumination and reduced ceiling void depth. Riyadh commercial towers are accelerating panel procurement as SASO 2870 efficacy tiers compress demand toward high-efficacy certified products.
- Downlights:Compact directional fixtures with integrated heat sinks dominate retrofit cycles in Jeddah's central business district as fluorescent downlight generations expire. Dammam bonded warehousing operators face inventory stranding risk when efficacy thresholds ratchet between import cycles.
- Bulbs:Retrofit A-shape and globe formats serve residential replacement demand in Riyadh and Jeddah metropolitan zones with instant-on operation and reduced thermal load.
- Tubes:Linear replacements for fluorescent troffers occupy mature commercial stock renovation cycles across government and educational facilities in the Kingdom's major urban centers.
Today's leader: Panels. Tomorrow's challenger: Downlights.
Technology:
Cost tier stratification is emerging as connected commissioning protocols capture expanding margin pools in premium commercial verticals.
- Smart:Networked fixtures with embedded sensors and wireless commissioning interfaces command premium positioning in Riyadh commercial towers where building automation integrators bundle lighting with energy management dashboards. Interoperability friction with legacy 0-10V and DALI infrastructure constrains retrofit deployment in existing Saudi building stock.
- Dimmable:Phase-cut and 0-10V control compatibility serves hospitality specification requirements across Eastern Province construction projects where operational technology budgets now eclipse standalone lighting allocations.
- RGB:Tunable color-mixing arrays address architectural accent and entertainment venue applications with wavelength precision for dynamic scene programming.
- Standard:Fixed-output fixtures without control interfaces occupy price-sensitive residential and basic commercial replacement cycles with minimal specification friction.
Smart technology is climbing the fastest. Standard formats are ceding share to control-capable alternatives.
Application:
Volume concentration in municipal programs and healthcare construction is reshaping demand patterns across metropolitan zones.
- Commercial:Office towers, retail centers, and hospitality fit-outs across Riyadh and Jeddah drive specification-grade procurement with connected commissioning requirements and green building code compliance embedded in permitting.
- Outdoor:Municipal street lighting programs in Riyadh and Jeddah are accelerating fixture replacement cycles with high-bay and roadway-optimized packages for high-ambient thermal environments.
- Residential:Homeowner replacement demand concentrates in major metropolitan zones with retrofit bulb and downlight procurement driven by electricity tariff awareness and SASO 2870 retail filtering.
- Industrial:High-bay and hazardous-location fixtures face thermal dissipation limits in Dammam industrial zones where mid-power package lumen density constraints affect specification.
Commercial applications dominate current value capture. Outdoor infrastructure is expanding most quickly.
End User:
Customer type determines procurement channel access and certification compliance burden across the Saudi distribution landscape.
- Government:Municipal street lighting programs and public facility renovation across Riyadh and Jeddah concentrate demand through tender processes with SASO 2870 compliance mandatory for contract eligibility.
- Contractors:Hospitality and healthcare construction specialists in the Eastern Province and Mecca Region control specification lock-in through direct relationships with vertically integrated fixture suppliers.
- Businesses:Corporate facility managers in Riyadh commercial towers are bundling smart lighting procurement with building automation system upgrades and energy management dashboard integration.
- Homeowners:Residential purchasers in Jeddah and Riyadh metropolitan zones access LED products through retail channels filtered by SASO 2870 registration requirements at port-of-entry.
Government procurers set compliance benchmarks. Contractors control specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Eastern Province's Dammam-Jubail industrial corridor anchors Saudi Arabia's LED fixture demand through petrochemical facility retrofits and bonded warehousing concentration near port infrastructure.
Riyadh
Municipal street lighting programs and commercial tower construction drive specification-grade procurement across the capital metropolitan zone. SASO 2870 efficacy standards filter retail distribution channels through the Saudi Energy Efficiency Center's product registration requirements. The Riyadh Metro expansion and King Salman Park development concentrate high-bay and architectural fixture demand in central business district clusters.
Eastern Province
Hospitality construction along the Arabian Gulf coast and healthcare facility expansion in Dammam and Al Khobar disproportionately specify panel luminaires for recessed modular grids. The Saudi Aramco residential compound renovations and Sadara Chemical Company facility upgrades create sustained industrial lighting replacement cycles. Bonded warehousing operators near King Fahd Industrial Port face inventory compliance pressure from evolving SASO efficacy tier enforcement.
Mecca Region
Religious infrastructure modernization and hospitality construction surrounding the Grand Mosque generate concentrated demand for downlight and accent lighting categories. The Makkah Region Development Authority's green building guidelines embed LED specifications into hotel and commercial permitting processes. Jeddah's central business district fluorescent tube replacement cycles present mature retrofit opportunity as legacy generations expire.
Western Region
Red Sea coastal tourism projects and King Abdullah Economic City construction accelerate fixture procurement for mixed-use developments. The NEOM northwest corridor's smart city infrastructure plans command connected commissioning protocols with building automation integration. Taif's high-altitude residential construction drives residential bulb and downlight demand through electricity tariff awareness campaigns.
Saudi Arabia LED Lights Market Key Industry Players
Capacity expansion dominates the current landscape as vertically integrated suppliers recalibrate procurement strategies around gallium nitride substrate sourcing. The vendor base concentrates among multinational lighting specialists with captive semiconductor relationships and regional distribution infrastructure. Two strategic archetypes define positioning: chip-scale specialists leveraging upstream substrate control, and fixture assemblers specializing in form-factor optimization for Saudi construction verticals. Portfolio diversification into horticultural wavelength portfolios and smart technology layers represents the dominant competitive vector alongside geographic anchoring through Saudi-registered entities.
Among multinational lighting specialists with Middle Eastern regional structures, Philips Lighting Saudi Arabia Company Limited, Osram Middle East FZE, and Samsung Electronics Saudi Arabia Limited exemplify the integrated archetype. Philips occupies a position tied to premium commercial project specification through semiconductor sourcing advantages. Osram represents specialization around wavelength-specific applications for controlled-environment agriculture. Samsung anchors a position spanning chip-to-fixture control integration for connected home ecosystems. These three entities sit within the tier commanding expanding margin pools through smart technology convergence and SASO 2870 certification compliance.
| Leading Market Players |
|---|
| General Electric Saudi Arabia |
| Zumtobel Group Middle East FZE |
| Philips Lighting Saudi Arabia Company Limited |
| Dialight Saudi Arabia Limited |
| Samsung Electronics Saudi Arabia Limited |
| Osram Middle East FZE |
| Hubbell Incorporated – Saudi Arabia |
| Panasonic Lighting Saudi Arabia Co. Ltd. |
| Acuity Brands Lighting Saudi Arabia LLC |
| Others |
Cost & Logistics Intelligence
Government tender programs and municipal street lighting procurement in Riyadh and Jeddah anchor pricing power with volume-scale buyers who negotiate project-based contract structures. SASO 2870 certification tiers stratify fixture pricing across premium certified, standard compliant, and non-compliant economy levels, with bonded warehousing operators absorbing inventory risk from efficacy threshold ratchets.
Pricing Analysis
Gallium nitride substrate cost pass-through from Taiwan and South Korea suppliers compresses margins for fixture assemblers while expanding capture for chip-scale specialists with captive sourcing. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels differentiates on SASO 2870 registration status and after-sales commissioning bundling. Pricing pressure stems from semiconductor allocation constraints forcing spot-market premium payments for substrate access. Residential retail channels exhibit highest price sensitivity, while Riyadh commercial tower developers absorb premium positioning for smart technology integration.
Supply Chain Analysis
Dual-sourcing mandates from Saudi Energy Efficiency Center procurement guidelines require fixture manufacturers to qualify gallium nitride substrate suppliers across Taiwan, South Korea, and China production bases. The supply chain draws from sapphire wafer inputs, phosphor conversion materials, and aluminum heat sink extrusions with concentration risk in Taiwan semiconductor foundry capacity. Tariff exposure at Jeddah and Dammam port-of-entry inspection points creates logistics chokepoint vulnerability for non-conforming shipments. Distribution runs through bonded warehousing near King Fahd Industrial Port and direct contractor relationships in Eastern Province construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride substrate cost curves and smart technology premium tiers frame this market as a margin-expansion story for participants controlling upstream semiconductor access or downstream connected commissioning integration.
For Market Incumbents: Deepen captive gallium nitride sourcing relationships to defend margin structure against substrate allocation volatility from Taiwan and South Korea suppliers. Expand SASO 2870 certification bandwidth to accelerate product re-qualification cycles and strand competitor inventory in bonded warehousing. Reinforce specification lock-in with Eastern Province hospitality contractors through integrated panel luminaire and building automation system bundling. For New Entrants and Emerging Players: Horticultural wavelength specialization for Qassim Region controlled-environment agriculture offers a technology-first wedge with limited incumbent coverage. Target Jeddah central business district fluorescent downlight retrofit cycles where legacy tube expiration creates specification-neutral procurement windows. Pursue distributor partnerships with bonded warehousing operators seeking compliant product lines to replace stranded non-certified inventory. For Investors and Strategic Acquirers: Building automation integrators are the most active acquirer in this space, seeking lighting hardware capabilities to complete energy management dashboard offerings. The five-to-ten year viability window favors chip-scale specialists with gallium nitride substrate relationships over pure fixture assemblers facing margin compression. Monitor SASO 2870 efficacy tier evolution announcements as the inflection signal for inventory stranding events and replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Substrates | Captive semiconductor sourcing insulates margin structure from Taiwan foundry allocation constraints. |
| Smart Fixture Platform Integration | Connected commissioning protocols capture Riyadh commercial tower building automation budgets. |
| Horticultural Wavelength Portfolio Launch | Tunable-spectrum fixtures address Qassim Region controlled-environment agriculture demand. |
| SASO 2870 Certification Acceleration | Compliance leadership strands competitor inventory at Jeddah and Dammam bonded warehousing. |
| Eastern Province Contractor Partnership | Direct relationships with hospitality and healthcare builders secure specification lock-in. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with Saudi fixture manufacturers, semiconductor distributors, and Eastern Province hospitality contractors with secondary validation. Regulatory filings from the Saudi Energy Efficiency Center, SASO 2870 registration databases, and customs import records at Jeddah and Dammam ports anchored supply-side calibration. Bottom-up volume triangulation across panel, downlight, bulb, and tube product categories converged with top-down market sizing from construction permit data and municipal procurement disclosures.
Comparable-period anchoring to historical fixture replacement cycles and efficacy standard evolution established the forecast framework baseline across the projection horizon. Segmentation modeling incorporated product type, technology tier, application vertical, and end-user procurement channel dimensions with regional disaggregation across Riyadh, Eastern Province, Mecca Region, and Western Region construction corridors. CAGRs derived from regression analysis of certified luminaire adoption rates and smart technology penetration in commercial building stock, with gallium nitride substrate cost curves and SASO enforcement granularity as primary forecast inputs.
The model holds under steady SASO 2870 efficacy tier enforcement and stable Taiwan semiconductor foundry capacity; deviation in regulatory ratchet timing or substrate supply disruption would shift the outlook materially. Forecasts reflect assumptions around municipal program execution pace and hospitality construction pipeline continuity in the Eastern Province and Mecca Region.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Egypt LED Lighting Market
LED
Global Outdoor LED Lighting Market
LED
Brazil LED Market
LED
Germany Automotive LED Lighting Market
LED
Monochrome Outdoor LED Display Market
LED
Linear LED Strip Fixture Market
LED
France Outdoor LED Lighting Market
LED
LED Digital Scoreboard Market
LED
India LED Outdoor Lighting Market
LED
Infrared (IR) LED Market
LED
Japan LED Lighting Market
LED
Japan Outdoor LED Lighting Market
LED
Japan LED Market
LED
GCC LED Lighting Market
LED
Architectural LED Products Market
LED
Russia LED Market