
 Europe Indoor LED Lighting Market | 2026-2036
Europe Indoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Indoor LED Lighting Market Insights
A shift from single-source procurement to multi-source LED module sourcing is pivoting how European fixture assemblers manage supply risk. Signify sustains broad channel control across wholesale and project-direct routes. ams-OSRAM AG anchors upstream LED chip and driver supply for multiple downstream brands. Zumtobel Group AG specializes in architectural-grade luminaires for premium commercial interiors.
Europe indoor LED lighting encompasses solid-state luminaires employing gallium nitride emitters, typically operating at correlated color temperatures between 2700K and 6500K with efficacies exceeding 130 lumens per watt, designed for enclosed building environments. Panel lights and troffers dominate volume flows in office and healthcare retrofit programs where ceiling-grid compatibility determines specification. Smart lighting and sensor-integrated technologies capture expanding specification share as building management systems demand interoperable daylight harvesting and occupancy response. Downlights retain stable specification in residential and hospitality verticals where recessed aesthetic integration governs selection.
The EU Ecodesign Directive and F-Gas Regulation constrain legacy fluorescent and HID product availability, while CE marking and RoHS compliance establish mandatory entry thresholds for LED luminaires sold across member states. ECHA substance restrictions on hazardous materials in electronics further shape component sourcing decisions for manufacturers serving the European market. Stakeholders must monitor evolving EU Green Deal implementation timelines and national transpositions to anticipate next-phase efficiency tier upgrades and circular economy requirements.
Market Dynamics
EU Ecodesign Directive mandates are compressing fixture replacement cycles across commercial real estate, forcing building operators to retire fluorescent troffers ahead of scheduled maintenance windows and redirect capital toward sensor-integrated LED retrofits.
Growth Catalysts
- Benelux corridor retrofit density:Office stock concentration in Brussels, Amsterdam and Luxembourg creates contiguous demand for ceiling-grid-compatible LED panels. Facility managers specify interoperable daylight harvesting systems to meet municipal energy performance contracts.
- EU Green Deal implementation:National transposition timelines accelerate building renovation wave funding. Member states channel subsidies toward lighting upgrades that demonstrate measurable kilowatt-hour reductions in public sector buildings.
- Human-centric lighting protocols:Circadian rhythm tuning via tunable white LED arrays gains specification in Nordic healthcare and education verticals. Architects embed melanopic lux targets into wellness-certified building designs.
Market Restraints
- Gallium nitride wafer supply concentration:Epitaxial substrate fabrication clusters in East Asia expose European luminaire assemblers to shipping volatility and tariff exposure. Foundry capacity constraints extend driver component lead times.
- RoHS substance compliance costs:ECHA restricted substance lists require reformulation of solder alloys and phosphor coatings. Small-scale fixture manufacturers face disproportionate testing and certification overhead.
- Fluorescent tube residual stock:Legacy T8 inventory in southern European maintenance channels delays full LED conversion. Price-sensitive public procurement in Spain and Italy extends dual-technology specification windows.
Strategic Opportunities
- Polish industrial warehouse buildout:E-commerce fulfillment center construction near Warsaw and Wrocław generates specification demand for high-bay LED arrays with motion-sensing controls. Local electrical contractors seek packaged lighting-and-controls solutions.
- Power-over-Ethernet convergence:IT infrastructure and lighting control architectures merge as building owners deploy single-cable systems. Cisco and Philips partnerships demonstrate integrated data-and-illumination network value.
- France's tertiary sector decree:National regulations mandate consumption reduction targets for commercial buildings exceeding specific floor areas. Energy service companies capture recurring revenue through lighting-as-a-service contracting models.
Industry Challenges
- Building management system integration complexity:Facility engineers struggle to harmonize proprietary lighting control protocols with legacy BACnet and Modbus infrastructure. Interoperability testing extends project commissioning timelines.
- Lighting designer skill scarcity:Architectural practices lack staff fluent in both photometric calculation software and IoT network configuration. Cross-functional training programs remain underdeveloped across vocational institutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Indoor LED Lighting Market |
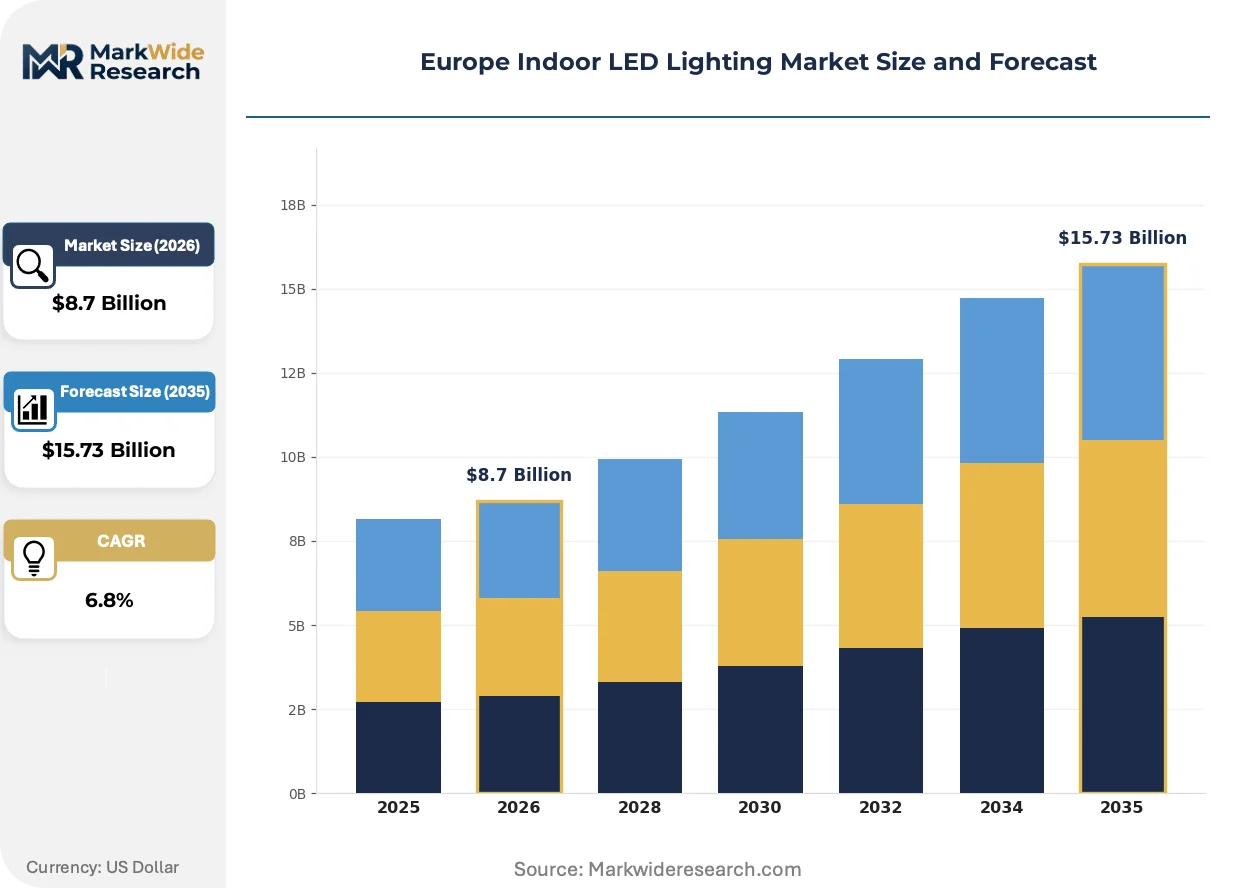
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Troffers, Panel Lights, Downlights, Decorative Lights End User: Commercial, Industrial, Residential, Retail Technology: Dimmable, Smart Lighting, Sensor-Integrated, Zigbee Installation: New Construction, Retrofit, Integrated Systems, Custom Designs |
| Companies Covered | Trilux GmbH & Co. KG, Thorn Lighting Ltd., Signify, Dialight, Fagerhult Group, ams-OSRAM AG, LEDVANCE GmbH, EGLO Leuchten GmbH, Zumtobel Group AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Indoor LED Lighting Market Trends and Innovations
Photobiological safety standards and wireless mesh protocols are simultaneously elevating performance thresholds and rewiring how luminaire intelligence distributes through commercial buildings.
Chip-on-board LED arrays with integrated driver electronics is consolidating mid-wattage fixture categories previously served by discrete component architectures. German automotive suppliers repurposing surface-mount expertise now dominate COB module supply to architectural lighting brands. This integration is consolidating supplier tiers as assemblers reduce vendor counts and negotiate volume commitments with single-source module providers.
REACH substance restriction expansions are forcing reformulation of thermal interface materials and encapsulant chemistries across LED module production. Compound manufacturers in the Netherlands and Belgium invest in halogen-free alternatives to maintain CE marking eligibility. Luminaire brands serving healthcare and food processing verticals face accelerated audit cycles as ECHA adds candidate list substances.
Specification authority is migrating from electrical contractors toward facilities IT directors as networked lighting becomes a data collection node. Large French and German corporate real estate portfolios now require IP-addressable luminaires with open API architectures for energy analytics integration. Channel conflict intensifies between traditional electrical wholesalers and systems integrators competing for project-margin capture.
Europe Indoor LED Lighting Market Segmentation
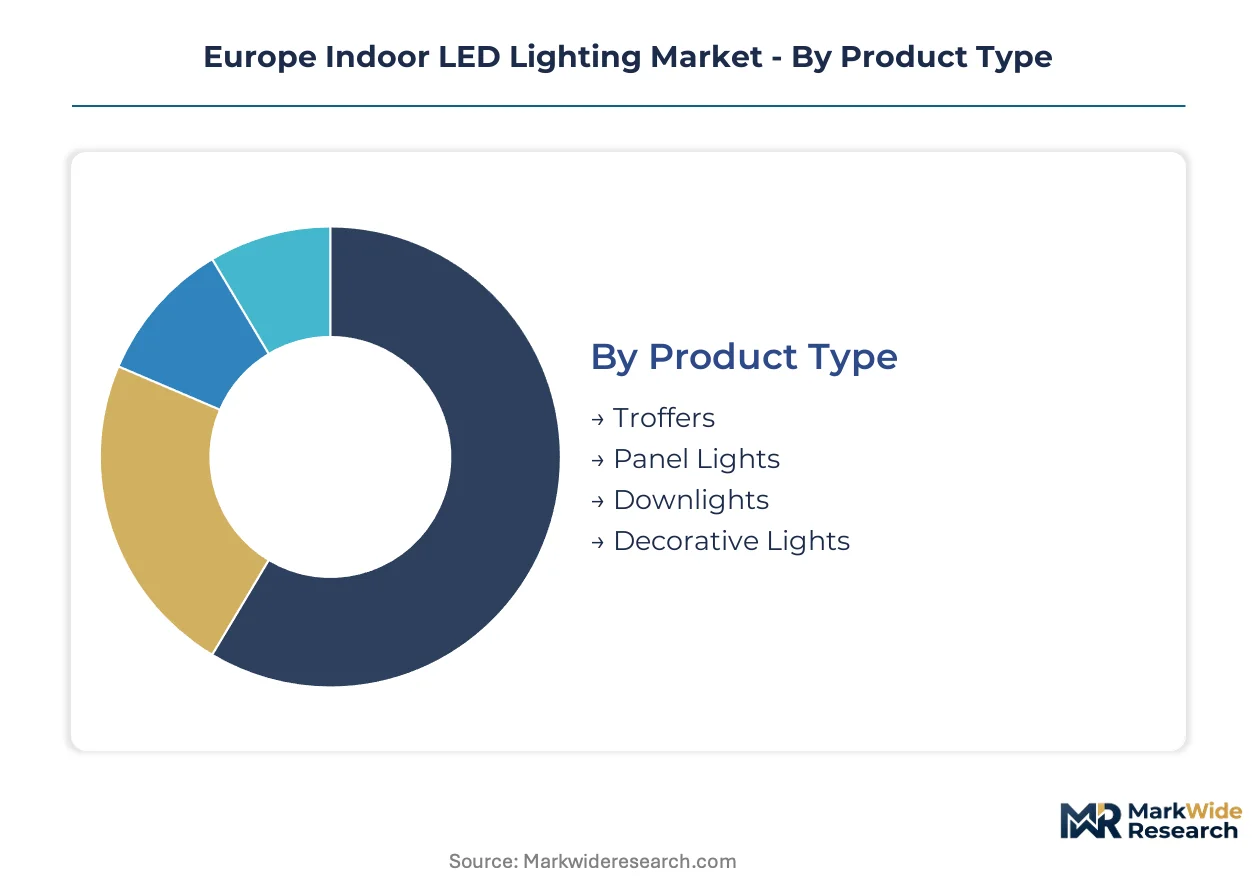
Segmentation in Europe indoor LED lighting reveals how regulatory tiers and application requirements fragment procurement behavior. CE marking and Ecodesign compliance thresholds vary sharply across product categories, forcing assemblers to maintain multiple certification tracks.
Product Type:
CE marking complexity escalates with fixture form factor, as troffers and panels face stricter photometric testing under EN 12464-1 workplace lighting standards than decorative categories.
- Troffers:Modular ceiling-grid fixtures housing linear LED arrays with prismatic or parabolic diffusers. German and French office retrofits concentrate demand here, driven by EU Ecodesign mandates phasing out fluorescent predecessors in commercial real estate.
- Panel Lights:Edge-lit or direct-backlit flat luminaires delivering uniform surface illumination. Benelux healthcare and education specifications favor these for glare control and circadian tuning compatibility, with Brussels facility managers embedding daylight harvesting requirements.
- Downlights:Recessed point-source fixtures for residential and hospitality verticals where aesthetic integration governs selection. CE marking suffices for most residential applications, reducing compliance overhead versus commercial categories.
- Decorative Lights:Ornamental luminaires prioritizing design over raw efficacy. Italian and Spanish hospitality projects sustain niche demand despite looser Ecodesign enforcement timelines in southern Europe.
Troffers sit at the top of the volume ranking, with panel lights climbing the fastest.
End User:
Capital intensity and procurement sophistication diverge across end-user categories, with commercial and industrial buyers demanding interoperable controls while residential segments prioritize upfront cost.
- Commercial:Office, healthcare, and institutional facilities specifying networked lighting with open API architectures. French tertiary sector decrees mandate consumption reduction targets, accelerating lighting-as-a-service contracting.
- Industrial:Manufacturing and logistics facilities requiring high-bay arrays with motion-sensing controls. Polish warehouse buildouts near Warsaw and Wrocław concentrate specification demand for packaged lighting-and-controls solutions.
- Residential:Single-family and multi-unit housing where price sensitivity and installer familiarity shape selection. Downlights dominate retrofit activity in German and Nordic residential markets.
- Retail:Merchandising environments balancing color rendering accuracy with energy performance. Spanish and Italian retail chains lag northern Europe in LED conversion due to fluorescent residual stock in maintenance channels.
Commercial commands the largest installed base, though industrial applications are expanding most quickly.
Technology:
Intelligence integration tiers separate premium specification from commodity replacement, with sensor-integrated and smart systems requiring additional EMC and cybersecurity validation under EU radio equipment directives.
- Dimmable:Phase-cut or 0-10V control compatibility enabling basic luminous flux adjustment. Standard in German commercial retrofits where building management systems demand baseline interoperability.
- Smart Lighting:IP-addressable luminaires with cloud-connected control platforms. French and German corporate real estate portfolios now require open API architectures, migrating specification authority from electrical contractors to facilities IT directors.
- Sensor-Integrated:Occupancy and daylight harvesting sensors embedded at fixture level. Benelux municipal energy performance contracts drive specification for interoperable systems meeting strict measurement and verification protocols.
- Zigbee:Wireless mesh protocol enabling fixture-to-fixture communication without dedicated control wiring. Healthcare and education verticals in Nordic countries favor this for retrofit flexibility where rewiring is cost-prohibitive.
Dimmable fixtures retain the broadest penetration, while smart lighting systems are gaining specification share fastest.
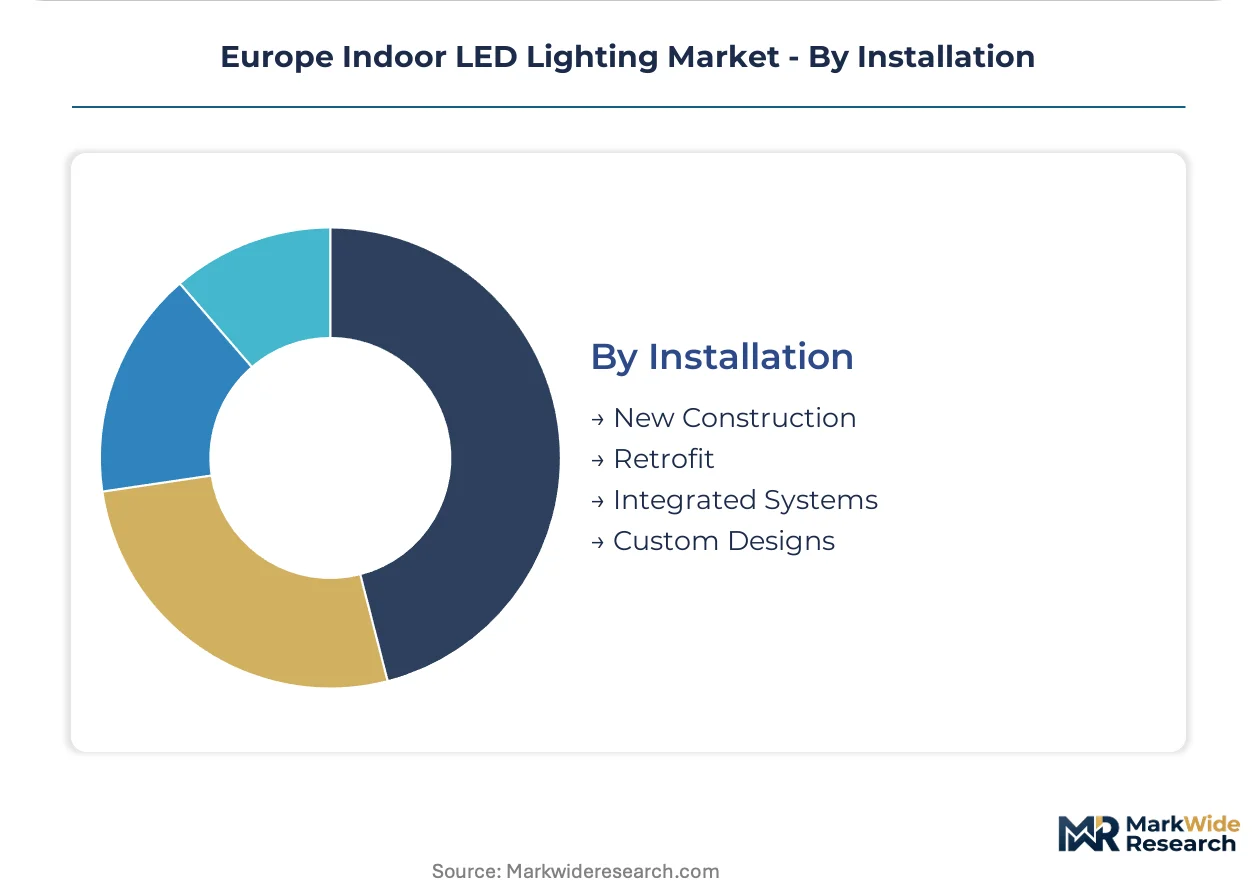
Installation:
Project type determines channel access and margin structure, with new construction offering systems integrator entry points that retrofits rarely permit.
- New Construction:Greenfield projects where lighting design integrates with architectural planning from schematic phase. Power-over-Ethernet convergence finds traction here as IT and illumination networks merge in Dutch and German commercial developments.
- Retrofit:Existing building upgrades constrained by ceiling infrastructure and electrical distribution. EU Green Deal renovation wave funding channels subsidies toward these projects, particularly in public sector buildings.
- Integrated Systems:Lighting bundled with HVAC, security, and building management platforms. Large German automotive and industrial campuses specify these for unified facility control.
- Custom Designs:Bespoke luminaires for heritage buildings or architecturally significant interiors. Zumtobel Group and comparable specialists dominate this margin-rich niche across premium commercial and cultural institutions.
Retrofit installations handle the highest transaction volume, with integrated systems showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Benelux corridor anchors European indoor LED lighting demand through concentrated office stock and aggressive municipal energy performance contracting. National transpositions of EU Green Deal funding are diverging in speed and subsidy depth across member states. Regulatory enforcement tightness varies between northern retrofit urgency and southern fluorescent residual clearance.
Germany
Commercial office retrofits in Frankfurt and Munich are compressing fixture replacement cycles ahead of Ecodesign mandates. The national tertiary sector decree mandates consumption reduction targets for buildings exceeding specific floor areas. Industrial campuses in Baden-Württemberg specify integrated lighting-and-controls systems for unified facility management.
France
Healthcare and education verticals in Paris and Lyon are embedding human-centric lighting protocols with melanopic lux targets. National regulations enforce strict building renovation wave funding timelines for public sector upgrades. Energy service companies in Île-de-France capture recurring revenue through lighting-as-a-service contracting models.
Netherlands
Power-over-Ethernet convergence finds traction in Amsterdam commercial developments merging IT and illumination networks. Municipal energy performance contracts in Rotterdam and The Hague drive specification for interoperable daylight harvesting systems. Dutch compound manufacturers invest in halogen-free thermal interface materials to maintain CE marking eligibility.
Poland
E-commerce fulfillment center construction near Warsaw and Wrocław generates demand for high-bay LED arrays with motion-sensing controls. EU Green Deal renovation wave funding channels subsidies toward warehouse lighting upgrades demonstrating measurable kilowatt-hour reductions. Local electrical contractors seek packaged lighting-and-controls solutions for industrial buildouts.
Belgium
Brussels facility managers specify ceiling-grid-compatible LED panels with embedded sensor integration for circadian tuning. Benelux corridor retrofit density creates contiguous demand for interoperable building management system compatibility. Architectural practices in Flanders face skill scarcity in photometric calculation software and IoT network configuration.
Europe Indoor LED Lighting Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated and connected lighting architectures. The market structure consolidates around vertically integrated module suppliers and specialized fixture assemblers with distinct channel strategies. Three archetypes dominate: upstream chip-and-driver specialists, broad-channel lighting conglomerates, and architectural-grade premium specialists. Competitive moves center on strategic partnerships for Power-over-Ethernet convergence and geographic expansion into Polish industrial corridors.
Within the upstream specialist tier, ams-OSRAM AG anchors LED chip and driver supply for multiple downstream brands. Signify occupies a position exemplifying broad-channel control across wholesale and project-direct routes. Zumtobel Group AG represents the architectural-grade archetype for premium commercial interiors. These three entities illustrate how European fixture assemblers manage supply risk through multi-source module sourcing while maintaining distinct specification authority in their respective market tiers.
| Leading Market Players |
|---|
| Trilux GmbH & Co. KG |
| Thorn Lighting Ltd. |
| Signify |
| Dialight |
| Fagerhult Group |
| ams-OSRAM AG |
| LEDVANCE GmbH |
| EGLO Leuchten GmbH |
| Zumtobel Group AG |
| Others |
Pricing and Supply Chain Analysis
Surface-mount electronics engineers concentrated in Baden-Württemberg and Bavaria command wage premiums that compress margins for German fixture assemblers, widening spreads between premium architectural-grade luminaires and economy-tier imports from Eastern European contract manufacturers.
Pricing Analysis
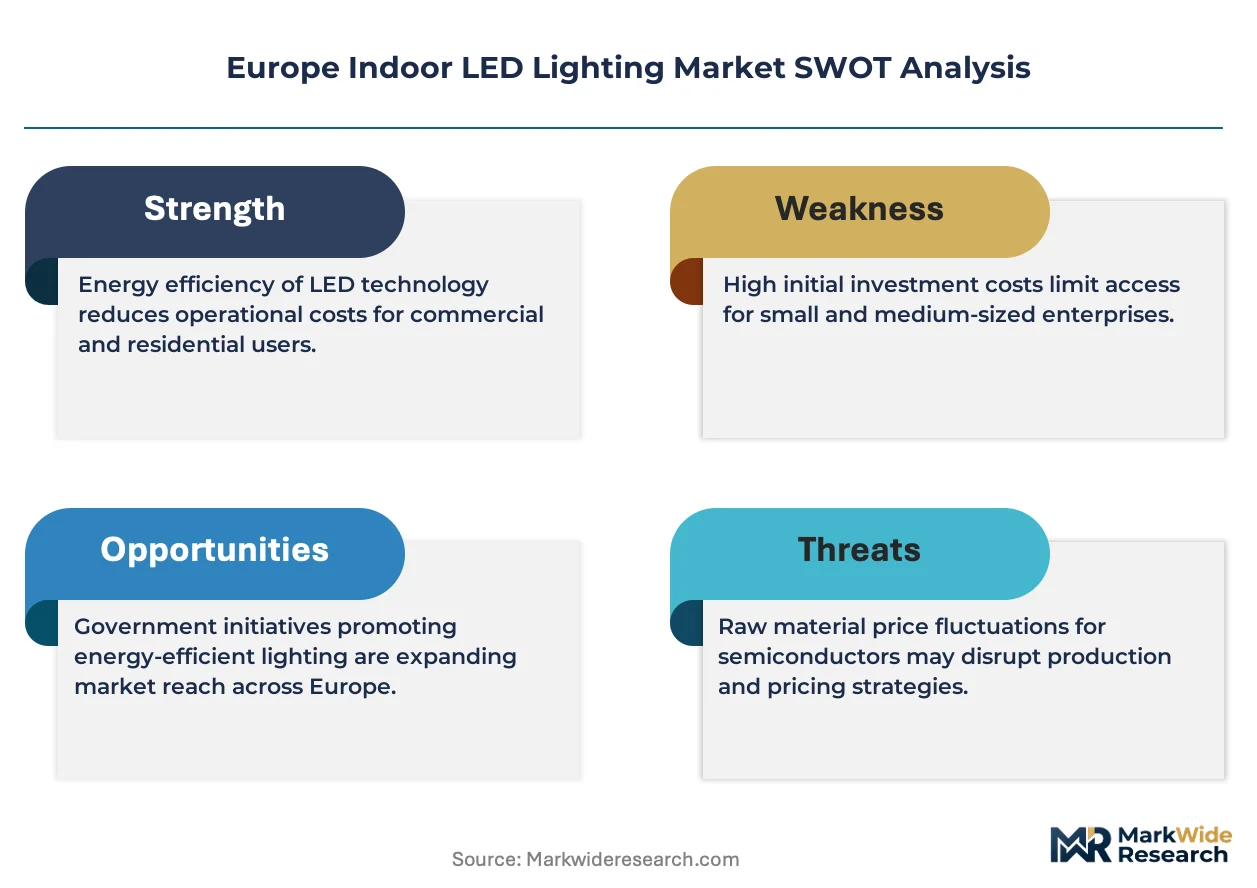
Input-cost pass-through from gallium nitride wafer and driver IC procurement determines fixture pricing trajectories across the value chain. A three-tier pricing structure across premium, standard, and economy levels separates Zumtobel-grade architectural specification from wholesale-channel commodity panels. CE marking complexity and Ecodesign compliance tier act as price differentiation drivers, with certified commercial troffers commanding substantial premiums over residential downlights. Pricing pressure stems from RoHS substance reformulation costs that disproportionately burden small-scale manufacturers. Public procurement in southern Europe exhibits highest price sensitivity, while Nordic healthcare facilities demonstrate lowest sensitivity due to wellness-certification mandates.
Supply Chain Analysis
Freight cost volatility on Asia-Europe routes erodes landed cost predictability for LED chip and driver imports from Taiwan, South Korea, and China. European luminaire assemblers draw from East Asian epitaxial substrate fabrication for gallium nitride wafers, Dutch and Belgian compound manufacturers for halogen-free thermal interface materials, and German automotive suppliers repurposing surface-mount expertise for chip-on-board modules. Single-source vulnerability concentrates in East Asian foundry capacity for driver electronics. Distribution runs through traditional electrical wholesalers facing channel conflict from systems integrators capturing smart-lighting project margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe indoor LED lighting market functions as a stable compounder, with EU Ecodesign Directive mandates ensuring predictable fixture replacement cycles regardless of macroeconomic cycles.
For Market Incumbents: Deploy channel control levers to defend specification authority against systems integrators encroaching on project-direct routes. Incumbents should consolidate vendor counts through volume commitments with single-source chip-on-board module providers, while investing in open API architectures to satisfy French and German facilities IT directors migrating procurement authority from electrical contractors. The threat of Power-over-Ethernet convergence demands interoperability certification with Cisco-grade network infrastructure. For New Entrants and Emerging Players: The price-point gap between Signify-grade smart systems and unbranded economy panels offers entry space for mid-tier sensor-integrated offerings. New entrants should target Polish industrial warehouse buildouts near Warsaw and Wrocław, where packaged lighting-and-controls solutions face supply scarcity from established brands. A go-to-market angle through local electrical contractors seeking turnkey high-bay specifications bypasses entrenched wholesale channel gatekeepers. For Investors and Strategic Acquirers: Building automation conglomerates are the most active acquirer in this space, seeking lighting-as-a-service capabilities to complement HVAC and security portfolios. Long-term viability rests on recurring revenue models rather than transactional fixture sales, favoring targets with installed-base scale for retrofit service contracts. The signal to watch is tertiary sector decree enforcement velocity in France and Germany, which accelerates lighting-as-a-service contracting adoption and revalues asset-light service providers above hardware manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Power-over-Ethernet Convergence | Cisco and Philips partnerships demonstrate integrated data-and-illumination network value for IT directors. |
| Lighting-as-a-Service Contracting | Energy service companies in Île-de-France capture recurring revenue through consumption-reduction guarantees. |
| Chip-on-Board Module Integration | German automotive suppliers dominate COB supply, consolidating supplier tiers for architectural lighting brands. |
| Halogen-Free Material Reformulation | Dutch compound manufacturers invest in REACH-compliant alternatives to maintain CE marking eligibility. |
| Open API Architecture Development | French corporate real estate portfolios mandate IP-addressable luminaires for energy analytics integration. |
Research Methodology
Coverage spans Germany, France, Benelux, and Poland, with primary inputs from each market cluster combined with secondary validation. The research team conducted interviews with lighting fixture procurement managers at French energy service companies, facilities IT directors at German corporate real estate portfolios, electrical contractors in Polish industrial corridors, and specification architects at Benelux healthcare institutions. Secondary sources included EU Ecodesign Directive implementation timelines, ECHA substance restriction updates, CE marking compliance databases, and national building renovation wave funding disclosures. Bottom-up volume estimates triangulated against top-down market sizing from trade association shipment data.
Granularity-level modeling deployed separate forecast tracks by product type, end-user vertical, technology tier, and installation mode across the projection horizon. The analytical framework treated troffers and panel lights as distinct volume categories given divergent specification authority and replacement cycle dynamics. CAGRs derived from regression analysis against EU Green Deal funding trajectories and national tertiary sector decree enforcement schedules. Industry-specific inputs included municipal energy performance contract penetration rates in Brussels, Amsterdam, and Luxembourg, plus Power-over-Ethernet infrastructure deployment timelines in Dutch commercial developments.
Caveats apply where gallium nitride wafer supply disruptions or ECHA substance list expansions could materially shift the outlook. Forecasts reflect assumptions about Ecodesign Directive phase-out schedules and national transposition consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Thailand LED Market
LED
Programmable LED Drivers Market
LED
LED Power Supplies Market
LED
Mexico LED Lighting Market
LED
Global Chip Scale Package (CSP) LED Market
LED
UV LED Market
LED
LED High Bay Drivers Market
LED
US Outdoor LED Lighting Market
LED
Superluminescent Diodes Market
LED
UAE LED Lights Market
LED
Global Industrial and Commercial LED Lighting Market
LED
Surface Mount PLCC Leds Market
LED
LED Work Light Market
LED
LED Modular Display Market
LED
LED Panel Market
LED
LED Mask Market