
 Europe LED Packaging Market | 2026-2036
Europe LED Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe LED Packaging Market Foresight
Multi-source procurement strategies for phosphor substrates and ceramic carriers is shifting toward hybrid in-house and outsourced arrangements across European LED packaging operations. ams-OSRAM leverages its Austrian-German manufacturing footprint to sustain captive die-attach capabilities. Nichia Corporation anchors premium phosphor supply relationships with continental automotive tier-ones. Samsung Electronics competes through scale advantages in mid-power chip-on-board assemblies for commercial retrofit channels.
Europe LED packaging encompasses the encapsulation, thermal management, and optical conditioning of semiconductor light-emitting dies into functional emitters, typically involving silicone or epoxy molding compounds applied over gallium nitride chips mounted on metal or ceramic substrates to achieve specified lumen output and color rendering indices. The primary purpose centers on protecting fragile junctions while optimizing heat dissipation and light extraction for downstream luminaire manufacturers. Surface Mount Device formats dominate volume shipments across general lighting retrofit programs, while Flip Chip architectures command margin pools in automotive forward-lighting modules where thermal density thresholds are most severe. Silicone encapsulants are displacing epoxy formulations in high-flux segments due to superior photothermal stability under prolonged operation.
REACH compliance through ECHA governs chemical substance registration across encapsulant and phosphor chemistries, while the EU Green Deal's ecodesign requirements shape minimum efficacy standards for packaged emitters sold into member states. CE marking under the RoHS directive restricts hazardous substance thresholds in metallic lead frames and solder interfaces, directly influencing material substitution roadmaps. Germany's KBA type-approval processes for automotive exterior lighting create additional conformance layers for suppliers targeting OEM assembly lines. Stakeholders must monitor evolving F-Gas Regulation amendments for their indirect pressure on cooling-dependent packaging processes and assess how CSRD disclosure mandates will reshape supplier qualification criteria across European value chains.
Market Dynamics
Substrate material transitions driven by REACH compliance and EU Green Deal ecodesign mandates are compressing legacy epoxy-based packaging architectures across European manufacturing corridors.
Growth Catalysts
- Automotive forward-lighting modules:German and Czech OEM assembly lines are absorbing Flip Chip architectures for thermal density management in adaptive headlamp systems.
- EU Green Deal ecodesign requirements:Minimum efficacy standards for packaged emitters are accelerating silicone encapsulant adoption over epoxy formulations in high-flux segments.
- Bavaria and Baden-Württemberg industrial clusters:Concentrated luminaire manufacturing demand is pulling volume shipments of Surface Mount Device formats through regional distribution channels.
Market Restraints
- Phosphor substrate cost volatility:Rare-earth element price swings in ceramic carrier supply chains are compressing margin pools for mid-power chip-on-board assemblies.
- Captive die-attach concentration:Austrian-German manufacturing corridors dominate in-house capabilities, creating supplier qualification bottlenecks for tier-two packaging houses.
- RoHS material substitution timelines:CE marking restrictions on metallic lead frames are forcing extended validation cycles for solder interface redesigns.
Strategic Opportunities
- Polish and Romanian retrofit channels:Underpenetrated commercial lighting upgrade programs offer white space for mid-power chip-on-board volume expansion.
- CSRD disclosure mandates:Supplier qualification criteria reshaping across European value chains create first-mover advantage for transparent substrate sourcing documentation.
- Silicone-encapsulant thermal convergence:Hybrid molding compound formulations combining photothermal stability with epoxy processing economics are opening premium-general lighting crossover segments.
Industry Challenges
- Gallium nitride junction thermal modeling:Specialized simulation talent scarcity in continental packaging houses is extending new product introduction timelines for automotive qualification.
- KBA type-approval certification cycles:Germany's automotive exterior lighting conformance layers are creating multi-quarter validation backlogs for suppliers targeting OEM assembly lines.
- Legacy epoxy process equipment:Capital intensity of silicone encapsulant conversion is straining mid-tier packaging operations with limited access to equipment financing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe LED Packaging Market |
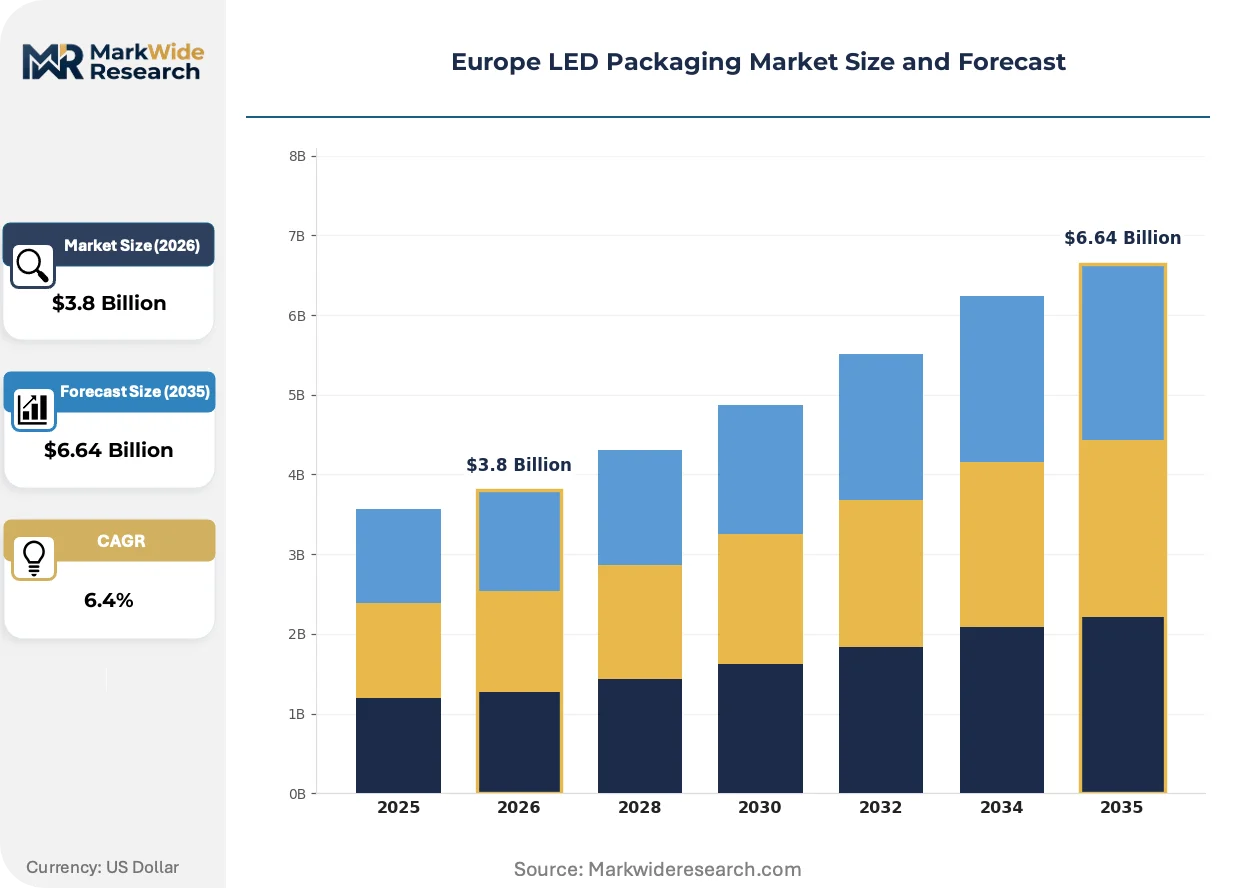
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Mount Device, Chip-on-Board, Dual In-line Package, Flip Chip Material: Silicone, Epoxy, Glass, Metal Application: General Lighting, Automotive Lighting, Backlighting, Signage End User: Residential, Commercial, Industrial, Others |
| Companies Covered | Nichia Corporation, Samsung Electronics, ams-OSRAM, Cree Inc., LG Innotek, TT Electronics, Seoul Semiconductor, Lumileds Holding, Stanley Electric, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe LED Packaging Market Shifts & Advancements
Material science advances in thermal interface layers and regulatory pressure on chemical substance registration are jointly reshaping European LED packaging process flows and equipment specifications.
Flip Chip die-attach architectures with direct-bonded copper substrates are electrifying thermal management performance in automotive forward-lighting modules. German tier-one suppliers are adopting these configurations at accelerated qualification paces for adaptive headlamp programs. The technology is electrifying margin compression in legacy wire-bond packaging houses unable to fund copper-substrate capital transitions.
REACH compliance through ECHA is tightening chemical substance registration requirements across phosphor chemistries and silicone encapsulant formulations. Industrial consequence includes extended safety data sheet validation cycles and reformulation costs for packaging material suppliers. Automotive exterior lighting segments targeting Germany's KBA type-approval are most affected, with suppliers accelerating pre-registration dossier preparation.
Hybrid in-house and outsourced procurement arrangements for phosphor substrates and ceramic carriers are displacing pure multi-source strategies across European operations. Tier-one automotive suppliers are consolidating qualified vendor lists while retaining captive die-attach capabilities. This pattern is most visible across Bavaria and Baden-Württemberg industrial clusters where luminaire manufacturers face margin pressure from retrofit channel price compression.
Europe LED Packaging Market Segmentation
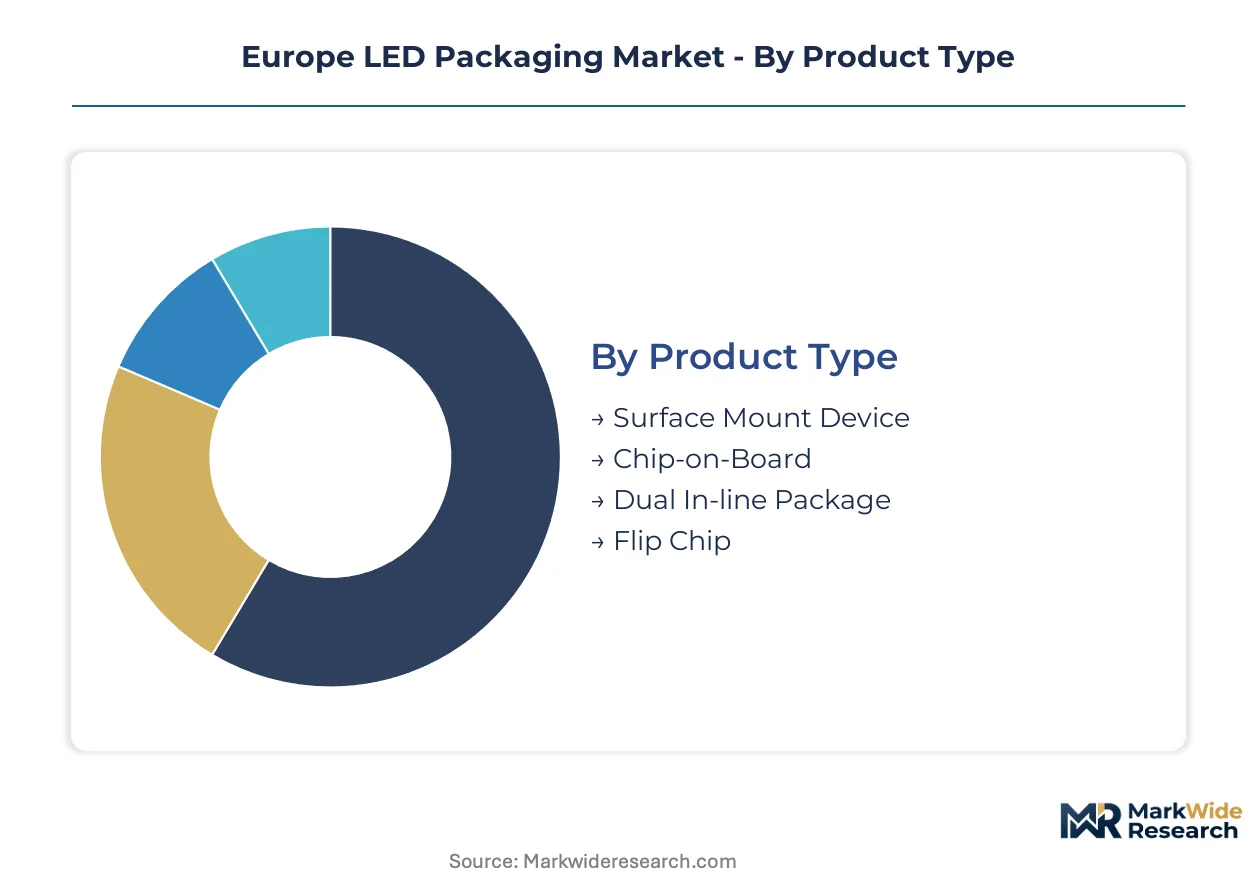
Segmentation in Europe LED packaging reveals how substrate architectures, encapsulant chemistries, and thermal management specifications diverge across regulatory compliance tiers and end-use thermal density requirements. Understanding these divides exposes where margin pools concentrate and where standardization pressures compress differentiation.
Product Type:
Customization intensity spans from commoditized volume formats to thermally engineered automotive architectures requiring die-level thermal modeling.
- Surface Mount Device:Standardized rectangular packages with solderable terminations dominate retrofit channel volumes. Bavaria and Baden-Württemberg luminaire manufacturers pull these formats through regional distribution networks facing EU Green Deal efficacy mandates.
- Flip Chip:Direct die-attach configurations eliminate wire bonds to reduce thermal resistance in high-flux applications. German and Czech OEM assembly lines absorb these architectures for adaptive headlamp modules where KBA type-approval cycles demand extended qualification timelines.
- Chip-on-Board:Bare die arrays mounted directly on substrates optimize lumen density per unit area. Mid-power commercial retrofit programs in Polish and Romanian channels favor this format for cost-sensitive upgrade projects.
- Dual In-line Package:Through-hole configurations with parallel leads persist in legacy industrial equipment replacement cycles. Maintenance-driven demand concentrates in Eastern European manufacturing corridors with extended equipment depreciation schedules.
Most installed capacity flows through Surface Mount Device formats. Expansion is steepest in Flip Chip architectures.
Material:
Cost tier stratification separates photothermally stable formulations commanding premium pricing from legacy chemistries facing substitution timelines.
- Silicone:Polysiloxane encapsulants withstand junction temperatures exceeding epoxy degradation thresholds while maintaining optical clarity. REACH compliance through ECHA is accelerating reformulation investments as suppliers pre-register safety data dossiers for automotive exterior lighting segments.
- Epoxy:Thermoset resins offer processing economics and mechanical rigidity at lower material cost. RoHS-driven lead frame substitution is forcing extended validation cycles for solder interface compatibility with epoxy molding compounds.
- Glass:Hermetic sealing solutions protect dies in extreme environment applications. Specialized demand concentrates in industrial process lighting with chemical exposure requirements.
- Metal:Copper and aluminum substrates and lead frames manage thermal dissipation in high-power packages. CE marking restrictions on hazardous substance thresholds are reshaping alloy composition roadmaps across continental supply chains.
Volume shipments concentrate in Silicone formulations. The steepest expansion trajectory belongs to Metal substrates in automotive thermal management applications.
Application:
Geographic demand concentration within Europe varies by application maturity and regulatory enforcement intensity across member states.
- General Lighting:Retrofit and new installation demand spans residential, commercial, and municipal segments. EU Green Deal ecodesign requirements are compressing legacy efficacy thresholds and accelerating silicone encapsulant transitions.
- Automotive Lighting:Forward-lighting, interior, and signal applications command stringent thermal and optical specifications. German tier-one suppliers dominate qualification pipelines for adaptive headlamp programs requiring Flip Chip die-attach capabilities.
- Backlighting:Display edge-lighting and direct-lit configurations serve consumer electronics and automotive infotainment. Demand concentration follows display panel manufacturing footprints in Central European assembly corridors.
- Signage:Channel letter, billboard, and architectural illumination applications prioritize lumen maintenance and color consistency. Commercial retrofit channels in underpenetrated Eastern European markets offer white space for mid-power volume expansion.
General Lighting absorbs the largest share of packaged emitter volumes. Automotive Lighting is climbing the fastest as thermal density requirements intensify.
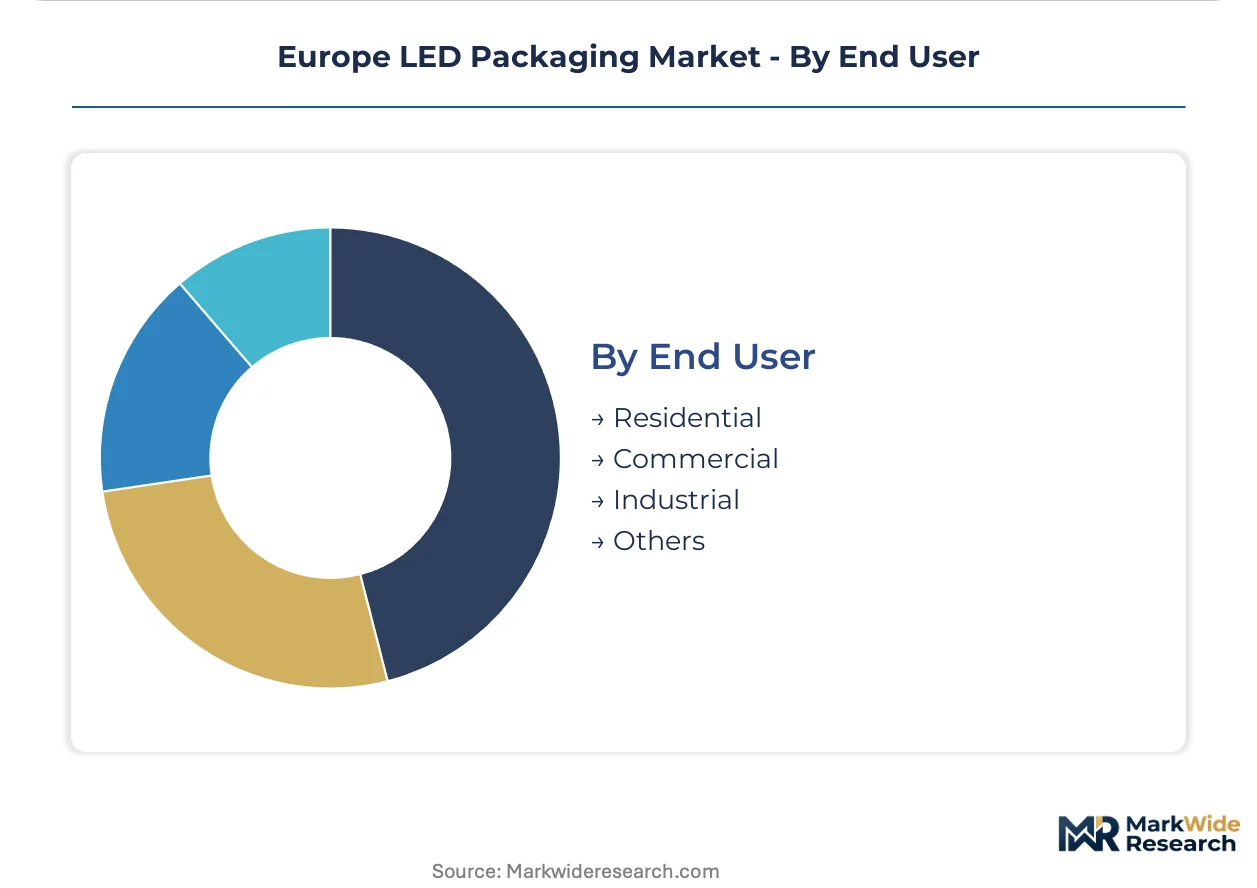
End User:
Customer type determines procurement scale, specification stringency, and supplier qualification depth across European value chains.
- Commercial:Office, retail, and hospitality retrofit programs drive volume demand for standardized Surface Mount Device formats. CSRD disclosure mandates are reshaping supplier qualification criteria toward transparent substrate sourcing documentation.
- Industrial:Manufacturing facility and warehouse lighting prioritizes durability and maintenance interval extension. Demand concentrates in German automotive supplier parks and Czech electronics manufacturing zones.
- Residential:Consumer replacement bulb and fixture markets exhibit price-sensitive procurement patterns. Distribution runs through big-box retail and electrical wholesale channels with private-label concentration.
- Others:Agricultural, medical, and specialty applications require spectral tuning and hermetic sealing. Niche specifications create margin pools for qualified packaging houses with customized phosphor formulation capabilities.
Commercial end users represent the largest volume absorption. Industrial segments are gaining share fastest as automation-driven facility upgrades accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between Western and Eastern European jurisdictions are redirecting packaging volume toward corridors with streamlined REACH pre-registration pathways and lower ecodesign verification overhead.
Germany
Adaptive headlamp programs at BMW and Mercedes-Benz assembly plants absorb Flip Chip architectures for thermal density management. KBA type-approval cycles enforce multi-quarter validation timelines for exterior lighting suppliers. Bavaria and Baden-Württemberg industrial clusters concentrate captive die-attach operations and luminaire manufacturing demand.
Czech Republic
Automotive OEM assembly lines for Škoda and Hyundai-Kia facilities drive premium phosphor substrate procurement. EU Green Deal ecodesign mandates accelerate silicone encapsulant transitions over legacy epoxy formulations. The Moravia-Silesia manufacturing corridor hosts tier-one lighting module suppliers serving German vehicle programs.
Poland
Commercial retrofit channels in Warsaw and Kraków metropolitan areas offer underpenetrated volume expansion for mid-power chip-on-board formats. CSRD disclosure mandates reshape supplier qualification criteria toward transparent substrate sourcing. The Silesian industrial zone concentrates distribution networks for Eastern European luminaire manufacturers.
Netherlands
Signage and architectural illumination demand in the Randstad urban agglomeration prioritizes lumen maintenance specifications. ECHA REACH compliance enforcement tightens chemical substance registration for silicone encapsulant formulations. The Eindhoven high-tech corridor anchors phosphor formulation R&D and specialty packaging operations.
Romania
Price-sensitive commercial lighting upgrade programs in Bucharest and Cluj-Napoca absorb standardized Surface Mount Device volumes. RoHS CE marking restrictions on metallic lead frames extend solder interface validation cycles. The Transylvania industrial region attracts mid-tier packaging houses seeking lower-cost manufacturing footprints.
Europe LED Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive thermal management specializations and CSRD-compliant substrate sourcing documentation. The vendor base stratifies across three capability tiers: integrated die-attach specialists with captive substrate operations, mid-scale packaging houses dependent on outsourced phosphor supply, and regional retrofit channel distributors with limited formulation control. Consolidation pressure intensifies as REACH compliance costs favor scaled safety data dossier preparation. Dominant competitive moves include hybrid procurement arrangements combining in-house die-attach with qualified vendor list consolidation, and geographic expansion into underpenetrated Eastern European retrofit corridors.
Within the integrated tier, ams-OSRAM and Nichia Corporation exemplify divergent geographic anchoring strategies. The Austrian-German manufacturing footprint of ams-OSRAM sustains captive capabilities across die-attach and thermal interface operations. Nichia Corporation represents premium phosphor supply relationship concentration with continental automotive tier-ones. Samsung Electronics occupies a position at the scale-driven end, competing through volume advantages in mid-power chip-on-board assemblies for commercial retrofit channels.
| Leading Market Players |
|---|
| Nichia Corporation |
| Samsung Electronics |
| ams-OSRAM |
| Cree Inc. |
| LG Innotek |
| TT Electronics |
| Seoul Semiconductor |
| Lumileds Holding |
| Stanley Electric |
| Others |
Supply & Pricing Matrix
Rare-earth element price indices for yttrium and cerium feed directly into ceramic carrier cost structures, cascading through phosphor substrate procurement tiers to compress margin pools for mid-power chip-on-board assemblies while amplifying pricing power for integrated die-attach specialists with captive material operations.
Pricing Analysis
Input-cost pass-through from phosphor substrate volatility stratifies pricing across three tiers: premium Flip Chip architectures for German automotive OEMs, standard Surface Mount Device formats for Bavaria luminaire manufacturers, and economy chip-on-board assemblies for Polish retrofit channels. Price differentiation hinges on REACH compliance certification grade and volume scale, with silicone encapsulant formulations commanding material premiums over epoxy alternatives. Pricing pressure stems from rare-earth cost compression in mid-power segments, while tier-one automotive suppliers exhibit lowest price sensitivity due to KBA type-approval switching costs.
Supply Chain Analysis
Direct-to-OEM channels handle German and Czech automotive tier-one demand for Flip Chip architectures, while distribution networks through Silesian hubs serve Eastern European luminaire manufacturers. Geographic supply concentration centers on Germany, Austria, and the Netherlands for die-attach and phosphor formulation capabilities. Raw material dependencies include gallium nitride wafers, rare-earth phosphors, and silicone molding compounds. Single-source vulnerability in premium phosphor supply creates structural risk, particularly for automotive exterior lighting segments facing extended ECHA registration timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in silicone encapsulant transitions and captive substrate operations, as EU Green Deal efficacy mandates compress legacy epoxy economics while rewarding photothermal stability investments.
For Market Incumbents: Anchor qualification pipelines through accelerated KBA type-approval dossier preparation for adaptive headlamp programs, while consolidating phosphor vendor lists to reduce REACH compliance redundancy costs. Threat from emerging Polish and Romanian packaging houses with lower-cost footprints demands defensive capacity positioning in captive die-attach operations. Prioritize backward integration into ceramic carrier sourcing to defend margin pools against rare-earth volatility. For New Entrants and Emerging Players: The premium-economy price-point gap in mid-power chip-on-board assemblies offers white space for volume capture in underpenetrated Romanian commercial retrofit channels. Target Warsaw and Kraków metropolitan distribution networks with standardized Surface Mount Device formats. CSRD-compliant substrate sourcing documentation serves as the primary go-to-market differentiator for European commercial procurement committees. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier packaging houses possessing silicone encapsulant conversion capabilities and automotive qualification pipelines in progress. Long-term viability favors operations with demonstrated ECHA pre-registration completion and established German tier-one supplier relationships. Monitor KBA type-approval certification velocity as the critical inflection signal for automotive revenue conversion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Encapsulant Capacity Expansion | Captures EU Green Deal efficacy mandate premiums across Bavaria luminaire manufacturing clusters. |
| Backward Integration into Ceramic Carriers | Reduces rare-earth phosphor cost volatility exposure for automotive forward-lighting module suppliers. |
| KBA Type-Approval Fast-Track Investment | Compresses multi-quarter validation timelines for German OEM adaptive headlamp programs. |
| Eastern European Distribution Partnership | Accesses underpenetrated Polish and Romanian commercial retrofit channel volumes. |
| CSRD-Compliant Sourcing Documentation | Meets reshaped supplier qualification criteria across European commercial end-user value chains. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Eastern Europe, with primary inputs from each regional manufacturing corridor. The research combines structured interviews with LED packaging plant managers, procurement leads at German automotive tier-ones, phosphor substrate suppliers, and luminaire manufacturer technical directors with secondary validation through ECHA REACH registration databases, EU Green Deal ecodesign directive filings, and customs trade data for gallium nitride wafer imports. Bottom-up volume modeling across substrate architectures triangulates against top-down value estimates from regional distribution channel assessments.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including package architecture type, encapsulant chemistry grade, thermal management specification tier, end-use application intensity, and regional regulatory compliance cluster. CAGRs derive from installed base replacement cycles, automotive content-per-vehicle trajectories, and efficacy standard escalation curves. Forecast inputs incorporate phosphor substrate cost indices, silicone encapsulant adoption rates, and KBA type-approval pipeline visibility.
Caveats apply where ECHA REACH amendment timelines or F-Gas Regulation cooling process restrictions could materially shift the outlook for high-flux packaging operations. Forecasts reflect assumptions regarding substrate material transition velocities and automotive qualification cycle durations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Europe LED Lighting Market
LED
Japan Indoor LED Lighting Market
LED
LED Street Light Drivers Market
LED
North America LED Packaging Market
LED
Global Waterproof LED Module Market
LED
Microled Market
LED
Bi-Color LED Ring Light Market
LED
France Outdoor LED Lighting Market
LED
Infrared (IR) LED Market
LED
Brazil LED Market
LED
Arrow LED Displays Market
LED
Europe Indoor LED Lighting Market
LED
France LED Lighting Market
LED
Global Outdoor LED Lighting Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Japan LED Market