
 China LED Lighting Market | 2026-2036
China LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
China LED Lighting Market Insights
Gallium nitride is decoupling from sapphire substrate dependence as Chinese foundries shift to silicon-based epitaxy, cutting wafer costs by meaningful increments. Opple Lighting Co., Ltd. leverages captive die-production capacity to defend margin structure in residential downlight categories. Zhejiang Yankon Group Co., Ltd. anchors export volume through dedicated ASEAN distribution subsidiaries. MLS Co., Ltd. competes on COB package density for high-lumen industrial arrays.
China LED lighting denotes solid-state illumination systems employing compound semiconductor junctions, typically operating at correlated color temperatures between 2700K and 6500K with luminous efficacies exceeding 130 lumens per watt in premium tiers, engineered to replace thermal-radiation and discharge lamp technologies across built environments. LED panels and LED downlights concentrate margin pools in commercial retrofit channels where labor-minimized installation drives specification preference. Smart lighting and solar LED segments attract capital allocation as grid-edge autonomy and demand-response protocols gain traction in utility-managed building portfolios.
MEE enforcement of dual carbon targets compels accelerated decommissioning of mercury-containing fluorescent tubes in public buildings. GB standards under SAMR jurisdiction mandate minimum efficacy thresholds and flicker metrics that filter low-cost import competition. Stakeholders must monitor NMPA-equivalent quality registration pathways for connected fixtures carrying data-collection capabilities, as cybersecurity compliance becomes inseparable from product access.
Market Dynamics
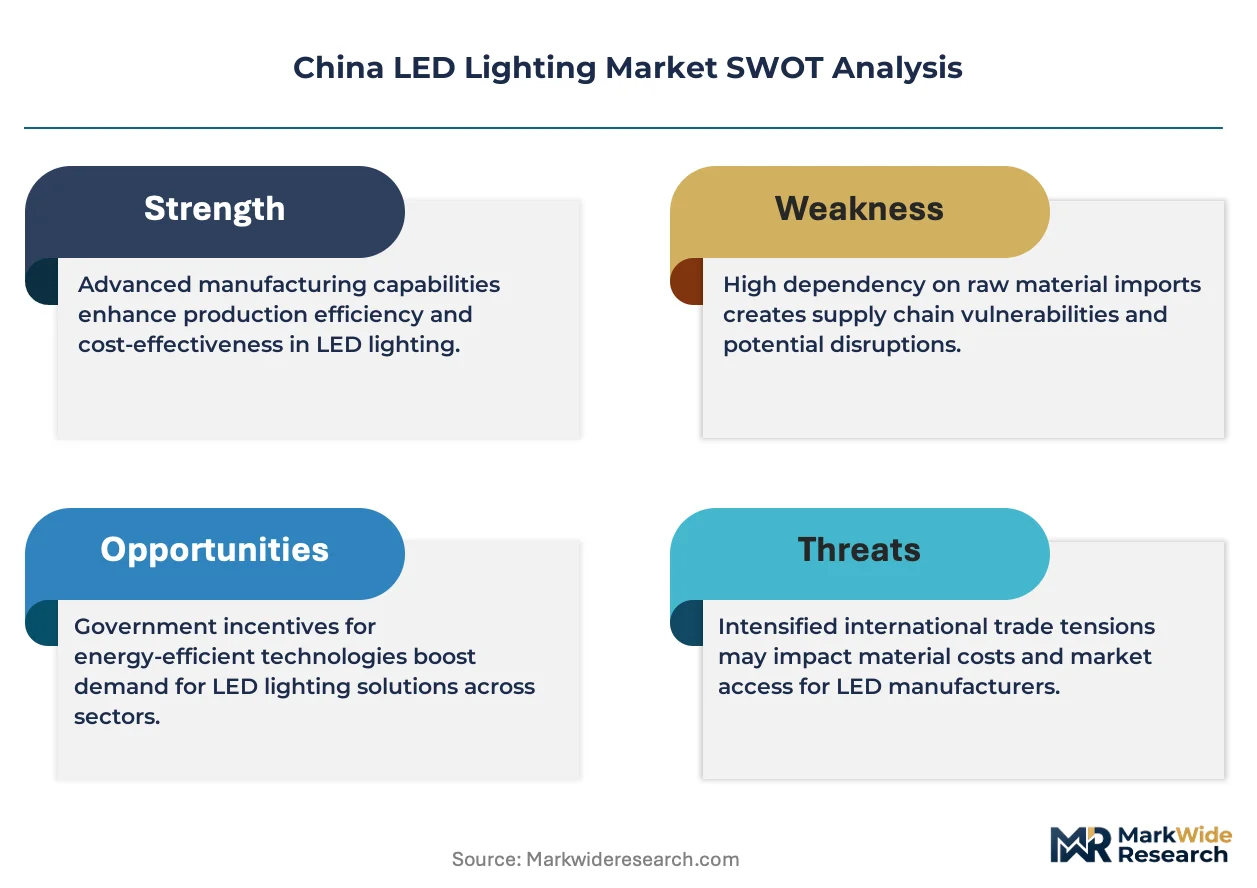
Silicon-based gallium nitride epitaxy is collapsing substrate costs and redrawing competitive boundaries across fixture manufacturing in China. MEE enforcement of dual carbon mandates is accelerating fluorescent decommissioning timelines in public infrastructure.
Growth Catalysts
- Dual carbon enforcement:MEE oversight compels mercury-lamp phase-out across municipal buildings, forcing replacement demand into LED channels.
- Smart city deployment:Shenzhen and Hangzhou infrastructure programs compress fixture replacement cycles in street and public lighting.
- Silicon epitaxy transition:Foundry migration from sapphire to silicon substrates cuts wafer input costs and expands margin capture for domestic manufacturers.
Market Restraints
- Upstream concentration:High-purity gallium refining capacity clusters in specific Chinese provinces, creating supply vulnerability for non-integrated players.
- Import competition filtering:GB standards under SAMR jurisdiction block low-cost foreign fixtures that fail flicker and efficacy thresholds.
- Legacy stock inertia:Fluorescent tube installed base in aging industrial facilities resists capital conversion despite operating cost penalties.
Strategic Opportunities
- Grid-edge autonomy:Solar-LED convergence creates off-grid lighting solutions for rural western provinces beyond reliable utility access.
- Data-collection fixtures:Connected luminaires with environmental sensing capabilities open building-management service contracts.
- ASEAN export channels:Dedicated distribution subsidiaries in Southeast Asian markets capture regional infrastructure build-out demand.
Industry Challenges
- Compound semiconductor talent scarcity:Epitaxy engineering and chip-scale packaging expertise concentrates at a handful of research institutes and captive foundries.
- Cybersecurity compliance complexity:NMPA-equivalent registration pathways for connected fixtures extend product launch timelines as data-collection capabilities trigger additional oversight.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China LED Lighting Market |
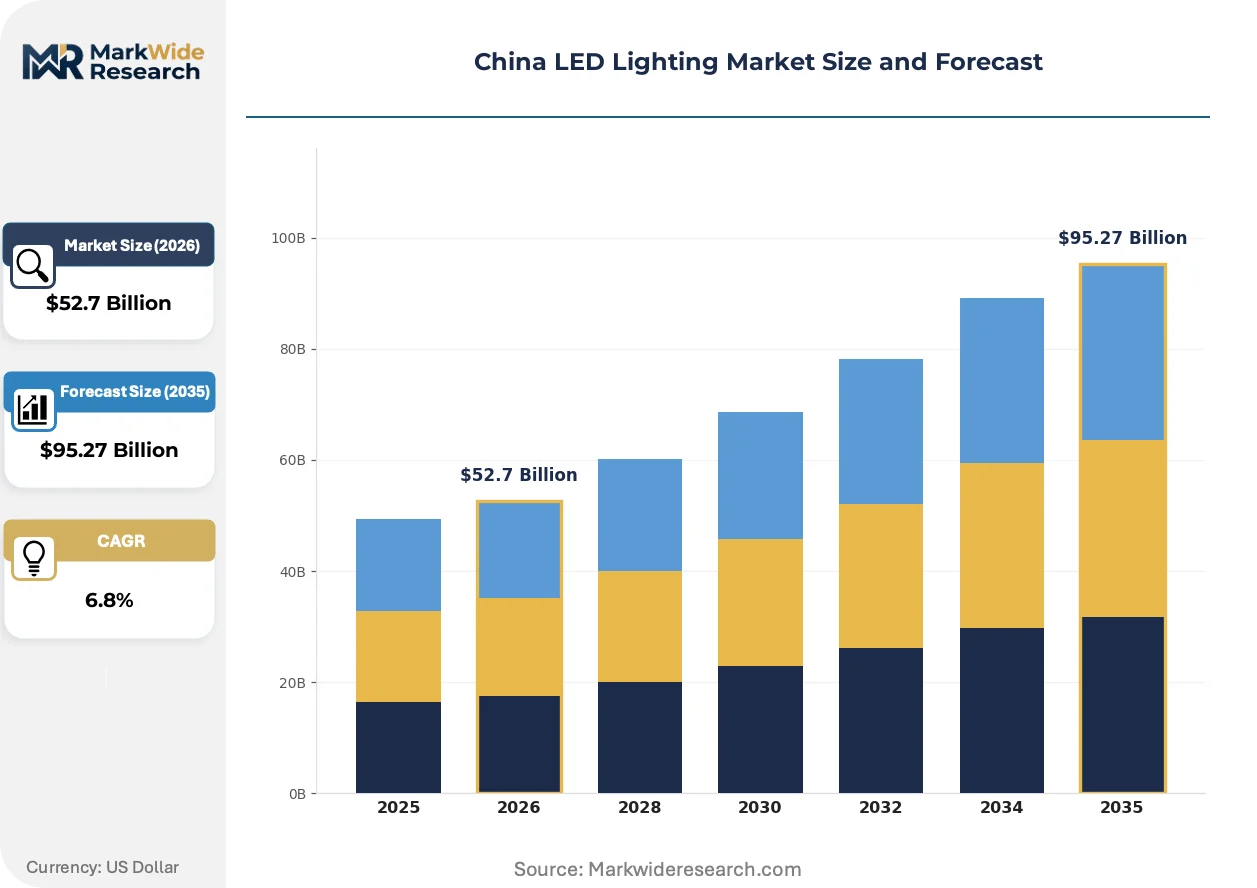
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Bulbs, LED Tubes, LED Panels, LED Downlights Application: Residential Lighting, Commercial Lighting, Outdoor Lighting, Industrial Lighting Technology: Smart Lighting, Dimmable Systems, Human Centric Lighting, Solar LED End User: Retail, Hospitality, Warehousing, Healthcare |
| Companies Covered | Opple Lighting Co., Ltd., Zhejiang Yankon Group Co., Ltd., MLS Co., Ltd., NVC Lighting Holding Ltd., Foshan Electrical and Lighting Co., Ltd., SANSI, Forest Lighting, Kingsun Optoelectronic, Leedarson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China LED Lighting Market Trends and Innovations
Fixture architecture is fragmenting into interchangeable sub-assemblies as manufacturers compete on speed-to-site and labor minimization. Three developments are compressing traditional product lifecycles and reshaping specification behavior.
Chip-on-board LED engines are modularizing around standardized thermal and electrical interfaces. Commercial retrofit contractors in the Yangtze River Delta manufacturing corridor specify these sub-assemblies to slash on-site labor hours. The technology is modularizing procurement from finished-fixture transactions to component-level sourcing with field-assembly protocols.
GB efficacy and flicker standards under SAMR jurisdiction are tightening minimum performance floors annually. Low-cost import competitors from Southeast Asian manufacturing bases face exclusion as testing protocols expand. Industrial high-bay applications face the steepest compliance gradient as lumen-per-watt thresholds ratchet upward.
Building operators now unbundle lighting installation from long-term energy performance contracts. Facility management platforms in Shanghai and Beijing commercial towers specify fixtures through procurement channels that separate capital acquisition from operational optimization. This restructuring concentrates buying power among engineering-procurement-construction firms with integrated project delivery capabilities.
China LED Lighting Market Segmentation
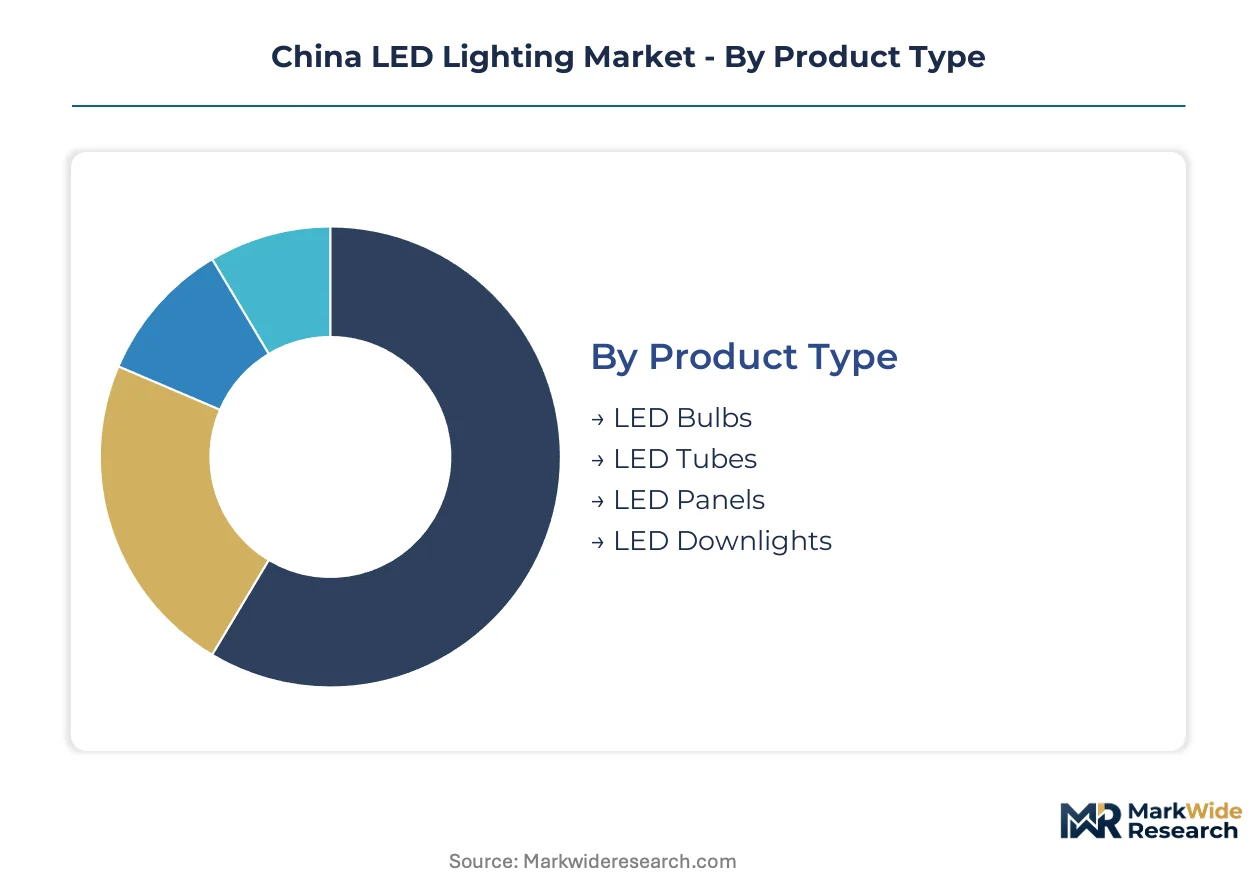
China LED lighting procurement decisions diverge sharply across installation environments, with retrofit labor economics dominating commercial channels while residential buyers prioritize fixture cost and color consistency. Specification behavior fragments further by underlying technology architecture and end-user operational requirements.
Product Type:
Buyers select form factors based on installation labor intensity and existing luminaire infrastructure rather than lumen output alone.
- LED Panels:Flat-profile edge-lit or back-lit modules with standardized 600x600mm ceiling grid compatibility dominate Yangtze River Delta commercial retrofit specifications. Office towers in Shanghai and Hangzhou specify these for labor-minimized drop-ceiling replacements where fluorescent troffers previously dominated.
- LED Downlights:Recessed ceiling fixtures with COB or SMD emitters concentrate margin pools in residential and hospitality channels. Opple Lighting leverages captive die-production capacity to defend position in premium residential downlight tiers where color rendering index above 90 commands specification preference.
- LED Bulbs:Retrofit lamps with Edison or bayonet bases serve legacy socket infrastructure in aging residential stock across tier-two and tier-three cities.
- LED Tubes:Linear replacements for T8 and T5 fluorescent systems face accelerated phase-out pressure under MEE dual carbon enforcement in municipal buildings.
Volume sits with LED panels; growth tilts toward LED downlights.
Application:
Capital allocation intensity varies by sector electrification rates and operating hour profiles.
- Commercial Lighting:Office, retail, and institutional installations with extended operating schedules drive premium efficacy specifications. GB standards under SAMR jurisdiction mandate minimum luminous efficacy thresholds that filter low-cost competition in this channel.
- Outdoor Lighting:Street, roadway, and area illumination systems concentrate smart city deployment momentum. Shenzhen infrastructure programs compress replacement cycles through integrated sensor and communication module bundling.
- Residential Lighting:Single-family and multi-unit dwelling fixtures prioritize first-cost minimization over lifecycle economics in price-sensitive tier-three and tier-four markets.
- Industrial Lighting:High-bay and hazardous-location fixtures face the steepest compliance gradient as GB efficacy thresholds ratchet upward annually for lumen-per-watt performance.
Revenue concentrates in commercial lighting; expansion accelerates fastest in outdoor lighting.
Technology:
Control architecture and energy autonomy reshape competitive boundaries beyond emitter efficiency.
- Smart Lighting:Networked fixtures with occupancy sensing, daylight harvesting, and centralized management protocols capture building-automation integration demand. NMPA-equivalent registration pathways extend launch timelines as cybersecurity compliance becomes mandatory for data-collection capabilities.
- Solar LED:Off-grid photovoltaic-integrated luminaires address western provincial markets beyond reliable utility access. Rural infrastructure programs in Xinjiang and Qinghai specify these for roadway and public area illumination.
- Dimmable Systems:Phase-cut or 0-10V controlled fixtures enable demand-response participation in utility-managed commercial portfolios.
- Human Centric Lighting:Tunable white and circadian-rhythm-optimized systems penetrate healthcare and premium office specifications where occupant wellness metrics influence lease rates.
Shipment volume favors dimmable systems; value expansion shifts toward smart lighting.
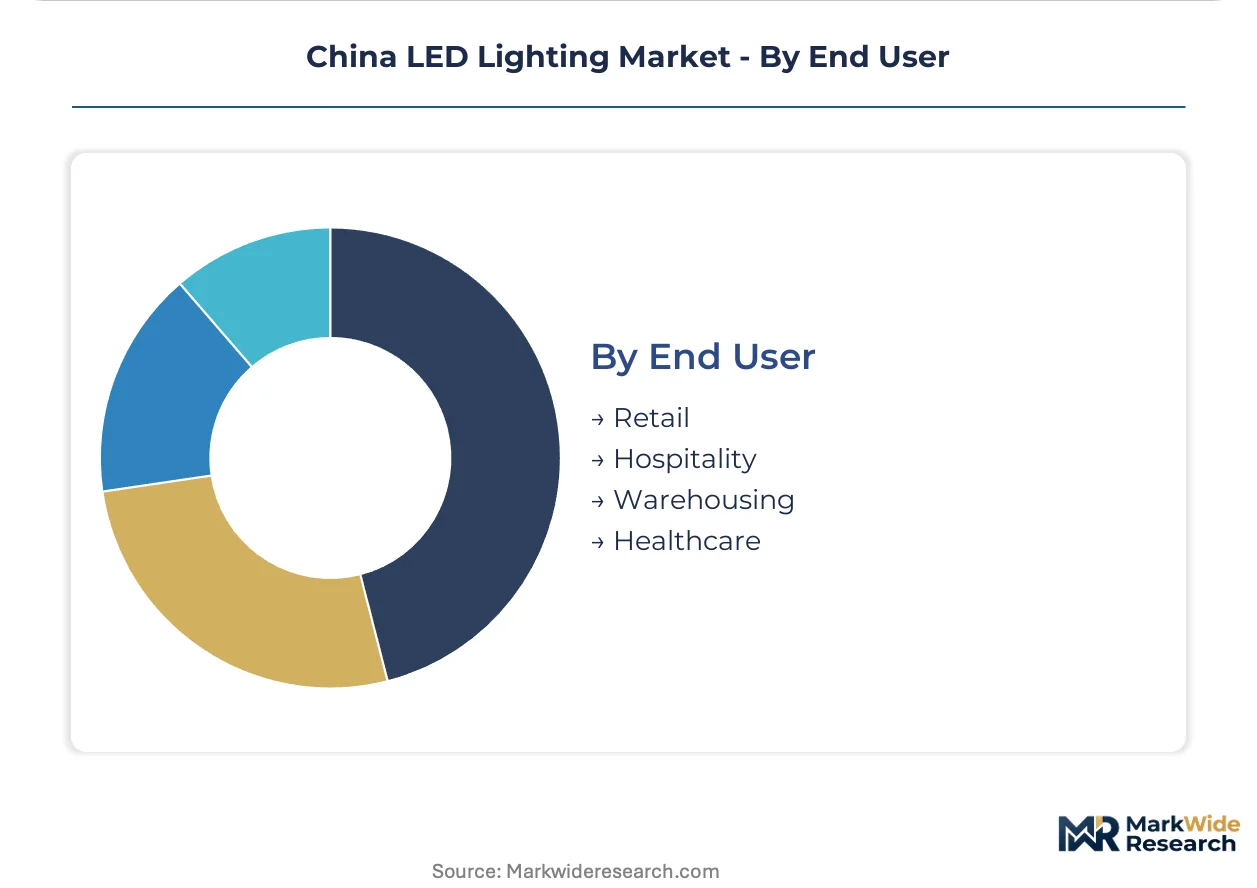
End User:
Operational hour intensity and regulatory exposure differentiate procurement behavior across verticals.
- Warehousing:High-rack storage facilities with 24-hour operational profiles prioritize lumen maintenance and thermal management in high-bay configurations. MLS Co., Ltd. competes on COB package density for these industrial arrays.
- Healthcare:Hospitals and clinics demand flicker-free operation and color-accurate examination lighting where GB standards specify maximum ripple current thresholds.
- Retail:Merchandise display environments balance color rendering against energy cost minimization in extended-hour mall and flagship store deployments.
- Hospitality:Hotels and restaurants emphasize aesthetic fixture design and scene-setting capabilities over raw efficacy metrics.
Installed base concentrates in warehousing; specification velocity runs highest in healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial retrofit intensity concentrates in eastern coastal provinces where manufacturing density and regulatory enforcement timelines converge. Municipal procurement programs and industrial electrification rates diverge sharply across China's sub-regional economies.
Yangtze River Delta
Shanghai and Hangzhou office towers drive LED panel specifications for fluorescent troffer replacement under MEE dual carbon mandates. SAMR efficacy thresholds filter low-cost competitors from municipal procurement channels. The manufacturing corridor spanning Suzhou to Ningbo anchors captive die-production capacity for downstream fixture integration.
Pearl River Delta
Shenzhen smart city infrastructure compresses street lighting replacement cycles through sensor-integrated fixture bundling. GB standards under SAMR jurisdiction mandate flicker metrics that accelerate legacy mercury-lamp decommissioning. Dongguan and Foshan host export-oriented production clusters serving ASEAN distribution networks.
Beijing-Tianjin-Hebei
State-owned facility retrofits prioritize high-bay industrial arrays with COB package density for 24-hour warehousing operations. MEE enforcement timelines for public building phase-outs run ahead of national schedules. Tianjin port logistics support northern provincial distribution for solar-LED rural electrification programs.
Sichuan-Chongqing
Western infrastructure build-out creates demand for off-grid solar-LED solutions beyond reliable utility access in Qinghai and Xinjiang border regions. Provincial rural development programs specify photovoltaic-integrated luminaires for roadway illumination. Chengdu electronics manufacturing bases supply component sub-assemblies to coastal fixture integrators.
Shandong Peninsula
Qingdao and Weihai industrial zones concentrate LED tube production for fluorescent replacement in aging manufacturing facilities. Legacy stock inertia resists capital conversion despite operating cost penalties in heavy industry segments. Port access supports Korean and Japanese export channels for premium residential downlight tiers.
China LED Lighting Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated players capturing margin in premium tiers while OEM fabricators serve price-sensitive volume channels. The vendor base organizes around three archetypes: captive foundry operators with backward integration into epitaxy, export-focused specialists with dedicated ASEAN subsidiaries, and modular sub-assembly suppliers for field-assembly protocols. Competitive moves concentrate on silicon-based substrate transitions and smart fixture cybersecurity registration pathways.
Among integrated domestic specialists, Opple Lighting Co., Ltd. and Zhejiang Yankon Group Co., Ltd. exemplify divergent strategic positions. Opple Lighting occupies a position within the captive die-production tier, leveraging in-house semiconductor capacity to defend margin structure in color-critical residential applications. Zhejiang Yankon Group anchors export volume through regional distribution infrastructure. MLS Co., Ltd. represents the high-lumen industrial specialist archetype, competing on package density for warehousing and manufacturing environments. These three players collectively illustrate the competitive spectrum from upstream semiconductor control through downstream channel specialization.
| Leading Market Players |
|---|
| Opple Lighting Co., Ltd. |
| Zhejiang Yankon Group Co., Ltd. |
| MLS Co., Ltd. |
| NVC Lighting Holding Ltd. |
| Foshan Electrical and Lighting Co., Ltd. |
| SANSI |
| Forest Lighting |
| Kingsun Optoelectronic |
| Leedarson |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists with multi-decade operational histories dominate fixture manufacturing clusters across Guangdong and Zhejiang provinces, anchoring supply discipline through retained earnings financing rather than external capital. Their ownership structure insulates pricing from quarterly earnings pressure while concentrating procurement leverage over domestic sapphire-substrate suppliers. MEE enforcement timelines for dual carbon compliance create asymmetric pricing power for manufacturers with captive gallium nitride foundry capacity.
Pricing Analysis
Volume concentrates in standardized LED panels for commercial retrofit channels where Yangtze River Delta contractors prioritize labor-minimized installation over unit cost. Three-tier pricing structure across premium, standard, and economy levels separates GB-certified fixtures with flicker compliance from uncertified imports facing SAMR exclusion. Cost compression in economy tiers intensifies because silicon-epitaxy transitions at domestic foundries are not yet fully passed through. Municipal procurement under MEE mandates shows least price sensitivity; tier-three residential distributors exhibit highest.
Supply Chain Analysis
Workforce availability in Dongguan and Foshan manufacturing zones constrains capacity expansion for chip-on-board packaging operations despite automated epitaxy lines. Supply concentrates in China for gallium refining and sapphire wafer processing, with Taiwan and South Korea providing specialty phosphor and driver IC components. Raw material dependencies include high-purity gallium metal, aluminum nitride ceramic substrates, and rare-earth phosphor formulations. Single-source vulnerability runs through concentrated gallium refining capacity in specific Chinese provinces. Distribution runs through engineering-procurement-construction firms with integrated project delivery capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: compound semiconductor epitaxy engineering expertise concentrates at a handful of research institutes and captive foundries, propping pricing for premium-tier fixtures with color-critical specifications.
For Market Incumbents: Hedge against silicon-epitaxy cost compression by locking long-term wafer supply agreements before substrate transitions fully diffuse. Defend margin structure in residential downlight categories through captive die-production capacity expansion. Prioritize NMPA-equivalent cybersecurity registration for connected fixtures ahead of data-collection compliance mandates.
For New Entrants and Emerging Players: Solar-LED convergence technology offers a technology-first wedge into western provincial markets beyond reliable utility access where grid-edge autonomy commands specification preference. Target rural infrastructure programs in Xinjiang and Qinghai for photovoltaic-integrated luminaire deployment. Pursue component-level sub-assembly supply to field-assembly contractors rather than finished-fixture distribution.
For Investors and Strategic Acquirers: MEE acceleration of fluorescent decommissioning timelines in public buildings is the leading indicator that replacement demand will sustain elevated fixture pricing through the mid-term. Long-term viability favors vertically integrated specialists with backward control into epitaxy rather than pure-play assemblers. Target acquisition archetype: mid-caps with silicon-based GaN foundry transitions underway. Watch for GB standard threshold tightening as signal for import competitor exclusion.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Epitaxy Foundry Transition | Migrating from sapphire substrates cuts wafer input costs and expands margin capture for domestic manufacturers. |
| Smart Fixture Cybersecurity Registration | NMPA-equivalent compliance for data-collection capabilities extends product launch timelines but blocks non-compliant competitors. |
| ASEAN Distribution Subsidiary Buildout | Dedicated regional infrastructure captures Southeast Asian infrastructure build-out demand beyond saturated domestic channels. |
| COB Package Density Expansion | Higher lumen-per-watt industrial arrays penetrate warehousing verticals with 24-hour operational profiles. |
| Energy Performance Contract Unbundling | Separating capital acquisition from operational optimization concentrates buying power among EPC firms. |
Research Methodology
Trade association filings, SAMR regulatory bulletins, and MEE enforcement disclosures formed the secondary backbone for supply-side capacity assessment. Primary interviews with fixture procurement managers at Shanghai commercial tower operators, epitaxy engineering directors at captive foundries, and retrofit contractors across the Yangtze River Delta manufacturing corridor were cross-referenced against customs export data and GB standard revision schedules. Bottom-up shipment estimates by product category were triangulated against top-down market sizing derived from semiconductor wafer input volumes.
Historical trendline analysis of fluorescent-to-LED replacement cycles informed projection assumptions across the analysis window. Segmentation modeling incorporated product type, application environment, control technology architecture, and end-user operational intensity. CAGRs were derived from curve-fitting observed adoption rates against regulatory enforcement timelines. Industry-specific forecast inputs included MEE dual carbon mandate phase-out schedules and silicon-epitaxy yield improvement trajectories at domestic foundries.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt GB standard threshold revisions or gallium supply disruptions. Forecasts reflect assumptions regarding MEE enforcement consistency and silicon-substrate yield maturation. Material deviation in MEE penalty escalation or foundry transition timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
France Indoor LED Lighting Market
LED
Japan LED Lighting Market
LED
Thailand LED Market
LED
UK LED Lighting Market
LED
UAE LED Lights Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
Europe LED Packaging Market
LED
Infrared (IR) LED Market
LED
LED Phosphor Materials Market
LED
Japan Indoor LED Lighting Market
LED
LED Light Bar Market
LED
Light Emitting Diode (LED) Backlight Display Market
LED
Global Outdoor LED Lighting Market
LED
7 Segment LED Displays Market
LED
LED Floodlight Drivers Market
LED
Global Industrial and Commercial LED Lighting Market