
 US and Europe LED Lighting Market | 2026-2036
US and Europe LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
US and Europe LED Lighting Market Analytics
Lighting-as-a-service and subscription-based maintenance contracts is restructuring how buyers procure illumination across commercial portfolios. Signify Holding leverages its Interact IoT platform to anchor recurring revenue streams in European facility management contracts. Acuity Brands Inc. competes through deep specification relationships with North American electrical distributors. Eaton Corporation sustains project pipeline visibility via its Cooper Lighting specification-grade portfolio in municipal and infrastructure verticals.
US and Europe LED lighting encompasses solid-state electroluminescent devices fabricated on sapphire or silicon carbide substrates, typically emitting in the 2700K to 6500K correlated color temperature range with system efficacies exceeding 130 lumens per watt in premium tiers. These devices convert electrical energy directly to visible light through electron-hole recombination in semiconductor junctions, eliminating filament degradation and enabling directional optical control for task-specific illumination in commercial, industrial, and residential environments. The commercial application segment dominates installed value due to longer operating hours and faster payback periods on retrofit investments, while smart LED technology captures disproportionate attention from facility managers seeking occupancy-based dimming and daylight harvesting integration. White LED products still occupy the volume base across residential replacement cycles, though RGB LED installations accelerate in hospitality and retail experience design where tunable ambiance commands specification premiums.
The US Department of Energy enforces ENERGY STAR certification and FTC lighting facts labeling that filters substandard imports from distribution channels, while the European Commission applies Ecodesign Directive Lot 19 requirements and CE marking obligations through notified bodies in Germany and Italy. The EU F-Gas Regulation indirectly shapes LED thermal management strategies by restricting conventional refrigerants in climate-controlled luminaire applications, pushing manufacturers toward passive cooling architectures. Stakeholders must monitor divergence between US DOE rulemakings and EU harmonized standards to avoid dual-certification cost burdens in transatlantic product planning.
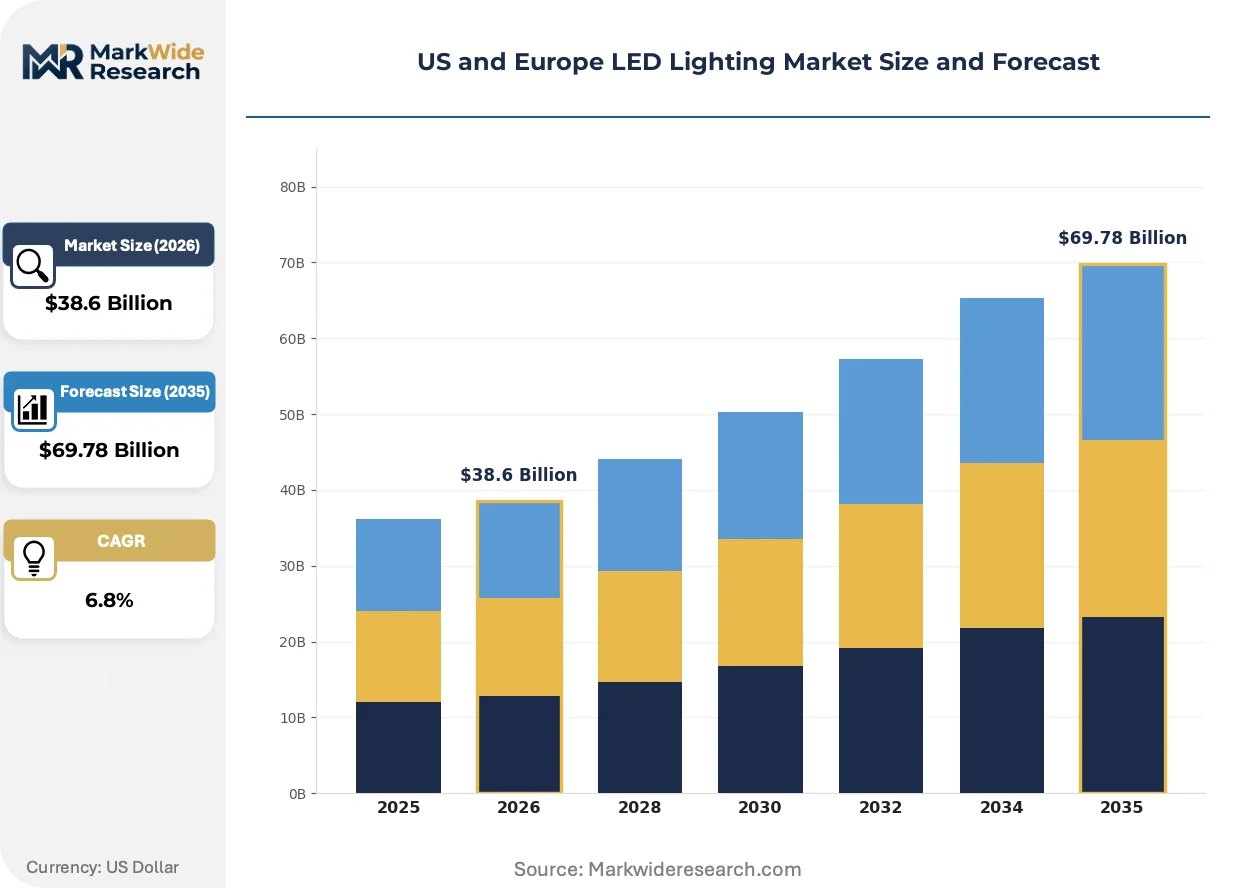
Market Dynamics
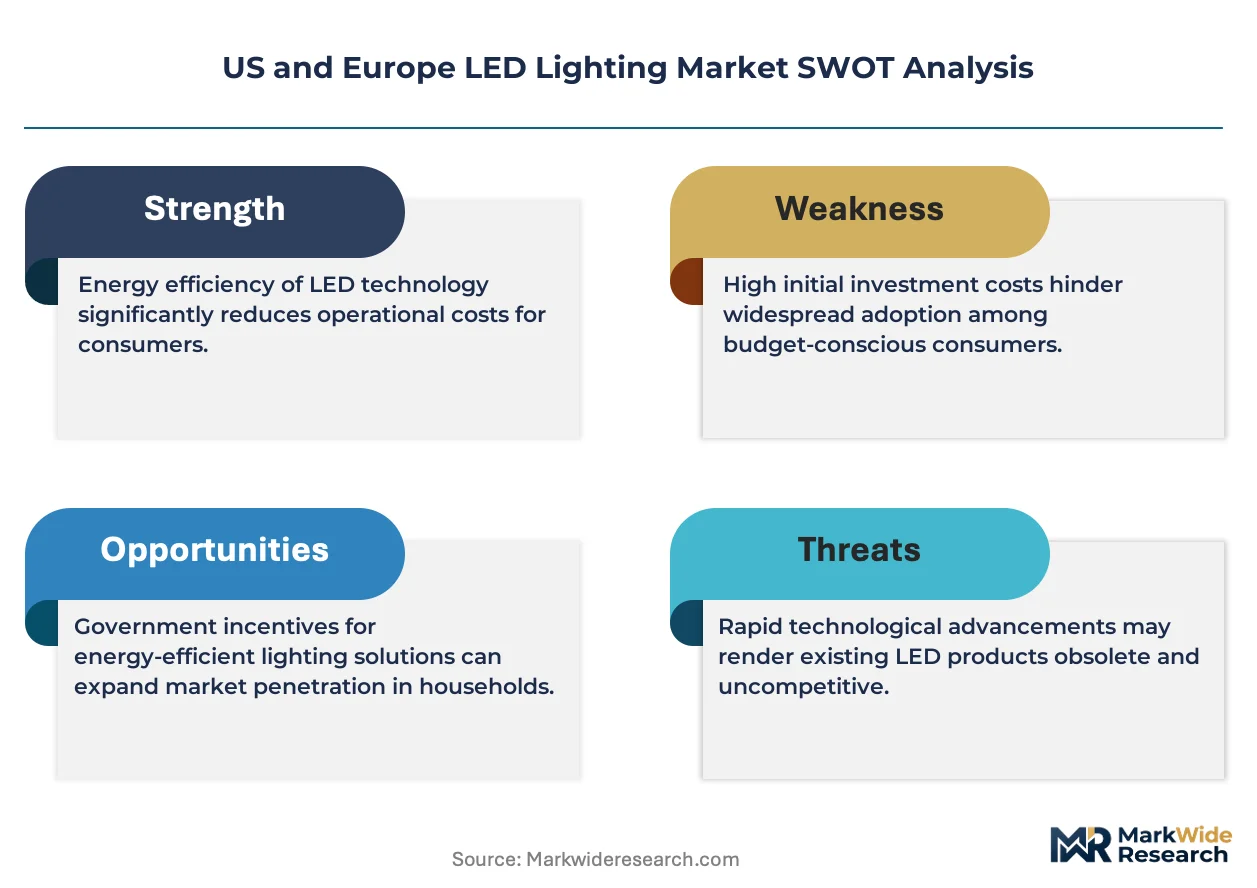
Retrofit mandates across commercial building stock are compressing replacement cycles as facility managers face simultaneous pressure from EU Ecodesign Directive efficacy floors and US ENERGY STAR specification tightening, forcing simultaneous hardware and control system upgrades.
Growth Catalysts
- EU Ecodesign Directive Lot 19:Minimum efficacy requirements eliminate legacy fluorescent and halogen inventories from distribution channels, accelerating fixture replacement in German and French commercial portfolios.
- Smart building retrofits:Facility managers in warehouse and logistics verticals deploy occupancy-based dimming and daylight harvesting to capture utility rebate programs and reduce HVAC cooling loads.
- Sapphire substrate supply concentration:Vertical integration among Asian wafer manufacturers stabilizes LED chip pricing, enabling tier-one fixture producers to maintain margin structures while expanding specification-grade portfolios.
Market Restraints
- Driver and phosphor cost volatility:Rare earth element pricing fluctuations in Chinese processing facilities compress gross margins for mid-tier luminaire assemblers without captive component sourcing.
- Thermal management complexity:Passive cooling architectures required under EU F-Gas Regulation constraints add engineering overhead and extend product development timelines for climate-controlled applications.
- Incumbent fixture longevity:Existing LED installations from 2012-2018 replacement waves exhibit slower lumen depreciation than projected, delaying second-cycle retrofit demand in mature commercial segments.
Strategic Opportunities
- Lighting-as-a-service models:Subscription-based maintenance contracts in North American office portfolios transfer capital expenditure to operating budgets while locking in multi-year recurring revenue streams for platform providers.
- Human-centric lighting:Circadian rhythm tuning in healthcare and education verticals commands specification premiums through tunable white and amber-shifted product lines.
- Polish and Romanian commercial expansion:Underpenetrated warehouse and manufacturing facility stock in Eastern European markets offers first-mover positioning before harmonized EU efficiency mandates fully phase in.
Industry Challenges
- Dual-certification cost burdens:Divergence between US DOE rulemakings and EU harmonized standards forces redundant testing protocols for transatlantic product portfolios, extending time-to-market by 4-8 months.
- Legacy control system incompatibility:Integration complexity with existing 0-10V and DALI infrastructure in aging commercial buildings limits smart LED penetration without full rewiring investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Europe LED Lighting Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Panels Application: Residential, Commercial, Outdoor, Industrial Technology: Smart LED, RGB LED, White LED, High Bay LED End User: Retail, Hospitality, Offices, Warehouses |
| Companies Covered | Eaton Corporation (Cooper Lighting), Zumtobel Group AG, Signify Holding (Philips Lighting), Current Lighting Solutions, LLC., Fagerhult Group, OSRAM GmbH, LEDVANCE GmbH, Schreder SA, Acuity Brands Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Europe LED Lighting Market Evolving Landscape
Semiconductor architecture advances and procurement model restructuring are converging to redefine value capture in commercial illumination, shifting competitive advantage from component cost to system integration and service attachment.
LiFi visible light communication is integrating infrared emitter arrays into standard LED form factors, enabling simultaneous illumination and high-speed data transmission. German automotive suppliers and French defense contractors pilot secure wireless networks in electromagnetic-sensitive environments. This convergence is compressing the boundary between lighting infrastructure and IT backbone, forcing traditional electrical distributors to develop data networking competencies.
The EU F-Gas Regulation and evolving ENERGY STAR specifications are tightening thermal performance thresholds for enclosed luminaires, restricting conventional refrigerant-based cooling in climate-controlled applications. Manufacturers respond with graphene-enhanced heat sinks and ceramic substrate migration. Commercial office segments in California and the Netherlands face the steepest compliance curves, driving specification-grade portfolio refreshes ahead of enforcement deadlines.
Facility management procurement departments are consolidating vendor relationships around integrated service contracts that bundle hardware, installation, energy monitoring, and predictive maintenance. Traditional fixture-only distributors lose specification influence to platform providers with IoT software stacks. This concentration is most visible in US healthcare and UK education verticals, where capital budget constraints favor operational expenditure models with guaranteed energy savings clauses.
US and Europe LED Lighting Market Segmentation
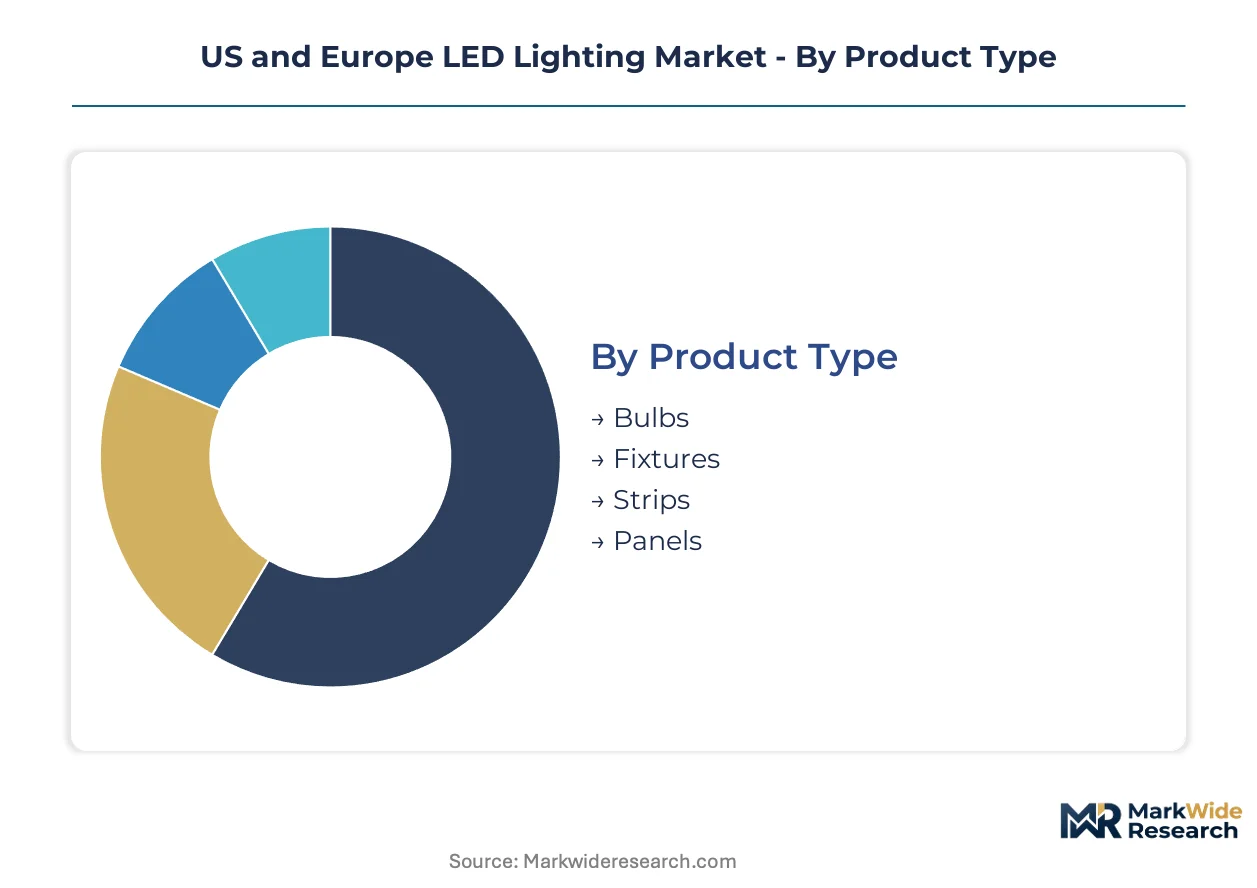
LED lighting segmentation reveals divergent margin structures across hardware categories and starkly different procurement behaviors between facility managers and residential buyers. Understanding these divides illuminates where platform providers can extract recurring revenue versus where component cost compression dominates competitive dynamics.
Product Type:
Volume concentrates in replacement bulbs, while premium capture resides in specification-grade fixtures with integrated controls.
- Fixtures:Enclosed luminaires with integrated drivers and thermal management systems dominate commercial retrofit specifications. German warehouse operators and French office facility managers prioritize efficacy-rated troffers and linear high-bays to satisfy EU Ecodesign Directive Lot 19 compliance deadlines.
- Bulbs:Standard A19 and PAR form factors with Edison bases serve residential replacement cycles and legacy socket retrofits. US big-box retail channels move volume through ENERGY STAR-labeled SKUs, though margin compression from private-label imports intensifies price competition.
- Panels:Edge-lit and direct-lit flat panels target suspended ceiling grids in commercial office environments.
- Strips:Flexible linear arrays with adhesive backing address cove lighting and architectural accent applications.
Today's leader: Fixtures. Tomorrow's challenger: Smart-enabled panels with embedded sensor arrays.
Application:
Commercial buildings generate disproportionate value due to longer operating hours and faster payback calculations on energy savings.
- Commercial:Office towers, retail chains, and healthcare facilities drive specification-grade demand through professional procurement channels. California Title 24 compliance mandates and Netherlands BREEAM certification requirements accelerate LED retrofits with daylight harvesting controls.
- Industrial:Manufacturing plants and logistics centers deploy high-bay fixtures with occupancy sensors to reduce HVAC cooling loads. Polish and Romanian warehouse stock remains underpenetrated, offering first-mover positioning before full EU efficiency harmonization.
- Outdoor:Street lighting and area illumination face municipal budget cycles and utility rebate program timing.
- Residential:Homeowner replacement purchases follow bulb burnout rates and renovation activity.
Commercial commands current margins. Industrial offers the steepest expansion trajectory as Eastern European manufacturing capacity expands.
Technology:
Smart capabilities are restructuring competitive advantage from lumen output to software integration and data services.
- Smart LED:Networked luminaires with embedded sensors enable occupancy-based dimming, asset tracking, and space utilization analytics. UK education and US healthcare verticals consolidate procurement around IoT platform providers with guaranteed energy savings clauses.
- White LED:Phosphor-converted blue emitters in fixed color temperatures dominate volume shipments for general illumination. ENERGY STAR and CE marking requirements filter substandard imports, stabilizing quality tiers across distribution channels.
- RGB LED:Multi-chip arrays with independent red, green, and blue channels enable tunable ambiance in hospitality and retail experience design.
- High Bay LED:Specialized thermal architectures and optical distributions target ceiling heights exceeding 20 feet in warehouse and manufacturing environments.
White LED anchors volume economics. Smart LED redefines vendor relationships through recurring service attachment.
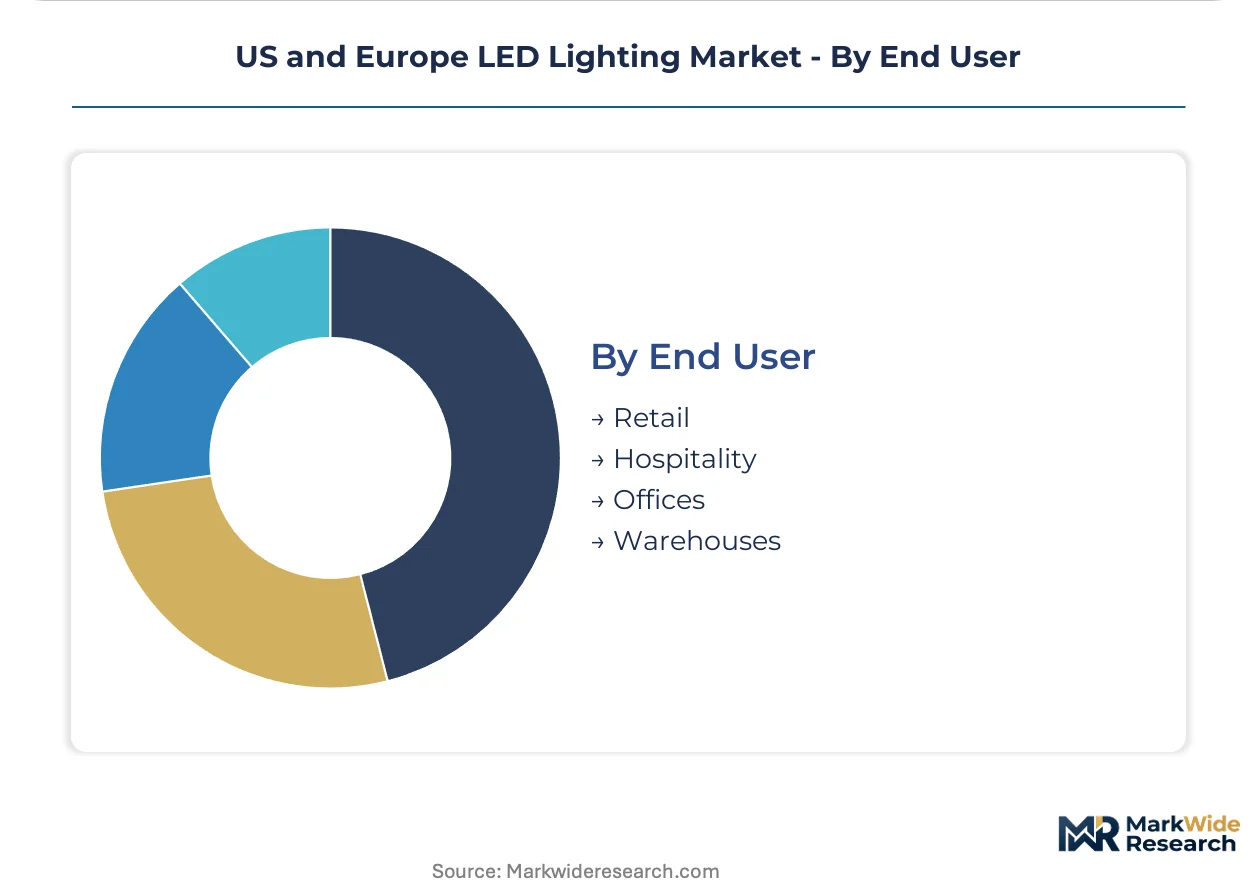
End User:
Warehouse operators and office facility managers exhibit the strongest procurement consolidation around integrated service contracts.
- Warehouses:Logistics operators prioritize rapid payback through 24/7 operating schedules and utility rebate capture. German automotive suppliers and French e-commerce fulfillment centers deploy LiFi-enabled fixtures for secure wireless networking in electromagnetic-sensitive zones.
- Offices:Corporate real estate teams face capital budget constraints that favor lighting-as-a-service models with operational expenditure treatment. Human-centric lighting with circadian rhythm tuning commands specification premiums in Netherlands and California commercial towers.
- Retail:Merchandise presentation requirements drive color rendering index specifications and tunable white installations.
- Hospitality:Guest experience design prioritizes dimming performance and aesthetic fixture forms over raw efficacy metrics.
Warehouses lead on retrofit velocity. Offices present the deepest service-contract penetration opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys specification-grade troffers faster than France accelerates fixture replacement, yet both markets face synchronized pressure from EU Ecodesign Directive Lot 19 compliance deadlines.
United States
California Title 24 mandates and utility rebate programs drive commercial office retrofits with daylight harvesting controls. The Department of Energy enforces ENERGY STAR certification and FTC lighting facts labeling that filters substandard imports. The Pacific Northwest and Northeast Corridor concentrate warehouse and healthcare facility upgrades where lighting-as-a-service models transfer capital expenditure to operating budgets.
Germany
Smart building retrofits in automotive supplier facilities and logistics centers compress replacement cycles for high-bay fixtures with occupancy sensors. The EU Ecodesign Directive and F-Gas Regulation tighten thermal performance thresholds for enclosed luminaires. Bavaria and Baden-Württemberg host pilot deployments of LiFi-enabled fixtures for secure wireless networking in electromagnetic-sensitive manufacturing environments.
France
Corporate real estate teams in commercial towers favor operational expenditure models with guaranteed energy savings clauses. BREEAM certification requirements accelerate LED retrofits with human-centric lighting and circadian rhythm tuning. The Île-de-France region anchors specification-grade demand from facility managers consolidating vendor relationships around integrated service contracts.
United Kingdom
Education and healthcare verticals consolidate procurement around IoT platform providers with multi-year maintenance agreements. The country's building regulations and net-zero targets push municipal and infrastructure verticals toward specification-grade portfolio refreshes. Greater London and the Southeast lead on smart-enabled panel installations with embedded sensor arrays for space utilization analytics.
Poland
Underpenetrated warehouse and manufacturing facility stock offers first-mover positioning before full EU efficiency harmonization phases in. Logistics operators prioritize rapid payback through 24/7 operating schedules and utility rebate capture. The Silesian and Greater Poland industrial clusters attract specification-grade fixture producers seeking expansion ahead of harmonized mandate enforcement.
US and Europe LED Lighting Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier specification relationships concentrated among electrical distributors and facility management platforms. The vendor base organizes around three strategic archetypes: integrated platform providers with IoT software stacks, specification-grade fixture specialists with deep distributor relationships, and component-scale producers with captive substrate sourcing. Consolidation pressure favors multi-year service contracts over transactional hardware sales. Competitive moves center on geographic expansion into Eastern European industrial corridors and portfolio diversification toward human-centric lighting product lines.
Among European-headquartered platform providers, Signify Holding and Zumtobel Group AG exemplify the integrated service-contract archetype. Signify occupies a position anchoring recurring revenue streams through IoT-enabled facility management relationships. Zumtobel represents specification-grade penetration in German and Austrian commercial portfolios. At the North American vector, Acuity Brands Inc. sits within the distributor-relationship archetype, with its specification influence concentrated in professional procurement channels.
| Leading Market Players |
|---|
| Eaton Corporation (Cooper Lighting) |
| Zumtobel Group AG |
| Signify Holding (Philips Lighting) |
| Current Lighting Solutions, LLC. |
| Fagerhult Group |
| OSRAM GmbH |
| LEDVANCE GmbH |
| Schreder SA |
| Acuity Brands Inc. |
| Others |
Value Network & Pricing Analysis
EU Ecodesign Directive Lot 19 efficacy mandates gate qualified supply and premium-tier pricing access, forcing mid-tier luminaire assemblers toward economy positioning while specification-grade producers capture service-attachment premiums through ENERGY STAR and CE-marked portfolios.
Pricing Analysis
Capacity additions in Chinese wafer manufacturing are reshaping price floors for LED chips, compressing margins for fixture-only assemblers without captive sourcing. Three-tier pricing structure across premium, standard, and economy levels separates IoT-enabled platform providers from specification-grade fixture specialists and import-dependent volume players. Price differentiation hinges on certification tier and after-sales service bundling. Cost compression in residential bulb channels intensifies because private-label imports flood big-box retail, while commercial facility managers exhibit lowest price sensitivity due to lighting-as-a-service operational expenditure treatment.
Supply Chain Analysis
CE marking and ENERGY STAR certification gate qualified supply, filtering substandard imports from distribution channels. Substrate fabrication concentrates in China, Taiwan, and South Korea, while driver assembly and luminaire integration cluster in Germany, Mexico, and Vietnam. Rare earth phosphors and sapphire wafers feed from Chinese processing facilities. Single-source vulnerability in rare earth element supply creates exposure to export restriction shocks. Distribution runs through electrical distributors and facility management platforms with specification influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on thermal management cost-down through passive cooling architectures and premium capture via human-centric lighting specification premiums.
For Market Incumbents: Extend platform-rollup capabilities through lighting-as-a-service contract consolidation in North American healthcare and UK education verticals. Deepen backward integration into driver electronics to offset rare earth cost volatility threatening mid-tier margin structures. Defend against IoT platform entrants by anchoring multi-year maintenance agreements with guaranteed energy savings clauses. For New Entrants and Emerging Players: EU Ecodesign Directive Lot 19 in Poland and Romania opens a window for specification-grade fixture penetration before full efficiency harmonization phases in. Target underpenetrated warehouse stock in Silesian industrial clusters with rapid-payback high-bay offerings. Pursue LiFi-enabled fixture pilots with German automotive suppliers as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for IoT platform providers because facility management procurement consolidation favors integrated service contracts over transactional hardware. Five-to-ten-year viability hinges on software stack differentiation and recurring revenue attachment rates. Watch for inflection in Eastern European manufacturing capacity expansion as signal for specification-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Lighting-as-a-Service Platform Expansion | Transfers capital expenditure to operating budgets while locking multi-year recurring revenue in US healthcare verticals. |
| Passive Cooling Architecture Migration | Addresses EU F-Gas Regulation constraints without refrigerant-based thermal management in climate-controlled luminaires. |
| LiFi Communication Integration | Enables secure wireless networking for German automotive suppliers in electromagnetic-sensitive manufacturing zones. |
| Human-Centric Lighting Portfolio Development | Commands specification premiums through circadian rhythm tuning in Netherlands and California commercial towers. |
| Eastern European Geographic Expansion | Captures first-mover positioning in Polish and Romanian warehouse stock before EU efficiency mandate enforcement. |
Research Methodology
Multiple input streams — facility manager procurement directors, electrical distributor specification specialists, luminaire manufacturer product managers, and regulatory affairs leads at notified bodies — were reconciled against customs records, ENERGY STAR certification databases, EU Ecodesign Directive implementation reports, and SEC filings from listed lighting companies. Bottom-up channel checks across German automotive supplier facilities and French logistics centers were triangulated with top-down market sizing from trade flow analysis.
Historical replacement cycle data from 2012-2018 LED retrofit waves were cross-referenced against panel input from facility management procurement departments regarding planned upgrade timelines. Segmentation modeling incorporated product type, application vertical, technology tier, and end-user archetype dimensions across the projection horizon. CAGRs were derived from fixture shipment trajectories, efficacy improvement curves, and service contract attachment rate assumptions. Forecast inputs included EU Ecodesign Directive phase-in schedules and US DOE rulemaking timelines.
Revisions become necessary when regulatory enforcement delays, rare earth supply disruptions, or smart building retrofit acceleration materialize beyond modeled scenarios. Forecasts reflect underlying assumptions about efficacy improvement rates and procurement model transition speeds. A model refresh is warranted upon material change in EU F-Gas Regulation scope or ENERGY STAR specification tightening schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Asia Pacific LED Lighting Market
LED
LED Services Market
LED
China Indoor LED Lighting Market
LED
LED Panel Market
LED
Smart LED Indoor Signage Market
LED
China LED Market
LED
LED Street Light Drivers Market
LED
South America Indoor LED Lighting Market
LED
7 Segment LED Displays Market
LED
Mini LED Display Market
LED
Europe Indoor LED Lighting Market
LED
Europe Outdoor LED Lighting Market
LED
Asia Pacific Indoor LED Lighting Market
LED
Europe LED Packaging Market
LED
Middle East LED Lights Market
LED
LED Flip Chip Market