
 High Power LED Market | 2026-2036
High Power LED Market Size, Share, and Industry Trends Forecast 2026-2036
High Power LED Market Analysis
RoHS is hardening material compliance thresholds for phosphor formulations and substrate metallization across the European supply base. Nichia Corporation leverages captive gallium nitride crystal growth to sustain margin structure in blue pump chips. OSRAM Opto Semiconductors anchors automotive forward-lighting programs through its regulated-channel relationships with Tier-1 module suppliers. Cree LED dominates silicon carbide substrate supply for high-current density architectures.
High power LEDs are semiconductor emitters typically rated above one watt of electrical input, fabricated on sapphire or silicon carbide substrates with flip-chip or vertical electrode geometries, designed to deliver luminous efficacy exceeding 130 lumens per watt in street and industrial applications. Chip-on-Board configurations occupy the highest thermal-density tier where lumen maintenance requirements exceed 50,000 hours, while Surface Mount packages compete on assembly automation compatibility for volume indoor retrofits. Automotive Lighting applications lead value capture due to ADB matrix module complexity, whereas Street Lighting segments anchor unit volume through municipal procurement cycles.
The EU Ecodesign Directive and the US EPA ENERGY STAR framework jointly shape minimum efficacy thresholds and lumen depreciation testing protocols for import eligibility. China's GB standards from SAMR enforce domestic color consistency and thermal cycling specifications that diverge from IEC baselines. Japan's METI Top Runner program accelerates efficiency benchmarks ahead of global harmonization timelines. Stakeholders must monitor divergence between regional test methods as a source of compliance cost fragmentation.
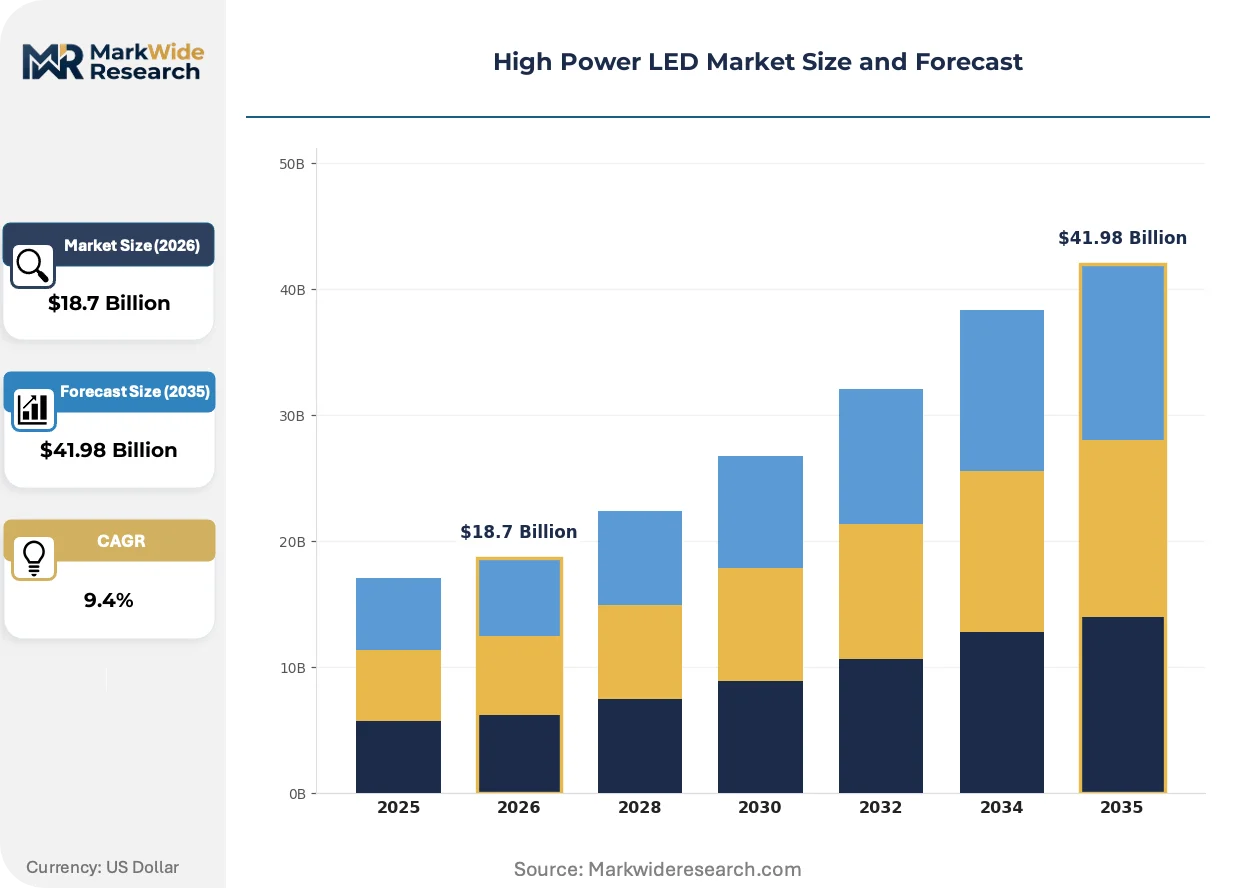
Market Dynamics
Automotive OEMs are dismantling incumbent halogen supply chains as adaptive driving beam modules mandate solid-state architectures with precise pixel control and thermal management density previously unattainable.
Growth Catalysts
- China's dual carbon goals:Municipal procurement guidelines from the MEE now mandate efficacy floors for street lighting retrofits, accelerating replacement cycles in the Yangtze River Delta cluster.
- Chip-on-Board thermal density:Lumen maintenance requirements exceeding 50,000 hours in industrial applications are forcing migration from discrete packages to COB configurations with direct substrate attachment.
- Silicon carbide substrate availability:Foundry capacity expansion in Germany and Japan is resolving prior bottlenecks for high-current density vertical electrode geometries.
Market Restraints
- Gallium nitride crystal supply concentration:Captive ingot growth capabilities remain concentrated among three Japanese and American suppliers, constraining merchant market availability.
- RoHS phosphor formulation compliance:Europium and cerium dopant sourcing restrictions under ECHA scrutiny are forcing reformulation cycles that extend qualification timelines.
- Halogen incumbent residual value:Existing installed base depreciation schedules in Eastern European municipalities delay full LED conversion despite lifecycle cost advantages.
Strategic Opportunities
- India's smart city infrastructure:The CEA's grid modernization directives create demand for networked street lighting with remote dimming and fault detection capabilities.
- Human-centric lighting convergence:Tunable white and circadian rhythm algorithms are integrating high power emitters into healthcare and education specifications.
- Automotive interior ambient expansion:Tier-1 module suppliers are specifying multi-zone RGB architectures that multiply emitter counts per vehicle platform.
Industry Challenges
- Thermal simulation talent scarcity:Computational fluid dynamics expertise for junction temperature prediction remains concentrated among semiconductor packaging veterans.
- GB standard divergence from IEC:China's SAMR color consistency testing protocols require duplicate qualification runs, fragmenting R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Power LED Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chip-on-Board, Surface Mount, High-Bay, Linear Application: Street Lighting, Automotive Lighting, Indoor Lighting, Backlighting Technology: Standard LED, Smart LED, Tunable White, RGB End User: Residential, Commercial, Industrial, Architectural |
| Companies Covered | Nichia Corporation, OSRAM Opto Semiconductors, Lumileds Holding B.V., Cree LED, Samsung Electronics Co. Ltd., Seoul Semiconductor Co. Ltd., EPISTAR Corporation, LG Innotek, Everlight Electronics Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Power LED Market Emerging Trajectories
Packaging architectures are compressing thermal resistance paths while regulatory frameworks fragment test methodologies across major procurement jurisdictions.
Flip-chip electrode geometries are eliminating wire bond thermal bottlenecks in high-current applications. Automotive forward-lighting programs are adopting these configurations for ADB matrix modules where junction temperature stability determines optical precision. The technology is integrating thermal management directly into substrate metallization design rules, collapsing the traditional separation between chip and package engineering functions.
The EU Ecodesign Directive is tightening minimum efficacy thresholds for import eligibility while extending lumen depreciation testing durations. Module suppliers must now maintain 90% output at 6,000 hours under standardized thermal conditions. European street lighting tenders are responding with performance-bond requirements that shift warranty liability to component vendors.
Municipal procurement is consolidating around total-cost-of-ownership frameworks that internalize energy and maintenance over 15-year horizons. Traditional lowest-bid award mechanisms are losing share to performance-contracting structures where ESCOs assume installation risk. This rotation is most visible in German and Dutch infrastructure programs where energy service company accreditation has become a tender prerequisite.
High Power LED Market Segmentation
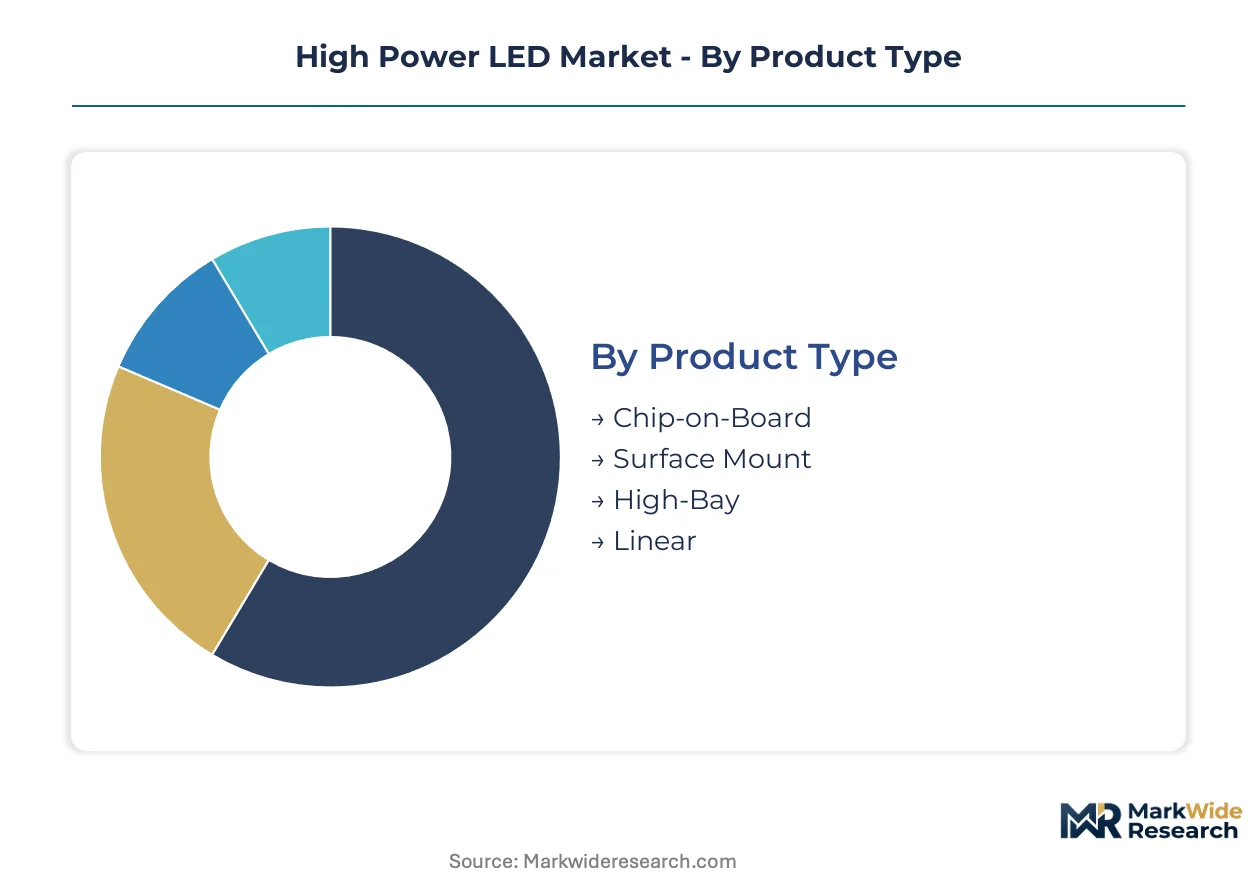
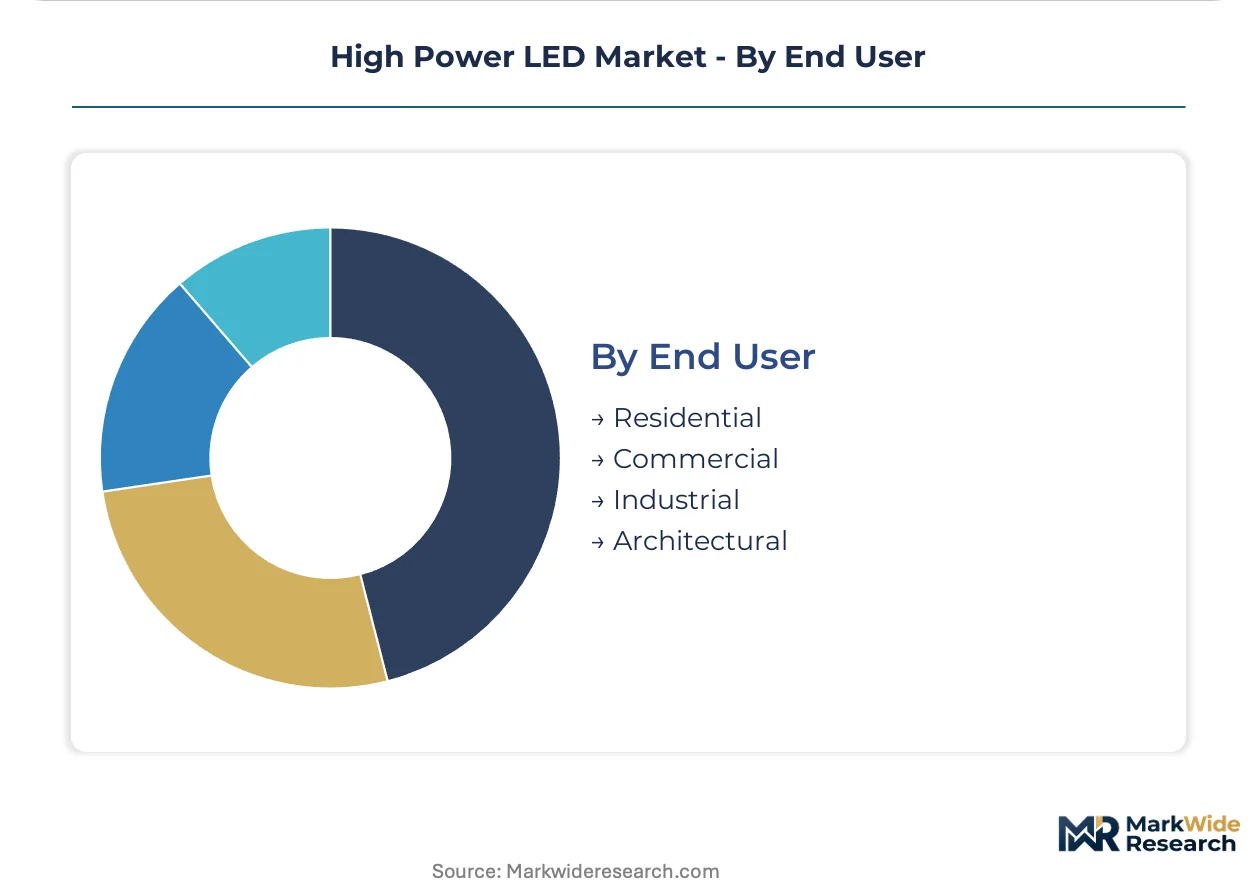
High power LED procurement patterns diverge sharply across thermal density requirements, regulatory compliance frameworks, and installation scale economics. Manufacturers configure substrate geometries and phosphor formulations specifically for each segment's lumen maintenance and color consistency thresholds.
Product Type:
Customization intensity spans from fully standardized surface mount packages to application-specific thermal substrates requiring co-design with module integrators.
- Chip-on-Board:Direct die attachment to aluminum or ceramic substrates eliminates wire bond thermal resistance. Municipal street lighting programs in China's Yangtze River Delta specify COB architectures for 50,000-hour lumen maintenance guarantees under GB standards from SAMR.
- Surface Mount:Standardized package footprints enable high-volume pick-and-place assembly automation. Indoor retrofit demand concentrates in German commercial building efficiency programs governed by EU Ecodesign Directive efficacy floors.
- High-Bay:Optimized for industrial ceiling heights with specialized optic beam patterns.
- Linear:Configured for continuous run installations in warehousing and transportation infrastructure.
Leading the category by volume: Surface Mount. Expanding most quickly: Chip-on-Board.
Application:
Margin structure correlates directly with optical complexity and thermal management density requirements.
- Automotive Lighting:Adaptive driving beam matrix modules demand pixel-level optical precision and junction temperature stability. Tier-1 suppliers specify flip-chip geometries with silicon carbide substrates for forward-lighting programs.
- Street Lighting:Anchors unit volume through municipal procurement cycles with 15-year total-cost-of-ownership frameworks. India's CEA grid modernization directives accelerate networked fixture deployment with remote dimming capabilities.
- Indoor Lighting:Commercial retrofit volume driven by energy service company performance contracting in Dutch and German infrastructure programs.
- Backlighting:Large-format display applications with specific luminance uniformity requirements.
Commanding premium pricing: Automotive Lighting. Steepest expansion trajectory: Street Lighting.
Technology:
Intelligence integration separates commodity emitters from specification-grade solutions with embedded control architectures.
- Smart LED:Integrated drivers and communication protocols enable networked lighting management. Human-centric lighting specifications in healthcare and education facilities require circadian rhythm algorithm compatibility.
- Tunable White:Correlated color temperature adjustment from 2700K to 6500K supports biological lighting design. Japan's METI Top Runner program accelerates efficiency benchmarks for these variable-output configurations.
- Standard LED:Fixed output emitters for cost-sensitive high-volume replacement markets.
- RGB:Multi-channel architectures for architectural accent and automotive ambient interior applications.
Highest current R&D allocation: Smart LED. Gaining specification share fastest: Tunable White.
End User:
Procurement sophistication varies from residential price sensitivity to industrial total-cost-of-ownership modeling.
- Industrial:Chip-on-Board thermal density configurations dominate where operating hours exceed 6,000 annually. Foundry capacity expansion in Germany and Japan resolves prior silicon carbide substrate bottlenecks for high-current density vertical electrode geometries.
- Commercial:ESCO-accredited performance contracting structures predominate in German and Dutch tender frameworks with 15-year energy and maintenance internalization.
- Residential:Price-driven retrofit demand with shorter payback horizon requirements.
- Architectural:Specification-driven projects with custom optic and color rendering requirements.
Leading specification complexity: Industrial. Fastest procurement volume growth: Commercial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta manufacturing cluster concentrates substrate foundries and packaging houses, while municipal procurement across Germany, Japan, India, and the United States drives specification-grade demand through divergent regulatory frameworks.
China
MEE dual carbon goals mandate efficacy floors for street lighting retrofits, accelerating replacement cycles in municipal infrastructure. SAMR enforces GB standards for color consistency and thermal cycling that diverge from IEC baselines. The Yangtze River Delta cluster co-locates substrate foundries with packaging houses to serve domestic procurement.
Germany
ESCO-accredited performance contracting structures predominate in infrastructure tenders with 15-year total-cost-of-ownership frameworks. The EU Ecodesign Directive tightens minimum efficacy thresholds and extends lumen depreciation testing durations. Foundry capacity expansion in German industrial regions resolves silicon carbide substrate bottlenecks for high-current density architectures.
Japan
METI Top Runner program accelerates efficiency benchmarks ahead of global harmonization timelines for variable-output configurations. Municipal and industrial procurement follows JIS standards with stringent lumen maintenance requirements. Kyushu and Kansai manufacturing bases sustain captive gallium nitride crystal growth capabilities among leading suppliers.
India
CEA grid modernization directives create demand for networked street lighting with remote dimming and fault detection capabilities. Smart city infrastructure programs specify Chip-on-Board thermal density configurations for 50,000-hour operating life. Procurement concentrates in Maharashtra and Gujarat industrial corridors with domestic assembly integration.
United States
EPA ENERGY STAR framework shapes minimum efficacy thresholds and lumen depreciation testing protocols for import eligibility across commercial retrofit segments. Municipal procurement cycles in California and Texas anchor unit volume through performance-bond requirements. Automotive forward-lighting programs in Michigan and the Southeast specify silicon carbide substrates for adaptive driving beam modules.
High Power LED Market Vendor Landscape
Japanese and American producers anchor the premium substrate tier; Chinese and South Korean specialists hold volume manufacturing positions. The vendor base splits between vertically integrated compound semiconductor fabricators and merchant packaging houses serving modular integrators. Three archetypes dominate: captive crystal growers with proprietary substrate supply, automotive-qualified module suppliers with regulated-channel relationships, and scale-driven packaging houses competing on assembly automation. Competitive moves concentrate on foundry capacity expansion for silicon carbide substrates and strategic partnerships for phosphor formulation qualification.
Among Japanese compound semiconductor specialists, Nichia Corporation and OSRAM Opto Semiconductors exemplify the captive supply archetype through upstream control over gallium nitride crystal growth and regulated-channel positioning in automotive forward-lighting. Cree LED anchors American substrate specialization for high-current density vertical electrode geometries. These three occupy positions where thermal management density and optical precision requirements filter out merchant-market competitors.
| Leading Market Players |
|---|
| Nichia Corporation |
| OSRAM Opto Semiconductors |
| Lumileds Holding B.V. |
| Cree LED |
| Samsung Electronics Co. Ltd. |
| Seoul Semiconductor Co. Ltd. |
| EPISTAR Corporation |
| LG Innotek |
| Everlight Electronics Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Substrate-tier divergence between silicon carbide premium architectures and sapphire-based commodity emitters manifests in parallel pricing and sourcing configurations. Automotive forward-lighting programs absorb silicon carbide premiums through regulated-channel relationships, while municipal street lighting procurement in China's Yangtze River Delta drives sapphire substrate volume through standardized GB compliance tiers.
Pricing Analysis
Volume-margin splits separate automotive ADB matrix modules commanding specification premiums from high-bay industrial retrofits competing on lumen-per-dollar metrics. Three-tier pricing structure across automotive-qualified, industrial-performance, and economy-retail levels tracks certification depth under EU Ecodesign Directive and China's SAMR thermal cycling protocols. Cost compression in surface-mount packages intensifies as German ESCO performance contracting internalizes 15-year maintenance liabilities. Residential retrofit buyers exhibit highest price sensitivity, whereas Tier-1 automotive module suppliers prioritize junction temperature stability over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and China's Yangtze River Delta operate hub-and-spoke patterns for substrate foundry outputs. Merchant gallium nitride crystal supply draws from captive ingot growth in Kyushu and Michigan, while phosphor formulation feeds from Dutch and Chinese specialty chemical processors. Single-source vulnerability concentrates in silicon carbide substrate supply from German and Japanese foundry expansions. Distribution runs through Tier-1 module suppliers with automotive-qualified packaging houses, bypassing merchant markets for specification-grade applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
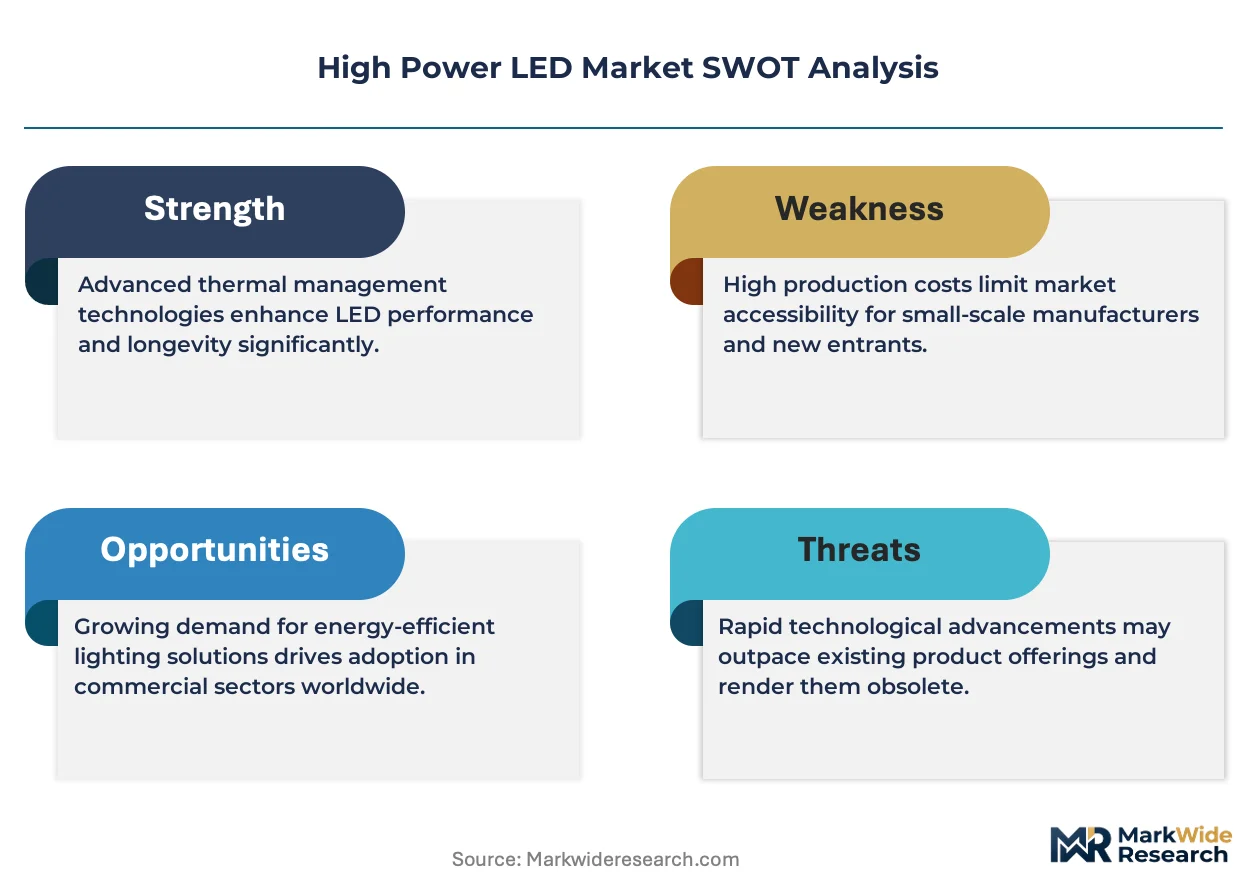
RoHS phosphor formulation compliance under ECHA scrutiny has erected a cost-of-compliance barrier that filters out undercapitalized packaging houses, concentrating margin capture among qualified compound semiconductor fabricators with in-house reformulation capabilities.
For Market Incumbents: To counter merchant gallium nitride crystal supply constraints, anchor positions through captive substrate foundry expansion in Germany or Japan, while deepening phosphor formulation qualification partnerships with ECHA-registered specialty chemical suppliers to extend compliance moats. For New Entrants and Emerging Players: Flip-chip thermal management expertise offers entry into India's CEA-mandated smart city infrastructure where 50,000-hour lumen maintenance specifications remain underpenetrated by established automotive-qualified suppliers. Target networked street lighting deployments in Maharashtra and Gujarat industrial corridors through direct ESCO channel relationships. For Investors and Strategic Acquirers: Re-rating potential sits with captive gallium nitride crystal growers given METI Top Runner efficiency acceleration and China's dual carbon procurement mandates tightening substrate supply inelasticity. Monitor silicon carbide foundry utilization rates as inflection signal for margin expansion in high-current density vertical electrode architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Expansion | Resolves substrate bottlenecks for ADB matrix modules under German automotive qualification. |
| Phosphor Formulation Requalification | ECHA RoHS compliance extends tender eligibility across EU municipal procurement cycles. |
| Flip-Chip Packaging Scale-Up | Eliminates wire bond thermal resistance for India's CEA smart city lumen maintenance specifications. |
| ESCO Channel Accreditation | Unlocks German and Dutch performance contracting with 15-year total-cost frameworks. |
| GB Standard Parallel Qualification | Captures Yangtze River Delta municipal procurement diverging from IEC baselines. |
Methodological Framework
Independent corroboration across packaging house operations directors, Tier-1 automotive module procurement leads, municipal infrastructure planners, and phosphor formulation chemists underwrites the qualitative findings. Secondary validation draws from SAMR GB standard filings, EU Ecodesign Directive efficacy databases, ECHA substance restriction notifications, and CEA grid modernization directives. Bottom-up emitter shipment analysis triangulates against top-down municipal procurement budget allocations across the analysis window.
Rate-of-change decomposition separates substrate foundry capacity expansion effects from regulatory mandate acceleration in automotive lighting and street infrastructure segments. The analytical framework models product type, application complexity, technology integration level, and end-user procurement sophistication across the projection horizon. CAGRs derive from segment-level volume trajectory reconciliation with value capture in premium substrate tiers and thermal density configurations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under gallium nitride crystal supply disruption or ECHA phosphor dopant restriction escalation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Outdoor LED Display Market
LED
Programmable LED Drivers Market
LED
LED Display Market
LED
Japan Indoor LED Lighting Market
LED
UK Outdoor LED Lighting Market
LED
South America LED Lighting Market
LED
France Outdoor LED Lighting Market
LED
LED Floodlight Drivers Market
LED
Thailand LED Market
LED
Surface Mount PLCC Leds Market
LED
LED Street Light Drivers Market
LED
Africa LED Lighting Market
LED
Global Outdoor LED Lighting Market
LED
Germany LED Lighting Market
LED
Linear LED Strip Fixture Market
LED
LED Tube Market