
 Dual-Digit 7 Segment LED Displays Market | 2026-2036
Dual-Digit 7 Segment LED Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Dual-Digit 7 Segment LED Displays Market Analytics
Industrial buyer concentration is rebalancing as original equipment manufacturers consolidate display procurement across fewer qualified vendors while specialist integrators fragment demand into application-specific batches. Kingbright leverages its vertical integration in LED chip packaging to sustain cost advantages in high-volume common cathode production. Vishay Intertechnology anchors North American supply through its broad distributor network and automotive qualification pedigree. Broadcom Inc. competes primarily in hybrid technology modules where signal conditioning integration commands premium positioning.
Dual-digit 7 segment LED displays combine two independent seven-segment arrays in a single package, typically driven through multiplexed cathode or anode configurations with forward voltages between 1.8V and 2.2V per segment depending on semiconductor material. These devices serve as numeric readout elements in equipment requiring compact, reliable numerical indication without full graphical capability. Common cathode architectures dominate industrial equipment applications where simplified driving circuitry reduces bill-of-material complexity, while ultra-bright variants capture outdoor and high-ambient-light segments at elevated margin pools. Multi-color configurations represent the fastest-growing technology subset as appliance designers adopt dual-color indication for status and alarm states in a single mechanical footprint.
RoHS and REACH compliance in the European Union restricts hazardous substance content in display housings and solder interfaces, while the CE marking framework mandates electromagnetic compatibility testing for microcontroller-based digital variants. The United States FCC governs unintentional radiated emissions from digital drive circuitry, particularly affecting hybrid and microcontroller-based technology segments. Stakeholders must monitor evolving efficiency benchmarks from the EU Ecodesign framework and assess qualification pathways for medical device displays under FDA device regulations.
Market Dynamics
Industrial OEM procurement consolidation is compressing vendor margins while fragmenting demand into application-specific batches, forcing display manufacturers to defend position through qualification pedigree and captive chip supply.
Growth Catalysts
- EU Ecodesign efficiency mandates:Appliance OEMs in Germany and France are retrofitting control panels with low-current common cathode architectures to meet standby power limits.
- Outdoor signage digitization:Ultra-bright variants with forward voltage optimization are capturing traffic management and parking meter retrofits in high-ambient-light environments.
- Process control interface standardization:Multi-color dual-digit configurations are displacing separate indicator lamps in PLC-based industrial equipment across US Midwest manufacturing clusters.
Market Restraints
- Epoxy resin and copper leadframe volatility:Housing and interconnect material costs swing with petrochemical and base metal indices, squeezing mid-volume contract manufacturers.
- Backend packaging concentration in Taiwan and Malaysia:Die-attach and wire-bond capacity bottlenecks create allocation risk for non-priority customers during semiconductor upswings.
- OLED and e-paper substitution in consumer timers:Battery-operated portable devices are migrating to lower-power alternatives for extended runtime.
Strategic Opportunities
- Medical device qualification pathways:FDA 510(k) clearance for vital signs monitors creates premium positioning for displays with documented biocompatibility and EMC test history.
- India appliance manufacturing expansion:BIS certification requirements and PLI scheme incentives are pulling display sourcing toward domestic assembly for air conditioner and inverter control panels.
- Hybrid module signal conditioning integration:Combining LED drive with microcontroller-based serial interfaces is consolidating BOM count in space-constrained industrial handhelds.
Industry Challenges
- RoHS and REACH substance tracking:OEMs demand full material declaration documentation through three-tier supplier depth, extending qualification timelines.
- Legacy 5V TTL interface obsolescence:Equipment refresh cycles lag behind 3.3V CMOS logic migration, forcing dual-voltage drive circuit complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual-Digit 7 Segment LED Displays Market |
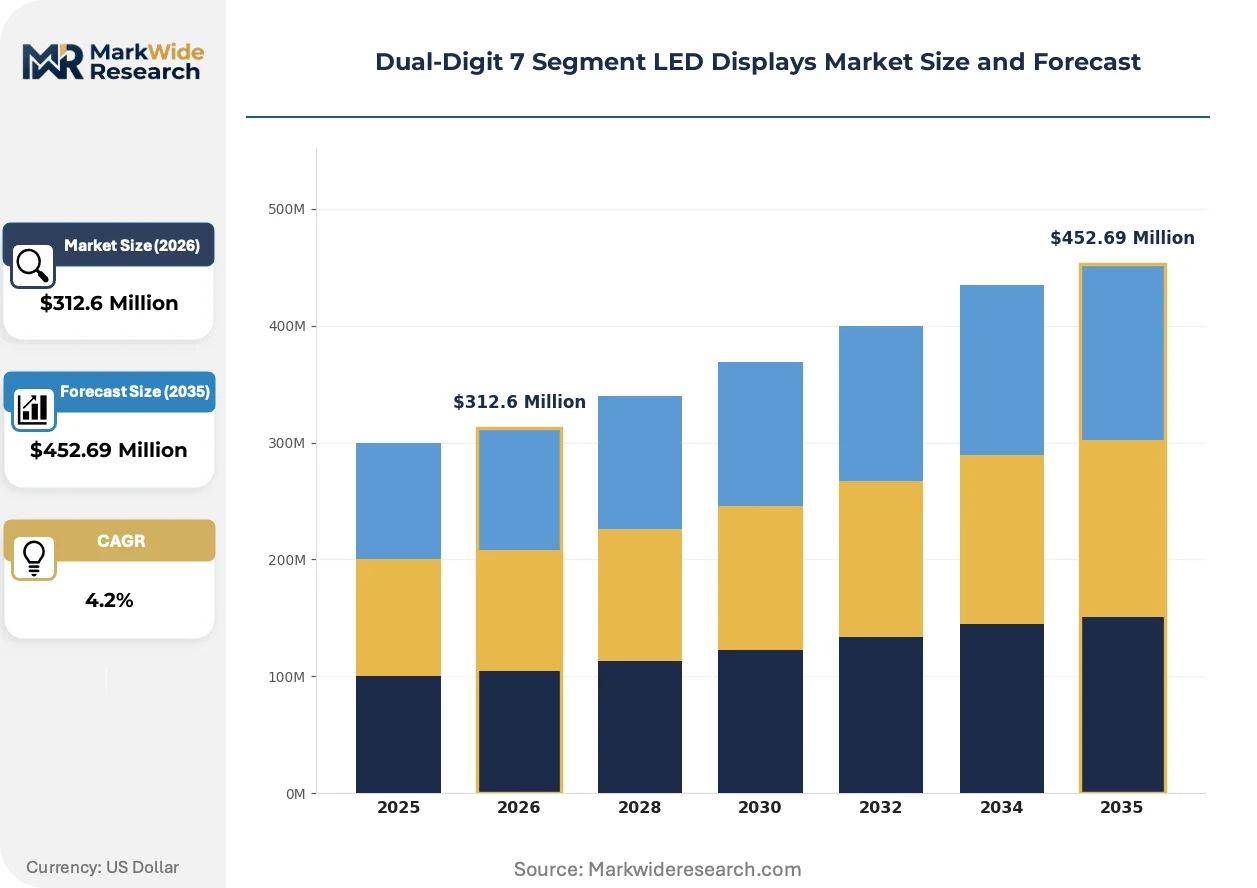
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $452.69 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Common Cathode, Common Anode, Multi-Color, Ultra-Bright End User: Consumer Electronics, Industrial Equipment, Automotive Applications, Medical Devices Technology: Analog, Digital, Hybrid, Microcontroller-Based Application: Home Appliances, Clocks, Measurement Instruments, Gaming Devices |
| Companies Covered | Kingbright, Broadcom Inc., Lumex Inc., Visual Communications Company, Forge Europa, LITE-ON Technology Corporation, Everlight Electronics, Oasistek, Vishay Intertechnology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual-Digit 7 Segment LED Displays Market Evolving Landscape
Display technology evolution is compressing mechanical footprint while expanding functional density, with regulatory pressure and procurement rationalization as concurrent forcing mechanisms.
Chip-on-board (COB) packaging is consolidating segment drive electronics directly onto the ceramic or FR4 substrate, eliminating discrete LED packages and wire bonds. Industrial automation OEMs in Germany and Japan are specifying COB modules for 50,000-hour lifetime targets in continuous-operation environments. This architecture is consolidating supplier tiers by collapsing die sourcing, packaging, and module assembly into single-source qualification.
REACH substance restriction enforcement through ECHA is tightening cadmium and lead thresholds in display housings and solder interfaces, with downstream documentation obligations extending to distributors. Medical and appliance OEMs are responding with Design for Environment (DfE) specifications that pre-qualify compliant material sets. The heaviest compliance burden falls on small-batch integrators lacking in-house toxicology assessment.
Vendor-managed inventory programs are displacing traditional purchase-order cycles for high-volume appliance manufacturers, with consignment stock positioned at Tier 1 EMS facilities. This shift transfers working capital burden upstream while locking in volume commitments through multi-year frame agreements. The restructuring is most advanced in US and Chinese white-goods production clusters where procurement teams have consolidated supplier panels below five qualified vendors.
Dual-Digit 7 Segment LED Displays Market Segmentation
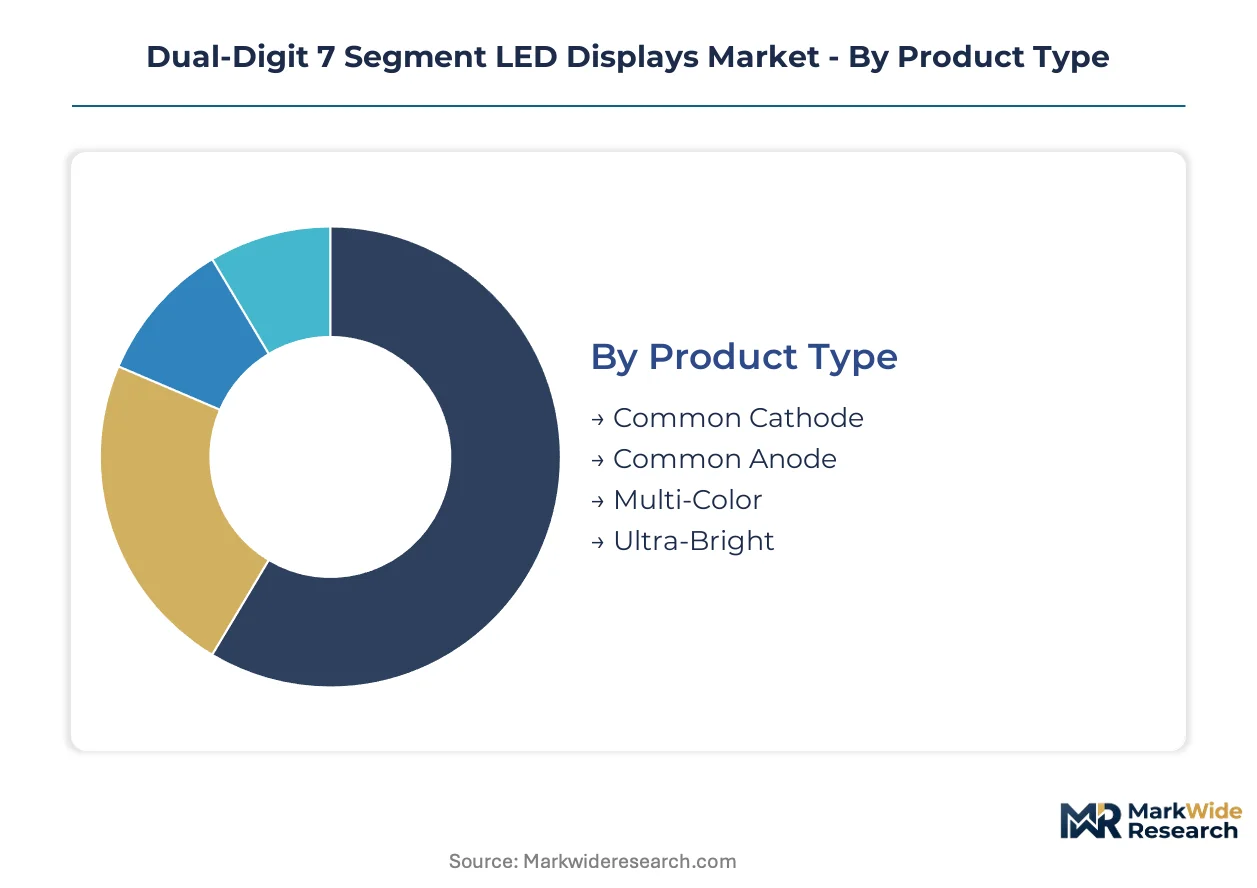
Segmentation in dual-digit 7 segment LED displays reflects divergent supply chain economics across electrical architectures, end-use reliability requirements, and interface complexity tiers. Procurement patterns fragment sharply between high-volume appliance manufacturers seeking cost-optimized common cathode units and specialized industrial buyers prioritizing qualification pedigree over unit price.
Product Type:
Supply concentration in chip packaging and leadframe stamping favors producers with captive die attach capacity, compressing margins for outsourced assemblers.
- Common Cathode:Multiplexed cathode configurations simplify drive circuitry through shared ground paths, reducing external component count. Industrial equipment manufacturers in Germany specify these architectures for PLC interface panels where bill-of-material minimization outweighs marginal efficiency losses.
- Ultra-Bright:Forward voltage optimization and enhanced phosphor formulations deliver luminance exceeding 5000 mcd for direct sunlight readability. Traffic management system retrofits in the United States and parking meter installations across Australian municipalities concentrate demand for these elevated-margin variants.
- Common Anode:Shared positive rail architectures suit specific legacy industrial control systems with established sourcing patterns.
- Multi-Color:Dual-color die configurations enable status and alarm indication within identical mechanical footprints, gaining appliance design wins.
Today's leader: Common Cathode. Tomorrow's challenger: Multi-Color.
End User:
Cost tier stratification separates qualified medical and automotive suppliers from commodity consumer electronics vendors competing on cycle time.
- Industrial Equipment:Continuous-operation environments specify 50,000-hour lifetime targets with documented thermal cycling resistance. Process control interface standardization across US Midwest manufacturing clusters sustains volume procurement through multi-year frame agreements.
- Medical Devices:FDA 510(k) clearance requirements and biocompatibility documentation create substantial qualification barriers. Vital signs monitor manufacturers pay premium positioning for displays with established electromagnetic compatibility test histories and material declaration depth through three-tier supplier tracking.
- Consumer Electronics:Price-sensitive procurement favors offshore assembly with minimized qualification overhead.
- Automotive Applications:AEC-Q100 stress test qualification and thermal grade specifications filter supplier panels aggressively.
Medical Devices command the steepest pricing tier. Industrial Equipment delivers the steadiest volume base.
Technology:
Volume concentration in legacy analog and digital segments contrasts with emerging hybrid architectures consolidating signal conditioning functions.
- Hybrid:Integrated LED drive with serial communication interfaces reduces microcontroller I/O requirements and external component count. Space-constrained industrial handheld manufacturers specify these modules where printed circuit board area commands severe premiums.
- Microcontroller-Based:Embedded intelligence enables dynamic brightness adjustment, diagnostic feedback, and protocol translation. Appliance OEMs in China adopt these configurations for smart home integration requiring non-volatile parameter storage.
- Analog:Direct segment drive without intermediate processing persists in cost-minimized timer and counter applications.
- Digital:Standard logic-level interfaces dominate established industrial equipment with stable specification requirements.
Hybrid modules are climbing the fastest. Analog maintains the largest installed base.
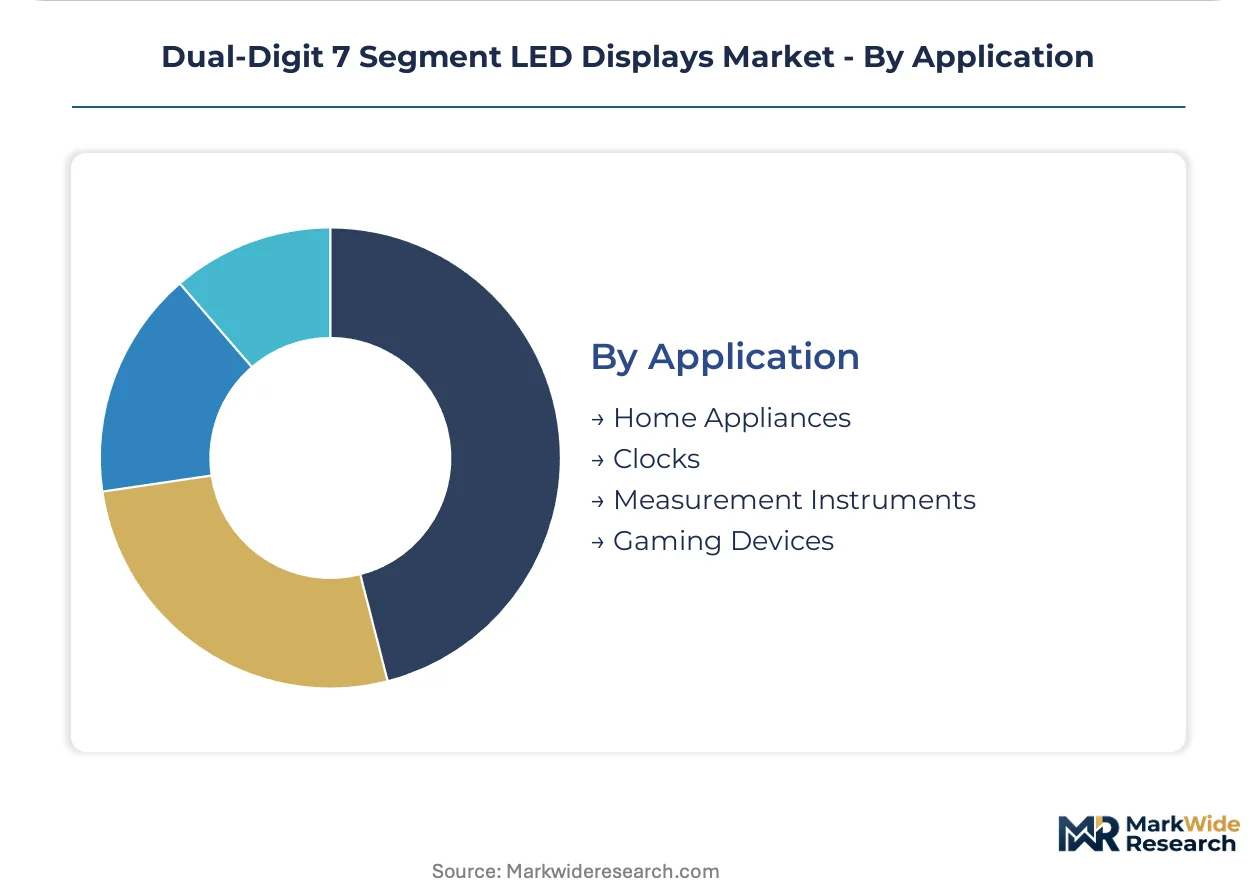
Application:
Margin structure varies dramatically between replacement-driven home appliance refresh cycles and specialized measurement instrument requirements.
- Home Appliances:Air conditioner and washing machine control panels in India concentrate demand following PLI scheme manufacturing incentives. BIS certification requirements pull sourcing toward domestic assembly operations with established component qualification pathways.
- Measurement Instruments:Precision readout applications specify tight luminance uniformity and segment-to-segment color consistency. Laboratory equipment manufacturers in Switzerland and Japan source through qualified vendor lists with extensive incoming inspection protocols.
- Clocks:Battery-operated timer applications face accelerating OLED and e-paper substitution pressure.
- Gaming Devices:Aesthetic integration requirements favor custom mechanical packaging over standard catalog offerings.
Home Appliances generate the highest unit volumes. Measurement Instruments sustain the most defensible margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates industrial automation demand while China dominates appliance manufacturing scale, creating divergent procurement patterns across the dual-digit 7 segment LED displays supply base.
United States
Midwest manufacturing clusters in Michigan and Ohio drive process control interface standardization for PLC-based equipment. FCC regulations govern unintentional radiated emissions from digital drive circuitry, particularly affecting hybrid and microcontroller-based technology segments. Traffic management system retrofits in California and Texas concentrate demand for ultra-bright variants with direct sunlight readability.
Germany
Industrial equipment manufacturers in Bavaria and Baden-Württemberg specify common cathode architectures for bill-of-material minimization in automation panels. EU Ecodesign efficiency mandates push appliance OEMs toward low-current display architectures to meet standby power limits. The Stuttgart and Munich industrial corridors sustain dense supplier networks for 50,000-hour lifetime targets in continuous-operation environments.
China
Air conditioner and washing machine production in Guangdong and Jiangsu provinces generates high-volume procurement for home appliance control panels. GB standards and MIIT regulations shape electromagnetic compatibility requirements for microcontroller-based digital variants. Yangtze River Delta manufacturing clusters anchor backend packaging capacity for die-attach and wire-bond operations serving regional display assembly.
India
PLI scheme incentives pull air conditioner and inverter control panel manufacturing toward domestic assembly operations. BIS certification requirements mandate component qualification pathways for display sourcing in appliance production. Maharashtra and Gujarat industrial zones concentrate emerging demand as OEMs establish regional supply chains to serve South Asian markets.
Japan
Measurement instrument manufacturers in Tokyo and Osaka specify tight luminance uniformity for precision laboratory equipment readout applications. METI efficiency benchmarks and JIS standards govern industrial display performance specifications. Nagoya-area automotive suppliers filter vendor panels aggressively through AEC-Q100 stress test qualification requirements for thermal grade specifications.
Dual-Digit 7 Segment LED Displays Market Competitive Landscape
Taiwanese and Chinese producers anchor the high-volume tier; European and North American specialists hold qualification-dependent positions in medical and automotive segments. The vendor base separates into three strata: captive chip packagers with backward integration into LED die sourcing, distributor-anchored broadliners with automotive qualification pedigree, and application-specific integrators serving fragmented industrial batches. Consolidation pressure from OEM procurement rationalization forces competitive moves around multi-year frame agreements and vendor-managed inventory programs.
Among Taiwan-based fabricators, LITE-ON Technology Corporation and Everlight Electronics occupy positions within the scale-driven archetype, leveraging regional packaging capacity for cost-optimized common cathode production. Kingbright represents the vertically integrated specialist tier, with captive control over LED chip packaging sustaining advantages in high-volume segments. Vishay Intertechnology anchors North American supply through broad distribution networks, exemplifying the qualification-focused broadliner archetype that serves industrial and automotive end-users requiring documented EMC test histories.
| Leading Market Players |
|---|
| Kingbright |
| Broadcom Inc. |
| Lumex Inc. |
| Visual Communications Company |
| Forge Europa |
| LITE-ON Technology Corporation |
| Everlight Electronics |
| Oasistek |
| Vishay Intertechnology Inc. |
| Others |
Value Network & Pricing Analysis
Appliance OEM procurement consolidation across fewer qualified vendors concentrates price-setting power among chip packagers with captive die attach capacity. This buyer concentration shifts pricing models toward multi-year frame agreements with vendor-managed inventory programs that transfer working capital burden upstream.
Pricing Analysis
Capacity additions in Malaysia and Taiwan are reshaping price floors for common cathode variants while ultra-bright and multi-color configurations sustain premium positioning through phosphor formulation differentiation. Three-tier pricing structure across medical-grade, industrial-qualified, and consumer-economy levels separates FDA-cleared displays with biocompatibility documentation from commodity timer applications. Cost compression in high-volume appliance tiers intensifies because OEMs consolidate supplier panels below five qualified vendors. Consumer electronics buyers exhibit highest price sensitivity while medical device manufacturers accept steep premiums for established EMC test histories.
Supply Chain Analysis
Workforce availability constraints in Guangdong and Jiangsu provinces are tightening backend packaging capacity for die-attach and wire-bond operations serving regional display assembly. Manufacturing concentrates in China, Taiwan, and Malaysia where LED chip fabrication and module assembly anchor regional supply networks. Raw material dependencies center on gallium arsenide wafers, epoxy resin housings, and copper leadframes tethered to petrochemical and base metal indices. Single-source vulnerability in Taiwan-based die-attach capacity creates allocation risk for non-priority customers during semiconductor upswings. Distribution runs through broadline distributors and Tier 1 EMS facilities with consignment stock positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dual-digit 7 segment LED displays market functions as a stable compounder where industrial automation refresh cycles and appliance manufacturing expansion in India generate predictable demand trajectories.
For Market Incumbents: Anchor qualification pedigree through AEC-Q100 and FDA 510(k) clearance pathways to defend against OLED substitution in portable timers and hybrid module encroachment. Deepen backward integration into LED chip packaging to sustain cost advantages as epoxy resin and copper leadframe volatility squeezes mid-volume contract manufacturers. Lock in multi-year frame agreements with vendor-managed inventory programs to secure volume commitments from consolidating appliance OEMs. For New Entrants and Emerging Players: The price-point gap between medical-grade premium displays and economy consumer timers creates entry space for mid-tier industrial specialists with targeted certification investment. Target India appliance manufacturing expansion under PLI scheme incentives where BIS certification requirements favor domestic assembly partnerships over established offshore suppliers. Pursue hybrid module development combining LED drive with serial interfaces to capture space-constrained industrial handheld applications. For Investors and Strategic Acquirers: Industrial automation OEMs are the most active acquirer in this space, seeking captive display supply to secure component availability for process control interface standardization. Long-term viability rests on qualification depth rather than volume scale, favoring targets with documented biocompatibility and EMC test histories across three-tier supplier tracking. Watch for FDA medical device submission acceleration as inflection signal for premium positioning demand.| Strategic Initiative | Industry Significance |
|---|---|
| Chip-on-Board Packaging Transition | COB modules eliminate wire bonds for 50,000-hour lifetime targets in German automation environments. |
| Multi-Color Configuration Development | Dual-color die integration captures appliance design wins for status and alarm indication consolidation. |
| Medical Device Qualification Pathway | FDA 510(k) clearance creates premium positioning for vital signs monitor display suppliers. |
| India Manufacturing Footprint Expansion | BIS certification and PLI scheme incentives pull sourcing toward domestic assembly operations. |
| Hybrid Module Signal Integration | Combining LED drive with microcontroller interfaces reduces BOM count in space-constrained handhelds. |
Research Methodology
Bottom-up industrial equipment and appliance modeling reconciled against top-down LED packaging capacity tracking forms the analytical core of this study. Primary interviews with display procurement managers at appliance OEMs, industrial automation engineers, medical device regulatory affairs leads, and EMS supply chain directors combined with secondary validation from SEC 10-K filings, customs trade data, FDA 510(k) clearance databases, and ECHA REACH substance restriction updates. Triangulation across these sources calibrated segment-level volume and value estimates.
Input-output matrices mapped die attach capacity, leadframe stamping output, and module assembly throughput against end-use demand across common cathode, ultra-bright, and multi-color product tiers. Segmentation dimensions modeled include electrical architecture, end-user reliability requirements, interface complexity tiers, and regional manufacturing cluster concentration. CAGRs were derived from installed base replacement cycles, appliance production forecasts, and industrial automation capital expenditure patterns across the projection horizon.
Caveats apply where EU Ecodesign efficiency mandate acceleration, Taiwan packaging capacity allocation disruptions, or OLED substitution penetration in battery-operated devices could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
UK Outdoor LED Lighting Market
LED
LED High Bay Drivers Market
LED
Germany Outdoor LED Lighting Market
LED
LED Lighting Controllers Market
LED
LED Work Light Market
LED
France Outdoor LED Lighting Market
LED
LED Light Bar Market
LED
United States Micro LED Market
LED
North America Micro-LED Display Market
LED
LED Power Supplies Market
LED
Mini LED Market
LED
East Africa LED Lighting Market
LED
LED Phosphor Materials Market
LED
Russia LED Market
LED
Africa LED and OLED Displays and Lighting Products Market