
 Global Smart Tailgate Market | 2026-2036
Global Smart Tailgate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Tailgate Market Outlook
Premium hands-free actuation is bifurcating the competitive landscape into factory-integrated and retrofit-upgrade tiers. Magna International leverages its captive stamping and mechatronics capacity to dominate OEM supply contracts for electric tailgate assemblies. Bosch sustains technology leadership through ultrasonic sensor fusion and capacitive foot-activation modules. Continental competes on integrated control-unit architectures that bundle tailgate logic with central vehicle gateways.
A smart tailgate is an electronically actuated rear vehicle closure system incorporating proximity sensors, motorized struts, and wireless authentication protocols to enable hands-free opening and closing. The assembly typically integrates torque-rich linear actuators, anti-pinch force-feedback circuits, and IP67-rated control modules to withstand repeated cargo-area exposure. Electric tailgate systems anchor the value pool due to their prevalence in mid-luxury crossovers and full-size pickups, while ultrasonic authentication technology leads growth as OEMs phase out physical key fob dependency. Factory-installed configurations occupy the dominant margin tier because captive assembly eliminates aftermarket calibration risks and warranty exposure.
NHTSA rear-visibility standards and EU MDR pedestrian-impact protocols are forcing structural reinforcement and sensor redundancy into tailgate designs, raising engineering compliance costs. ISO 26262 functional-safety ratings and CE marking under the EU Machinery Directive govern market access for electromechanical subsystems in Europe and North America. Stakeholders must monitor how cybersecurity regulations for vehicle entry systems evolve across multiple jurisdictions, as wireless authentication surfaces become attack vectors requiring standardized encryption mandates.
Market Dynamics
Factory-level integration of hands-free actuation systems is compressing aftermarket upgrade windows while concentrating procurement power among luxury SUV and full-size pickup OEMs in Germany, the United States, and China.
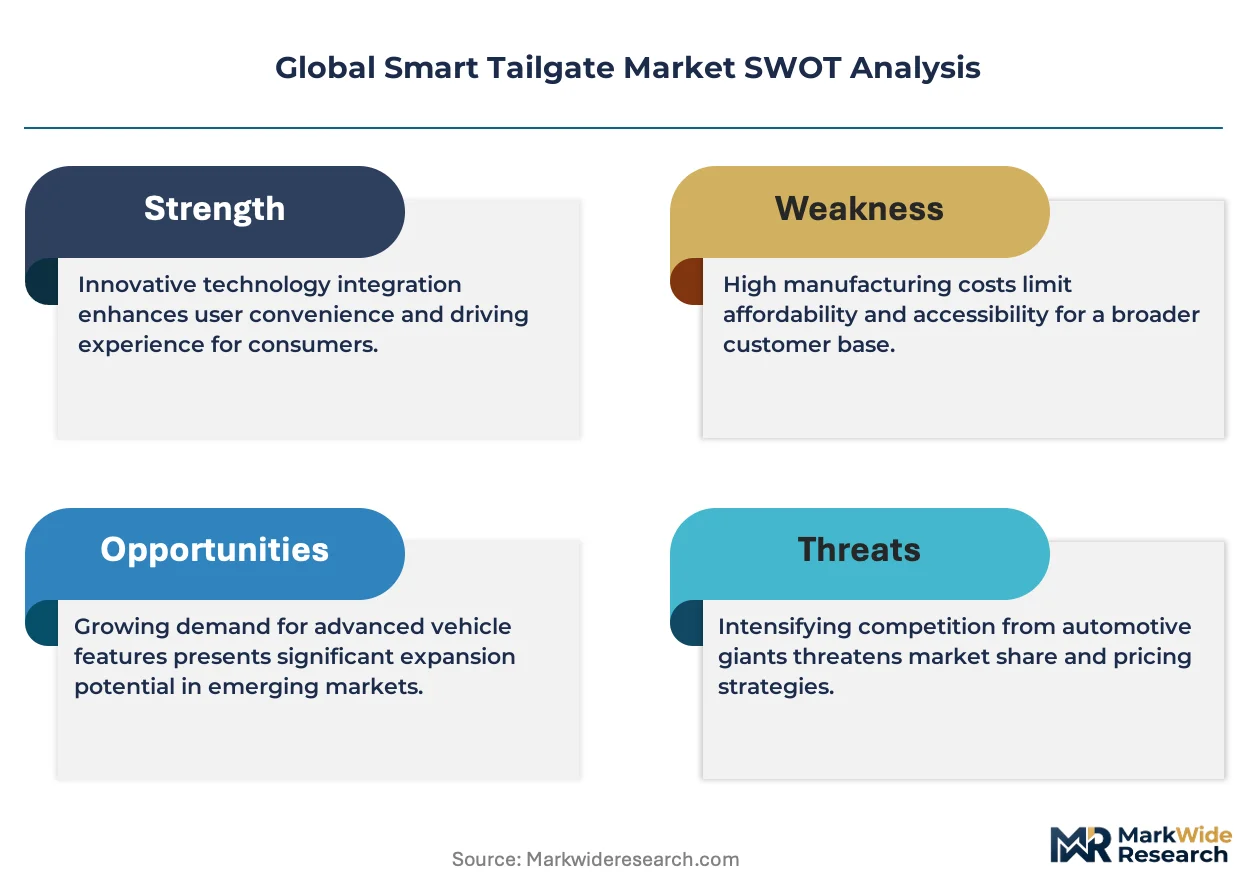
Growth Catalysts
- NHTSA Rear-Visibility Mandate:The US safety regulator now requires rear-obstacle detection systems on light vehicles, forcing OEMs to bundle ultrasonic sensors with electric tailgate assemblies as standard equipment rather than optional accessories.
- Capacitive Foot-Activation:This authentication technology eliminates physical key fob dependency for cargo access, with premium crossovers and fleet operators in China adopting the interface at accelerating rates.
- German Premium Assembly Concentration:Stuttgart and Munich anchor global volume allocation for luxury SUV platforms, where captive stamping and mechatronics integration at factory level locks in multi-year supplier contracts.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium price swings directly impact linear actuator motor costs, squeezing margins on mid-luxury vehicle configurations where pricing power remains constrained.
- EU MDR Pedestrian-Impact Testing:The European Medical Device Regulation's mechanical safety protocols extend to vehicle rear closures, adding 8-12 months to certification timelines for electromechanical subsystems.
- IP67 Control Module Supply Concentration:Sealed electronic enclosures capable of withstanding repeated cargo-area exposure concentrate among three Asian contract manufacturers, creating single-source vulnerability.
Strategic Opportunities
- India Premium SUV Pipeline:Domestic OEMs and joint ventures in Pune and Chennai are localizing electric tailgate assembly for export markets, opening supplier qualification windows for tier-2 mechatronics specialists.
- Wireless Authentication Convergence:Ultra-wideband positioning fused with Bluetooth Low Energy is fragmenting legacy radio-frequency key fob architectures, enabling smartphone-native vehicle access without hardware retrofit.
- US IRA Commercial Fleet Incentives:Tax credits for domestic light truck production are accelerating full-size pickup electrification, bundling smart tailgate actuation into platform-wide electronics architectures.
Industry Challenges
- ISO 26262 Functional-Safety Talent Scarcity:ASIL-D rated electromechanical system validation requires embedded software engineers with automotive safety experience, a skill set concentrated among German and Japanese suppliers.
- Legacy Gateway Integration Complexity:Tailgate control units must synchronize with central vehicle gateways running disparate CAN-FD and Ethernet protocols, extending calibration cycles and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Tailgate Market |
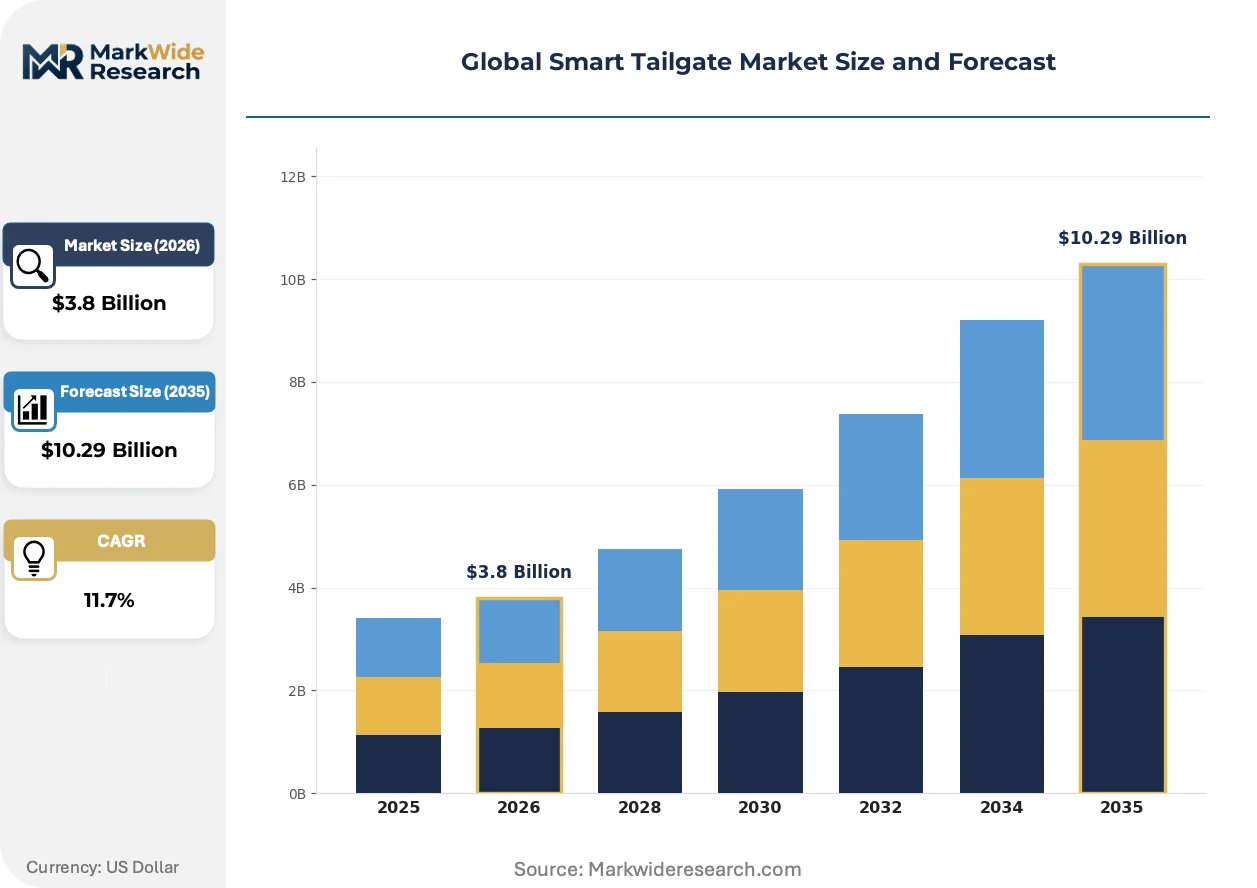
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tailgate, Manual Tailgate, Hybrid Tailgate, Smart Lock Tailgate Technology: Bluetooth, RFID, Wi-Fi, Ultrasonic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Dealerships Installation Type: Factory Installed, Aftermarket Installation, DIY Kits, Upgraded Systems |
| Companies Covered | Magna International, Bosch, Continental, Aptiv, Aisin Seiki, Faurecia, ZF Friedrichshafen, Valeo, Hella, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Tailgate Market Strategic Shifts
Authentication protocols and sensor fusion architectures are displacing standalone mechanical systems, while regulatory pressure on rear-visibility and pedestrian safety is forcing hardware redundancy into designs.
Ultra-wideband spatial positioning is fragmenting proximity detection standards for hands-free cargo access. The technology enables centimeter-accurate occupant ranging without line-of-sight requirements. Luxury pickup and SUV platforms in the United States are adopting the interface fastest, with Ford and GM assembly lines phasing out capacitive kick sensors. This fragmentation is compressing retrofit upgrade viability as factory-integrated modules lock in encrypted authentication keys.
EU MDR mechanical safety protocols are extending testing burdens to vehicle rear closures previously exempt from pedestrian-impact simulation. The regulation forces structural reinforcement and energy-absorption redesign into tailgate assemblies. German OEM supply chains are responding by consolidating stamping and sensor integration under single-source mechatronics contracts, eliminating tier-2 subsystem suppliers from qualification.
Fleet procurement of light commercial vehicles is unbundling after-sales service from hardware acquisition, with leasing operators demanding predictive maintenance telemetry from tailgate actuators. This reconfiguration favors suppliers offering integrated control-unit architectures with embedded diagnostic capability. The shift is most visible in United States full-size pickup segments, where commercial fleet penetration exceeds retail volume in certain model lines.
Global Smart Tailgate Market Segmentation
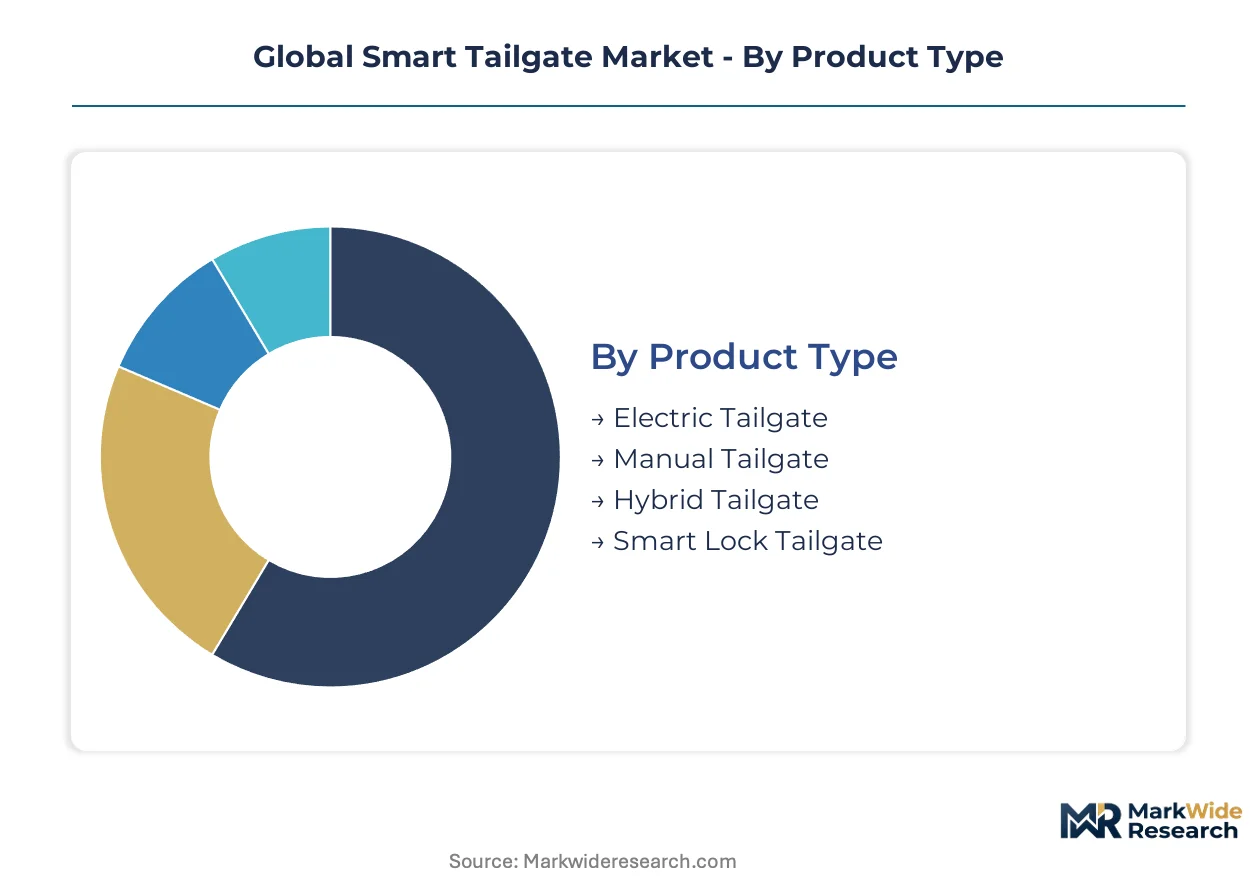
Smart tailgate procurement splits across electromechanical configurations, wireless authentication layers, supply chain tiers, and installation modalities. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier qualification requirements.
Product Type:
NHTSA rear-visibility mandates and EU MDR pedestrian-impact protocols force divergent engineering investments across closure architectures, with factory-integrated systems facing stricter ASIL-D functional-safety ratings than retrofit alternatives.
- Electric Tailgate:Motorized strut assemblies with torque-rich linear actuators and anti-pinch force-feedback circuits dominate mid-luxury crossovers and full-size pickups in the United States and Germany. NHTSA rear-obstacle detection requirements bundle ultrasonic sensors with these systems as standard equipment, compressing optional accessory pricing.
- Manual Tailgate:Conventional mechanical hinges with assisted dampening persist in economy pickups and commercial fleet configurations where cost constraints override convenience premiums. Demand concentrates in emerging markets where OEMs prioritize base-trim volume over feature differentiation.
- Hybrid Tailgate:Dual-mode actuation combining manual override with electric assist targets fleet operators requiring redundancy for field reliability.
- Smart Lock Tailgate:Integrated electronic latches with wireless authentication protocols address theft-sensitive cargo applications in last-mile delivery segments.
Electric tailgate handles the majority of throughput; smart lock tailgate is the fastest mover on share.
Technology:
Authentication protocol selection determines cybersecurity exposure and smartphone-native integration potential, with ultra-wideband positioning fragmenting legacy radio-frequency architectures fastest in premium vehicle segments.
- Bluetooth:Low-energy pairing with smartphone-native vehicle access enables keyless entry without dedicated hardware, with Ford and GM assembly lines phasing out physical fob dependency fastest in United States luxury pickup platforms.
- Ultrasonic:Proximity detection for hands-free foot-activation concentrates in German premium SUVs where capacitive kick sensors face reliability challenges in winter conditions.
- RFID:Passive tag authentication persists in fleet-managed commercial vehicles where driver-specific access logging trumps consumer convenience.
- Wi-Fi:High-bandwidth connectivity supports over-the-air diagnostic telemetry from tailgate actuators, favored by United States leasing operators unbundling after-sales service from hardware acquisition.
Bluetooth handles the majority of authentication volume; ultrasonic is expanding most quickly on protocol share.
End User:
Supply chain position determines warranty exposure and calibration complexity, with captive OEM assembly eliminating aftermarket liability while fragmenting procurement power among factory-integrated tier-1 suppliers.
- OEMs:Factory-level integration of hands-free actuation systems locks in multi-year supplier contracts at Stuttgart and Munich assembly plants, where captive stamping and mechatronics capacity dominates global volume allocation.
- Aftermarket Providers:Retrofit-upgrade tier faces compressed installation windows as factory configurations eliminate calibration risks, concentrating demand in aging vehicle parcs outside warranty coverage.
- Vehicle Assemblers:Contract manufacturing for export markets in Pune and Chennai opens supplier qualification windows for tier-2 mechatronics specialists serving India-based joint ventures.
- Dealerships:Dealer-installed accessory programs target lease-return volume and certified pre-owned segments where original equipment omission creates upgrade opportunity.
OEMs handle the majority of throughput; vehicle assemblers are gaining share fastest.
Installation Type:
Margin stratification follows warranty liability concentration, with factory-installed configurations capturing premium pricing while DIY kits face IP67 control module supply constraints from Asian contract manufacturers.
- Factory Installed:Captive assembly with encrypted authentication keys and centralized gateway synchronization commands dominant margin tier, with German OEM supply chains consolidating stamping and sensor integration under single-source mechatronics contracts.
- Aftermarket Installation:Professional retrofit services face ISO 26262 functional-safety talent scarcity, extending calibration cycles and warranty exposure for electromechanical subsystem validation.
- DIY Kits:Consumer-installable modules with plug-and-play wiring harnesses target price-sensitive pickup owners in United States retail channels.
- Upgraded Systems:Dealer-facilitated hardware refreshes with predictive maintenance telemetry address fleet operator demands for embedded diagnostic capability in full-size pickup segments.
Factory installed handles the majority of throughput; upgraded systems are climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented assembly in Germany and China supplies premium SUV platforms worldwide, while the United States runs a modest trade surplus in electric tailgate subsystems. Import dependency for IP67-rated control modules concentrates among Asian contract manufacturers, creating regional supply vulnerabilities.
Germany
Stuttgart and Munich assembly plants anchor captive stamping and mechatronics integration for luxury SUV platforms. EU MDR pedestrian-impact protocols extend testing burdens to rear closures, forcing structural reinforcement redesigns. Baden-Württemberg suppliers consolidate sensor integration under single-source contracts, eliminating tier-2 subsystem vendors from qualification windows.
United States
NHTSA rear-obstacle detection mandates bundle ultrasonic sensors with electric tailgate assemblies as standard equipment. IRA commercial fleet incentives accelerate full-size pickup electrification, embedding smart actuation into platform-wide electronics. Detroit-area OEMs concentrate procurement power among tier-1 suppliers with embedded diagnostic capability.
China
Premium crossover demand in Shanghai and Beijing drives capacitive foot-activation adoption at accelerating rates. MIIT cybersecurity regulations for vehicle entry systems impose encryption mandates on wireless authentication surfaces. Yangtze River Delta contract manufacturers dominate IP67-rated control module output, creating single-source concentration risk.
India
Domestic OEMs and joint ventures in Pune and Chennai localize electric tailgate assembly for export markets. BIS certification requirements for electromechanical subsystems extend supplier qualification timelines. Tamil Nadu-based vehicle assemblers open tier-2 mechatronics specialist windows for component sourcing.
Japan
ASIL-D functional-safety talent scarcity concentrates among embedded software engineers in automotive safety clusters. METI standards for vehicle gateway integration govern tailgate control unit synchronization protocols. Nagoya-area suppliers maintain legacy CAN-FD calibration expertise for central vehicle gateway compatibility.
Global Smart Tailgate Market Competitive Environment
Listed leaders compete with private specialists across factory-integration and retrofit-upgrade tiers. The market structure concentrates procurement power among tier-1 suppliers with captive stamping capacity, while tier-2 mechatronics specialists face compressed qualification windows. Three archetypes dominate: integrated mechatronics contractors, sensor-technology licensors, and control-unit architects. Competitive moves center on backward integration into sealed electronic enclosures and strategic partnerships for ultra-wideband positioning modules.
Within the integrated mechatronics tier, Magna International and Continental exemplify factory-level suppliers consolidating stamping and sensor integration. Bosch occupies a position representing sensor-technology leadership through ultrasonic fusion and capacitive activation modules. These three anchors illustrate how European and North American listed players dominate OEM supply contracts, while Asian specialists concentrate on contract manufacturing for IP67-rated enclosures.
| Leading Market Players |
|---|
| Magna International |
| Bosch |
| Continental |
| Aptiv |
| Aisin Seiki |
| Faurecia |
| ZF Friedrichshafen |
| Valeo |
| Hella |
| Others |
Value Chain & Pricing Dynamics
ISO 26262 functional-safety certification gates both supplier qualification and price differentiation simultaneously, with ASIL-D rated electromechanical subsystems commanding premium positioning against uncertified alternatives. NHTSA rear-visibility mandates and EU MDR pedestrian-impact protocols compress optional accessory pricing while elevating factory-integrated system margins through warranty liability consolidation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ASIL-D certification grade and captive stamping integration, with German luxury SUV platforms absorbing the highest premiums. Cost compression in mid-luxury configurations is intensifying because neodymium magnet volatility squeezes linear actuator margins. Fleet operators exhibit the greatest price sensitivity, while premium OEM procurement teams prioritize qualification security over unit cost.
Supply Chain Analysis
Inventory lead times for IP67-rated control modules extend disproportionately versus stamped metal components, creating working capital asymmetry across tiers. Manufacturing concentrates in Germany, China, and the United States, with Yangtze River Delta contract manufacturers dominating sealed electronic enclosure output. Raw material dependencies center on neodymium magnets, high-grade aluminum stampings, and automotive-grade microcontroller units. Single-source vulnerability in Asian contract manufacturing creates concentration risk. Distribution runs through captive OEM assembly channels and tier-1 supplier direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as commercial fleet electrification accelerates full-size pickup platform refreshes, embedding smart tailgate actuation into volume production schedules.
For Market Incumbents: Secure ASIL-D functional-safety talent pools through targeted acquisition of German and Japanese embedded software engineering clusters. Deepen backward integration into IP67-rated control module production to eliminate single-source exposure from Yangtze River Delta contract manufacturers. Lock in multi-year mechatronics contracts with Stuttgart and Munich assembly plants before India-based joint ventures mature qualification alternatives. For New Entrants and Emerging Players: Lead with wireless authentication convergence targeting ultra-wideband positioning modules for United States luxury pickup platforms phasing out capacitive kick sensors. Exploit tier-2 supplier qualification windows at Pune and Chennai vehicle assemblers serving export markets. Anchor go-to-market strategy on predictive maintenance telemetry bundles for fleet operators unbundling after-sales service from hardware acquisition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across factory-integrated electric tailgate assembly as OEMs consolidate stamping and sensor integration under single-source contracts. Five-to-ten year viability favors vertically integrated mechatronics specialists with captive IP67 enclosure production. Monitor ultra-wideband authentication adoption rates in Ford and GM assembly lines as the inflection signal for protocol standardization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into IP67 Control Modules | Eliminates single-source dependency on Yangtze River Delta contract manufacturers for sealed electronic enclosures. |
| Ultra-Wideband Positioning Partnership | Captures smartphone-native vehicle access demand as Ford and GM phase out capacitive kick sensors. |
| ASIL-D Certification Investment | Opens qualification pathways for German OEM supply chains consolidating under functional-safety mandates. |
| Predictive Maintenance Telemetry Launch | Addresses United States fleet operator demands for embedded diagnostic capability in full-size pickups. |
| India Assembly Localization | Qualifies tier-2 mechatronics specialists for Pune and Chennai joint venture export production. |
Study Parameters
A spread of perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and dealership operations converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and NHTSA regulatory filings. Bottom-up volume modeling triangulated against top-down OEM platform allocation data.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the analysis window. CAGRs were derived from regression analysis of historical platform penetration rates and forward projection of regulatory mandate phase-in schedules. Forecast inputs incorporated NHTSA rear-visibility compliance timelines and EU MDR pedestrian-impact testing burden estimates.
Underlying assumptions cover continued neodymium price stability and IP67 module supply continuity, with deviation risk concentrated in rare earth magnet volatility and cybersecurity regulation evolution for wireless authentication surfaces. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Global Automotive Carpeting Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Car Canopies Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Automotive Sealants Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Automotive Lighting Molds Market