
 Automotive Exterior Trim Parts Market | 2026-2036
Automotive Exterior Trim Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exterior Trim Parts Market Analysis
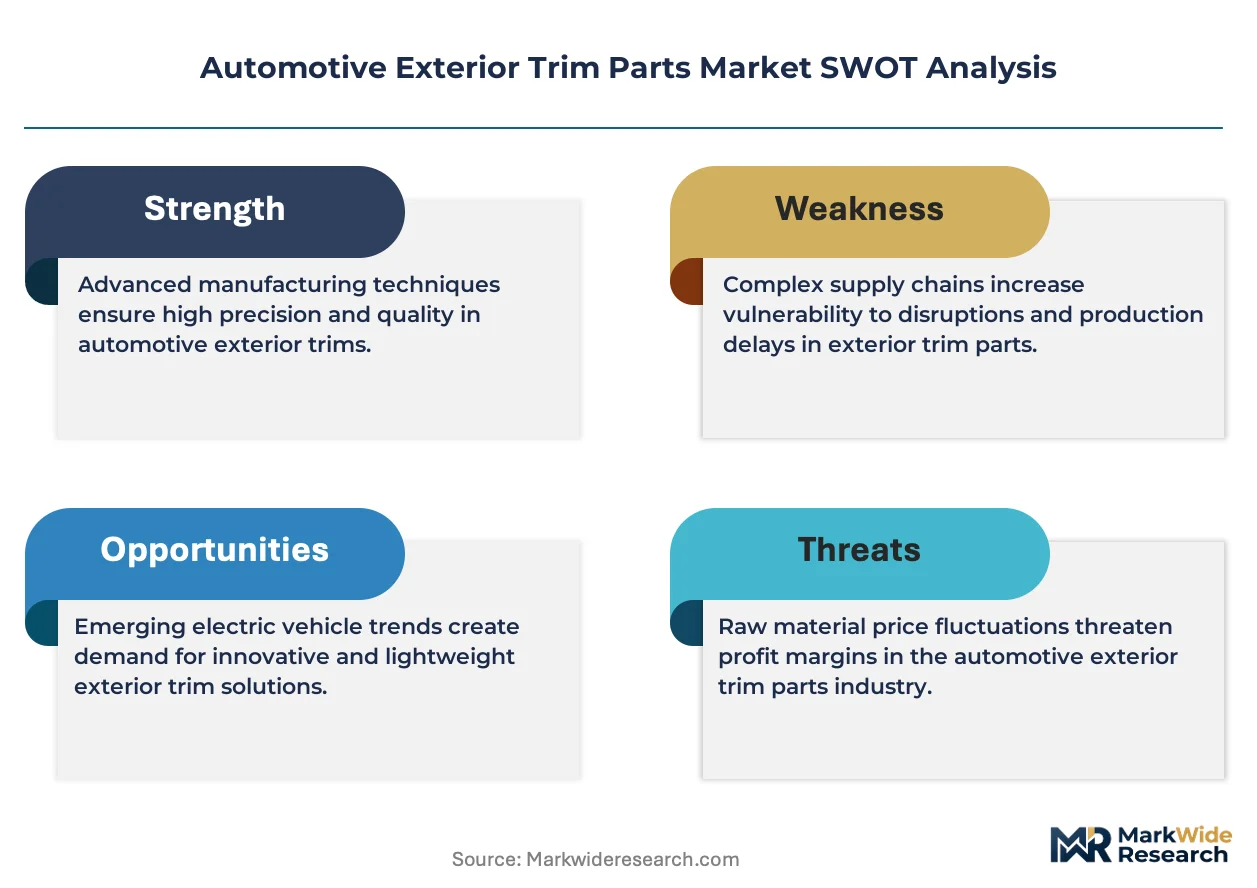
Modular thermoplastic processing is tilting supplier investment toward injection-molded bumper systems and integrated grille modules. Magna International leverages its stamping and assembly scale to anchor North American pickup truck programs. Plastic Omnium competes through fuel-cell-ready exterior panels and hydrogen storage integration. Samvardhana Motherson Group specializes in mirror-to-molding subsystem bundling for European luxury platforms.
Automotive exterior trim parts encompass bumpers, moldings, spoilers, and grilles manufactured through injection molding, thermoforming, or metal stamping to provide aerodynamic performance, pedestrian protection, and brand differentiation. Polypropylene compounds dominate bumper substrates due to impact resistance at sub-zero temperatures and paint adhesion compatibility. Composite materials represent the fastest-growing material segment as carbon-fiber-reinforced spoilers penetrate performance EV lineups, while plastic molding commands the largest volume share across economy and mid-range vehicle classes where cost-per-part thresholds govern sourcing decisions.
The EPA enforces Corporate Average Fuel Economy standards that push OEMs toward lighter exterior materials, while EMA in Europe mandates material traceability under REACH for end-of-life recyclability. China's MIIT imposes GB standards on plastic component flame retardancy and weathering resistance for domestic-market homologation. Stakeholders must monitor how dual carbon goals in Beijing and the EU Green Deal's embodied-carbon reporting reshape material qualification timelines and supplier certification burdens.
Market Dynamics
Electric vehicle platform consolidation is compressing exterior trim development cycles, forcing suppliers to synchronize thermoplastic bumper and composite spoiler programs with 18-month vehicle redesign timelines rather than traditional 36-month schedules.
Growth Catalysts
- EPA Fuel-Economy Mandates:Corporate Average Fuel Economy standards in the United States compel OEMs to specify polypropylene bumper substrates and carbon-fiber-reinforced spoilers that reduce curb weight and extend electric range.
- China's Dual Carbon Goals:Beijing's embodied-carbon reporting requirements accelerate supplier certification for localized exterior trim production near EV assembly clusters in Shanghai and Hefei.
- Modular Thermoplastic Processing:Injection-molded integrated grille modules consolidate multiple components into single assemblies, reducing part count and assembly labor for high-volume EV platforms.
Market Restraints
- Polypropylene Feedstock Volatility:Propylene monomer prices fluctuate with crude oil and naphtha markets, compressing margins for bumper substrate suppliers locked into annual OEM pricing agreements.
- REACH Compliance Burden:ECHA substance-of-very-high-concern listings force reformulation of paint adhesion promoters and UV stabilizers, extending material qualification timelines by 8-14 months.
- Steel-Intensive Pickup Platforms:North American full-size truck programs retain metal-intensive exterior architectures, limiting thermoplastic penetration in the highest-margin vehicle segment.
Strategic Opportunities
- India's PLI Scheme for Auto Components:Production-linked incentives for advanced automotive materials attract exterior trim investment toward Chennai and Pune manufacturing corridors serving domestic EV brands.
- Hydrogen Storage Integration:Fuel-cell vehicle architectures create demand for exterior panels with embedded hydrogen tank protection structures, merging crash safety with aerodynamic surfaces.
- Mirror-to-Molding Subsystem Bundling:European luxury platforms consolidate side mirror housings, camera mounts, and fender extensions into single supplier responsibilities, raising contract values and technical barriers.
Industry Challenges
- Multi-Material Bonding Expertise:Adhesive development for polypropylene-to-carbon-fiber joints requires chemists and process engineers scarce in traditional metal-stamping supplier bases.
- GB Standard Homologation:China's MIIT flame-retardancy and weathering-resistance certifications demand dedicated testing facilities and 6-9 month validation cycles for each new material grade.
- End-of-Life Traceability Systems:REACH Article 33 and EU Green Deal embodied-carbon reporting require supplier IT infrastructure to track resin batches through molding, painting, and vehicle recycling stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exterior Trim Parts Market |
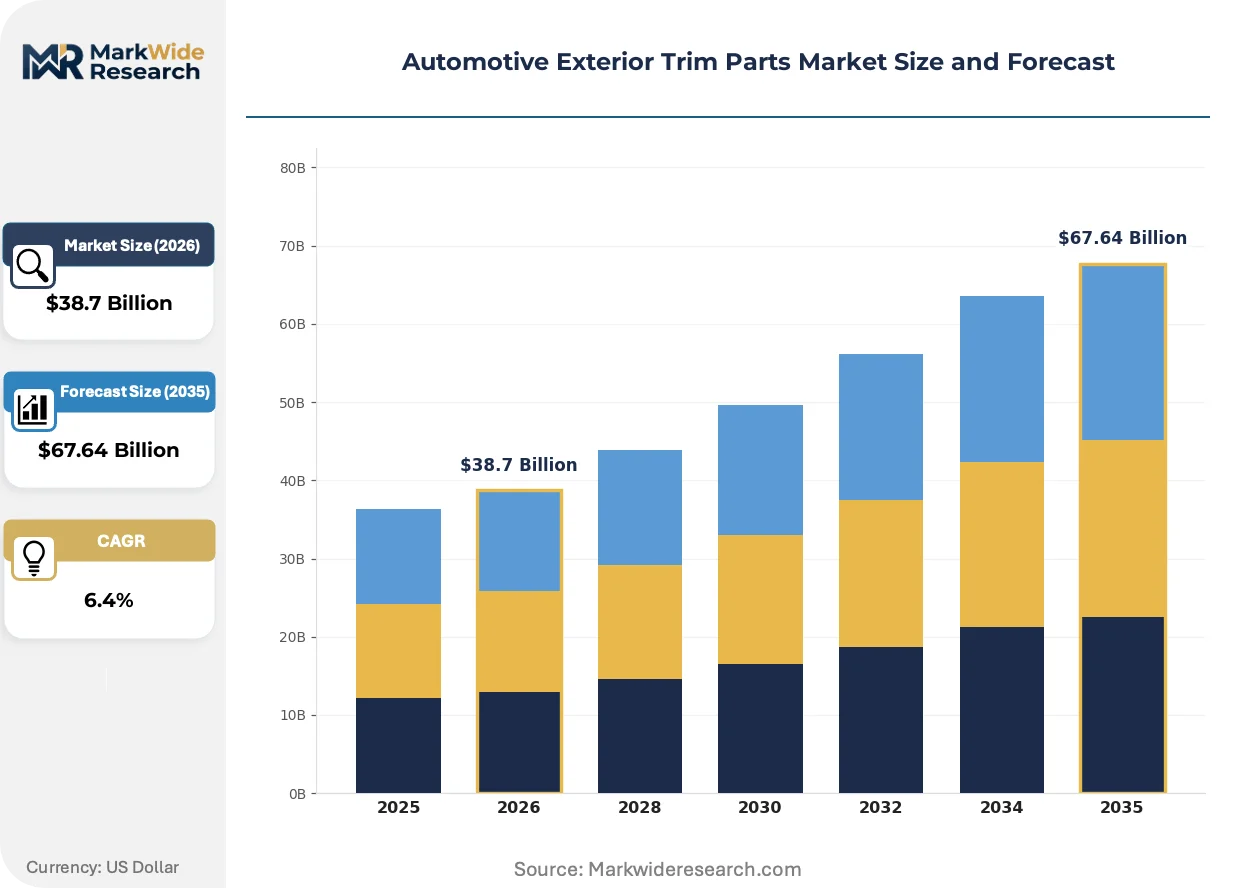
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bumpers, Molding, Spoilers, Grilles Material: Plastic, Metal, Composite, Rubber Application: OEM, Aftermarket, Custom Parts, Replacement Parts End User: Auto Manufacturers, Dealerships, Repair Shops, Retailers |
| Companies Covered | Samvardhana Motherson Group, Aisin Corporation, Magna International, Valeo SA, Toyoda Gosei, Plastic Omnium, Forvia SA, Grupo Antolin, Flex-N-Gate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exterior Trim Parts Market Emerging Trajectories
Digital twin technology and generative design software are compressing exterior trim development timelines while enabling mass customization of aerodynamic surfaces previously constrained by tooling economics.
Generative topology optimization is virtualizing the structural design of bumper beams and spoiler supports. Tier-1 suppliers deploy cloud-based simulation platforms to iterate crash-performance geometries in hours rather than weeks. This capability compresses prototype iterations and enables platform-specific variants without dedicated hard-tooling investments.
REACH SVHC candidate list expansions are tightening material specifications for plasticizers and flame retardants in exterior trim. ECHA notifications now cover phthalate alternatives and halogen-free synergists, forcing compounders to validate replacement chemistries. European premium EV lineups face the strictest compliance timelines, with homologation gates synchronized to quarterly SVHC updates.
Direct-to-OEM digital sampling platforms are displacing traditional physical prototype programs. Suppliers in China and Germany now ship photorealistic renderings and AR-configured models to vehicle studios, cutting international courier cycles and tooling deposits. Procurement teams at domestic EV brands in Hefei and Shenzhen have adopted these channels fastest, compressing supplier selection from 16 weeks to 6 weeks.
Automotive Exterior Trim Parts Market Segmentation
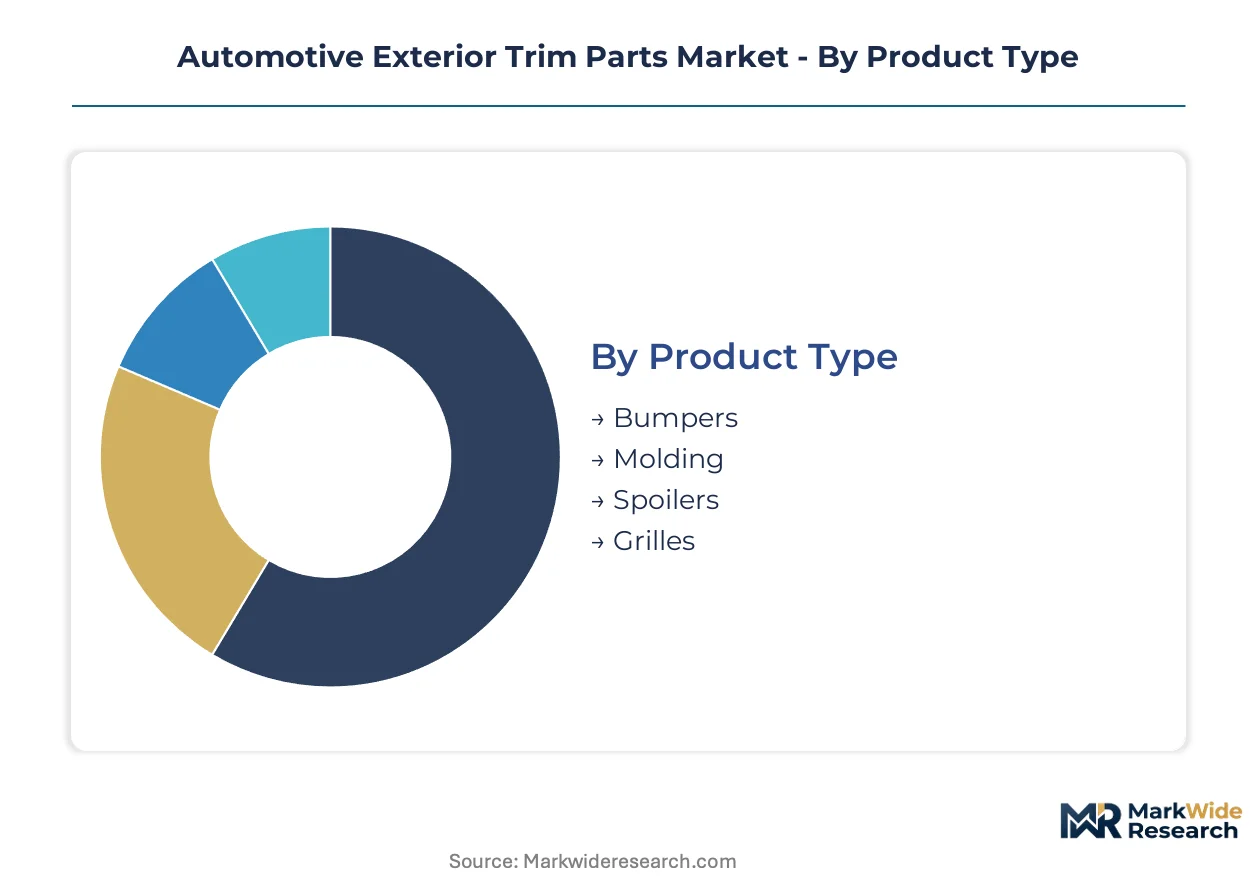
Segmentation in exterior trim parts reveals how material choices and channel structures govern margin profiles. Product type cycles drive tooling amortization schedules, while material selection determines regulatory compliance burdens across EPA, REACH, and GB standard jurisdictions.
Product Type:
Bumper programs turn over on 18-month EV platform cycles, while grille modules refresh slower due to shared stamping investments across model years.
- Bumpers:Thermoplastic injection-molded substrates dominate EV specifications for impact resistance at sub-zero temperatures and paint adhesion compatibility. Polypropylene compounds anchor programs at Shanghai and Hefei assembly clusters where domestic brands compress development timelines.
- Grilles:Integrated modules consolidate sensors, cameras, and active aerodynamic elements into single assemblies. European luxury platforms demand these for pedestrian protection compliance under EMA safety directives, extending contract values.
- Molding:Side body and window surround components protect panel edges while enabling color-matched finishes.
- Spoilers:Carbon-fiber-reinforced variants penetrate performance EV lineups for curb weight reduction.
Bumpers dominate installed base. Spoilers are where expansion concentrates.
Material:
Cost tiers separate commodity feedstocks from engineered compounds with traceability documentation.
- Plastic:Polypropylene commands volume leadership across economy and mid-range classes where cost-per-part thresholds govern sourcing. REACH SVHC listings force reformulation of plasticizers and UV stabilizers, extending qualification timelines.
- Composite:Carbon-fiber-reinforced polymers represent the steepest expansion trajectory as fuel-cell-ready panels embed hydrogen tank protection structures. OEMs specify these for EPA fuel-economy compliance in electric range extension.
- Metal:Steel-intensive architectures persist in North American full-size pickup programs, limiting thermoplastic penetration in the highest-margin segment.
- Rubber:Sealing and impact-absorption components require halogen-free flame retardants under ECHA notifications.
Plastic anchors volume throughput. Composite is climbing the fastest.
Application:
Channel structures split between captive OEM supply with long-term agreements and fragmented aftermarket procurement.
- OEM:Direct supply to vehicle assembly plants requires synchronized 18-month development cycles and MIIT GB standard homologation for China market entry.
- Aftermarket:Replacement demand concentrates at dealership networks and independent repair channels.
- Custom Parts:Performance and aesthetic modifications serve enthusiast segments with shorter run quantities.
- Replacement Parts:Insurance-driven collision repair generates demand for certified paint-match compatibility.
OEM locks in capacity utilization. Aftermarket is gaining share fastest.
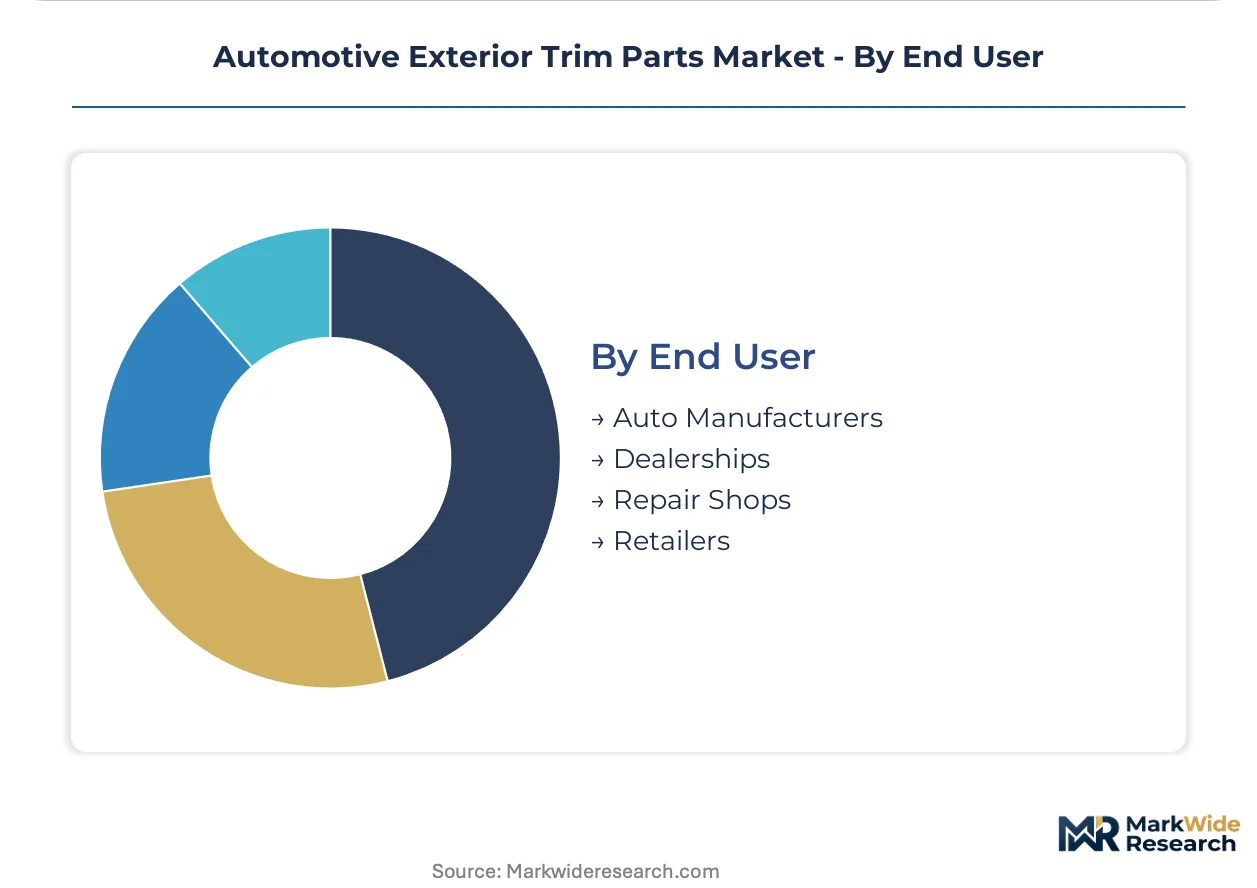
End User:
Procurement authority varies from centralized OEM commodity teams to dispersed retail channels.
- Auto Manufacturers:Platform engineering teams specify materials against EPA, REACH, and dual carbon goal requirements, consolidating supplier responsibilities for mirror-to-molding subsystems.
- Dealerships:Authorized service networks source OEM-certified replacement components with warranty compliance.
- Repair Shops:Independent collision centers prioritize part availability and paint adhesion compatibility.
- Retailers:Accessory channels serve consumer-direct customization demand.
Auto Manufacturers concentrate specification authority. Repair Shops are expanding procurement autonomy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive exterior trim procurement concentrates around three buyer archetypes: domestic EV brands in China seeking localized supply, European luxury OEMs demanding subsystem bundling, and North American truck manufacturers retaining steel-intensive architectures. Each archetype drives distinct supplier certification requirements and regional investment patterns.
China
Domestic EV brands NIO, XPeng, and BYD compress exterior trim development cycles to 18 months, forcing suppliers to co-locate near Shanghai and Hefei assembly clusters. MIIT enforces GB standards on plastic component flame retardancy and weathering resistance, extending homologation timelines by 6-9 months per material grade. Supplier parks in Hefei now host captive injection-molding operations for polypropylene bumper substrates.
Germany
Luxury platform engineering teams at BMW, Mercedes-Benz, and Audi consolidate mirror-to-molding subsystem responsibilities, raising contract values and technical barriers for exterior trim suppliers. ECHA REACH SVHC listings force reformulation of paint adhesion promoters and UV stabilizers, extending material qualification timelines by 8-14 months. Industrial concentration in Baden-Württemberg and Bavaria anchors composite spoiler development for performance EV lineups.
United States
Full-size pickup programs at Ford, GM, and Stellantis retain metal-intensive exterior architectures, limiting thermoplastic penetration in the highest-margin vehicle segment. EPA Corporate Average Fuel Economy standards nonetheless compel light-weighting investments in polypropylene bumper substrates for electric truck variants. Supplier engineering centers in Michigan and Ohio coordinate stamping and assembly scale for North American truck platforms.
India
Domestic EV brands Tata Motors and Mahindra & Mahindra source exterior trim through Chennai and Pune manufacturing corridors. PLI scheme production-linked incentives for advanced automotive materials attract investment in thermoplastic processing capabilities. BIS certification requirements for automotive plastics create qualification bottlenecks for imported compound grades.
Japan
Toyota, Honda, and Nissan integrate exterior trim development with hybrid and fuel-cell platform architectures. METI guidance on hydrogen storage integration creates demand for exterior panels embedding tank protection structures. Industrial clusters in Aichi Prefecture and Kanto region concentrate composite spoiler manufacturing for domestic and export markets.
Automotive Exterior Trim Parts Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Full-service Tier-1 suppliers anchor OEM direct supply through long-term platform agreements, while mid-cap specialists occupy niche positions in composite aerodynamics and hydrogen-ready exterior systems. The market structure rewards scale in injection-molded bumper programs and subsystem bundling expertise. Dominant competitive moves include strategic partnerships for fuel-cell integration and geographic expansion into captive supplier parks near EV assembly clusters.
Within the full-service Tier-1 tier, Magna International, Plastic Omnium, and Samvardhana Motherson Group represent archetypal positioning strategies. Magna International exemplifies North American scale advantages in stamping and assembly integration. Plastic Omnium occupies a position at the intersection of exterior panels and hydrogen storage architecture. Samvardhana Motherson Group anchors European luxury platform relationships through mirror-to-molding subsystem bundling capabilities.
| Leading Market Players |
|---|
| Samvardhana Motherson Group |
| Aisin Corporation |
| Magna International |
| Valeo SA |
| Toyoda Gosei |
| Plastic Omnium |
| Forvia SA |
| Grupo Antolin |
| Flex-N-Gate |
| Others |
Supply Flow & Price Mechanics
Hefei's captive supplier parks concentrate polypropylene bumper substrate capacity within 50 kilometers of NIO and BYD assembly plants, translating geographic proximity into pricing leverage for domestic EV brands sourcing localized exterior trim.
Pricing Analysis
Cost-plus contracts with propylene monomer indexation dominate annual OEM pricing agreements, locking bumper substrate suppliers into margin compression when crude oil and naphtha markets fluctuate. Price differentiation hinges on REACH SVHC compliance grade and MIIT GB standard certification tier, with European premium EV lineups commanding qualification premiums. Pricing pressure intensifies as domestic Chinese brands consolidate procurement volumes through platform engineering teams. Aftermarket collision repair channels exhibit highest price sensitivity due to insurance reimbursement ceilings, while OEM direct supply maintains lowest sensitivity through long-term platform commitments.
Supply Chain Analysis
Magna International, Plastic Omnium, and Samvardhana Motherson Group anchor contract manufacturing capacity across North American truck platforms, European luxury subsystems, and Chinese EV clusters respectively. Geographic supply concentration centers on Germany, China, and Mexico for injection-molded bumper systems and composite spoiler manufacturing. Raw material dependencies rest on polypropylene compounds from petrochemical feedstocks, carbon-fiber precursors from acrylonitrile supply, and paint adhesion promoters subject to ECHA reformulation mandates. Single-source vulnerability persists in specialized hydrogen storage integration panels for fuel-cell architectures. Distribution runs through captive OEM supply parks near Shanghai, Hefei, and Stuttgart assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive exterior trim parts constitute a high-growth disruption as EPA fuel-economy mandates and China's dual carbon goals force material transitions from steel-intensive architectures to thermoplastic and composite substrates within compressed 18-month development cycles.
For Market Incumbents: Entrench platform engineering relationships by embedding generative design capabilities and digital twin simulation into OEM co-development programs. Backward integration into polypropylene compounding mitigates feedstock volatility exposure. Prioritize REACH SVHC pre-certification investments to compress qualification timelines for European premium EV lineups facing quarterly ECHA update cycles.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme corridors serving Tata Motors and Mahindra & Mahindra EV platforms, where BIS certification bottlenecks create qualification barriers for imported compound grades. Target aftermarket collision repair channels with certified paint-match compatibility as insurance-driven procurement expands fastest. Deploy direct-to-OEM digital sampling platforms to compress supplier selection timelines from 16 weeks to 6 weeks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors subsystem bundling specialists with mirror-to-molding integration capabilities and fuel-cell-ready exterior panel expertise. Long-term viability over the projection horizon hinges on multi-material bonding chemistry competencies scarce in traditional metal-stamping supplier bases. Acquisition screening should prioritize compounders with validated halogen-free flame retardant formulations. Monitor quarterly ECHA SVHC candidate list expansions as inflection indicators for material qualification timeline extensions and reformulation cost shocks.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidates bumper and grille modules across 18-month EV redesign cycles for NIO and XPeng. |
| Battery Supply Agreement | Secures localized polypropylene substrate capacity for electric truck variants at Ford and GM. |
| Software-Defined Vehicle Investment | Integrates active aerodynamic grille elements with sensor fusion architectures for pedestrian protection. |
| Geographic Manufacturing Footprint | Captures PLI scheme incentives in Chennai and Pune corridors for Tata Motors EV sourcing. |
| Charging Infrastructure Partnership | Aligns exterior trim lightweighting with EPA range extension targets for electric pickup programs. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, MIIT GB standard filings, and ECHA REACH SVHC notifications. Bottom-up segmentation modeling triangulated with top-down market sizing across material grade, vehicle class, propulsion architecture, and regional production cluster dimensions.
Demand-supply-balance framing anchored the forecast framework, modeling content-per-vehicle trajectories for thermoplastic bumpers and composite spoilers against EV platform rollout schedules across the analysis window. Segmentation dimensions included product type, material compound, application channel, and end-user procurement authority. CAGRs derived from regression analysis of historical platform refresh cycles and OEM lightweighting investment disclosures, with propylene monomer price elasticity and REACH compliance cost pass-through as industry-specific forecast inputs.
Stress conditions across propylene feedstock volatility, ECHA SVHC listing frequency, and MIIT homologation timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EV platform consolidation rates and dual carbon goal enforcement intensity. Quarterly review of ECHA candidate list updates, MIIT certification queue lengths, and domestic Chinese EV brand procurement consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Paint Protection Film Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Cups and Glass Holder Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Glazing for Automotive Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Automotive Heat Shield Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market