
 Automotive Door Sills Market | 2026-2036
Automotive Door Sills Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Door Sills Market Outlook
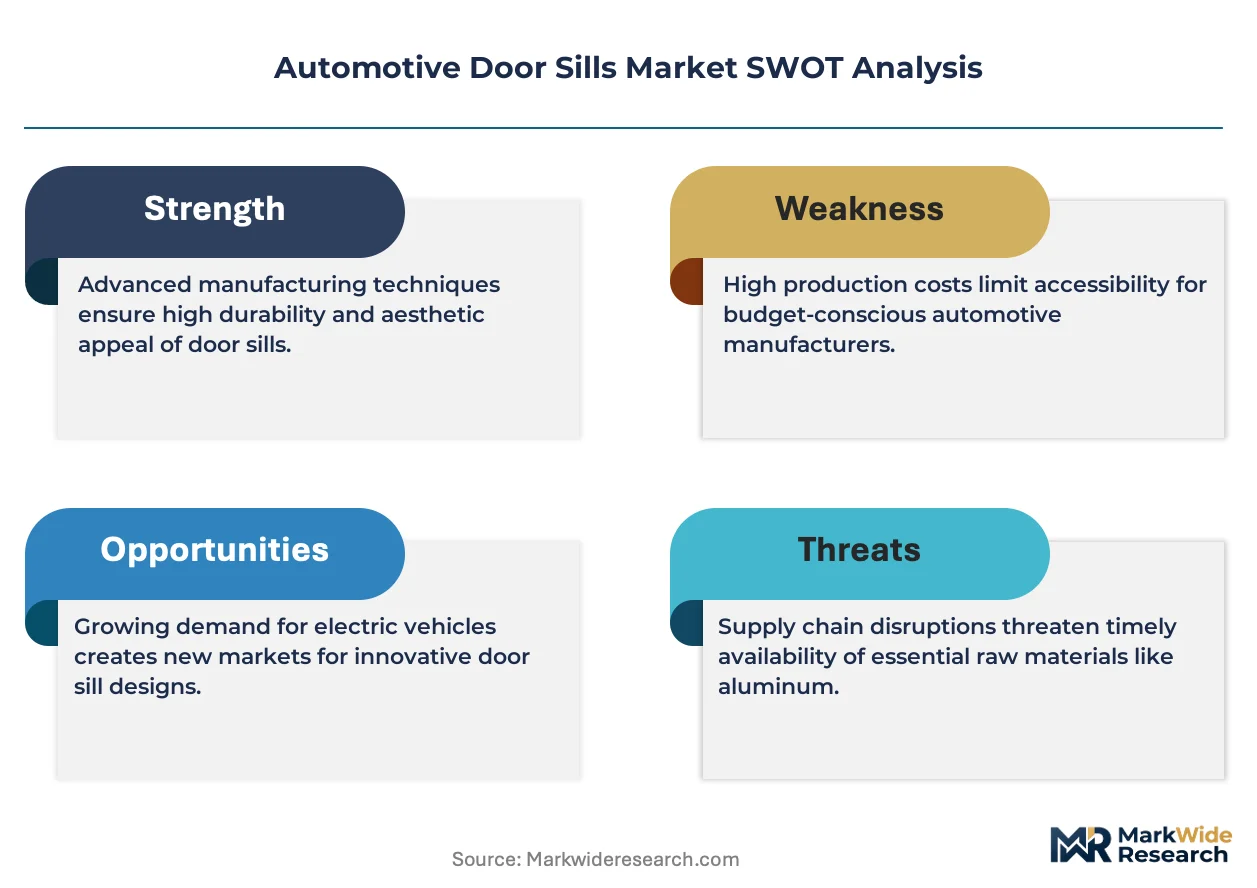
Electric vehicle OEM procurement of lightweight sill assemblies is expanding as battery-electric platforms prioritize mass reduction at the rocker panel zone. SSAB sustains technology leadership in high-strength steel formulations for impact-resistant sills. Gestamp dominates large-scale stamping operations across European and North American OEM supply chains. Bosch leverages its sensor integration expertise to develop smart sill modules with embedded obstacle detection.
Automotive door sills are structural threshold components installed at the vehicle entry point, typically formed from stamped aluminum, high-strength steel, or fiber-reinforced polymer composites with specified yield strengths exceeding 300 MPa to manage side-impact loads and occupant compartment integrity. Their primary industrial purpose spans structural reinforcement, aerodynamic sealing, and cosmetic finishing at the cabin ingress point. Metal sills anchored by stainless steel and aluminum variants command the largest volume share due to OEM preference for proven crash performance, while composite formulations represent the fastest-expanding segment as thermoplastic manufacturers achieve cost parity at scale. Aftermarket installation channels occupy a distinct margin pool driven by collision repair and customization demand, though OEM fitment retains pricing power through captive supply agreements.
The EU Green Deal and REACH compliance frameworks mandate recyclability thresholds and restricted substance controls that reshape material selection across European supplier bases. NHTSA side-impact standards and FMVSS 214 protocols in the United States enforce minimum intrusion resistance that sustains demand for high-strength metal architectures. Stakeholders must monitor evolving platform electrification strategies that trade conventional sill load paths against battery pack structural integration requirements.
Market Dynamics
Platform electrification is compressing traditional rocker panel load paths as battery pack housings absorb structural duties, forcing suppliers to redesign sill geometries for crash energy management without legacy floorpan anchoring points.
Growth Catalysts
- EU Green Deal material mandates:Recyclability thresholds above 85% are redirecting procurement toward closed-loop aluminum suppliers and thermoplastic compounders with validated regrind pathways.
- Battery-electric platform proliferation:EV architectures prioritize mass reduction at the threshold zone, expanding specification windows for carbon fiber-reinforced polymer hybrid sills in premium segments.
- NHTSA side-impact protocol enforcement:FMVSS 214 intrusion resistance requirements sustain OEM demand for high-strength steel stampings with yield strengths exceeding 340 MPa in North American supply chains.
Market Restraints
- Aluminum ingot price volatility:LME spot fluctuations above 15% annually compress fabrication margins for tier-2 stampers serving mid-volume OEM programs.
- High-strength steel tooling amortization:Press hardening die sets require 18-24 month payback cycles, deterring supplier investment in niche EV platform volumes below 50,000 units annually.
- REACH substance restrictions:ECHA candidate list expansions for chromium VI in surface coatings are disqualifying legacy electroplating lines from European OEM qualification.
Strategic Opportunities
- Smart sill module integration:Convergence of capacitive sensing and LED illumination creates specification openings for tier-1 electronics suppliers to displace pure metal formers.
- Aftermarket collision repair channels:Certified aluminum repair networks in Germany and the United States represent underpenetrated margin pools distinct from captive OEM supply.
- Indian PLI scheme localization:Component-level incentives for advanced automotive materials are attracting joint venture stamping capacity for export-oriented premium OEM programs.
Industry Challenges
- Multi-material joining certification:OEM weld-bond qualification protocols for steel-aluminum hybrid sills extend validation timelines by 8-14 months versus single-metal architectures.
- Thermoplastic crash simulation fidelity:Anisotropic fiber orientation modeling requires specialized CAE talent scarce among traditional metal-stamping engineering pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Door Sills Market |
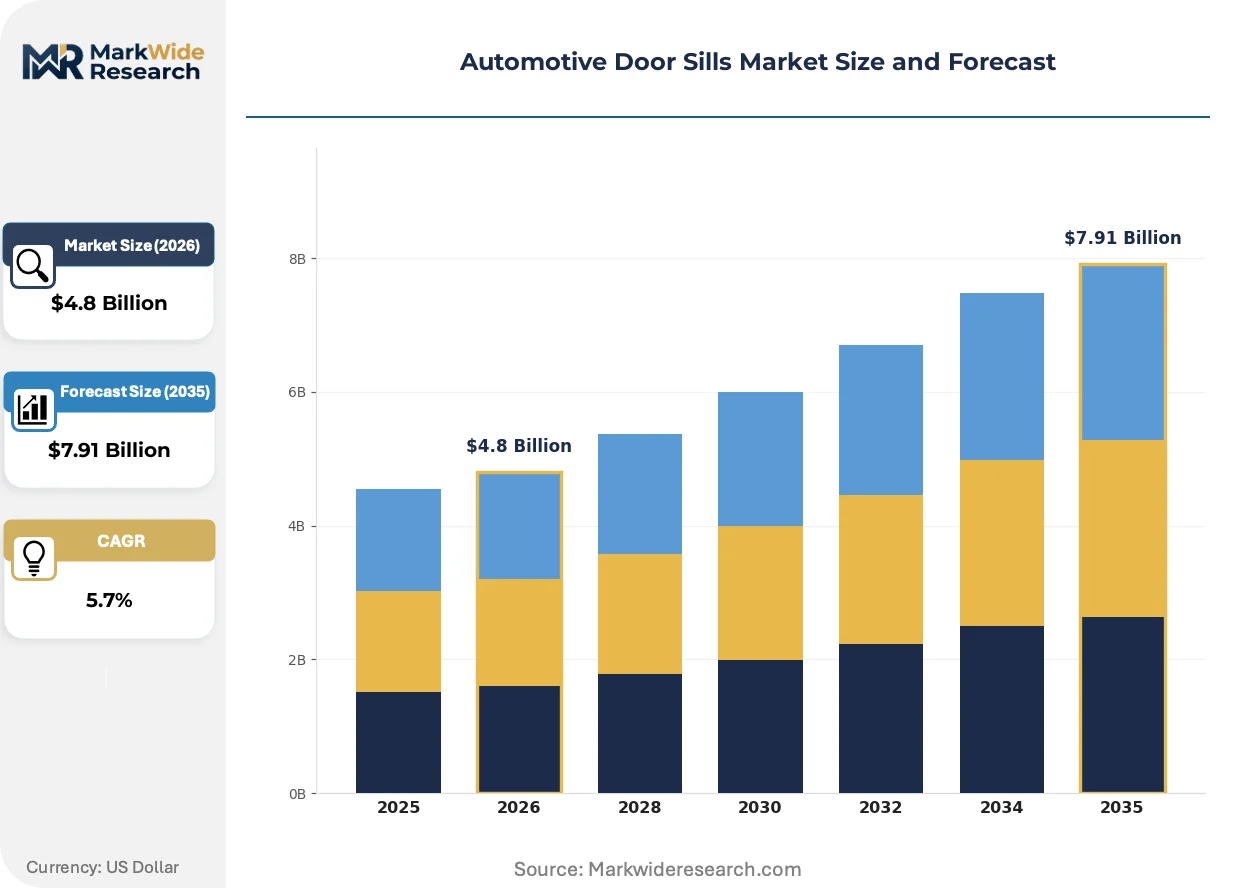
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Composite, Rubber Installation Type: OEM, Aftermarket, Custom Fit, Universal Vehicle Type: SUV, Sedan, Truck, Coupe Material: Aluminum, Stainless Steel, Vinyl, Others |
| Companies Covered | SSAB, Gronbach GmbH, Bosch, Innotec, Normic Industries, Gestamp, Hoshion Aluminium, Hangzhou Green Offroad Auto Parts, Mahle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Door Sills Market Strategic Shifts
Active material substitution and embedded electronics are bifurcating the supplier base into commodity metal stampers and integrated module specialists, with qualification protocols increasingly favoring the latter.
Hot-stamped boron steel is consolidating as the dominant high-strength solution for side-impact sills in mass-market electric platforms. European and North American OEMs specify these grades for 60% of new battery-electric vehicle programs launching through 2027. The technology is consolidating supplier relationships around stampers with in-house press hardening and laser trimming capability, marginalizing conventional cold-stamping operations.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating legacy corrosion pretreatments from European automotive coating lines. Suppliers must qualify zirconium-based conversion coatings or plasma electrolytic oxidation alternatives by Q4 2026 to maintain OEM qualification. German premium manufacturers are most exposed, with sill assemblies representing high-surface-area components subject to accelerated substance scrutiny.
Fleet procurement centralization among mobility-as-a-service operators is compressing replacement cycles and unbundling after-sales service from initial equipment supply. Leasing aggregators in the Netherlands and California now specify 10-year corrosion warranties and modular fast-replace sill designs. This behavior is visible most acutely in ride-hail vehicle specifications, where threshold damage frequency exceeds private-vehicle averages by 3-4x.
Automotive Door Sills Market Segmentation
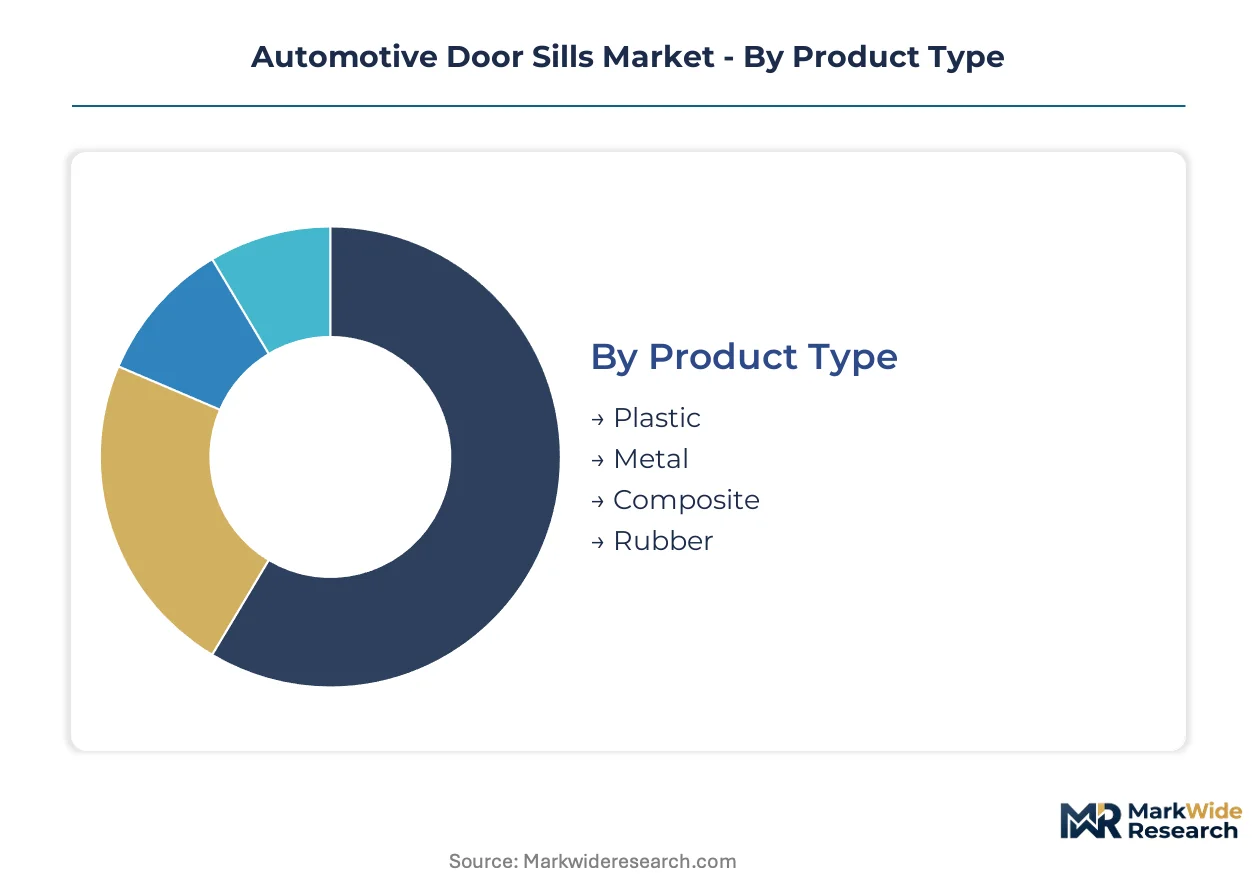
Door sill procurement splits across material performance tiers and channel structures, with OEM captive supply dominating volume while aftermarket customization captures margin. Segment boundaries are blurring as smart module integration and multi-material architectures reshape supplier qualifications.
Product Type:
Supply concentration clusters around metal-forming specialists with press-hardening capability, while polymer compounders fight for specification in emerging EV platforms.
- Metal:Stamped aluminum and high-strength steel variants exceed 300 MPa yield strength for side-impact compliance. German premium OEMs source hot-stamped boron steel sills from specialized European stampers with in-house laser trimming. Metal sills absorb the bulk of installed capacity across mass-market and luxury vehicle programs.
- Composite:Fiber-reinforced thermoplastic hybrids achieve weight reduction targets for battery-electric architectures. Carbon fiber-reinforced polymer formulations are expanding most quickly in premium EV segments where mass reduction at the rocker panel zone justifies material cost premiums.
- Plastic:Injection-molded ABS and polypropylene variants serve economy vehicle tiers and aftermarket cosmetic overlays.
- Rubber:Elastomeric sealing profiles integrate with primary sill structures for aerodynamic and acoustic management.
Metal absorbs the bulk of installed capacity; composite is expanding most quickly.
Installation Type:
Channel economics diverge sharply between captive OEM supply with long-term contracting and fragmented aftermarket distribution through collision repair networks.
- OEM:Factory-fit sill assemblies are locked into platform-specific supply agreements with qualification protocols spanning 18-24 months. European and North American automakers mandate REACH-compliant surface treatments and FMVSS 214 crash validation. OEM channels command pricing power through volume commitments and design-in exclusivity.
- Aftermarket:Collision repair and customization demand operates through certified aluminum repair networks in Germany and the United States. Aftermarket channels represent underpenetrated margin pools distinct from captive supply, with ride-hail fleet operators driving modular fast-replace specifications.
- Custom Fit:Vehicle-specific designs target enthusiast segments with premium finishing and illuminated branding elements.
- Universal:Trim-to-fit solutions serve budget repair segments with standardized mounting systems.
OEM channels lock in the majority of production volume; aftermarket is climbing the fastest as fleet procurement centralization accelerates replacement cycles.
Vehicle Type:
Platform architecture dictates sill load path design, with battery-electric SUVs and sedans forcing structural redesign as battery housings absorb traditional rocker panel duties.
- SUV:Higher ground clearance and step-in height requirements drive reinforced sill geometries with enhanced stone-chip protection. North American full-size SUV programs specify thick-gauge aluminum stampings for threshold durability.
- Sedan:Low-profile sill designs prioritize aerodynamic sealing and cabin ingress ergonomics. European premium sedans integrate capacitive sensing and LED illumination for smart entry systems.
- Truck:Commercial and heavy-duty applications demand maximum impact resistance with utility-focused step surfaces.
- Coupe:Low-volume sports car platforms accommodate exotic material specifications including carbon fiber structural sills.
SUV platforms consume the largest share of high-strength steel tonnage; sedan applications are gaining share fastest through EV platform proliferation.
Material:
Raw material sourcing and conversion coating qualifications are reshaping supplier bases as REACH substance restrictions eliminate legacy electroplating lines.
- Aluminum:Closed-loop recycled aluminum suppliers are securing European OEM qualification under EU Green Deal recyclability mandates. LME spot price volatility above 15% annually compresses tier-2 stamper margins serving mid-volume programs.
- Stainless Steel:Austenitic and ferritic grades provide corrosion resistance for coastal and winter-road environments without supplemental coatings.
- Vinyl:PVC and TPO overlay films serve cosmetic protection and aftermarket customization with lower structural load requirements.
- Others:Magnesium alloys and natural fiber composites occupy niche applications in motorsport and concept vehicle development.
Aluminum commands the dominant specification share; stainless steel is expanding most quickly in corrosion-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive door sill production clusters around specialized stamping corridors in Germany, the United States, China, Japan, and India, each shaped by distinct regulatory frameworks and OEM procurement strategies.
Germany
Premium EV platforms from BMW and Mercedes-Benz drive specification for hot-stamped boron steel sills with integrated LED illumination. The EU Green Deal mandates 85% recyclability thresholds that redirect procurement toward closed-loop aluminum suppliers in the Ruhr industrial belt. Stuttgart and Munich anchor high-strength stamping operations serving luxury OEM programs.
United States
Full-size SUV and truck platforms from Detroit automakers sustain demand for thick-gauge aluminum threshold assemblies. NHTSA FMVSS 214 side-impact protocols enforce intrusion resistance standards that favor high-strength steel architectures in North American supply chains. Michigan and Ohio host concentrated stamping capacity for domestic OEM captive supply agreements.
China
Battery-electric vehicle proliferation from BYD and NIO compresses traditional rocker panel load paths as battery housings absorb structural duties. MIIT dual carbon goals accelerate thermoplastic composite adoption for mass reduction at the threshold zone. Yangtze River Delta stamping clusters around Shanghai specialize in aluminum sill assemblies for export-oriented EV platforms.
Japan
Keiretsu supply relationships lock tier-1 stampers into long-term platform-specific contracts with Toyota and Honda. METI carbon neutrality targets push material substitution toward fiber-reinforced polymer hybrids in premium EV segments. Nagoya and Tokyo metropolitan areas concentrate precision stamping operations with integrated surface treatment capabilities.
India
PLI scheme localization incentives attract joint venture stamping capacity for export-oriented premium OEM programs serving European markets. BIS automotive material standards align with REACH substance restrictions to qualify suppliers for German OEM procurement. Maharashtra and Gujarat host emerging aluminum stamping corridors targeting EV platform volumes.
Automotive Door Sills Market Competitive Environment
Top-tier vendors anchor OEM captive supply with press-hardening and laser trimming capabilities, while mid-tier stampers compete on price for aftermarket collision repair channels. The supplier base splits between consolidated metal-forming specialists and fragmented polymer compounders fighting for EV platform specification. Three archetypes dominate: integrated module specialists with sensor capabilities, high-volume stampers with in-house heat treatment, and regional fabricators serving certified repair networks. Competitive moves center on multi-material joining certification and backward integration into aluminum recycling.
Within the integrated module tier, Bosch exemplifies the convergence of electronics and structural components, while Gestamp occupies a position as a scale-driven stamper with European and North American OEM relationships. SSAB represents the materials-science archetype, supplying high-strength steel formulations that downstream stampers convert into impact-resistant sill architectures.
| Leading Market Players |
|---|
| SSAB |
| Gronbach GmbH |
| Bosch |
| Innotec |
| Normic Industries |
| Gestamp |
| Hoshion Aluminium |
| Hangzhou Green Offroad Auto Parts |
| Mahle |
| Others |
Value Chain & Pricing Dynamics
Backward integration into closed-loop aluminum recycling anchors supply positioning and pricing power for European stampers serving German premium OEMs under EU Green Deal mandates. Captive heat-treatment capacity and in-house laser trimming insulate tier-1 suppliers from spot-market volatility while locking in multi-year platform contracts.
Pricing Analysis
Short lead-time premiums command pricing power for hot-stamped boron steel stampers with press-hardening lines qualified by BMW and Mercedes-Benz. Three-tier pricing structure across premium smart modules, standard high-strength steel stampings, and economy aluminum variants tracks certification grade and crash-test validation burden. Cost compression in mid-volume aluminum stampings intensifies because LME spot volatility above 15% annually squeezes tier-2 fabricator margins. Fleet procurement aggregators exhibit highest price sensitivity, while captive OEM supply agreements demonstrate lowest sensitivity due to design-in exclusivity and long-term volume commitments.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Detroit automakers and European luxury manufacturers, with tier-1 stampers maintaining dedicated production lines for platform-specific sill geometries. Supply concentrates in Germany, the United States, and China, with raw material flows drawing from primary aluminum smelters, boron steel mills, and carbon fiber prepreg suppliers. Single-source vulnerability runs through specialized press-hardening die sets requiring 18-24 month qualification cycles. Distribution runs through captive OEM supply agreements for factory-fit volume, with certified collision repair networks handling aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Door Sills Market functions as a cost-of-compliance story where REACH substance restrictions and EU Green Deal recyclability mandates erect barrier-to-entry moats for qualified suppliers. ECHA candidate list expansions disqualify legacy electroplating operations, consolidating procurement relationships around certified surface-treatment specialists.
For Market Incumbents: Hedge aluminum price exposure through backward integration into closed-loop recycling partnerships in the Ruhr industrial belt. Secure multi-material joining certification ahead of steel-aluminum hybrid sill proliferation, as OEM weld-bond qualification protocols extend validation timelines and freeze out unqualified competitors. Defend against sensor-integrated module specialists by acquiring capacitive sensing capabilities or partnering with tier-1 electronics suppliers. For New Entrants and Emerging Players: Digital aftermarket channels offer the most penetrable entry vector, with certified aluminum repair networks in Germany and the United States representing underpenetrated margin pools distinct from captive OEM supply. Target ride-hail fleet operators specifying modular fast-replace sill designs and extended corrosion warranties. Pursue white-label manufacturing agreements with established stampers to bypass 18-24 month OEM qualification cycles while building proprietary heat-treatment capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by tier-1 automotive suppliers seeking press-hardening and laser trimming capabilities. Long-term viability favors stampers with in-house heat treatment, REACH-compliant surface treatment, and relationships with battery-electric platform engineers. Monitor MIIT dual carbon targets in China as an inflection indicator for thermoplastic composite adoption rates that would displace metal-intensive architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Joining Certification | OEM weld-bond qualification for steel-aluminum hybrid sills locks in 18-24 month supplier relationships. |
| Backward Integration into Aluminum Recycling | Closed-loop suppliers in Germany secure EU Green Deal compliance and insulate margins from LME volatility. |
| Smart Module Integration | Capacitive sensing and LED illumination capabilities displace pure metal formers in premium EV specifications. |
| Aftermarket Collision Repair Certification | Certified aluminum repair networks in Germany and the United States capture fleet replacement cycle acceleration. |
| Indian PLI Scheme Localization | Joint venture stamping capacity in Maharashtra targets export-oriented premium OEM programs serving European markets. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and collision repair network operators. ECHA REACH substance restriction updates, NHTSA FMVSS 214 protocol documentation, and EU Green Deal implementation guidance provided regulatory boundary conditions. Bottom-up vehicle production forecasts triangulated against top-down material consumption estimates from aluminum and high-strength steel trade associations.
Granularity-level modeling disaggregated volume and value across material type, installation channel, vehicle class, and regional production cluster throughout the forecast period. Propulsion architecture differentiation between battery-electric and internal combustion platforms shaped content-per-vehicle assumptions. CAGR derivation synthesized platform electrification timelines, regulatory compliance phase-ins, and supplier capacity expansion announcements across the analysis window.
The model holds under steady regulatory enforcement and OEM platform launch schedules; deviation in REACH substance list expansion timing or battery-electric vehicle adoption rates would shift material substitution trajectories. Periodic stress-testing of base assumptions against aluminum price volatility bands and OEM qualification backlog data is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Glazing for Automotive Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Door Handle Sensors Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Europe Automotive Interiors Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Seat Climate Systems Market
Automotive Interior & Exterior
Two Wheeler Backrest Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market