
 Latin America Biomedical Sensors Market | 2026-2036
Latin America Biomedical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Biomedical Sensors Market Foresight
Sensor-as-a-service subscription models for remote patient monitoring is pivoting how vendors monetize hardware deployments in Latin America. Medtronic leverages its cardiac rhythm management infrastructure to bundle disposable biosensors with cloud analytics contracts across Brazilian hospital networks. Abbott Laboratories anchors glucose monitoring penetration through pharmacy-direct channels in Mexico and Colombia, competing against lower-cost Asian imports.
Biomedical sensors are electromechanical transducers that convert physiological signals—electrical impedance, optical absorbance, or thermal gradients—into quantifiable digital outputs for clinical decision-making, typically operating within precision ranges of ±0.1°C for thermoelectric variants or single-digit millivolt sensitivity for electrochemical electrodes. Non-invasive optical pulse oximetry and wearable accelerometry dominate current volume shipments across Latin American hospitals, while implantable pressure sensors command premium pricing in cardiac and neurological applications where invasive measurement accuracy determines therapeutic outcomes. Electrochemical sensing platforms sustain the fastest technology trajectory, displacing legacy thermoelectric methods in continuous glucose and lactate monitoring systems deployed through home care networks.
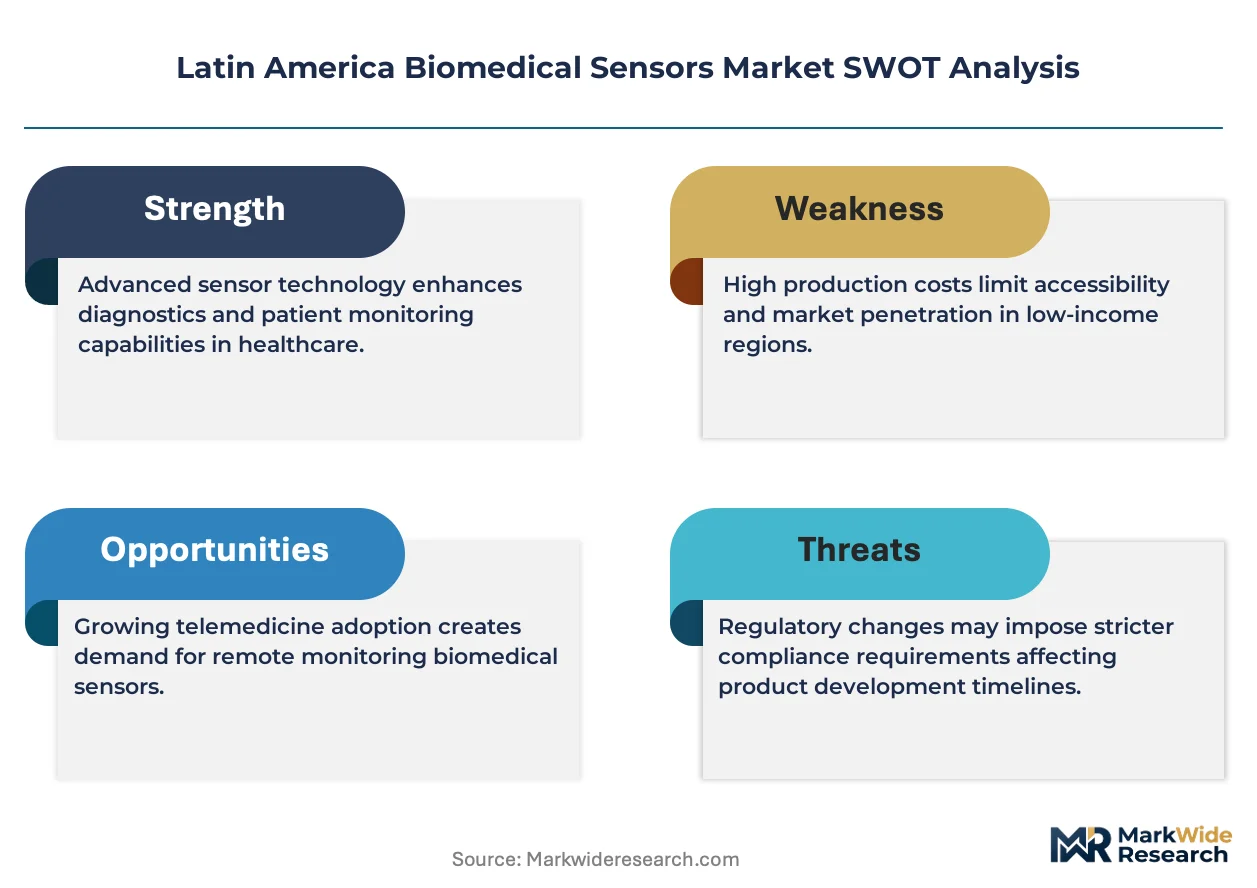
Brazil's ANVISA and Mexico's COFEPRIS enforce escalating medical device registration requirements that filter out uncertified Asian suppliers, creating compliance moats for established multinationals. REACH-aligned substance restrictions from Europe are propagating through Latin American import standards, forcing sensor manufacturers to reformulate electrode coatings and substrate materials. Stakeholders must track how regional trade integration under Pacific Alliance frameworks reshapes cross-border device approval reciprocity and procurement pooling mechanisms.
Market Dynamics
Subscription-based sensor monetization is compressing hardware margins while expanding recurring revenue pools across Brazilian and Mexican healthcare networks. ANVISA's escalating registration requirements for imported devices are filtering supplier bases and elevating compliance costs for market entry.
Growth Catalysts
- Home care expansion:Brazil's aging demographic and chronic disease burden are accelerating demand for wearable glucose and cardiac monitors outside hospital settings, with pharmacy-direct channels capturing patient volume.
- ANVISA regulatory harmonization:Brazil's alignment with MDR-equivalent standards is creating compliance reciprocity pathways that reduce dual-registration burdens for established multinationals.
- Nearshoring manufacturing corridors:Guadalajara and Monterrey clusters are attracting contract medical device production serving North American supply chains, pulling sensor component demand northward from Mexican industrial zones.
Market Restraints
- Precious metal input volatility:Platinum and silver electrode coatings face price swings that compress sensor manufacturing margins, particularly for disposable electrochemical strips.
- Single-source substrate concentration:Polyimide flexible circuit substrates for wearable form factors concentrate in East Asian suppliers, exposing Latin American assemblers to logistics disruptions.
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity validation queues at COFEPRIS-accredited labs extend product launch timelines by 8-14 months for novel implantable sensors.
Strategic Opportunities
- Colombian market penetration:Pharmacy-direct glucose monitoring channels remain underdeveloped relative to Mexico and Brazil, offering first-mover positioning for subscription-based remote patient monitoring.
- Pacific Alliance procurement pooling:Chile, Colombia, Mexico and Peru are advancing cross-border device approval reciprocity that could streamline multi-country sensor registrations.
- Optical-electrochemical convergence:Hybrid sensing platforms combining photoplethysmography with enzymatic electrodes are opening continuous multi-analyte monitoring applications in diabetes management.
Industry Challenges
- Biomedical engineering talent scarcity:Brazilian universities produce insufficient electrochemical sensor specialists to meet ANVISA-mandated quality engineering demands at expanding manufacturing facilities.
- Legacy hospital IT integration:Wearable sensor data streams require HL7 FHIR interface development that stretches thin biomedical informatics teams at public health institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Biomedical Sensors Market |
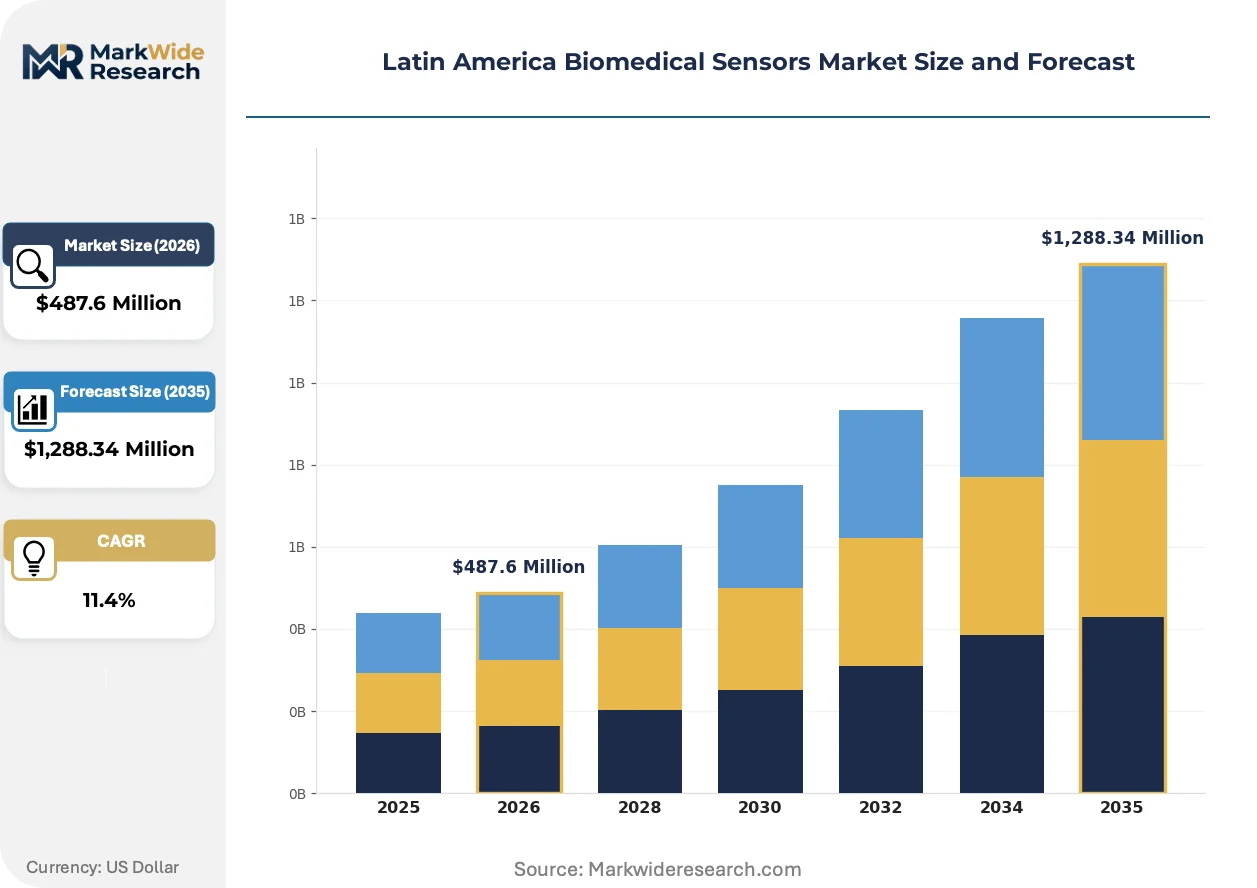
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Invasive Sensors, Non-Invasive Sensors, Implantable Sensors Technology: Optical Sensors, Electrochemical Sensors, Thermoelectric Sensors, RFID Sensors End User: Hospitals, Clinics, Research Laboratories, Home Care Application: Monitoring, Diagnostics, Rehabilitation, Clinical Trials |
| Companies Covered | Medtronic, GE Healthcare, Analog Devices, Inc., STMicroelectronics N.V., NXP Semiconductors N.V., Smiths Group plc., Abbott Laboratories, Koninklijke Philips N.V., Texas Instruments, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Biomedical Sensors Market Shifts & Advancements
Digital biomarker extraction from continuous physiological streams is compressing diagnostic decision cycles and enabling predictive intervention models. Sensor hardware is becoming a loss-leader for analytics platforms that monetize longitudinal patient data.
Multiplexed electrochemical arrays are unifying glucose, lactate, and ketone detection on single disposable strips. Brazilian diabetes management networks are piloting these platforms in public health clinics. This convergence is unifying previously separate consumable supply chains into consolidated procurement contracts that favor volume suppliers with flexible manufacturing.
COFEPRIS is tightening post-market surveillance requirements for Class II and III medical devices, mandating annual safety reporting that mirrors FDA MedWatch structures. Mexican distributors now face liability exposure for imported sensor failures. Implantable pressure monitoring devices face the steepest compliance cost escalation, with some suppliers withdrawing from neurological applications.
Hospital procurement committees are consolidating vendor relationships to reduce contract management overhead, favoring integrated sensor-analytics suppliers over point-solution hardware vendors. Group purchasing organizations in São Paulo and Mexico City are negotiating enterprise-wide remote monitoring subscriptions. This concentration is most visible in cardiac rhythm management, where three-year bundled contracts now displace annual hardware purchases.
Latin America Biomedical Sensors Market Segmentation
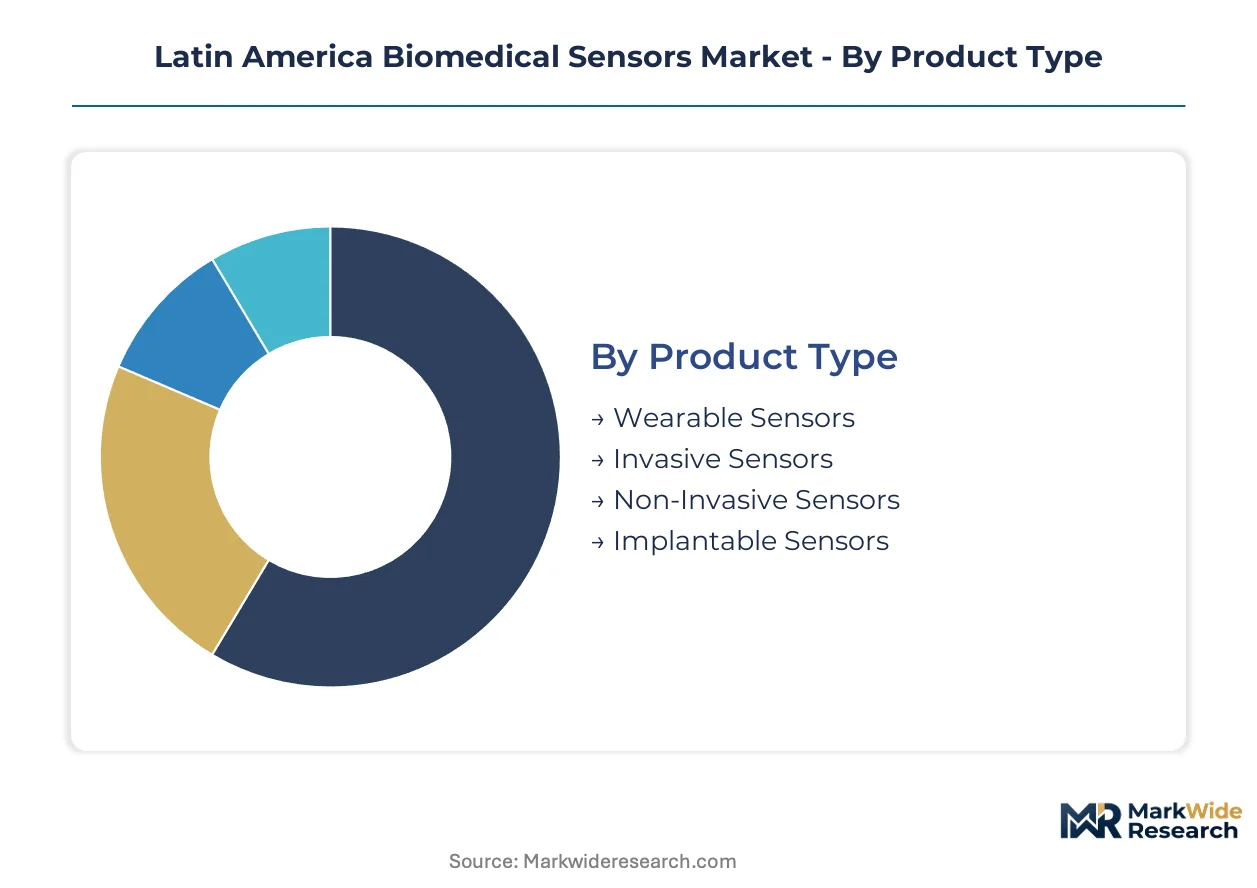
Biomedical sensor architectures in Latin America diverge sharply across physiological interface methods, with electrochemical and optical platforms commanding distinct procurement channels. ANVISA and COFEPRIS registration pathways further stratify segment economics by risk classification.
Product Type:
Physiological interface depth determines regulatory burden and reimbursement eligibility across Brazilian and Mexican procurement networks.
- Wearable Sensors:Flexible polyimide substrates integrate photoplethysmography and accelerometry for continuous ambulatory monitoring. Pharmacy-direct channels in São Paulo and Mexico City are capturing patient volume for diabetes and cardiac rhythm applications outside hospital settings.
- Non-Invasive Sensors:Optical pulse oximetry and infrared thermography dominate current hospital procurement volumes through disposable finger-clip and forehead-applied configurations. Brazilian public health networks favor these for reduced infection control overhead versus invasive alternatives.
- Invasive Sensors:Percutaneous catheter-mounted pressure and flow transducers serve intensive care hemodynamic monitoring. COFEPRIS Class III registration requirements extend approval timelines for new entrants.
- Implantable Sensors:Miniaturized pressure transducers for cardiac and intracranial applications command premium pricing tiers. ANVISA-mandated biocompatibility testing bottlenecks constrain supplier bases to established multinationals.
Non-invasive sensors lead on scale; wearable sensors lead on momentum.
Technology:
Signal transduction mechanisms are displacing legacy methods as electrochemical platforms achieve multiplexed analyte detection.
- Electrochemical Sensors:Enzymatic glucose and lactate electrodes on disposable strips are consolidating previously separate consumable supply chains. Brazilian diabetes management networks pilot unified glucose-ketone-lactate arrays in public health clinics.
- Optical Sensors:Photoplethysmography and near-infrared spectroscopy enable SpO2 and regional oxygen saturation monitoring without vascular access. Mexican manufacturing corridors near Guadalajara assemble these for North American supply chain integration.
- Thermoelectric Sensors:Precision thermistors and thermopiles measure core body temperature within ±0.1°C tolerance. These are retreating to niche applications as optical methods expand.
- RFID Sensors:Passive and battery-assisted passive tags track sensor inventory and patient identification in hospital logistics. RFID-temperature loggers monitor cold chain integrity for vaccine distribution across Pacific Alliance member states.
Electrochemical platforms are expanding most quickly; optical sensors retain installed base dominance.
End User:
Care setting economics are pivoting procurement from capital equipment sales toward subscription-based remote monitoring contracts.
- Home Care:Wearable glucose monitors and cardiac event recorders deploy through pharmacy-direct channels with cloud analytics bundling. Brazil's aging demographic and chronic disease burden accelerate demand outside institutional settings.
- Hospitals:Integrated sensor-analytics suppliers capture multi-year bundled contracts for cardiac rhythm management. São Paulo and Mexico City group purchasing organizations consolidate vendor relationships to reduce contract management overhead.
- Clinics:Outpatient facilities favor point-of-care electrochemical strips for rapid glucose and cholesterol screening. These settings prioritize low capital expenditure and minimal training requirements.
- Research Laboratories:Investigational device exemptions support novel biomarker validation for Pacific Alliance harmonization pathways. Preclinical biocompatibility studies feed into ANVISA and COFEPRIS registration dossiers.
Hospitals lead on scale; home care leads on momentum.
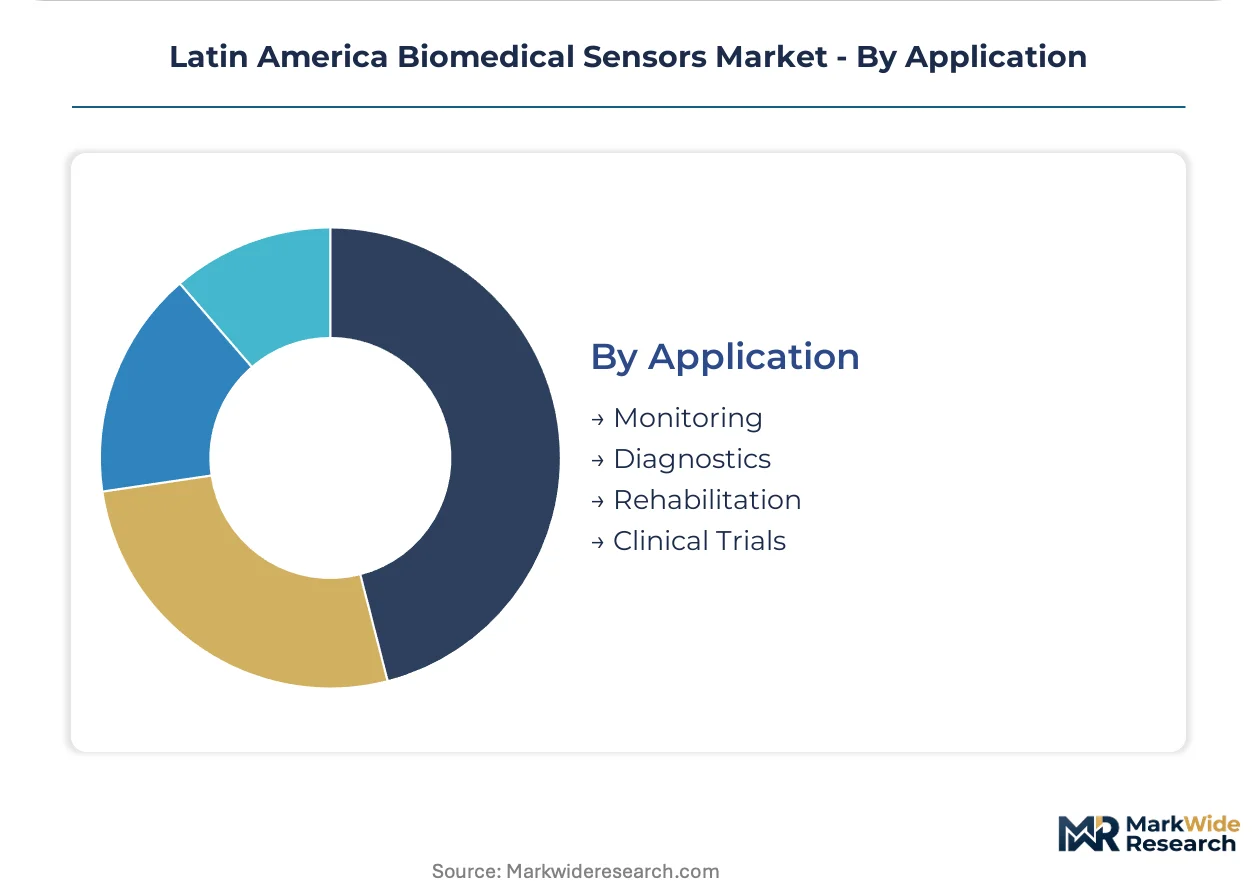
Application:
Clinical utility determines sensor specification requirements and regulatory classification intensity.
- Monitoring:Continuous physiological surveillance for glucose, cardiac rhythm, and respiratory parameters drives volume shipments. Real-time data streams require HL7 FHIR interface development that strains biomedical informatics capacity at Brazilian public institutions.
- Diagnostics:Single-use electrochemical strips and optical readers deliver rapid point-of-care results for infectious disease and metabolic panels. These applications face margin compression from lower-cost Asian imports.
- Rehabilitation:Wearable accelerometry and surface electromyography track motor recovery progress for stroke and orthopedic patients. Mexican rehabilitation centers integrate these with telemedicine platforms for rural patient reach.
- Clinical Trials:Validated sensor endpoints support decentralized trial designs across Chile, Colombia, Mexico and Peru. Pacific Alliance regulatory reciprocity discussions aim to streamline multi-country device approvals for trial sponsors.
Monitoring leads on scale; clinical trials lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands the largest addressable base while Mexico leverages manufacturing proximity to North American supply chains. Chile and Colombia are advancing regulatory reciprocity frameworks that could streamline multi-country device approvals. Argentina's economic volatility constrains import-dependent sensor procurement despite substantial clinical demand.
Brazil
Home care expansion for diabetes and cardiac monitoring drives wearable sensor volume through pharmacy-direct channels. ANVISA's medical device registration requirements filter uncertified Asian suppliers and elevate compliance costs for market entry. São Paulo's healthcare procurement clusters anchor group purchasing organization negotiations for multi-year remote monitoring subscriptions.
Mexico
Contract medical device production serving North American supply chains concentrates sensor component demand in Guadalajara and Monterrey manufacturing corridors. COFEPRIS tightens post-market surveillance for Class II and III devices through annual safety reporting mandates. Mexico City distributors face expanded liability exposure for imported sensor failures under revised regulatory frameworks.
Colombia
Pharmacy-direct glucose monitoring channels remain underdeveloped relative to regional peers, creating first-mover positioning for subscription-based remote patient monitoring. The national pharmaceutical regulator advances alignment with Pacific Alliance harmonization pathways. Bogotá's healthcare networks pilot hybrid optical-electrochemical sensing platforms for diabetes management in public clinics.
Chile
Decentralized clinical trial designs leverage validated sensor endpoints across Santiago's research hospital networks. Pacific Alliance regulatory reciprocity discussions aim to streamline multi-country device approvals for trial sponsors. Valparaiso's logistics infrastructure supports cold chain integrity monitoring for vaccine distribution through RFID-temperature loggers.
Argentina
Import-dependent sensor procurement faces persistent currency volatility and foreign exchange controls that stretch hospital procurement timelines. The national medical device regulator maintains registration requirements that favor established multinational suppliers with local quality engineering presence. Buenos Aires public health institutions prioritize low-capital-expenditure point-of-care electrochemical strips over integrated sensor-analytics systems.
Latin America Biomedical Sensors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated sensor-analytics suppliers capturing multi-year bundled contracts while point-solution hardware vendors face procurement consolidation pressure. The vendor base concentrates around three strategic archetypes: diversified healthcare conglomerates with cardiac rhythm management infrastructure, semiconductor specialists supplying transducer components, and pure-play sensor manufacturers competing on disposable strip economics. M&A activity targets analytics platform capabilities, while geographic expansion focuses on Pacific Alliance regulatory harmonization pathways.
Among diversified healthcare conglomerates, Medtronic and Abbott Laboratories exemplify the integrated sensor-analytics archetype through bundled hardware-cloud contracts. STMicroelectronics N.V. represents the semiconductor component supplier tier, occupying a position upstream from finished device assembly. These anchors illustrate how competitive positioning stratifies across subscription monetization, component supply, and disposable manufacturing vectors.
| Leading Market Players |
|---|
| Medtronic |
| GE Healthcare |
| Analog Devices, Inc. |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| Smiths Group plc. |
| Abbott Laboratories |
| Koninklijke Philips N.V. |
| Texas Instruments |
| Others |
Supply & Pricing Matrix
São Paulo and Mexico City group purchasing organizations concentrate procurement volume for remote patient monitoring subscriptions, anchoring a contract-based pricing model that favors multi-year bundled agreements over transactional hardware sales. ANVISA-mandated biocompatibility testing costs and platinum electrode input volatility feed directly into supplier pricing power.
Pricing Analysis
Capacity additions in Mexican manufacturing corridors near Guadalajara and Monterrey are reshaping price floors for optical sensor assemblies serving North American supply chains. Three-tier pricing structure across premium, standard, and economy levels separates implantable pressure transducers with full ANVISA Class III certification from unvalidated imports and mid-tier hospital-grade disposables. Cost compression in disposable electrochemical strips is intensifying because of silver and platinum price volatility. Public health institutions in Brazil exhibit highest price sensitivity due to budget constraints, while private cardiac networks in São Paulo demonstrate lowest sensitivity for premium implantable devices.
Supply Chain Analysis
Brazil's escalating local-content requirements for ANVISA-registered devices are reshaping sourcing patterns, pushing assemblers toward regional substrate suppliers. Polyimide flexible circuit substrates draw from East Asian suppliers in Taiwan, South Korea, and Japan, while enzymatic electrode coatings source from specialized chemical processors in Germany and Switzerland. Single-source concentration in polyimide substrates exposes Latin American assemblers to logistics chokepoint risk from transpacific shipping disruptions. Distribution runs through authorized medical device distributors in São Paulo and Mexico City who maintain COFEPRIS and ANVISA import licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily because chronic disease prevalence across Brazil and Mexico generates recurring demand for continuous monitoring hardware and analytics subscriptions. Regulatory compliance moats protect incumbent positions while subscription monetization expands addressable revenue per patient.
For Market Incumbents: Deploy cloud analytics bundling to deepen recurring revenue attachment rates on disposable sensor hardware. Integrate backward into electrode coating production to insulate margins from precious metal volatility. Consolidate vendor relationships with São Paulo group purchasing organizations before Pacific Alliance procurement pooling matures. ANVISA registration reciprocity pathways threaten to lower barriers for European competitors. For New Entrants and Emerging Players: Pharmacy-direct digital channels in Colombia offer the most penetrable route for subscription-based glucose monitoring, with channel infrastructure underdeveloped relative to Mexican and Brazilian benchmarks. Target Bogotá's public health clinic networks with hybrid optical-electrochemical platforms piloted for diabetes management. Secure COFEPRIS registration through Pacific Alliance harmonization pathways to accelerate multi-country market access without sequential national filings. For Investors and Strategic Acquirers: Diversified healthcare conglomerates with cardiac rhythm management infrastructure are the most active acquirers in this space, seeking analytics platform capabilities to complete sensor-to-cloud integration. Acquisition target archetype: pure-play electrochemical sensor manufacturers with ANVISA-approved quality systems and established pharmacy-direct distribution. Watch for Pacific Alliance regulatory reciprocity implementation as inflection signal for cross-border procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Reciprocity Pathway | European MDR-aligned certifications accelerate Brazilian market entry for established multinationals. |
| Hospital System Partnership | São Paulo GPOs negotiate enterprise-wide remote monitoring subscriptions spanning three-year terms. |
| Software Companion Development | Cloud analytics platforms monetize longitudinal patient data streams from wearable glucose monitors. |
| Reimbursement Strategy | Pharmacy-direct channels in Mexico and Colombia require private payer contract alignment for subscription uptake. |
| CE Marking Pathway | European certification propagates through Latin American import standards via REACH-aligned substance restrictions. |
Research Methodology
Coverage spans Brazil, Mexico, Colombia, Chile, and Argentina, with primary inputs from each national market. The research combines structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at ANVISA and COFEPRIS with secondary validation from hospital procurement databases, GPO contract disclosures, and medical device registration filings. Bottom-up sensor shipment estimates triangulate against top-down healthcare expenditure allocations across home care, hospital, and clinic settings.
Rate-of-change decomposition separates volume growth from price trajectory across the analysis window. The analytical framework models segmentation across physiological interface depth, signal transduction technology, care setting economics, and clinical application intensity. CAGRs derive from installed base expansion rates for wearable monitors, replacement demand for disposable electrochemical strips, and subscription attach rates for cloud analytics platforms. Forecast inputs incorporate ANVISA registration queue timelines, Pacific Alliance regulatory reciprocity progression, and precious metal price volatility assumptions for electrode manufacturing.
The model assumes a particular technology adoption path; alternative pathways for optical-electrochemical hybrid platforms would alter the outlook if multiplexed analyte detection achieves cost parity with single-parameter sensors. Forecasts reflect assumptions regarding chronic disease prevalence trends, regulatory harmonization timelines, and supply chain regionalization incentives. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Middle East and Africa Surgical Equipment Market
Medical Devices
Invisible Orthodontics Market
Medical Devices
Bone Conduction Hearing Devices Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
Surgical Robotics Performance and Safety Validation Test Platforms Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Foot Suction Unit Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
3D Printed Medical Implants Market
Medical Devices
Intraosseous Infusion Device Market
Medical Devices
Transport Chairs Market