
 UAE Satellite Communication Market | 2026-2036
UAE Satellite Communication Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Satellite Communication Market Insights
Software-defined payload management is rebalancing how satellite capacity gets monetized in the UAE, shifting buyers from fixed transponder leases toward flexible, usage-based models. Yahsat leverages its in-orbit fleet and ground infrastructure to anchor government and enterprise contracts across the Middle East and Africa. Thuraya competes through specialized mobile satellite services for maritime and remote enterprise users. Es'hailSat controls broadcast and broadband distribution from its geostationary slots serving the region.
Satellite communication encompasses the transmission, relay, and reception of voice, video, and data signals via artificial Earth-orbiting spacecraft operating in designated frequency bands, with Ku Band and Ka Band systems enabling high-throughput connectivity exceeding 100 Mbps per user terminal. Its primary commercial purpose is to deliver reliable, wide-area coverage for applications where terrestrial networks prove uneconomical or physically impossible. Broadcast Services still generates the largest revenue pool among service types, though Internet Services is expanding fastest as fiber-backhaul gaps persist in rural Emirates. Ka Band technology leads capacity economics for broadband deployment, while L Band retains structural importance for mobile and safety-of-life applications.
TRAI spectrum coordination rules and the UAE Space Agency's licensing framework shape operator market access and orbital slot utilization, with MOHAP and the Telecommunications and Digital Government Regulatory Authority enforcing cybersecurity and data sovereignty standards for satellite-linked critical infrastructure. National content requirements and foreign ownership caps in telecom infrastructure further condition how international operators like Intelsat and SES structure local partnerships. Stakeholders must monitor how the UAE's evolving space commercialization policies and emerging low-Earth-orbit constellation authorizations reshape competitive dynamics for incumbent geostationary providers.
Market Dynamics
Software-defined payload architectures are redistributing value capture across the UAE satellite value chain, compressing traditional transponder lease economics while expanding addressable markets for on-demand capacity provisioning.
Growth Catalysts
- UAE Space Agency orbital slot licensing:Accelerated authorization timelines for geostationary and non-geostationary constellations reduce market entry friction for domestic and partnered operators.
- Defense and maritime procurement expansion:Government-backed fleet modernization programs under the National Space Strategy sustain multi-year service contracts with integrated ground segment requirements.
- Ka Band throughput economics:Higher spectral efficiency per orbital slot enables competitive broadband pricing in fiber-underserved Emirates, unlocking enterprise and consumer segments previously served by lower-bandwidth alternatives.
Market Restraints
- Launch cost volatility:Dependence on foreign launch providers exposes operators to payload deployment delays and insurance premium fluctuations.
- Spectrum coordination complexity:ITU filing procedures and cross-border interference mitigation requirements extend time-to-revenue for new orbital assets.
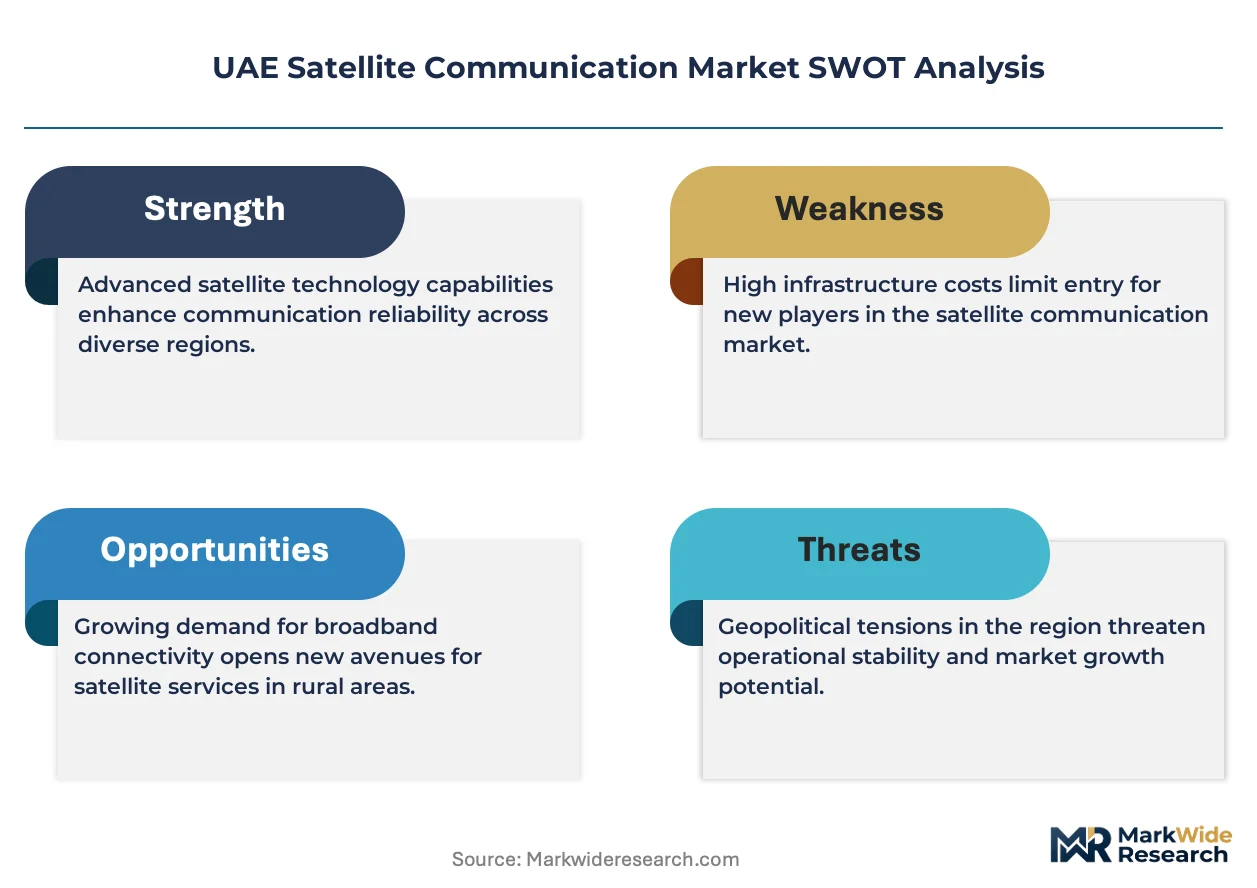
- Terrestrial 5G backhaul substitution:Fiber rollout acceleration in Dubai and Abu Dhabi urban corridors compresses addressable market for satellite broadband in high-density zones.
Strategic Opportunities
- Northern Emirates connectivity gaps:Ras Al Khaimah and Fujairah present underpenetrated demand for maritime and remote enterprise satellite services where terrestrial infrastructure remains uneconomical.
- IoT and M2M convergence:Integration of satellite narrowband with terrestrial LPWAN networks creates bundled offerings for oilfield monitoring and logistics tracking applications.
- MOHAP cybersecurity certification pathways:Streamlined approval processes for satellite-linked critical infrastructure reduce compliance friction for healthcare and energy sector deployments.
Industry Challenges
- RF engineering talent scarcity:Limited domestic pipeline of satellite systems engineers and spectrum analysts constrains fleet expansion and ground segment scaling timelines.
- Legacy ground infrastructure integration:Existing teleport and hub architectures require costly retrofitting to support software-defined network orchestration and multi-orbit interoperability.
- Dual-use export control navigation:Defense-civilian technology overlap complicates component sourcing and international partnership structuring under evolving trade compliance frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Satellite Communication Market |
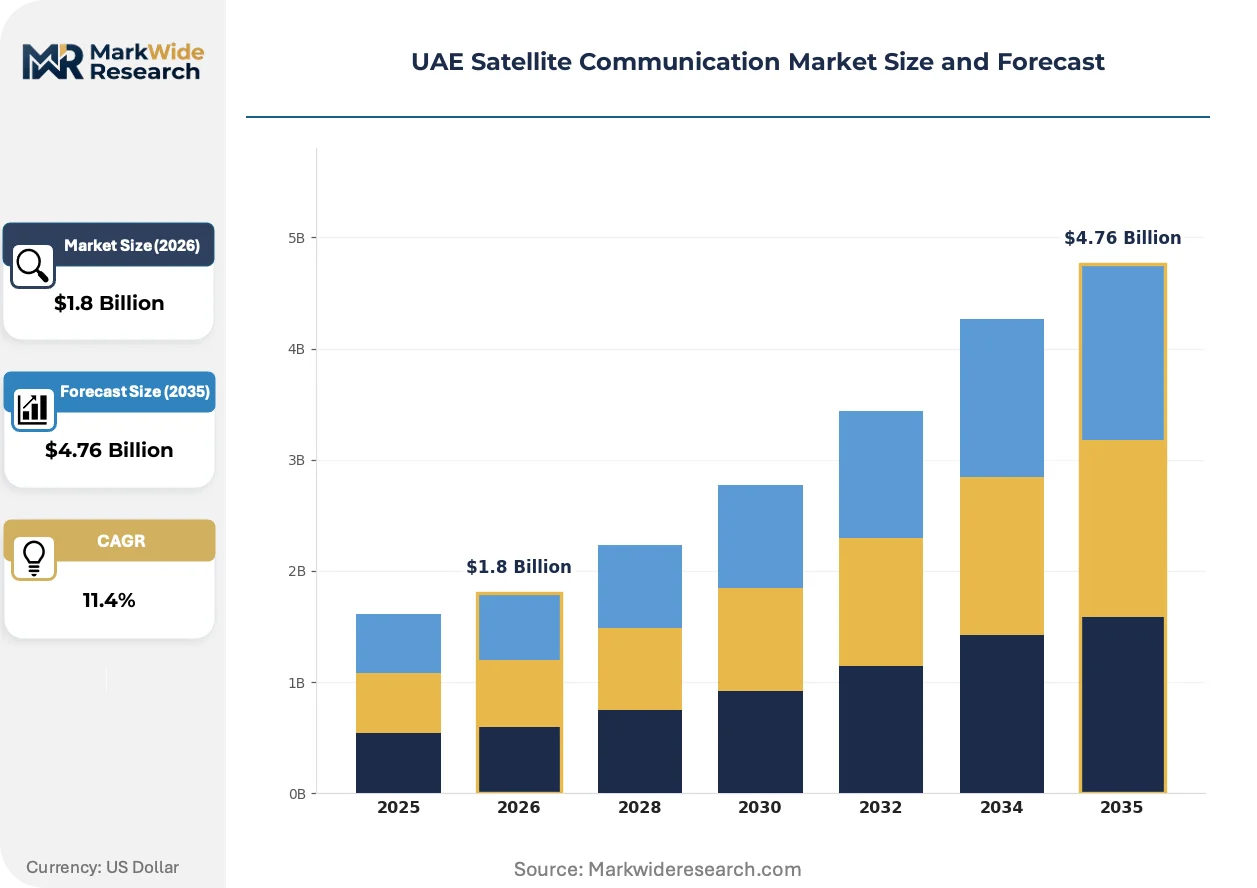
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadcast Services, Mobile Services, Internet Services, Data Services Application: Aerospace, Maritime, Defense, Telecommunications Technology: C/V Band, Ku Band, Ka Band, L Band End User: Enterprise, Government, Residential, Military |
| Companies Covered | Emirates Integrated Telecommunications Company, Intelsat, Yahsat, Arabsat, Viasat, Thuraya, SES, Es’hailSat, Emirates Telecommunications Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Satellite Communication Market Trends and Innovations
Digital payload architectures and regulatory frameworks are converging to restructure how satellite capacity is provisioned, priced, and secured across the Emirates. These shifts compress legacy operating models while opening new service categories.
Software-defined radios and digital beamforming are modularizing satellite payload design, replacing analog hardware with reprogrammable signal processing chains. Defense integrators and maritime fleet operators are accelerating procurement of terminals compatible with these architectures. This modularity is compressing hardware refresh cycles from decade-long satellite lifespans to incremental ground-segment upgrades.
Telecommunications and Digital Government Regulatory Authority cybersecurity mandates for satellite-linked critical infrastructure are tightening data sovereignty and encryption standards. Industrial consequence includes mandatory local data processing nodes and enhanced breach notification protocols. Energy and healthcare verticals are responding by restructuring service contracts to include dedicated UAE-terrestrial gateway requirements.
Enterprise buyers are unbundling satellite connectivity from integrated hardware-service bundles, preferring bring-your-own-terminal arrangements with usage-based capacity pricing. Systems integrators and direct operator channels are displacing traditional value-added reseller networks. This pattern is most pronounced in Dubai's logistics and offshore oil services sectors where fleet standardization across multiple connectivity providers reduces switching costs.
UAE Satellite Communication Market Segmentation
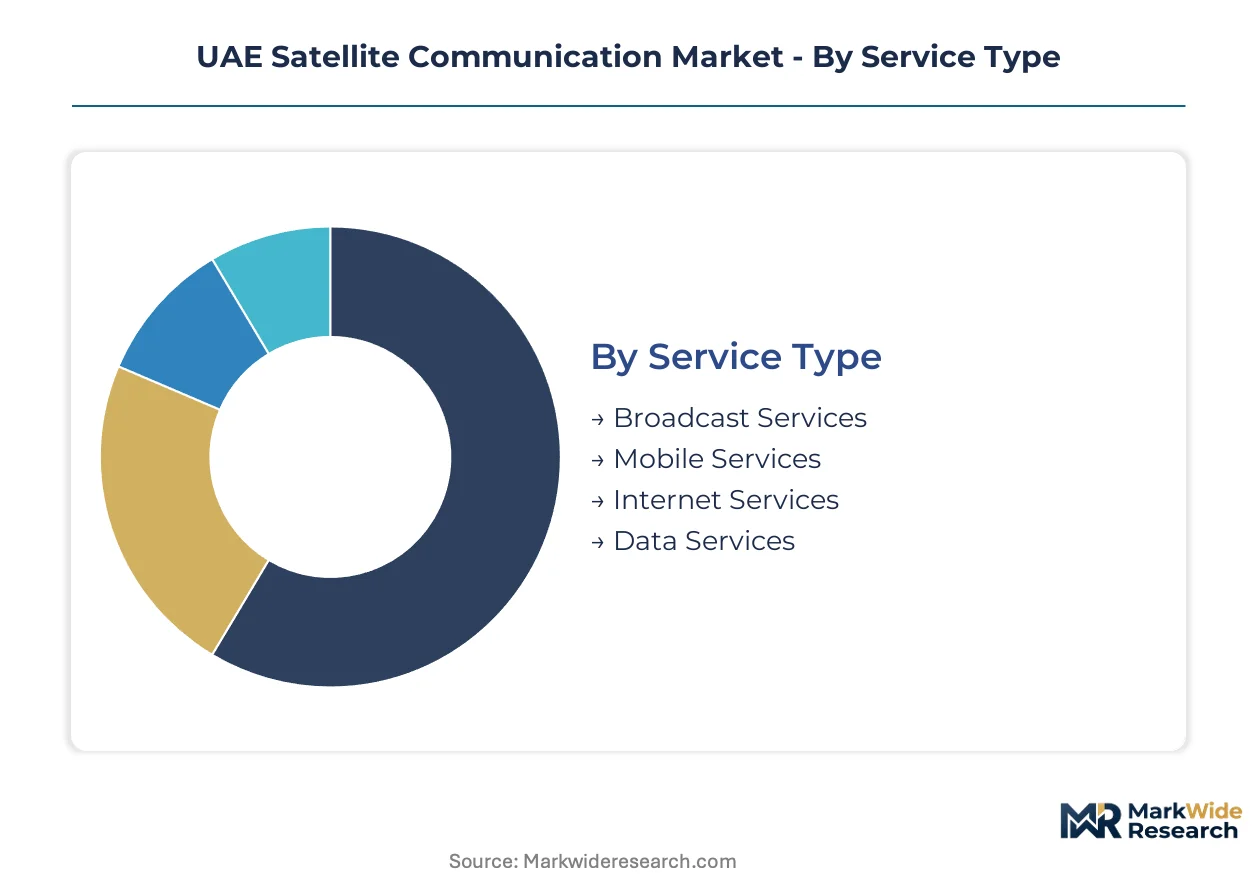
Segmentation in the UAE satellite communication market reveals how regulatory requirements and infrastructure economics shape procurement patterns across government, enterprise, and consumer tiers. Understanding these divides clarifies where MOHAP cybersecurity certifications, UAE Space Agency licensing, and Telecommunications and Digital Government Regulatory Authority standards apply differentially.
Service Type:
MOHAP cybersecurity certification and Telecommunications and Digital Government Regulatory Authority data sovereignty standards impose tiered compliance burdens across service categories, with critical infrastructure-linked offerings facing the most stringent gateway localization requirements.
- Broadcast Services:Linear television and radio distribution via geostationary transponders still commands the largest revenue pool among service types. Abu Dhabi and Dubai media clusters sustain multi-year capacity commitments, though direct-to-home subscriber growth plateaus as streaming penetration deepens.
- Internet Services:Broadband access provision via Ka Band high-throughput satellites is expanding most quickly, driven by fiber-backhaul gaps in Ras Al Khaimah and Fujairah where terrestrial deployment remains uneconomical. Enterprise and government buyers increasingly favor usage-based pricing over fixed transponder leases.
- Mobile Services:Narrowband voice and data for maritime and remote enterprise users, requiring L Band terminals certified for safety-of-life applications. Thuraya specializes in this segment across the Middle East and Africa.
- Data Services:Enterprise-grade private networks and backhaul for cellular infrastructure, subject to UAE Space Agency orbital slot coordination and cross-border interference mitigation protocols.
Leading the category by volume: Broadcast Services. Growing fastest: Internet Services.
Application:
Cost tier stratification separates defense-grade integrated solutions from commercial off-the-shelf offerings, with aerospace and maritime commanding premium pricing for certified terminals and dedicated ground segment infrastructure.
- Defense:Military-grade secure communications demand end-to-end encryption, anti-jamming capabilities, and dedicated UAE-terrestrial gateways compliant with National Space Strategy procurement frameworks. Multi-year service contracts integrate satellite capacity with classified ground infrastructure.
- Maritime:Fleet broadband and safety communications for commercial shipping and offshore energy operations concentrate demand in Fujairah's port cluster and Abu Dhabi offshore fields. L Band mobile satellite services retain structural importance for global coverage continuity.
- Aerospace:In-flight connectivity and unmanned aerial system command-and-control links, requiring low-latency Ka Band solutions and aviation regulatory certification pathways.
- Telecommunications:Cellular backhaul and rural broadband extension, where satellite fills gaps in Dubai and Abu Dhabi exurbs and Northern Emirates fiber buildouts.
Highest contract values: Defense. Steepest expansion trajectory: Maritime.
Technology:
Application requirements dictate frequency band selection, with throughput economics and terminal mobility needs driving divergent deployment patterns across the Emirates.
- Ka Band:High-frequency spectrum enabling 100+ Mbps per user terminal through spot beam architectures, now dominant for broadband internet services. Spectral efficiency per orbital slot supports competitive pricing in fiber-underserved zones.
- Ku Band:Established broadcast and enterprise VSAT standard, balancing rain fade resilience with capacity economics. Legacy infrastructure across UAE teleports sustains transitional demand.
- L Band:Lower frequency allocation optimized for mobile terminals and safety-of-life applications, including maritime distress signaling and remote asset tracking. Thuraya's specialized services anchor this segment.
- C/V Band:Traditional broadcast distribution and institutional networks, with C Band offering superior rain fade tolerance for tropical climate resilience in regional uplink scenarios.
Widest deployment: Ku Band. Gaining share fastest: Ka Band.
End User:
Customer type determines procurement channel structure, with government and military buyers favoring direct operator relationships while residential segments flow through retail distribution partnerships.
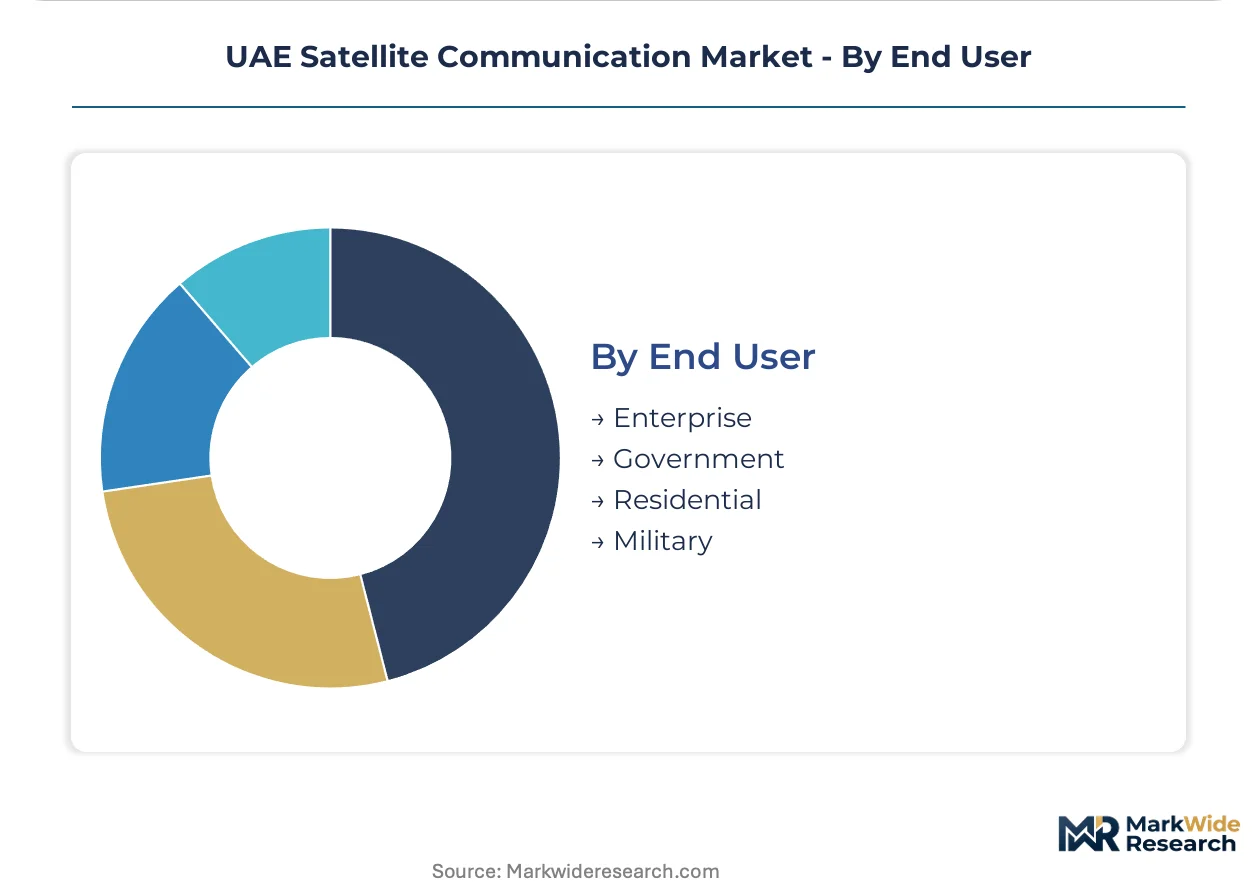
- Government:Federal and emirate-level agencies procuring secure communications under UAE Space Agency oversight, with mandatory local data processing nodes and MOHAP cybersecurity certification for critical infrastructure applications.
- Enterprise:Oilfield operators, logistics providers, and financial institutions in Dubai and Abu Dhabi, increasingly unbundling hardware from service contracts and standardizing terminals across multiple connectivity providers.
- Military:Defense-specific requirements overlapping with civilian technology, complicating component sourcing under dual-use export control frameworks and demanding specialized integration partners.
- Residential:Direct-to-home broadcast and emerging consumer broadband, concentrated in Northern Emirates connectivity gaps where terrestrial alternatives remain unavailable.
Dominant revenue source: Government. Expanding most quickly: Enterprise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of satellite capacity concentrates in orbital slots licensed through the UAE Space Agency, while consumption clusters in Abu Dhabi and Dubai government contracts and Northern Emirates connectivity gaps.
Dubai
Dubai's logistics and offshore oil services sectors drive enterprise demand for flexible capacity pricing. Telecommunications and Digital Government Regulatory Authority cybersecurity mandates tighten data sovereignty requirements for satellite-linked critical infrastructure. Jebel Ali port cluster and Dubai Media City anchor maritime and broadcast service procurement respectively.
Abu Dhabi
Abu Dhabi hosts defense and government procurement under National Space Strategy frameworks. UAE Space Agency licensing accelerates orbital slot authorization for geostationary assets. Yas Island and Masdar City clusters concentrate media and clean technology satellite applications.
Sharjah
Sharjah's industrial zones generate enterprise VSAT demand for remote facility connectivity. MOHAP certification pathways apply to healthcare sector satellite deployments. Hamriyah Free Zone supports ground segment equipment import and distribution.
Northern Emirates
Ras Al Khaimah and Fujairah present underpenetrated broadband demand where terrestrial fiber remains uneconomical. TRAI spectrum coordination rules govern cross-border interference mitigation for maritime services. Fujairah's port cluster sustains L Band mobile satellite procurement for shipping safety.
UAE Satellite Communication Market Competitive Landscape
Capital-heavy satellite operators compete with asset-light service integrators for value capture in the UAE market. Fleet ownership and orbital slot control concentrate among three domestic and regional operators, while international players access the market through partnership structures. Strategic archetypes include integrated fleet operators, specialized mobile service providers, and global capacity wholesalers. Dominant competitive moves involve ground infrastructure partnerships and multi-orbit service bundling.
Within the integrated operator tier, Yahsat and Es'hailSat anchor government and broadcast contracts through UAE-registered entities. Thuraya occupies a specialized position in L Band mobile satellite services. Among international capacity providers, Intelsat and SES exemplify the global wholesaler archetype accessing UAE demand through local partnership structures rather than direct licensing.
| Leading Market Players |
|---|
| Emirates Integrated Telecommunications Company |
| Intelsat |
| Yahsat |
| Arabsat |
| Viasat |
| Thuraya |
| SES |
| Es’hailSat |
| Emirates Telecommunications Group |
| Others |
Pricing and Supply Chain Analysis
Enterprise unbundling of hardware from service contracts in Dubai's logistics sector is compressing traditional bundled pricing models and forcing operators toward usage-based capacity provisioning with thinner equipment margins.
Pricing Analysis
Margin tightening in broadband services reflects enterprise procurement teams standardizing terminals across multiple connectivity providers. Pricing stratifies across premium defense-grade encryption, standard enterprise VSAT, and economy direct-to-home tiers. Cost-down pressure on ground segment equipment accelerates because buyers increasingly source terminals independently. Government and military segments demonstrate lowest price sensitivity due to National Space Strategy procurement mandates.
Supply Chain Analysis
Single-source vulnerability sits with foreign launch providers for payload deployment. Manufacturing concentration spans the United States, France, and Japan for satellite bus components and propulsion systems. Raw material dependencies include gallium arsenide semiconductors, composite structural materials, and specialty alloys for thermal management. Tariff exposure on space-qualified electronics complicates component sourcing timelines. Distribution runs through UAE-registered entities holding UAE Space Agency orbital licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as software-defined payload architectures compress legacy transponder lease economics and strand operators without digital beamforming capabilities.
For Market Incumbents: Anticipate displacement by asset-light service integrators by deepening ground infrastructure partnerships in Ras Al Khaimah and Fujairah. Secure MOHAP cybersecurity certification pathways ahead of tightened Telecommunications and Digital Government Regulatory Authority mandates to maintain government contract eligibility. Prioritize multi-orbit service bundling to defend against low-Earth-orbit constellation entrants. For New Entrants and Emerging Players: Northern Emirates maritime operators present the most penetrable demand cluster for specialized L Band mobile satellite services. Target healthcare sector satellite deployments requiring streamlined MOHAP certification pathways. Pursue bring-your-own-terminal arrangements with usage-based pricing to bypass incumbent hardware-service bundles. For Investors and Strategic Acquirers: The window for entry favors operators with software-defined payload capabilities and existing UAE Space Agency licensing relationships. Long-term viability hinges on orbital slot control and ground segment density rather than fleet scale alone. Watch for low-Earth-orbit constellation authorization announcements as inflection indicators for geostationary incumbent repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Ground Infrastructure Partnership | Teleport expansion in Fujairah secures maritime service contracts under TRAI coordination rules. |
| Multi-Orbit Service Bundling | Combined geostationary and low-Earth-orbit offerings address latency-sensitive aerospace applications. |
| Cybersecurity Certification Investment | MOHAP approval unlocks healthcare and energy sector satellite-linked critical infrastructure deployments. |
| Software-Defined Payload Upgrade | Digital beamforming architectures enable flexible capacity monetization beyond fixed transponder leases. |
| Orbital Slot Licensing Expansion | UAE Space Agency authorizations for non-geostationary constellations preempt competitive entry friction. |
Research Methodology
SEC filings, ITU satellite network filings, and UAE Space Agency licensing records formed the secondary backbone for capacity and orbital slot analysis. Primary interviews with satellite fleet operators, ground segment integrators, defense procurement officers, and maritime fleet managers validated demand assumptions. Bottom-up and top-down triangulation reconciled operator-reported capacity metrics with government contract disclosure patterns.
Bottom-up modeling aggregated individual orbital slot economics and ground segment deployment timelines across the projection horizon. Segmentation dimensions included service type, frequency band technology, end-user category, and emirate-level demand clustering. CAGRs derived from fitted growth curves applied to disclosed contract values and capacity utilization trajectories. Forecast inputs incorporated TRAI spectrum coordination timelines and National Space Strategy procurement schedules.
Revisions become necessary when launch cost volatility disrupts payload deployment schedules or when terrestrial 5G backhaul substitution accelerates beyond modeled fiber rollout assumptions. Forecasts reflect documented assumptions about regulatory authorization timelines and enterprise procurement pattern stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Launch Vehicle (SLV) Market
Satellite
Europe Small Satellite Market
Satellite
Military Satellite Market
Satellite
North America Small Satellite Market
Satellite
Satellite Internet Market
Satellite
Cubesat Market
Satellite
Commercial LEO Satellite Market
Satellite
Germany Satellite Connectivity Market
Satellite
Satellite Data Service Market
Satellite
Latin America Satellite Connectivity Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
US Satellite-Based Earth Observation Market
Satellite
Asia-Pacific Satellite Connectivity Market
Satellite
Satellite Transponder Market
Satellite
China Satellite Connectivity Market
Satellite
Earth Observation Satellite Market