
 Latin America Defense Market | 2026-2036
Latin America Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Defense Market Foresight
Brazilian aerospace manufacturing capacity is decoupling from traditional import dependency as Embraer S.A. extends its defense division into tactical transport and ISR platforms. Saab AB leverages its Gripen E partnership with Embraer to anchor regional fighter production with local assembly lines in São Paulo state. Lockheed Martin Corporation competes through sustained F-16 upgrade programs across Andean air forces. Thales Group differentiates in naval combat management systems, occupying the frigate modernization segment in Chile and Peru.
Latin America defense encompasses military hardware, software, and services procured by national security establishments across the region, spanning platforms with operational ranges from coastal patrol to continental air defense and specifications calibrated to tropical and high-altitude environments. Aircraft procurement leads absolute spending as Brazil, Colombia, and Chile replace aging fleets with multirole fighters and transport platforms, while naval systems represent the fastest-growing category driven by offshore resource protection mandates. Cybersecurity Solutions within the Technology dimension is capturing disproportionate investment attention as militaries harden command infrastructure against electronic warfare threats.
Brazil's Comissão de Valores Mobiliários and Colombia's national contracting oversight frameworks shape procurement transparency requirements, while ANVISA and analogous health regulators indirectly influence military medical and biosecurity equipment standards. The EU Green Deal's extraterritorial carbon accounting provisions are beginning to condition European-origin platform bids in the region. Stakeholders must monitor how local content thresholds evolve across Mercosur and Pacific Alliance procurement codes to calibrate partnership strategies.
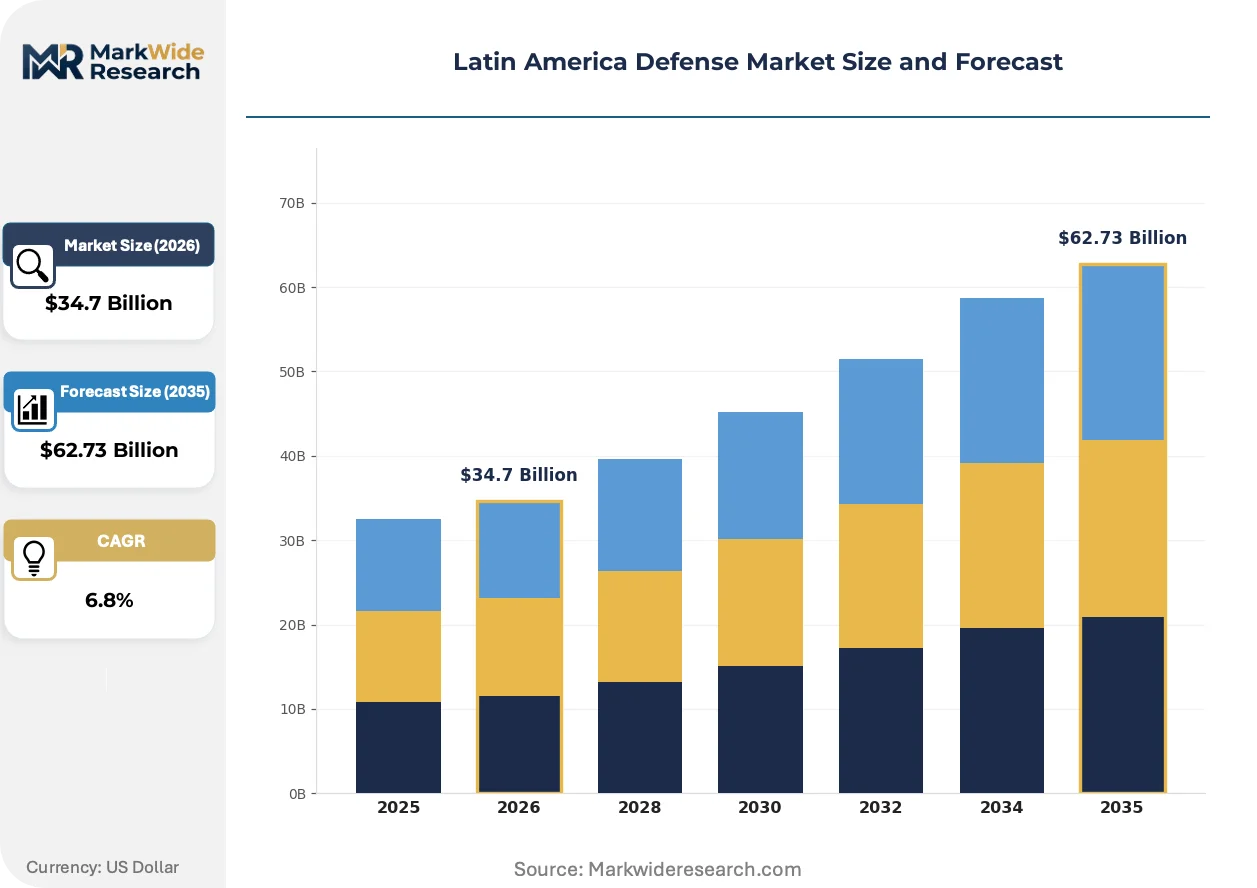
Market Dynamics
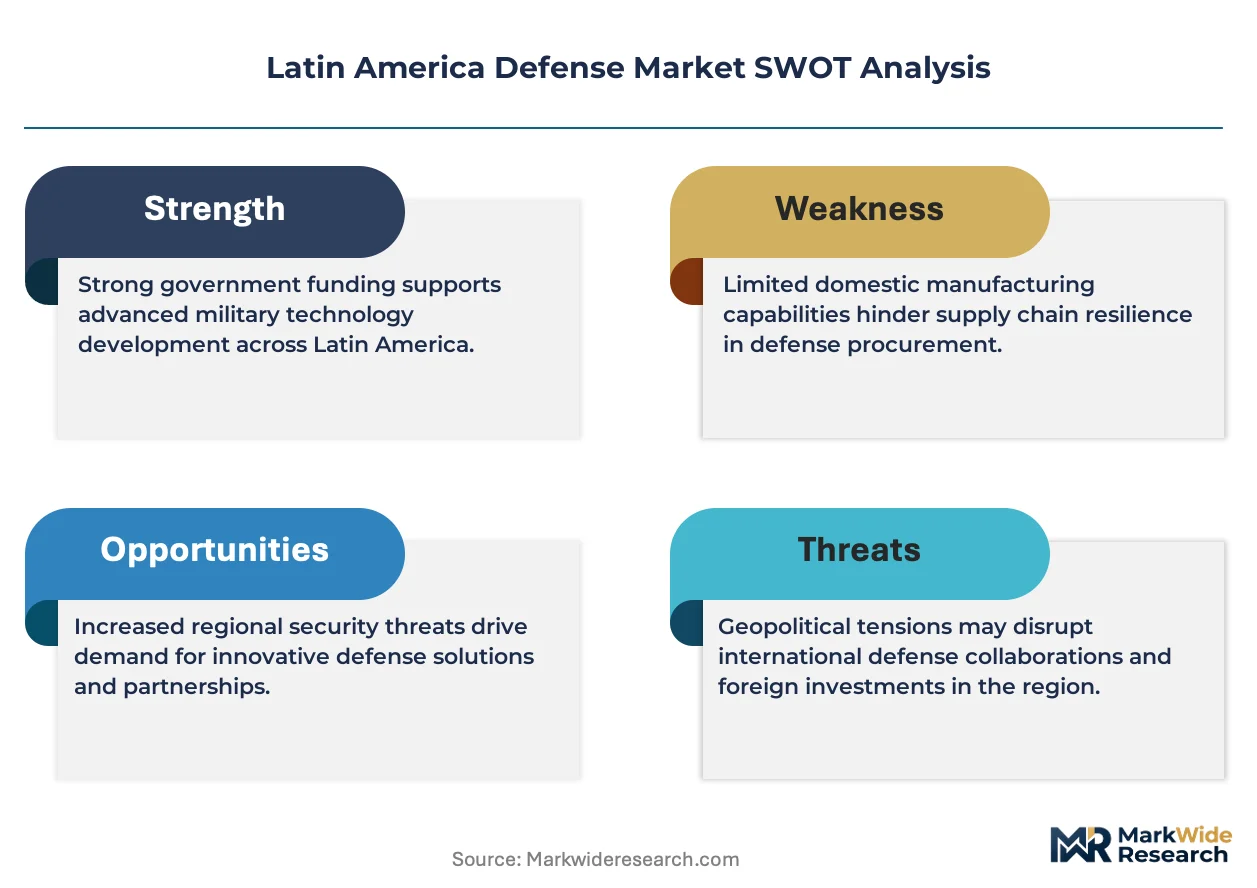
Technology transfer mandates embedded in Brazilian offset agreements are restructuring how foreign OEMs establish local production capacity, forcing permanent facility investments rather than temporary assembly arrangements.
Growth Catalysts
- Offshore Resource Protection Mandates:Brazil's expanded maritime policing jurisdiction around pre-salt oil fields drives patrol vessel procurement. Chilean and Colombian navies mirror this priority.
- EU Green Deal Extraterritoriality:Carbon accounting provisions now condition European defense platform bids, accelerating hybrid-electric propulsion adoption in regional naval modernization programs.
- Illicit Network Disruption Requirements:Andean governments prioritize ISR aircraft for counter-narcotics operations, creating sustained demand for persistent surveillance capabilities.
Market Restraints
- Foreign Exchange Volatility:Local currency depreciation against the dollar and euro compresses procurement budgets, forcing multi-year payment restructuring in Brazilian and Argentine contracts.
- Single-Source Engine Dependencies:Regional fighter and transport programs rely on concentrated US and European propulsion suppliers, exposing programs to export control delays.
- Technical Workforce Gaps:Sustained emigration of aerospace engineers to North American and European markets constrains Embraer's defense division expansion timelines.
Strategic Opportunities
- Amazon Basin Surveillance Integration:Underpenetrated border monitoring infrastructure across Brazil, Colombia, and Peru creates demand for fused ground-radar and satellite systems.
- Cyber Command Infrastructure Hardening:Military digital transformation programs in Santiago and Brasília outpace installed cybersecurity capacity, opening managed security services contracts.
- Local Content Threshold Escalation:Pacific Alliance procurement codes are tightening domestic assembly requirements, rewarding early facility investments by foreign primes.
Industry Challenges
- ANVISA Medical Equipment Certification:Military biosecurity and field hospital systems face extended approval timelines that misalign with urgent procurement schedules.
- Interoperability with Legacy Platforms:Colombian and Chilean forces operate mixed US and European equipment generations, complicating network-centric warfare integration.
- Offset Compliance Verification:CVM transparency requirements demand auditable local employment and technology transfer documentation that many foreign suppliers struggle to provision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Defense Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft, Ground Vehicles, Naval Systems, Ammunition Technology: Cybersecurity Solutions, Surveillance Systems, Communication Equipment, Weapon Systems End User: Defense Forces, Government Agencies, Private Contractors, Research Institutions Solution: Logistics Support, Training Services, Maintenance Services, Integration Services |
| Companies Covered | Saab AB, Northrop Grumman Corporation, Embraer S.A., COTECMAR, Thales Group, Lockheed Martin Corporation, Airbus SE, INDUMIL, Avibras Indústria Aeroespacial S.A., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Defense Market Shifts & Advancements
Artificial intelligence integration into command-and-control architectures is compressing sensor-to-shooter timelines across Latin American air and naval forces, while local manufacturing requirements reshape supplier facility strategies.
Unmanned aerial systems are converging with maritime patrol operations as Brazilian and Colombian navies deploy long-endurance drones for exclusive economic zone monitoring. Coastal commands in both nations now prioritize platforms with automatic identification system integration and synthetic aperture radar. This convergence is displacing manned maritime patrol aircraft in secondary surveillance roles while preserving crewed platforms for armed interdiction.
ANVISA and analogous health regulators across Mercosur are extending medical device traceability requirements into military field hospital equipment, forcing suppliers to retrofit supply chain documentation systems. Equipment vendors must now provision lot-level tracking for trauma kits and portable diagnostic units. Brazilian Army medical service procurement has become the most affected segment, with bidders restructuring quality management systems to satisfy dual-use compliance.
After-sales service unbundling is fragmenting traditional platform-plus-support contracts as Chilean and Peruvian defense ministries separate hardware acquisition from maintenance provision. Third-party technical service providers now compete for depot-level overhaul work previously captured by OEMs. This pattern is most visible in F-16 upgrade programs across Andean air forces, where national maintenance organizations assume increasing component repair responsibility.
Latin America Defense Market Segmentation
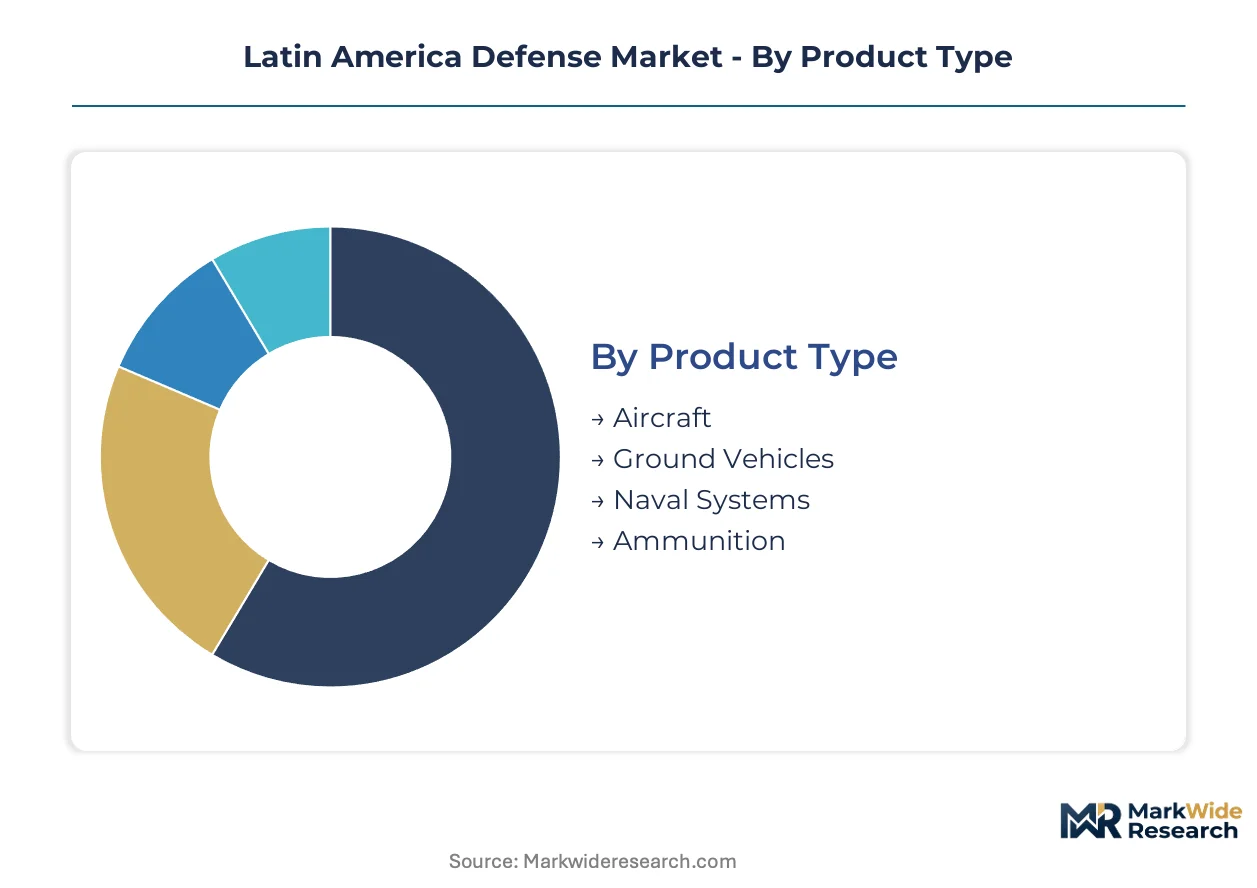
Defense procurement across Latin America fragments along operational domain and capability maturity, with platform choices driven by terrain specificity and threat vector evolution. Segment boundaries blur where dual-use technologies migrate from military to internal security applications.
Product Type:
Aircraft procurement concentrates manufacturing partnerships with Embraer in São Paulo state, while naval systems attract European shipyard alliances for offshore patrol vessel construction.
- Aircraft:Multirole fighters and tactical transport platforms dominate absolute spending, with Brazilian F-39 Gripen assembly anchoring regional production capacity. Colombian and Chilean air forces prioritize ISR aircraft replacement for Andean counter-narcotics corridors.
- Naval Systems:Patrol vessels and frigate modernization programs accelerate fastest, driven by Brazil's pre-salt oil field protection mandates and Chilean EEZ enforcement requirements. Hybrid-electric propulsion adoption responds to EU Green Deal carbon accounting conditions.
- Ground Vehicles:Armored personnel carriers and tactical mobility platforms serve Amazon basin border operations and urban security contingencies.
- Ammunition:Small-caliber and precision-guided munitions sustain operational readiness across mixed US and European legacy inventories.
Aircraft absorbs the bulk of installed capacity; naval systems is expanding most quickly.
Technology:
Capability gaps in military digital infrastructure create procurement priority tiers, with command hardening preceding sensor network deployment.
- Cybersecurity Solutions:Military command infrastructure hardening outpaces installed capacity in Brasília and Santiago, opening managed security services contracts for network defense and electronic warfare protection.
- Surveillance Systems:Ground radar and satellite fusion architectures address underpenetrated Amazon basin monitoring requirements across Brazil, Colombia, and Peru.
- Communication Equipment:Secure tactical networks bridge interoperability gaps between US and European legacy platforms in Colombian and Chilean forces.
- Weapon Systems:Precision strike and area denial capabilities modernize deterrent posture against non-state actor threats.
Cybersecurity Solutions commands premium procurement attention; Surveillance Systems climbs the fastest as border infrastructure gaps close.
End User:
Contracting authority fragmentation shapes vendor engagement models, with defense ministries retaining platform acquisition while internal security agencies expand service procurement.
- Defense Forces:Brazilian, Colombian, and Chilean armed forces concentrate multi-year platform procurement with technology transfer mandates embedded in offset agreements.
- Government Agencies:National police and coast guard organizations absorb ISR and patrol capabilities for illicit network disruption without full military command integration.
- Private Contractors:Third-party technical service providers capture depot-level overhaul work unbundled from OEM platform contracts in Peruvian and Chilean maintenance programs.
- Research Institutions:Defense technology development partnerships with universities support local content threshold compliance in Pacific Alliance procurement codes.
Defense Forces retains platform acquisition dominance; Government Agencies gains share fastest as internal security missions expand.
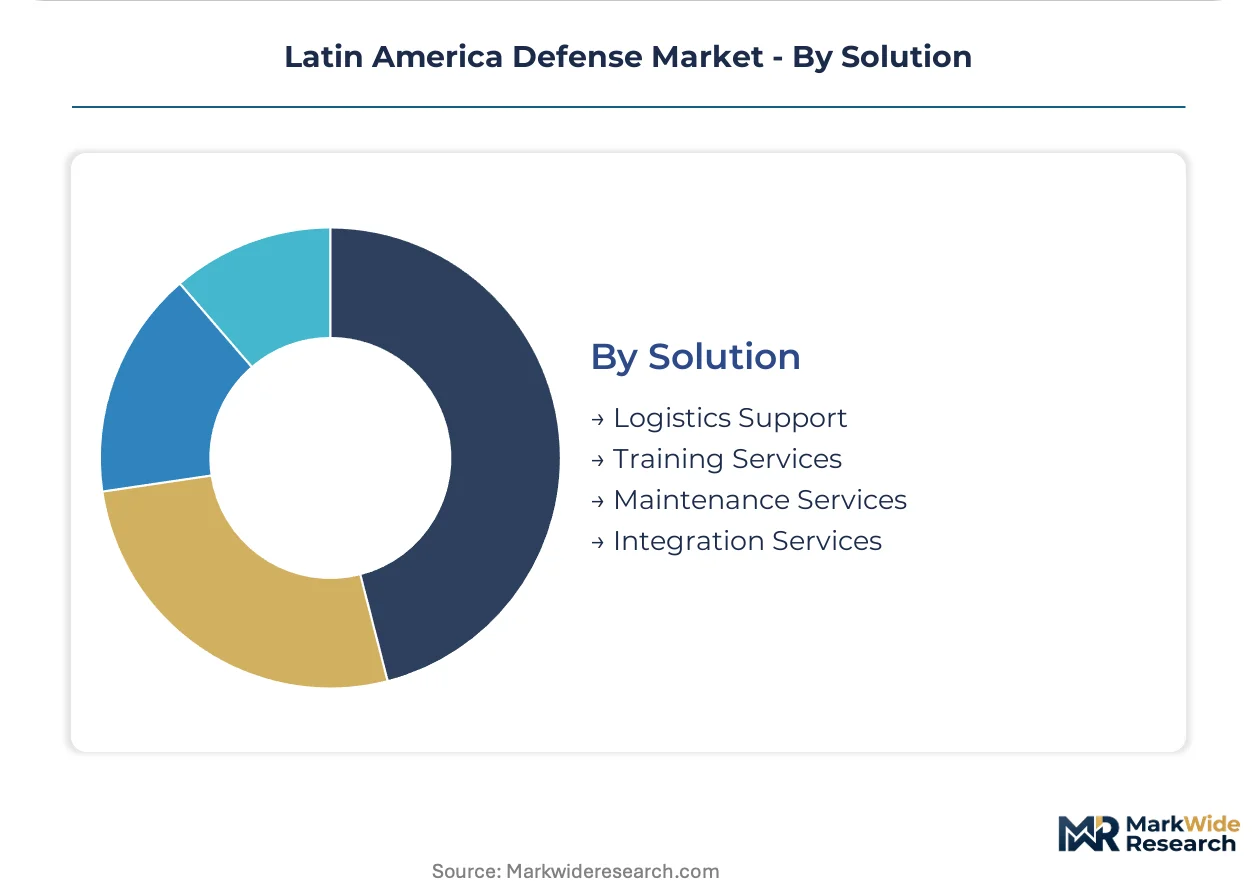
Solution:
Service unbundling restructures vendor revenue streams, with national maintenance organizations assuming component repair responsibility previously captured by foreign primes.
- Maintenance Services:After-sales support fragmentation accelerates as Chilean and Peruvian ministries separate hardware acquisition from depot-level overhaul, enabling national technical organizations to compete for component repair work.
- Training Services:Crew qualification and simulator-based instruction localize as Embraer defense division expands tactical transport and ISR platform expertise.
- Logistics Support:Supply chain and field deployment services sustain operational readiness across remote Amazon and Andean operating environments.
- Integration Services:Network-centric warfare architecture installation addresses mixed US-European equipment generation interoperability challenges in Colombian forces.
Maintenance Services captures the largest service contract volume; Training Services shows steepest expansion trajectory as local capability requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pre-salt oil reserves off Brazil's southeastern coast anchor regional maritime security investment. Defense procurement concentrates in Atlantic-facing states where offshore patrol infrastructure protects hydrocarbon extraction zones. Technology transfer mandates reshape foreign contractor facility placement across Mercosur and Pacific Alliance jurisdictions.
Brazil
The Brazilian Navy accelerates patrol vessel acquisition to secure pre-salt oil fields beyond the continental shelf. ANVISA medical equipment certification requirements extend into military field hospital procurement, delaying trauma kit deployments. São Paulo state's aerospace corridor hosts Embraer's defense division expansion into tactical transport platforms.
Colombia
Andean counter-narcotics operations drive persistent ISR aircraft demand across mountainous border zones. The national contracting oversight framework mandates auditable local employment documentation for foreign defense primes. Bogotá's maintenance organizations capture depot-level overhaul work unbundled from OEM platform contracts.
Chile
Exclusive economic zone enforcement requirements accelerate frigate modernization and hybrid-electric propulsion adoption. EU Green Deal carbon accounting provisions condition European-origin naval platform bids. Santiago's cyber command infrastructure hardening programs outpace installed cybersecurity capacity.
Peru
Amazon basin surveillance integration creates demand for fused ground-radar and satellite systems along Brazilian and Colombian borders. Pacific Alliance procurement codes tighten domestic assembly requirements for foreign contractors. Lima's naval shipyard partnerships with European builders concentrate on offshore patrol vessel construction.
Mexico
Coastal security mandates expand maritime patrol capabilities against illicit trafficking networks in the Gulf and Pacific approaches. The Secretariat of National Defense procurement framework emphasizes local content thresholds for foreign equipment bids. Baja California's aerospace suppliers position for defense subcontracting opportunities.
Latin America Defense Market Competitive Landscape
Global majors compete with regional champions across technology transfer and local production capacity. The market structure tiers between full-system integrators and component specialists, with foreign primes forced into permanent facility investments rather than temporary assembly arrangements. Two strategic archetypes dominate: European naval-systems providers leveraging shipyard partnerships, and aerospace manufacturers anchoring fighter and transport production through Embraer alliances. Competitive moves concentrate on strategic partnerships for local assembly rights and portfolio diversification into cybersecurity services.
Within the regional production tier, Embraer S.A. and Saab AB exemplify the technology-transfer archetype through their São Paulo-based Gripen E partnership. Thales Group occupies a position among European naval-systems providers, while Lockheed Martin Corporation represents the legacy-platform upgrade segment serving Andean air forces.
| Leading Market Players |
|---|
| Saab AB |
| Northrop Grumman Corporation |
| Embraer S.A. |
| COTECMAR |
| Thales Group |
| Lockheed Martin Corporation |
| Airbus SE |
| INDUMIL |
| Avibras Indústria Aeroespacial S.A. |
| Others |
Supply & Pricing Matrix
Aerospace engineering talent concentration in São Paulo state's industrial corridor feeds labor-cost differentials that widen pricing-tier spreads between technology-transfer platforms and direct-import alternatives. Brazilian offset mandates requiring permanent facility investments rather than temporary assembly arrangements compress margins for foreign primes while elevating local-content premiums.
Pricing Analysis
Warranty and depot-level maintenance unbundling from platform acquisition contracts is fragmenting traditional bundled pricing structures across Chilean and Peruvian defense ministries. Three-tier pricing structure across premium, standard, and economy levels separates full technology-transfer partnerships from limited assembly arrangements and direct equipment imports. Price differentiation hinges on local employment documentation intensity and ANVISA certification compliance scope. Cost compression in economy-tier direct imports is intensifying because foreign exchange volatility forces multi-year payment restructuring. National maintenance organizations exhibit highest price sensitivity due to budget fragmentation, while defense ministries with technology-transfer mandates show lowest sensitivity to upfront premiums.
Supply Chain Analysis
Propulsion system supply rests on concentrated US and European specialty engine producers, creating single-source vulnerability exposure for regional fighter and transport programs. Component sourcing draws from Germany, France, and the United States for naval combat management systems, avionics suites, and precision munitions guidance packages. Raw material dependencies span titanium alloys for airframes, gallium arsenide for radar components, and specialized marine-grade steel alloys for patrol hull construction. Tariff exposure runs through EU-origin equipment bids conditioned by extraterritorial carbon accounting provisions. Distribution runs through São Paulo-based Embraer defense division assembly lines and European shipyard partnerships with COTECMAR in Cartagena.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical workforce emigration to North American markets constrains production capacity expansion, propping pricing power for qualified engineering services and sustaining premium tiers for technology-transfer partnerships.
For Market Incumbents: Anchor defensive positioning through permanent facility investments in São Paulo state that satisfy CVM transparency requirements for auditable local employment documentation. Deepen backward integration into tactical transport subsystems to offset single-source engine dependencies threatening program timelines. Counter third-party technical service provider encroachment by unbundling maintenance contracts selectively to retain high-margin component repair work. For New Entrants and Emerging Players: Launch via managed security services contracts targeting Santiago and Brasília cyber command infrastructure hardening programs that outpace installed capacity. Exploit white-space in Amazon basin surveillance integration across Brazilian, Colombian, and Peruvian border zones where ground-radar and satellite fusion architectures remain underpenetrated. Prioritize Pacific Alliance procurement code compliance through early domestic assembly facility commitments that precede threshold escalations. For Investors and Strategic Acquirers: The window for entry favors component specialists with ANVISA-certification capabilities and established European naval-systems shipyard partnerships. Long-term viability centers on acquisition targets possessing dual-use medical equipment traceability systems that satisfy Mercosur health regulator extensions into military field hospital procurement. Monitor EU Green Deal carbon accounting provision adoption rates across Chilean and Brazilian naval modernization bids as inflection indicator for hybrid-electric propulsion demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Transfer Partnership | Saab AB's São Paulo Gripen E assembly anchors regional fighter production capacity with permanent Embraer facility investment. |
| Cybersecurity Capability Buildout | Military command infrastructure hardening in Santiago and Brasília outpaces installed capacity, opening managed security services contracts. |
| Local Content Threshold Compliance | Pacific Alliance procurement code escalation rewards early foreign prime facility investments with domestic assembly requirements. |
| After-Sales Service Unbundling | Chilean and Peruvian ministries separate hardware acquisition from depot-level overhaul, fragmenting traditional platform-plus-support contracts. |
| Hybrid-Electric Propulsion Adoption | EU Green Deal carbon accounting provisions condition European-origin naval platform bids, accelerating green technology integration. |
Research Methodology
Document review covered defense ministry procurement disclosures, ANVISA medical equipment certification filings, and Pacific Alliance trade frameworks, complemented by interviews with aerospace engineering directors, naval systems procurement officers, Embraer defense division executives, and CVM compliance specialists. Secondary validation drew from customs import records, SEC 10-K filings of listed defense contractors, and EU Green Deal implementation guidance documents. Bottom-up platform delivery schedules and top-down national budget appropriations were triangulated to establish market sizing.
Installed base projections across the analysis window reflect segment-level modeling of aircraft, naval systems, ground vehicles, and ammunition procurement trajectories. Segmentation dimensions incorporated operational domain specificity, technology maturity tiers, and end-user contracting authority fragmentation between defense ministries and internal security agencies. CAGRs were derived from weighted average of historical delivery patterns and announced modernization program timelines. Forecast inputs included pre-salt oil field protection mandate acceleration rates and Andean counter-narcotics ISR replacement cycles.
Foreign exchange volatility, export control delay cascades from concentrated propulsion suppliers, and technical workforce emigration acceleration are the dominant revision risks to installed base projections. Forecasts reflect documented assumptions regarding technology transfer mandate continuity and Pacific Alliance procurement code stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Europe Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Naval Ship Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Global CBRN Defense Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Used Serviceable Material (USM) Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Soft Wall Military Shelter Market
Military Equipment and Infrastructure
Asia-Pacific Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
Land Digital Battlefield Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Global Stealth Warfare Market
Military Equipment and Infrastructure
NATO Defense Market
Military Equipment and Infrastructure
Global Soldier Modernization Market
Military Equipment and Infrastructure
Rubber Tracks for Defense and Security Market
Military Equipment and Infrastructure
CBRN Protection Equipment Market