
 Japan Satellite Communication Market | 2026-2036
Japan Satellite Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Satellite Communication Market Insights
High-throughput specification upgrades is bifurcating procurement patterns across defense and commercial fleets. NEC Space Technologies Ltd leverages its heritage in government satellite systems to anchor premium contract flows. Mitsubishi Electric sustains manufacturing scale across geostationary and low-earth platforms. SKY Perfect JSAT Corporation dominates broadcast distribution while competing for maritime mobility contracts.
Satellite communication encompasses radio-frequency transmission between ground stations and orbiting spacecraft, typically operating in Ku-band, Ka-band, or X-band frequencies with throughput thresholds exceeding 100 Mbps per transponder. These systems enable continuous connectivity for vessels, aircraft, and remote installations beyond terrestrial infrastructure reach. Broadband service type captures the dominant revenue pool as enterprise and maritime subscribers migrate from legacy Ku-band to Ka-band high-throughput services. LEO technology segments are expanding fastest among technology categories, though GEO platforms retain margin concentration in broadcast and military applications. Government end-user channels absorb the largest procurement volume, with research institutions representing an emerging demand node for earth observation downlink services.
METI spectrum allocation directives and Japan's Space Activity Law shape operator licensing timelines and domestic manufacturing requirements. The country's national space policy mandates indigenous satellite production for classified government payloads, tightening market access for non-domestic system integrators. JIS standards and ITU coordination protocols govern terminal certification and orbital slot registration, adding compliance layers for new entrants. Stakeholders must weigh METI's push for commercial space utilization against procurement inertia in defense channels when allocating R&D and production capacity.
Market Dynamics
High-throughput Ka-band migration is fragmenting procurement patterns across Japan's defense and maritime verticals, forcing terminal manufacturers to recalibrate production lines for dual-frequency compatibility while METI spectrum directives accelerate domestic LEO constellation deployment timelines.
Growth Catalysts
- Maritime Fleet Connectivity Mandates:International Maritime Organization safety regulations now require continuous broadband links for vessel tracking and crew welfare, pulling Japanese shipping operators into long-term service contracts.
- METI Commercial Space Utilization Framework:METI's policy push for private-sector LEO participation is unlocking venture capital flows into domestic small-satellite manufacturing clusters.
- Ka-band Throughput Thresholds:Transponder capacities exceeding 100 Mbps per channel are displacing legacy Ku-band installations across enterprise and government ground stations.
Market Restraints
- Indigenous Manufacturing Mandates:Japan's Space Activity Law requires classified government payloads to use domestically produced satellites, constraining procurement options for defense integrators.
- Orbital Slot Scarcity:ITU coordination protocols for geostationary registration create multi-year licensing delays for new GEO entrants.
- Ground Segment Capital Intensity:High-throughput terminal certification under JIS standards demands specialized test facilities that concentrate among legacy electronics manufacturers.
Strategic Opportunities
- Earth Observation Downlink Services:Research institutions in Hokkaido and Tsukuba are emerging as demand nodes for low-latency data relay from remote-sensing constellations.
- Aviation In-flight Connectivity:Japan Airlines and ANA fleet retrofit programs are creating service contract white space for regional satellite operators.
- Dual-use Technology Convergence:Civilian LEO broadband platforms are converging with military resilient communications architectures, opening cross-funded R&D channels.
Industry Challenges
- RF Engineering Talent Scarcity:Ka-band phased-array antenna design expertise concentrates among a shrinking cohort of defense-sector veterans approaching retirement.
- Legacy System Integration Friction:Government ground stations running 1990s-era Ku-band infrastructure face complex retrofit requirements for multi-orbit interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Satellite Communication Market |
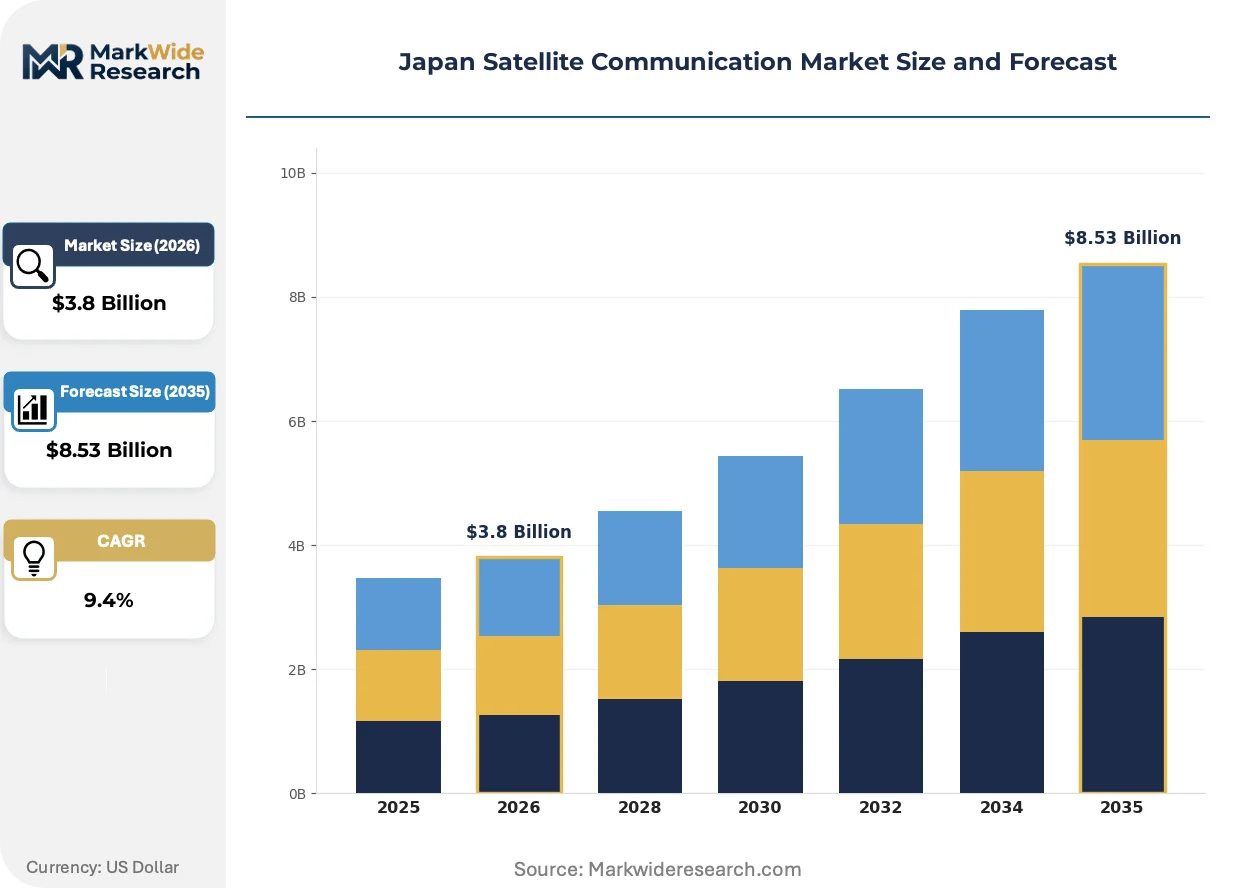
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadband, Broadcasting, Telemetry, Emergency Services End User: Government, Commercial, Military, Research Institutions Technology: LEO, MEO, GEO, HTS Application: Aerospace, Maritime, Education, Disaster Management |
| Companies Covered | NEC Space Technologies Ltd, Furuno Electric Co Ltd, SKY Perfect JSAT Corporation, KYOCERA Corporation, New Japan Radio Co Ltd, Mitsubishi Electric, Axelspace Corporation, Infostellar Inc, Broadcasting Satellite System Corporation (B-Sat), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Satellite Communication Market Trends and Innovations
Software-defined payload architectures are enabling rapid frequency reconfiguration without hardware replacement, compressing satellite upgrade cycles from decade-long timelines to 18-month software iterations across Japanese operator fleets.
Optical inter-satellite links using laser communication terminals are fragmenting traditional RF relay architectures. Maritime operators in the Pacific corridor are piloting these systems for low-latency vessel-to-shore data transfer. The technology is compressing ground station dependency and shifting margin pools toward space-segment manufacturers with in-house laser terminal capabilities.
METI's spectrum reallocation directives for Q/V-band experimental licenses are forcing terminal manufacturers to expand test matrices. Defense procurement channels are absorbing the compliance burden fastest, embedding JIS certification requirements into source-selection criteria. Commercial operators lag by approximately two certification cycles, creating a bifurcated equipment supply base.
Service unbundling is separating bandwidth provision from managed network operations. Maritime shipping lines in Yokohama and Kobe are contracting directly with satellite operators for raw capacity while outsourcing ground network management to specialized IT integrators. This pattern is most visible among mid-size container operators seeking cost transparency without building in-house space-segment expertise.
Japan Satellite Communication Market Segmentation
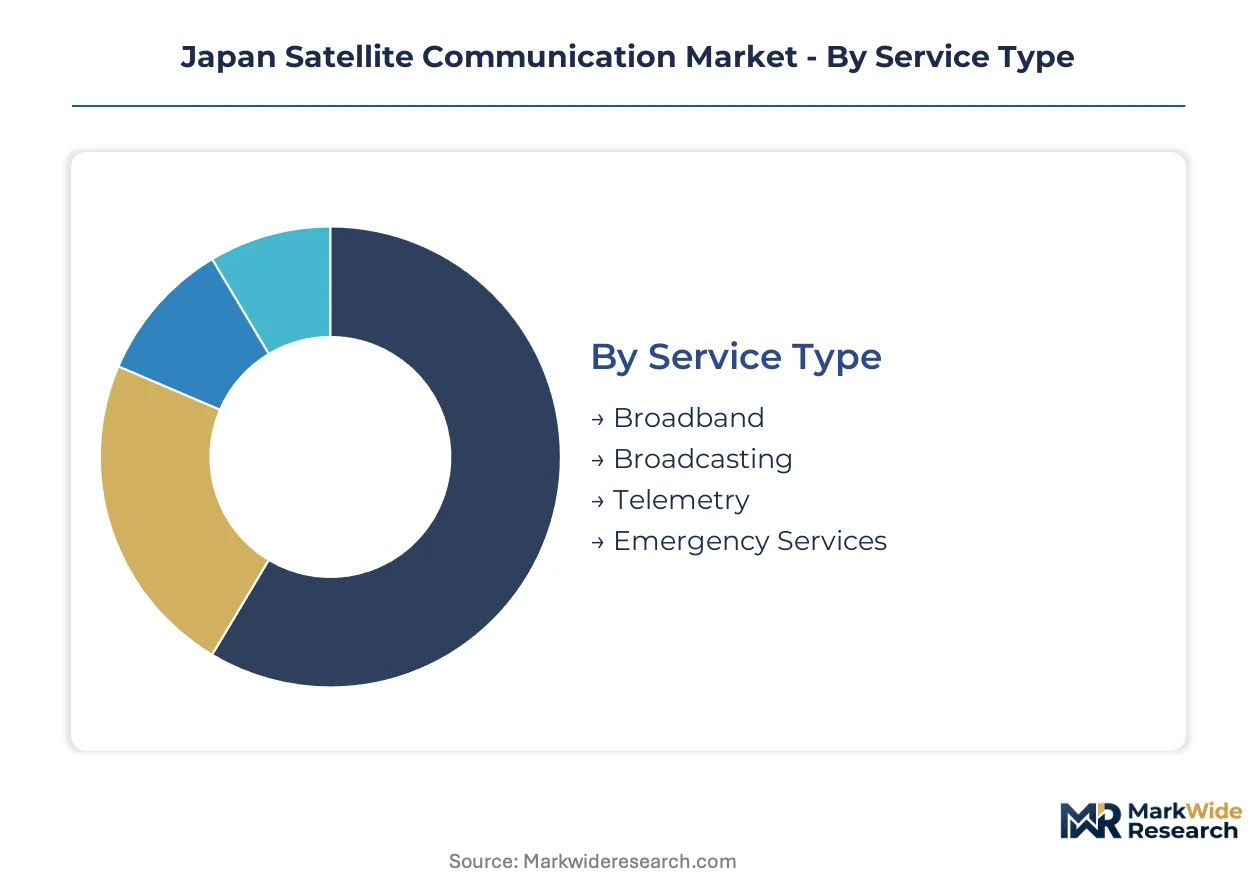
Japan's satellite communication market segments reflect divergent procurement logics across defense, commercial shipping, and research verticals. Each dimension carries distinct regulatory overlays from METI and the Space Activity Law that constrain substitution pathways and shape vendor access.
Service Type:
Broadband services face intensifying substitution pressure from terrestrial fiber and 5G backhaul in coastal zones, while Broadcasting retains defensive positioning through content licensing moats.
- Broadband:Ka-band high-throughput links exceeding 100 Mbps per transponder dominate maritime fleet contracts and enterprise ground stations. Japanese shipping operators in Yokohama and Kobe are migrating from legacy Ku-band installations under International Maritime Organization safety mandates. Defense procurement channels absorb premium capacity for resilient command networks.
- Broadcasting:SKY Perfect JSAT Corporation anchors distribution infrastructure for domestic content distribution. Spectrum allocation from METI and content licensing frameworks create regulatory barriers to terrestrial substitution despite streaming platform encroachment.
- Telemetry:Spacecraft tracking and data relay services support domestic launch operations and satellite health monitoring.
- Emergency Services:Disaster response communications activate during seismic events when terrestrial infrastructure fails.
Broadband retains volume leadership; Emergency Services holds the steepest expansion curve as climate resilience budgets expand.
End User:
Cost tier stratification separates classified defense budgets from commercial procurement governed by JIS certification requirements and METI utilization frameworks.
- Government:Classified payloads under Japan's Space Activity Law mandate indigenous satellite production, tightening vendor pools to NEC Space Technologies and Mitsubishi Electric. Procurement concentrates in geostationary platforms for sovereign communications.
- Military:Dual-use LEO broadband architectures converge with civilian resilient communications specifications. Ka-band terminal certification under JIS standards absorbs disproportionate R&D allocation from defense integrators.
- Commercial:Maritime shipping lines and enterprise networks drive service unbundling trends separating raw bandwidth from managed operations.
- Research Institutions:Hokkaido and Tsukuba facilities emerge as demand nodes for earth observation downlink services requiring low-latency data relay.
Government channels dominate procurement volume; Research Institutions are climbing the fastest as remote-sensing constellation deployments accelerate.
Technology:
Orbital altitude correlates directly with capital intensity and margin structure, with LEO platforms fragmenting traditional geostationary procurement patterns.
- LEO:Low-earth constellations deliver sub-50ms latency for maritime mobility and aviation connectivity. METI's commercial space utilization framework is unlocking venture capital flows into domestic small-satellite manufacturing clusters in Tokyo and Fukuoka.
- GEO:Geostationary platforms retain margin concentration in broadcast distribution and military applications. ITU coordination protocols for orbital slot registration create multi-year licensing delays that protect incumbent operator positions.
- MEO:Medium-earth orbit systems occupy intermediate latency and coverage trade-offs.
- HTS:High-throughput satellite architectures enable frequency reconfiguration through software-defined payloads without hardware replacement.
GEO platforms retain volume leadership; LEO systems are gaining share fastest among technology categories.
Application:
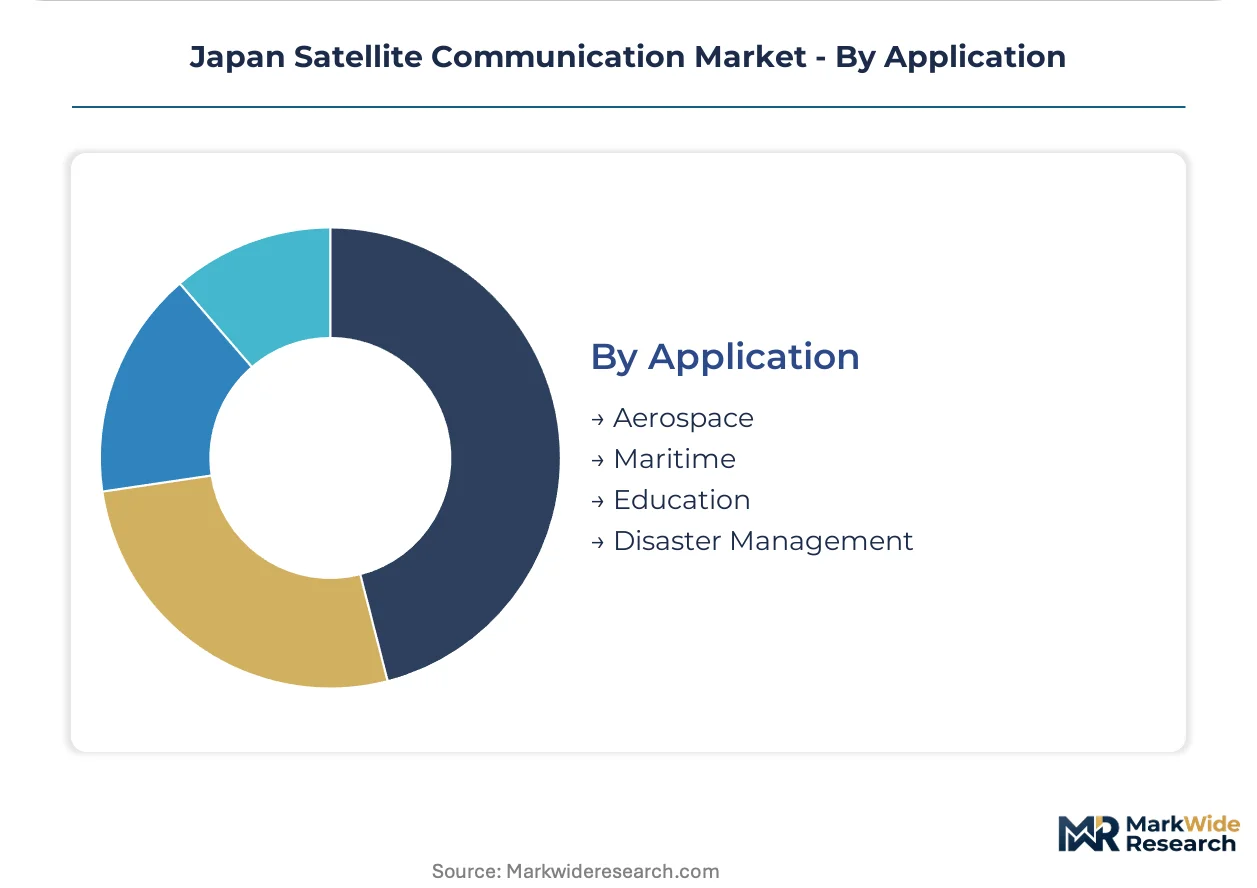
Geographic dispersion of demand nodes across Japan's archipelago creates divergent infrastructure requirements from dense urban corridors to remote island chains.
- Maritime:Pacific corridor shipping routes drive continuous broadband demand for vessel tracking and crew welfare. Japanese container operators are contracting directly with satellite operators for raw capacity while outsourcing ground network management.
- Aerospace:Japan Airlines and ANA fleet retrofit programs are creating service contract white space for regional operators seeking in-flight connectivity market entry.
- Disaster Management:Seismic and typhoon response protocols mandate satellite backup for terrestrial network failures.
- Education:Remote island schools and rural prefectures rely on satellite links where fiber deployment remains uneconomical.
Maritime applications retain volume leadership; Aerospace holds the steepest expansion trajectory as aviation retrofit cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for satellite systems concentrates among defense-heritage electronics conglomerates in Japan's major industrial corridors. METI's commercial space utilization framework is redistributing venture capital toward emerging clusters in secondary cities.
Kanto/Tokyo
Defense procurement channels and broadcast distribution networks anchor demand in the capital region. METI spectrum allocation directives govern operator licensing timelines for metropolitan earth stations. The Tsukuba aerospace cluster hosts research institutions demanding low-latency earth observation downlink services.
Kansai/Osaka
Maritime shipping operators in Kobe and Osaka Bay drive fleet connectivity contract volumes under International Maritime Organization safety mandates. JIS terminal certification requirements concentrate specialized test facilities among legacy electronics manufacturers. The Osaka manufacturing belt supplies Ka-band phased-array components for dual-use applications.
Chubu/Nagoya
Industrial machinery exporters in Aichi Prefecture generate enterprise ground station demand for resilient supply chain communications. The national space policy's indigenous manufacturing mandates favor domestic system integrators in this corridor. Nagoya's precision electronics sector feeds component supply for software-defined payload architectures.
Kyushu
Tanegashima Space Center operations sustain telemetry and spacecraft tracking service demand. METI directives for commercial LEO participation are unlocking small-satellite manufacturing investment in Fukuoka. The island's geographic isolation positions it as a disaster management communications backup node.
Hokkaido
Research institutions in Sapporo and surrounding districts emerge as demand nodes for remote-sensing data relay. The prefecture's sparse terrestrial infrastructure sustains satellite-dependent connectivity for rural education networks. Hokkaido's northern latitude offers favorable orbital access geometry for polar-orbiting constellation ground segments.
Japan Satellite Communication Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Japan's satellite communication market. Defense-heritage conglomerates retain premium positioning in classified government procurement channels. Emerging venture-backed specialists capture commercial LEO constellation opportunities. Dominant competitive moves include strategic partnerships for ground segment integration and capacity expansion in software-defined payload manufacturing.
Among defense-heritage system integrators, NEC Space Technologies Ltd and Mitsubishi Electric exemplify the premium-tier archetype anchored in government satellite production. SKY Perfect JSAT Corporation occupies a distinct position bridging broadcast distribution infrastructure with maritime mobility service expansion. These three entities represent the structural segmentation between classified procurement channels and commercial service markets.
| Leading Market Players |
|---|
| NEC Space Technologies Ltd |
| Furuno Electric Co Ltd |
| SKY Perfect JSAT Corporation |
| KYOCERA Corporation |
| New Japan Radio Co Ltd |
| Mitsubishi Electric |
| Axelspace Corporation |
| Infostellar Inc |
| Broadcasting Satellite System Corporation (B-Sat) |
| Others |
Pricing and Supply Chain Analysis
Ka-band transponder migration displacing legacy Ku-band infrastructure is simultaneously concentrating procurement leverage among defense-heritage manufacturers and compressing terminal price premiums across commercial maritime channels. METI spectrum reallocation directives amplify this shift by mandating JIS certification investments that stratify equipment supply tiers.
Pricing Analysis
METI's Space Activity Law dictates the pricing tier structure across Japan's satellite communication procurement channels. Three-tier pricing separates classified government payloads from dual-use commercial applications and raw bandwidth spot markets. Price differentiation centers on JIS certification grade and indigenous manufacturing compliance, with defense integrators absorbing premium tiers while maritime operators face cost compression from service unbundling trends. Pricing pressure stems from terrestrial 5G backhaul substitution in coastal zones, rendering commercial satellite bandwidth increasingly price-sensitive among enterprise ground station buyers.
Supply Chain Analysis
Japan and the United States anchor satellite system manufacturing, with domestic production mandated for classified government payloads under national space policy. Component supply draws from Taiwan for semiconductor fabrication and South Korea for memory and RF subsystems. Single-source vulnerability concentrates in Ka-band phased-array antenna modules where defense-sector engineering expertise pools among retiring cohorts. Distribution runs through defense procurement channels for sovereign payloads and direct operator contracts for commercial maritime and aviation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terrestrial fiber and 5G backhaul expansion in coastal Japan presents the central substitution threat that satellite incumbents must navigate through service differentiation and latency-sensitive application capture.
For Market Incumbents: Consolidate manufacturing scale in software-defined payload architectures to defend margin position against emerging LEO constellation entrants. Deepen backward integration into laser terminal production as optical inter-satellite links fragment traditional RF relay margins. Prioritize JIS certification maintenance as METI Q/V-band directives tighten compliance barriers. For New Entrants and Emerging Players: Aviation in-flight connectivity service gaps where ANA and Japan Airlines retrofit programs outpace incumbent capacity allocation offer the most penetrable white space. Earth observation downlink services for Hokkaido and Tsukuba research institutions provide a secondary entry vector. Position through managed network operations outsourcing rather than raw bandwidth provision to bypass capital-intensive space-segment requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed small-satellite manufacturers in Tokyo and Fukuoka clusters facing Series C funding cliffs. Long-term viability hinges on dual-use technology convergence enabling cross-funded R&D across civilian and defense channels. Monitor METI commercial space utilization framework implementation velocity as the primary inflection signal for domestic LEO constellation deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Payload Investment | Enables 18-month upgrade cycles versus decade-long hardware replacement timelines for Japanese operators. |
| Laser Terminal Manufacturing Scale-Up | Captures margin migration from ground stations to space-segment manufacturers with in-house optical capabilities. |
| Dual-Use Certification Pathway | Opens defense procurement channels to civilian LEO platforms under converging resilient communications architectures. |
| Maritime Service Unbundling Partnership | Separates raw bandwidth sales from managed operations to capture cost-transparent container operator contracts. |
| Regional Ground Station Expansion | Positions Hokkaido and Kyushu facilities for polar-orbiting constellation access and disaster backup demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with satellite procurement officers at Japanese shipping lines, defense system integrators, METI policy officials, and ground station engineering leads. Secondary validation incorporated JAXA technical documentation, ITU orbital registration filings, METI spectrum allocation directives, and customs data on satellite component trade flows. Bottom-up demand modeling across maritime, aviation, and government verticals was triangulated against top-down market sizing from operator capacity disclosures.
Across the analysis window, forecasts employed segmented growth accounting across service type, end user, technology, and application dimensions with particular weighting for Ka-band migration velocity and LEO constellation deployment schedules. CAGRs were derived from installed base replacement cycles, procurement pipeline visibility, and spectrum utilization efficiency trajectories. Industry-specific inputs included International Maritime Organization safety mandate implementation timelines and METI commercial space utilization policy progression.
Material uncertainties — defense budget reallocation, terrestrial 5G substitution acceleration, and orbital slot coordination delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory continuity and indigenous manufacturing mandate persistence. Recalibration cycles align with material shifts in METI policy directives and ITU spectrum reallocation outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Satellite Manufacturing and Launch Systems Market
Satellite
Satellite Data Analytics Services Market
Satellite
France Satellite Imagery Services Market
Satellite
US Remote Sensing Technology Market
Satellite
LEO Satellite System Market
Satellite
US Satellite Connectivity Market
Satellite
LEO Satellite Constellation Market
Satellite
UK Satellite Imagery Services Market
Satellite
Satellite Compass Market
Satellite
Satellite Communications Service Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
China Satellite Imagery Services Market
Satellite
India Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Africa Satellite Connectivity Market
Satellite
North America Remote Sensing Services Market