
 Latin America RFID Tags Market | 2026-2036
Latin America RFID Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America RFID Tags Market Foresight
Multi-source procurement among Latin American distributors is broadening as buyers reduce dependency on single-origin chip supply. Zebra Technologies leverages its regional service infrastructure to anchor enterprise accounts across Mexico and Colombia. Honeywell International Inc. competes through ruggedized hardware lines suited for mining and port logistics. Impinj Inc. specializes in RAIN RFID chipsets that sustain margin pools in high-volume apparel tagging programs.
Latin America RFID tags are data-carrying transponders composed of a microchip bonded to an antenna substrate, typically operating in the 860–960 MHz UHF band for passive variants, designed to store and transmit identification data via radio waves without line-of-sight requirements. Passive tags dominate unit volumes due to sub-dollar unit economics and absence of battery maintenance, while active tags command premium positioning in cold-chain pharmaceutical monitoring where real-time location telemetry justifies higher lifecycle cost. Near Field Communication tags are gaining traction in Brazil's contactless payment infrastructure, though Ultra High Frequency remains the structural revenue backbone across supply chain and asset tracking deployments.
ANATEL in Brazil and IFT in Mexico enforce spectrum allocation and electromagnetic compatibility standards that shape transponder design and import certification pathways for RFID hardware. Argentina's ENACOM and Chile's SUBTEL maintain divergent frequency band permissions, fragmenting regional product homogeneity and forcing vendors to maintain SKU differentiation across Andean markets. Stakeholders must monitor pending spectrum harmonization talks between Mercosur regulators to anticipate whether unified UHF band alignment will compress compliance costs or prolong multi-standard inventory requirements.
Market Dynamics
ANATEL's tightening certification timelines for radio frequency devices are compressing product launch cycles across Brazil's industrial corridor, forcing vendors to front-load compliance investment before inventory procurement decisions crystallize.
Growth Catalysts
- Apparel Retail Digitization:Brazil's São Paulo-based fashion conglomerates are mandating source-tagged UHF deployment for omnichannel inventory accuracy, pulling passive tag volumes through distribution networks.
- IFT Spectrum Allocation:Mexico's telecommunications regulator finalized 902–928 MHz harmonization in 2023, eliminating frequency fragmentation that previously required dual-SKU inventory for cross-border logistics.
- Cold-Chain Pharmaceutical Monitoring:Active RFID with temperature telemetry is penetrating Brazil's vaccine distribution infrastructure, driven by ANVISA traceability mandates for biologics transport.
Market Restraints
- Silicon Wafer Supply Concentration:Passive tag inlay production depends on imported IC substrates from East Asian foundries, exposing Latin American converters to freight cost volatility and extended lead times.
- Andean Frequency Fragmentation:Argentina's ENACOM and Chile's SUBTEL maintain divergent UHF band permissions, forcing vendors to maintain non-interoperable SKU variants for Andean markets.
- Barcode Substitution in Low-Value Goods:Printed barcode labels retain cost advantage for FMCG producers in Mexico's informal retail sector, capping RFID penetration in price-sensitive categories.
Strategic Opportunities
- Colombia's Pacific Port Modernization:Buenaventura container terminal automation projects are soliciting ruggedized UHF tag systems for chassis tracking, creating first-mover positioning for integrated solution providers.
- NFC Payment Infrastructure Convergence:Brazil's banking sector is deploying contactless POS terminals that double as RAIN RFID interrogators, enabling unified hardware footprints for retail chains.
- Mercosur Spectrum Harmonization Talks:Pending regulatory alignment could collapse multi-standard inventory requirements into single-SKU regional products, compressing compliance overhead for vendors.
Industry Challenges
- RF Engineering Talent Scarcity:Mexico's Guadalajara electronics cluster faces acute shortages of antenna design specialists capable of optimizing UHF tag performance for metallic asset environments.
- Legacy WMS Integration Friction:Brazilian third-party logistics providers operate warehouse management systems predating EPC Gen 2 protocols, requiring middleware development for tag data ingestion.
- ANATEL Recertification Cycles:Hardware modifications trigger fresh electromagnetic compatibility testing, extending product refresh timelines by four to six months for Brazil-bound shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America RFID Tags Market |
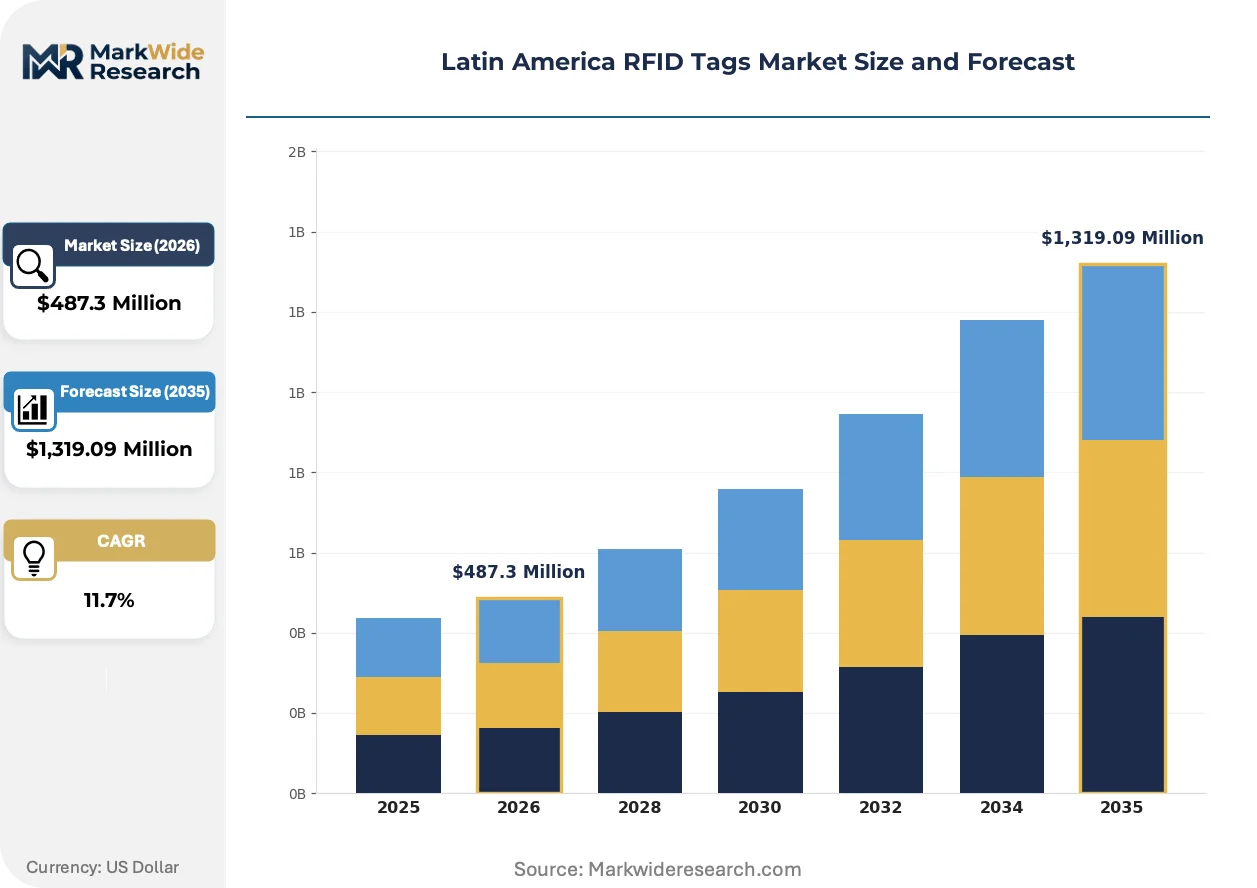
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Tags, Active Tags, Semi-Passive Tags, NFC Tags Application: Inventory Management, Asset Tracking, Access Control, Supply Chain Technology: Ultra High Frequency, High Frequency, Low Frequency, Near Field Communication End User: Retail, Healthcare, Logistics, Manufacturing |
| Companies Covered | Zebra Technologies Corporation, Honeywell International Inc., Impinj Inc., Alien Technology, NXP Semiconductors, AVERY DENNISON CORPORATION, Checkpoint Systems Inc., HID Global Corporation, Microchip Technology, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America RFID Tags Market Shifts & Advancements
Chipless RFID encoding methods are disrupting cost structures at the tag-inlay layer, while regulatory pressure on spectrum efficiency accelerates reader infrastructure replacement cycles across major Latin American logistics hubs.
Sensor-integrated passive UHF tags with humidity and shock detection capabilities are overtaking conventional memory-only transponders in Brazil's agricultural export supply chain. Coffee cooperatives in Minas Gerais are piloting these tags for moisture monitoring during containerized ocean transit. The technology is compressing insurance claim disputes by providing timestamped environmental breach evidence.
ANATEL's updated Resolution 2422 tightened spurious emission limits for 902–928 MHz devices, forcing reader manufacturers to redesign RF front-ends for Brazil-specific certification. Industrial automation vendors in São Paulo's ABC manufacturing belt are absorbing these compliance costs into bundled system pricing. The regulation most acutely affects high-power portal installations at distribution centers.
Consolidated procurement consortia among Mexican retail chains are displacing fragmented distributor relationships that historically dominated tag sourcing. Grupo Elektra and Coppel have formed joint technical specifications for private-label apparel tagging, standardizing inlay designs across their combined supplier bases. This concentration is most visible in Mexico City's garment district, where converter margins face compression from volume-commitment negotiations.
Latin America RFID Tags Market Segmentation
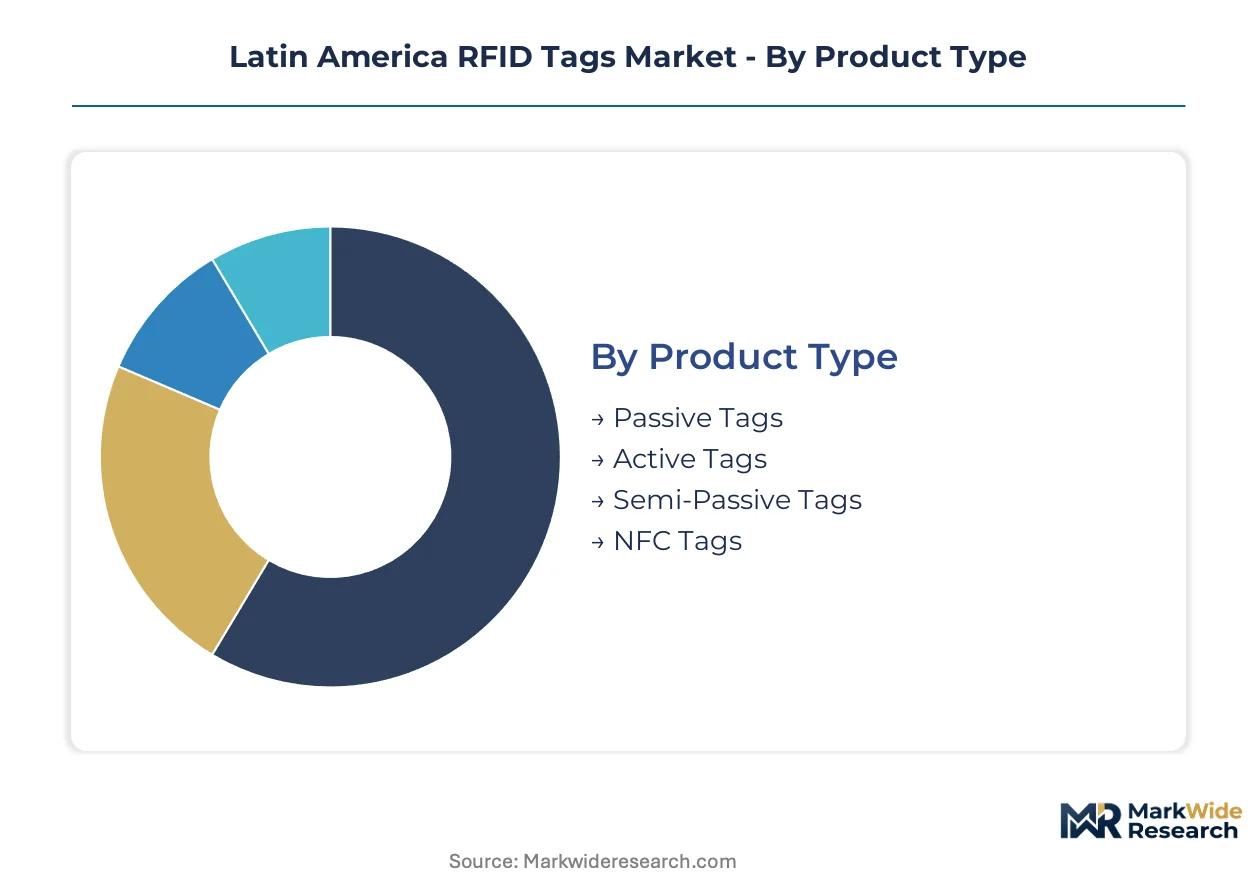
RFID tag procurement across Latin America fragments sharply by power source, frequency band, and asset environment. Buyers in São Paulo's logistics corridor and Mexico City's retail hubs prioritize different technical specifications, forcing suppliers to maintain parallel inventory lanes.
Product Type:
Supply concentration for passive tag inlays centers on East Asian IC foundries, while active tag assembly clusters in Mexican contract electronics facilities near Guadalajara.
- Passive Tags:These transponders harvest interrogator energy through backscatter modulation, eliminating battery maintenance. Brazilian apparel retailers in São Paulo's fashion district mandate source-tagged UHF passive deployment for omnichannel inventory accuracy, pulling volumes through distribution networks.
- Active Tags:Battery-powered transponders with onboard transmitters enable real-time location telemetry across extended ranges. Cold-chain pharmaceutical monitoring in Brazil's vaccine distribution infrastructure drives procurement, justified by ANVISA traceability mandates for biologics transport.
- Semi-Passive Tags:Hybrid designs use battery-assisted backscatter for sensor functionality without full transmitter power.
- NFC Tags:Contactless payment infrastructure across Brazilian banking terminals accelerates deployment in dual-use retail environments.
Today's leader: Passive Tags. Tomorrow's challenger: Active Tags.
Application:
Cost tier differentiation separates enterprise-grade asset tracking from high-volume inventory tagging programs.
- Inventory Management:Source-tagging mandates from Brazilian fashion conglomerates standardize UHF passive deployment at garment origin. Mexico City's consolidated retail procurement consortia compress converter margins through volume-commitment negotiations.
- Asset Tracking:Ruggedized active tag systems track mining equipment and port chassis across Colombia's Pacific modernization projects. Buenaventura container terminal automation creates first-mover positioning for integrated solution providers.
- Access Control:Personnel credentialing systems in corporate campuses and healthcare facilities.
- Supply Chain:End-to-end visibility platforms integrating multiple transport modes and customs checkpoints.
Inventory Management commands current procurement volumes. Asset Tracking presents the steepest expansion trajectory.
Technology:
Frequency band selection determines antenna design complexity and regulatory compliance pathways across fragmented national spectrum allocations.
- Ultra High Frequency:Operating in the 860–960 MHz band, UHF delivers read ranges exceeding 10 meters for passive tags. ANATEL's Resolution 2422 tightened spurious emission limits, forcing reader manufacturers to redesign RF front-ends for Brazil-specific certification.
- High Frequency:13.56 MHz operation enables reliable near-field performance in liquid and metal-rich environments. Industrial automation vendors in São Paulo's ABC manufacturing belt absorb compliance costs into bundled system pricing.
- Low Frequency:125–134 kHz bands penetrate dense materials but sacrifice read range and data rate.
- Near Field Communication:Protocol harmonization with contactless payment terminals enables unified hardware footprints for Brazilian retail chains.
UHF anchors structural revenue. NFC is climbing the fastest.
End User:
Customer type dictates performance requirements, with retail prioritizing unit economics and healthcare demanding sensor integration.
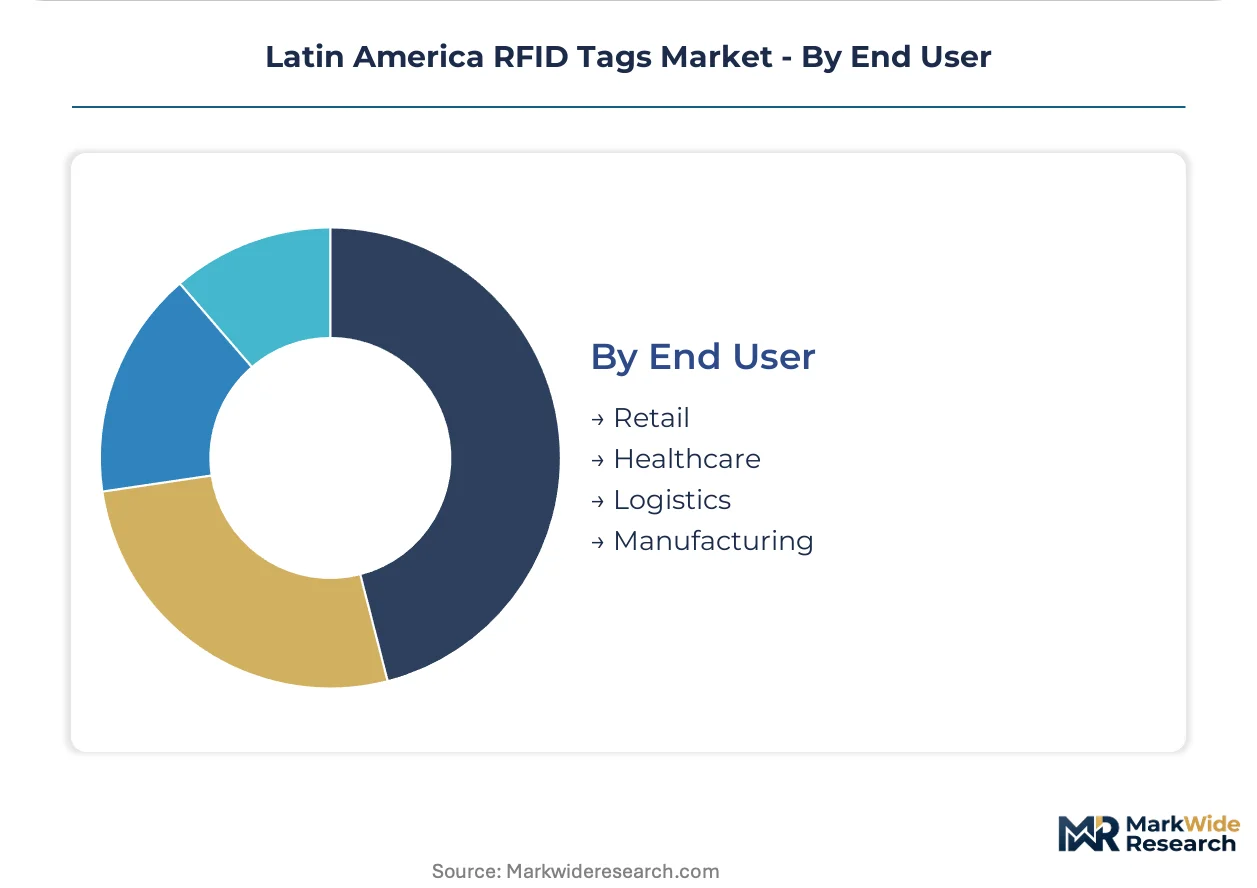
- Retail:Omnichannel inventory accuracy mandates from São Paulo-based fashion conglomerates pull passive tag volumes through distribution networks. Barcode substitution in Mexico's informal retail sector caps RFID penetration in price-sensitive FMCG categories.
- Healthcare:ANVISA traceability mandates for biologics transport drive active RFID with temperature telemetry into Brazil's vaccine distribution infrastructure. Sensor-integrated passive UHF tags with humidity detection pilot in Minas Gerais coffee cooperatives for moisture monitoring during ocean transit.
- Logistics:Third-party warehouse operators face legacy WMS integration friction, requiring middleware development for EPC Gen 2 tag data ingestion.
- Manufacturing:Metallic asset environments in automotive and electronics assembly demand specialized antenna optimization.
Retail dominates unit volumes. Healthcare offers premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's industrial corridor anchors Latin American RFID demand through logistics hub procurement and retail chain digitization mandates.
Brazil
Apparel retailers in São Paulo's fashion district mandate source-tagged UHF deployment for omnichannel inventory accuracy. ANATEL's Resolution 2422 tightened spurious emission limits for 902–928 MHz devices, forcing reader manufacturers to redesign RF front-ends. Cold-chain pharmaceutical monitoring accelerates in the ABC manufacturing belt as ANVISA traceability mandates drive active RFID adoption for biologics transport.
Mexico
Consolidated procurement consortia among Mexico City retail chains displace fragmented distributor relationships. IFT finalized 902–928 MHz spectrum harmonization in 2023, eliminating dual-SKU inventory requirements for cross-border logistics. Guadalajara's electronics cluster faces acute shortages of antenna design specialists for metallic asset optimization.
Colombia
Buenaventura container terminal automation projects solicit ruggedized UHF tag systems for chassis tracking. The Pacific port modernization creates first-mover positioning for integrated solution providers. Mining operations in Antioquia deploy active tags for equipment telemetry across extended ranges.
Argentina
ENACOM maintains divergent UHF band permissions that force vendors to maintain non-interoperable SKU variants. Buenos Aires logistics operators absorb compliance costs into multi-standard inventory requirements. Agricultural exporters in the Pampas region pilot sensor-integrated passive tags for grain moisture monitoring.
Chile
SUBTEL's spectrum allocation fragments regional product homogeneity alongside Argentine regulations. Santiago's retail sector adopts NFC-enabled contactless infrastructure alongside RAIN RFID deployments. Copper mining operations in the Atacama Desert drive demand for ruggedized active tag systems in extreme environments.
Latin America RFID Tags Market Competitive Landscape
Global majors compete with regional champions across certification pathways and service infrastructure. The vendor base stratifies between integrated hardware-software providers and specialized chipset suppliers. Three archetypes dominate: enterprise solution bundlers, ruggedized industrial specialists, and RAIN RFID component innovators. Competitive moves center on regional service network expansion and spectrum-specific product certification.
Among US-based technology providers, Zebra Technologies Corporation leverages regional service infrastructure to anchor enterprise accounts, while Honeywell International Inc. occupies a position within ruggedized hardware lines suited for mining and port logistics. Impinj Inc. exemplifies the RAIN RFID chipset specialization archetype. These three represent distinct competitive vectors—service density, environmental durability, and silicon innovation—without overlapping positioning.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Honeywell International Inc. |
| Impinj Inc. |
| Alien Technology |
| NXP Semiconductors |
| AVERY DENNISON CORPORATION |
| Checkpoint Systems Inc. |
| HID Global Corporation |
| Microchip Technology |
| Others |
Supply & Pricing Matrix
ANATEL's Resolution 2422 spurious emission limits gate qualified supply for Brazil's 902–928 MHz devices, compressing premium-tier pricing access to vendors with certified RF front-end redesigns while locking out uncertified competitors from São Paulo's industrial corridor procurement.
Pricing Analysis
Silicon wafer cost pass-through from East Asian foundries intensifies margin pressure on Latin American tag converters. Pricing stratifies across ANATEL-certified premium tiers, uncertified standard imports, and economy-grade barcode-competing alternatives. Cost compression in standard-tier passive tags reflects freight volatility and consolidated retail procurement consortia. Mexico's informal retail sector exhibits highest price sensitivity, while Brazil's pharmaceutical cold-chain buyers accept premium active tag pricing for ANVISA compliance.
Supply Chain Analysis
ANATEL and IFT certification requirements gate inbound hardware flows, filtering supplier participation before inventory decisions crystallize. IC substrate production centers on Taiwan, South Korea, and China, while tag assembly clusters in Mexican contract facilities near Guadalajara. Passive tag inlay production rests on imported silicon substrates, exposing converters to single-source vulnerability from East Asian foundry concentration. Distribution runs through São Paulo-based industrial distributors and Mexico City's consolidated retail procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's RFID market functions as a geographic-arbitrage play where Mexico's IFT spectrum harmonization eliminates dual-SKU costs that still burden Brazil-Argentina cross-border logistics, creating margin expansion opportunities for unified product strategies.
For Market Incumbents: Deepen ANATEL certification investment to defend São Paulo enterprise accounts against emerging Asian chipset suppliers with faster compliance cycles. Prioritize backward integration into antenna design capability to offset Guadalajara's RF engineering talent scarcity. Lock in multi-year volume commitments with Brazilian retail consortia before spectrum harmonization collapses pricing premiums.
For New Entrants and Emerging Players: Launch via direct converter partnerships targeting Colombia's Buenaventura port automation projects, the most penetrable infrastructure vertical with unconsolidated vendor relationships. Exploit Argentina's ENACOM frequency fragmentation by offering dual-band SKU flexibility that incumbents resist. Position sensor-integrated passive tags for Minas Gerais agricultural exporters as a differentiated entry wedge.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional certification specialists with ANATEL-approved product lines but limited scale. Long-term viability over the next decade hinges on Mercosur spectrum harmonization execution. Watch pending regulatory alignment talks as the inflection signal for single-SKU margin compression or sustained multi-standard premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Certification Fast-Track | Accelerates Brazil market entry before Resolution 2422 compliance deadlines tighten. |
| Sensor-Integrated Tag Development | Captures ANVISA-mandated cold-chain pharmaceutical monitoring premiums in São Paulo. |
| Guadalajara RF Engineering Partnership | Addresses antenna design scarcity for metallic asset optimization in manufacturing. |
| Mercosur Spectrum Harmonization Lobbying | Collapses multi-SKU inventory costs into unified regional product lines. |
| Buenaventura Port System Integration | Secures first-mover positioning in Colombia's Pacific container terminal automation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ANATEL certification officers, São Paulo logistics procurement directors, Guadalajara electronics manufacturing executives, and Brazilian retail supply chain managers with secondary validation from ANATEL regulatory filings, IFT spectrum allocation records, ANVISA traceability mandates, and customs import data for RFID hardware. Bottom-up tag volume estimates triangulated against top-down market sizing across the analysis window.
Segment-weighting distributed value and volume projections across power source, frequency band, application, and end-user dimensions, with additional weighting for national regulatory cluster alignment. CAGRs derived from fitted growth curves incorporating procurement lead times, certification cycle durations, and retail digitization capex trajectories. Forecast inputs included ANATEL recertification timelines and IFT harmonization implementation progress.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Mercosur spectrum negotiation failure or East Asian foundry supply disruption scenarios. Model outputs reflect documented assumptions on regulatory alignment and silicon substrate availability. A model refresh is warranted upon material change in ANATEL certification timelines or IFT spectrum enforcement posture.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Radio Frequency Filters Market
RF Components
Radio Frequency Front End Market
RF Components
RF Transceiver Chip Market
RF Components
Phase Shifters Market
RF Components
RFID Tags Market
RF Components
Monolithic Microwave Integrated Circuit (MMIC) Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
Gaas RF Switch Market
RF Components
RF Tunable Filters Market
RF Components
Multiband Booster Market
RF Components
Coaxial Connectors (RF) Market
RF Components
Small Signal Mosfets Market
RF Components
Americas Small Signal Transistor Market
RF Components
Embedded Antenna Systems Market
RF Components
RF Duplexer Market
RF Components
Wireless Module Market