
 Small Signal Mosfets Market | 2026-2036
Small Signal Mosfets Market Size, Share, and Industry Trends Forecast 2026-2036
Small Signal Mosfets Market Analytics
Multi-source procurement among tier-one OEMs is rebalancing supplier relationships across the small signal Mosfets landscape. Infineon Technologies leverages its European fabrication footprint to sustain long-term supply agreements with automotive module makers. STMicroelectronics anchors its position through deep specialization in silicon carbide-adjacent process technologies for high-efficiency switching. Texas Instruments competes by extending its analog-plus-power integration strategy into low-voltage signal chains.
Small signal Mosfets are metal-oxide-semiconductor field-effect transistors engineered for low-power switching and amplification, typically handling drain currents below one ampere at gate-source thresholds of one to three volts. Their primary purpose centers on precision power management, signal conditioning, and load switching in battery-operated and space-constrained electronics. Enhancement mode devices dominate unit shipments due to their default-off behavior and compatibility with standard logic-level drive circuits. Gallium nitride technology represents the fastest-expanding material platform as RF switching and telecommunications infrastructure demand higher electron mobility. Industrial equipment end users command the most concentrated margin pool, since factory automation and process control systems require extended temperature ratings and qualification traceability.
The EPA regulates hazardous substance reporting for electronics manufacturing facilities operating within the United States, while REACH and RoHS constrain material composition across European supply chains. FDA electromagnetic compatibility requirements for portable medical devices further shape product validation protocols and documentation burdens. Stakeholders must monitor how evolving dual-use export controls and semiconductor subsidy conditions in major producing jurisdictions reshape competitive access to fabrication capacity and qualified component supply.
Market Dynamics
Material platform competition between silicon and wide-bandgap semiconductors is compressing traditional process node advantages while elevating packaging and thermal management as differentiation vectors in small signal Mosfets procurement.
Growth Catalysts
- Portable medical device proliferation:FDA electromagnetic compatibility mandates for wireless health monitors are expanding qualified component volumes across diagnostic and therapeutic equipment categories.
- REACH substance restrictions:The EU RoHS directive and ECHA framework are accelerating lead-free and halogen-free material transitions, creating replacement demand cycles in legacy automotive and industrial installed bases.
- GaN electron mobility:Gallium nitride's superior switching characteristics at sub-ampere drain currents are penetrating RF infrastructure and telecommunications test equipment, displacing silicon in frequency-critical signal paths.
Market Restraints
- Foundry concentration:Taiwan Semiconductor Manufacturing and Samsung Foundry control advanced node capacity for precision analog devices, exposing supply continuity risks during geopolitical friction or natural disaster events.
- Silicon carbide cost premium:SiC substrate prices remain elevated versus silicon epitaxy, constraining adoption in cost-sensitive consumer electronics despite efficiency advantages.
- Dual-use export controls:US Bureau of Industry and Security licensing requirements for semiconductor manufacturing equipment are complicating capacity expansion plans for Chinese domestic foundries.
Strategic Opportunities
- India PLI scheme:Production-linked incentive programs for semiconductor assembly and testing are attracting EMS investment in Gujarat and Tamil Nadu, creating localized sourcing alternatives to East Asian supply chains.
- Silicon carbide-adjacent processes:STMicroelectronics and Infineon are licensing trench-gate architectures that bridge silicon cost structures with wide-bandgap thermal performance, opening mid-market industrial applications.
- Direct OEM engagement:Tier-one automotive and medical device manufacturers are bypassing distribution layers for long-term supply agreements, compressing channel margins while securing allocation priority.
Industry Challenges
- Analog design talent scarcity:Precision power management circuit design requires deep transistor-level expertise that semiconductor engineering programs are producing at insufficient rates relative to demand expansion.
- Extended qualification timelines:Automotive AEC-Q101 and medical ISO 13485 certification cycles stretch 18-24 months, delaying revenue recognition for new process introductions and constraining rapid iteration.
- Legacy system integration friction:Factory automation retrofits require signal-level compatibility with 20-30 year-old control architectures, complicating voltage threshold and package footprint standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Signal Mosfets Market |
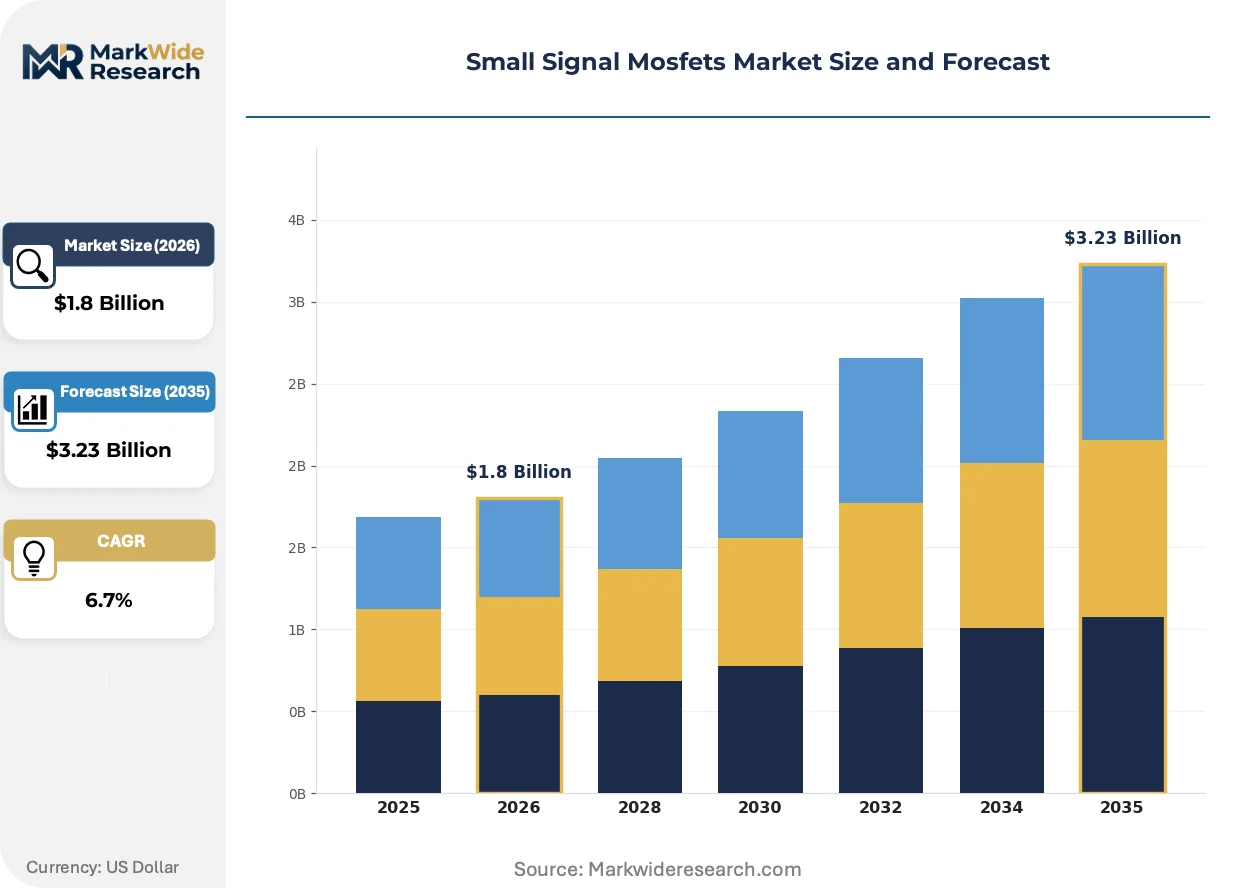
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enhancement Mode, Depletion Mode, Lateral Mosfets, Vertical Mosfets Technology: Si, GaN, SiC, Organic End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Application: Power Management, Signal Amplification, RF Switching, Audio Drivers |
| Companies Covered | Infineon Technologies, onsemi, STMicroelectronics, Nexperia, Toshiba, Texas Instruments, Vishay Intertechnology, ROHM, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Signal Mosfets Market Evolving Landscape
Process integration and packaging miniaturization are converging to redefine competitive positioning, as discrete component suppliers compete with system-in-package integrators for socket access in space-constrained electronics.
Silicon-on-insulator substrates with integrated passive devices are unifying multiple small-signal functions into single-die solutions. Medical wearable manufacturers in Switzerland and Germany are adopting these at accelerated cadences for continuous glucose monitors and cardiac event recorders. This unification is compressing the addressable market for standalone discrete Mosfets while expanding total available revenue per socket for integrated solution providers.
REACH Annex XIV authorization requirements for phthalates and flame retardants are forcing reformulation of molding compounds and leadframe finishes. Electronics manufacturers serving European medical and industrial markets are accelerating supply chain audits to preempt substance restriction deadlines. High-reliability automotive module suppliers face the steepest compliance documentation burdens, with some qualifying alternative materials 18 months ahead of regulatory effective dates.
Consolidation among contract electronics manufacturers is concentrating component procurement authority. Jabil, Flex, and Foxconn Industrial Internet now negotiate directly with Infineon and Texas Instruments for multi-year allocation guarantees, displacing traditional distributor intermediaries in high-volume programs. This concentration is most pronounced in China, where domestic EMS clusters serving Xiaomi, Huawei, and BYD are securing preferential pricing through captive demand aggregation.
Small Signal Mosfets Market Segmentation
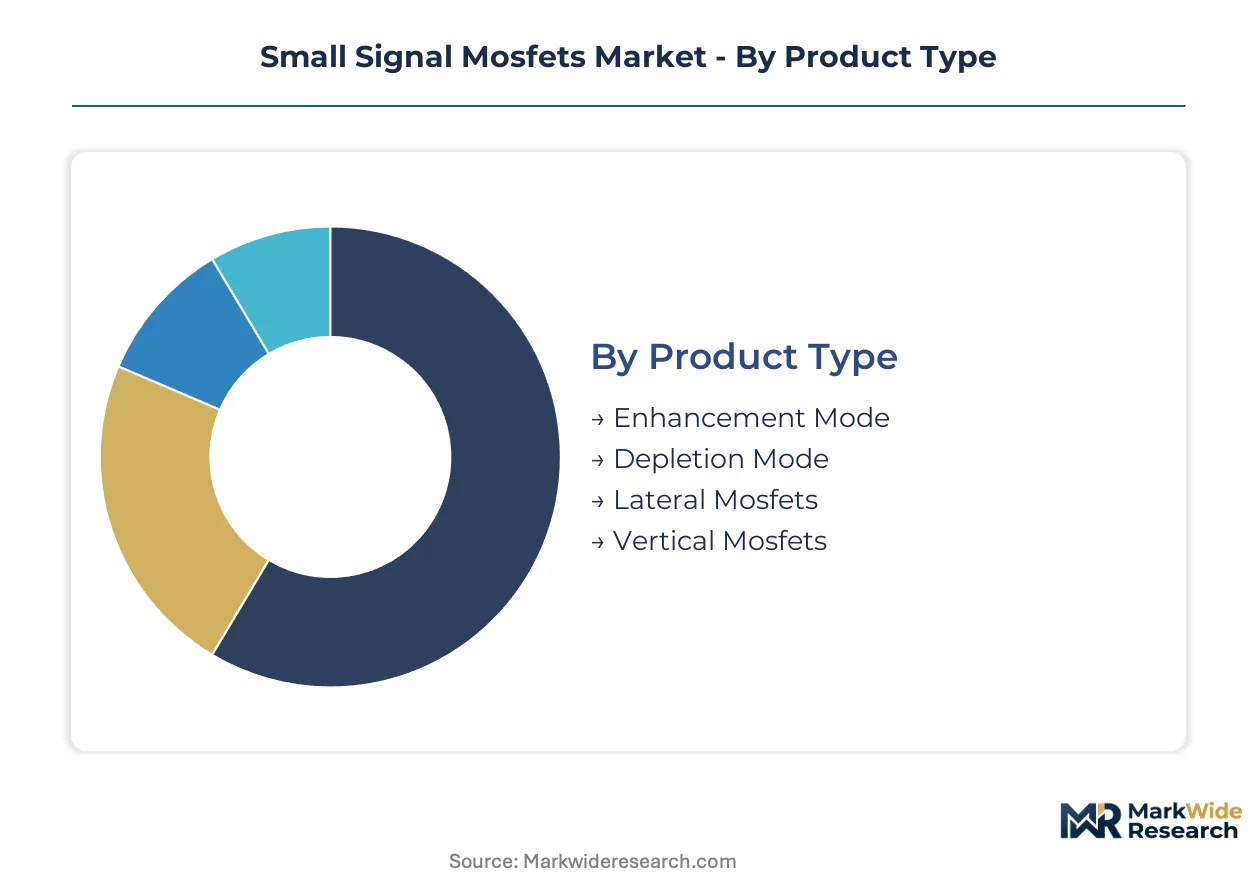
Small signal Mosfets serve divergent technical requirements across voltage thresholds, switching frequencies, and thermal envelopes. Procurement patterns vary sharply by end-use qualification burden and material platform maturity. Understanding segment boundaries illuminates where process technology investments translate to defendable margin positions.
Product Type:
Engineering teams select device architecture based on default-state behavior and integration compatibility with existing drive circuits.
- Enhancement Mode:These devices remain off at zero gate-source voltage, requiring positive bias to conduct. Default-off behavior aligns with fail-safe design priorities in battery-operated medical wearables and automotive sensor modules. Consumer electronics OEMs in Shenzhen and Dongguan specify enhancement mode for logic-level compatibility with microcontroller GPIO outputs.
- Depletion Mode:Normally-on characteristics suit specific analog switching applications where continuous conduction is desired. RF test equipment manufacturers in Germany leverage depletion mode for bias-tee configurations and active load switching. Demand concentrates in telecommunications infrastructure where signal path continuity outweighs power efficiency priorities.
- Lateral Mosfets:Current flows horizontally across the substrate surface, enabling higher switching speeds in RF applications. These devices dominate cellular base station signal chains.
- Vertical Mosfets:Drain current travels through the silicon bulk, delivering superior on-resistance for power management tasks. Industrial motor drives favor this architecture.
Enhancement mode leads on scale; lateral Mosfets lead on momentum.
Technology:
Material platform selection trades off electron mobility, fabrication cost, and supply chain maturity against target application frequency and efficiency requirements.
- Si:Silicon epitaxy dominates unit economics through established 200mm and 300mm foundry infrastructure. Precision analog foundries in Taiwan and Japan maintain cost leadership for sub-100V signal switching. Automotive module suppliers rely on silicon for AEC-Q101 qualified devices with 15-year traceability requirements.
- GaN:Gallium nitride delivers electron mobility approximately 1000x silicon, enabling sub-nanosecond switching in 5G massive MIMO arrays. Base station OEMs in South Korea and Finland specify GaN for mmWave front-ends where insertion loss budgets are tight. Foundry capacity constraints at X-FAB and Tower Semiconductor limit volume expansion.
- SiC:Silicon carbide substrates remain cost-prohibitive for sub-ampere signal applications despite superior thermal conductivity. Niche adoption appears in aerospace radiation-hardened electronics.
- Organic:Solution-processed semiconductors enable flexible substrate integration for disposable medical sensors. Swiss wearable startups pilot these for continuous glucose monitoring patches.
Silicon commands production volume; GaN claims the steepest expansion trajectory.
End User:
Qualification intensity and procurement authority concentration vary dramatically across end-use sectors, reshaping supplier engagement models.
- Consumer Electronics:High-volume, low-margin procurement from smartphone and laptop OEMs drives extreme cost compression. EMS clusters in Guangdong province negotiate directly with discrete component suppliers, bypassing distribution. Rapid product cycles demand 12-week qualification timelines incompatible with automotive-grade documentation.
- Automotive:AEC-Q101 certification and PPAP documentation create substantial barriers to supplier switching. Tier-one module makers in Germany and Japan require 18-24 month validation cycles for signal conditioning circuits in battery management systems. Electrification trends expand small signal Mosfet content per vehicle for sensor interfacing and gate driving.
- Telecommunications:Base station and optical transceiver manufacturers prioritize RF performance over unit cost. 5G deployment waves in India and Brazil sustain demand for low-noise amplification stages.
- Industrial Equipment:Factory automation retrofits demand voltage threshold compatibility with legacy 24V control architectures. Extended temperature ratings and conformal coating requirements support premium pricing.
Consumer electronics leads on unit volume; automotive leads on margin capture.
Application:
Functional use case determines critical specification parameters including threshold voltage precision, switching loss budgets, and linearity requirements.
- Power Management:Load switching and DC-DC control demand tight threshold voltage distribution for predictable turn-on behavior. Portable medical device manufacturers in Switzerland specify sub-1V gate thresholds for single-cell lithium-ion compatibility. Battery life extension drives specification of ultra-low leakage devices in microampere standby states.
- Signal Amplification:Small-signal audio and sensor front-ends require transconductance linearity across temperature extremes. Hearing aid manufacturers in Denmark and Minnesota source matched pairs for differential amplifier stages. Electret microphone preamplification consumes billions of units annually.
- RF Switching:Antenna tuning and filter bank selection demand minimal insertion loss at gigahertz frequencies. Smartphone RF front-end modules integrate these with acoustic wave filters.
- Audio Drivers:Class-D amplification stages utilize complementary Mosfet pairs for headphone and speaker output stages. Low total harmonic distortion specifications differentiate premium tier products.
Power management leads on unit scale; RF switching leads on technology premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting small signal Mosfet production toward jurisdictions with streamlined environmental compliance frameworks and concentrated EMS infrastructure. Fabricators in lower-cost manufacturing zones capture volume contracts as tier-one OEMs diversify geographic risk.
China
Domestic semiconductor foundries and EMS clusters in Shenzhen and Dongguan drive volume procurement of discrete power components for consumer electronics OEMs. MIIT's industrial upgrading directives accelerate localization of precision analog device supply chains. Yangtze River Delta fabrication facilities expand capacity for logic-compatible enhancement mode devices serving Xiaomi and Huawei ecosystems.
Germany
Automotive module makers in Stuttgart and Munich require AEC-Q101 qualified devices with 15-year traceability for battery management systems. KBA safety regulations and REACH substance restrictions tighten material documentation burdens for industrial equipment suppliers. Bavarian precision electronics manufacturers qualify alternative molding compounds 18 months ahead of regulatory deadlines.
United States
Portable medical device manufacturers in Minnesota and Massachusetts integrate sensing and wireless connectivity functions requiring FDA electromagnetic compatibility validation. EPA hazardous substance reporting shapes fabrication facility operations across domestic electronics manufacturing. Greater Boston hearing aid producers source matched Mosfet pairs for differential amplifier stages.
Japan
Precision analog foundries in Kyushu and Nagoya maintain cost leadership for sub-100V signal switching through established 200mm infrastructure. METI semiconductor subsidy programs support capacity preservation for automotive-grade discrete components. Kansai region industrial automation retrofits demand voltage threshold compatibility with legacy 24V control architectures.
India
Production-linked incentive programs for semiconductor assembly and testing attract EMS investment in Gujarat and Tamil Nadu, creating localized sourcing alternatives. CDSCO medical device regulations shape validation protocols for diagnostic equipment manufacturers. Bengaluru and Hyderabad electronics clusters negotiate directly with discrete component suppliers for multi-year allocation guarantees.
Small Signal Mosfets Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wide-bandgap material platforms and integrated signal chain solutions. The vendor base organizes around three strategic archetypes: diversified analog-plus-power integrators, specialized discrete component fabricators, and wide-bandgap technology licensors. Competitive moves concentrate on strategic partnerships for foundry capacity allocation and portfolio diversification into silicon carbide-adjacent process architectures.
Among European fabrication specialists, Infineon Technologies and STMicroelectronics exemplify the integrated device manufacturer archetype with captive process technology development. Texas Instruments occupies a position bridging analog integration with low-voltage signal chain expertise. These three anchors represent distinct competitive vectors: European fabrication footprint leverage, silicon carbide-adjacent trench-gate specialization, and analog-plus-power integration strategy.
| Leading Market Players |
|---|
| Infineon Technologies |
| onsemi |
| STMicroelectronics |
| Nexperia |
| Toshiba |
| Texas Instruments |
| Vishay Intertechnology |
| ROHM |
| Microchip Technology |
| Others |
Value Network & Pricing Analysis
Gallium nitride process migration toward 200mm foundry compatibility is compressing wafer cost premiums while redistributing bargaining power toward RF infrastructure OEMs with multi-year allocation contracts. Taiwan Semiconductor Manufacturing and X-FAB capacity commitments for GaN-on-silicon epitaxy are reshaping how tier-one automotive module makers negotiate silicon legacy pricing.
Pricing Analysis
Distributor margin compression is accelerating as Jabil, Flex, and Foxconn Industrial Internet negotiate direct long-term supply agreements with Infineon and Texas Instruments, bypassing traditional channel markups of fifteen to twenty percent. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade qualification levels differentiates contract terms, with AEC-Q101 certification commanding substantial premiums over standard commercial offerings. Pricing pressure stems from EMS procurement concentration in Guangdong province, where Xiaomi and Huawei ecosystem suppliers aggregate demand for logic-compatible enhancement mode devices. Consumer electronics OEMs exhibit highest price sensitivity, while medical device manufacturers in Switzerland and Minnesota absorb premiums for FDA electromagnetic compatibility validation and matched pair specifications.
Supply Chain Analysis
Dual-sourcing mandates from tier-one automotive and medical device manufacturers are forcing qualification of secondary foundries for precision analog devices, extending supplier onboarding timelines. Taiwan, Japan, and Germany anchor fabrication capacity for sub-100V signal switching, with Kyushu and Nagoya precision analog foundries maintaining cost leadership through established 200mm infrastructure. Silicon epitaxy wafers, gold wire bonding materials, and epoxy molding compounds constitute critical input dependencies. Single-source vulnerability concentrates around Taiwan Semiconductor Manufacturing's advanced node capacity for GaN RF devices, exposing continuity risks during geopolitical friction. Distribution runs through consolidated EMS clusters in Shenzhen and Dongguan, with domestic Chinese foundries capturing preferential allocation through MIIT localization directives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide-bandgap material cost curves are steepening margin expansion potential as GaN epitaxy yields improve and silicon carbide-adjacent processes bridge mid-market industrial applications.
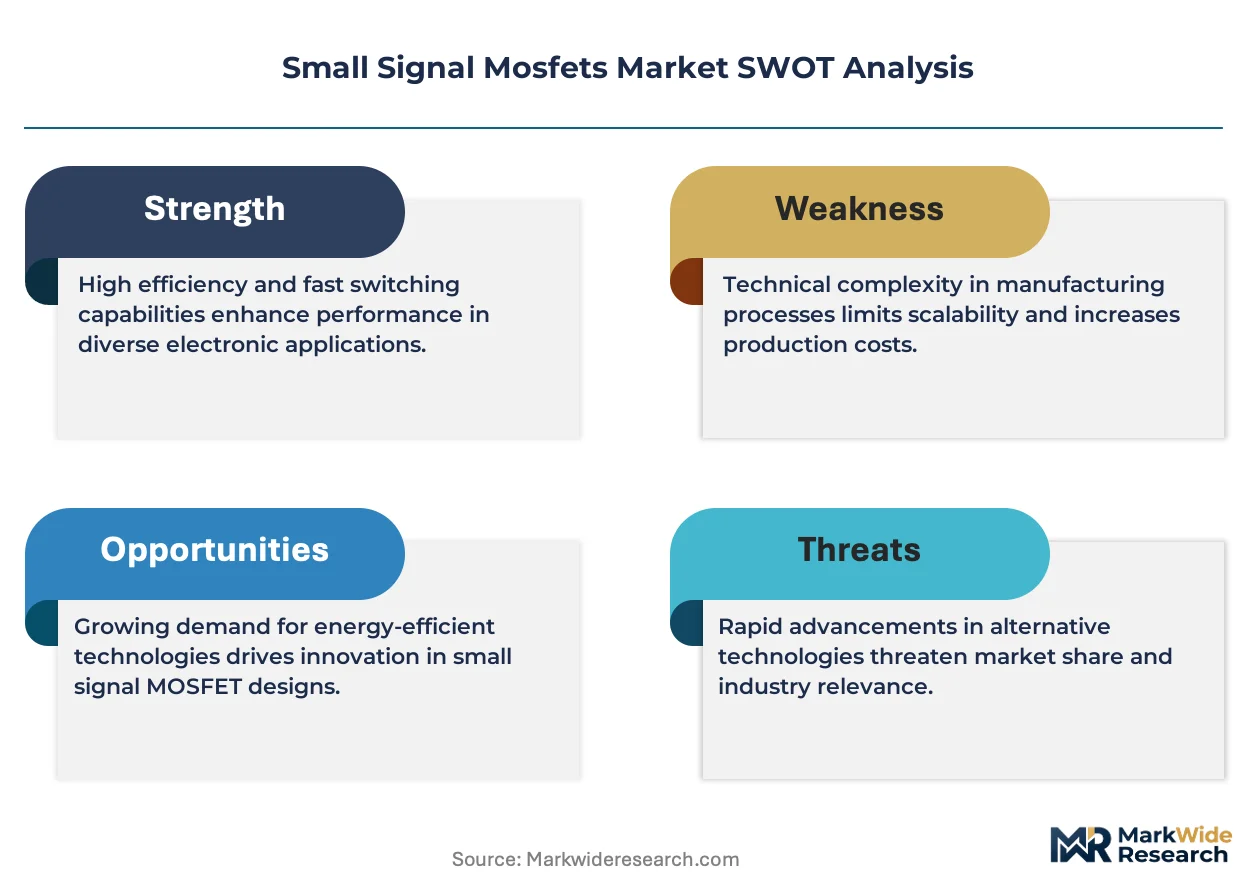
For Market Incumbents: Anticipate displacement pressure from GaN RF switching in 5G massive MIMO arrays by accelerating trench-gate architecture licensing to EMS partners in India and Southeast Asia. Defend automotive socket access through captive AEC-Q101 qualification pipelines and 15-year traceability documentation that emerging entrants cannot replicate within compressed product cycles. Prioritize backward integration into 200mm GaN-on-silicon epitaxy capacity to secure allocation priority as foundry constraints persist at X-FAB and Tower Semiconductor. For New Entrants and Emerging Players: The premium-to-economy tier price gap in industrial equipment signal conditioning creates white-space opportunity for silicon carbide-adjacent process entrants targeting factory automation retrofits. Target underpenetrated geographies in India where PLI scheme subsidies for semiconductor assembly and testing reduce capital barriers in Gujarat and Tamil Nadu. Pursue direct OEM engagement models with Bengaluru and Hyderabad electronics clusters, bypassing distribution layers that incumbent relationships have consolidated. For Investors and Strategic Acquirers: Valuations sit cheapest among analog design boutiques with captive trench-gate IP and established automotive qualification pipelines. Long-term viability hinges on five-to-ten year GaN process roadmaps and foundry partnership depth rather than discrete component market share alone. Signal to monitor: CDSCO medical device regulatory harmonization with FDA electromagnetic compatibility standards, which would expand addressable market for qualified component suppliers in Indian diagnostic equipment manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-Silicon Foundry Partnership | Secures 200mm epitaxy allocation for RF infrastructure OEMs competing in 5G massive MIMO deployment. |
| AEC-Q101 Certification Pipeline Investment | Creates eighteen-month qualification moats for automotive battery management system socket access. |
| India PLI Scheme Localization | Captures EMS demand aggregation in Gujarat and Tamil Nadu through assembly and testing incentives. |
| Trench-Gate Architecture Licensing | Monetizes silicon carbide-adjacent IP across mid-market industrial motor drive applications. |
| Direct OEM Engagement Model | Compresses channel margins while securing multi-year allocation guarantees from tier-one medical device manufacturers. |
Research Methodology
Multiple input streams — primary interviews with semiconductor procurement directors, analog design engineers, and EMS supply chain managers, alongside secondary validation through SEC 10-K filings, MIIT industrial policy directives, and ECHA REACH substance restriction databases — were reconciled through bottom-up and top-down triangulation. Field intelligence from precision analog foundries in Taiwan and Japan informed capacity utilization assumptions, while regulatory documentation from FDA, EPA, and KBA shaped compliance cost modeling for medical and automotive qualification tiers.
Data-stream reconciliation across product type, material platform, end-user sector, and geographic production cluster dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling and substitution curve analysis for GaN versus silicon signal switching. Foundry capacity expansion timelines, REACH Annex XIV authorization schedules, and PLI scheme disbursement trajectories constituted industry-specific forecast inputs.
Caveats apply where dual-use export control tightening, Taiwan Strait logistics disruption, or GaN epitaxy yield shortfalls could materially shift the outlook. Deviation in automotive electrification content-per-vehicle assumptions or FDA electromagnetic compatibility validation timeline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Japan Small Signal Transistor Market
RF Components
RF Tester Market
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
EMI Microwave Absorber Market
RF Components
Global RF Transceiver Market
RF Components
RF Spectrum Analyzer Market
RF Components
Global Gan RF Devices Market
RF Components
Multi-Mode Receiver Market
RF Components
RF Transceiver Chip Market
RF Components
Z-Wave Products Market
RF Components
RF Mixers Market
RF Components
RFID Tags Market
RF Components
RF and Microwave Diodes Market
RF Components
Noise Suppression Components Market
RF Components
Global Ceramic Dielectric Filters Market