
 Embedded Antenna Systems Market | 2026-2036
Embedded Antenna Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Antenna Systems Market Analysis
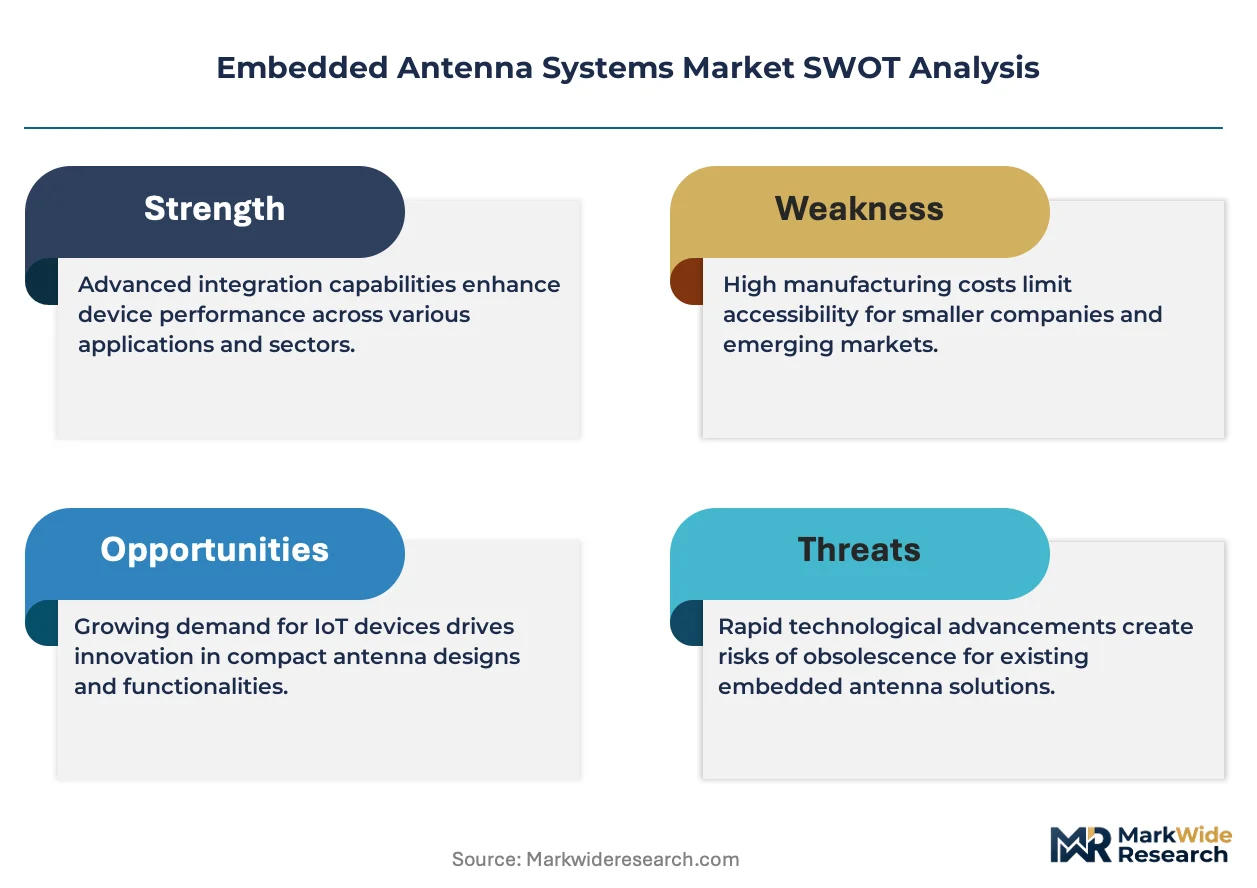
Multi-band integration at the chip-package level is tilting RF front-end design toward module-first architectures rather than discrete component assembly. TE Connectivity leverages its connector-to-antenna integration pipeline to dominate high-reliability automotive sockets. Murata Manufacturing sustains ceramic substrate leadership that anchors miniature dielectric antenna supply for smartphone OEMs. Qualcomm competes through modem-antenna co-design, embedding adaptive tuning directly into baseband reference platforms.
Embedded antenna systems integrate radiating elements directly into device substrates, enclosures, or circuit boards, typically operating between 400 MHz and 6 GHz with form factors below 10 mm in longest dimension for consumer applications. Their primary purpose is to eliminate external protrusions while maintaining gain efficiency across licensed and unlicensed spectrum allocations. PCB antennas occupy the highest volume tier in consumer electronics where cost-per-unit compression governs procurement, while LTE technology segments carry premium positioning in automotive and industrial IoT due to carrier certification complexity and thermal durability requirements. Dielectric antennas represent the fastest-growing product category as ceramic-filled polymer processes enable 5G mmWave penetration in medical equipment housings.
FCC Part 15 testing protocols, CE marking under the EU Radio Equipment Directive, and MIIT radio transmission type approval in China collectively determine market access timelines and retooling costs for antenna suppliers. REACH substance restrictions and RoHS compliance further constrain substrate material selection, pushing manufacturers toward halogen-free laminates and low-temperature co-fired ceramic alternatives. Stakeholders must monitor spectrum reallocation proceedings in major economies and pre-position module designs for Wi-Fi 7 and 6G candidate bands before regulatory frameworks crystallize into mandatory certification paths.
Market Dynamics
Module-first RF architectures are compressing procurement timelines as automotive OEMs and smartphone manufacturers consolidate antenna-connector-modem sourcing into single-vendor relationships, eliminating discrete component qualification cycles.
Growth Catalysts
- MIIT type approval acceleration:China's streamlined radio transmission certification for 5G NR devices reduces time-to-market for domestic IoT manufacturers, pulling embedded antenna demand toward Shenzhen and Shanghai production clusters.
- Connected vehicle mandate expansion:Automotive OEMs in Germany and Japan are embedding cellular-V2X antennas directly into bumper substrates and mirror housings to satisfy emergency call regulations without external shark-fin protrusions.
- Ceramic-filled polymer processes:Dielectric antenna manufacturing is achieving sub-millimeter precision for mmWave medical imaging equipment, opening surgical robotics and portable diagnostic devices as new volume tiers.
Market Restraints
- Laminate substrate cost volatility:Halogen-free FR-4 and low-loss hydrocarbon materials face price pressure from epoxy resin supply disruptions concentrated in South Korean and Taiwanese chemical feedstock channels.
- Single-source ceramic powder concentration:High-purity barium titanate and magnesium titanate for dielectric antennas rely on Chinese raw material processors, creating geographic concentration risk for Murata and TDK supply chains.
- Thermal durability certification complexity:LTE-M and NB-IoT antennas for industrial IoT must satisfy extended temperature cycling under FCC Part 15 and ETSI EN 301 489, extending qualification timelines by 8-14 months for new entrants.
Strategic Opportunities
- Indian PLI scheme for telecom equipment:Production-linked incentives for 5G radio units and CPE devices are attracting Foxconn and Dixon to Gujarat and Tamil Nadu, creating localized antenna module demand outside traditional China-Taiwan supply corridors.
- Wi-Fi 7 spectrum allocation:The 6 GHz band expansion in the US, EU, and Japan enables tri-band antenna designs that command premium positioning in enterprise access points and gaming routers.
- Antenna-in-package integration:Co-design with millimeter-wave radar SoCs for autonomous vehicles merges 77-81 GHz automotive radar with 5G connectivity into single substrate solutions, collapsing BOM line counts for Tier-1 suppliers.
Industry Challenges
- Electromagnetic simulation talent scarcity:Finite-element modeling for multi-physics antenna optimization requires rare expertise in CST Studio and HFSS tools, constraining design service capacity at mid-tier EMS providers.
- Retrofit integration with legacy CAN bus architectures:Automotive electronics suppliers face software-defined radio compatibility issues when embedding cellular antennas into vehicles with 2015-2019 model year electrical platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Antenna Systems Market |
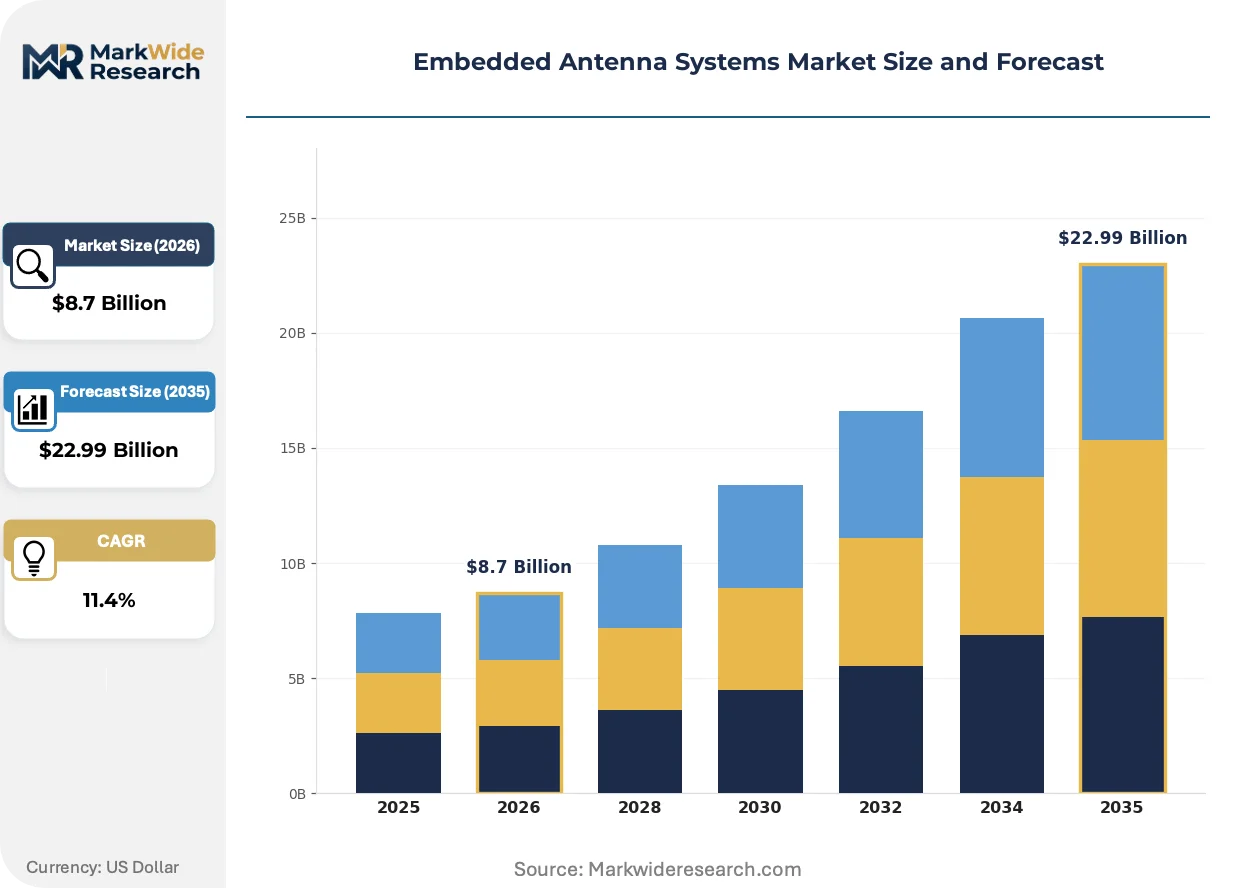
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCB Antennas, Dielectric Antennas, Fractal Antennas, Planar Antennas Technology: Wi-Fi, Bluetooth, NFC, LTE Application: Smart Devices, Automotive, Industrial IoT, Healthcare Devices End User: Telecommunications, Consumer Electronics, Medical Equipment, Aerospace |
| Companies Covered | TE Connectivity, Amphenol Corporation, Qualcomm, Taoglas, Antenova, Murata Manufacturing, Molex, NXP Semiconductors, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Antenna Systems Market Emerging Trajectories
Antenna subsystem integration is collapsing the traditional boundary between RF front-end and baseband processing, compressing supplier tiers and rewriting qualification protocols across consumer, automotive, and industrial verticals.
Chip-package-antenna co-design is migrating from reference platform demonstrations into production vehicle programs. Qualcomm and MediaTek are embedding adaptive impedance matching directly into modem firmware, allowing OEMs to substitute antenna vendors without recertifying baseband stacks. This migration from hardware-tuned to software-defined RF chains is compressing antenna supplier margins while accelerating platform consolidation.
REACH substance restrictions and RoHS recast directives in Europe are banning cadmium-based plating and certain brominated flame retardants from antenna substrates by 2026. Manufacturers are pivoting to electroless nickel immersion gold finishes and phosphorus-based flame retardants, with medical device and aerospace antenna suppliers facing the steepest retooling costs due to legacy qualification inertia.
Automotive procurement teams are consolidating antenna sourcing through direct RF module contracts rather than discrete component purchasing. Tier-1 suppliers including Bosch, Continental, and Denso are capturing antenna specification authority from OEM engineering departments, compressing the qualified vendor base and privileging partners with in-house electromagnetic simulation and rapid prototyping capabilities in Stuttgart, Nagoya, and Detroit engineering centers.
Embedded Antenna Systems Market Segmentation
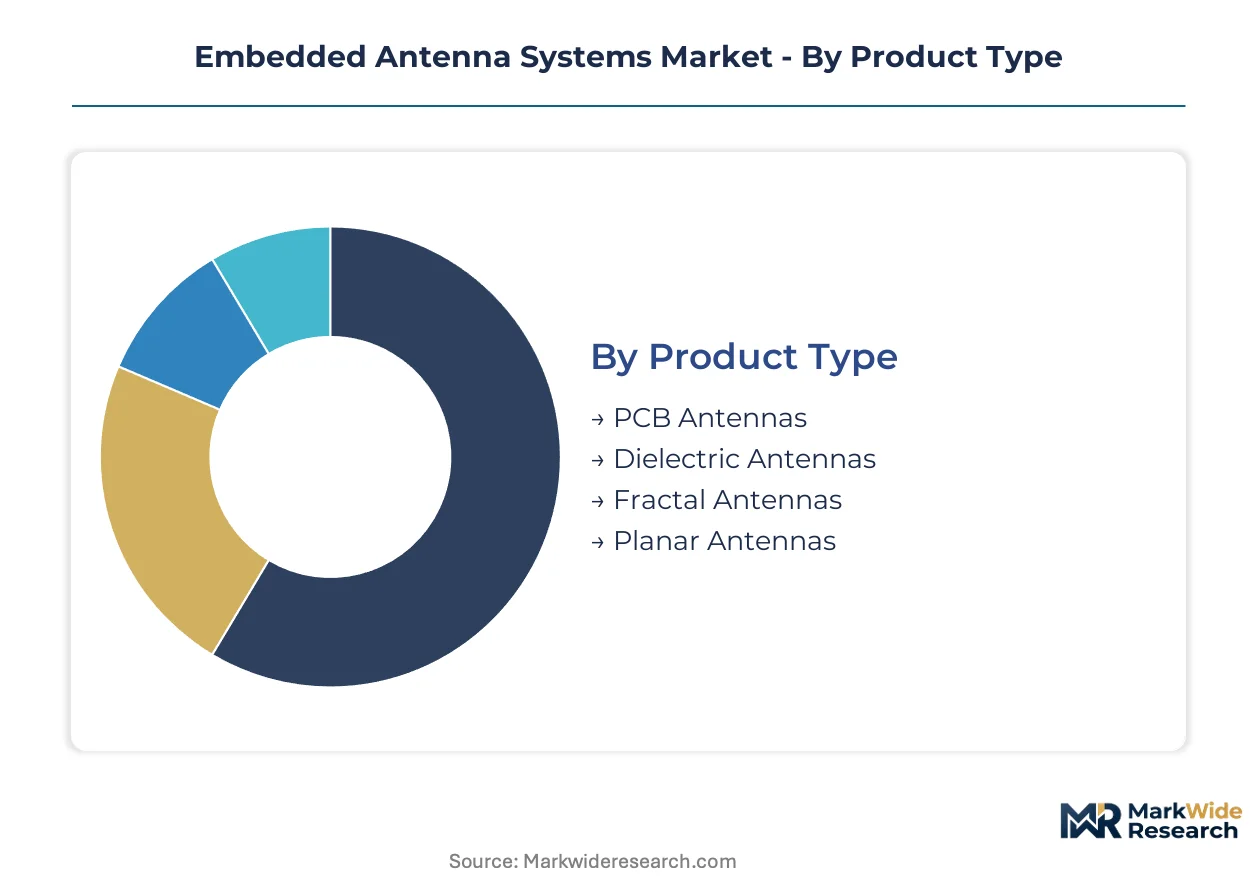
Embedded antenna procurement patterns diverge sharply across substrate technologies, wireless protocols, and end-use durability requirements. Each segmentation axis reveals distinct margin structures and certification barriers that reshape supplier positioning.
Product Type:
Cost tier stratification separates high-volume consumer electronics from premium automotive and medical applications where thermal cycling and precision tolerances command price premiums.
- PCB Antennas:These copper-etched radiating elements laminate onto standard FR-4 or low-loss hydrocarbon substrates, typically achieving 2-4 dBi gain across sub-6 GHz bands. Shenzhen and Dongguan manufacturing clusters absorb the highest procurement volumes for smartphone and tablet OEMs, though epoxy resin price volatility compresses margins for mid-tier suppliers.
- Dielectric Antennas:Ceramic-filled polymer substrates enable sub-millimeter precision for 5G mmWave penetration, with barium titanate formulations delivering stable permittivity across temperature extremes. Medical imaging equipment and surgical robotics in Germany and Japan drive premium demand for these components.
- Fractal Antennas:Self-similar geometric patterns miniaturize electrical length while maintaining bandwidth, suiting space-constrained IoT sensors.
- Planar Antennas:Flat radiating apertures integrate directly into device enclosures, common in aerospace radome applications requiring aerodynamic profiles.
PCB antennas hold installed capacity. Dielectric antennas are rotating up the share rankings.
Technology:
Application requirements determine protocol selection, with cellular certification complexity creating steeper barriers to entry than unlicensed alternatives.
- Wi-Fi:Tri-band 2.4/5/6 GHz designs dominate enterprise access point procurement, with FCC Part 15 and ETSI EN 301 893 compliance mandatory for US and EU market access. Gaming router manufacturers in Taipei and Seoul specify high-isolation antenna modules for 6 GHz band expansion.
- Bluetooth:Low-energy 2.4 GHz implementations saturate wearable and peripheral markets where cost-per-unit compression governs sourcing decisions.
- NFC:13.56 MHz inductive loops enable contactless payment and access control, with antenna coil precision determining read range consistency.
- LTE:Carrier certification under FCC Part 27 and MIIT radio transmission type approval extends qualification timelines, privileging incumbents with established operator relationships. Automotive eCall mandates in Germany and connected vehicle architectures in Japan sustain premium positioning.
LTE maintains certification moats. Wi-Fi is climbing fastest on 6 GHz band allocation.
Application:
Volume concentration varies by durability specification, with industrial and automotive segments demanding extended temperature ranges that consumer electronics ignore.
- Smart Devices:Smartphone and tablet OEMs specify sub-10 mm form factors with multi-band coexistence, driving PCB antenna volumes through Shenzhen production clusters.
- Automotive:Cellular-V2X integration into bumper substrates and mirror housings satisfies emergency call regulations without external protrusions, with Bosch and Continental consolidating RF module sourcing authority.
- Industrial IoT:NB-IoT and LTE-M antennas for factory automation must satisfy -40°C to +85°C cycling under ETSI EN 301 489.
- Healthcare Devices:Portable diagnostic equipment and surgical robotics specify dielectric antennas for 5G mmWave imaging, with REACH substance restrictions pushing halogen-free substrate adoption.
Smart Devices anchor volume scale. Healthcare Devices are expanding most quickly on medical robotics adoption.
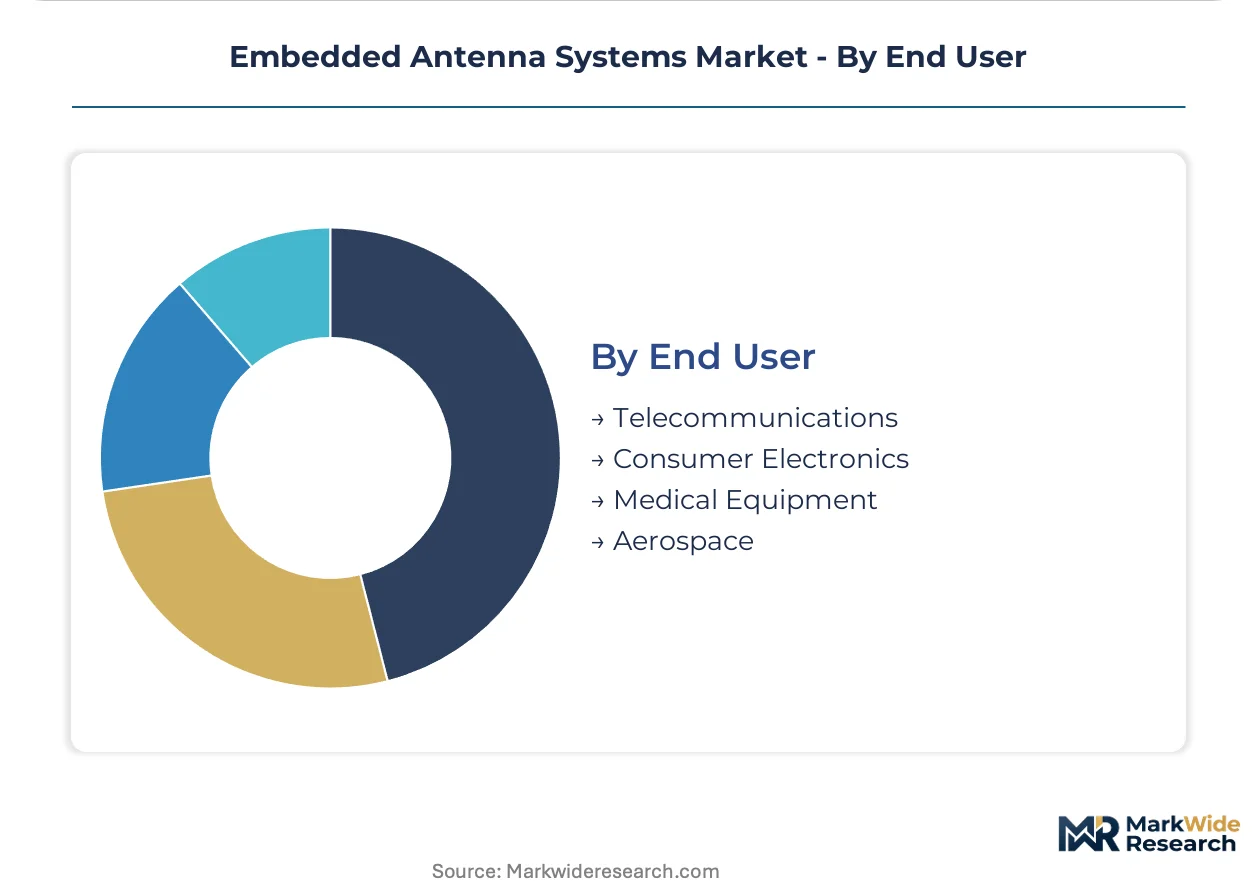
End User:
Customer procurement maturity separates consolidated module sourcing from discrete component purchasing across telecommunications infrastructure and consumer electronics.
- Telecommunications:5G base station and CPE manufacturers specify integrated antenna-connector-modem modules, with India's PLI scheme for telecom equipment attracting Foxconn and Dixon to Gujarat assembly.
- Consumer Electronics:Smartphone OEMs compress antenna-connector-modem sourcing into single-vendor relationships, eliminating discrete qualification cycles.
- Medical Equipment:Imaging and diagnostic device manufacturers face steepest retooling costs from RoHS recast directives banning cadmium plating.
- Aerospace:Radome-integrated planar antennas demand FAA and EASA certification for commercial aviation applications.
Telecommunications commands module consolidation. Medical Equipment is ascending on surgical robotics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in embedded antenna systems tilt heavily toward export-oriented manufacturing clusters, with component shipments from East Asian production hubs dominating inbound supply to North American and European assembly operations for automotive and telecommunications equipment.
China
Domestic 5G infrastructure buildouts and IoT device manufacturing clusters in Shenzhen and Shanghai generate sustained procurement pull for PCB and dielectric antennas. MIIT radio transmission type approval acceleration for 5G NR devices compresses certification timelines for domestic manufacturers. The Yangtze River Delta and Pearl River Delta concentrate the highest volume of antenna module production for global smartphone OEMs.
United States
Automotive OEMs in Michigan and California embed cellular-V2X antennas into bumper substrates to satisfy NHTSA emergency call regulations without external protrusions. FCC Part 15 rules for unlicensed RF devices shape certification requirements for Wi-Fi and Bluetooth implementations. The Detroit and Silicon Valley engineering corridors drive RF module integration into connected vehicle architectures.
Germany
Automotive eCall mandates and cellular-V2X integration requirements pull embedded antenna demand toward Stuttgart and Munich engineering centers. REACH substance restrictions and RoHS recast directives constrain substrate material selection, pushing manufacturers toward halogen-free laminates. Baden-Württemberg hosts concentrated electromagnetic simulation and rapid prototyping capabilities for Tier-1 suppliers.
Japan
Connected vehicle architectures and emergency call regulations sustain premium positioning for LTE-certified antennas in Nagoya and Tokyo automotive programs. METI industrial policy supports domestic ceramic substrate leadership for dielectric antenna manufacturing. The Chubu region around Nagoya anchors dielectric antenna supply for medical imaging equipment and surgical robotics.
India
Production-linked incentives for 5G radio units and CPE devices attract Foxconn and Dixon to Gujarat and Tamil Nadu assembly operations. TRAI spectrum allocation proceedings for 6 GHz Wi-Fi expansion create antenna module demand outside traditional China-Taiwan supply corridors. The Tamil Nadu and Gujarat manufacturing belts are emerging as localized antenna procurement sources for telecommunications infrastructure.
Embedded Antenna Systems Market Vendor Landscape
On the supply side, the industry is consolidating around module-first RF architectures that compress procurement timelines and eliminate discrete component qualification cycles. Tier-1 automotive suppliers and smartphone OEMs are consolidating antenna-connector-modem sourcing into single-vendor relationships, privileging partners with in-house electromagnetic simulation capabilities. Three archetypes dominate: connector-to-antenna integrators, ceramic substrate specialists, and modem-antenna co-design platforms. Competitive moves center on strategic partnerships for RF module bundling and geographic expansion into Indian PLI scheme corridors.
Within the connector-to-antenna integration tier, TE Connectivity and Molex exemplify suppliers capturing automotive RF module authority through direct OEM relationships. Murata Manufacturing and TDK Corporation occupy positions as ceramic substrate specialists anchoring dielectric antenna supply for precision-tolerance applications. Qualcomm represents the modem-antenna co-design archetype, embedding adaptive tuning into baseband reference platforms that compress antenna supplier margins while accelerating platform consolidation.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Qualcomm |
| Taoglas |
| Antenova |
| Murata Manufacturing |
| Molex |
| NXP Semiconductors |
| TDK Corporation |
| Others |
Supply Flow & Price Mechanics
Shenzhen and Dongguan manufacturing clusters absorb the highest PCB antenna volumes globally, and their epoxy resin cost volatility transmits directly into margin compression for mid-tier suppliers serving smartphone OEMs. This geographic concentration of laminate substrate capacity creates asymmetric pricing power that favors integrated module vendors over discrete component specialists.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for LTE-certified antennas, where FCC Part 27 and MIIT type approval tiers separate premium automotive sockets from economy IoT implementations. Cost compression in PCB antennas intensifies because epoxy resin supply disruptions from South Korean and Taiwanese chemical feedstock channels squeeze halogen-free FR-4 margins. Smartphone OEMs exhibit the highest price sensitivity, while medical imaging equipment manufacturers accept premium positioning for sub-millimeter dielectric precision.
Supply Chain Analysis
High-purity barium titanate and magnesium titanate feedstock draws from Chinese raw material processors, creating geographic concentration risk for ceramic substrate supply chains serving Murata and TDK manufacturing. Halogen-free laminates and low-temperature co-fired ceramic alternatives rest on Taiwanese and South Korean chemical channel stability. Single-source ceramic powder vulnerability threatens dielectric antenna output continuity. Distribution runs through Tier-1 automotive suppliers and smartphone OEM module consolidation programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded antenna procurement is shifting toward RF module bundling where electromagnetic simulation services and rapid prototyping capabilities generate recurring revenue expanding faster than hardware unit sales. Antenna subsystem integration collapses traditional component boundaries, creating attach opportunities for design-to-certification service layers.
For Market Incumbents: Insulate automotive RF module authority by deepening in-house electromagnetic simulation capabilities in Stuttgart, Nagoya, and Detroit engineering centers against Tier-1 supplier consolidation threats. Capture certification investment moats through early positioning for Wi-Fi 7 and 6G candidate bands before regulatory frameworks crystallize into mandatory paths. For New Entrants and Emerging Players: Build out antenna-in-package integration capabilities for millimeter-wave radar SoCs serving autonomous vehicle programs, where 77-81 GHz automotive radar merges with 5G connectivity into single substrate solutions. India's PLI scheme for telecom equipment offers the most penetrable geography, with Gujarat and Tamil Nadu assembly operations creating localized demand outside China-Taiwan corridors. Pursue direct RF module partnerships with Foxconn and Dixon rather than discrete component qualification cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant ceramic substrate divisions capable of pivoting toward dielectric antenna precision manufacturing for medical robotics. Long-term viability centers on software-defined RF chain migration and adaptive impedance matching firmware integration. Watch Qualcomm and MediaTek reference platform announcements as inflection indicators for antenna supplier margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Antenna-in-Package Integration | Co-design with 77-81 GHz automotive radar SoCs collapses BOM line counts for Tier-1 suppliers. |
| MIIT Certification Pre-Positioning | Early 5G NR type approval investment accelerates time-to-market for domestic IoT manufacturers in Shenzhen clusters. |
| Halogen-Free Substrate Transition | REACH and RoHS recast compliance opens premium positioning for electroless nickel immersion gold finish specialists. |
| Indian PLI Corridor Establishment | Gujarat and Tamil Nadu manufacturing belts localize antenna procurement for 5G radio unit and CPE assembly. |
| Electromagnetic Simulation Service Layer | CST Studio and HFSS expertise scarcity creates recurring revenue attach beyond hardware unit sales. |
Methodological Framework
The analysis maps PCB antenna, dielectric antenna, and antenna-in-package integration sub-sectors, each validated through RF front-end engineering directors, Tier-1 automotive procurement managers, and electromagnetic simulation specialists. Primary interviews with smartphone OEM antenna specification leads, medical device R&D heads, and telecommunications infrastructure planners combined with secondary validation from FCC Part 15 filings, MIIT radio transmission type approval databases, and ETSI EN standard documentation. Bottom-up shipment modeling and top-down value chain triangulation anchored volume estimates.
Assumption sets held fixed regulatory timelines for Wi-Fi 7 spectrum allocation while varying epoxy resin cost trajectories and ceramic powder supply continuity across the projection horizon. Segmentation dimensions modeled include substrate technology, wireless protocol certification tier, end-use durability specification, and geographic production cluster. CAGRs derived from historical shipment elasticities applied to projected 5G infrastructure buildout and connected vehicle mandate expansion curves. Millimeter-wave medical imaging equipment adoption and surgical robotics penetration served as demand-side forecast inputs.
Stress conditions across laminate substrate cost volatility, single-source ceramic powder disruption, and thermal durability certification timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and could revise substantially if REACH substance restrictions accelerate or if automotive eCall mandates expand beyond current regulatory jurisdictions. Cross-checking against MIIT 5G NR device approval velocity and NHTSA emergency call regulation implementation pace is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Phase Shifters Market
RF Components
RF Isolator Market
RF Components
High Reliability Oscillators Market
RF Components
Digital Phase Shifter Market
RF Components
Radio Frequency Counter Market
RF Components
RF-Microwave for 5G Market
RF Components
RF Antenna Market
RF Components
RF Tester Market
RF Components
Low Noise Amplifier Market
RF Components
RF Components Market
RF Components
Radio Frequency Duplexer Market
RF Components
Small Signal Mosfets Market
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
RF Power Amplifiers Market
RF Components
Radio Frequency Filters Market
RF Components
GPS Low Noise Amplifier Market