
 RF Transceiver Chip Market | 2026-2036
RF Transceiver Chip Market Size, Share, and Industry Trends Forecast 2026-2036
RF Transceiver Chip Market Outlook
Silicon-germanium is consolidating its position over legacy gallium arsenide in sub-6 GHz transceiver architectures, trimming die costs and simplifying CMOS integration for high-volume cellular applications. Qualcomm leverages vertical integration from modem to antenna to dominate premium smartphone sockets. Texas Instruments sustains broad catalog coverage across industrial and automotive radar bands. NXP Semiconductors anchors European automotive V2X programs with dedicated transceiver portfolios.
An RF transceiver chip is a mixed-signal integrated circuit that combines transmitter and receiver signal chains onto a single die, typically operating across frequency ranges from sub-GHz to millimeter-wave bands with power consumption measured in milliwatts per channel. The device modulates baseband digital signals to radio frequencies for transmission and performs inverse downconversion for reception, serving as the electromagnetic interface in virtually every wireless system. SoCs command the largest value pool by embedding baseband processing alongside RF front-ends, while software-defined transceivers represent the fastest-expanding technology category as field-upgradable architectures displace fixed-function designs in military and satellite communications. Standalone chips retain durable demand in test equipment and specialized industrial telemetry where customization outweighs integration economics.
The FCC in the United States, ETSI in Europe, and MIIT in China each enforce distinct spectrum allocation and emission mask standards that dictate transceiver bandwidth, linearity, and spurious suppression requirements across regional variants. REACH and RoHS frameworks in Europe further constrain material selections in packaging and solder metallurgy, elevating compliance costs for multi-region product families. Stakeholders must monitor spectrum auction outcomes and standardization timelines for 6G research bands to align R&D roadmaps with regulatory windows that will determine next-generation architecture winners.
Market Dynamics
Silicon-germanium process migration is compressing die economics across sub-6 GHz cellular architectures, forcing gallium arsenide foundries to defend legacy positions in defense and satellite niches where radiation tolerance still commands premium positioning.
Growth Catalysts
- 5G Massive MIMO Deployment:Base station densification in China and India is pulling multi-channel transceiver arrays into macro and small-cell infrastructure, with each site requiring 64+ integrated RF chains.
- Automotive Radar Mandates:NHTSA pedestrian safety regulations and Euro NCAP protocols are embedding 77-81 GHz transceivers into mid-range vehicle platforms as standard equipment.
- Spectrum Reallocation:FCC C-band auctions and MIIT 5G-Advanced band assignments are opening contiguous 400 MHz+ channels that demand wideband linearity previously reserved for military applications.
Market Restraints
- Compound Semiconductor Supply Concentration:Gallium nitride epitaxy capacity clusters in Taiwan and the United States, creating single-source vulnerability for millimeter-wave power amplifiers.
- REACH Material Restrictions:ECHA candidate list expansions targeting indium phosphide and certain gold-tin solders are forcing package redesigns for European automotive qualifications.
- Die-Area Cost Floor:FinFET mask sets at advanced nodes now exceed $15 million per reticle revision, freezing fabless entrants below 10,000 wafer starts per month.
Strategic Opportunities
- India Telecom Infrastructure:BSNL and private operator 5G rollouts are creating first-mover openings for domestic system integrators seeking non-Chinese RF sourcing.
- LEO Satellite Constellations:Ka-band and Q/V-band user terminals require phased-array transceivers with beam-steering ASICs, opening volume sockets outside terrestrial cellular economics.
- Software-Defined Radio Convergence:FPGA-RFSoC integration from Xilinx and Altera is collapsing discrete transceiver counts in military test equipment, with field upgradability extending platform lifecycles.
Industry Challenges
- Millimeter-Wave Calibration Expertise:Sub-6 GHz design talent pools inadequately cover 28 GHz and 39 GHz path loss modeling, forcing recruitment from satellite communications and radar backgrounds.
- Multi-Region Certification Parallelism:Simultaneous FCC, ETSI, and SRRC approval tracks for 5G NR devices extend time-to-revenue by 8-14 months for new transceiver variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Transceiver Chip Market |
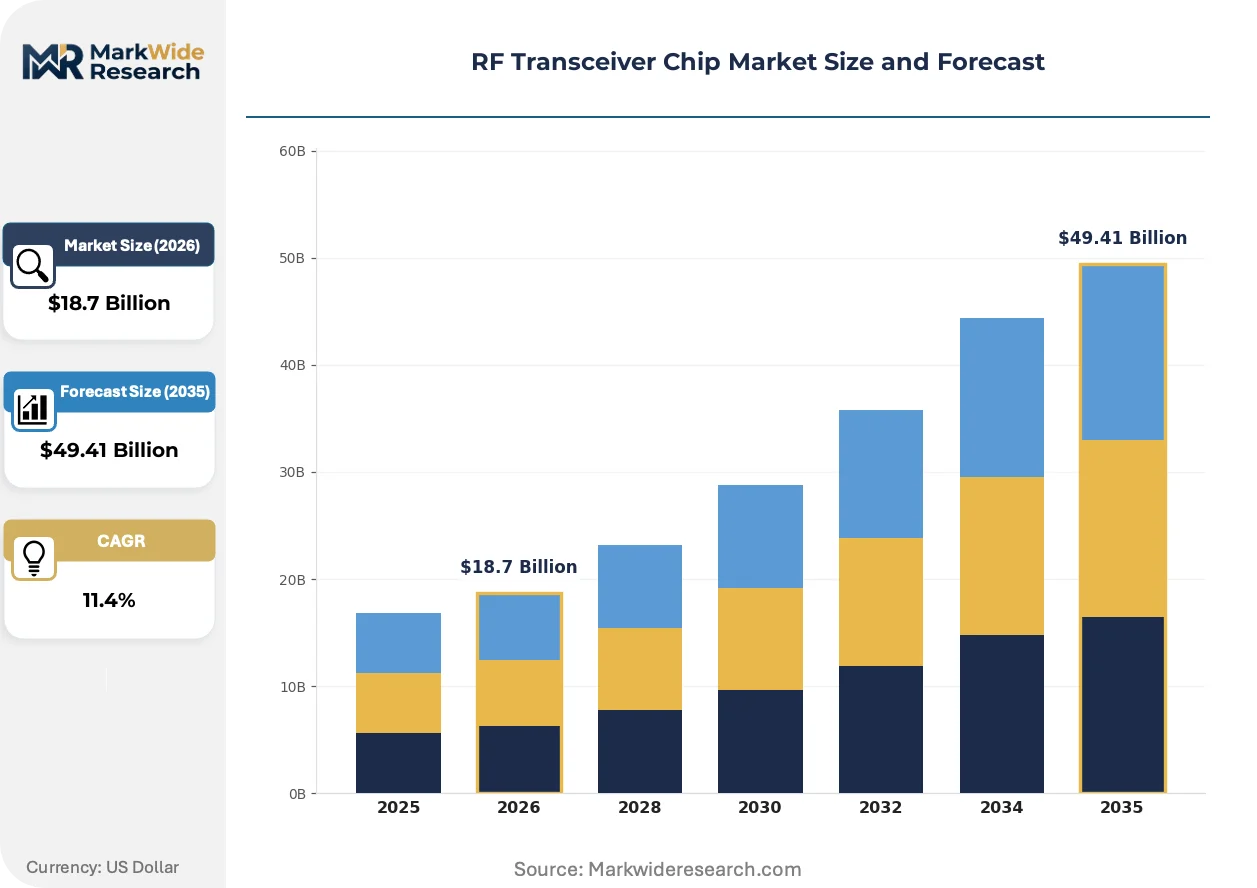
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Chips, Standalone Chips, Modules, SoCs Technology: Analog, Digital, Mixed-Signal, Software Defined End User: Telecommunications, Consumer Electronics, Automotive, Industrial Application: Wireless Communication, IoT Devices, Smart Grid, Telemetry |
| Companies Covered | Qualcomm, Texas Instruments, NXP Semiconductors, Broadcom, Analog Devices, Skyworks Solutions, Qorvo, STMicroelectronics, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Transceiver Chip Market Strategic Shifts
RF front-end integration is accelerating beyond discrete transceivers toward antenna-in-package modules, with baseband-to-antenna consolidation eliminating board-level matching networks and trimming bill-of-materials complexity.
Digital pre-distortion engines embedded in CMOS transceivers are modularizing power amplifier linearization, allowing handset OEMs to source PAs from second-tier suppliers without sacrificing adjacent-channel leakage performance. Baseband processor vendors now bundle DPD IP as standard, collapsing the historical RF subsystem vendor count from five to two dominant socket holders.
ETSI Reconfigurable Radio Systems standards are mandating cognitive spectrum sensing for 6 GHz Wi-Fi 6E and 7 devices, forcing transceiver architectures to embed real-time interference detection without dedicated companion chips. European router and CPE manufacturers must certify against EN 303 687, adding 4-6 weeks to hardware validation cycles compared to FCC-only variants.
Automotive OEMs now specify transceiver lifetime buy guarantees stretching 15 years, compressing supplier selection to foundries with demonstrated longevity in industrial and aerospace programs. Tier-1 module houses in Germany and Japan are consolidating RF sourcing to single-vendor relationships with wafer-level burn-in documentation, displacing multi-source commodity strategies that dominated 4G telematics procurement.
RF Transceiver Chip Market Segmentation
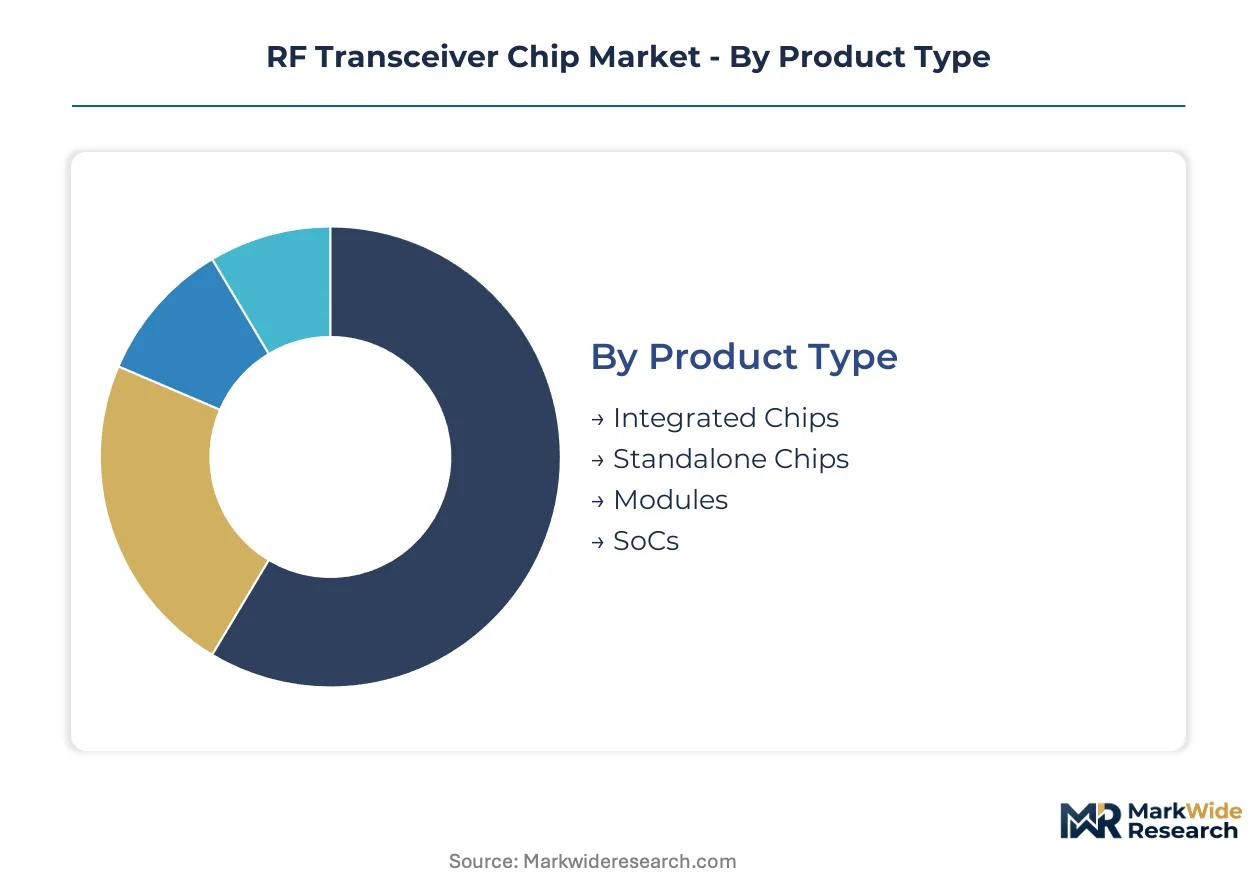
RF transceiver procurement decisions hinge on integration depth versus customization flexibility. Buyers weigh die economics against regulatory certification burdens across cellular, automotive, and satellite verticals.
Product Type:
System architects select integration tiers based on volume scale and time-to-market pressure.
- Integrated Chips:Multi-function dies combine LNA, mixer, and synthesizer blocks for cellular handsets. Procurement concentrates with Qualcomm and MediaTek modem platforms where baseband-RF co-design trims board area.
- SoCs:Baseband processors with embedded transceiver chains dominate 5G smartphone sockets. China MIIT domestic integration programs are reshaping supplier qualification lists toward local design houses.
- Standalone Chips:Discrete transmitters and receivers serve test equipment and military radios where frequency agility outweighs cost optimization.
- Modules:Pre-certified RF front-end assemblies accelerate router and CPE development for Wi-Fi 6E certification deadlines.
SoCs lead on scale; Modules lead on momentum.
Technology:
Process node selection determines linearity, power consumption, and foundry access.
- Mixed-Signal:CMOS transceivers with integrated ADC/DAC arrays dominate sub-6 GHz cellular infrastructure. Deployment accelerates in India BSNL 5G rollouts where cost-per-channel drives procurement.
- Software Defined:Field-programmable architectures with FPGA-RFSoC integration collapse discrete component counts. Military test equipment and satellite ground stations adopt these for waveform upgradability.
- Analog:Traditional superheterodyne architectures persist in aerospace applications where radiation tolerance exceeds digital integration benefits.
- Digital:All-digital RF transmitters using RF-DAC topologies emerge in research programs for 6G waveform flexibility.
Mixed-Signal dominates volume; Software Defined climbs fastest.
End User:
Vertical-specific certification cycles and lifetime requirements shape supplier relationships.
- Telecommunications:Base station OEMs demand 64+ channel transceiver arrays per massive MIMO panel. China and India infrastructure programs pull silicon-germanium die into macro and small-cell deployments.
- Automotive:NHTSA pedestrian safety mandates embed 77-81 GHz radar transceivers into mid-range platforms. European OEMs require 15-year lifetime buy guarantees, compressing sourcing to qualified foundries.
- Consumer Electronics:Smartphone RF front-ends prioritize die shrink and carrier aggregation support for FCC C-band and MIIT 5G-Advanced bands.
- Industrial:Telemetry and process control applications favor wideband linearity over integration density in oilfield and utility deployments.
Telecommunications leads on scale; Automotive leads on momentum.
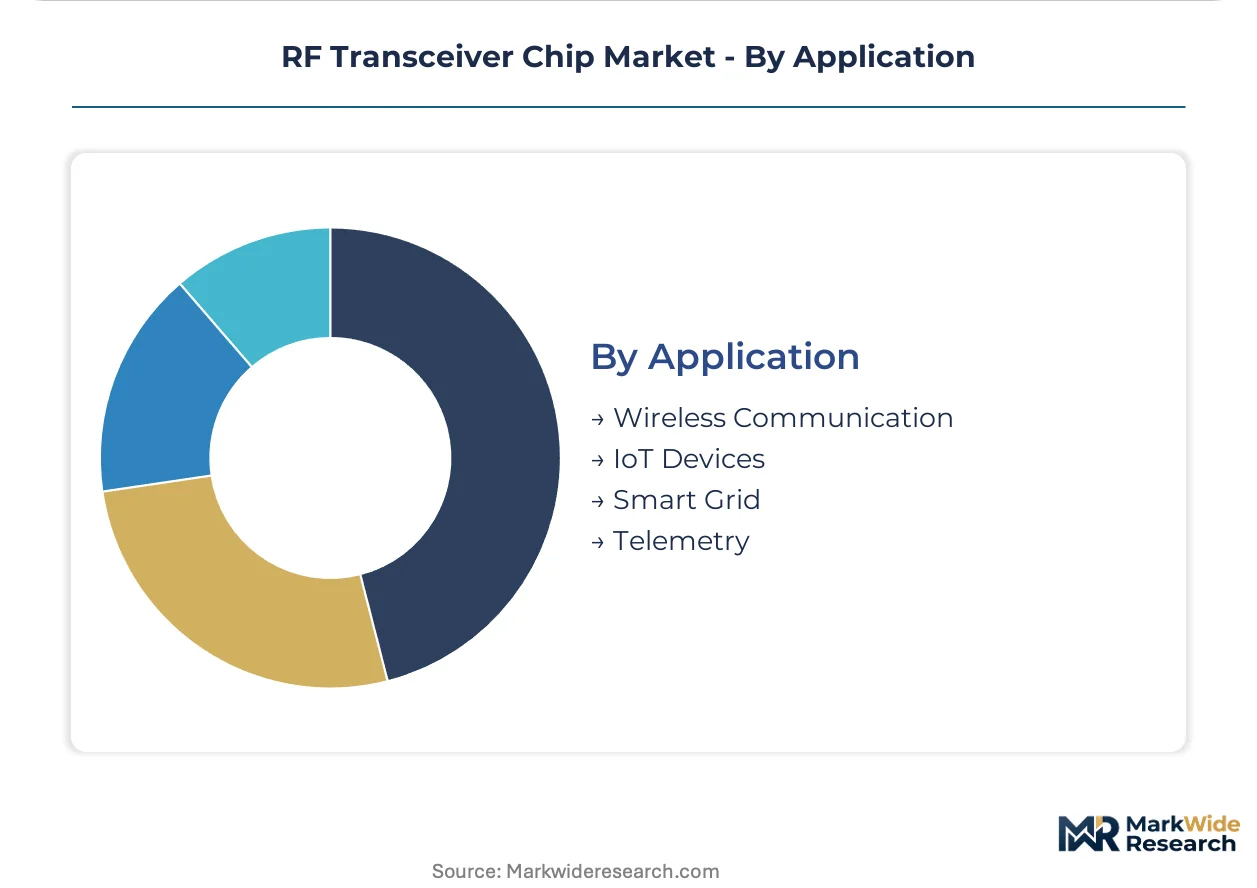
Application:
Spectrum allocation and link reliability requirements determine architecture selection.
- Wireless Communication:Cellular and Wi-Fi transceivers absorb the highest unit volumes. FCC C-band auctions and ETSI 6 GHz standards mandate wideband architectures with 400 MHz+ contiguous channels.
- IoT Devices:Sub-GHz and 2.4 GHz transceivers for LPWAN and mesh networks prioritize sleep-mode power draw over peak data rates.
- Smart Grid:Utility AMI deployments require ruggedized transceivers with 10+ year field life in substation and meter infrastructure.
- Telemetry:Industrial and aerospace data links demand specialized modulation formats outside cellular standards, preserving standalone chip demand.
Wireless Communication leads on scale; IoT Devices leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Pudong New Area anchors the world's densest concentration of RF transceiver design houses and foundry partnerships. The United States maintains critical GaN epitaxy capacity for millimeter-wave power amplifiers. Germany's automotive tier-1 ecosystem drives qualification standards for 15-year lifetime transceiver guarantees.
United States
FCC C-band spectrum auctions and 5G-Advanced infrastructure buildouts drive transceiver procurement for macro base stations. NHTSA pedestrian safety mandates embed 77-81 GHz radar chips into vehicle platforms. Austin and San Diego clusters host fabless design centers supplying defense and satellite communication programs.
China
MIIT domestic integration programs reshape supplier qualification lists toward local baseband-to-RF SoC houses. BSNL-scale 5G rollouts absorb multi-channel transceiver arrays for massive MIMO panels. Shenzhen and Beijing design centers concentrate talent for sub-6 GHz cellular and emerging 6G research bands.
Germany
Euro NCAP protocols and REACH material restrictions compress automotive RF sourcing to qualified foundries with wafer-level burn-in documentation. ETSI Reconfigurable Radio Systems standards mandate cognitive spectrum sensing for Wi-Fi 6E certification. Munich and Stuttgart clusters anchor European V2X program supply chains.
India
BSNL and private operator 5G infrastructure programs create first-mover openings for domestic system integrators seeking non-Chinese RF sourcing. TRAI spectrum allocation timelines align with silicon-germanium die procurement for cost-per-channel optimization. Bengaluru and Hyderabad design centers concentrate talent for sub-6 GHz base station architectures.
South Korea
5G-Advanced handset refresh cycles and carrier aggregation requirements drive premium smartphone transceiver socket competition. MFDS equipment certification parallels FCC and ETSI approval tracks for export-bound devices. Seoul Capital Area fabs maintain advanced-node CMOS capacity for integrated modem-RF platforms.
RF Transceiver Chip Market Competitive Environment
Global majors compete with regional champions across spectrum access and foundry partnerships. The vendor base stratifies into three tiers: integrated platform providers controlling modem-to-antenna stacks, catalog suppliers spanning industrial and automotive bands, and specialized houses serving defense and satellite niches. Dominant competitive moves include backward integration into GaN epitaxy capacity and strategic partnerships with India-based system integrators seeking non-Chinese sourcing.
Within the integrated platform tier, Qualcomm and MediaTek exemplify modem-RF co-design architectures that trim board area for smartphone OEMs. Texas Instruments occupies a position spanning industrial radar and automotive telemetry bands with broad catalog coverage. NXP Semiconductors anchors European automotive V2X qualification programs with dedicated transceiver portfolios and demonstrated longevity in 15-year lifetime buy guarantees.
| Leading Market Players |
|---|
| Qualcomm |
| Texas Instruments |
| NXP Semiconductors |
| Broadcom |
| Analog Devices |
| Skyworks Solutions |
| Qorvo |
| STMicroelectronics |
| Infineon Technologies |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between automotive-qualified and consumer-grade transceivers manifests in both unit economics and foundry allocation patterns, with REACH-compliant packaging and 15-year lifetime guarantees commanding 40-60% premiums over handset-optimized variants while concentrating procurement among German and Japanese tier-1 module houses with wafer-level burn-in documentation.
Pricing Analysis
Input-cost pass-through from gallium nitride epitaxy and advanced FinFET mask sets shapes contract structures across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates automotive V2X-qualified sockets from industrial radar bands and commodity handset RF front-ends. Pricing pressure stems from silicon-germanium die economics compressing sub-6 GHz margins as China MIIT domestic integration programs accelerate local sourcing. Handset OEMs exhibit highest price sensitivity, while automotive tier-1s prioritize lifetime buy guarantees over unit cost.
Supply Chain Analysis
Certification and qualification gating restricts automotive RF sourcing to foundries with demonstrated longevity in aerospace and industrial programs. Taiwan, South Korea, and the United States anchor gallium nitride epitaxy and advanced CMOS capacity. Raw material dependencies center on germanium substrates, indium phosphide, and gold-tin solder metallurgies constrained by REACH candidate list expansions. Single-source vulnerability clusters in Taiwan-based GaN foundry capacity. Distribution runs through authorized tier-1 module houses in Germany and Japan with wafer-level traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon-germanium process migration and antenna-in-package consolidation create margin-expansion headroom for suppliers mastering sub-6 GHz integration economics.
For Market Incumbents: Acquire GaN epitaxy capacity to secure millimeter-wave power amplifier supply amid Taiwan concentration risk. Defend automotive sockets by embedding 15-year lifetime documentation and REACH-compliant packaging ahead of Euro NCAP mandate expansions. Prioritize backward integration into silicon-germanium foundry partnerships as China MIIT programs displace foreign baseband-RF integration. For New Entrants and Emerging Players: Enter via India BSNL and private operator 5G infrastructure programs where non-Chinese sourcing requirements create first-mover openings for domestic system integrators. Target sub-6 GHz base station transceiver arrays for cost-per-channel optimization against Qualcomm and MediaTek modem platforms. Pursue qualification partnerships with German automotive tier-1s seeking second-source diversity for V2X programs. For Investors and Strategic Acquirers: Consolidation pressure builds where fabless design houses lack captive GaN capacity or automotive qualification track records. Long-term viability favors suppliers with demonstrated longevity in 15-year lifetime programs and multi-region certification parallelism. Watch for FCC 6G research band standardization timelines as inflection indicator for next-generation architecture winners.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Epitaxy Capacity Acquisition | Captive supply of millimeter-wave power amplifiers reduces Taiwan single-source vulnerability for defense and satellite programs. |
| Automotive Qualification Investment | REACH-compliant packaging and wafer-level burn-in documentation unlock 15-year lifetime buy guarantees from German OEMs. |
| India System Integrator Partnership | Non-Chinese RF sourcing requirements from BSNL 5G rollouts create volume sockets outside established Qualcomm-MediaTek dominance. |
| Antenna-in-Package Module Development | Baseband-to-antenna consolidation eliminates board-level matching networks and trims bill-of-materials complexity for smartphone OEMs. |
| Software-Defined Radio Platform Launch | FPGA-RFSoC integration collapses discrete transceiver counts in military test equipment and extends platform lifecycles through field upgradability. |
Study Parameters
Bottom-up telecommunications infrastructure modeling reconciled against top-down semiconductor foundry tracking forms the analytical core. Primary interviews with base station OEM procurement directors, automotive tier-1 RF engineers, fabless design house CTOs, and foundry account managers combined with secondary validation from FCC spectrum auction records, MIIT 5G-Advanced band assignments, ETSI Reconfigurable Radio Systems standards documentation, and SEC 10-K filings from listed semiconductor suppliers.
Input-output matrices map transceiver channel counts per massive MIMO panel against silicon-germanium die economics and GaN epitaxy capacity utilization across the projection horizon. Segmentation dimensions span integration depth, process technology, end-use vertical, and regional regulatory cluster. CAGRs derive from unit-volume buildups by application crossed with average selling price trajectories tied to node migration and certification tier.
Inputs from ETSI standardization committees and India TRAI spectrum allocation timelines were available through the study window; gaps in China MIIT domestic integration program procurement data introduce uncertainty bands around local supplier market share assumptions. Deviation in FCC 6G research band auction timing or REACH candidate list expansion pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Multiband Booster Market
RF Components
Dielectric Resonator Market
RF Components
High-Power Microwave Source Market
RF Components
High-Frequency RF Evaluation Board Market
RF Components
RF Duplexer Market
RF Components
Flat Panel Antenna Market
RF Components
Space Traveling Wave Tube Amplifiers Market
RF Components
Coaxial Splitters Market
RF Components
RF Microwave MLCC Market
RF Components
Toroid Inductor Market
RF Components
Radio Frequency (RF) Signal Generators Market
RF Components
SMD Resonator Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
Silicon Tuners Market
RF Components
Americas Small Signal Transistor Market