
 Spinal and Bulbar Muscular Atrophy Treatment Market | 2026-2036
Spinal and Bulbar Muscular Atrophy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal and Bulbar Muscular Atrophy Treatment Market Insights
A shortage of neurogeneticists with rare-disease trial expertise is unwinding the pace of site activation for SBMA studies. Pfizer Inc leverages its established rare-disease infrastructure to sustain early-phase programs. Boehringer Ingelheim International GmbH anchors its neurology pipeline through specialized research partnerships. Takeda Pharmaceutical Company Limited competes by extending its global reach into underserved patient populations.
Spinal and Bulbar Muscular Atrophy treatment encompasses therapeutic interventions targeting the polyglutamine expansion in the androgen receptor gene, including antisense oligonucleotides designed to silence mutant transcript expression and small-molecule androgen receptor degraders formulated to clear toxic protein aggregates from motor neurons. The primary purpose centers on slowing or halting lower motor neuron degeneration while preserving bulbar and limb function in affected individuals. Antisense oligonucleotides currently occupy the most advanced clinical position among product types, though gene therapy approaches attract the deepest R&D investment due to their potential for single-administration disease modification. Intravenous delivery dominates present treatment administration, while intrathecal routes gain investigator attention for achieving higher central nervous system drug exposure.
The FDA Orphan Drug Designation program shapes development economics through tax incentives and market exclusivity provisions, while the EMA's parallel designation streamlines European access pathways for emerging therapies. Japan's PMDA operates a Sakigake fast-track framework that prioritizes review for first-in-class neurology treatments. Stakeholders must weigh manufacturing scalability against the small addressable patient population when committing to platform investments.
Market Dynamics
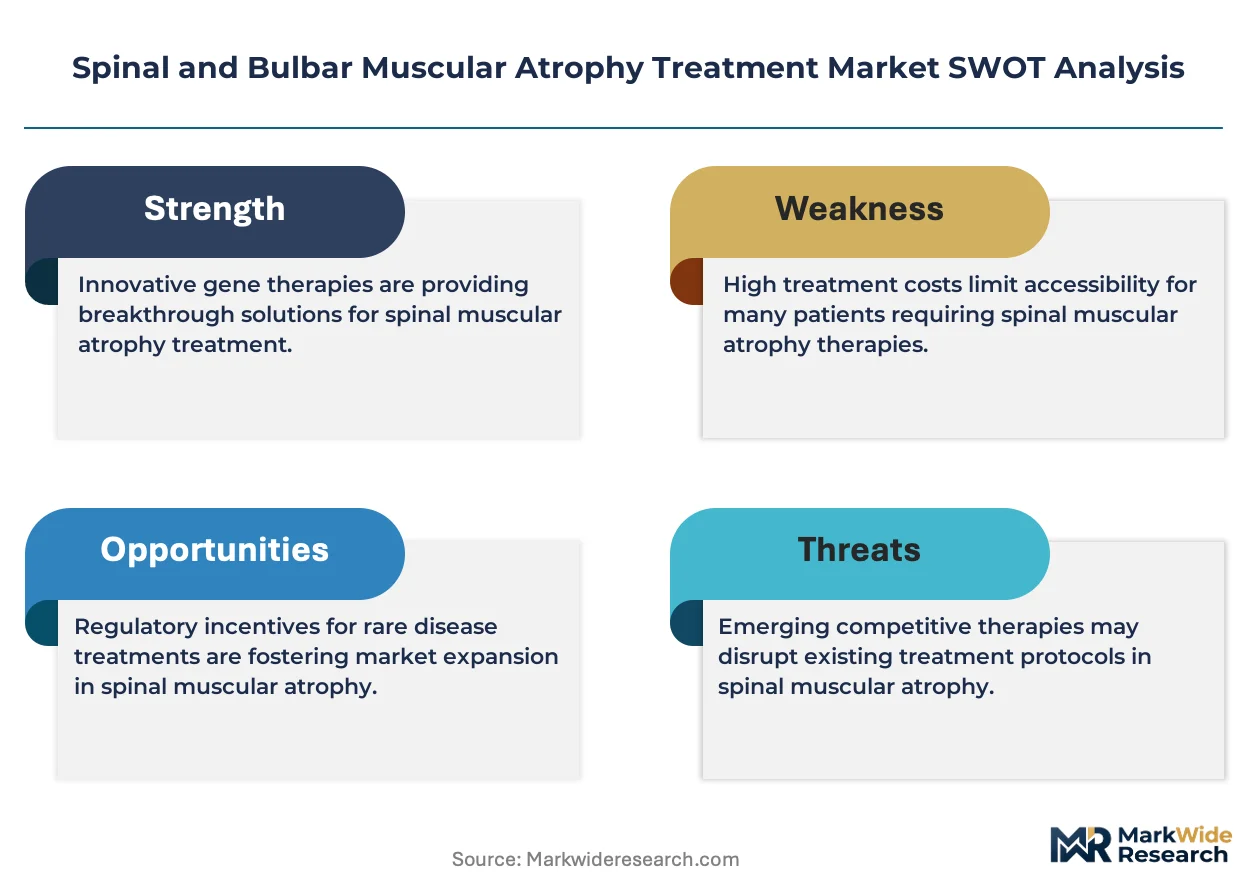
The SBMA treatment landscape pivots on the tension between ultra-orphan patient economics and the capital intensity of neurodegenerative drug development, with antisense oligonucleotide manufacturing costs constraining program viability despite strong unmet need.
Growth Catalysts
- FDA Orphan Drug Designation:Tax credits and market exclusivity provisions de-risk early-stage investment for developers targeting the polyglutamine expansion mechanism. Biotechnology firms prioritize SBMA programs within rare-disease portfolios.
- Intravenous-to-intrathecal delivery evolution:Cerebrospinal fluid administration protocols enable higher motor neuron drug exposure. Academic medical centers in the United States pioneer site-specific injection techniques.
- Patient registry maturation:The United States hosts the largest longitudinal SBMA cohort databases. Natural history data accelerates biomarker validation and endpoint selection for registrational trials.
Market Restraints
- Neurogeneticist scarcity:Rare-disease trial expertise concentrates at fewer than forty academic sites worldwide. Site activation timelines extend eighteen to thirty-six months.
- Antisense manufacturing scale limits:Oligonucleotide synthesis requires specialized solid-phase chemistry capacity. Contract manufacturers prioritize larger indications, creating queue bottlenecks.
- Androgen receptor biology complexity:Wild-type receptor performs essential physiological functions. Selective mutant silencing without hormonal disruption remains technically unproven.
Strategic Opportunities
- Japan PMDA Sakigake fast-track:First-in-class neurology treatments receive priority review and early reimbursement dialogue. Developers gain accelerated access to the second-largest pharmaceutical market.
- Gene therapy single-administration potential:Adeno-associated viral vectors targeting androgen receptor knockdown promise durable disease modification. Manufacturing scale economics favor one-time interventions over chronic dosing.
- Neurology specialty clinic expansion:Dedicated rare disease centers consolidate diagnosis, genetic counseling, and trial access. Patients bypass fragmented general neurology referrals.
Industry Challenges
- Biomarker qualification timelines:Neurofilament light chain and other candidate markers lack regulatory validation. Endpoint uncertainty prolongs Phase II to Phase III transitions.
- Cross-border trial coordination:Genetic testing protocols, informed consent standards, and data privacy requirements fragment across jurisdictions. Multinational enrollment requires redundant ethics submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal and Bulbar Muscular Atrophy Treatment Market |
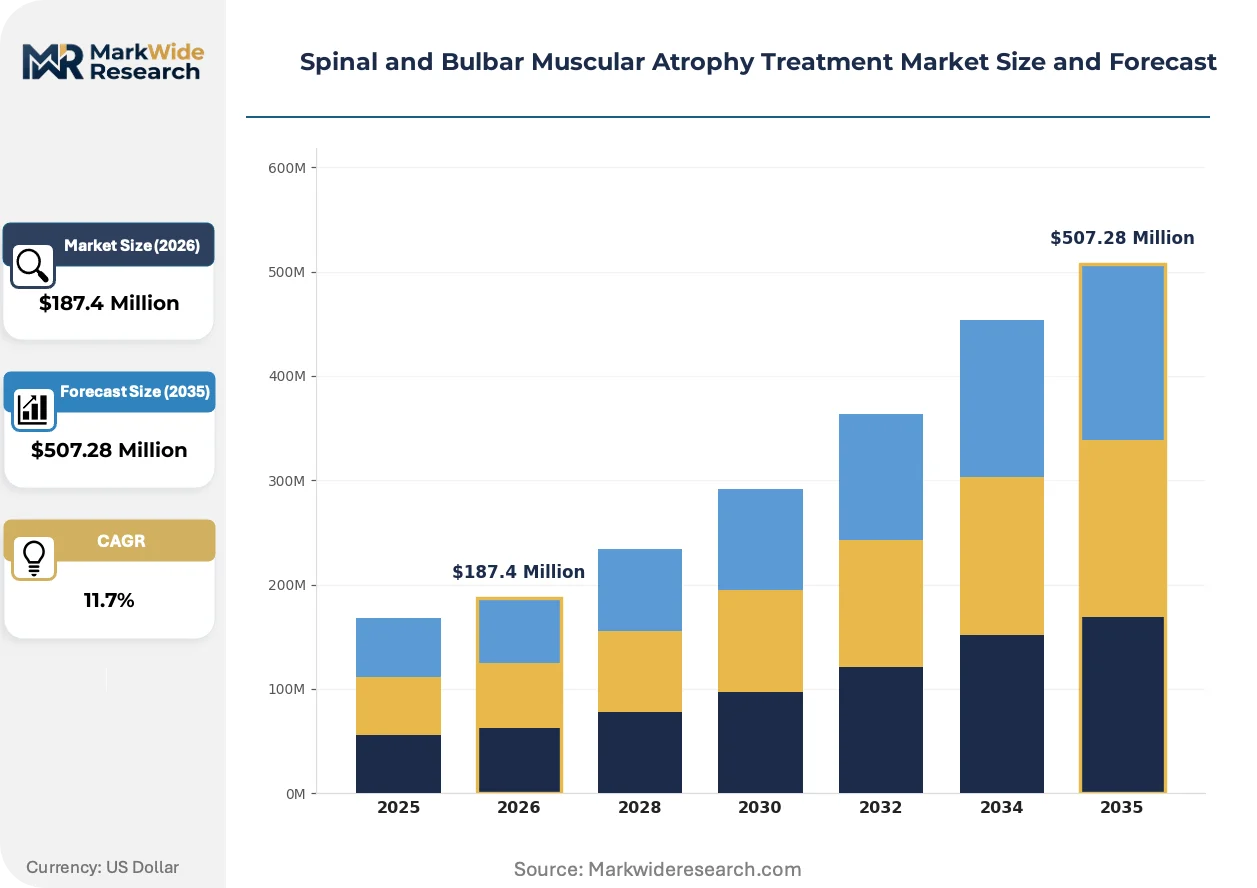
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Antisense Oligonucleotides, Small Molecules, Protein Replacement Delivery Mode: Intravenous, Subcutaneous, Intrathecal, Oral End User: Hospitals, Specialty Clinics, Home Care Settings, Research Institutions Application: Symptomatic Relief, Disease Modification, Supportive Care, Clinical Trials |
| Companies Covered | GlaxoSmithKline plc, AbbVie Inc, Takeda Pharmaceutical Company Limited, Century Pharmaceuticals Ltd, Johnson and Johnson, Astellas Pharma, Pfizer Inc, Boehringer Ingelheim International GmbH, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal and Bulbar Muscular Atrophy Treatment Market Trends and Innovations
Antisense oligonucleotide chemistry is bifurcating the development pipeline, separating next-generation backbone modifications from established gapmer architectures. Regulatory science and patient access models are co-evolving to match these technical trajectories.
Next-generation stereopure oligonucleotide chemistry is bifurcating competitive positioning between precision backbone manufacturers and conventional suppliers. Biopharmaceutical sponsors evaluate stereochemical control for enhanced potency and reduced off-target effects. The technology is bifurcating investment flows toward platforms demonstrating differentiated central nervous system penetration.
EMA's parallel orphan designation framework streamlines European access pathways for emerging therapies. Developers gain unified scientific advice and accelerated assessment procedures. Small biotechnology firms lacking EU regulatory infrastructure partner with established rare-disease marketers to navigate centralized procedures.
Patient advocacy organizations now coordinate directly with contract research organizations for trial awareness and retention. Traditional physician-referral channels face displacement from digital recruitment platforms and direct-to-patient outreach. The United States demonstrates the most mature advocacy-CRO collaboration models, with European patient groups rapidly adopting similar structures.
Spinal and Bulbar Muscular Atrophy Treatment Market Segmentation
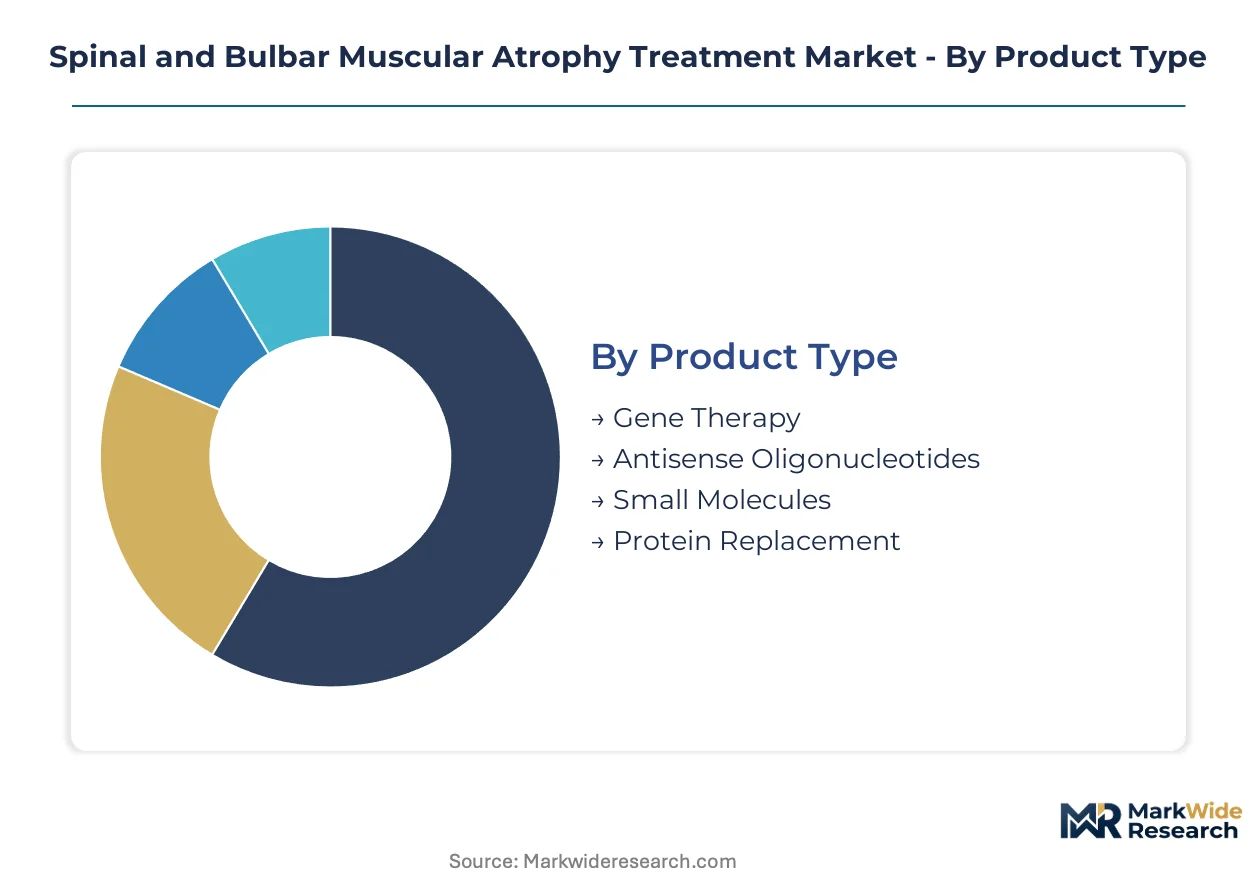
Segmentation in SBMA treatment reveals how therapeutic modality, administration route, and care setting intersect with patient disease stage and clinical infrastructure. These divisions expose where development capital concentrates and which access pathways face structural constraints.
Product Type:
Domestic R&D investment in the United States and Japan dominates gene therapy and antisense programs, while small-molecule development spreads across European contract research networks.
- Gene Therapy:Adeno-associated viral vectors deliver androgen receptor knockdown sequences for single-administration disease modification. Manufacturing scale economics favor one-time interventions, with the United States hosting the majority of active vector production facilities. Patient advocacy groups in North America drive early-phase trial enrollment for this modality.
- Antisense Oligonucleotides:Synthetic nucleic acid strands silence mutant androgen receptor transcript expression through RNase H-mediated degradation. Gapmer and stereopure chemistries compete for CNS penetration advantage. The FDA's Orphan Drug Designation program accelerates timelines for developers targeting this mechanism.
- Small Molecules:Oral androgen receptor degraders and modulators target protein clearance with simpler distribution logistics than biologics.
- Protein Replacement:Exogenous protein supplementation addresses secondary deficiency states in advanced disease stages.
Antisense oligonucleotides command the established base. The steepest expansion trajectory runs through gene therapy.
Delivery Mode:
Cost tier separation distinguishes hospital-based infusion services from outpatient self-administration, with intrathecal delivery commanding premium reimbursement due to specialized neuraxial access requirements.
- Intravenous:Peripheral vascular administration of antisense oligonucleotides enables systemic distribution with established nursing protocols. United States academic medical centers have standardized infusion scheduling for SBMA cohorts. Home infusion services are expanding to reduce site-of-care costs.
- Intrathecal:Direct cerebrospinal fluid delivery achieves higher motor neuron drug exposure than systemic routes. Specialized neuraxial access centers in Japan and Germany pioneer lumbar puncture and intrathecal catheter techniques for chronic dosing.
- Subcutaneous:Self-administered injection reduces clinic dependency for maintenance dosing of small molecules and some oligonucleotide formulations.
- Oral:Simplest patient adherence profile but limited bioavailability for large-molecule therapeutics targeting CNS pathology.
Intravenous delivery commands the established base. The steepest expansion runs through intrathecal administration as CNS exposure optimization becomes a clinical priority.
End User:
Patient volume concentrates at sites with neurogeneticist staffing and genetic counseling capabilities, creating geographic concentration of diagnosis and trial access.
- Specialty Clinics:Dedicated neuromuscular centers consolidate SBMA diagnosis, multidisciplinary care, and clinical trial access. The United States hosts the largest concentration of these facilities, with fewer than forty academic sites worldwide possessing rare-disease trial expertise. Neurology specialty clinic expansion is accelerating patient identification.
- Hospitals:General medical centers provide acute complication management and initial diagnostic workup. Inpatient gene therapy administration requires specialized pharmacy and intensive care capabilities available at tertiary referral hospitals in major metropolitan areas.
- Home Care Settings:Nurse-administered subcutaneous and oral therapies shift chronic management away from institutional sites.
- Research Institutions:Academic medical centers with NIH or equivalent funding maintain natural history cohorts and first-in-human trial capacity.
Hospitals command the established base. The steepest expansion runs through specialty clinics as rare disease capabilities consolidate.
Application:
Maturity separation distinguishes decades-old supportive care protocols from emerging disease-modifying approaches still seeking regulatory validation.
- Disease Modification:Therapies targeting the polyglutamine expansion mechanism aim to slow or halt lower motor neuron degeneration. Antisense oligonucleotides and gene therapy vectors represent the primary investigative modalities. Regulatory endpoints remain under negotiation between sponsors and the FDA.
- Symptomatic Relief:Androgen deprivation, muscle cramp management, and respiratory support address manifest disease burden. Established protocols in Japan and Europe provide the clinical foundation for comparative effectiveness studies of novel therapeutics.
- Supportive Care:Multidisciplinary management of swallowing dysfunction, mobility limitation, and respiratory insufficiency maintains function in advanced disease.
- Clinical Trials:Experimental therapy access concentrates at sites with biomarker validation capabilities and longitudinal cohort infrastructure.
Symptomatic relief commands the established base. The steepest expansion runs through disease modification as mechanistic understanding enables targeted intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies with mature neurogenetic infrastructure and those relying on general neurology referrals. The United States concentrates disease-modifying trial enrollment, while Japan and Germany optimize intrathecal delivery protocols. Emerging markets remain dependent on symptomatic management pathways.
United States
The NIH maintains the largest longitudinal SBMA patient registries, accelerating biomarker validation for registrational trials. FDA Orphan Drug Designation provides tax credits and seven-year market exclusivity for polyglutamine-targeting therapies. Academic medical centers in Boston and Baltimore pioneer site-specific intrathecal injection techniques for motor neuron drug delivery.
Japan
PMDA's Sakigake fast-track framework prioritizes review for first-in-class neurology treatments, compressing approval timelines. The Ministry of Health, Labour and Welfare coordinates early reimbursement dialogue alongside scientific advice. Tokyo and Osaka host specialized neuraxial access centers that refine lumbar puncture protocols for chronic antisense dosing.
Germany
EMA parallel orphan designation streamlines centralized European procedures through the German medicines regulator, BfArM. The country's statutory health insurance funds negotiate outcome-based reimbursement for rare disease therapies. Heidelberg and Munich consolidate neurogeneticist expertise at dedicated neuromuscular centers serving cross-border patient flows.
United Kingdom
NICE technology appraisals set cost-effectiveness thresholds for NHS commissioning of SBMA disease-modifying treatments. The MHRA operates an innovative licensing pathway for promising medicines in areas of unmet need. London and Oxford anchor academic research networks linking natural history cohorts to first-in-human trial capacity.
Canada
Health Canada's priority review pathway for rare neurological disorders aligns with FDA submission timelines for North American regulatory efficiency. Provincial drug plans coordinate pan-Canadian pricing negotiations through the pCPA. Toronto and Montreal concentrate neurogenetic counseling services and multidisciplinary SBMA clinic infrastructure.
Spinal and Bulbar Muscular Atrophy Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical conglomerates leveraging rare-disease infrastructure against biotechnology firms focused on single-modality platforms. The upper tier commands regulatory relationships and manufacturing scale. The specialist tier competes on mechanistic novelty and CNS penetration chemistry. Dominant competitive moves include strategic research partnerships with academic medical centers and portfolio diversification into gene therapy vectors.
Among established pharmaceutical conglomerates, GlaxoSmithKline plc and Pfizer Inc occupy positions reflecting deep rare-disease operational experience, while Takeda Pharmaceutical Company Limited exemplifies geographic expansion strategies targeting underserved patient populations. Boehringer Ingelheim International GmbH anchors the specialist tier through neurology-focused research alliances. These archetypes represent divergent bets on whether manufacturing scale or biological precision will capture value in ultra-orphan neurodegeneration.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AbbVie Inc |
| Takeda Pharmaceutical Company Limited |
| Century Pharmaceuticals Ltd |
| Johnson and Johnson |
| Astellas Pharma |
| Pfizer Inc |
| Boehringer Ingelheim International GmbH |
| Sanofi |
| Others |
Pricing and Supply Chain Analysis
FDA Orphan Drug Designation gates both manufacturing qualification and reimbursement tiering, creating a dual-filter where tax-credit eligibility and seven-year exclusivity provisions simultaneously certify supply-chain partners and stratify price positioning across development-stage and commercial-stage therapies.
Pricing Analysis
Long-term offtake contracts between biotechnology sponsors and contract manufacturers dominate antisense oligonucleotide procurement, with gapmer chemistry commanding premium positioning against conventional backbone formulations due to validated central nervous system penetration data. Price differentiation rests on stereochemical purity grades and FDA fast-track certification status, with manufacturing queue priority driving tiered access. Cost compression in chronic intravenous dosing regimens is intensifying as sponsors evaluate intrathecal delivery conversion economics. Academic medical centers exhibit lowest price sensitivity given grant-funded trial infrastructure, while commercial payers in Germany and Japan negotiate hardest on outcome-based reimbursement terms.
Supply Chain Analysis
Specialized solid-phase chemistry capacity constrains antisense oligonucleotide synthesis, with United States, Switzerland, and Japan hosting the qualified contract manufacturing organizations capable of GMP-grade oligonucleotide production at clinical scale. Manufacturing feeds from phosphoramidite reagent supply chains concentrated in German and Chinese chemical sectors, with viral vector production for gene therapy programs drawing from plasmid DNA sources in United States and Canadian bioproduction facilities. Single-source vulnerability runs through neuraxial access device suppliers for intrathecal delivery programs. Distribution runs through cold-chain logistics networks anchored at academic medical center pharmacies, with specialty clinic consolidation reducing fragmentation in patient-facing dispensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antisense-to-gene-therapy modality transition creates platform-economics inflection, with vector manufacturing scale and stereopure chemistry intellectual property emerging as interoperable standards that will concentrate value capture among integrated developers.
For Market Incumbents: Compound rare-disease infrastructure advantages by locking long-term neuraxial access center partnerships before intrathecal delivery protocols standardize, while accelerating backward integration into plasmid DNA production to defuse viral vector supply bottlenecks threatening gene therapy program timelines. For New Entrants and Emerging Players: Japan PMDA Sakigake fast-track offers the most penetrable regulatory pathway for first-in-class neurology treatments, with Tokyo and Osaka academic sites providing established intrathecal administration expertise; target white-space in stereopure oligonucleotide manufacturing partnerships as incumbent queue congestion creates sponsor willingness to diversify supply. For Investors and Strategic Acquirers: FDA breakthrough therapy designation reshapes the acquisition landscape by de-risking Phase II-to-Phase III transitions for platform biotechnology firms; prioritize targets with validated central nervous system delivery chemistry and locked neuraxial access site relationships, watching neurofilament light chain biomarker qualification as the signal for registrational trial readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Intrathecal Delivery Protocol Standardization | Academic medical centers in Boston and Baltimore pioneer site-specific injection techniques for motor neuron drug delivery. |
| Orphan Drug Designation Acceleration | FDA tax credits and market exclusivity provisions de-risk early-stage investment for polyglutamine-targeting developers. |
| Stereopure Chemistry Platform Investment | Precision backbone manufacturers capture differentiated central nervous system penetration advantages over conventional suppliers. |
| Neuraxial Access Center Partnership | Specialized centers in Tokyo and Osaka refine lumbar puncture protocols for chronic antisense dosing. |
| Gene Therapy Vector Manufacturing Scale-Up | United States vector production facilities consolidate single-administration disease modification capacity. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchors the qualitative findings, with secondary validation drawing from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases; bottom-up patient registry analysis and top-down pharmaceutical pipeline valuation triangulate market sizing across the treatment modality segmentation.
Sensitivity analysis around antisense manufacturing capacity expansion timelines and gene therapy regulatory approval probability weights the analytical framework, with segmentation dimensions spanning treatment line, administration route, patient disease stage, and regional regulatory cluster; CAGRs derive from enrollment velocity in active SBMA trials and natural history cohort progression rates, with biomarker validation timelines and intrathecal delivery adoption curves as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable Orphan Drug Designation incentives and continued academic site activation; material deviation in neurogeneticist hiring rates or antisense contract manufacturing queue dynamics would warrant model refresh. Practitioners should keep alternative scenarios live as Japan PMDA Sakigake eligibility criteria and EMA parallel orphan designation procedures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
Lateral Epicondylitis (Tennis Elbow) Treatment Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Odontogenic Tumor Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Tinea Corporis Market