
 Narcolepsy Market | 2026-2036
Narcolepsy Market Size, Share, and Industry Trends Forecast 2026-2036
Narcolepsy Market Outlook
Patient support and adherence program subscriptions is rebalancing revenue streams beyond pill dispensing toward ongoing care relationships. Jazz Pharmaceuticals leverages vertical integration across development and commercialization to sustain its franchise position. Harmony Biosciences anchors its growth on pitolisant's differentiated mechanism. Takeda Pharmaceutical Company navigates the competitive landscape through its established rare disease infrastructure.
Narcolepsy constitutes a chronic neurological disorder characterized by dysregulated sleep-wake cycles, with diagnostic criteria requiring polysomnography and multiple sleep latency testing to confirm excessive daytime sleepiness and REM sleep abnormalities. The condition demands pharmacological intervention to restore functional alertness and prevent cataplexy-related injury during waking hours. Sodium oxybate formulations command premium positioning due to their dual efficacy against cataplexy and nighttime sleep architecture, while stimulants occupy the largest volume tier for excessive daytime sleepiness management. Specialty centers represent the fastest-growing end user channel as they concentrate diagnostic expertise and access to restricted distribution products.
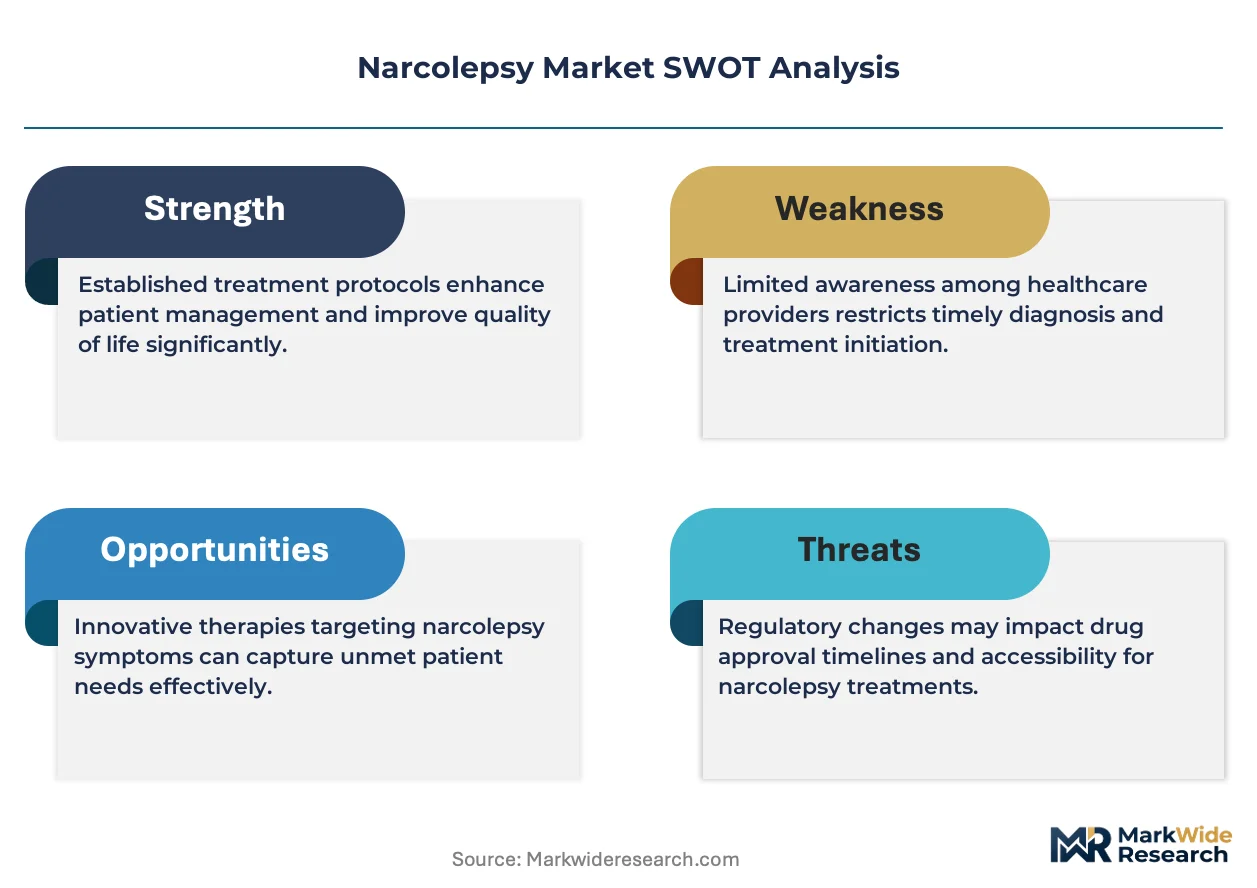
The FDA, EMA, and DEA collectively shape market access through distinct pathways: the FDA grants breakthrough therapy and orphan drug designations, the EMA enforces centralized pediatric investigation plans, and the DEA imposes scheduling controls on sodium oxybate that constrain distribution architecture. These frameworks elevate compliance costs while creating protected exclusivity periods for innovators. Stakeholders must monitor how evolving controlled-substance policies and biosimilar entry timelines will reshape competitive moats and pricing power across the narcolepsy therapeutic landscape.
Market Dynamics
The narcolepsy therapeutic landscape is being fundamentally restructured by the DEA's scheduling controls on sodium oxybate, which create artificial scarcity and force manufacturers into restricted distribution architectures that reshape competitive positioning.
Growth Catalysts
- FDA Orphan Drug Designation:The FDA's accelerated approval pathway reduces clinical trial burdens and extends market exclusivity for novel narcolepsy therapies, incentivizing pipeline investment.
- Specialty Center Expansion:Concentrated diagnostic expertise at sleep disorder centers streamlines polysomnography access and drives patient identification in the United States.
- Dual-Mechanism Formulations:Sodium oxybate's simultaneous efficacy against cataplexy and nocturnal sleep fragmentation commands preferential reimbursement positioning.
Market Restraints
- DEA Schedule III Controls:The DEA's stringent distribution requirements for sodium oxybate impose compliance costs and limit pharmacy network participation.
- Polysomnography Bottleneck:Diagnostic capacity constraints at accredited sleep centers create patient backlogs and delay treatment initiation.
- Stimulant Tolerance Ceiling:Long-term amphetamine-based therapy faces diminishing returns and cardiovascular risk profiles that restrict chronic use.
Strategic Opportunities
- Pediatric Indication Gaps:The EMA's centralized pediatric investigation plan mandates age-appropriate formulations, opening underserved younger patient segments.
- Telemedicine Diagnostic Channels:Remote sleep latency testing and home polysomnography are disrupting traditional clinic-dependent referral pathways.
- Histamine H3 Antagonist Expansion:Pitolisant's wake-promoting mechanism without abuse potential is displacing controlled-substance alternatives in risk-sensitive populations.
Industry Challenges
- Sleep Medicine Specialist Shortage:Board-certified somnologists remain concentrated at academic medical centers, limiting community-based diagnostic access.
- Prior Authorization Complexity:Payer requirements for step-therapy documentation and cataplexy severity verification create administrative friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Narcolepsy Market |
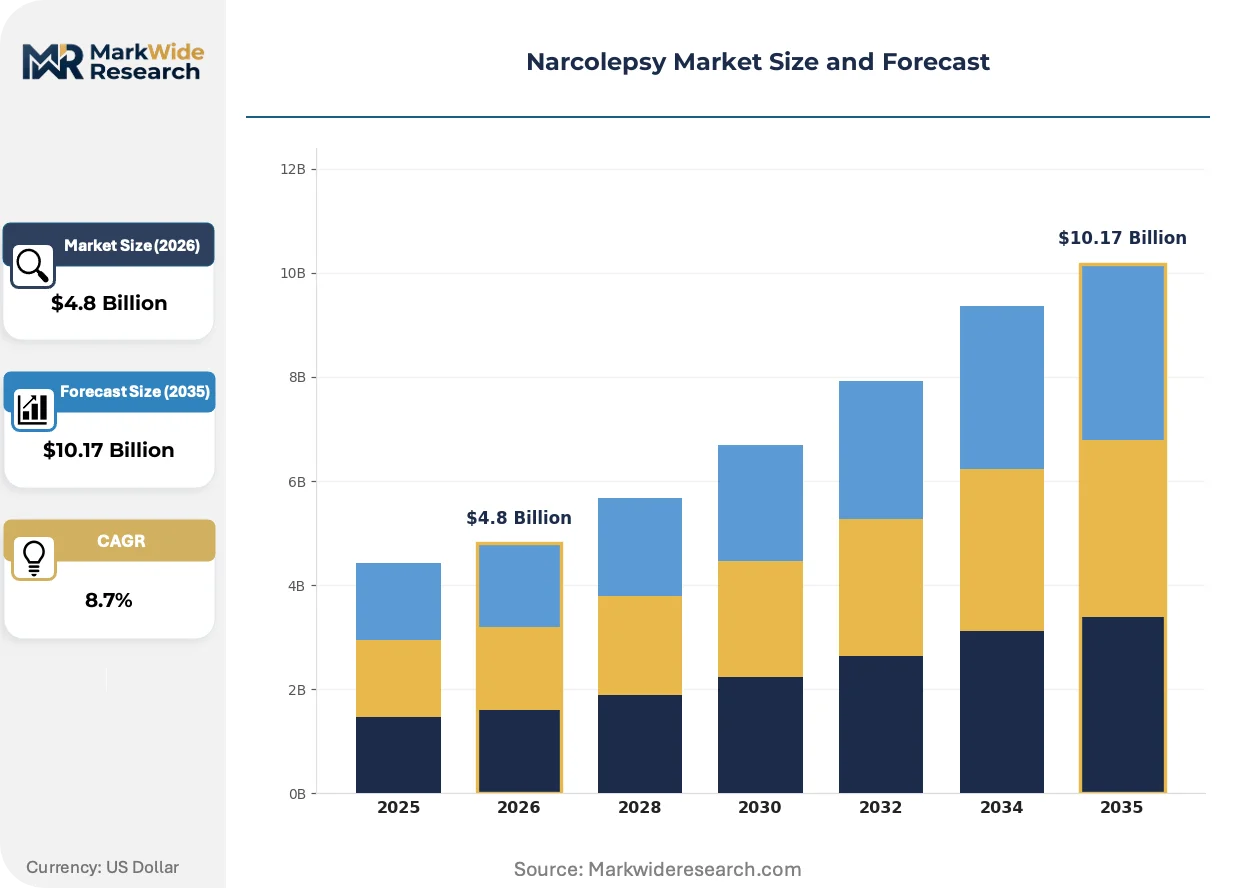
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stimulants, Antidepressants, Sodium Oxybate, Modafinil End User: Hospitals, Clinics, Homecare, Specialty Centers Distribution Channel: Retail Pharmacy, Online Pharmacy, Hospital Pharmacy, Direct Sales Application: Excessive Daytime Sleepiness, Cataplexy, Sleep Attacks, Sleep Paralysis |
| Companies Covered | Jazz Pharmaceuticals, Harmony Biosciences, Teva Pharmaceutical Industries, Avadel Pharmaceuticals, Axsome Therapeutics, Takeda Pharmaceutical Company, Novartis, Alkermes, Hikma Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Narcolepsy Market Strategic Shifts
Three intersecting developments are compressing development timelines and redrawing competitive boundaries across the narcolepsy therapeutic space. Technology convergence, regulatory pathway evolution, and patient-centric delivery models are simultaneously reshaping how therapies reach diagnosed populations.
Once-nightly sodium oxybate formulations are rewriting the treatment burden calculus for narcolepsy patients. Sleep centers in the United States are rapidly adopting these extended-release alternatives to reduce middle-of-the-night dosing interruptions. The structural consequence is a compression in patient discontinuation rates and an expansion of addressable populations previously non-adherent to twice-nightly regimens.
The FDA's breakthrough therapy designation framework is accelerating novel mechanism reviews for narcolepsy candidates. This regulatory pathway compresses Phase III timelines and enables rolling submission protocols for therapies addressing excessive daytime sleepiness. Small-cap developers are responding by prioritizing orphan indications with biomarker-defined patient stratification.
Patient advocacy organizations are consolidating purchasing influence through direct-to-payer negotiation platforms. These groups are disrupting traditional pharmaceutical account management by aggregating real-world outcome data and demanding value-based contract structures. The United States exhibits the most advanced development of this model, with narcolepsy foundations now sitting on pharmacy benefit manager formulary committees.
Narcolepsy Market Segmentation
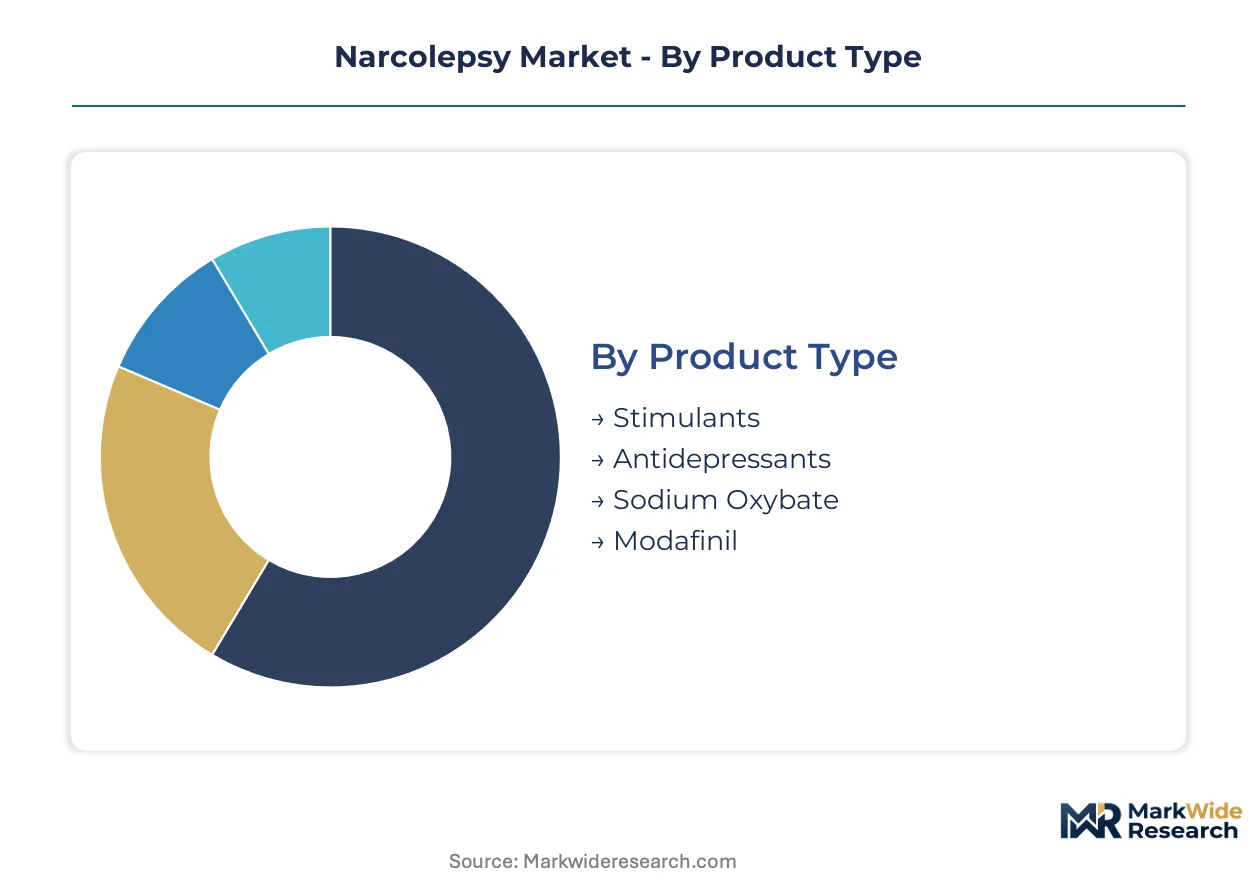
Narcolepsy treatment pathways diverge sharply across patient severity, comorbidity profiles, and reimbursement access. Segmentation reveals how sodium oxybate's restricted distribution architecture creates distinct channel economics versus stimulant commoditization. Understanding these fracture lines enables targeted positioning across controlled-substance and non-controlled therapeutic tiers.
Product Type:
Customization intensity spans from standardized stimulant generics to patient-titrated sodium oxybate protocols with mandatory REMS enrollment.
- Sodium Oxybate:Dual-mechanism agent addressing cataplexy and nocturnal sleep architecture through consolidated REM suppression. Demand concentrates at US specialty centers managing REMS compliance, where prior authorization density creates physician loyalty and pricing insulation. The DEA's Schedule III controls enforce restricted distribution that limits pharmacy competition and sustains premium positioning.
- Stimulants:Amphetamine and methylphenidate formulations occupying the highest prescription volume tier for excessive daytime sleepiness. Generic saturation has compressed margins, though cardiovascular risk labeling and DEA Schedule II controls preserve some structural differentiation. Payer step-therapy requirements typically mandate stimulant failure before authorizing pitolisant or sodium oxybate.
- Modafinil:Wake-promoting agent with lower abuse potential than traditional stimulants, serving as first-line therapy in risk-sensitive populations.
- Antidepressants:Off-label venlafaxine and fluoxetine protocols for cataplexy suppression in patients with comorbid mood disorders.
Leading the category by volume: Stimulants. Growing fastest: Sodium Oxybate.
End User:
Channel economics vary by diagnostic equipment requirements, controlled-substance licensing, and patient acuity thresholds.
- Specialty Centers:Accredited sleep disorder centers with polysomnography suites and board-certified somnologists. These facilities concentrate sodium oxybate prescribing due to REMS certification requirements and manage the most complex cataplexy cases with multimodal protocols.
- Hospitals:Academic medical centers and community hospitals with sleep medicine divisions. Inpatient narcolepsy encounters remain rare; hospital pharmacy formulary placement primarily enables discharge continuity and prior authorization infrastructure.
- Clinics:Neurology and primary care practices handling stable patients on maintenance therapy with simplified regimens.
- Homecare:Infusion and nursing services supporting sodium oxybate patients with adherence monitoring and adverse event reporting obligations.
Volume concentrates at Specialty Centers. Fastest expansion trajectory: Homecare adherence programs.
Distribution Channel:
Regulatory segmentation creates channel fragmentation between controlled-substance restrictions and convenience-driven fulfillment.
- Direct Sales:Manufacturer-controlled dispensing through specialty pharmacies with REMS certification, mandatory for sodium oxybate. This channel captures the highest revenue per prescription while absorbing compliance infrastructure costs.
- Hospital Pharmacy:Captive dispensing within integrated delivery networks, particularly for patients enrolled in academic center protocols with intensive monitoring requirements.
- Retail Pharmacy:Traditional community pharmacies handling stimulant and modafinil prescriptions with standard DEA Schedule II protocols.
- Online Pharmacy:Mail-order fulfillment expanding for maintenance medications in states with telemedicine prescribing authority.
Direct Sales leads revenue concentration. Online Pharmacy shows steepest expansion trajectory.
Application:
Treatment targeting shifts from symptom-specific monotherapy to integrated management of the narcolepsy tetrad.
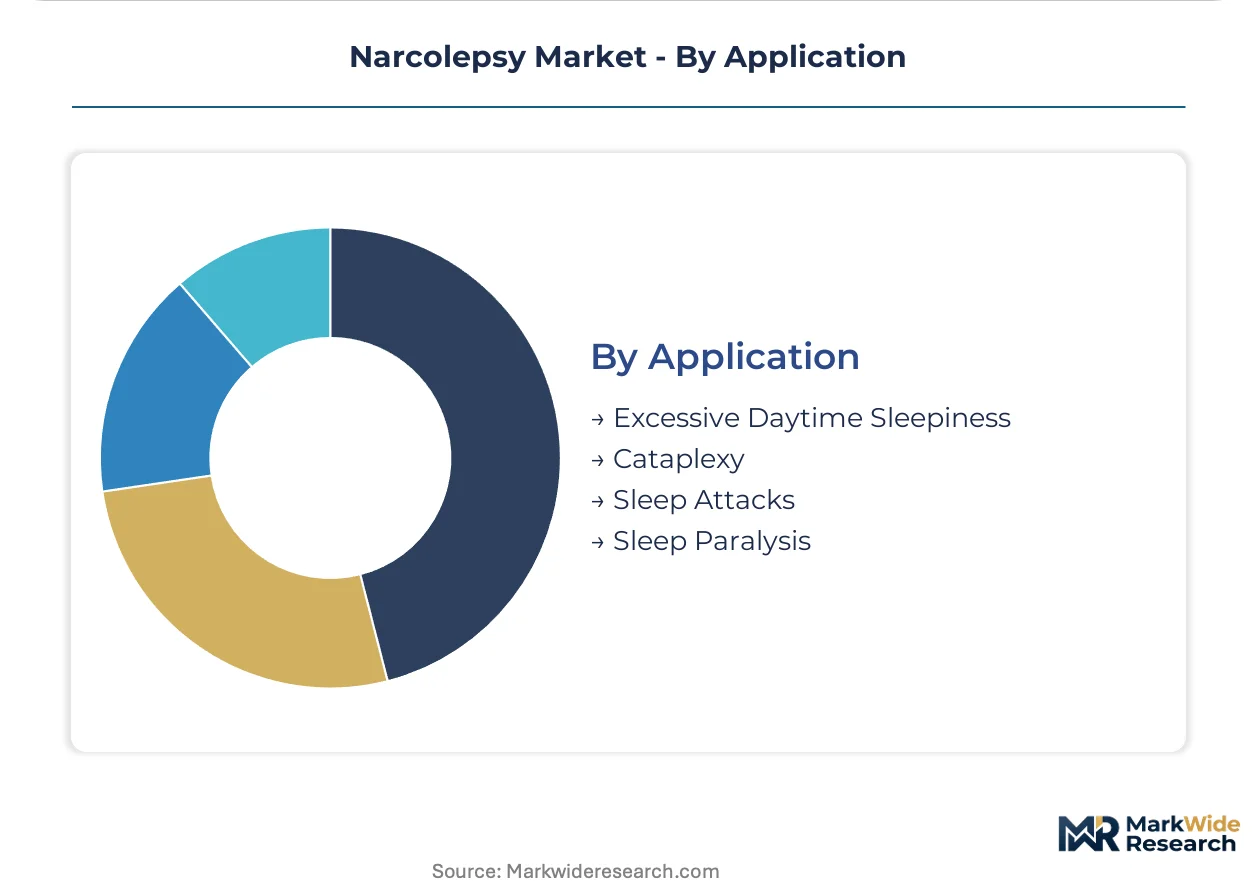
- Excessive Daytime Sleepiness:Core functional impairment driving the majority of treatment initiations and stimulant prescriptions. Diagnostic confirmation requires multiple sleep latency testing with mean sleep latency thresholds.
- Cataplexy:Sudden muscle atonia triggered by emotional stimuli, representing the most distinctive narcolepsy symptom and the primary indication for sodium oxybate. Severity correlates with orexin neuron loss.
- Sleep Paralysis:REM atonia intrusion during sleep-wake transitions, often co-managed with antidepressant therapy.
- Sleep Attacks:Irresistible sleep episodes distinct from gradual sleepiness onset, requiring rapid-onset interventions.
Excessive Daytime Sleepiness dominates prescription volume. Cataplexy commands highest per-patient revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the narcolepsy therapeutic development corridor, with Massachusetts General Hospital's sleep disorders division driving clinical trial recruitment and biomarker discovery that shapes treatment protocols worldwide.
United States
Patient advocacy infrastructure and REMS-certified specialty centers concentrate diagnostic capacity in major metropolitan corridors. The FDA's breakthrough therapy designation accelerates novel mechanism reviews for excessive daytime sleepiness candidates. Sleep medicine clusters in Philadelphia and Stanford University Medical Center manage complex cataplexy cases with multimodal protocols.
Germany
Academic medical centers in Munich and Heidelberg advance orexin-based research and polysomnography standardization. The EMA's centralized pediatric investigation plan mandates age-appropriate formulations for younger patient segments. Bavaria's sleep medicine network coordinates cross-border referral pathways with Austria and Switzerland.
Japan
PMDA's orphan drug framework incentivizes development for narcolepsy subtypes with biomarker-defined stratification. Tokyo's National Center of Neurology and Psychiatry leads Asia-Pacific diagnostic protocol harmonization. Osaka-based sleep centers pioneer home polysomnography adoption for maintenance therapy monitoring.
United Kingdom
NHS England's specialized commissioning framework concentrates sodium oxybate prescribing at designated tertiary centers. The MHRA's post-Brexit regulatory autonomy enables accelerated access schemes for histamine H3 antagonists. London's Guy's and St Thomas' NHS Foundation Trust anchors a national sleep disorder biobank.
Switzerland
Swissmedic's precision medicine pathways support pharmacogenomic-guided stimulant selection. Basel's pharmaceutical research corridor connects academic sleep laboratories with commercial development infrastructure. Zurich University Hospital's narcolepsy unit coordinates European registry data for real-world outcome analysis.
Narcolepsy Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the narcolepsy therapeutic space. The market structure consolidates around vertically integrated developers with captive distribution infrastructure and restricted-substance licensing. Three archetypes dominate: established rare disease specialists with REMS expertise, mid-cap neurology-focused developers with novel mechanisms, and generic manufacturers capturing stimulant volume tiers. Competitive moves concentrate on pediatric indication expansion and once-nightly formulation development.
Within the rare disease specialist tier, Jazz Pharmaceuticals and Harmony Biosciences exemplify divergent strategic positioning. Jazz Pharmaceuticals anchors its presence through backward integration into development and commercialization infrastructure. Harmony Biosciences occupies a position defined by pitolisant's non-controlled substance status. Takeda Pharmaceutical Company represents the diversified pharmaceutical conglomerate archetype, leveraging established infrastructure across multiple therapeutic areas.
| Leading Market Players |
|---|
| Jazz Pharmaceuticals |
| Harmony Biosciences |
| Teva Pharmaceutical Industries |
| Avadel Pharmaceuticals |
| Axsome Therapeutics |
| Takeda Pharmaceutical Company |
| Novartis |
| Alkermes |
| Hikma Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Once-nightly sodium oxybate formulations are compressing manufacturing cost structures while concentrating production expertise among REMS-certified facilities in the United States. This formulation shift simultaneously reduces patient discontinuation economics and elevates compliance infrastructure as a pricing determinant.
Pricing Analysis
Value-based pricing anchors on functional alertness restoration and cataplexy prevention outcomes. Sodium oxybate commands premium positioning through its dual-mechanism efficacy and DEA Schedule III restricted distribution, while stimulant generics compete on volume with compressed margins. Price differentiation hinges on REMS certification requirements and controlled-substance licensing tiers. Pricing pressure stems from pitolisant's non-controlled status displacing risk-sensitive prescriptions. Payers exhibit highest sensitivity to stimulant tier costs, whereas specialty centers absorb sodium oxybate premiums for complex cataplexy cases.
Supply Chain Analysis
Direct-to-specialty-pharmacy channels handle sodium oxybate distribution under REMS mandates, while retail and online pharmacies manage stimulant and modafinil fulfillment. Active pharmaceutical ingredient sourcing concentrates in the United States, Switzerland, and India for orexin-targeting mechanisms. Finished formulation production draws from domestic US facilities and Irish pharmaceutical manufacturing corridors. Supply chain risk centers on single-source sodium oxybate API dependency and DEA quota allocation volatility. Distribution runs through manufacturer-controlled specialty networks for controlled substances, with standard wholesale channels for non-scheduled alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The narcolepsy therapeutic space is transitioning from twice-nightly sodium oxybate regimens to once-nightly extended-release formulations, with pitolisant's histamine H3 mechanism displacing controlled-substance alternatives in risk-sensitive populations.
For Market Incumbents: To counter pitolisant's non-controlled substance encroachment, incumbents should deepen backward integration into orexin-targeting R&D pipelines and secure pediatric indication exclusivities through EMA-mandated investigation plans. Channel control via REMS-certified specialty pharmacy networks preserves pricing insulation against generic stimulant commoditization. For New Entrants and Emerging Players: Begin with telemedicine-enabled diagnostic platforms that bypass polysomnography bottlenecks at academic sleep centers. The most penetrable white space sits in homecare adherence monitoring for sodium oxybate patients and biomarker-defined narcolepsy subtype stratification. A direct-to-payer value demonstration approach, aggregating real-world outcome data through patient foundations, circumvents traditional pharmaceutical account management barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap neurology specialists with novel mechanisms and orphan designation portfolios. Long-term viability over the next decade hinges on formulation innovation that reduces treatment burden and expands addressable populations beyond REMS-constrained channels. The critical signal to watch is FDA breakthrough therapy designation velocity for excessive daytime sleepiness candidates with biomarker-defined patient selection.| Strategic Initiative | Industry Significance |
|---|---|
| Once-Nightly Formulation Development | Reduces patient discontinuation and expands addressable non-adherent populations at US specialty centers. |
| Pediatric Indication Expansion | EMA's centralized pediatric investigation plan mandates age-appropriate formulations for underserved younger segments. |
| REMS-Certified Distribution Infrastructure | DEA Schedule III controls enforce restricted pharmacy networks that sustain premium sodium oxybate positioning. |
| Histamine H3 Antagonist Pipeline Investment | Pitolisant's wake-promoting mechanism without abuse potential captures risk-sensitive prescriber preference. |
| Telemedicine Diagnostic Platform Integration | Remote sleep latency testing disrupts traditional clinic-dependent referral pathways and accelerates patient identification. |
Study Parameters
FDA filings, EMA centralized procedure documents, and ClinicalTrials.gov registries formed the secondary backbone of this analysis, cross-referenced with formulary database audits and DEA controlled-substance manufacturing quota records. Primary interviews with drug development executives, regulatory affairs leads at rare disease specialists, formulary directors at national pharmacy benefit managers, and sleep medicine specialists at accredited centers validated secondary findings. Bottom-up patient-flow modeling and top-down therapeutic class revenue triangulation reconciled volume and value estimates.
Historical trendline analysis of sodium oxybate prescription patterns, stimulant generic substitution rates, and pitolisant uptake curves informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, end-user channel, distribution architecture, and application targeting excessive daytime sleepiness versus cataplexy. CAGRs were derived from epidemiological prevalence adjustments, diagnosis rate improvement assumptions, and therapy penetration elasticity by severity tier. Forecast inputs incorporated FDA breakthrough therapy designation timelines and EMA pediatric investigation plan compliance schedules.
Underlying measurement precision varies by segment; sodium oxybate revenue flows through REMS-tracked channels with tighter precision than off-label antidepressant prescribing estimates. Forecasts reflect assumptions regarding DEA scheduling continuity, payer step-therapy durability, and diagnostic capacity expansion at US sleep centers. Periodic stress-testing of base assumptions is recommended given regulatory pathway volatility and controlled-substance policy evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Asia-Pacific Sports Medicine Market
Specialty Medicine
Pigmented Villonodular Synovitis Treatment Market
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Global Hammertoe Market
Specialty Medicine
Short Bowel Syndrome Market