
 Liver Metastases Treatment Market | 2026-2036
Liver Metastases Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Liver Metastases Treatment Market Analytics
The shift from single-source biologics procurement to multi-source portfolio contracting is pivoting how hospital pharmacy committees evaluate liver metastases protocols. F. Hoffmann-La Roche Ltd. anchors its position through deep R&D pipelines in hepatocellular combination therapies. Bristol-Myers Squibb Company differentiates via checkpoint inhibitor portfolios that compete across colorectal cancer metastases. Bayer AG sustains manufacturing scale for targeted small-molecule supply to European oncology networks.
Liver metastases treatment encompasses systemic and locoregional interventions designed to control secondary hepatic tumors originating from primary colorectal, breast, lung, or neuroendocrine cancers, utilizing cytotoxic agents, monoclonal antibodies, kinase inhibitors, and interventional radiology techniques to prolong survival and preserve liver function. Immunotherapy represents the fastest-expanding product category as PD-1 and CTLA-4 combinations demonstrate durable responses in microsatellite-instability-high populations. Hospitals capture the dominant share of end-user value given the infusion supervision requirements and interventional radiology infrastructure needed for advanced cases. Localized delivery modes command premium positioning where transarterial chemoembolization and radioembolization procedures concentrate at academic medical centers.
The FDA, EMA, and Japan's PMDA collectively govern clinical trial endpoints and post-market surveillance for hepatic oncology therapies, with each agency tightening biomarker-driven patient selection criteria that filter which regimens reach reimbursement lists. The EU's MDR and ISO 13485 standards shape device qualification for ablation and embolization platforms used in interventional suites. Stakeholders must monitor how real-world evidence requirements from national health technology assessment bodies redefine access negotiations for combination protocols.
Market Dynamics
The FDA's accelerated approval pathways for breakthrough oncology therapies compress commercialization timelines from years to months, forcing hospital pharmacy committees to restructure formulary evaluation workflows around real-time biomarker data rather than traditional clinical endpoints.
Growth Catalysts
- Immunotherapy Expansion:PD-1 and CTLA-4 checkpoint inhibitors demonstrate durable responses in microsatellite-instability-high populations, pulling investment toward combination regimen development. Academic medical centers in the United States, Germany, and Japan are expanding dedicated hepatobiliary units to capture this patient volume.
- EMA Adaptive Pathways:The European Medicines Agency's conditional marketing authorization framework allows earlier patient access to novel liver-directed therapies while confirmatory evidence accumulates. This regulatory flexibility accelerates reimbursement negotiations across European oncology networks.
- Interventional Radiology Infrastructure:Transarterial chemoembolization and radioembolization platforms require specialized angiography suites that tertiary hospitals are constructing to capture high-margin procedures. Equipment manufacturers are scaling training programs to address operator shortages.
Market Restraints
- Biomarker Testing Cost Burden:Comprehensive genomic profiling for patient selection in immunotherapy protocols adds substantial per-patient expense that community oncology practices struggle to absorb. Payer reimbursement for companion diagnostics remains fragmented across national health systems.
- Isotope Supply Concentration:Yttrium-90 for radioembolization depends on aging nuclear reactors concentrated in Canada and the Netherlands. Production outages create procedure backlogs at centers lacking alternative radioisotope options.
- Technical Limitation in Liver Reserve Assessment:Current volumetric and functional imaging tools inadequately predict post-treatment hepatic decompensation in patients with marginal baseline liver function. This uncertainty restricts treatment candidacy and limits addressable populations.
Strategic Opportunities
- Underpenetrated Neuroendocrine Tumor Segment:Peptide receptor radionuclide therapy for liver-dominant neuroendocrine metastases shows strong efficacy signals but limited center availability. Expansion of lutetium-177 production capacity in the United States and Germany would unlock substantial volume.
- Real-World Evidence Mandates:National health technology assessment bodies in the United Kingdom and France increasingly require post-market outcome data for reimbursement continuation. Early movers in electronic health record integration can capture preferred formulary positioning.
- Convergence of Ablation and Immunotherapy:Percutaneous thermal ablation combined with intralesional immunostimulant injection represents an emerging locoregional-systemic hybrid approach. Device manufacturers with ablation platform installed bases can leverage existing physician relationships.
Industry Challenges
- Interventional Radiology Talent Pipeline:Training sufficient operators for complex transarterial procedures requires years of specialized fellowship exposure. Academic medical centers compete aggressively for limited fellowship graduates.
- Combination Protocol Supply Chain Complexity:Coordinating biologic, small-molecule, and device inventory across multi-agent regimens strains hospital pharmacy logistics. Cold chain requirements for checkpoint inhibitors compound storage challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liver Metastases Treatment Market |
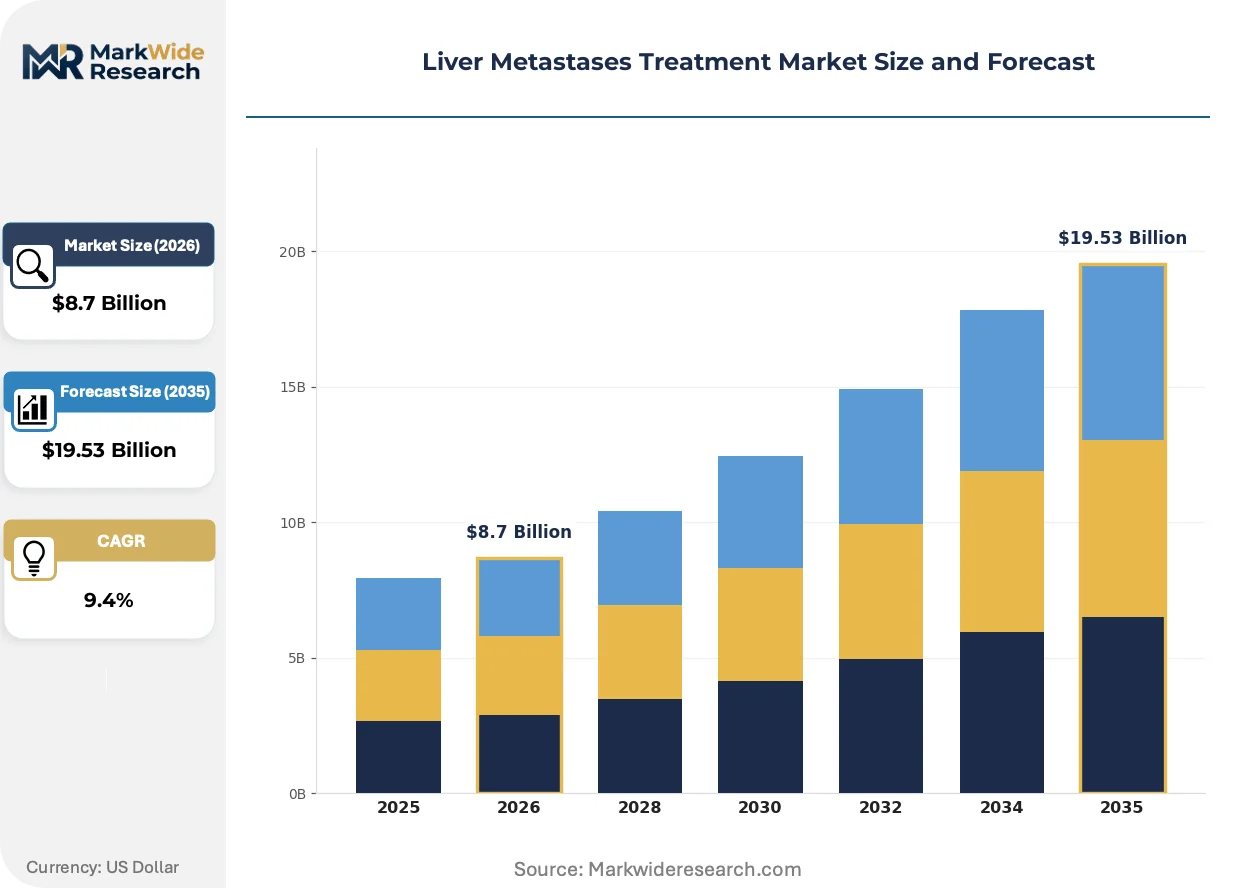
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Chemotherapy, Targeted Therapy, Immunotherapy Delivery Mode: Intravenous, Oral, Localized, Injectable End User: Hospitals, Clinics, Research Institutes, Homecare Application: Symptomatic Relief, Palliative Care, Disease Management, Neoadjuvant Therapy |
| Companies Covered | F. Hoffmann-La Roche Ltd., AstraZeneca, Bayer AG, Eli Lilly and Company, Pfizer, Inc., Bristol-Myers Squibb Company, Ono Pharmaceutical, Merck & Co., Ipsen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liver Metastases Treatment Market Evolving Landscape
Artificial intelligence applications are penetrating hepatic oncology at multiple points, from automated tumor segmentation in pre-procedure planning to real-time catheter navigation guidance, compressing procedure times and reducing operator variability.
Machine learning algorithms trained on contrast-enhanced CT and MRI datasets are automating volumetric tumor burden assessment and treatment response prediction. Interventional radiology departments at tertiary centers in the United States and Germany are deploying these tools to standardize patient selection for locoregional therapies. The technology is automating previously manual contouring tasks that consumed hours of specialist physician time per case.
The European Union's Medical Device Regulation imposes stricter clinical evidence requirements on ablation and embolization platforms, extending device qualification timelines by 12-18 months. Manufacturers must now generate prospective safety and performance data for legacy devices previously grandfathered under prior directives. Interventional oncology suites are responding by consolidating purchases toward established vendors with robust MDR technical documentation.
Hospital pharmacy committees are unbundling interventional radiology procedure bundles to scrutinize device and drug costs separately. Procurement officers at German university hospitals are negotiating direct sourcing agreements with radioisotope suppliers, bypassing traditional distributor markups. This disintermediation is most visible in high-volume centers performing over 200 radioembolization procedures annually.
Liver Metastases Treatment Market Segmentation
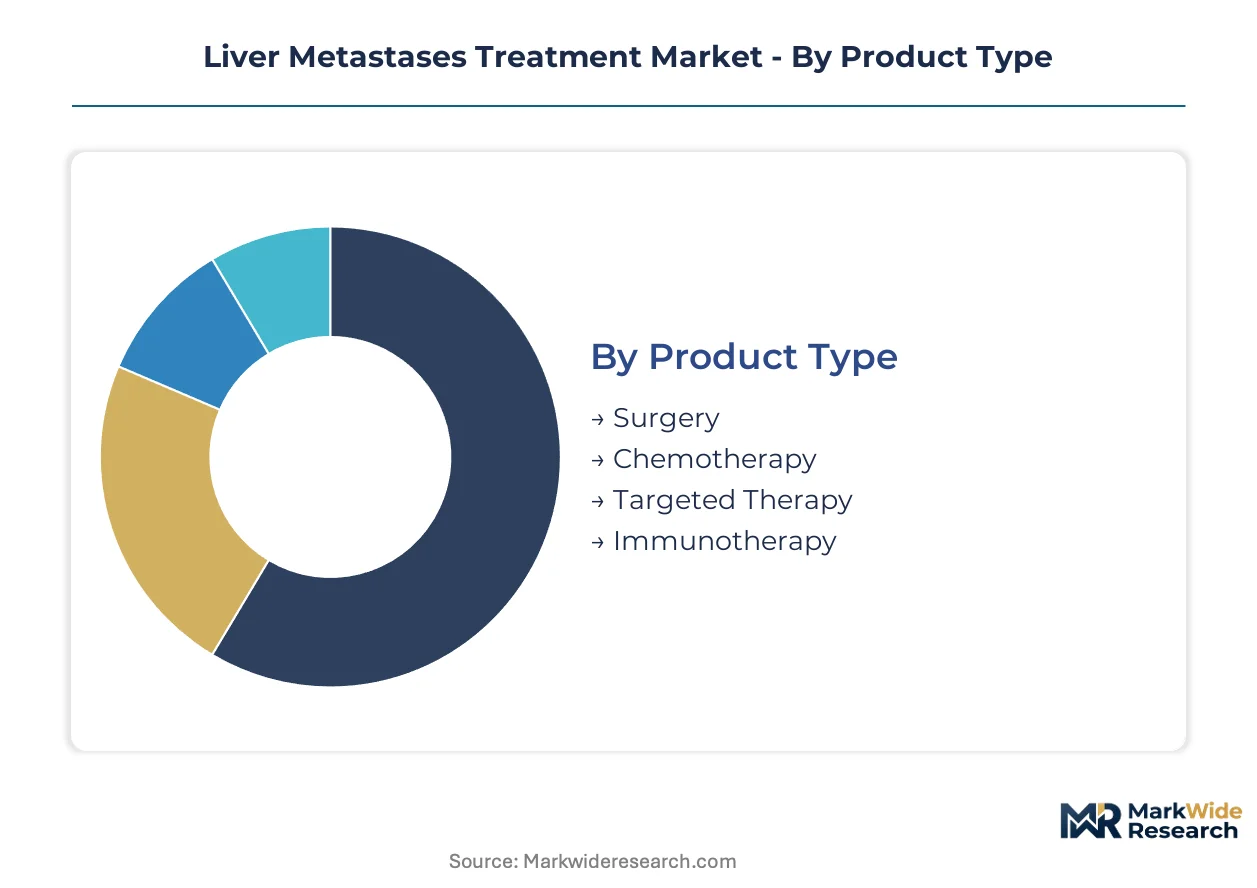
Segmentation in the liver metastases treatment market reveals how capital allocation, infrastructure requirements, and patient acuity distribute value across the care continuum. Treatment modality selection hinges on hepatic functional reserve, primary tumor origin, and access to specialized interventional radiology suites.
Product Type:
Surgery and immunotherapy demand the steepest upfront capital investment, with the former requiring dedicated hepatobiliary operating theaters and the latter necessitating cold-chain biologics infrastructure and infusion center staffing.
- Surgery:Hepatic resection and metastasectomy procedures require intraoperative ultrasound guidance and specialized anesthesia protocols for portal triad clamping. Demand concentrates at tertiary centers in the United States and Germany where multidisciplinary tumor boards coordinate care. Hospital margins compress when extended hepatectomies exceed reimbursed episode costs.
- Immunotherapy:Checkpoint inhibitors targeting PD-1 and CTLA-4 pathways require biomarker-driven patient selection and continuous infusion monitoring. Academic medical centers in Japan and the United States capture this volume through dedicated hepatobiliary units. EMA adaptive pathways accelerate European access while confirmatory trials accumulate.
- Chemotherapy:Cytotoxic regimens utilizing oxaliplatin or irinotecan remain the backbone of first-line systemic therapy across community oncology networks.
- Targeted Therapy:Kinase inhibitors and anti-angiogenic agents serve molecularly selected populations with specific driver mutations.
Most installed capacity flows through surgery. Expansion is steepest in immunotherapy.
Delivery Mode:
Route of administration determines site-of-care economics, with localized and intravenous delivery commanding premium reimbursement tied to procedure complexity and supervision intensity.
- Localized:Transarterial chemoembolization and radioembolization deliver therapeutic agents directly to hepatic tumor vasculature through femoral artery catheterization. Demand clusters at academic medical centers in Germany and Japan where specialized angiography suites support complex navigation. Yttrium-90 supply concentration in Canadian and Dutch reactors creates procedure vulnerability.
- Intravenous:Systemic biologic and cytotoxic infusion requires supervised infusion centers with emergency resuscitation capability and extended monitoring protocols. Hospital outpatient departments in the United States capture this volume through bundled payment structures. Cold chain logistics for checkpoint inhibitors strain pharmacy inventory systems.
- Oral:Small-molecule kinase inhibitors enable ambulatory administration with periodic laboratory monitoring.
- Injectable:Subcutaneous formulations of supportive care agents reduce infusion chair time but require patient training.
Revenue concentration favors localized delivery. Patient volume expansion runs through intravenous administration.
End User:
Facility type determines reimbursement tier and capital equipment thresholds, with hospitals absorbing the highest fixed costs for interventional radiology infrastructure.
- Hospitals:Tertiary academic centers integrate surgical oncology, interventional radiology, and medical oncology under unified hepatobiliary programs. Centers in the United States, Germany, and Japan compete for fellowship-trained operators. FDA breakthrough therapy designations force real-time formulary restructuring.
- Clinics:Community oncology practices handle stable patients on oral regimens or routine infusion cycles without acute complication risk. German university hospital networks are bypassing traditional distributor markups through direct radioisotope sourcing agreements.
- Research Institutes:Early-phase trial sites manage investigational protocols with intensive biomarker monitoring requirements.
- Homecare:Limited to oral maintenance therapy and supportive care administration in select markets with robust nursing networks.
Procedure margin capture concentrates in hospitals. Addressable volume expansion is shifting toward clinics.
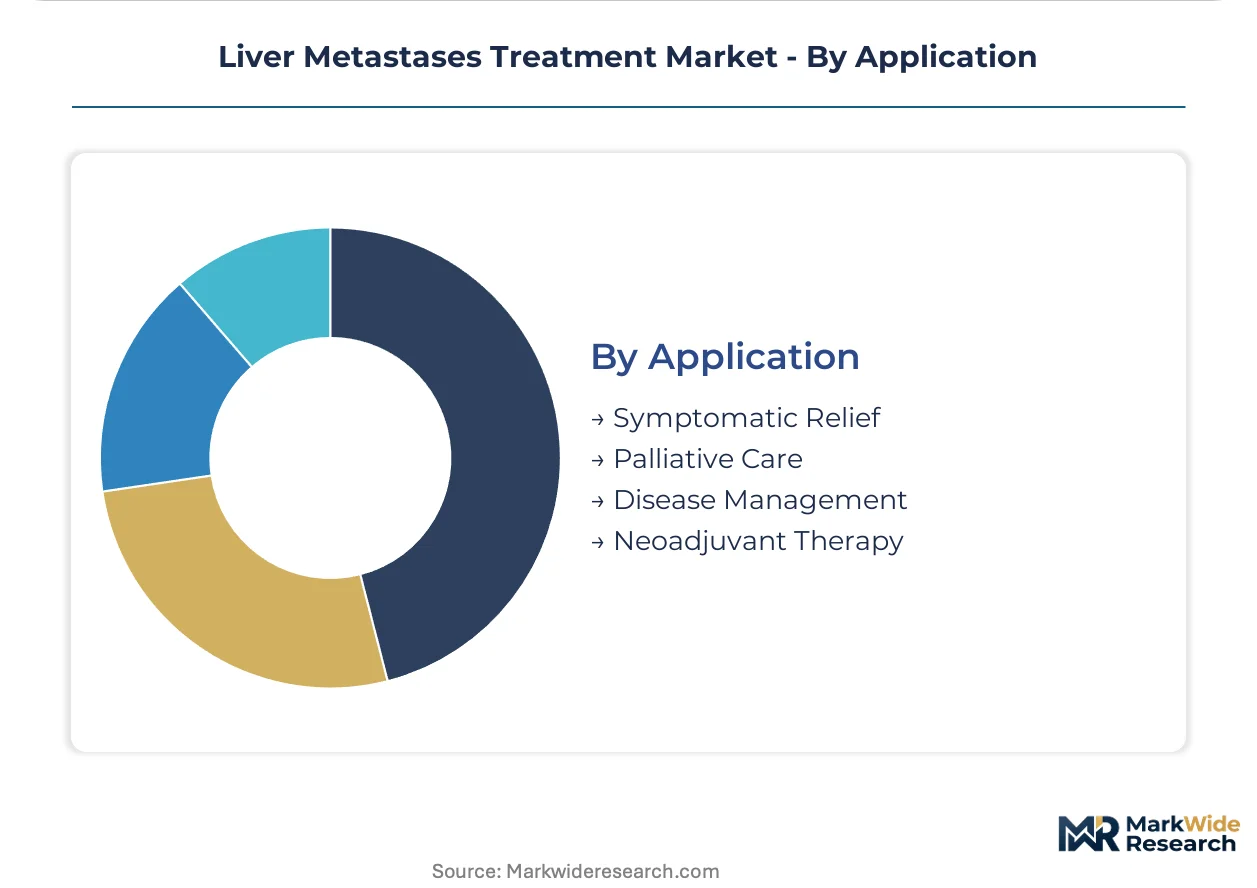
Application:
Treatment intent stratifies patient selection criteria and reimbursement pathways, with curative-intent segments requiring the most intensive resource deployment.
- Disease Management:Long-term systemic therapy for controlled metastatic disease demands continuous biomarker monitoring and sequential regimen navigation. Oncology networks in the United States and Japan are deploying machine learning tools for automated treatment response assessment. Real-world evidence mandates from United Kingdom and French health technology assessment bodies reshape continuation criteria.
- Neoadjuvant Therapy:Preoperative systemic or locoregional treatment aims to convert unresectable disease to resectable status or reduce recurrence risk. Specialized centers in Germany and the United States are refining liver reserve assessment algorithms to expand surgical candidacy. Current volumetric imaging tools inadequately predict post-treatment hepatic decompensation.
- Palliative Care:Symptom-focused intervention prioritizes quality of life over survival extension in end-stage presentations.
- Symptomatic Relief:Targeted procedures address pain, obstruction, or metabolic complications without disease-modifying intent.
Treatment episode value concentrates in disease management. Neoadjuvant protocols are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hepatobiliary centers in the United States, Germany, and Japan concentrate the highest procedure volumes for liver metastases treatment, with each market shaped by distinct reimbursement architectures and regulatory acceleration pathways.
United States
FDA breakthrough therapy designations compress commercialization timelines for checkpoint inhibitors, compelling academic medical centers to restructure formulary workflows around real-time biomarker data. The IRA's drug pricing provisions reshape negotiation dynamics for combination regimens. Major hepatobiliary programs at Memorial Sloan Kettering, MD Anderson, and Mayo Clinic compete aggressively for fellowship-trained interventional radiologists.
Germany
EMA adaptive pathways enable earlier patient access to novel liver-directed therapies while confirmatory evidence accumulates, accelerating reimbursement negotiations across oncology networks. University hospital pharmacy committees are unbundling procedure bundles to scrutinize device and drug costs separately. High-volume centers in Munich and Hamburg negotiate direct sourcing agreements with radioisotope suppliers, bypassing traditional distributor markups.
Japan
PMDA's Sakigake designation system prioritizes review of innovative oncology therapies, reducing regulatory lag for hepatocellular combination protocols. METI funding supports construction of specialized angiography suites at designated cancer centers. Tokyo and Osaka academic medical centers anchor the Asia-Pacific's densest concentration of peptide receptor radionuclide therapy capacity for neuroendocrine metastases.
United Kingdom
NICE technology appraisals increasingly mandate real-world evidence for reimbursement continuation, forcing early movers in electronic health record integration to capture preferred formulary positioning. The NHS's specialized commissioning framework concentrates complex hepatic procedures at designated supra-regional centers. London, Manchester, and Birmingham host the country's principal hepatobiliary surgical volumes.
France
ANSM's early access programs allow temporary authorization for promising therapies in unmet medical needs, bridging gaps before full marketing authorization. HAS health technology assessment requirements filter which regimens reach national reimbursement lists. Paris and Lyon academic centers lead expansion of transarterial chemoembolization infrastructure for colorectal cancer metastases.
Liver Metastases Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue radioligand and bispecific antibody platforms. The competitive structure concentrates around three archetypes: integrated pharmaceutical conglomerates with deep oncology pipelines, mid-cap specialists in interventional radiology devices, and emerging radiopharmaceutical developers. Dominant competitive moves include strategic partnerships for isotope supply security and portfolio diversification into locoregional-systemic combination protocols.
Within the integrated pharmaceutical tier, F. Hoffmann-La Roche Ltd. and Bristol-Myers Squibb Company exemplify divergent strategic positions. Roche anchors its presence through hepatocellular combination therapy development, while Bristol-Myers Squibb occupies a position defined by checkpoint inhibitor portfolio breadth. Bayer AG represents the European-based archetype with sustained manufacturing scale for targeted small-molecule supply. These three entities collectively illustrate how geographic origin and therapeutic modality focus differentiate competitive positioning in hepatobiliary oncology.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| AstraZeneca |
| Bayer AG |
| Eli Lilly and Company |
| Pfizer, Inc. |
| Bristol-Myers Squibb Company |
| Ono Pharmaceutical |
| Merck & Co. |
| Ipsen |
| Others |
Value Network & Pricing Analysis
Checkpoint inhibitor cold-chain logistics bifurcate the market into premium biologics and commoditized cytotoxic agents, with the former commanding per-infusion pricing that reflects nuclear reactor isotope dependency and specialized angiography suite amortization across United States and German tertiary centers.
Pricing Analysis
Input-cost pass-through from Yttrium-90 radioisotope production concentrates pricing power among Canadian and Dutch reactor operators, with hospital pharmacy committees absorbing volatility through multi-year radioembolization contracts. Three-tier pricing structure across premium immunotherapy, standard targeted therapy, and economy cytotoxic levels reflects biomarker stratification and infusion supervision intensity. Pricing pressure stems from IRA drug pricing provisions reshaping Medicare negotiation dynamics for combination regimens. Community oncology practices exhibit highest price sensitivity due to fragmented companion diagnostic reimbursement.
Supply Chain Analysis
Radioisotope supply rests on aging nuclear reactors concentrated in Canada and the Netherlands, with cold-chain biologics distribution anchored in United States and German hospital networks. Yttrium-90 and lutetium-177 dependencies create single-source vulnerability for radioembolization and peptide receptor radionuclide therapy procedures. Tariff exposure runs through Chinese-sourced contrast media and European-ablation catheter components. Distribution runs through specialized radiopharmaceutical distributors serving academic medical center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in liver metastases treatment hinges on isotope supply security and premium-tier immunotherapy positioning, with biomarker-driven patient selection reducing waste and improving per-patient economics.
For Market Incumbents: Deepen backward integration into radioisotope production partnerships to secure Yttrium-90 supply against Canadian reactor outages. Expand dedicated hepatobiliary unit capacity in German and Japanese academic centers to capture fellowship-trained interventional radiologists. Invest in FDA breakthrough therapy designation pathways to compress formulary evaluation timelines.
For New Entrants and Emerging Players: Enter via peptide receptor radionuclide therapy capacity expansion in United States and German markets where neuroendocrine tumor penetration remains limited. Target academic medical center partnerships for lutetium-177 production infrastructure. Pursue EMA adaptive pathway submissions to accelerate European reimbursement negotiations.
For Investors and Strategic Acquirers: Consolidation pressure builds where radiopharmaceutical developers lack isotope supply security and hospital system distribution relationships. Long-term viability favors entities with integrated locoregional-systemic combination portfolios. Acquisition target archetypes include mid-cap interventional radiology device manufacturers with installed ablation platform bases. Watch FDA real-world evidence guidance evolution as inflection indicator for reimbursement continuity risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Radioisotope Supply Security Partnership | Direct sourcing agreements with Canadian and Dutch reactor operators bypass distributor markups for high-volume centers. |
| Biomarker-Driven Patient Selection Platform | Machine learning integration with EHR systems captures preferred formulary positioning under NICE and HAS requirements. |
| Interventional Radiology Fellowship Pipeline | Academic medical center training programs address operator shortages for complex transarterial procedures. |
| EMA Adaptive Pathway Submission | Conditional marketing authorization accelerates European patient access while confirmatory evidence accumulates. |
| Real-World Evidence Integration | Electronic health record connectivity satisfies United Kingdom and French HTA continuation criteria for reimbursement. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down pharmaceutical shipment tracking forms the analytical core of this study. Primary interviews with interventional radiologists, hospital pharmacy directors, formulary committee chairs, and payer access specialists were validated against FDA breakthrough therapy designations, EMA adaptive pathway approvals, ClinicalTrials.gov hepatobiliary oncology entries, and hospital procurement database extracts. Secondary sources include CMS Medicare reimbursement filings, GPO contract terms, and nuclear medicine procedure volume registries.
Historical trendline analysis across immunotherapy adoption curves and radioembolization procedure volumes established baseline growth patterns. Segmentation modeling incorporated treatment modality, delivery mode, end-user facility type, and regional regulatory cluster dimensions. CAGRs were derived from procedure volume trajectories and per-patient therapy cost evolution across the projection horizon. Forecast inputs include biomarker testing penetration rates and interventional radiology suite construction pipelines at designated cancer centers.
Inputs from hospital procurement systems and pharmaceutical distribution networks were available through the study window; gaps in real-world outcome data for combination regimens introduce uncertainty bands around reimbursement continuation assumptions. Forecasts reflect modeled assumptions regarding FDA accelerated approval sustainability and EMA conditional authorization conversion rates. Material deviation in isotope supply reliability or IRA negotiation scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Personalized Medicine Market
Specialty Medicine
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Global Acute Agitation and Aggression Treatment Market
Specialty Medicine
Global Melanoma Therapeutics Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
Zygomycosis Treatments Market
Specialty Medicine
Global Gastrointestinal Therapeutics Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market