
 Carcinoid Tumor Syndrome Management Market | 2026-2036
Carcinoid Tumor Syndrome Management Market Size, Share, and Industry Trends Forecast 2026-2036
Carcinoid Tumor Syndrome Management Market Outlook
Long-acting injectable formulations is redrawing competitive boundaries in carcinoid syndrome management. Novartis leverages its established manufacturing scale in peptide therapeutics to sustain supply security across hospital networks. Ipsen Biopharmaceuticals differentiates through specialized commercial infrastructure in neuroendocrine oncology. Crinetics Pharmaceuticals positions its pipeline assets toward next-generation somatostatin receptor modulation.
Carcinoid tumor syndrome management encompasses the clinical and pharmacologic interventions directed at controlling hormonal hypersecretion, flushing, diarrhea, and bronchospasm arising from neuroendocrine tumors, with somatostatin analogues functioning as first-line therapy through receptor-mediated inhibition of peptide release. The primary purpose centers on symptom palliation, tumor growth suppression, and prevention of carcinoid crisis during surgical or interventional procedures. Somatostatin analogues occupy the dominant revenue position given their entrenched guideline status and extended-release formulation advantages, while targeted therapy represents the fastest-expanding segment as mTOR and tyrosine kinase inhibitors gain traction in progressive disease. Injectable delivery mode commands the largest volume share, though subcutaneous administration is gaining ground in home care transitions.
The FDA's orphan drug program and the EMA's Committee for Orphan Medicinal Products shape development incentives and exclusivity frameworks for rare neuroendocrine indications, directly influencing pipeline prioritization and market access timelines. The WHO's essential medicines criteria and national formularies in Germany, France, and Japan determine reimbursement thresholds for somatostatin analogue therapy across public health systems. Stakeholders must monitor evolving radioligand therapy integration patterns and their impact on traditional pharmacologic management sequencing decisions.
Market Dynamics
The integration of radioligand therapy into standard care sequences is compressing the treatment window for traditional somatostatin analogues, forcing repositioning of long-acting injectables as bridge or maintenance therapy rather than sole disease management.
Growth Catalysts
- FDA Orphan Drug Designation:The accelerated approval pathway reduces clinical trial requirements for novel somatostatin receptor modulators, compressing development timelines for rare neuroendocrine indications.
- Specialty Clinic Expansion:Dedicated neuroendocrine tumor service lines at academic medical centers concentrate referral volume and standardize guideline-concordant prescribing patterns.
- Peptide Manufacturing Scale-Up:Contract manufacturing organizations in Switzerland and Ireland are expanding GMP capacity for complex parenteral formulations.
Market Restraints
- API Supply Concentration:Cyclic octapeptide active pharmaceutical ingredients depend on a limited supplier base in Northern Europe, creating single-source vulnerability.
- Reimbursement Friction:Germany's AMNOG process imposes early benefit assessment requirements that delay market access for novel analogue formulations.
- Substitute Therapy Displacement:Lutetium-177 based radioligand therapy captures progressive disease patients who would otherwise escalate pharmacologic management.
Strategic Opportunities
- Home Administration Transition:Subcutaneous device platforms enable shift from infusion center to self-administered care, opening ambulatory and retail pharmacy channels.
- Japan's Sakigake Pathway:The PMDA's expedited review system for innovative drugs offers priority consultation and shortened approval timelines for first-in-class entrants.
- Biomarker-Guided Sequencing:SSTR2 expression profiling creates segmentation opportunity for personalized analogue selection ahead of radioligand candidacy determination.
Industry Challenges
- Peptide Synthesis Expertise Gap:Purification and cyclization chemistry capabilities required for somatostatin analogue production remain concentrated among legacy specialists.
- Multinational Trial Complexity:Rare disease enrollment requirements across FDA, EMA, and PMDA jurisdictions extend study duration and inflate clinical development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carcinoid Tumor Syndrome Management Market |
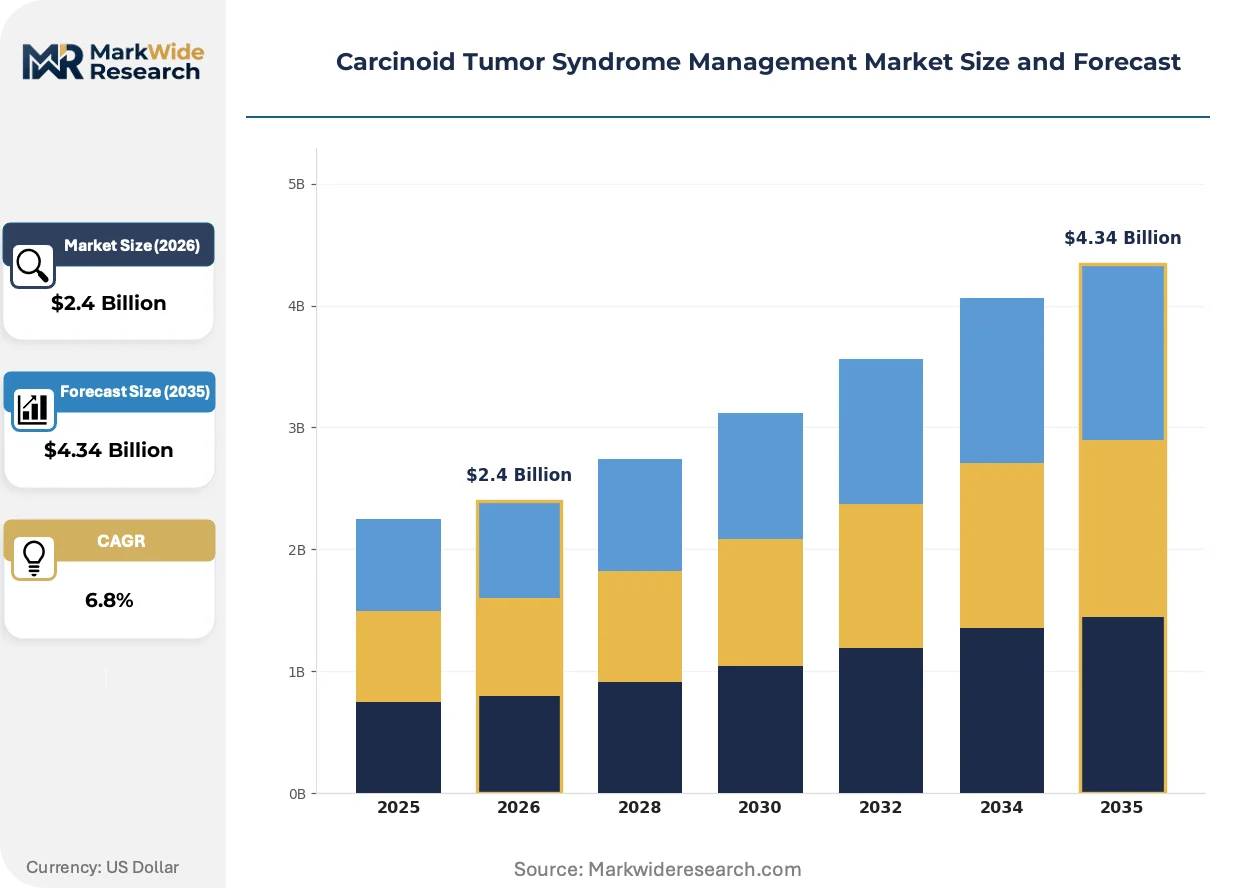
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Somatostatin Analogues, Chemotherapy, Interferon Therapy, Targeted Therapy Delivery Mode: Injectable, Oral, Intravenous, Subcutaneous End User: Hospitals, Specialty Clinics, Research Institutes, Home Care Treatment Type: Symptomatic Treatment, Curative Treatment, Palliative Care, Follow-Up Care |
| Companies Covered | Novartis, Ipsen Biopharmaceuticals, Pfizer, Teva Pharmaceutical, BTG International, Crinetics Pharmaceuticals, Sandoz, Lexicon Pharmaceuticals, Sanwa Kagaku Kenkyusho, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carcinoid Tumor Syndrome Management Market Strategic Shifts
Radiopharmaceutical integration is forcing simultaneous evolution in diagnostic companion imaging and therapeutic sequencing protocols, reshaping how medical oncologists coordinate care across interventional radiology and medical oncology service lines.
Next-generation somatostatin receptor subtype-selective agonists are fragmenting the historical SSTR2-dominant paradigm. Crinetics Pharmaceuticals and specialized biotech developers are advancing compounds with differential affinity profiles for SSTR1 and SSTR5 subtypes. Academic medical centers with dedicated neuroendocrine programs are adopting these candidates in basket trial frameworks. The established long-acting octreotide and lanreotide franchise is fragmenting into indication-specific and receptor-optimized substitutable segments.
The EMA's revised orphan drug exclusivity framework now requires demonstration of significant benefit over existing therapies, tightening the evidentiary threshold for new somatostatin analogue approvals. This policy shift elevates the importance of head-to-head noninferiority or superiority trial designs. German and French health technology assessment bodies are responding with stricter incremental cost-effectiveness ratio ceilings for products lacking differentiated clinical outcomes.
Specialty pharmacy distribution is displacing traditional hospital-based procurement for stable carcinoid syndrome patients. Payers in the United States are mandating exclusive specialty pharmacy relationships to capture rebates and manage prior authorization workflows. Community oncology practices without neuroendocrine tumor expertise are referring stable patients to these channels, concentrating volume with distributors possessing dedicated rare disease cold-chain capabilities.
Carcinoid Tumor Syndrome Management Market Segmentation
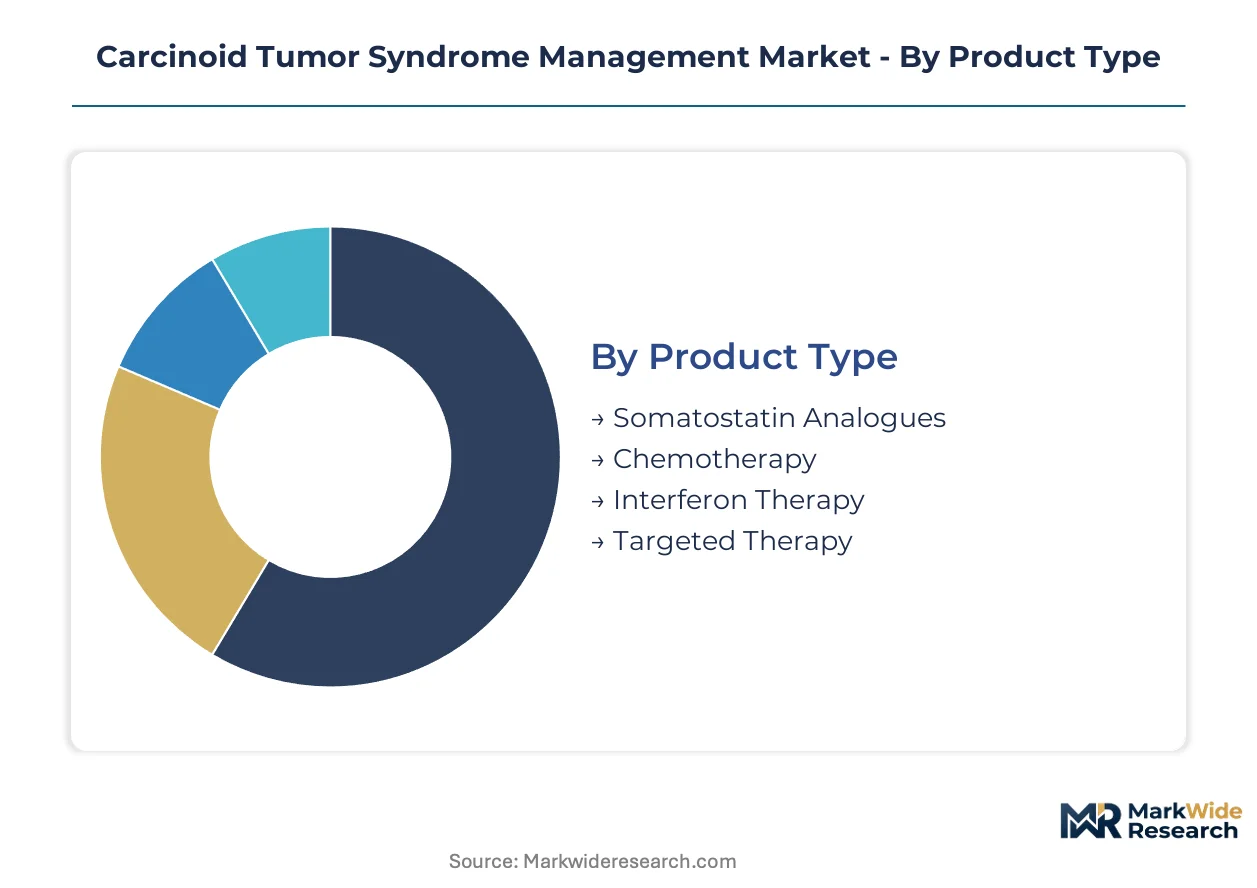
Segmentation in carcinoid syndrome management reveals how treatment settings, administration routes, and therapeutic modalities fragment across care pathways. Each dimension carries distinct regulatory, reimbursement, and supply chain implications that shape commercial strategy.
Product Type:
Somatostatin analogues anchor domestic demand in the United States and Western Europe, where established reimbursement pathways support chronic administration. Export-led growth concentrates in targeted therapy segments seeking accelerated approval in Asian markets.
- Somatostatin Analogues:Cyclic octapeptide formulations including octreotide and lanreotide bind SSTR2 receptors to inhibit peptide hormone secretion. Demand clusters in academic medical centers with dedicated neuroendocrine tumor programs across the United States, Germany, and France, driven by entrenched guideline recommendations and long-acting depot formulations that reduce injection frequency.
- Targeted Therapy:mTOR inhibitors and tyrosine kinase inhibitors address progressive disease through distinct mechanistic pathways. Expansion concentrates in Japan's Sakigake pathway and South Korea's MFDS fast-track designations, where novel mechanisms receive priority review for orphan indications.
- Chemotherapy:Cytotoxic regimens retain niche application in poorly differentiated neuroendocrine neoplasms.
- Interferon Therapy:Immunomodulatory approach employed when somatostatin analogues prove insufficient.
Somatostatin analogues command the established base. The steepest expansion runs through targeted therapy.
Delivery Mode:
Cost tier differentiation separates hospital-administered intravenous formulations from subcutaneous devices enabling ambulatory migration. Volume concentration favors long-acting injectables, while margin accretion concentrates in patient-administered platforms.
- Injectable:Long-acting intramuscular depot formulations dominate maintenance therapy, requiring cold-chain distribution through specialty pharmacy networks. Manufacturing scale at Novartis and Ipsen facilities in Switzerland and Ireland secures supply for hospital and clinic channels.
- Subcutaneous:Device-enabled self-administration shifts care from infusion centers to home settings. United States payers increasingly mandate exclusive specialty pharmacy relationships, capturing rebates while reducing site-of-care costs.
- Intravenous:Acute administration route for carcinoid crisis management and perioperative coverage.
- Oral:Limited current application given peptide bioavailability constraints, though formulation innovation continues.
Injectable delivery retains volume leadership. Subcutaneous platforms are gaining share fastest through home care transitions.
End User:
Customer type stratification reflects referral concentration versus dispersion. Academic medical centers with neuroendocrine tumor expertise drive complex case management, while community settings handle stable maintenance populations.
- Hospitals:Tertiary centers manage acute carcinoid crisis, surgical coordination, and radioligand therapy integration. United States National Cancer Institute-designated centers concentrate trial enrollment and novel therapy access.
- Specialty Clinics:Dedicated neuroendocrine tumor service lines at institutions like MD Anderson and Memorial Sloan Kettering standardize guideline-concordant sequencing. Germany's university hospitals and France's cancer centers (CLCCs) replicate this model across public systems.
- Home Care:Stable patients on established somatostatin analogue regimens transition to self-administration with nursing oversight.
- Research Institutes:Academic centers conduct basket trials for receptor-subtype selective agonists.
Hospitals anchor complex case management. Specialty clinics are expanding most quickly as service line differentiation intensifies.
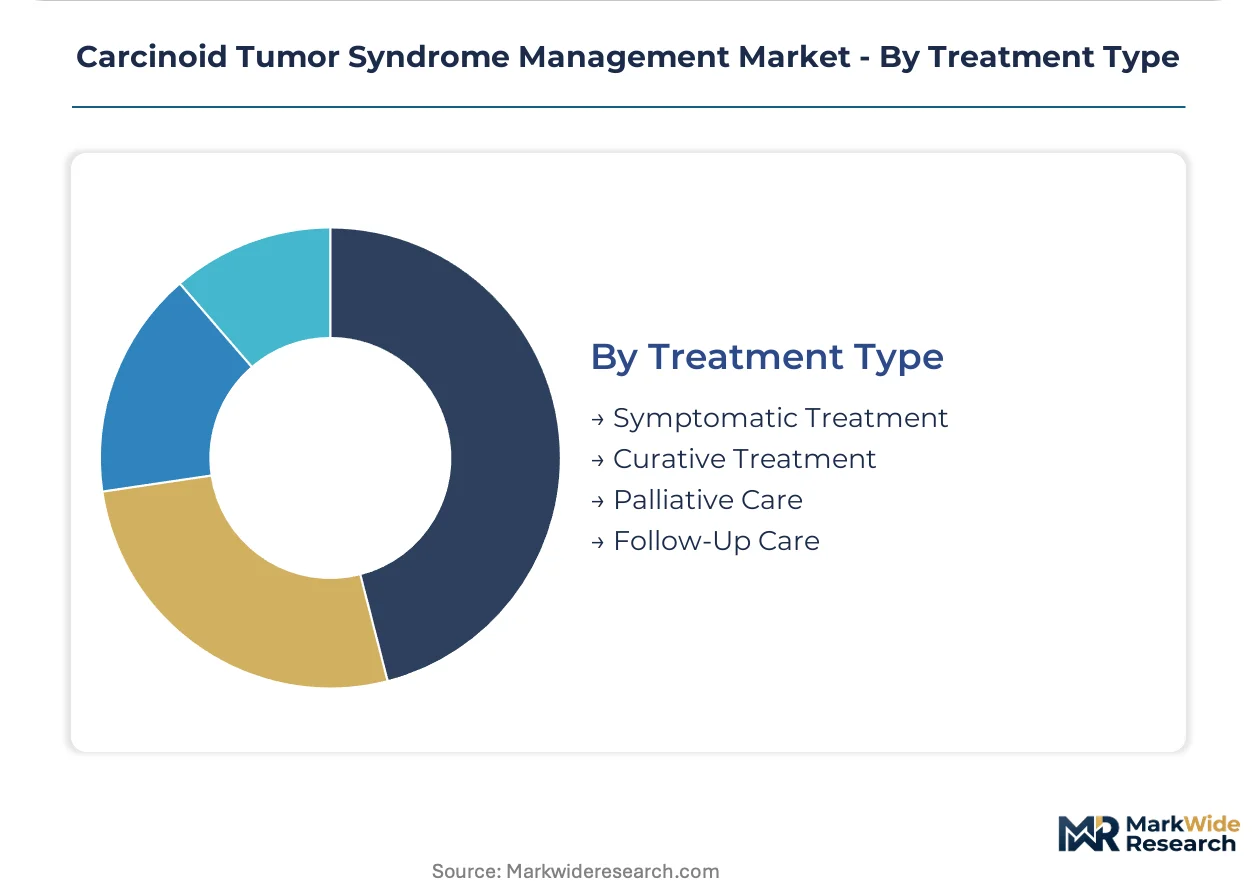
Treatment Type:
Maturity gradients separate decades-established symptomatic control from evolving curative intent paradigms. Application focus varies by disease stage, with palliative and follow-up care extending duration of pharmacologic exposure.
- Symptomatic Treatment:First-line somatostatin analogue therapy for flushing, diarrhea, and bronchospasm control. Demand concentrates in United States community oncology referrals and European hospital outpatient departments, where rapid symptom palliation drives initiation decisions.
- Palliative Care:End-stage disease management emphasizes quality-of-life preservation through optimized analogue dosing and anti-secretory adjuncts. Hospice partnerships in the United States and palliative care networks in the United Kingdom create dedicated procurement channels.
- Curative Treatment:Surgical resection coordination with perioperative somatostatin analogue coverage to prevent carcinoid crisis.
- Follow-Up Care:Long-term surveillance with biochemical monitoring and imaging surveillance.
Symptomatic treatment commands the established base. Palliative care is climbing the fastest as disease prevalence in aging populations expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland exports long-acting somatostatin analogue formulations to hospital networks across Germany, France, and the United States, anchoring the trade corridor for carcinoid syndrome therapeutics.
United States
NCI-designated cancer centers concentrate referral volume for neuroendocrine tumor management, with MD Anderson and Memorial Sloan Kettering standardizing somatostatin analogue sequencing. The FDA orphan drug designation accelerates development timelines for novel receptor modulators. Specialty pharmacy networks in Boston and Houston manage cold-chain distribution for home-administered depot formulations.
Germany
University hospitals in Munich and Heidelberg anchor complex case management for progressive neuroendocrine neoplasms. The AMNOG early benefit assessment process imposes stringent cost-effectiveness requirements on novel analogue entrants. Bavaria's peptide manufacturing cluster supplies active pharmaceutical ingredients to formulation facilities across the Rhine-Main region.
Japan
Aging demographics expand the addressable population for palliative carcinoid syndrome management. The PMDA Sakigake pathway offers priority consultation and shortened review timelines for first-in-class somatostatin receptor agonists. Tokyo's academic medical centers lead basket trial enrollment for receptor-subtype selective compounds.
France
Cancer centers (CLCCs) in Paris and Lyon coordinate multidisciplinary neuroendocrine tumor care with standardized guideline protocols. ANSM regulates somatostatin analogue market access through the Temporary Authorization for Use framework for orphan indications. The Île-de-France region concentrates radioligand therapy integration with pharmacologic management.
Carcinoid Tumor Syndrome Management Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and commercial infrastructure dimensions. The market consolidates around established peptide therapeutics manufacturers with captive synthesis capabilities and emerging biotech developers advancing next-generation receptor modulation. Three archetypes dominate: legacy pharmaceutical conglomerates with integrated supply chains, specialized oncology-focused biopharmaceuticals, and clinical-stage innovators pursuing subtype-selective agonists. Capacity expansion in Swiss and Irish GMP facilities and strategic partnerships for radioligand therapy co-development represent the dominant competitive moves.
Among established manufacturers, Novartis and Ipsen Biopharmaceuticals occupy positions defined by manufacturing scale and specialized commercial infrastructure in neuroendocrine oncology. Crinetics Pharmaceuticals exemplifies the clinical-stage archetype, with its pipeline oriented toward differentiated somatostatin receptor subtype targeting.
| Leading Market Players |
|---|
| Novartis |
| Ipsen Biopharmaceuticals |
| Pfizer |
| Teva Pharmaceutical |
| BTG International |
| Crinetics Pharmaceuticals |
| Sandoz |
| Lexicon Pharmaceuticals |
| Sanwa Kagaku Kenkyusho |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Swiss peptide manufacturers and United States specialty pharmacy networks lock in supply access while anchoring price visibility for somatostatin analogue formulations. These contracts insulate hospital procurement teams from API volatility while exposing them to step-pricing clauses tied to manufacturing scale achievements.
Pricing Analysis
Current-generation long-acting octreotide and lanreotide depot formulations command premium positioning against prior-generation short-acting alternatives, while next-generation SSTR1/SSTR5-selective agonists in development threaten to reset pricing benchmarks entirely. The market runs on a value-based pricing structure where reimbursement thresholds from Germany's G-BA and France's HAS determine commercial viability more than manufacturing cost. Price differentiation separates originator formulations with orphan exclusivity from biosimilar entrants competing on volume scale. Pricing pressure stems from radioligand therapy displacement capturing progressive disease patients who would otherwise escalate pharmacologic management. Community oncology practices exhibit highest price sensitivity due to thin margin profiles, while NCI-designated centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate hospital procurement for acute carcinoid crisis coverage, while strategic stockpiling characterizes specialty pharmacy networks managing chronic patient populations on depot formulations. Manufacturing concentrates in Switzerland, Ireland, and Denmark where cyclic octapeptide synthesis expertise and GMP cold-chain infrastructure cluster. Raw material dependencies center on protected amino acid precursors, specialized chromatography resins, and single-use bioreactor components. Single-source vulnerability in Northern European API supply creates structural risk given limited qualified cyclization chemistry specialists. Distribution runs through temperature-controlled specialty pharmacy channels with exclusive payer mandates increasingly displacing traditional hospital-based procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peptide synthesis expertise and radioligand therapy coordination capabilities have become the scarce assets determining competitive position, with fewer than a dozen facilities globally qualified for commercial-scale somatostatin analogue production.
For Market Incumbents: Compound manufacturing scale advantages by securing captive supply of cyclic octapeptide APIs through backward integration into Northern European synthesis facilities. Expand capacity in Swiss and Irish GMP sites to preempt supply constraints as radioligand therapy integration accelerates patient volume. Defend against SSTR-subtype selective entrants by accelerating head-to-head trial enrollment demonstrating non-inferiority in symptom control endpoints. For New Entrants and Emerging Players: Anchor in Japan's Sakigake pathway and South Korea's MFDS fast-track designations where novel mechanism priority review offers compressed approval timelines versus FDA and EMA queues. Target home-administration device platforms as the most penetrable segment given United States payer mandates shifting stable patients from infusion centers to self-managed care. Pursue biomarker-guided sequencing partnerships with academic medical centers running basket trials for receptor-subtype selective candidates. For Investors and Strategic Acquirers: Capital is best deployed toward clinical-stage innovators with differentiated SSTR1 or SSTR5 pharmacology and established peptide manufacturing partnerships rather than late-stage assets facing radioligand therapy displacement. Long-term viability hinges on radioligand therapy co-development capabilities or radiopharmaceutical integration expertise as standard-of-care sequencing evolves. Watch for EMA orphan exclusivity framework enforcement tightening evidentiary requirements for new analogue approvals as the inflection signal indicating consolidation pressure on marginal pipeline assets.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Swiss and Irish GMP capacity expansion secures supply security for hospital networks managing radioligand therapy integration. |
| Regulatory Approval Pathway | Japan's PMDA Sakigake priority consultation compresses timelines for first-in-class somatostatin receptor modulators. |
| Licensing Agreement | Radiopharmaceutical co-development partnerships enable coordinated diagnostic-therapeutic sequencing protocols. |
| Pipeline Diversification | SSTR1 and SSTR5 subtype-selective agonists fragment the historical SSTR2-dominant paradigm. |
| Reimbursement Strategy | Specialty pharmacy exclusive relationships capture payer rebates while reducing site-of-care costs. |
Study Parameters
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary interviews with neuroendocrine oncology specialists and payer access specialists were cross-validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down epidemiological triangulation anchored volume estimates across the analysis window.
Segmentation dimensions modeled include treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs were derived from patient population projections, therapy sequencing assumptions, and pricing trajectory analysis throughout the forecast period. Forecast inputs incorporated radioligand therapy penetration curves, orphan drug exclusivity expiration schedules, and biosimilar entry probability assessments.
Decision-makers should treat outputs as directional under assumptions of stable regulatory frameworks and continued radioligand therapy adoption; material deviation in reimbursement policy or therapeutic sequencing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Congenital Adrenal Hyperplasia Treatment Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Cerebral Palsy Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
CARD9 Deficiency Treatment Market
Specialty Medicine
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Hemochromatosis Treatment Market
Specialty Medicine
Triple X Syndrome Management Market