
 Global Nephropathic Cystinosis Treatment Market | 2026-2036
Global Nephropathic Cystinosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nephropathic Cystinosis Treatment Market Foresight
A shift from single-source orphan drug procurement to multi-source contracting is rebalancing supply security for cysteamine-based therapies across European hospital networks. Recordati Rare Diseases leverages its established European distribution infrastructure to sustain preferential formulary placement in Italian and French rare disease centers. Horizon Therapeutics plc competes through specialized patient support programs that anchor adherence rates among pediatric nephrology practices. Chiesi Farmaceutici S.p.A. differentiates via focused investment in heat-stable cysteamine formulations that occupy a narrow but defensible technical niche.
Nephropathic cystinosis treatment encompasses pharmaceutical and biologic interventions that reduce intralysosomal cystine accumulation through cystine-depleting agents, antioxidants, and emerging stabilizer compounds, typically administered via oral or intravenous routes to prevent renal Fanconi syndrome and end-stage kidney disease progression. Cystine Depleting Agents dominate current revenue pools due to decades of clinical validation and established reimbursement pathways, while the Oral administration route captures the majority of maintenance therapy volumes despite bioavailability challenges that drive research into sublingual alternatives. Homecare delivery is expanding fastest among End User segments as parents and adult patients seek to reduce hospital visitation burdens, though Hospitals retain concentrated margin capture from initial diagnosis and acute complication management.
FDA orphan drug designation and EMA's orphan medicinal product framework jointly shape clinical trial incentives and extended market exclusivity periods for developers targeting this ultra-rare indication. REACH compliance requirements for active pharmaceutical ingredient sourcing constrain European formulation choices, while WHO inclusion of cystinosis on its rare disease priority list is accelerating national newborn screening program expansions in middle-income health systems. Stakeholders must monitor gene therapy readouts from Avrobio and academic collaborators to assess whether in vivo correction approaches will displace chronic small-molecule management paradigms before manufacturing scale-up investments crystallize.
Market Dynamics
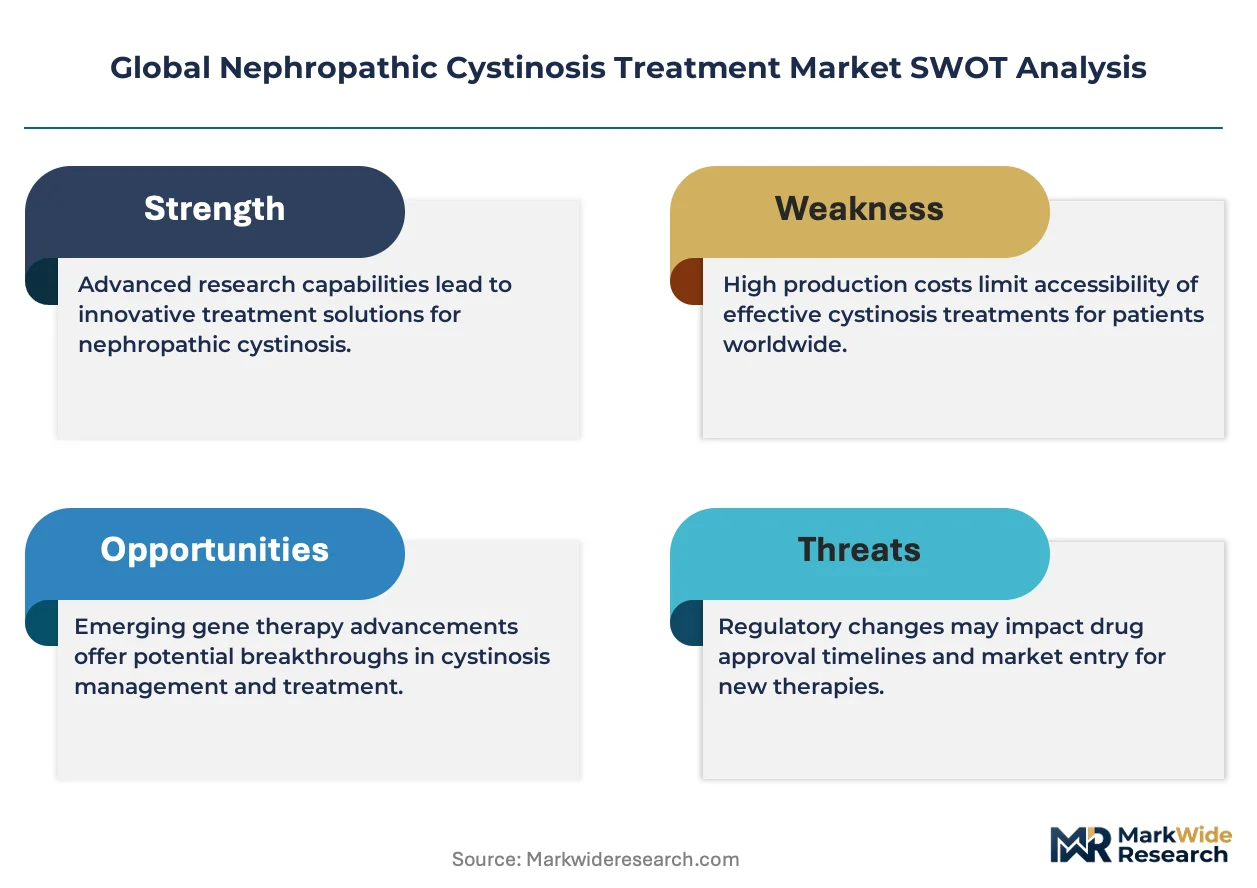
Gene therapy pipelines targeting the CTNS mutation are redirecting capital flows and clinical trial infrastructure toward modalities that could eventually displace chronic small-molecule management paradigms in nephropathic cystinosis care.
Growth Catalysts
- EMA Orphan Drug Incentives:Extended market exclusivity periods and protocol assistance are accelerating pediatric nephrology clinic procurement across Italy, France, and Germany.
- WHO Rare Disease Priority Listing:Inclusion of cystinosis on this list is driving national newborn screening program expansions in middle-income health systems across Southeast Asia and Latin America.
- Heat-Stable Formulation Advances:Next-generation cysteamine chemistry is reducing cold-chain dependency and enabling homecare delivery models in regions with limited hospital infrastructure.
Market Restraints
- Active Pharmaceutical Input Concentration:REACH compliance requirements constrain European formulation choices to a narrow supplier base in Switzerland and Germany.
- Gene Therapy Manufacturing Bottlenecks:Viral vector production capacity limitations in the United States and Switzerland are extending lead times for clinical-grade material.
- Reimbursement Fragmentation:Orphan drug pricing negotiations vary dramatically between national health technology assessment bodies in England, France, and Germany.
Strategic Opportunities
- Sublingual Delivery Platforms:Bioavailability-enhancing absorption technologies are opening maintenance therapy segments where oral cysteamine tolerance is poor.
- Homecare Channel Expansion:Specialty pharmacy networks in the United States are capturing margin from hospital-based infusion centers through direct-to-patient distribution.
- Academic Gene Therapy Collaborations:Partnerships between Swiss research institutes and US-based biotech developers are accelerating in vivo correction approaches.
Industry Challenges
- Patient Registry Data Harmonization:Cross-border clinical outcome tracking remains fragmented between European Reference Networks and US-based natural history studies.
- Gene Therapy Talent Scarcity:Shortages of translational medicine specialists with lysosomal storage disorder expertise are slowing pipeline progression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nephropathic Cystinosis Treatment Market |
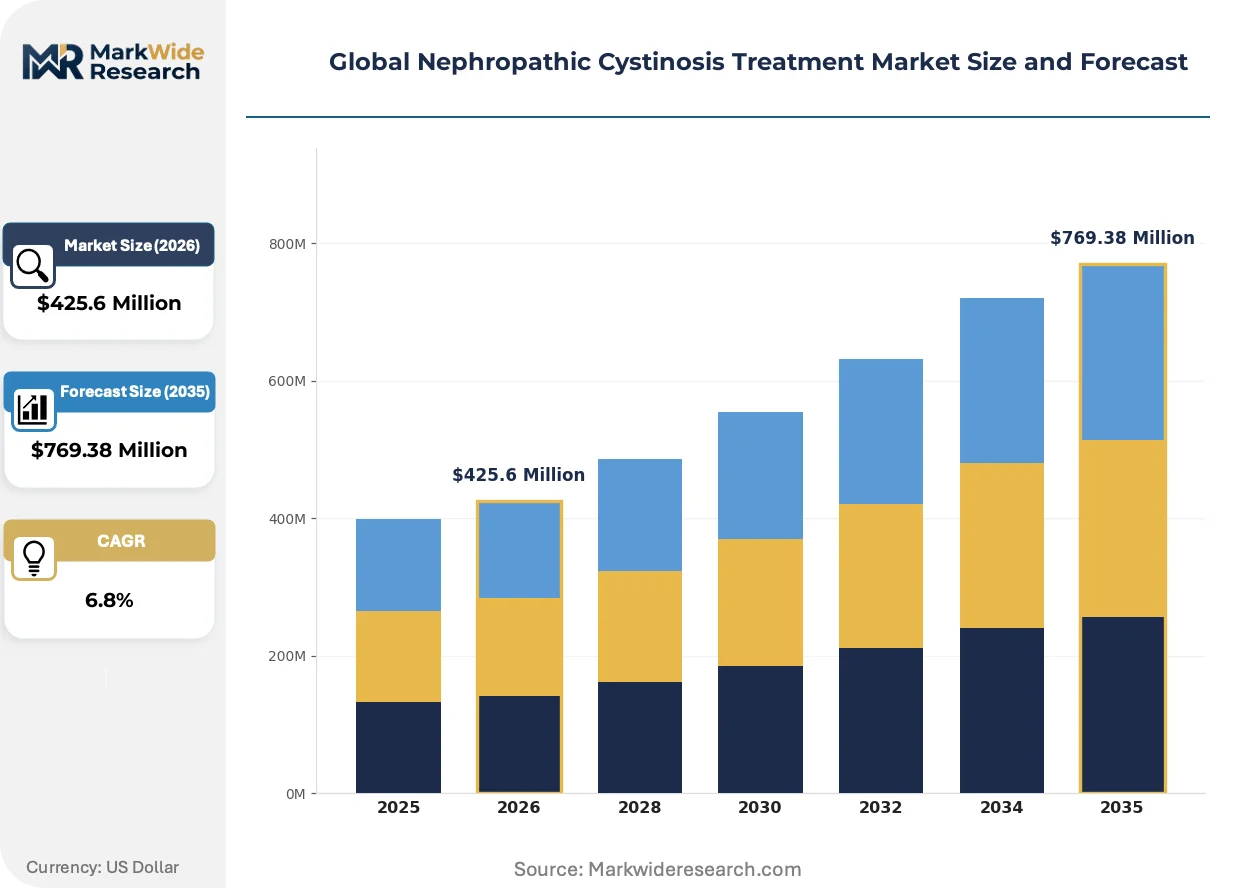
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $769.38 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cystine Depleting Agents, Antioxidants, Stabilizers, Other Therapeutics Administration Route: Oral, Injectable, Intravenous, Sublingual End User: Hospitals, Clinics, Homecare, Research Institutes Packaging Type: Bottles, Blister Packs, Vials, Sachets |
| Companies Covered | Horizon Therapeutics plc, Recordati Rare Diseases, Viatris Inc., Chiesi Farmaceutici S.p.A., Leadiant Biosciences, Inc., Eloxx Pharmaceuticals Inc., Amgen Inc., GlaxoSmithKline plc, Avrobio, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nephropathic Cystinosis Treatment Market Shifts & Advancements
Lentiviral and CRISPR-based gene editing platforms are competing for clinical validation in nephropathic cystinosis, while formulation chemistry and distribution models undergo parallel reinvention to reduce treatment burden.
Heat-stable cysteamine formulations are modularizing supply chain requirements for cystine-depleting therapy distribution. Italian and French rare disease centers are adopting these formulations to eliminate refrigeration dependencies in rural patient populations. The technology is compressing total cost of ownership for homecare delivery programs and expanding addressable geography beyond traditional hospital catchment zones.
REACH compliance for active pharmaceutical ingredient sourcing is tightening formulation choices available to European manufacturers. ECHA substance of very high concern listings are forcing reformulation investments for legacy cysteamine salts. German and Swiss contract manufacturers are responding by qualifying alternative synthetic routes that maintain impurity profiles within specification.
Parent and patient advocacy networks are consolidating purchasing influence through centralized procurement platforms in the United States. Pediatric nephrology practices are unbundling drug acquisition from clinical service fees, redirecting margin toward patient support program investments. This behavioral shift is most visible in California and Massachusetts, where integrated delivery networks dominate rare disease care coordination.
Global Nephropathic Cystinosis Treatment Market Segmentation
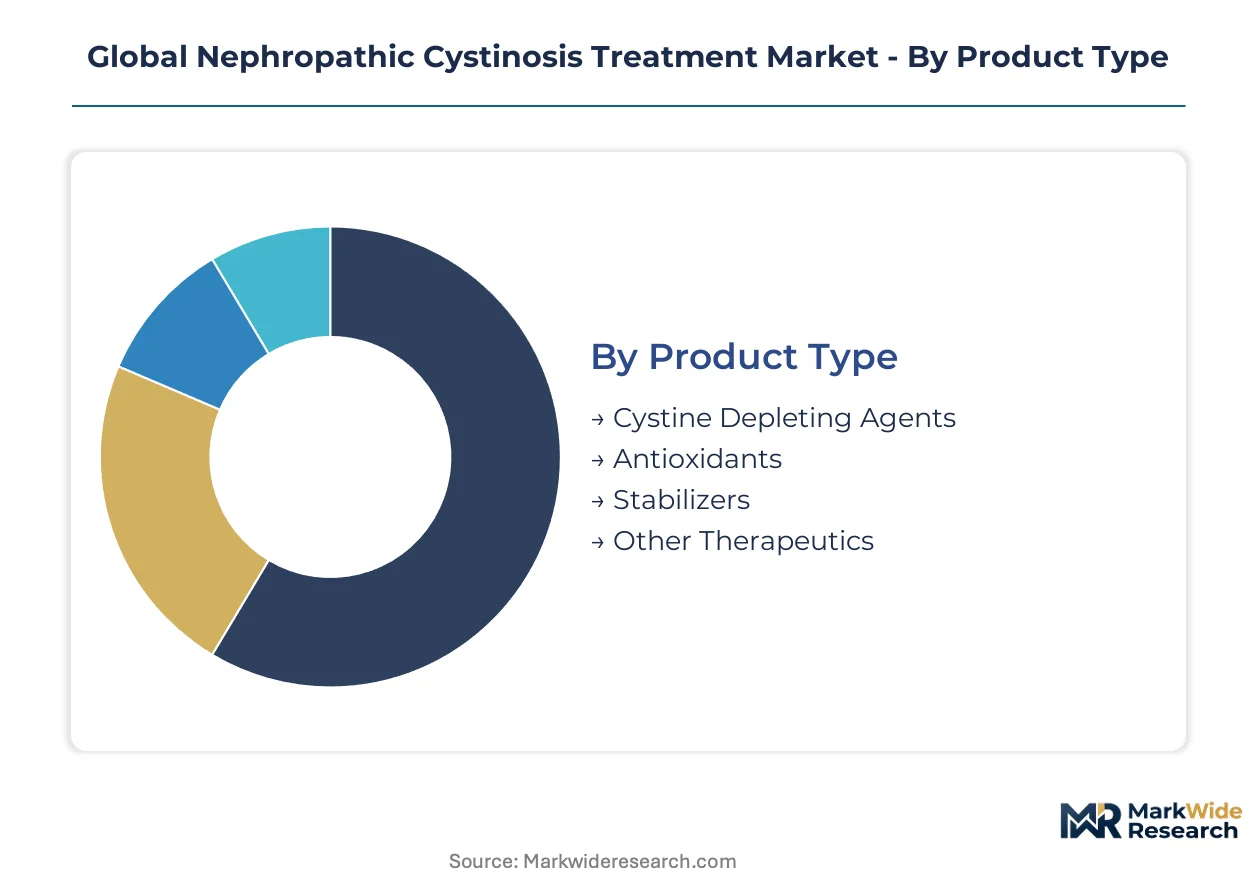
Nephropathic cystinosis treatment segments reflect competing pressures between chronic disease management economics and curative modality development. Product chemistry, delivery convenience, and care setting economics each create distinct procurement and reimbursement pathways across patient lifecycles.
Product Type:
Mechanism of action defines clinical positioning and regulatory precedent for each therapeutic class in this indication.
- Cystine Depleting Agents:Oral and topical cysteamine formulations reduce intralysosomal cystine accumulation through lysosomal cystine export restoration. Procurement concentrates in Italian and French rare disease centers where EMA orphan drug incentives sustain preferential formulary placement for chronic maintenance protocols.
- Antioxidants:Ascorbic acid and alpha-lipoic acid derivatives mitigate oxidative damage from cystine crystal accumulation. Demand clusters in German pediatric nephrology networks where combination therapy protocols address residual Fanconi syndrome complications.
- Stabilizers:Heat-stable cysteamine salts and modified-release matrices extend shelf stability beyond cold-chain requirements.
- Other Therapeutics:Adjunctive agents addressing electrolyte wasting and growth hormone deficiency in cystinosis patients.
Mature deployment sits with Cystine Depleting Agents. Newer deployment is concentrated in Stabilizers.
Administration Route:
Patient adherence economics and bioavailability limitations drive route selection across pediatric and adult patient populations.
- Oral:Immediate-release and enteric-coated cysteamine bitartrate capsules constitute the maintenance therapy standard despite gastrointestinal intolerance and six-hour dosing intervals. Volume concentrates in United States specialty pharmacy networks where direct-to-patient distribution reduces hospital visitation burdens for working-age adults.
- Sublingual:Mucoadhesive films and rapidly dissolving tablets bypass first-pass metabolism to improve bioavailability. Adoption is climbing the fastest in Swiss and United States academic medical centers where patient support programs address oral formulation failures.
- Injectable:Subcutaneous depot formulations for patients with severe malabsorption.
- Intravenous:Hospital-administered cysteamine for acute decompensation or perioperative management.
Oral administration captures the highest patient volumes. Sublingual delivery is gaining share fastest among route alternatives.
End User:
Care setting determines margin capture allocation between drug acquisition and clinical service reimbursement.
- Hospitals:Academic medical centers manage initial diagnosis, genotype confirmation, and acute complication protocols including electrolyte crises and thyroid dysfunction. Margin concentrates in California and Massachusetts integrated delivery networks where rare disease care coordination commands premium reimbursement.
- Homecare:Specialty pharmacy and nursing services enable maintenance therapy outside institutional settings. Expansion is steepest in United States markets where parents and adult patients prioritize reduced clinic visitation frequency.
- Clinics:Community pediatric nephrology practices for stable patient monitoring.
- Research Institutes:Academic gene therapy trial sites and natural history study enrollment centers.
Hospitals retain concentrated margin from diagnosis and acute episodes. Homecare is expanding most quickly among end user segments.
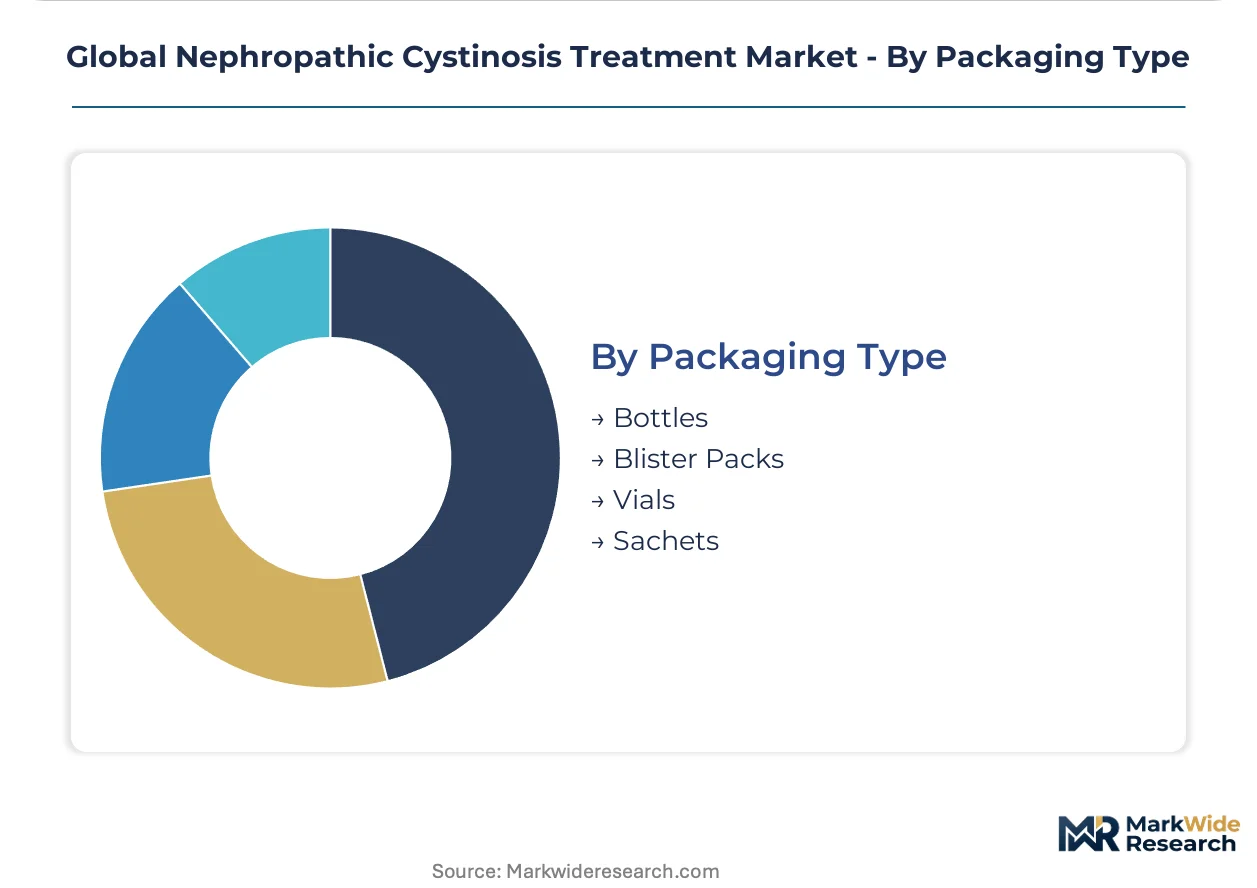
Packaging Type:
Unit-dose configuration shapes cold-chain requirements, patient compliance aids, and pharmacy inventory economics.
- Blister Packs:Aluminum-aluminum cold-form foil configurations protect moisture-sensitive cysteamine salts from humidity degradation. Procurement dominates in Western European hospital networks where REACH compliance constraints favor qualified barrier materials from German and Swiss suppliers.
- Bottles:HDPE containers with desiccant closures for high-volume institutional dispensing.
- Vials:Sterile glass for injectable and intravenous formulations.
- Sachets:Single-dose powder packets for pediatric patients requiring dose titration.
Blister pack deployment is most mature in regulated European markets. Sachet adoption is concentrating in emerging market expansions where dose flexibility addresses weight-based pediatric protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss pharmaceutical chemistry clusters and German contract manufacturing infrastructure anchor the active pharmaceutical ingredient supply base for cystine-depleting therapies. Pediatric nephrology demand concentrates in academic medical centers across five countries with distinct reimbursement and regulatory frameworks.
United States
FDA orphan drug exclusivity periods sustain premium pricing for maintenance cysteamine therapies. Integrated delivery networks in California and Massachusetts unbundle drug acquisition from clinical service fees. The National Institutes of Health funds natural history studies through the Rare Diseases Clinical Research Network.
Germany
EMA protocol assistance accelerates pediatric trial enrollment at Heidelberg and Berlin academic centers. REACH compliance requirements constrain formulation choices to qualified German and Swiss contract manufacturers. The Federal Joint Committee evaluates orphan drug cost-effectiveness through early benefit assessment pathways.
Switzerland
Swissmedic expedites marketing authorization for heat-stable cysteamine formulations targeting rural patient populations. Basel and Zurich host gene therapy vector production facilities serving European clinical trials. The country's bilateral agreements with EMA streamline regulatory convergence for rare disease therapies.
Italy
Regional health authorities in Lombardy and Lazio consolidate procurement for rare disease centers through centralized tenders. AIFA orphan drug designation provides tax incentives for local formulation investments. Milan-based pediatric nephrology networks coordinate newborn screening program expansions.
France
ANSM enforces stringent cold-chain documentation for hospital-based cysteamine distribution. The French National Authority for Health evaluates long-term cost-effectiveness through multi-criteria decision analysis. Paris and Lyon rare disease centers participate in European Reference Networks for lysosomal storage disorders.
Global Nephropathic Cystinosis Treatment Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers secure gene therapy manufacturing capacity and distribution infrastructure. The market structure consolidates around three tiers: established orphan drug specialists with European distribution networks, mid-cap biotechs advancing lentiviral platforms, and diversified pharmaceutical companies with rare disease franchises. Two archetypes anchor competitive positioning: formulation innovators pursuing heat-stable chemistry and gene therapy developers targeting curative modalities. M&A activity and technology licensing agreements constitute the primary competitive moves reshaping participant rosters.
Among established orphan drug specialists, Horizon Therapeutics plc and Recordati Rare Diseases exemplify distribution-centric competitive positioning, while Chiesi Farmaceutici S.p.A. occupies a technical niche through formulation investments. These three entities represent divergent strategic archetypes: patient support program anchoring, European infrastructure leveraging, and heat-stable chemistry differentiation respectively.
| Leading Market Players |
|---|
| Horizon Therapeutics plc |
| Recordati Rare Diseases |
| Viatris Inc. |
| Chiesi Farmaceutici S.p.A. |
| Leadiant Biosciences, Inc. |
| Eloxx Pharmaceuticals Inc. |
| Amgen Inc. |
| GlaxoSmithKline plc |
| Avrobio, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up orphan drug specialists have consolidated European distribution networks, tightening pricing discipline while locking in multi-year formulary contracts that insulate against spot-market volatility. This ownership concentration simultaneously compresses procurement costs and elevates patient support program investments as the primary price differentiation mechanism.
Pricing Analysis
Warranty and service bundling separates chronic therapy management from acute episode pricing, with patient adherence programs and homecare nursing now embedded in premium-tier contracts while standard tiers strip these services for cost-sensitive hospital buyers. Three-tier pricing structure across premium, standard, and economy levels reflects formulation stability grades and cold-chain requirements. Cost compression in economy tiers stems from heat-stable generic entry, while integrated delivery networks in California and Massachusetts exhibit lowest price sensitivity due to bundled reimbursement structures.
Supply Chain Analysis
Direct-to-patient specialty pharmacy channels handle maintenance therapy volumes, bypassing hospital markup layers while capturing margin through adherence monitoring services. Active pharmaceutical ingredient production draws from Switzerland, Germany, and India, with cysteamine bitartrate salts and modified-release matrices as critical inputs. Single-source vulnerability concentrates in Swiss contract manufacturers qualified for EMA orphan drug batches. Distribution runs through temperature-controlled logistics networks anchored in Basel and Frankfurt airport hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around gene therapy manufacturing capacity scarcity, forcing subscale formulation players toward asset sales or licensing exits as curative modalities redirect R&D funding.
For Market Incumbents: Acquire lentiviral vector production facilities in Switzerland or the United States to secure clinical-grade material supply before capacity constraints harden. Lock in exclusive distribution partnerships with Italian and French regional health authorities to defend against heat-stable formulation entrants. Gene therapy pipeline progression represents the primary substitution threat requiring manufacturing pre-positioning.
For New Entrants and Emerging Players: EMA orphan drug incentives in Italy and France open a window for sublingual delivery platform entry where oral cysteamine tolerance failures cluster. Target United States specialty pharmacy networks as the most penetrable channel, leveraging direct-to-patient distribution to bypass hospital formulary gatekeepers. Lead with bioavailability-enhancing absorption technologies paired with pediatric nephrology practice outreach.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap biotechs with Phase I/II gene therapy assets in Switzerland or the United States, where manufacturing partnerships can be renegotiated at favorable terms. Long-term viability hinges on curative modality proof-of-concept displacing chronic management paradigms. Watch Avrobio and academic collaborator readouts as the inflection signal for manufacturing scale-up investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Viral vector capacity expansion in Basel and Zurich accelerates European clinical trial enrollment timelines. |
| Heat-Stable Formulation Development | Chiesi Farmaceutici's chemistry investments eliminate cold-chain dependencies for rural patient populations. |
| Specialty Pharmacy Network Expansion | Horizon Therapeutics captures margin from hospital-based infusion centers through direct-to-patient distribution. |
| Academic Gene Therapy Collaboration | Swiss institute partnerships with US biotech developers accelerate in vivo CTNS correction approaches. |
| EMA Orphan Drug Designation Pursuit | Extended market exclusivity periods sustain premium pricing for cysteamine-based maintenance therapies. |
Research Methodology
Document review covered FDA orphan drug filings, EMA protocol assistance records, and ClinicalTrials.gov gene therapy registrations, complemented by interviews with drug development executives at biotech developers, regulatory affairs leads at Swiss and German contract manufacturers, formulary directors at Italian regional health authorities, and payer access specialists at US integrated delivery networks. Secondary validation drew from hospital procurement databases, GPO contracts, and WHO rare disease priority list documentation. Bottom-up patient population estimates and top-down revenue triangulation anchored market sizing.
Historical prescription volume trajectories were cross-referenced against expert panel inputs on gene therapy displacement timelines across the projection horizon. The analytical framework modeled segmentation dimensions including treatment line, administration route, patient lifecycle stage, and regional regulatory cluster. CAGRs were derived from therapy adoption curves and reimbursement pathway maturation. Forecast inputs incorporated newborn screening program expansion rates in middle-income health systems and viral vector manufacturing capacity buildout schedules.
Caveats apply where gene therapy clinical readouts, REACH compliance reformulation requirements, or national health technology assessment reevaluations could materially shift the outlook. Forecasts reflect documented assumptions regarding curative modality timelines and orphan drug exclusivity period extensions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Cholangitis Market
Specialty Medicine
Hemochromatosis Treatment Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Primary Immunodeficiency Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Global Chondrosarcoma Market