
 Latin America Hydroxypropyl Methylcellulose Market | 2026-2036
Latin America Hydroxypropyl Methylcellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Hydroxypropyl Methylcellulose Market Intelligence
Construction sector demand is pivoting toward HPMC-based cementitious systems across Brazil and Mexico, displacing traditional thickening chemistries in tile adhesives and self-leveling compounds. Dow Inc. leverages its regional distribution infrastructure to sustain bulk supply contracts with major mortar producers. Ashland Inc. anchors its position through specialized pharmaceutical-grade formulations serving CDSCO-aligned import requirements.
Hydroxypropyl methylcellulose is a semi-synthetic polymer derived from cellulose etherification, typically exhibiting methoxy substitution of 19-30% and hydroxypropyl content of 4-12%, functioning primarily as a water-retention agent, rheology modifier, and film-forming binder across industrial formulations. Pharmaceutical-grade HPMC dominates margin pools due to stringent purity certifications and CDSCO import compliance costs, while industrial-grade volumes compete on price in construction applications. Powder form leads distribution channels across Latin American ports, though concentrate solutions are gaining traction in cosmetics processing near São Paulo and Buenos Aires.
Brazil's ANVISA and Mexico's COFEPRIS enforce pharmaceutical-grade purity standards that filter import eligibility for cellulose ethers, while CONCRETO and NBR construction norms in Brazil mandate water-retention thresholds in cementitious systems that directly specify HPMC performance grades. Argentina's ANMAT maintains parallel pharmaceutical standards that create fragmented compliance requirements across Mercosur trade corridors. Stakeholders must monitor regulatory harmonization progress between ANVISA and COFEPRIS to anticipate consolidated testing protocols that could reshape supplier qualification timelines.
Market Dynamics
REACH-aligned regulatory convergence between Brazil and Mexico is compressing supplier qualification timelines and forcing cellulose ether producers to consolidate purity testing protocols across São Paulo and Mexico City formulation corridors.
Growth Catalysts
- ANVISA-COFEPRIS harmonization:Pharmaceutical-grade alignment is reducing redundant certification costs for cellulose ether imports, accelerating market entry for qualified suppliers.
- Self-leveling compounds:Brazil's construction sector is specifying HPMC-based rheology modifiers in cementitious systems under revised CONCRETO norms.
- São Paulo formulation clusters:Concentrated mortar production near Guarulhos and Diadema is generating dedicated demand for industrial-grade cellulose ethers.
Market Restraints
- Purified cotton linter supply:Raw material concentration in Asian supply chains exposes Latin American HPMC producers to freight volatility and currency mismatch.
- ANMAT fragmentation:Argentina's pharmaceutical regulator maintains non-aligned cellulose ether standards that fragment Mercosur trade corridors.
- Starch ether substitution:Lower-cost biopolymers are capturing price-sensitive construction segments in Colombia and Peru mortar markets.
Strategic Opportunities
- Buenos Aires cosmetics processing:Concentrate solution formats for personal care formulations remain underdeveloped relative to powder distribution dominance.
- CDSCO-aligned import pathways:Indian pharmaceutical-grade HPMC entering through São Paulo ports can leverage existing purity certifications for ANVISA fast-track.
- Tile adhesive specification:Mexican COFEPRIS construction chemical guidelines are mandating water-retention thresholds that favor HPMC over traditional thickeners.
Industry Challenges
- Etherification process engineering:Specialized reactor operation and methoxy substitution control require scarce technical talent across Latin American production facilities.
- Cross-border testing reciprocity:Absence of mutual recognition agreements between ANVISA, COFEPRIS, and ANMAT extends batch-release timelines for multi-country suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Hydroxypropyl Methylcellulose Market |
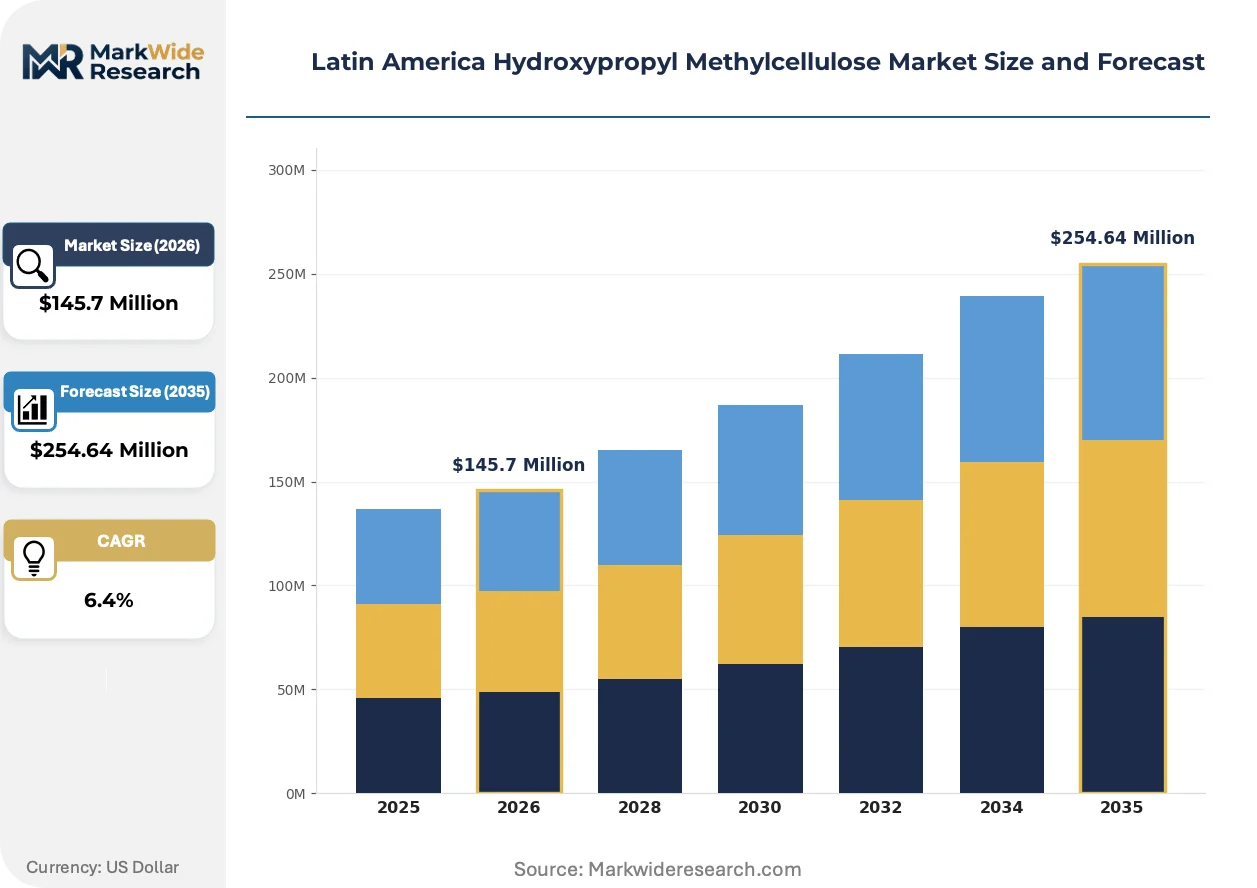
| Market Size in 2026 | $145.7 Million |
| Market Size in 2035 | $254.64 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Industrial Grade, Film-Forming Grade End Use: Pharmaceuticals, Food Processing, Cosmetics, Construction Form: Powder, Granules, Concentrate, Solution Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Dow Inc., Ashland Inc., Shin-Etsu Chemical Co Ltd, DuPont, SE Tylose GmbH & Co KG, Akzo Nobel N.V., Fufeng Group, Shandong Focus Chemistry Co. Ltd., Chongqing Guotong Huarong Chemical Co. Ltd., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Hydroxypropyl Methylcellulose Market Strategic Shifts & Innovations
Cellulose ether functionality is fragmenting along application-specific performance tiers, with pharmaceutical purity standards diverging sharply from construction-grade commodity positioning across Latin American ports.
Low-viscosity HPMC grades optimized for spray-applied tile adhesives is overtaking medium-viscosity legacy formulations in Brazilian construction chemical plants. Major mortar producers in São Paulo's ABC industrial zone are specifying sub-400 mPa·s grades for mechanized application equipment. This viscosity compression is enabling thinner-bed installation methods that reduce material waste per square meter.
COFEPRIS pharmaceutical-grade cellulose ether guidelines are tightening heavy metal and microbial contamination thresholds for imports through Veracruz and Lázaro Cárdenas. Industrial laboratories in Mexico City are investing in dedicated HPLC testing capacity to meet accelerated release schedules. The regulatory pressure is compressing informal supply channels that previously operated on technical-grade certifications.
Direct mill relationships are replacing distributor intermediation for large-volume construction chemical buyers in southeastern Brazil. Formulation houses in Guarulhos and Barueri are negotiating annual contracts with Asian producers, bypassing traditional São Paulo trading companies. The channel compression is most visible in 20-ton-plus industrial-grade orders where price transparency has improved through digital procurement platforms.
Latin America Hydroxypropyl Methylcellulose Market Segmentation
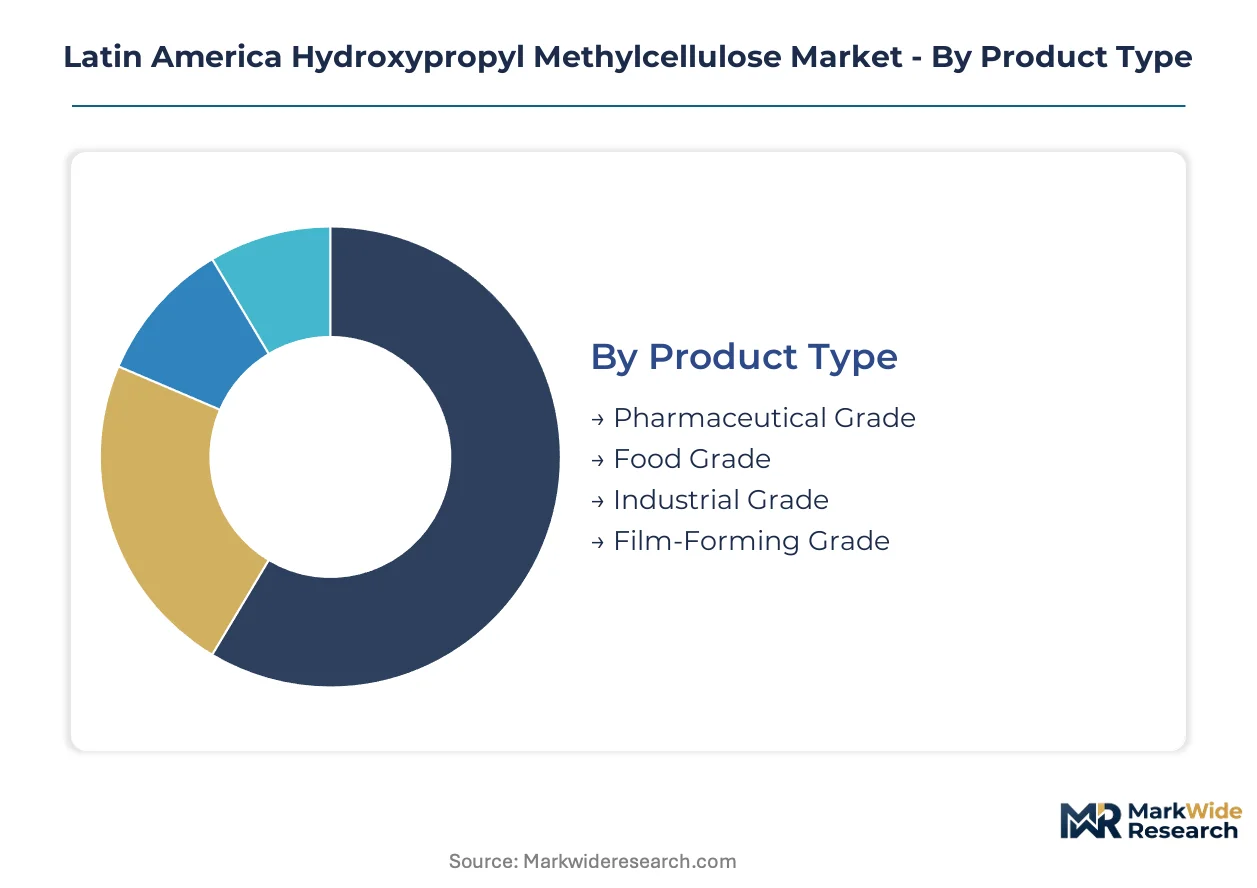
Segmentation across Latin America's HPMC market reflects divergent purity requirements between regulated pharmaceutical applications and price-driven construction sectors. Each category captures distinct margin structures and certification burdens that reshape supplier positioning across Brazilian and Mexican import corridors.
Product Type:
Customization intensity spans from certified pharmaceutical batches to standardized industrial bulk, with purity thresholds determining pricing power and regulatory compliance costs across the region.
- Pharmaceutical Grade:ANVISA and COFEPRIS mandate heavy metal limits below 10 ppm and microbial contamination thresholds that filter import eligibility through São Paulo and Mexico City testing laboratories. CDSCO-aligned Indian suppliers leverage existing certifications for accelerated market entry into Brazilian formulation clusters.
- Industrial Grade:Specifications center on methoxy substitution ranges of 19-30% and viscosity control for cementitious water retention. São Paulo's Guarulhos mortar producers negotiate annual tonnage contracts directly with Asian manufacturers, compressing traditional distributor margins.
- Food Grade:FSSAI-equivalent purity standards apply for regional food processing applications, with demand concentrating in southern Brazil's packaged food manufacturing belt.
- Film-Forming Grade:Specialized HPMC for coating applications requires controlled molecular weight distribution, serving pharmaceutical tablet production near Buenos Aires and Mexico City.
Leading the category by volume: Industrial Grade. Expanding most quickly: Pharmaceutical Grade.
End Use:
Application-driven demand clusters separate high-margin regulated sectors from commodity construction volumes, with certification requirements fragmenting supplier qualification pathways.
- Construction:CONCRETO and NBR norms mandate HPMC water-retention thresholds in tile adhesives and self-leveling compounds. Brazil's southeastern industrial corridor generates concentrated demand for sub-400 mPa·s grades optimized for mechanized application equipment.
- Pharmaceuticals:ANVISA-COFEPRIS harmonization is compressing redundant certification timelines for cellulose ether imports. Tablet coating and controlled-release matrix applications dominate formulation demand in São Paulo's pharmaceutical manufacturing zone.
- Cosmetics:Personal care formulations in Buenos Aires and São Paulo are shifting from powder toward concentrate solution formats for emulsion stabilization.
- Food Processing:Thickening and stabilizing applications in packaged foods operate under less stringent purity requirements than pharmaceutical tiers, with demand spread across southern Brazil's food manufacturing corridor.
Construction dominates absolute volume. Pharmaceuticals deliver the steepest margin expansion trajectory.
Form:
Physical format selection tracks application equipment requirements and dissolution efficiency needs, with powder maintaining logistics advantages across Latin American port infrastructure.
- Powder:Dominates cross-border distribution through Santos and Veracruz ports due to stability in tropical storage conditions and established bulk handling infrastructure.
- Solution:Gaining traction in cosmetics processing near Buenos Aires where ready-to-use formats eliminate dissolution steps in emulsion production.
- Granules:Intermediate dissolution characteristics serve specialized pharmaceutical coating applications requiring controlled hydration rates.
- Concentrate:Reduced freight costs per active unit appeal to high-volume construction chemical producers in São Paulo's ABC industrial zone.
Powder leads distribution volume. Solution formats are climbing the fastest in personal care applications.
Distribution Channel:
Channel structure reflects order scale fragmentation, with large construction chemical buyers bypassing intermediaries while smaller pharmaceutical formulators rely on specialized distributors.
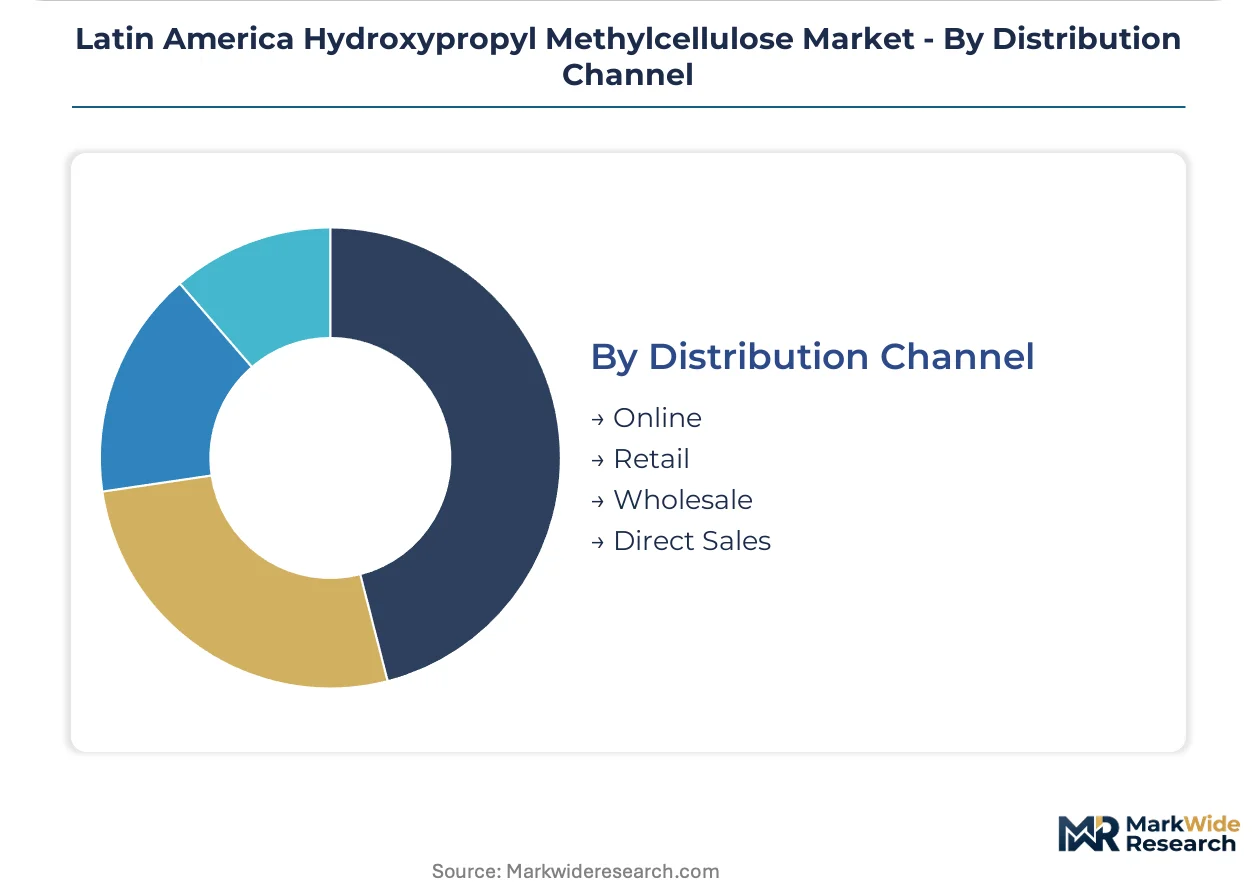
- Direct Sales:Annual contracts exceeding 20 tons now bypass São Paulo trading houses as Guarulhos and Barueri formulation houses negotiate directly with Asian producers.
- Wholesale:Regional distributors maintain relevance for mid-volume pharmaceutical and food-grade orders requiring batch-specific certification documentation.
- Online:Digital procurement platforms are emerging for standardized industrial-grade specifications where price transparency has improved.
- Retail:Limited to small-laboratory and research-scale quantities, with minimal share in commercial-volume HPMC movement.
Direct Sales commands the largest tonnage flows. Online channels are gaining share fastest in standardized industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Latin American HPMC consumption outpaces regional production capacity, forcing dependence on Asian and North American supply chains. Import flows concentrate through Santos, Veracruz, and Buenos Aires ports. Regulatory fragmentation across Mercosur members complicates cross-border distribution efficiency.
Brazil
São Paulo's Guarulhos and Diadema industrial zones generate concentrated demand for construction-grade HPMC in tile adhesives and self-leveling compounds. ANVISA enforces pharmaceutical-grade purity standards that filter import eligibility through certified testing laboratories. Direct procurement relationships between large mortar producers and Asian manufacturers are displacing traditional distributor channels for orders exceeding twenty tons.
Mexico
COFEPRIS pharmaceutical guidelines and construction chemical norms are tightening heavy metal thresholds for cellulose ether imports through Veracruz and Lázaro Cárdenas. Mexico City formulation laboratories are investing in dedicated HPLC testing capacity to meet accelerated release schedules. The regulatory pressure is compressing informal supply channels that previously operated on technical-grade certifications alone.
Argentina
ANMAT maintains pharmaceutical-grade cellulose ether standards that fragment Mercosur trade corridors and extend batch-release timelines for multi-country suppliers. Buenos Aires cosmetics processors are shifting from powder toward concentrate solution formats for emulsion stabilization. Personal care manufacturing clusters in Greater Buenos Aires remain underdeveloped relative to São Paulo's scale.
Chile
Construction activity in Santiago's metropolitan region drives steady industrial-grade HPMC consumption for cementitious systems and mortar applications. The country's national pharmaceutical regulator enforces import purity requirements that align loosely with ANVISA benchmarks. Northern mining corridor infrastructure projects generate sporadic bulk demand for specialized rheology modifiers.
Colombia
Bogotá and Medellín construction chemical distributors face price pressure from starch ether substitutes in price-sensitive mortar segments. The national food and drug surveillance institute maintains cellulose ether standards for pharmaceutical applications that lack mutual recognition with Brazilian or Mexican regulators. Regional distributors retain relevance for mid-volume orders requiring batch-specific documentation.
Latin America Hydroxypropyl Methylcellulose Market Key Industry Players
Top-tier vendors anchor premium pharmaceutical-grade supply, while mid-tier Asian producers compete aggressively on industrial-grade construction volumes. The vendor base separates into three distinct tiers: multinational chemical conglomerates with regional distribution infrastructure, specialized cellulose ether manufacturers with purity certification expertise, and commodity producers competing on freight-optimized bulk pricing. Capacity expansion and direct mill relationships represent the dominant competitive moves reshaping channel economics.
Among North American chemical conglomerates, Dow Inc. and Ashland Inc. occupy positions exemplifying the premium-tier archetype through established regional distribution networks. Shin-Etsu Chemical Co Ltd represents Japanese specialized manufacturers with technical-grade formulation capabilities. Chinese producers including Fufeng Group and Shandong Focus Chemistry Co. Ltd. anchor the scale-driven commodity segment, competing on tonnage pricing for construction-grade specifications.
| Leading Market Players |
|---|
| Dow Inc. |
| Ashland Inc. |
| Shin-Etsu Chemical Co Ltd |
| DuPont |
| SE Tylose GmbH & Co KG |
| Akzo Nobel N.V. |
| Fufeng Group |
| Shandong Focus Chemistry Co. Ltd. |
| Chongqing Guotong Huarong Chemical Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Pharmaceutical-industrial grade bifurcation creates divergent margin architectures across Latin American import corridors, with ANVISA-COFEPRIS certification tiers commanding freight-absorbed premiums while construction-grade volumes compete on landed-cost transparency through direct mill contracts.
Pricing Analysis
Short-lead-time premiums apply to pharmaceutical-grade HPMC batches released through São Paulo and Mexico City testing laboratories, while spot inventory discounts emerge for industrial-grade powder stored at Santos port consolidation warehouses. Three-tier pricing structure across pharmaceutical, industrial, and food-grade levels tracks certification burden and substitution elasticity, with starch ether alternatives intensifying cost compression in Colombian and Peruvian mortar segments. Construction chemical buyers in Guarulhos and Barueri exhibit highest price sensitivity due to direct Asian procurement relationships, while pharmaceutical formulators accept premium positioning for ANVISA-aligned import pathways.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical-grade HPMC remain minimal given batch-specific certification requirements that prevent returns, though industrial-grade powder consolidation at Santos enables redistribution to secondary construction markets when primary orders cancel. Supply concentrates in China, India, and South Korea for etherification capacity and purified cotton linter processing, with raw material dependencies spanning Asian cotton harvests, propylene oxide derivatives, and methyl chloride reagents. Single-source vulnerability runs through Veracruz and Lázaro Cárdenas port chokepoints for Mexican pharmaceutical imports. Distribution runs through direct sales contracts for large-volume construction buyers and specialized wholesale channels for certified pharmaceutical batches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into purified cotton linter sourcing and captive etherification capacity represents the dominant competitive lever reshaping margin capture across Latin American formulation corridors.
For Market Incumbents: Anticipate starch ether substitution pressure in Andean construction markets by locking annual tonnage contracts with São Paulo mortar producers and investing in ANVISA fast-track certification infrastructure to defend pharmaceutical-grade positioning against CDSCO-aligned Indian entrants. For New Entrants and Emerging Players: Capture underdeveloped concentrate solution demand in Buenos Aires cosmetics processing by targeting personal care emulsion manufacturers with ready-to-use formats that eliminate dissolution steps, leveraging powder-to-solution conversion as a differentiated go-to-market angle against established distributors. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier Asian producers possessing ANVISA pre-certification given accelerated market entry timelines under harmonized pharmaceutical standards, with long-term viability hinging on backward integration into propylene oxide supply chains; monitor ANVISA-COFEPRIS mutual recognition agreement progress as the inflection signal for consolidated testing protocol adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cotton Linter Supply | Captive raw material sourcing insulates Brazilian producers from Asian freight volatility and currency mismatch. |
| ANVISA Fast-Track Certification Investment | Accelerated release timelines compress competitor entry windows for pharmaceutical-grade cellulose ether batches. |
| Direct Mill Contract Negotiation | Annual tonnage agreements with Guarulhos mortar producers displace São Paulo trading house intermediation. |
| Concentrate Solution Format Development | Ready-to-use emulsion inputs capture Buenos Aires cosmetics processing demand from powder-dominant incumbents. |
| HPLC Testing Capacity Expansion | Mexico City laboratory investment meets COFEPRIS heavy metal threshold acceleration and compresses informal channel supply. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with primary interviews conducted among cellulose ether plant managers, procurement leads at Brazilian mortar OEMs, distribution channel partners, and pharmaceutical formulation technical directors. Secondary validation drew from ANVISA import registration databases, COFEPRIS construction chemical guidelines, CONCRETO norm documentation, and SEC filings from listed chemical conglomerates. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down trade flow analysis.
Data-stream reconciliation across customs import volumes, port throughput statistics, and formulation house procurement surveys informed the analytical framework across the analysis window. Segmentation dimensions modeled include grade tier (pharmaceutical, industrial, food, film-forming), end-use industry (construction, pharmaceuticals, cosmetics, food processing), physical form (powder, solution, granules, concentrate), and regional production hub (São Paulo, Mexico City, Buenos Aires corridors). CAGRs were derived from trend extrapolation of import growth rates adjusted for substitution effects and regulatory harmonization progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANVISA-COFEPRIS mutual recognition timing, Asian cotton linter supply disruptions, and starch ether substitution acceleration in price-sensitive segments. Forecasts reflect documented assumptions regarding regulatory convergence pace and freight cost normalization. Practitioners should monitor ANMAT alignment negotiations, propylene oxide derivative pricing, and digital procurement platform adoption rates for early signals of channel structure transformation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Stable Isotope Labeled Compounds Market
Specialty Compounds
Neohespiridine Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Lentein Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Stannous Chloride Market
Specialty Compounds
Eggshell Membrane Derivatives Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
US Non-Commercial Acrylic Paints Market
Specialty Compounds
Organoclay Market
Specialty Compounds
Resin Capsule Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Conductive Plastic Compounds Market