
 Neohespiridine Market | 2026-2036
Neohespiridine Market Size, Share, and Industry Trends Forecast 2026-2036
Neohespiridine Market Foresight
Pharmaceutical company demand is decoupling from traditional beverage applications as functional ingredient portfolios diversify. Layn Corp leverages its botanical extraction infrastructure to supply standardized neohesperidin to nutraceutical clients across Asia-Pacific. Merck KGaA anchors its position through pharmaceutical-grade certification protocols that command premium positioning in European markets. Nutrafur S.A. specializes in citrus-derived flavonoid concentrates from Spanish orange processing streams.
Neohespiridine denotes the flavanone glycoside neohesperidin, typically extracted from bitter orange peel and subsequently hydrogenated to produce the high-intensity sweetener neohesperidin dihydrochalcone with sweetness potency approximately 1500-1800 times that of sucrose. The compound serves primarily as a flavor modifier and sweetening agent in low-calorie formulations where bitter masking properties prove essential. Natural extract variants currently occupy the premium tier as clean-label procurement from food manufacturers intensifies, while synthetic production routes sustain cost-competitive supply for mainstream beverage applications. Powder formulations dominate pharmaceutical company purchasing due to precise dosing requirements in tablet and capsule production.
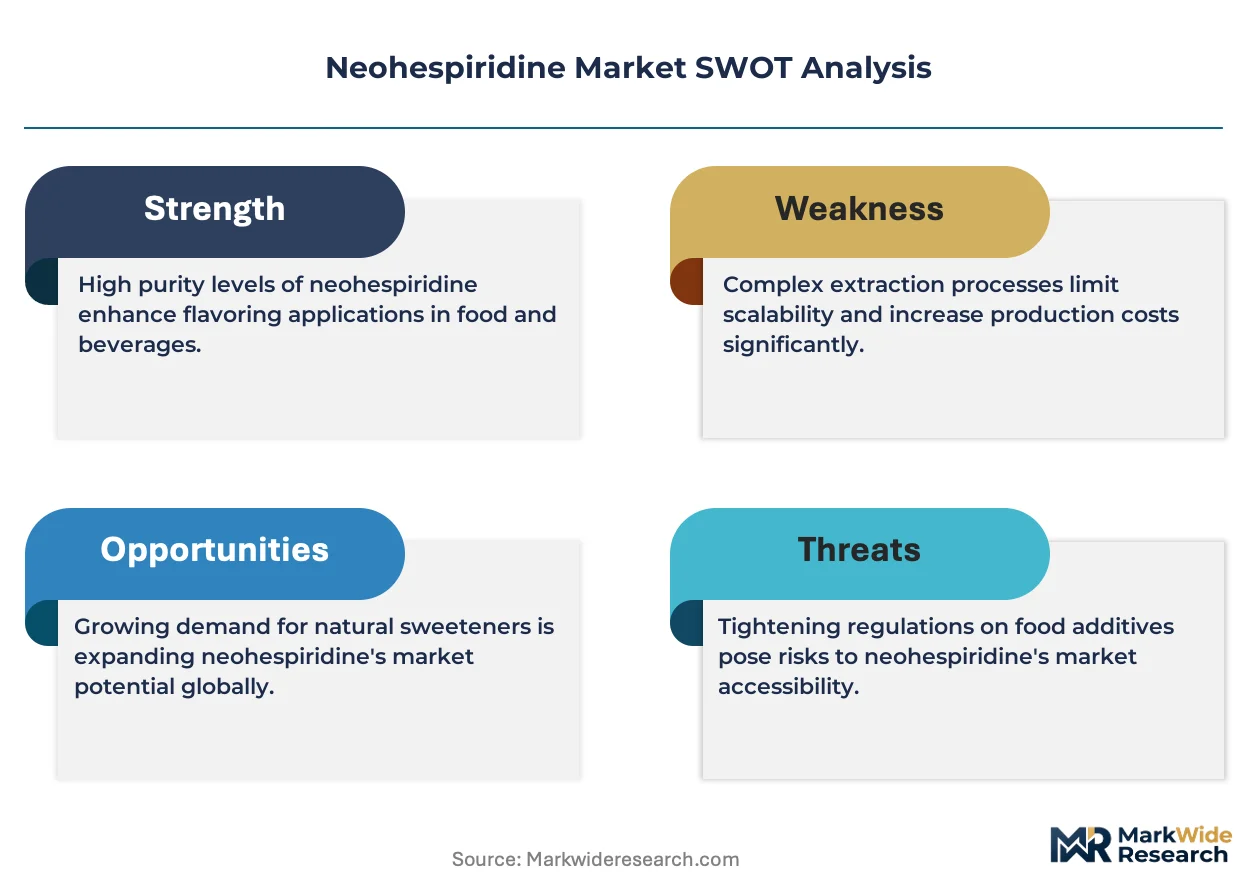
EFSA novel food evaluations and REACH chemical registration requirements in Europe are elevating analytical documentation burdens for imported citrus extracts. China's NMPA and GB standards for food additives impose parallel testing protocols that shape export readiness for domestic suppliers. Stakeholders must monitor evolving pharmacopeial monograph revisions and regional enforcement disparities to align quality investments with destination market requirements.
Market Dynamics
Pharmaceutical procurement of neohesperidin dihydrochalcone is diverging from beverage applications as functional ingredient portfolios fragment across therapeutic and nutraceutical channels. Hydrogenation capacity constraints and citrus peel supply volatility are compressing margins for non-integrated extractors.
Growth Catalysts
- EFSA novel food pathways:Accelerated safety assessments for hydrogenated flavonoid derivatives enable faster European market entry for clean-label sweetener formulations.
- Bitter masking in pediatric pharmaceuticals:Tablet and syrup manufacturers deploy neohesperidin dihydrochalcone to improve compliance in bitter active pharmaceutical ingredient delivery systems.
- China NMPA food additive approvals:Expanded GB standard recognition for citrus-derived sweeteners unlocks domestic formulation opportunities in functional beverages and dietary supplements.
Market Restraints
- Bitter orange peel supply concentration:Spanish and Chinese citrus processing streams dominate raw material availability, exposing formulators to harvest volatility and climate disruption.
- REACH registration cost burden:ECHA documentation requirements for hydrogenated flavonoid imports impose five-figure euro compliance costs that filter out smaller trading intermediaries.
- Stevia glycoside substitution:Reb M and reb D stevia variants capture cost-sensitive beverage applications where neohesperidin dihydrochalcone previously held technical advantages in thermal stability.
Strategic Opportunities
- India FSSAI functional food expansion:Regulatory clarity on flavonoid sweetener categories creates first-mover positioning for extractors targeting ayurvedic nutraceutical formulators.
- Encapsulation technology convergence:Spray-dried and liposomal delivery systems extend neohesperidin dihydrochalcone stability in baked goods and retort-processed applications.
- Direct-to-manufacturer digital procurement:B2B ingredient platforms disintermediate traditional distributor networks, enabling price transparency and smaller minimum order quantities for mid-tier formulators.
Industry Challenges
- Pharmacopeial monograph alignment:Divergent USP, EP, and ChP purity specifications force multi-standard testing protocols that extend batch release timelines by 15-30 days.
- Hydrogenation reactor capex intensity:Catalytic hydrogenation infrastructure requires seven-figure capital deployment, constraining capacity expansion to well-capitalized chemical processors.
- Cross-border documentation friction:Certificate of origin and phytosanitary certification complexity between citrus-growing regions and importing jurisdictions disrupts just-in-time supply scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neohespiridine Market |
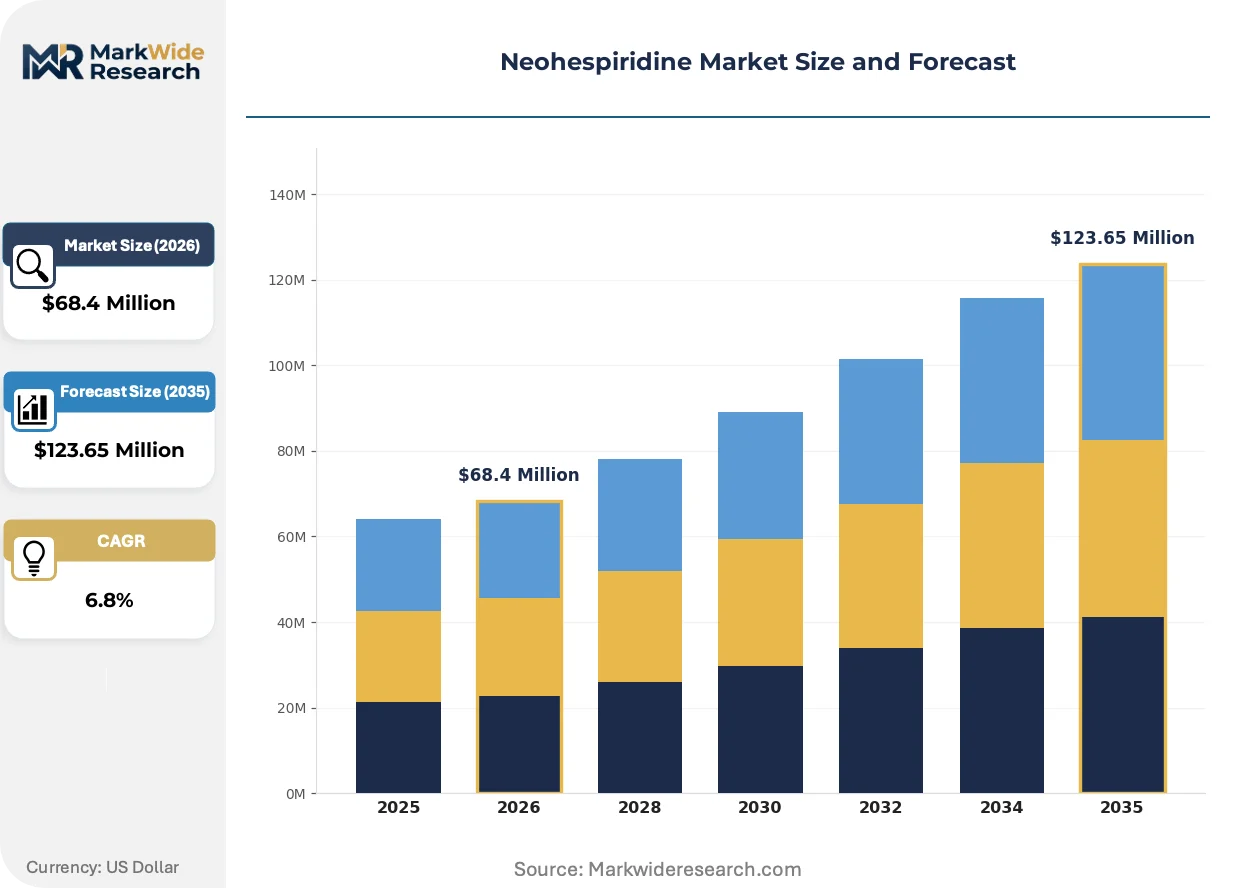
| Market Size in 2026 | $68.4 Million |
| Market Size in 2035 | $123.65 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Concentrated, Powder Application: Beverages, Confectionery, Dairy, Nutraceuticals End User: Food Manufacturers, Beverage Companies, Cosmetic Firms, Pharmaceutical Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Changsha Sunnycare, Nutrafur S.A., Gelfix, Kang Biotech, Bordas Distillations Chinchurreta, Okay Pharmaceutical, Layn Corp, Merck KGaA, Golden Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neohespiridine Market Shifts & Advancements
Clean-label procurement mandates and precision dosing requirements are reshaping how neohesperidin derivatives move from extraction through formulation. Technical innovation concentrates on stability enhancement and application expansion beyond traditional beverage sweetening.
Green extraction protocols using subcritical water and enzyme-assisted cell wall disruption are rewriting yield economics for citrus peel processing. Nutraceutical manufacturers in Germany and Switzerland adopt these methods to satisfy EFSA organic claim requirements. The technology is compressing solvent residue risks and enabling premium positioning in pharmaceutical-grade supply tiers.
REACH Article 33 disclosure obligations and evolving SCIP database requirements are tightening supply chain transparency for imported flavonoid concentrates. Downstream formulators now demand full substance composition data from Chinese and Spanish extractors. European pharmaceutical buyers are responding by consolidating supplier relationships with entities holding ECHA-registered dossiers.
Specification-driven procurement is displacing spot-market purchasing as quality variance between natural extract and synthetic neohesperidin dihydrochalcone batches intensifies. Large-scale beverage manufacturers in the United States and Japan now contract directly for certified-lot material with defined hydrogenation completeness metrics. This pattern is most visible in low-calorie carbonated drink segments where off-taste thresholds are measured in parts per million.
Neohespiridine Market Segmentation
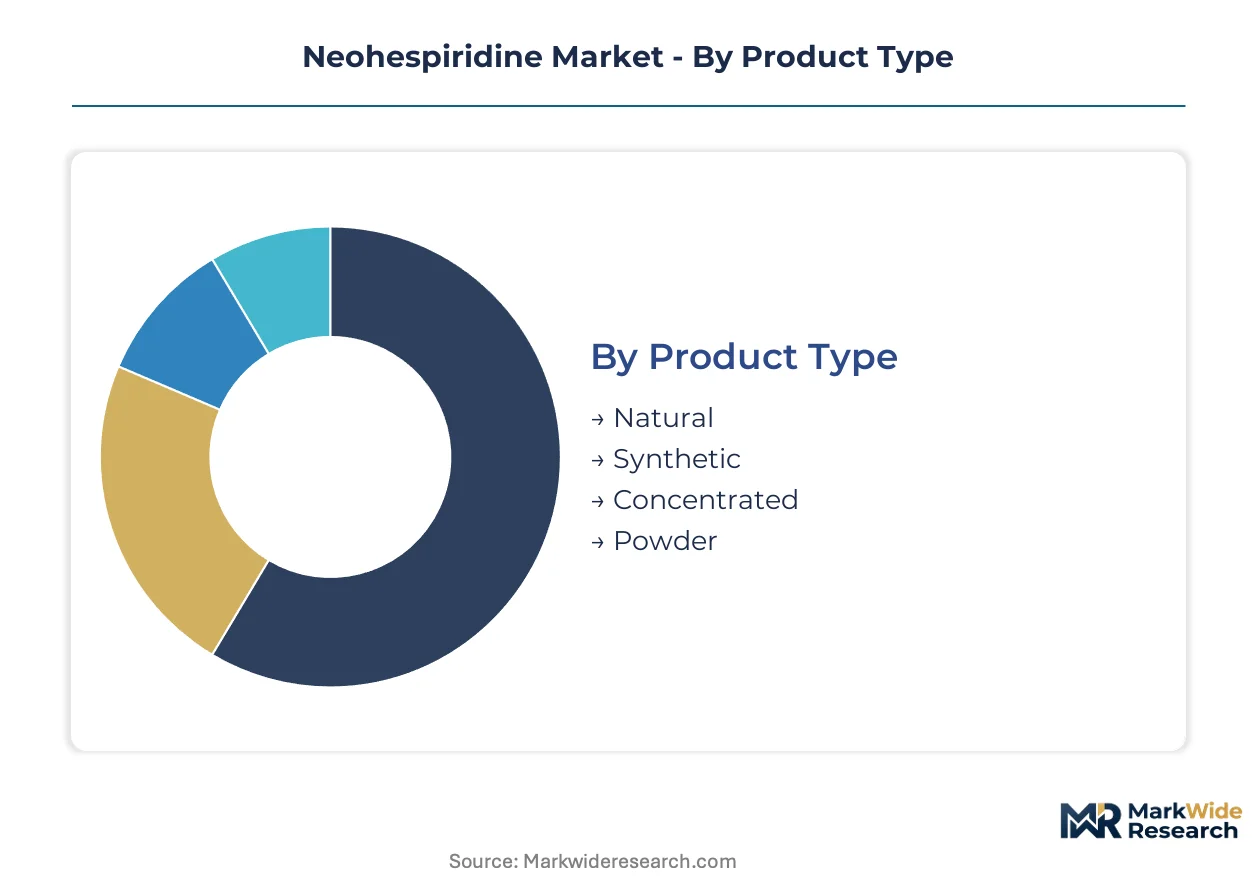
Neohespiridine procurement patterns diverge sharply across product grades and end-use specifications. Hydrogenation completeness, extraction origin, and pharmacopeial certification tiers create distinct value bands that shape supplier selection and pricing negotiation.
Product Type:
Specification hierarchies separate pharmaceutical-grade certification from mainstream beverage applications through hydrogenation metrics and residual solvent thresholds.
- Natural:Extracted from bitter orange peel through solvent or enzyme-assisted methods. EFSA organic claim requirements in Germany and Switzerland drive premium positioning for certified-lot material with full phytosanitary documentation.
- Synthetic:Manufactured through chemical synthesis routes achieving batch-to-batch consistency. Cost-competitive supply for high-volume carbonated beverage formulators in the United States and Japan where thermal stability specifications are measured in parts per million.
- Concentrated:High-purity flavonoid concentrates from Spanish orange processing streams serving nutraceutical capsule manufacturers.
- Powder:Standardized particle size distributions for precise tablet dosing in pharmaceutical production.
Mature deployment sits with Powder specifications in established pharmaceutical channels. Newer deployment is concentrated in Natural extracts as clean-label procurement accelerates across European functional food markets.
Application:
End-use thermal processing requirements and taste masking priorities segment demand across formulation complexity tiers.
- Beverages:Low-calorie carbonated drinks and functional waters deploy neohesperidin dihydrochalcone for thermal stability during pasteurization. Japanese and U.S. manufacturers contract directly for certified-lot material with defined hydrogenation completeness metrics.
- Nutraceuticals:Dietary supplement tablets and capsules leverage precise dosing control. China's NMPA GB standard recognition unlocks domestic formulation opportunities as local pharmaceutical companies scale procurement.
- Confectionery:Sugar-free hard candies and chewing gums utilize bitterness masking properties.
- Dairy:Fermented and flavored milk applications with pH stability requirements.
Volume leadership belongs to Beverage applications. Nutraceuticals are climbing the fastest as functional ingredient portfolios fragment across therapeutic channels.
End User:
Procurement sophistication varies from spot-market purchasing to specification-driven long-term contracts with defined quality metrics.
- Pharmaceutical Companies:Require USP, EP, and ChP pharmacopeial compliance with multi-standard testing protocols. Batch release timelines extend 15-30 days for documentation alignment across export destinations.
- Food Manufacturers:Prioritize clean-label certification and organic claims for premium positioning in German and Swiss retail channels.
- Beverage Companies:High-volume procurement with price transparency demands through B2B ingredient platforms.
- Cosmetic Firms:Emerging demand for flavonoid derivatives in topical formulations with antioxidant positioning.
Contract sophistication peaks with Pharmaceutical Companies. Direct-to-manufacturer digital procurement is expanding fastest among mid-tier Beverage Companies seeking smaller minimum order quantities.
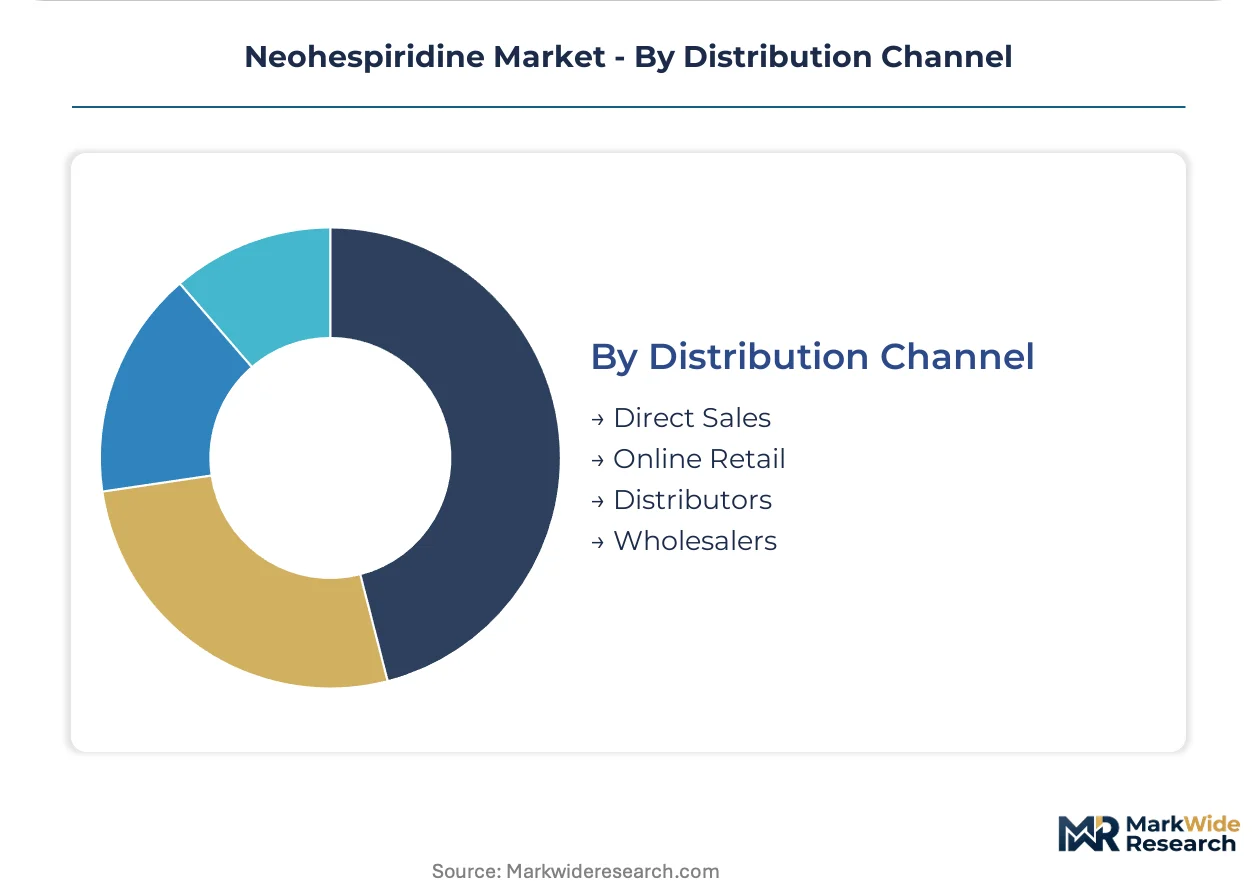
Distribution Channel:
Channel selection reflects order scale, documentation intensity, and geographic proximity to extraction capacity.
- Direct Sales:Large-scale pharmaceutical and beverage manufacturers bypass distributor networks for price transparency and certified-lot traceability. Layn Corp and Merck KGaA anchor relationships through pharmaceutical-grade certification protocols.
- Distributors:Traditional intermediaries serving smaller formulators with aggregated sourcing from Chinese and Spanish extraction clusters.
- Online Retail:B2B ingredient platforms disintermediate legacy networks for mid-tier nutraceutical formulators.
- Wholesalers:Bulk material aggregation for regional compounders with limited specification requirements.
Relationship density concentrates in Direct Sales for premium-tier material. Online Retail is gaining share fastest as digital procurement platforms reduce minimum order friction for emerging formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhangjiang Hi-Tech Park in Shanghai anchors neohespiridine extraction capacity expansion, drawing hydrogenation specialists through tax incentives and streamlined NMPA licensing pathways.
China
Domestic pharmaceutical companies scale procurement of citrus-derived flavonoids for tablet and capsule production. NMPA GB standards for food additives impose parallel testing protocols that shape export readiness for extraction clusters in Hunan and Sichuan provinces. Layn Corp leverages its botanical extraction infrastructure to supply standardized neohesperidin to nutraceutical clients across Asia-Pacific.
Germany
EFSA novel food evaluations and REACH chemical registration requirements elevate analytical documentation burdens for imported citrus extracts. ECHA documentation requirements for hydrogenated flavonoid imports impose five-figure euro compliance costs that filter out smaller trading intermediaries. Merck KGaA anchors its position through pharmaceutical-grade certification protocols commanding premium positioning in European markets.
United States
Large-scale beverage manufacturers contract directly for certified-lot material with defined hydrogenation completeness metrics. FDA food additive regulations and GRAS self-determination pathways shape formulation strategies for low-calorie carbonated drink segments. Direct-to-manufacturer digital procurement platforms disintermediate traditional distributor networks for mid-tier formulators seeking price transparency.
Spain
Spanish orange processing streams dominate raw material availability for natural extract variants. Nutrafur S.A. specializes in citrus-derived flavonoid concentrates serving European nutraceutical capsule manufacturers. Bordas Distillations Chinchurreta operates extraction capacity within Valencia's citrus belt, exposing formulators to harvest volatility and climate disruption risks.
India
Ayurvedic nutraceutical formulators expand procurement of bitter masking agents for pediatric pharmaceutical applications. FSSAI regulatory clarity on flavonoid sweetener categories creates first-mover positioning for extractors targeting domestic functional food markets. Kang Biotech and Okay Pharmaceutical represent emerging domestic suppliers scaling capacity to serve both local and export buyers.
Neohespiridine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade certification holders commanding premium positioning while beverage-focused suppliers compete on hydrogenation throughput and citrus peel supply security. The vendor base clusters around three strategic archetypes: integrated extraction-hydrogenation operators, botanical ingredient platform players, and pharmaceutical-grade certification specialists. Capacity expansion and strategic partnerships dominate competitive moves, with ECHA-registered dossier holders consolidating relationships with downstream formulators facing REACH Article 33 disclosure obligations.
Among Chinese extraction specialists, Changsha Sunnycare and Golden Health exemplify the integrated operator archetype, occupying positions within Hunan province's citrus processing corridor. Nutrafur S.A. represents the European botanical platform model, anchoring supply relationships through Spanish orange processing stream access. Merck KGaA sits within the pharmaceutical-grade certification tier, leveraging EMEA-registered manufacturing protocols to serve European pharmaceutical company procurement requirements.
| Leading Market Players |
|---|
| Changsha Sunnycare |
| Nutrafur S.A. |
| Gelfix |
| Kang Biotech |
| Bordas Distillations Chinchurreta |
| Okay Pharmaceutical |
| Layn Corp |
| Merck KGaA |
| Golden Health |
| Others |
Supply & Pricing Matrix
REACH Article 33 disclosure obligations and evolving SCIP database requirements gate qualified supply for European pharmaceutical buyers while compressing premium-tier pricing access to ECHA-registered dossier holders. Hydrogenation reactor capital intensity and citrus peel harvest volatility transmit upstream cost pressures into contract negotiations between extractors and downstream formulators.
Pricing Analysis
Lead-time-driven pricing stratification rewards certified-lot procurement with 15-30 day batch release timelines at premium positioning, while spot-market citrus peel availability trades at discounted rates amid harvest surplus windows. Three-tier pricing structure across pharmaceutical-grade certification, food-grade standard, and commodity economy levels differentiates on hydrogenation completeness metrics and residual solvent thresholds. Cost compression in economy tiers intensifies as stevia glycoside substitution erodes technical advantages in thermal stability applications. Beverage manufacturers exhibit highest price sensitivity through B2B platform transparency demands, whereas pharmaceutical companies absorb certification premiums for USP-EP-ChP multi-standard compliance.
Supply Chain Analysis
Reverse-logistics flows for citrus peel processing residues and spent hydrogenation catalysts are minimal, with Nutrafur S.A. and Bordas Distillations Chinchurreta operating limited refurbishment streams for solvent recovery. Geographic supply concentrates in Spain, China, and India, with Valencia's citrus belt and Hunan province's extraction clusters anchoring raw material availability. The supply chain draws from bitter orange peel, catalytic hydrogenation infrastructure, and pharmacopeial-grade packaging materials. Single-source vulnerability in Spanish citrus processing exposes formulators to climate disruption and harvest volatility. Distribution runs through direct sales relationships for premium-tier material, with B2B platforms disintermediating traditional distributor networks for mid-tier nutraceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neohespiridine procurement is consolidating around ECHA-registered dossier holders as REACH compliance costs filter smaller trading intermediaries from European pharmaceutical channels. Hydrogenation reactor capital intensity and multi-standard pharmacopeial testing burdens are forcing weaker non-integrated extractors toward exit or acquisition.
For Market Incumbents: Lock in backward integration into catalytic hydrogenation capacity within Zhangjiang Hi-Tech Park or Valencia's citrus belt to secure supply continuity amid Spanish harvest volatility. Consolidate supplier relationships with downstream formulators facing REACH Article 33 disclosure obligations through EMEA-registered manufacturing protocols, defending against Merck KGaA's pharmaceutical-grade certification dominance. For New Entrants and Emerging Players: Launch via B2B ingredient platforms targeting mid-tier Indian nutraceutical formulators seeking FSSAI-compliant bitter masking agents for pediatric pharmaceutical applications. White-space availability concentrates in ayurvedic functional food segments and encapsulation technology convergence for baked goods stability, with spray-dried delivery systems offering differentiated positioning against established beverage-focused suppliers. For Investors and Strategic Acquirers: EFSA novel food pathway acceleration for hydrogenated flavonoid derivatives is the leading indicator that clean-label procurement mandates will concentrate share among integrated extraction-hydrogenation operators with organic certification capabilities. The 5-10 year viability window favors acquisition of Chinese botanical platform players with NMPA GB standard recognition and scalable extraction infrastructure, monitoring India FSSAI regulatory clarity implementation as inflection signal for ayurvedic nutraceutical demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogenation Capacity | Catalytic reactor deployment in Zhangjiang Hi-Tech Park secures supply continuity against Spanish citrus harvest volatility. |
| EFSA Novel Food Pathway Acceleration | Expedited safety assessments for hydrogenated flavonoid derivatives unlock European clean-label formulation opportunities. |
| ECHA Dossier Registration Consolidation | REACH Article 33 compliance anchors premium-tier supplier relationships with pharmaceutical manufacturers. |
| Encapsulation Technology Convergence | Spray-dried delivery systems extend stability in baked goods and retort-processed applications beyond beverage segments. |
| Direct-to-Manufacturer Digital Procurement | B2B platforms disintermediate distributor networks for price transparency and reduced minimum order quantities. |
Research Methodology
Multi-period observation of hydrogenation capacity expansion, EFSA novel food evaluation timelines, and NMPA GB standard revision cycles anchored the trend analysis, supplemented by interviews with extraction plant managers, pharmaceutical procurement leads, nutraceutical formulators, and ECHA regulatory consultants. Secondary validation drew from customs trade data for citrus-derived flavonoid concentrates, SEC filings of listed botanical ingredient suppliers, REACH registration dossiers, and FSSAI regulatory circulars. Bottom-up triangulation across product-grade volume estimates and top-down cross-check against end-use application demand completed the analytical framework.
Segment-weighting across natural extract, synthetic, concentrated, and powder product types combined with beverage, nutraceutical, confectionery, and dairy application splits shaped the projection model. Hydrogenation completeness tiers, pharmacopeial certification levels, and geographic regulatory cluster adoption patterns provided additional segmentation dimensions. CAGRs were derived from supply-side capacity buildout trajectories and demand-side procurement scaling by pharmaceutical companies and functional food manufacturers throughout the forecast period. Forecast inputs included citrus peel harvest yield projections and EFSA novel food approval velocity assumptions.
Regulatory enforcement divergence between EFSA member states, climate disruption in Mediterranean citrus-growing regions, and stevia glycoside substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions on hydrogenation reactor commissioning schedules and pharmacopeial monograph alignment timelines. Practitioners should monitor India FSSAI implementation progress, Spanish citrus harvest reports, and EFSA novel food opinion publication velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
Lentein Market
Specialty Compounds
Stannous Chloride Market
Specialty Compounds
Europe Polypropylene Compounds Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Chromium Phosphate Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Sodium Stannate Market
Specialty Compounds
Nonene (Propylene Trimer) and Tetramer Market
Specialty Compounds
Compounding Systems Market
Specialty Compounds
Hydroxypropyl Methylcellulose Market
Specialty Compounds
Polyurea Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
Gulf Collagen Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Thermoset Molding Compounds Market