
 Lentein Market | 2026-2036
Lentein Market Size, Share, and Industry Trends Forecast 2026-2036
Lentein Market Analytics
USDA Organic certification is rotating competitive access in the Lentein Market, filtering out suppliers lacking verified cultivation and processing chains. Parabel USA Inc. leverages its Florida-based aquafarming infrastructure to control raw material supply. Kerry Group plc sustains formulation partnerships with global CPG brands seeking clean-label protein fortification. Cargill, Incorporated anchors downstream distribution through its existing ingredient trading networks.
Lentein denotes a protein-rich ingredient extracted from Lemna minor, commonly known as water lentils or duckweed, containing approximately 40-45% crude protein by dry weight alongside essential amino acids, omega-3 fatty acids, and dietary fiber. The ingredient serves as a sustainable alternative to soy and pea proteins in human nutrition applications, requiring minimal land and water inputs due to its aquatic cultivation on closed-loop ponds. Powder formulations dominate current commercial volumes due to superior shelf stability and ease of incorporation into dry blends, while liquid extracts represent the fastest-growing category as beverage manufacturers pursue cleaner dissolution profiles. Health Foods applications command premium positioning among specialty retailers, whereas Nutritional Bars segment volume concentrates through contract manufacturing channels serving private-label brands.
FDA GRAS self-affirmation pathways and EFSA novel food approval requirements shape ingredient market access timelines on opposite sides of the Atlantic. The EU Green Deal protein diversification targets and F-Gas Regulation compliance for freeze-drying operations add compliance layers to European production economics. Stakeholders must monitor evolving amino acid labeling standards and carbon accounting methodologies that will determine which suppliers retain formulation slots with multinational food manufacturers.
Market Dynamics
Protein extraction technology maturation is compressing unit economics for water lentil processors while FDA GRAS self-affirmation timelines determine which suppliers secure formulation slots with multinational food manufacturers.
Growth Catalysts
- EU Green Deal protein diversification targets:Mandates for sustainable protein sourcing are accelerating ingredient trials across European CPG brands seeking alternatives to soy and pea isolates.
- Sports nutrition end-use expansion:Functional beverage manufacturers are reformulating with Lentein powder to achieve clean-label positioning and complete amino acid profiles.
- Closed-loop aquafarming:Water-efficient cultivation systems in Florida and similar subtropical zones are securing year-round raw material supply with minimal land use.
Market Restraints
- Freeze-drying energy intensity:F-Gas Regulation compliance costs in Europe are elevating processing expenses for thermal-sensitive protein preservation.
- Raw material supply concentration:Aquafarming operations cluster in specific subtropical climates, creating geographic vulnerability to weather disruptions.
- Pea protein substitution threat:Established supply chains for yellow pea isolates maintain cost advantages and broader regulatory recognition.
Strategic Opportunities
- USDA Organic certification acceleration:Verified cultivation chains are unlocking premium positioning in specialty retail channels seeking differentiated protein sources.
- Liquid extract beverage applications:Cleaner dissolution profiles are enabling new product formats in ready-to-drink nutrition and functional hydration.
- Carbon accounting methodology alignment:Aquatic cultivation's minimal land-use footprint aligns with emerging Scope 3 emissions reporting requirements.
Industry Challenges
- Amino acid labeling standard complexity:Evolving FDA and EFSA requirements for protein quality scoring are forcing reformulation documentation updates.
- Novel food approval timeline uncertainty:EFSA dossier preparation and safety study completion create multi-year market access delays for European entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lentein Market |
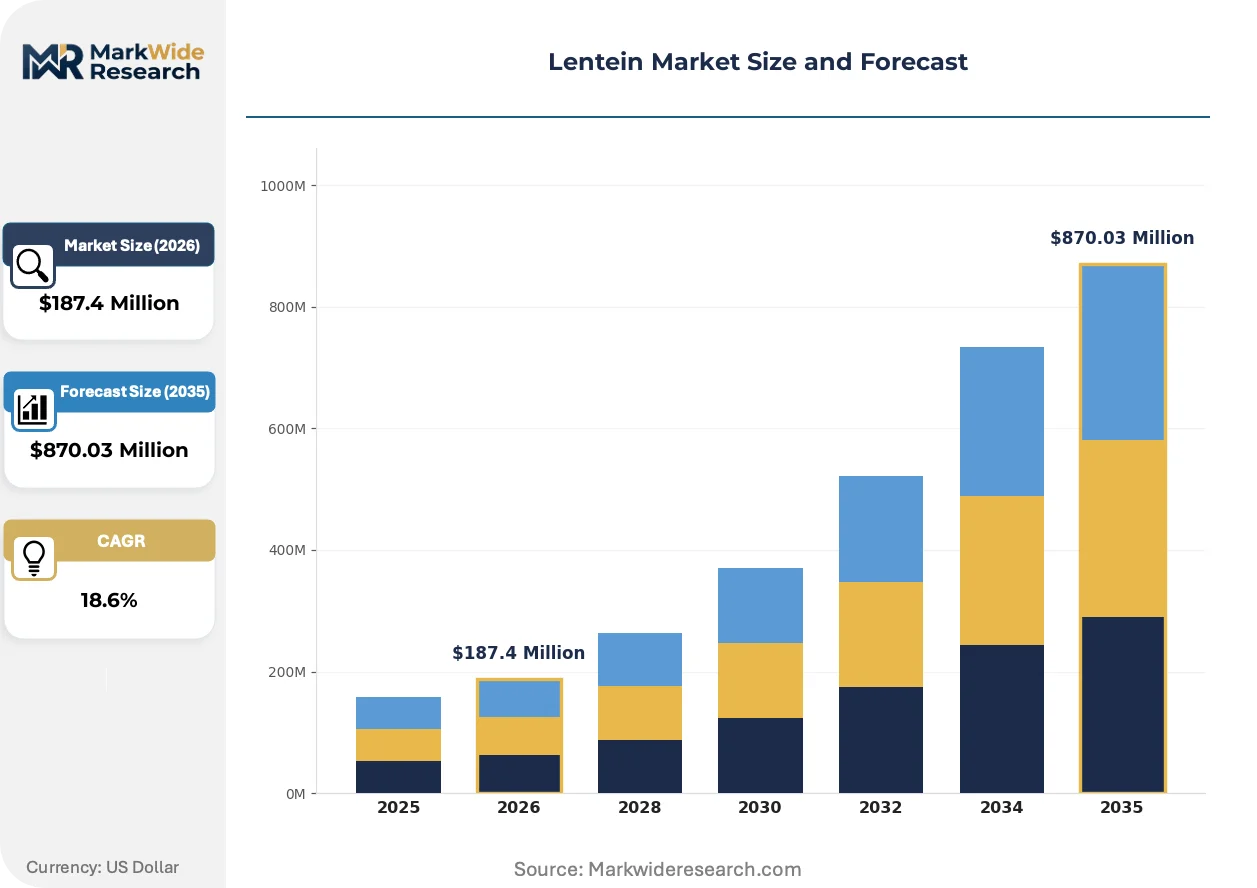
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Granules Application: Dietary Supplements, Nutritional Bars, Protein Shakes, Health Foods End User: Fitness Enthusiasts, Health-Conscious Consumers, Athletes, Vegans Distribution Channel: Online Retail, Health Stores, Supermarkets, Specialty Shops |
| Companies Covered | Parabel USA Inc., Cargill, Incorporated, Kerry Group plc, Hinoman Ltd., GreenOnyx Ltd., Plantible Foods Inc., Roquette Frères S.A., Ingredion Incorporated, Barentz International BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lentein Market Evolving Landscape
Novel protein extraction methods are fragmenting competitive advantage between cost-optimized and bioavailability-maximized processing routes. Regulatory carbon accounting and clean-label positioning are converging to reshape supplier selection criteria.
Enzymatic hydrolysis protocols are improving essential amino acid bioavailability in Lentein isolates. Nutritional bar contract manufacturers are adopting these extracts to reduce grittiness and improve mouthfeel. This processing advance is bifurcating the supplier base between commodity powder traders and specialized bioactive protein houses.
EFSA novel food approval requirements are extending market access timelines for European entrants. Dossier compilation and toxicology study costs are filtering out undercapitalized suppliers. Powder formulations face the longest review queues while liquid extracts with established safety precedents move through accelerated pathways.
Clean-label procurement mandates from specialty retailers are displacing commodity protein sourcing. Functional food brands now require verified cultivation chains and carbon footprint documentation. United States-based CPG manufacturers are leading this specification tightening, with European retailers following within twelve to eighteen months.
Lentein Market Segmentation
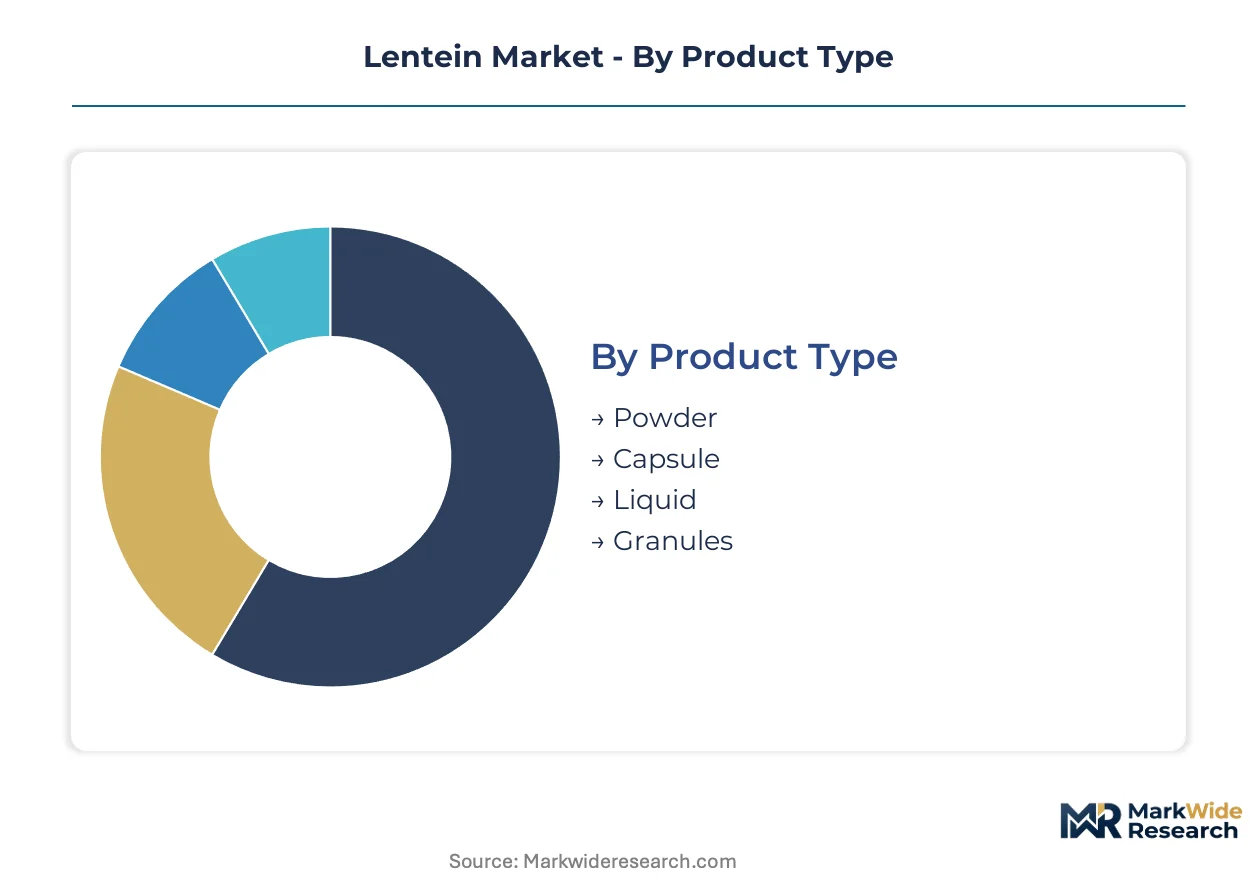
Water lentil ingredient suppliers configure production lines around specific physical formats and buyer specifications. Segmentation reveals where pea protein substitution pressure concentrates and which channels reward premium positioning.
Product Type:
Powder formulations face the most acute substitution threat from yellow pea isolates, while liquid extracts defend through dissolution performance advantages.
- Powder:Dry formulations containing 40-45% crude protein dominate commercial volumes due to superior shelf stability and ease of dry blend incorporation. Demand concentrates through contract manufacturers serving private-label nutritional bars, though freeze-drying energy costs compress margins. Powder retains volume leadership; liquid holds the steepest expansion curve.
- Liquid:Aqueous extracts achieve cleaner dissolution profiles for ready-to-drink functional beverages. Beverage manufacturers in the United States pursue these formats for clean-label protein fortification with minimal sedimentation.
- Capsule:Encapsulated formats target precise dosing in dietary supplement regimens. Supplement brands specify capsule fill weights for amino acid profile standardization.
- Granules:Intermediate particle size enables rapid hydration in instant beverage applications. Food technologists specify granule dimensions for controlled dispersal rates.
Powder commands current volume; liquid extracts gain share fastest through beverage format innovation.
Application:
Cost tier stratification separates commodity protein fortification from premium functional positioning.
- Health Foods:Specialty retail channels command premium positioning for USDA Organic certified ingredients. Florida-based aquafarming operations supply verified cultivation chains meeting clean-label procurement mandates.
- Nutritional Bars:Contract manufacturing channels concentrate volume for private-label brands seeking complete amino acid profiles. Enzymatic hydrolysis protocols reduce grittiness and improve mouthfeel in these applications.
- Dietary Supplements:Capsule and tablet formats emphasize standardized protein content per serving. Supplement brands require documented amino acid bioavailability for label claims.
- Protein Shakes:Ready-to-mix powders compete directly with whey and soy isolates in sports nutrition. Functional beverage manufacturers reformulate with Lentein to achieve differentiation from established protein sources.
Health Foods sustain premium pricing; Nutritional Bars drive volume scale through manufacturing partnerships.
End User:
Customer type determines specification stringency and willingness to absorb cost premiums.
- Athletes:Sports nutrition demands drive requirements for complete essential amino acid profiles and rapid absorption kinetics. Performance-oriented brands specify enzymatically hydrolyzed isolates for post-workout applications.
- Vegans:Plant-based dietary adherence creates demand for alternatives to soy and pea with novel sustainability narratives. This segment accepts price premiums for verified low-carbon cultivation documentation.
- Fitness Enthusiasts:Recreational exercisers seek convenient protein supplementation without dairy or soy allergens. Product developers target this segment with flavored powder formats.
- Health-Conscious Consumers:General wellness positioning emphasizes minimal processing and clean ingredient decks. Retail buyers in this segment prioritize USDA Organic certification and transparent supply chains.
Athletes define performance specifications; Vegans expand most quickly through ethical consumption alignment.
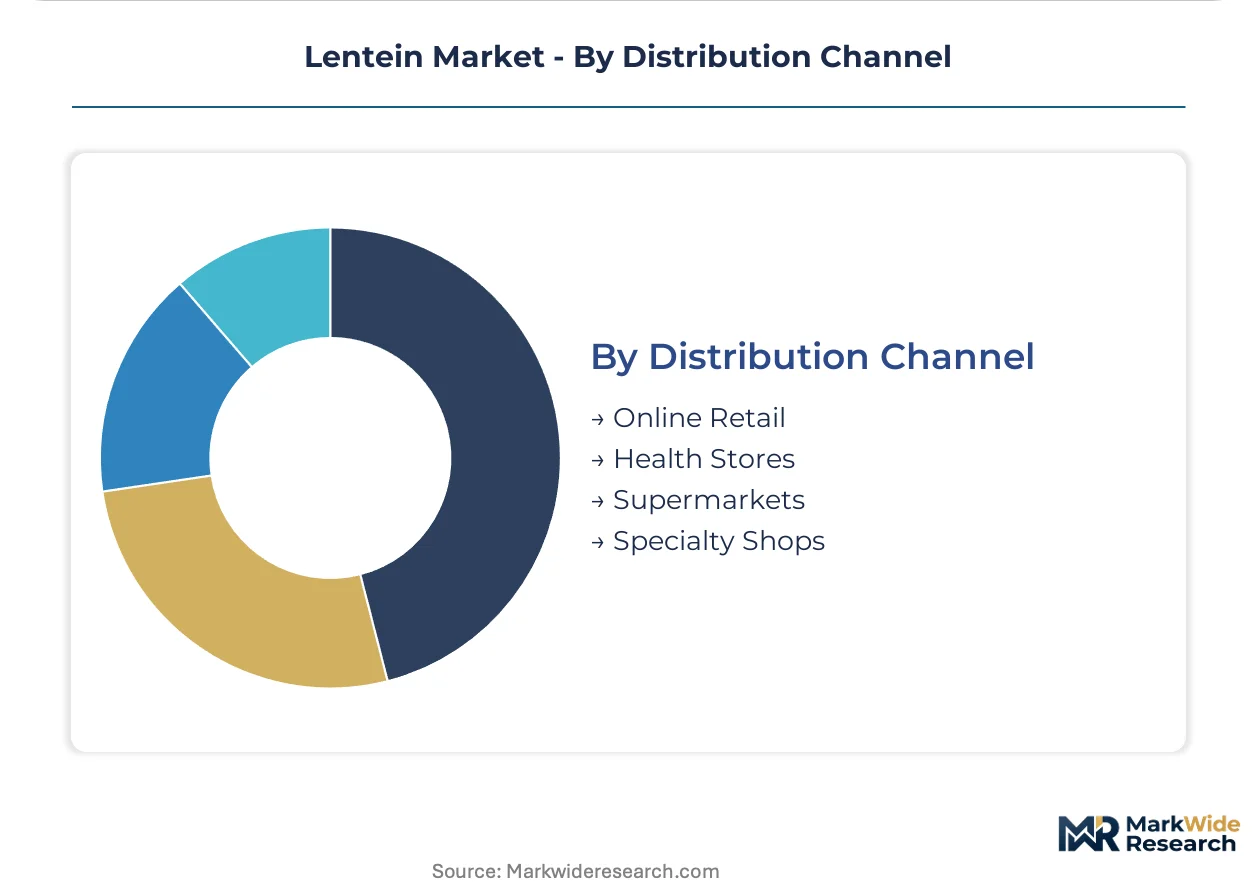
Distribution Channel:
Supply concentration in subtropical aquafarming regions shapes channel economics and geographic reach.
- Online Retail:Direct-to-consumer platforms enable subscription models for specialty protein products. E-commerce operations bypass traditional wholesale markups for margin capture.
- Health Stores:Specialty retailers enforce clean-label procurement mandates with verified cultivation documentation. These channels reward USDA Organic certification with premium shelf placement.
- Supermarkets:Mass retail placement requires cost-competitive positioning against yellow pea isolates. Private-label programs dominate volume in this channel.
- Specialty Shops:Boutique fitness and wellness retailers curate differentiated protein offerings. These outlets prioritize unique origin stories and carbon footprint transparency.
Health Stores anchor premium positioning; Online Retail climbs fastest through direct consumer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal protein diversification targets and USDA organic certification incentives are redirecting ingredient procurement toward verified sustainable supply chains. FDA GRAS self-affirmation pathways accelerate United States market entry timelines compared to EFSA novel food dossier requirements.
United States
Sports nutrition brands in Florida and California are reformulating with water lentil protein to achieve clean-label positioning. FDA GRAS self-affirmation allows rapid commercialization without pre-market approval. Parabel USA Inc. operates aquafarming infrastructure in Florida supplying year-round raw material to functional food manufacturers.
Germany
CPG manufacturers in Bavaria and North Rhine-Westphalia are trialing alternatives to soy isolates under EU Green Deal mandates. EFSA novel food approval requirements extend market access timelines to 18-24 months for dossier completion. Ingredient distributors in Hamburg coordinate freeze-dried powder imports while navigating F-Gas Regulation compliance costs.
Netherlands
Plant-based food startups in the Randstad region are sourcing novel proteins for meat alternative formulations. REACH registration requirements apply to imported protein isolates for industrial food applications. Rotterdam-based logistics hubs consolidate European distribution for subtropical aquafarming imports.
United Kingdom
Specialty retailers in London and Southeast England are enforcing clean-label procurement mandates with carbon footprint documentation. Post-Brexit regulatory divergence from EU novel food frameworks creates parallel approval pathways. Health food brands in the Midlands are pursuing direct supplier relationships with certified organic cultivators.
France
Functional beverage manufacturers in Île-de-France are testing liquid extract formats for ready-to-drink applications. ANSM oversees novel ingredient safety assessments alongside EFSA coordination for EU market access. Lyon-based food technology clusters are developing enzymatic hydrolysis partnerships with protein suppliers.
Lentein Market Competitive Landscape
Listed leaders compete with private specialists across formulation partnerships and raw material control. The supplier base organizes around three tiers: multinational ingredient traders with existing distribution networks, aquafarming operators with captive cultivation assets, and specialized bioactive protein houses with enzymatic processing capabilities. Strategic differentiation centers on USDA Organic certification velocity and carbon accounting documentation. Dominant competitive moves include backward integration into closed-loop aquafarming and exclusive supply agreements with contract manufacturers serving private-label nutritional bars.
Within the aquafarming-specialist tier, Parabel USA Inc. and Hinoman Ltd. exemplify geographic concentration strategies in subtropical cultivation zones. Parabel USA Inc. anchors North American supply through Florida-based operations. Hinoman Ltd. represents Israeli-controlled cultivation technology with expansion into multiple climate zones. Kerry Group plc occupies the formulation partnership archetype, leveraging Irish-listed scale to integrate novel proteins into global CPG brand portfolios. These three entities illustrate the competitive tension between raw material control and downstream formulation access.
| Leading Market Players |
|---|
| Parabel USA Inc. |
| Cargill, Incorporated |
| Kerry Group plc |
| Hinoman Ltd. |
| GreenOnyx Ltd. |
| Plantible Foods Inc. |
| Roquette Frères S.A. |
| Ingredion Incorporated |
| Barentz International BV |
| Others |
Value Network & Pricing Analysis
Freeze-drying capacity utilization rates in Florida aquafarming zones establish minimum viable scale thresholds that compress unit costs for powder processors while elevating entry barriers for smaller cultivators. This scale dynamic concentrates supply-side pricing power among vertically integrated operators who control both pond infrastructure and downstream drying assets.
Pricing Analysis
Certification level creates the primary spread between USDA Organic verified supply and conventional cultivation output. Three-tier pricing structure across premium organic, standard food-grade, and commodity feed-grade levels reflects differential compliance costs and buyer specification stringency. Cost compression in standard powder tiers intensifies because yellow pea isolates maintain established supply chain efficiencies. Health-conscious consumers at specialty retailers show lowest price sensitivity, while mass-market protein shake manufacturers absorb highest substitution pressure.
Supply Chain Analysis
Florida aquafarming infrastructure concentration underwrites North American raw material availability, with Israeli-controlled cultivation technology and Dutch logistics hubs completing the intercontinental flow. Production draws from subtropical pond systems, enzymatic hydrolysis processing lines, and freeze-drying preservation capacity. Single-source vulnerability concentrates in Florida weather exposure and European F-Gas Regulation compliance bottlenecks. Distribution runs through Kerry Group formulation partnerships and Cargill ingredient trading networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional food brand consolidation into fewer multinational CPG portfolios concentrates buyer negotiating leverage, forcing suppliers to absorb certification costs or surrender shelf placement. This power shift rewards cultivators with captive organic verification and penalizes commodity traders lacking traceability documentation.
For Market Incumbents: Shield formulation partnerships with sports nutrition brands by accelerating enzymatic hydrolysis capacity expansion in Florida. Parabel USA Inc.'s aquafarming model demonstrates how captive pond control defends against pea protein substitution. Kerry Group's CPG integration provides the template for channel lock-in through exclusive supply agreements with contract nutritional bar manufacturers.
For New Entrants and Emerging Players: Liquid extract dissolution performance gaps at beverage manufacturers represent the most penetrable white-space target, as incumbent powder specialists under-serve ready-to-drink format requirements. European EFSA novel food approval delays create window for US-based liquid extract specialists to establish brand preference before continental market access normalizes. Direct relationships with functional beverage startups bypass entrenched ingredient distributor markups.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aquafarming operators with proven organic certification velocity over downstream formulation houses facing margin compression. Long-term viability rests on carbon accounting methodology alignment as Scope 3 reporting mandates expand. Acquisition target archetype combines Florida pond infrastructure with enzymatic processing capabilities. Signal to watch: EFSA novel food approval timeline acceleration that erodes US-first mover advantage.
| Strategic Initiative | Industry Significance |
|---|---|
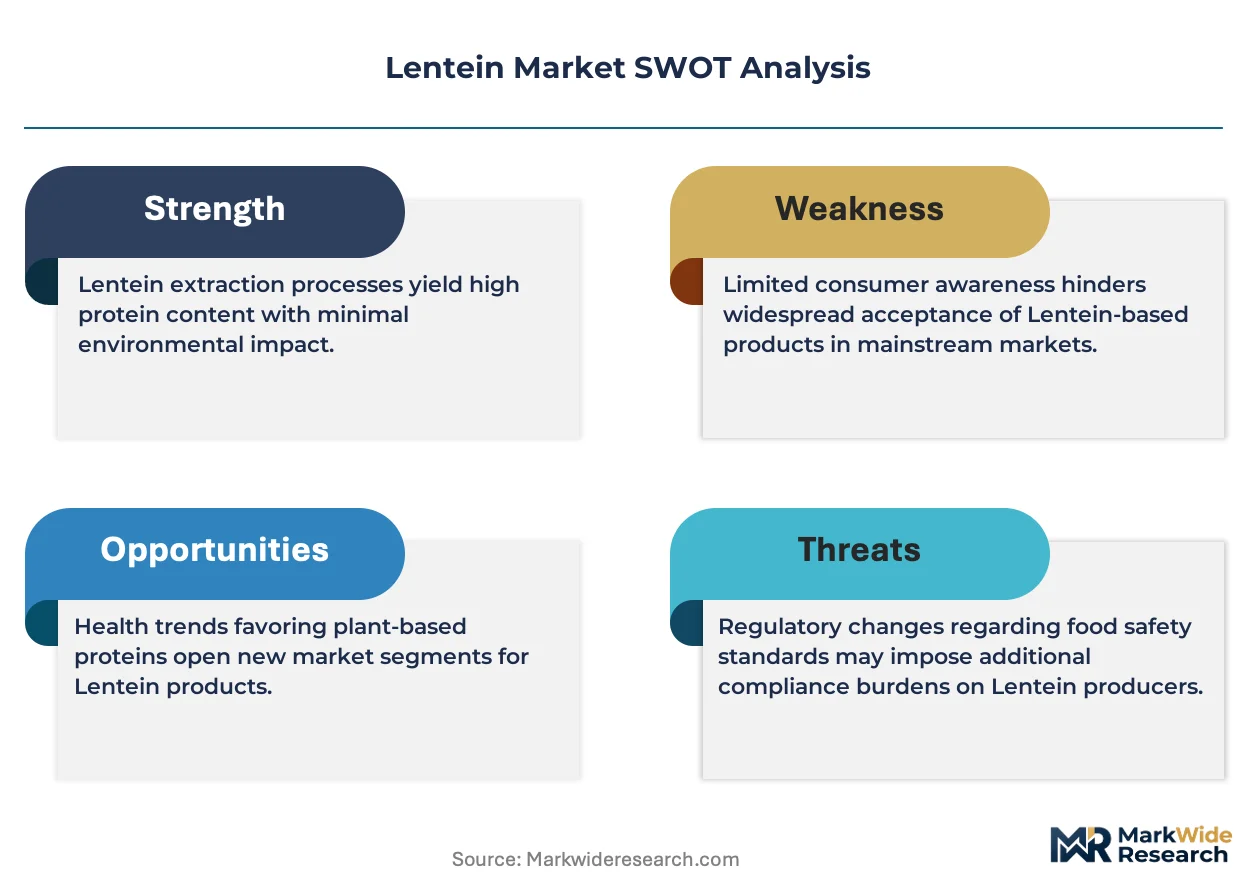
| Backward Integration into Aquafarming | Captive pond control secures raw material supply against weather disruption and certification bottlenecks. |
| Enzymatic Hydrolysis Scale-Up | Bioavailability-maximized processing routes command premium positioning in sports nutrition applications. |
| USDA Organic Certification Acceleration | Verified cultivation chains unlock specialty retail shelf placement and clean-label procurement mandates. |
| Liquid Extract Beverage Partnerships | Cleaner dissolution profiles enable ready-to-drink format innovation beyond incumbent powder dominance. |
| Carbon Accounting Methodology Alignment | Aquatic cultivation footprint documentation satisfies emerging Scope 3 emissions reporting requirements. |
Research Methodology
Operator-level perspectives from aquafarming facility managers, enzymatic processing engineers, CPG formulation scientists, and specialty retail category buyers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across cultivation, processing, and distribution tiers with secondary validation from FDA GRAS filings, EFSA novel food dossiers, USDA Organic certification records, and trade flow data. Bottom-up volume modeling triangulated against top-down protein ingredient market sizing.
Sensitivity analysis tested forecast robustness across protein extraction technology maturation scenarios and regulatory approval timeline variations. Segmentation dimensions modeled include physical format, application category, end-user archetype, and distribution channel across the projection horizon. CAGRs derived from unit economics trajectories, substitution elasticity estimates, and penetration rate assumptions for enzymatic hydrolysis adoption and liquid extract beverage integration.
Underlying assumptions cover FDA GRAS self-affirmation pathway stability and EFSA dossier processing capacity, with deviation risk concentrated in novel food approval timeline extensions and freeze-drying energy cost volatility. Practitioners should keep alternative scenarios live as EU Green Deal protein diversification targets and carbon accounting standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Polyimide Coatings Market
Specialty Compounds
India Sealants Market
Specialty Compounds
North America Lithium Compound Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
US Non-Commercial Acrylic Paints Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Saudi Arabia Collagen Market
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Toner Resins Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market