
 Sensory Modifiers Market | 2026-2036
Sensory Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Sensory Modifiers Market Analytics
ISO 22000 certification is bifurcating the competitive landscape into qualified suppliers and marginal participants. Givaudan leverages its integrated flavor creation platform to sustain technical partnerships with multinational food manufacturers. Symrise anchors its position through deep backward integration into natural extract supply chains. BASF competes on synthetic molecule scale, occupying cost-sensitive segments with standardized aroma modifier portfolios.
Sensory modifiers comprise formulated compounds that alter human perception of taste, smell, texture, or visual appearance in finished goods, typically active at parts-per-million concentrations and manufactured through controlled esterification, encapsulation, or fermentation pathways. Their primary commercial purpose is enabling recipe reformulation without perceptible quality loss to consumers. Flavor modifiers command the largest value pool as beverage producers strip sugar across carbonated and functional drink lines. Texture enhancers represent the fastest-growing category, driven by plant-based dairy and meat alternatives requiring mouthfeel reconstruction. Color additives remain the most mature segment, with margin compression from natural source supply constraints and synthetic pigment regulatory restrictions.
The FDA governs GRAS self-determination pathways for flavor modifiers in the United States, while EFSA sets purity thresholds for food contact substances across Europe; REACH compliance adds substance registration burdens for aroma chemical importers into EU member states. China's SAMR enforces GB standard conformity for imported sensory ingredients, creating separate testing protocols from Western frameworks. Stakeholders must monitor divergence between FDA GRAS notification trends and EFSA mandated safety re-evaluations to anticipate reformulation cost shifts.
Market Dynamics
Beverage manufacturers are stripping sugar from carbonated and functional drink formulations, forcing sensory modifier suppliers to rebuild taste profiles without caloric sweeteners while maintaining consumer acceptance thresholds.
Growth Catalysts
- Clean-label mandates:FDA reformulation timelines for bakery and dairy applications are accelerating procurement of natural flavor modifiers as manufacturers race to meet disclosure requirements.
- Plant-based mouthfeel reconstruction:Texture enhancers are capturing demand from oat milk and pea protein processors struggling to replicate dairy viscosity and fat distribution.
- REACH purity escalation:ECHA registration burdens for aroma chemical importers are filtering out marginal suppliers, concentrating volume with certified compounders.
Market Restraints
- Natural extract supply volatility:Vanilla and citrus terpene harvest fluctuations in Madagascar and Brazil are compressing margins for natural color and flavor portfolios.
- F-Gas synthetic pathway restrictions:EMA solvent limitations for certain esterification processes are forcing capital-intensive process reengineering at European manufacturing sites.
- Biotechnology substitution threat:Precision fermentation-derived flavor molecules from synthetic biology startups are threatening commodity positions in vanilla and citrus replication.
Strategic Opportunities
- India FSSAI alignment:Domestic food processors preparing for export certification are creating demand for ISO 22000-qualified sensory modifier suppliers with validated supply chains.
- Encapsulation-convergence:Coacervation and spray-drying technology integration is enabling heat-stable flavor release systems for baked snack and extruded pet food applications.
- SAMR import protocol mastery:Western suppliers with established GB standard testing capabilities are capturing share from competitors facing Chinese customs delays.
Industry Challenges
- ISO 22000 auditor scarcity:Certification backlogs at accredited bodies are extending supplier qualification timelines, delaying contract awards for reformulation projects.
- Legacy ERP integration friction:Food manufacturers running SAP or Oracle instances require custom API development to incorporate supplier traceability data into batch records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensory Modifiers Market |
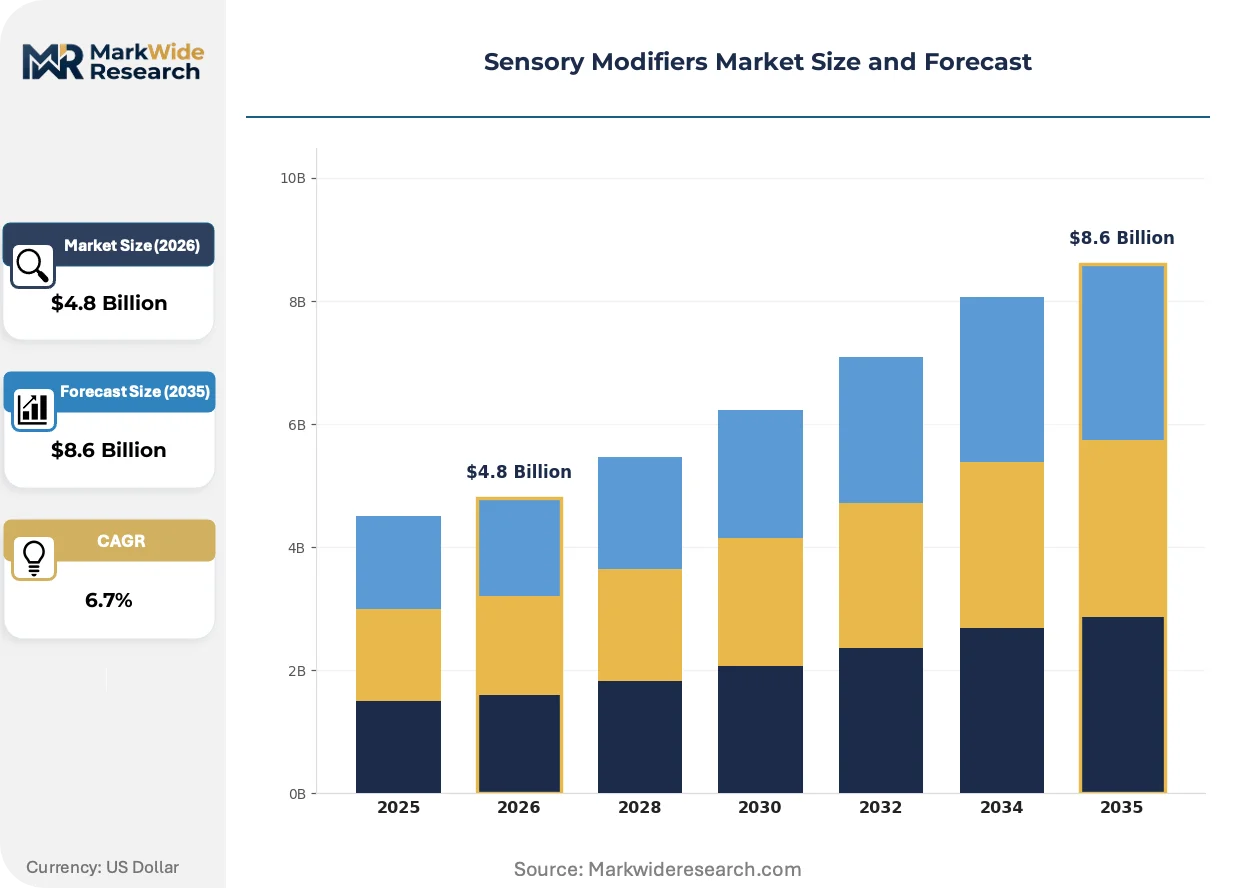
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavor Modifiers, Texture Enhancers, Aroma Modifiers, Color Additives End User: Food Manufacturers, Beverage Producers, Pharmaceuticals, Cosmetics Application: Bakery Products, Dairy Products, Snacks, Confectionery Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Givaudan, International Flavors & Fragrances, Symrise, Firmenich, Sensient Technologies, DSM, BASF, Lubrizol, SensoryCo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensory Modifiers Market Evolving Landscape
Controlled release technologies and bioprocess engineering are redrawing competitive boundaries between synthetic compounders and natural extract suppliers, with regulatory divergence between FDA self-determination and EFSA mandated review creating divergent innovation pathways.
Microencapsulation via complex coacervation is supplanting simple spray-dried flavor systems in heat-processed applications. Snack and ready-meal manufacturers are adopting these shell-core structures at accelerated procurement cycles. This technology is supplanting conventional flavor addition methods by protecting volatile compounds through extrusion and baking thermal profiles, compressing commodity flavor positions while expanding premium modifier margins.
EFSA mandated safety re-evaluations for food contact substances are diverging from FDA GRAS notification trends, creating dual-track compliance requirements. European flavor houses are absorbing additional toxicology study costs while American competitors accelerate self-affirmation pathways. Bakery and confectionery exporters to the EU are reformulating with EFSA-pre-cleared molecule libraries, segmenting product formulations by destination market.
Direct procurement from compounders is displacing distributor intermediaries among multinational food manufacturers with dedicated technical service requirements. Large beverage and dairy processors are establishing captive flavor development partnerships, bypassing traditional ingredient distribution channels. This concentration is most visible in the United States, where CPG giants have consolidated supplier panels to three qualified compounders per modifier category.
Sensory Modifiers Market Segmentation
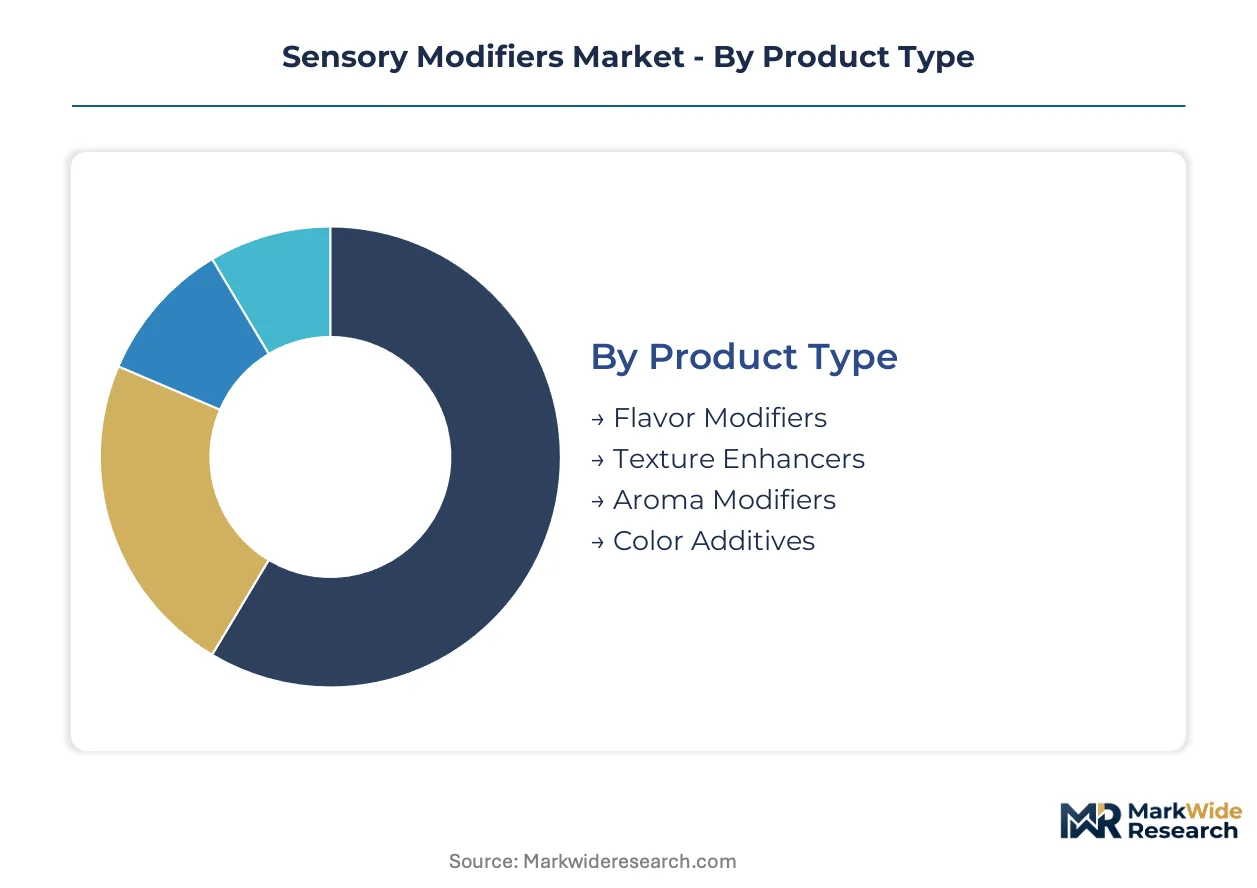
Sensory modifier procurement patterns diverge sharply across product physics and customer technical requirements. Margin capture depends on matching formulation complexity to end-use certification standards and thermal processing constraints.
Product Type:
Margin pools concentrate in texture reconstruction technologies where patent-protected rheology systems command formulation exclusivity.
- Flavor Modifiers:Formulated compounds including sweetness enhancers, salt replacers, and bitter blockers active at sub-ppm thresholds. Beverage producers in the United States are stripping sugar from carbonated lines, forcing rebuilds of complete taste profiles without caloric sweeteners while maintaining consumer acceptance thresholds.
- Texture Enhancers:Hydrocolloid, starch, and protein systems engineered to replicate fat mouthfeel and viscosity in plant-based matrices. Oat milk and pea protein processors are capturing the steepest expansion trajectory as they struggle to replicate dairy viscosity and fat distribution in alternative formulations.
- Aroma Modifiers:Volatile ester and terpene compounds manufactured through controlled esterification or fermentation pathways. REACH registration burdens are filtering out marginal suppliers and concentrating volume with certified compounders.
- Color Additives:Natural and synthetic pigments including carotenoids, anthocyanins, and caramel classes. Vanilla and citrus terpene harvest fluctuations in Madagascar and Brazil are compressing margins for natural portfolios.
Flavor Modifiers hold installed capacity. Texture Enhancers are rotating up the share rankings.
End User:
Customer scale determines service intensity, with multinational food manufacturers demanding captive technical partnerships that distributor channels cannot fulfill.
- Food Manufacturers:Bakery and dairy processors requiring heat-stable encapsulation systems for extruded and baked applications. FDA reformulation timelines are accelerating procurement of natural modifiers as manufacturers race to meet disclosure requirements.
- Beverage Producers:Carbonated and functional drink formulators stripping sugar while rebuilding complete sensory profiles. Direct procurement from compounders is displacing distributor intermediaries among multinationals with dedicated technical service requirements.
- Pharmaceuticals:Tablet coating and oral dosage formulators masking active pharmaceutical ingredient bitterness. EFSA mandated safety re-evaluations for food contact substances are diverging from FDA GRAS pathways, creating dual-track compliance requirements.
- Cosmetics:Fragrance and skincare formulators utilizing aroma modifiers for olfactory positioning. ISO 22000 certification is bifurcating the competitive landscape into qualified suppliers and marginal participants.
Food Manufacturers anchor contract volumes. Beverage Producers are climbing the fastest in technical service intensity.
Application:
Thermal processing severity dictates encapsulation technology selection and corresponding price tier.
- Bakery Products:Heat-processed applications requiring microencapsulated flavor systems to protect volatile compounds through extrusion and baking thermal profiles.
- Dairy Products:pH-sensitive formulations demanding cold-process stable texture systems for yogurt and fermented matrices.
- Snacks:Savory and extruded applications adopting complex coacervation shell-core structures at accelerated procurement cycles.
- Confectionery:Sugar-free and reduced-calorie segments requiring bitterness masking and texture reconstruction in hard candy and chocolate coatings.
Bakery Products command the premium encapsulation tier. Snacks are gaining share fastest in controlled-release adoption.
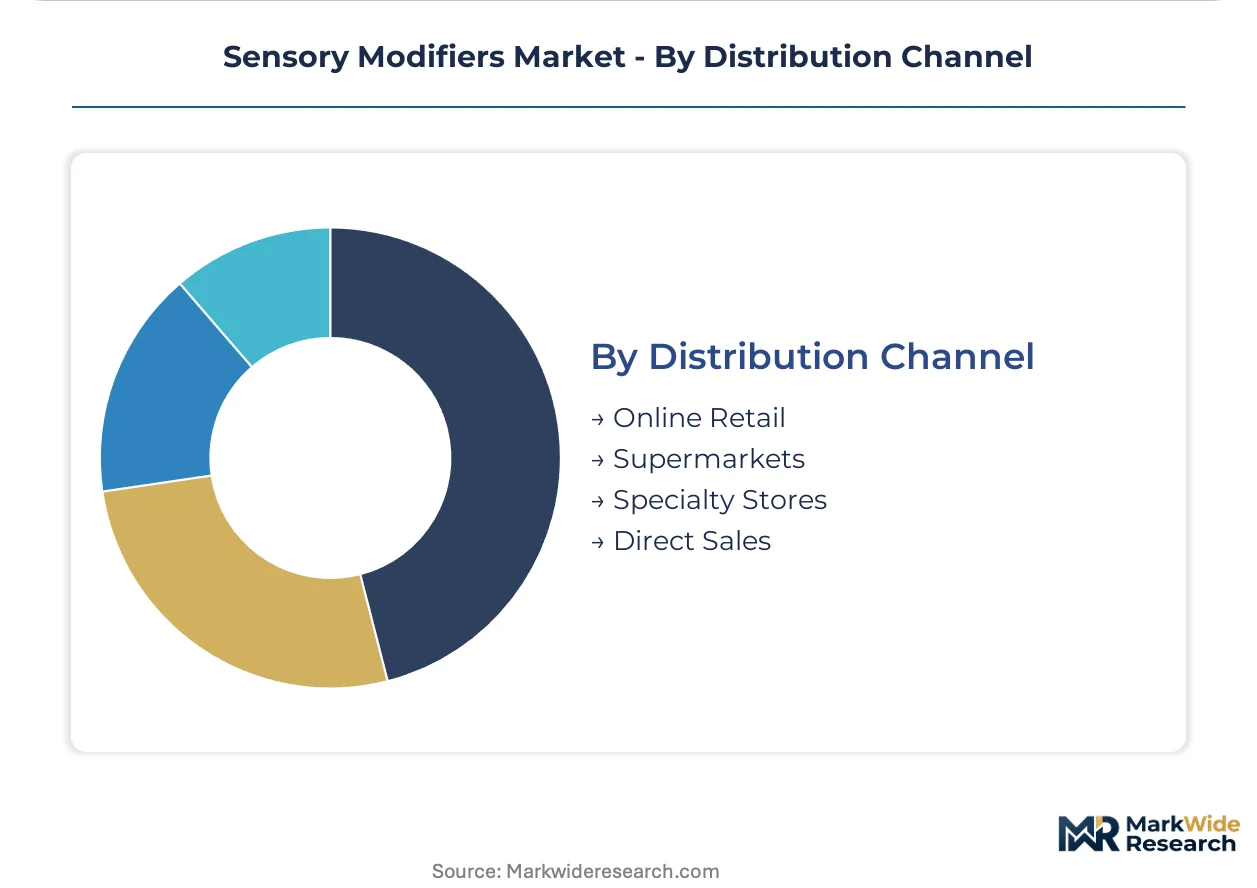
Distribution Channel:
Channel selection tracks customer technical sophistication and batch traceability requirements.
- Online Retail:Small-scale and artisanal formulators sourcing standardized modifier grades with limited technical support.
- Supermarkets:Mass-market food processors purchasing commodity-grade color and flavor portfolios through consolidated procurement.
- Specialty Stores:Regional compounders and natural extract suppliers serving clean-label mandates with validated supply chains.
- Direct Sales:Multinational food manufacturers establishing captive flavor development partnerships, bypassing traditional distribution channels entirely.
Direct Sales holds the technical partnership tier. Specialty Stores are rotating up in natural extract positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage producers and bakery manufacturers concentrate procurement power in the United States, Germany, China, and India, where clean-label mandates and sugar-reduction targets are forcing reformulation cycles at compound ingredient suppliers.
United States
FDA disclosure timelines for bakery and dairy applications are accelerating natural modifier procurement as manufacturers race to meet ingredient transparency requirements. The GRAS self-determination pathway allows faster flavor modifier approvals than European frameworks. Chicago and New Jersey host the densest clusters of beverage formulation labs, where carbonated drink producers are stripping sugar while rebuilding complete taste profiles.
Germany
REACH registration burdens for aroma chemical importers are filtering out marginal suppliers and concentrating volume with certified compounders. EFSA purity thresholds for food contact substances exceed FDA requirements, forcing additional toxicology study costs at flavor houses. The Rhine-Ruhr industrial corridor anchors European production of encapsulated flavor systems for heat-processed snack applications.
China
SAMR GB standard conformity for imported sensory ingredients creates separate testing protocols from Western frameworks, favoring suppliers with established in-country validation capabilities. Domestic oat milk and pea protein processors are driving texture enhancer demand as they struggle to replicate dairy viscosity. Shanghai and Guangzhou serve as import gateways where Western suppliers with mastered customs protocols capture share from delayed competitors.
India
FSSAI alignment requirements for export-bound food processors are creating demand for ISO 22000-qualified sensory modifier suppliers with validated supply chains. Domestic bakery and confectionery manufacturers are adopting natural color portfolios under pressure from retail clean-label mandates. Maharashtra and Gujarat concentrate formulation facilities where regional compounders are upgrading to international certification standards.
Brazil
Vanilla and citrus terpene harvest fluctuations are compressing margins for natural color and flavor portfolios dependent on South American agricultural inputs. ANVISA regulatory convergence with FDA frameworks is simplifying import pathways for multinational ingredient suppliers. São Paulo anchors Latin American technical service operations for beverage and dairy reformulation partnerships.
Sensory Modifiers Market Competitive Landscape
Player mix skews toward integrated flavor houses with captive technical service capabilities and commodity chemical producers competing on synthetic molecule scale. The vendor base separates into three tiers: multinational compounders with global certification portfolios, regional specialists with deep backward integration into natural extract supply chains, and synthetic manufacturers occupying cost-sensitive standardized segments. Dominant competitive moves include direct procurement partnerships that displace distributor intermediaries, and ISO 22000 certification investments that bifurcate qualified suppliers from marginal participants.
Within the integrated compounder tier, Givaudan and Symrise exemplify divergent strategic positioning. Givaudan leverages its flavor creation platform to sustain technical partnerships with multinational food manufacturers. Symrise anchors its market position through upstream control over natural extract supply chains. BASF occupies a distinct archetype as a scale-driven synthetic molecule producer serving cost-sensitive segments with standardized aroma modifier portfolios.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances |
| Symrise |
| Firmenich |
| Sensient Technologies |
| DSM |
| BASF |
| Lubrizol |
| SensoryCo Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between certified compounders and multinational beverage manufacturers lock in vanilla and citrus terpene supply access while anchoring price visibility against Madagascar and Brazilian harvest volatility. These contracts insulate procurement teams from spot market swings in natural extract portfolios.
Pricing Analysis
Cost-plus contracts with vanilla and citrus terpene indexation dominate natural flavor modifier procurement. Three-tier pricing structure across premium encapsulation systems, standard spray-dried grades, and economy synthetic molecules reflects ISO 22000 certification tier and thermal stability performance. Cost compression in economy synthetic segments is intensifying due to precision fermentation startup competition. Small-scale artisanal formulators exhibit highest price sensitivity; multinational food manufacturers with captive technical partnerships show lowest.
Supply Chain Analysis
Madagascar vanilla curing capacity and Brazilian citrus terpene distillation infrastructure act as chokepoints for natural aroma modifier availability. Manufacturing concentrates in Germany, China, and India, with raw material dependencies on Southeast Asian hydrocolloids, Indian spice oleoresins, and European starch derivatives. Single-source vulnerability runs through Madagascar vanilla bean supply. Distribution runs through direct sales channels for qualified compounders serving multinational accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived flavor molecules threaten commodity positions in vanilla and citrus replication, forcing incumbents to defend through certification moats and encapsulation technology differentiation.
For Market Incumbents: Consolidate supplier panels to three qualified compounders per modifier category to deepen technical service relationships and lock out biotechnology substitutes. Prioritize ISO 22000 certification investments that bifurcate qualified suppliers from marginal participants facing auditor scarcity backlogs. Backward integration into natural extract supply chains insulates against Madagascar and Brazilian harvest volatility. For New Entrants and Emerging Players: Technical service gaps in heat-stable encapsulation systems for baked snack applications present white-space entry points. Target Indian FSSAI-aligned export processors seeking ISO 22000-qualified suppliers with validated supply chains. Go-to-market leverage rests on GB standard testing capabilities for SAMR import protocol mastery. For Investors and Strategic Acquirers: Regional compounders with deep backward integration into natural extract supply chains represent priority acquisition archetypes. Long-term viability frames around biotechnology substitution timelines and regulatory divergence between FDA GRAS and EFSA re-evaluation pathways. Watch precision fermentation cost curves as inflection signal for commodity flavor modifier displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Extract Supply Chains | Madagascar and Brazilian sourcing control insulates margin compression from harvest volatility. |
| ISO 22000 Certification Investment | Auditor scarcity at accredited bodies creates qualification bottlenecks favoring early movers. |
| Encapsulation Technology Convergence | Complex coacervation systems command formulation exclusity in heat-processed snack applications. |
| Direct Procurement Partnership Establishment | Multinational beverage manufacturers bypass distributor channels for captive flavor development. |
| SAMR Import Protocol Mastery | GB standard testing capabilities capture share from Western competitors facing Chinese customs delays. |
Research Methodology
Initial hypotheses were tested against primary input from flavor creation platform directors, procurement leads at multinational beverage manufacturers, regulatory affairs specialists navigating FDA GRAS and EFSA pathways, and technical service heads at encapsulated systems compounders, then refined against secondary validation from FDA GRAS notification filings, EFSA food contact substance re-evaluation records, REACH registration databases, and SAMR GB standard conformity protocols. Bottom-up volume modeling triangulated with top-down value estimates anchored the market sizing framework.
Variance decomposition across flavor modifier, texture enhancer, aroma modifier, and color additive segments drove analytical structure over the projection horizon, with additional dimensions for thermal processing severity and certification tier. CAGRs derived from segment-level volume trajectories weighted by price tier mix. Forecast inputs incorporated biotechnology substitution timelines for vanilla and citrus replication, plus regulatory divergence between FDA self-determination and EFSA mandated review pathways.
Underlying assumptions cover REACH purity escalation timelines, F-Gas Regulation solvent limitation enforcement, and precision fermentation cost curve trajectories, with deviation risk concentrated in Madagascar vanilla harvest fluctuations and EFSA toxicology study cost absorption capacity. Practitioners should keep alternative scenarios live as biotechnology scale-up economics and regulatory framework convergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Anisic Aldehyde Market
Flavor and Fragrance Chemicals
Deodorization Systems Market
Flavor and Fragrance Chemicals
Sulphite Ammonia Caramel Market
Flavor and Fragrance Chemicals
3-Methyl Valeric Acid Market
Flavor and Fragrance Chemicals
Immortelle Oil Market
Flavor and Fragrance Chemicals
Anisole Market
Flavor and Fragrance Chemicals
Citronellol Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Global Bio Vanillin Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Cedarwood Oil Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market
Flavor and Fragrance Chemicals
Nonanal Market
Flavor and Fragrance Chemicals
Massoia Bark Essential Oil Market